
 Latin America Automotive Adaptive Lighting System Market | 2026-2036
Latin America Automotive Adaptive Lighting System Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Automotive Adaptive Lighting System Market Foresight
Multi-source supplier arrangements around LED and matrix modules is consolidating toward fewer Tier-1 partnerships as assemblers seek design accountability. HELLA KGaA Hueck & Co leverages its lamp engineering heritage to anchor high-specification programs with German-brand OEMs operating in Mexico. Valeo Group competes through integrated mechatronic headlamp platforms that reduce assembly complexity for vehicle manufacturers. Koito Manufacturing Co Ltd extends its manufacturing footprint to serve Japanese OEM transplant facilities across the region.
An automotive adaptive lighting system modulates beam pattern, intensity, and direction in response to vehicle speed, steering angle, and ambient conditions, typically incorporating arrays of individually addressable LEDs with camera-based scene analysis. These systems reduce glare exposure to oncoming traffic while maximizing driver visibility, directly supporting collision-avoidance performance. Matrix LED configurations command the strongest technology positioning due to their pixel-level beam segmentation capability, while factory-installed integration dominates value capture by embedding calibration protocols during vehicle assembly rather than post-production retrofit. Adaptive Front Lighting technology leads deployment frequency across OEM programs, though Intelligent Control architectures represent the fastest structural expansion as software-defined beam management displaces hardware-reliant solutions.
CONTRAN in Brazil and NOM standards in Mexico govern headlamp performance thresholds, compelling suppliers to validate adaptive systems against regional testing protocols before market entry. ECE Regulations, though originating in Europe, shape baseline technical expectations that Latin American OEMs reference for export-platform commonality. Stakeholders must track how upcoming Brazilian Inovação Automotiva incentives interact with local content requirements to determine whether adaptive lighting module production shifts toward regional captive supply or remains import-dependent.
Market Dynamics
Software-defined beam management is compressing hardware refresh cycles across Latin American OEM programs, forcing Tier-1 suppliers to recalibrate engineering roadmaps around intelligent control architectures rather than discrete lamp assemblies.
Growth Catalysts
- CONTRAN Nighttime Visibility Mandates:Brazil's federal traffic safety authority mandates improved headlamp performance thresholds, compelling domestic assemblers to factory-install adaptive systems on new vehicle platforms.
- Matrix LED Module Cost Curves:Manufacturing scale efficiencies in pixel-level beam segmentation technology reduce per-unit costs for high-specification headlamp configurations.
- Export-Oriented Mexican Assembly Clusters:German and Japanese OEM transplant facilities in Querétaro and Guanajuato specify adaptive lighting for vehicles destined for US and European markets.
Market Restraints
- Import-Dependent Module Supply:Regional captive production of LED drivers and camera-based scene analysis hardware remains underdeveloped, exposing assemblers to currency volatility and lead-time extension.
- ECE Regulation Divergence:European baseline technical expectations for adaptive beam patterns create validation friction for Latin American market variants, adding homologation cost layers.
- Aftermarket Retrofit Limitations:Post-production calibration protocol complexity restricts adaptive lighting penetration to factory-installed channels, excluding independent service networks.
Strategic Opportunities
- Brazilian Inovação Automotiva Incentives:Federal automotive innovation credits may subsidize domestic module assembly if local content thresholds are met, reshaping supply geography.
- Intelligent Control-Telematics Convergence:Integration of V2X communication protocols with adaptive beam management enables predictive road-illumination based on traffic infrastructure data.
- Colombian Andean Corridor Expansion:Assembly capacity growth in Bogotá and Medellín for premium SUV exports creates new specification pull for advanced lighting systems.
Industry Challenges
- Embedded Software Competency Scarcity:Regional engineering pools lack depth in machine-vision algorithm development for camera-based scene analysis, forcing reliance on foreign R&D centers.
- Multi-Protocol Calibration Complexity:Each OEM's proprietary beam-pattern mapping requires distinct assembly-line test equipment, fragmenting Tier-1 capital deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Automotive Adaptive Lighting System Market |
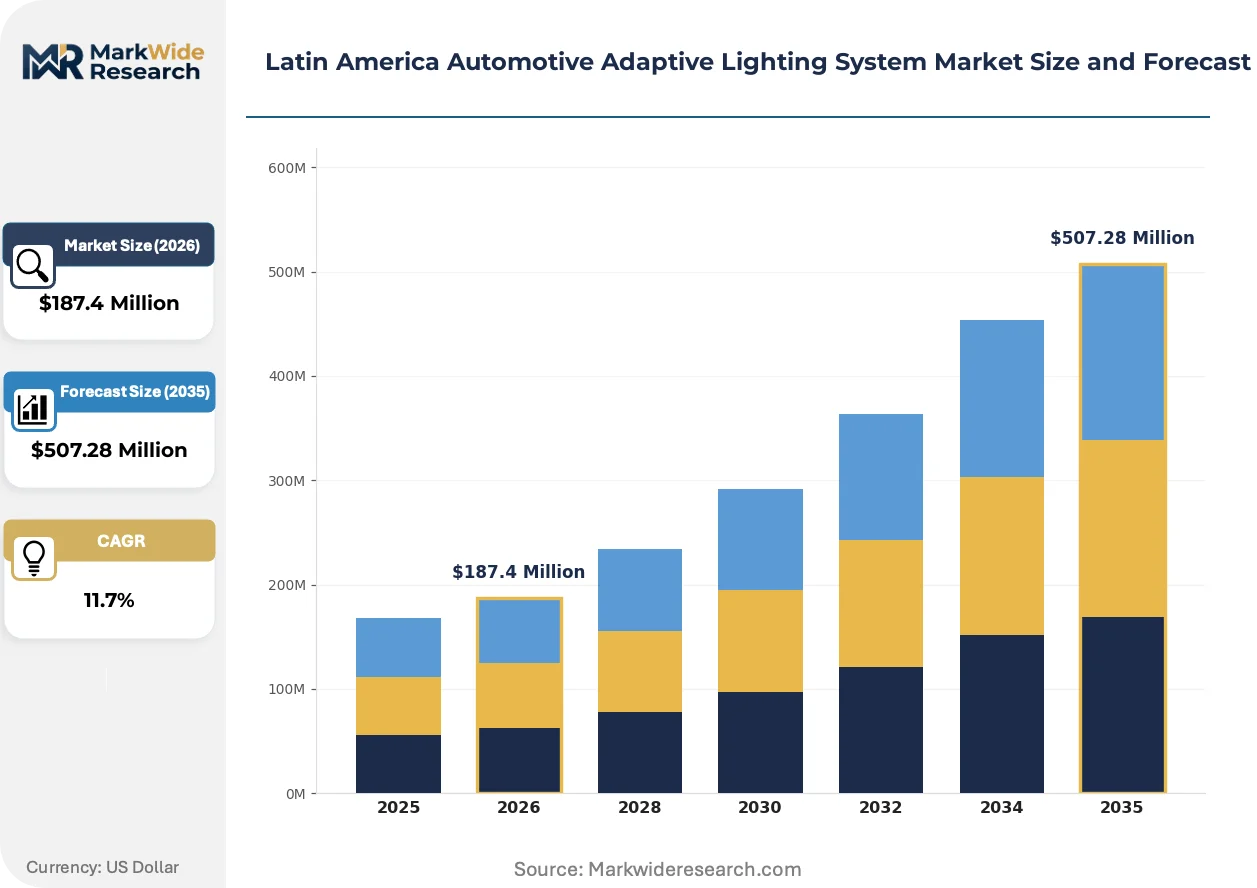
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Matrix LED, Dynamic Bending, LED, Laser Technology: Adaptive Front Lighting, Intelligent Control, Automatic Beam Adjustment, Advanced Signal Processing End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Installation: Factory Installed, Retrofit, Modular Systems, Integrated Solutions |
| Companies Covered | HELLA KGaA Hueck & Co, Valeo Group, Hyundai Mobis, Koito Manufacturing Co Ltd, Magneti Marelli SpA, Stanley Electric Co Ltd, Osram, Texas Instruments, ZKW Group, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Automotive Adaptive Lighting System Market Shifts & Advancements
Digital light processing is overtaking analog beam-shaping across Latin American OEM supply chains, compressing the traditional lamp-engineering cycle and elevating software architecture decisions above hardware specification.
Matrix LED technology modulates individual pixel intensity to create dynamic shadow zones around oncoming vehicles while maintaining full-beam illumination elsewhere. Premium passenger vehicle assemblers in São Paulo and Mexico City are adopting this configuration at accelerating pace for flagship sedan and SUV platforms. The technology is expanding into mid-segment vehicle lines as semiconductor cost curves flatten, enabling Tier-1 suppliers to defend margin position through software differentiation rather than discrete component premium.
CONTRAN's evolving headlamp performance framework now incorporates adaptive beam pattern validation within Brazilian type-approval procedures. This regulatory evolution forces suppliers to maintain dual homologation tracks—one for domestic sale, another for export-platform commonality with ECE baselines. Mexican NOM standards are following a similar trajectory, with draft amendments referencing camera-based glare-limitation performance thresholds.
Fleet procurement for ride-hail and corporate lease operators is concentrating specification authority with centralized technical teams rather than distributed dealership networks. These buyers prioritize total-cost-of-ownership metrics including bulb-life extension and collision-avoidance insurance discounts over upfront capital outlay. São Paulo-based fleet managers are most visible in this behavioral shift, specifying adaptive lighting as standard across executive vehicle categories.
Latin America Automotive Adaptive Lighting System Market Segmentation
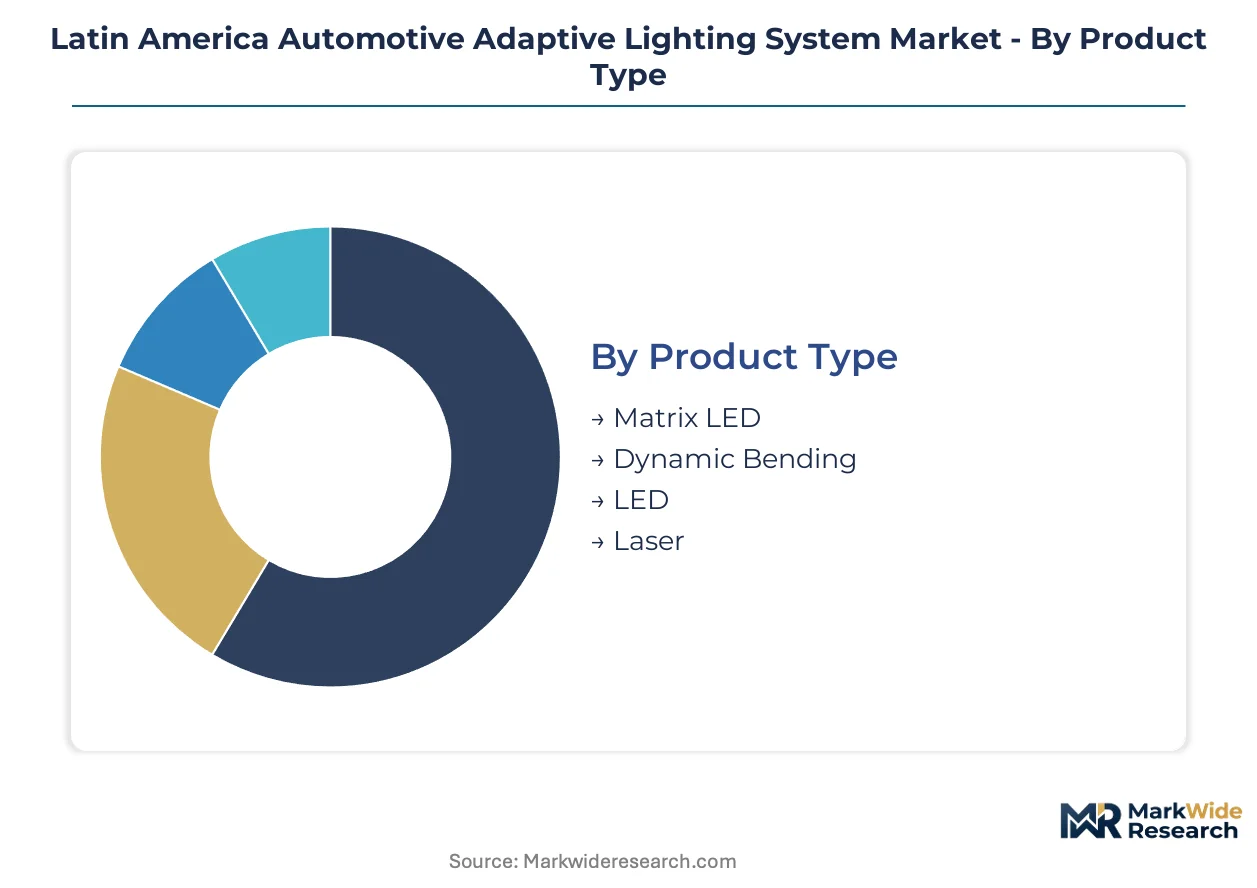
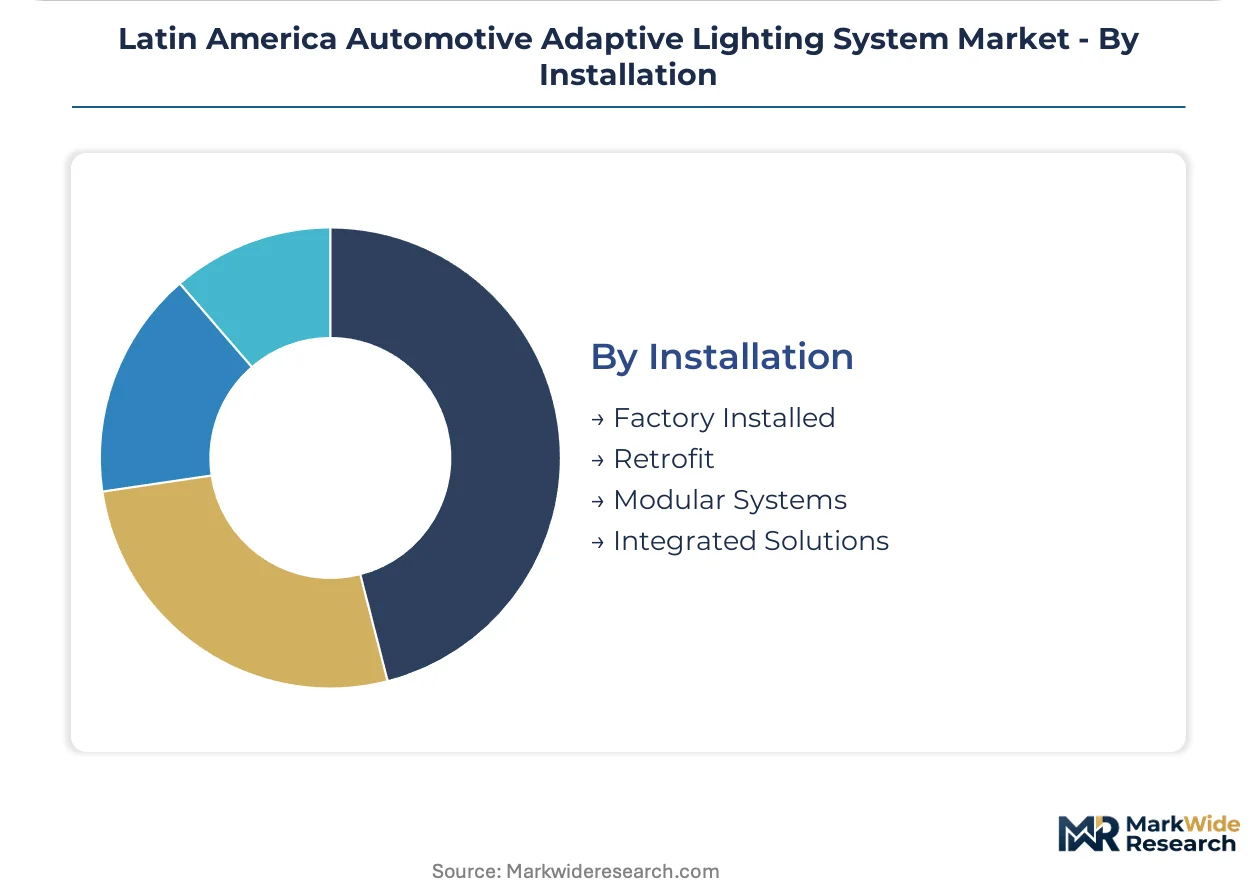
Adaptive lighting system segmentation reveals how technology tiers, installation channels, and supply chain positions distribute value across Latin American automotive production. Understanding these splits enables suppliers to align engineering investment with where specification authority actually concentrates.
Product Type:
Volume production favors established illumination technologies while premium platforms drive adoption of pixel-level beam modulation systems.
- Matrix LED:Arrays of individually addressable LEDs enable dynamic shadow zones around detected vehicles without full-beam dip. Brazilian premium sedan assemblers specify this configuration most aggressively for vehicles bound for domestic executive fleets and German-brand export programs.
- Dynamic Bending:Swiveling headlamp modules follow steering angle to illuminate curves before vehicle entry. Mexican assembly clusters serving Japanese OEM transplant facilities favor this technology for mid-segment SUV platforms where cost-positioning limits full matrix adoption.
- LED:Solid-state illumination with basic adaptive dimming functionality dominates fleet procurement specifications across São Paulo corporate lease operators.
- Laser:Coherent light amplification extends high-beam range beyond conventional LED throw, currently restricted to flagship German-brand imports due to CONTRAN homologation complexity.
Mature deployment sits with LED configurations. Newer deployment is concentrated in Matrix LED as semiconductor cost curves flatten.
Technology:
Hardware-centric beam management yields to software-defined architectures as OEMs prioritize calibration flexibility over discrete component specification.
- Adaptive Front Lighting:Camera-driven horizontal and vertical beam adjustment responds to oncoming traffic and road curvature. This architecture anchors current factory-installed penetration across Brazilian and Mexican vehicle platforms.
- Intelligent Control:Machine-vision algorithms predict illumination needs from navigation data and V2X inputs. German-brand OEMs operating in Querétaro specify this capability for vehicles destined for European markets where ECE regulation mandates predictive glare limitation.
- Automatic Beam Adjustment:Sensor-triggered high-beam activation without driver intervention satisfies CONTRAN minimum visibility thresholds for domestic-market vehicle type-approval.
- Advanced Signal Processing:Multi-camera fusion enables pedestrian and cyclist detection with targeted illumination. Regional engineering pools lack algorithm development depth, forcing import dependency for this capability.
Adaptive Front Lighting captures current volume. Intelligent Control is climbing the fastest as software-defined vehicle architectures proliferate.
End User:
Specification authority concentrates with entities controlling factory-installed integration rather than post-production channels.
- OEMs:Brand-holding vehicle manufacturers define adaptive lighting performance thresholds for platform-common export programs. German and Japanese OEMs operating Mexican transplant facilities exercise strongest specification control.
- Vehicle Assemblers:Contract manufacturing operations execute OEM-defined lighting configurations within local content compliance frameworks. Brazilian domestic assemblers balance CONTRAN mandates against import module cost exposure.
- Tier-1 Suppliers:Integrated headlamp system providers manage calibration protocol delivery to assembly line test equipment. HELLA and Valeo anchor these relationships through design accountability contracts.
- Aftermarket Providers:Independent service networks face calibration protocol barriers that restrict adaptive lighting to basic LED retrofits without dynamic beam functionality.
Factory-installed specification sits with OEMs and Vehicle Assemblers. Aftermarket deployment remains technically constrained.
Installation:
Integration depth during vehicle assembly determines calibration precision and regulatory compliance pathway.
- Factory Installed:Embedded calibration protocols during assembly line sequencing ensure CONTRAN and NOM compliance without post-production rework. This channel captures all Matrix LED and Intelligent Control deployment.
- Integrated Solutions:Headlamp modules pre-validated with vehicle electrical architecture reduce assembly complexity for Mexican export-oriented facilities.
- Modular Systems:Swappable lamp assemblies enable platform-variant flexibility without full electrical redesign, favored by Brazilian assemblers managing multiple OEM contracts.
- Retrofit:Post-production adaptive lighting installation faces homologation barriers and calibration equipment scarcity, limiting penetration to non-dynamic LED upgrades.
Factory Installed integration commands premium positioning. Retrofit channels face structural limitation from calibration protocol complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Semiconductor-grade gallium nitride substrates and rare-earth phosphor deposits anchor Latin American adaptive lighting supply chains to East Asian refining corridors. Regional module assembly concentrates where OEM transplant facilities cluster near export ports.
Brazil
São Paulo state assemblers drive Matrix LED specification for executive fleet procurement and German-brand export programs. CONTRAN mandates improved nighttime visibility thresholds through adaptive beam pattern validation in type-approval procedures. Campinas technology corridor hosts calibration equipment deployment for domestic OEM compliance testing.
Mexico
Querétaro and Guanajuato assembly clusters specify Intelligent Control architectures for vehicles destined for US and European markets. NOM standards draft amendments reference camera-based glare-limitation performance thresholds matching ECE baselines. Puebla transplant facilities anchor high-specification headlamp module integration for German-brand OEMs.
Argentina
Buenos Aires metropolitan fleet operators prioritize total-cost-of-ownership metrics including bulb-life extension for executive vehicle categories. The national automotive regulator maintains type-approval frameworks referencing ECE technical expectations for adaptive beam systems. Córdoba industrial corridor hosts limited module assembly serving Mercosur platform commonality.
Colombia
Bogotá and Medellín premium SUV export capacity creates new specification pull for advanced lighting systems targeting Andean market positioning. The national standards body aligns headlamp performance thresholds with emerging CONTRAN and NOM regulatory trajectories. Eastern savanna assembly zones concentrate contract manufacturing for regional OEM programs.
Chile
Santiago corporate lease operators concentrate procurement authority with centralized technical teams specifying adaptive lighting across executive categories. The national automotive regulator validates import adaptive systems against UN ECE baselines for type-approval efficiency. Valparaíso port logistics support module import distribution to regional assemblers.
Latin America Automotive Adaptive Lighting System Market Competitive Landscape
Global majors compete with regional champions across calibration protocol delivery and design accountability contracting. Market structure consolidates toward fewer Tier-1 partnerships as assemblers seek single-source responsibility for complex mechatronic headlamp platforms. Three archetypes dominate: integrated system providers with lamp engineering heritage, mechatronic platform specialists reducing assembly complexity, and manufacturing footprint extenders serving transplant OEM facilities. Competitive moves concentrate on strategic partnerships for software-defined beam management and geographic expansion through regional module assembly.
Within the integrated system tier, HELLA KGaA Hueck & Co and Valeo Group exemplify design accountability archetypes anchoring high-specification OEM programs. Koito Manufacturing Co Ltd occupies a position representing manufacturing footprint extension for Japanese OEM transplant facilities. These three entities sit within the supplier base referenced in the analysis, with their positioning reflecting broader industry patterns of heritage-based specification control versus platform integration specialization.
| Leading Market Players |
|---|
| HELLA KGaA Hueck & Co |
| Valeo Group |
| Hyundai Mobis |
| Koito Manufacturing Co Ltd |
| Magneti Marelli SpA |
| Stanley Electric Co Ltd |
| Osram |
| Texas Instruments |
| ZKW Group |
| Others |
Supply & Pricing Matrix
Matrix LED semiconductor cost curves flattening across East Asian foundries simultaneously compresses module pricing tiers and concentrates Tier-1 supplier power around calibration protocol ownership. Brazilian CONTRAN compliance costs and Mexican export-platform specifications feed into divergent pricing structures that reward design accountability contracting over component transactionalism.
Pricing Analysis
Extended warranty and calibration-service bundling distinguishes factory-installed Matrix LED configurations from unbundled LED retrofit offerings. Three-tier pricing structure across premium, standard, and economy levels separates Intelligent Control architectures with predictive beam management from basic Adaptive Front Lighting and non-adaptive LED replacements. Price differentiation stems from certification grade against ECE baselines and volume scale through OEM platform-common programs. Pricing pressure stems from semiconductor commoditization in pixel-driver chips. Fleet procurement teams at São Paulo corporate lease operators exhibit highest price sensitivity; German-brand OEM transplant facilities in Querétaro show lowest sensitivity due to export-market specification rigidity.
Supply Chain Analysis
Gallium nitride substrate supply rests on Japanese and Taiwanese specialty semiconductor producers, while rare-earth phosphor refining concentrates in Chinese processing corridors. LED die fabrication draws from South Korean and Chinese foundries, with camera-based scene analysis hardware sourcing from German and Japanese machine-vision specialists. Single-source vulnerability runs through East Asian gallium nitride wafer supply. Distribution runs through Puebla and Campinas module assembly hubs serving OEM transplant corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined beam management is displacing hardware-centric lamp engineering, compressing traditional supplier value capture and elevating embedded software competency as the primary competitive moat.
For Market Incumbents: To counter embedded software competency scarcity in regional engineering pools, Tier-1 suppliers should anchor design accountability contracts with backward integration into machine-vision algorithm development. Capacity addition in São Paulo state calibration equipment deployment defends against import-dependent module supply vulnerabilities.
For New Entrants and Emerging Players: Direct-to-fleet digital procurement channels offer lowest-friction entry for mid-segment LED configurations without Matrix complexity. Colombian Andean Corridor premium SUV assembly represents most penetrable geography. Calibration-protocol licensing to Brazilian domestic assemblers provides go-to-market leverage without full Tier-1 capital burden.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated mechatronic platform specialists seeking Latin American manufacturing footprint. Long-term viability favors suppliers with captive software architecture control over hardware-assembly operations. Watch CONTRAN local content threshold announcements as inflection signal for regional supply geography restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Beam Architecture Investment | Intelligent Control platforms reduce hardware refresh cycles for Mexican export programs. |
| Regional Module Assembly Footprint | Campinas and Puebla hubs capture Brazilian Inovação Automotiva incentive flows. |
| Calibration Protocol Standardization | Unified test equipment reduces capital fragmentation across multi-OEM contracts. |
| V2X-Telematics Integration Partnership | Predictive road-illumination enables premium positioning for Querétaro export vehicles. |
| Machine-Vision Algorithm Licensing | Foreign R&D center dependency creates acquisition targets for competency-hungry incumbents. |
Research Methodology
Independent corroboration across OEM platform engineering directors, Tier-1 supplier procurement leads, and Brazilian regulatory affairs specialists underwrites the qualitative findings. Primary interviews with aftermarket distribution network managers and Mexican transplant facility operations heads combined with secondary validation from ANFAVEA production databases, NOM regulatory filings, and vehicle registration data from IHS Markit. Bottom-up module shipment analysis triangulates against top-down OEM platform specification tracking.
Rate-of-change decomposition separates volume growth from value-per-vehicle content expansion across the projection horizon. Segmentation dimensions modeled include product type tier, technology architecture, installation channel, and regional production cluster alignment. CAGRs derive from fitted growth curves against historical technology adoption S-cycles. Forecast inputs incorporate CONTRAN mandate implementation timelines and semiconductor cost curve trajectories for pixel-driver components.
The model holds under stable regulatory enforcement and continued OEM export-platform commonality; deviation in local content threshold announcements or ECE-NOM regulatory divergence would shift supply geography assumptions. Forecasts reflect documented assumptions around technology transition pacing and import tariff stability. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Decorative Interior Trim Market
Automotive Interior & Exterior
Automotive Inside Rearview Mirrors (IRVM) Market
Automotive Interior & Exterior
Automotive Air Suspension System Market
Automotive Interior & Exterior
Railway Interior Lighting Market
Automotive Interior & Exterior
Automotive HVAC Market
Automotive Interior & Exterior
Automotive Outside Rearview Mirrors (ORVM) Market
Automotive Interior & Exterior
Global on Highway Vehicle Lighting Market
Automotive Interior & Exterior
Automotive Clear Coat Paint Market
Automotive Interior & Exterior
Automotive Digital Rear View Mirror Market
Automotive Interior & Exterior
Automotive Sound Proofing Material Market
Automotive Interior & Exterior
Automotive Head Up Display (HUD) Market
Automotive Interior & Exterior
Automotive Expanded Polypropylene (EPP) Foam Market
Automotive Interior & Exterior
Automotive Ventilated Seats Market
Automotive Interior & Exterior
Automotive Seats Market
Automotive Interior & Exterior
Automotive Plastic Interior Trims Market
Automotive Interior & Exterior
Fog Free Mirrors Market