
 Laser Headlight Market | 2026-2036
Laser Headlight Market Size, Share, and Industry Trends Forecast 2026-2036
Laser Headlight Market Outlook
Germany is reconfiguring European laser headlight supply chains through expanded cleanroom production near Stuttgart and Ingolstadt. Hella GmbH & Co. KGaA leverages its captive semiconductor laser sourcing to control module cost curves. OSRAM Licht AG sustains dominance in blue-laser diode substrates through vertical ownership of gallium nitride epitaxy. Continental AG anchors its position with integrated adaptive-beam software stacks that process real-time traffic data.
Laser headlights generate coherent, monochromatic blue light converted to broad-spectrum white via cerium-doped yttrium aluminum garnet phosphors, achieving luminous intensities exceeding 600 lux at 600-meter throw distances for high-speed highway safety. Diode laser technology occupies the dominant revenue position due to mature epitaxial growth yields and automotive-qualified package reliability. Solid-state laser architectures represent the fastest-expanding segment as OEMs pursue phosphor-free RGB mixing for tunable color temperature. Passenger vehicles concentrate the majority of unit demand, though heavy machinery applications in open-pit mining are emerging for glare suppression in dust-heavy environments.
NHTSA Federal Motor Vehicle Safety Standard 108 and the EU General Safety Regulation govern beam pattern geometry and glare limits, forcing suppliers to certify each adaptive mode through homologation cycles. ECE R149 addenda now explicitly address laser source classification and eye-safety interlock requirements for pedestrian exposure scenarios. Stakeholders must monitor divergence between U.S. self-certification and EU type-approval paradigms, as regulatory misalignment threatens platform engineering costs for global vehicle programs.
Market Dynamics
Factory-fit adoption by German and Japanese premium passenger vehicle OEMs is compressing module cost curves as diode laser architectures displace conventional LED headlamp systems, forcing supply chain reconfiguration around cleanroom production clusters.
Growth Catalysts
- NHTSA Federal Motor Vehicle Safety Standard 108:Updated beam-pattern regulations in the United States are mandating glare-free adaptive systems, compelling OEMs to certify laser headlight platforms for highway safety compliance.
- Open-pit mining machinery:Heavy equipment operators in dust-heavy extraction environments are adopting laser headlights for superior glare suppression compared to conventional high-intensity discharge lamps.
- Phosphor-free RGB mixing:Solid-state laser architectures enabling tunable color temperature are attracting OEM engineering investment for next-generation adaptive beam systems.
Market Restraints
- Gallium nitride epitaxy concentration:Vertical ownership of blue-laser diode substrate production by a limited supplier base creates input cost volatility and supply security exposure for module assemblers.
- ECE R149 homologation cycles:EU type-approval requirements for each adaptive mode extend certification timelines and inflate platform engineering costs for global vehicle programs.
- LED thermal management advances:Improved lumen-per-watt efficiency in advanced LED architectures presents a credible substitute threat for mid-market vehicle segments.
Strategic Opportunities
- EU General Safety Regulation tailwind:Mandated advanced driver-assistance system integration creates regulatory pull for adaptive laser headlight adoption across European premium vehicle fleets.
- Heavy machinery aftermarket:Retrofit demand from mining and construction equipment operators in Australia represents an underpenetrated channel for glare-suppression lighting systems.
- Real-time traffic data convergence:Integration of adaptive-beam software stacks with vehicle-to-infrastructure communication protocols is opening new value capture in intelligent highway systems.
Industry Challenges
- Automotive-qualified package reliability:Thermal cycling and vibration resistance requirements for diode laser modules demand specialized cleanroom assembly expertise that concentrates in Stuttgart and Ingolstadt corridors.
- Divergent certification paradigms:NHTSA self-certification and EU type-approval misalignment forces duplicate homologation investment for global platform engineering teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laser Headlight Market |
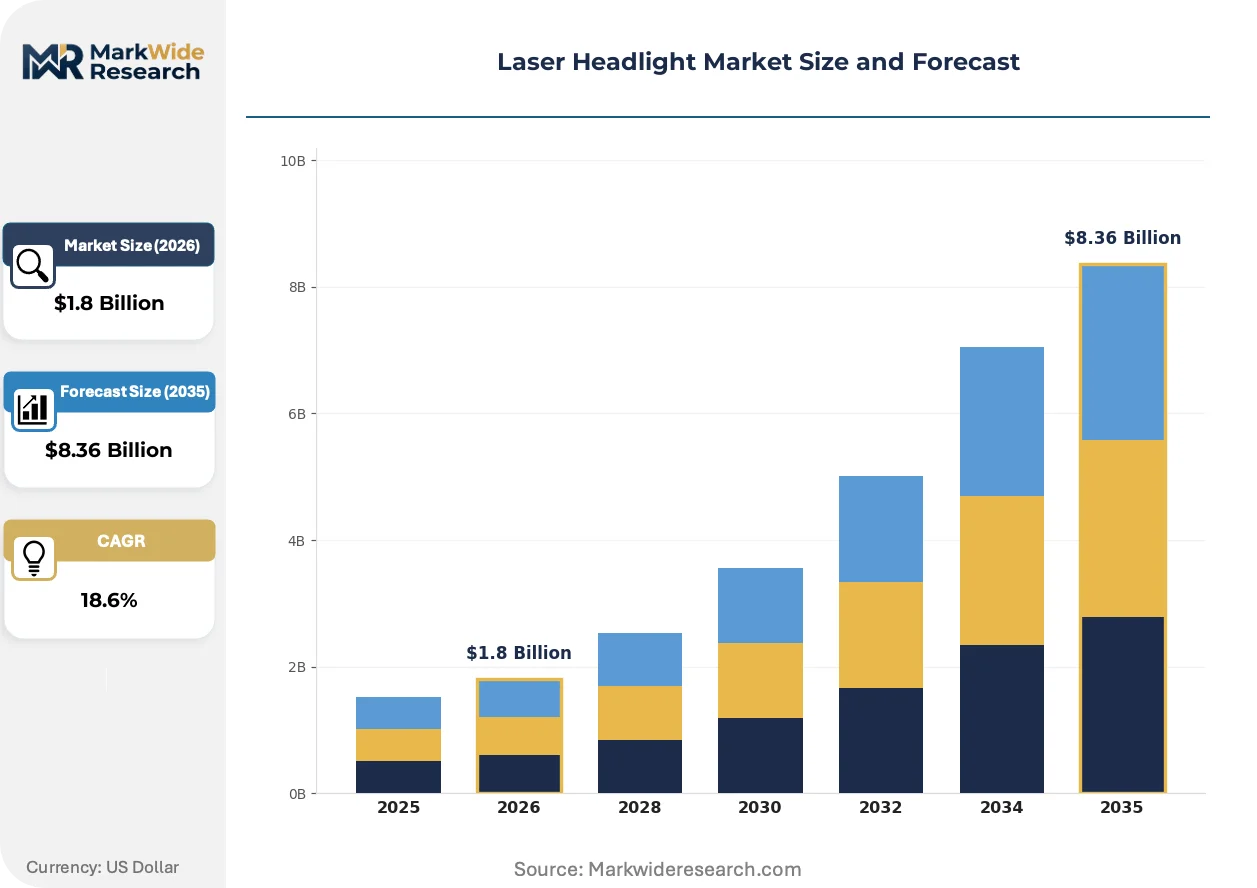
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Diode Laser, Fiber Laser, Solid-State Laser, Organic Laser Application: Passenger Vehicles, Commercial Vehicles, Motorcycles, Heavy Machinery End User: Vehicle Manufacturers, Aftermarket Suppliers, OEMs, Tier-1 Suppliers Feature: Adaptive Lighting, Daytime Running Light, High Beam Assistance, Energy Efficiency |
| Companies Covered | Hella GmbH & Co. KGaA, Continental AG, Valeo S.A., Stanley Electric Co., Ltd., ZKW Group, Koito Manufacturing Co., Ltd., Robert Bosch GmbH, Hyundai Mobis, OSRAM Licht AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laser Headlight Market Strategic Shifts
Active reshaping of the laser headlight market centers on three vectors: coherent light source evolution, tightening safety regulation, and procurement model compression toward captive semiconductor sourcing.
Diode laser technology is hybridizing with solid-state architectures as OEMs pursue phosphor-free RGB mixing for tunable color temperature. German luxury manufacturers are accelerating engineering validation of these dual-source systems for adaptive highway beams. This convergence is compressing the traditional technology refresh cycle and forcing module suppliers to maintain parallel production lines.
ECE R149 addenda now explicitly address laser source classification and eye-safety interlock requirements for pedestrian exposure scenarios. The regulation forces suppliers to redesign optical enclosures and software-controlled beam cutoff mechanisms. European premium OEMs are responding by co-locating homologation testing with module assembly to compress certification timelines.
Buyer concentration among Stuttgart and Ingolstadt manufacturing corridors is consolidating procurement leverage around captive semiconductor laser sourcing. Tier-1 suppliers are displacing spot-market component purchasing with backward integration into epitaxial growth partnerships. This shift is most visible in German supply chains, where module assemblers now negotiate multi-year wafer supply agreements directly with gallium nitride substrate manufacturers.
Laser Headlight Market Segmentation
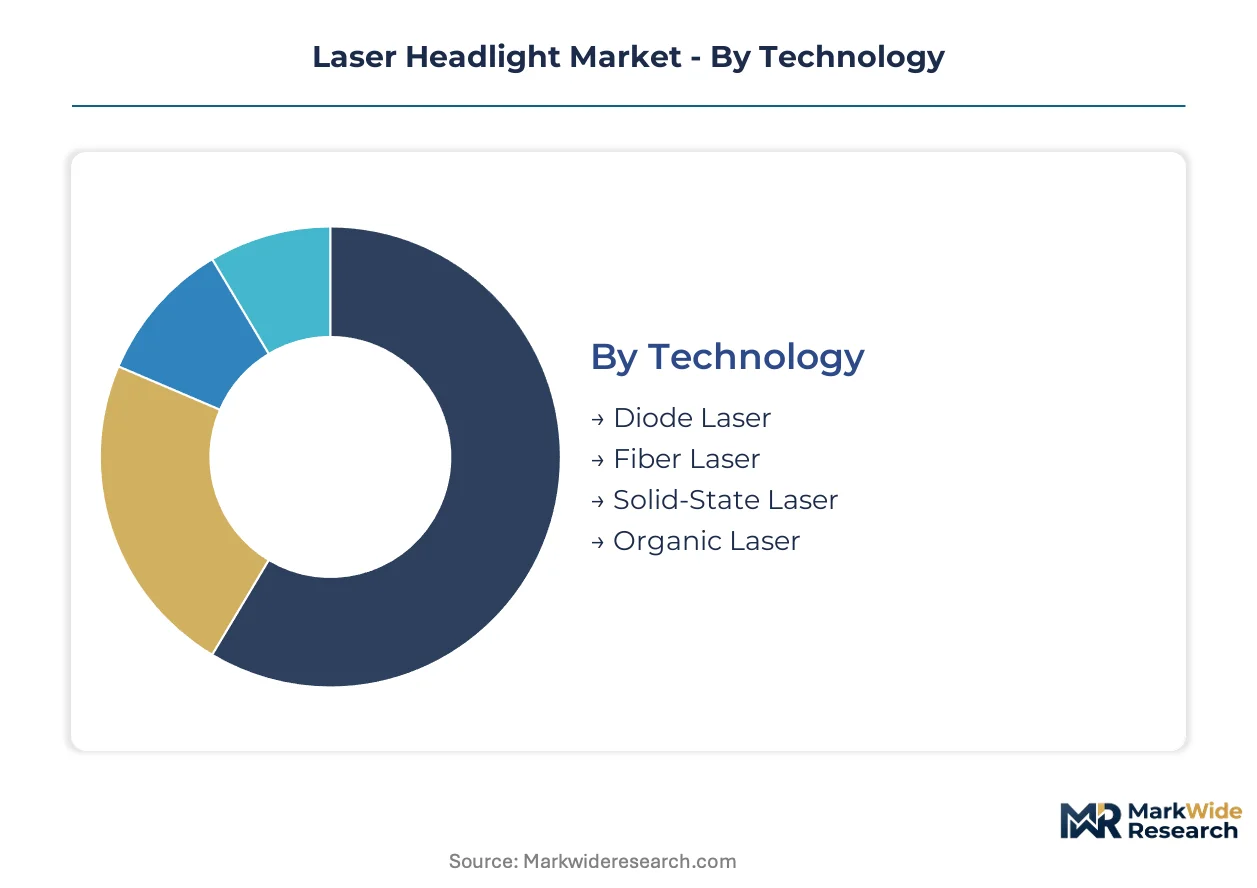
Laser headlight segmentation reveals divergent refresh cycles across technology tiers. Diode laser platforms mature on automotive-grade timelines while solid-state architectures compress development cadences for next-generation adaptive systems.
Technology:
Cycle times vary dramatically: diode laser modules refresh every 4-5 years against automotive platform cycles, while solid-state and organic laser development compresses to 18-24 month validation windows.
- Diode Laser:Coherent blue light generation through gallium nitride epitaxy, converted to white via cerium-doped YAG phosphors. German luxury OEMs in Stuttgart and Ingolstadt corridors concentrate factory-fit demand as diode architectures displace conventional LED headlamps for highway beam intensity exceeding 600 lux at 600-meter throw distances.
- Solid-State Laser:Phosphor-free RGB mixing enables tunable color temperature without wavelength conversion losses. Japanese premium manufacturers are accelerating engineering validation for adaptive highway beams, compressing traditional technology refresh cycles and forcing parallel production line investments.
- Fiber Laser:Rare-earth-doped silica fiber amplification delivers high beam quality with thermal stability. Mining equipment operators in Australia specify fiber architectures for dust-heavy open-pit extraction environments requiring superior glare suppression.
- Organic Laser:Solution-processable organic semiconductor gain media enable unconventional form factors. Early-stage automotive qualification focuses on flexible substrate integration for niche concept vehicle programs.
Diode laser dominates installed base. Solid-state laser is where expansion concentrates.
Application:
Volume tiers separate factory-fit automotive from retrofit industrial, with margin structures inversely correlated to shipment scale.
- Passenger Vehicles:Premium German and Japanese OEMs drive unit demand through adaptive beam integration with advanced driver-assistance systems. NHTSA Federal Motor Vehicle Safety Standard 108 compliance mandates glare-free certification for highway safety.
- Heavy Machinery:Open-pit mining operators in Australia adopt laser headlights for dust-heavy extraction environments. Superior glare suppression versus high-intensity discharge lamps commands aftermarket premium pricing.
- Commercial Vehicles:Long-haul freight operators specify adaptive high beams for nighttime highway safety. ECE R149 homologation requirements extend certification timelines for EU type-approval.
- Motorcycles:Limited adoption concentrates in premium touring segments. Compact packaging constraints favor diode laser miniaturization over fiber or solid-state alternatives.
Passenger vehicles capture volume concentration. Heavy machinery commands margin expansion.
End User:
Procurement authority determines specification control, with captive semiconductor sourcing reshaping supplier relationships.
- Tier-1 Suppliers:Module assemblers co-locate cleanroom production with headlamp integration lines in German manufacturing corridors. Multi-year wafer supply agreements with gallium nitride substrate manufacturers displace spot-market component purchasing.
- Vehicle Manufacturers:Stuttgart and Ingolstadt premium OEMs consolidate procurement leverage through backward integration into epitaxial growth partnerships. Engineering teams specify diode laser architectures for platform standardization.
- OEMs:Original equipment manufacturers manage homologation testing co-location with module assembly to compress ECE R149 certification timelines for European market entry.
- Aftermarket Suppliers:Australian mining and construction equipment operators represent underpenetrated retrofit demand for glare-suppression lighting systems.
Tier-1 suppliers dominate specification control. Aftermarket channels present expansion opportunity.
Feature:
Regulatory mandates separate baseline compliance from value-added differentiation, with software integration determining competitive position.
- Adaptive Lighting:Real-time beam pattern reshaping via traffic data processing. Continental AG anchors market position with integrated software stacks that process vehicle-to-infrastructure communication protocols.
- High Beam Assistance:Automated glare-free operation through camera-based oncoming vehicle detection. EU General Safety Regulation mandates advanced driver-assistance system integration across European premium vehicle fleets.
- Energy Efficiency:Lumen-per-watt optimization competes with advanced LED thermal management advances threatening substitution in mid-market segments.
- Daytime Running Light:Reduced intensity operation for visibility compliance. Lower specification tier faces cost pressure from improved LED efficiency.
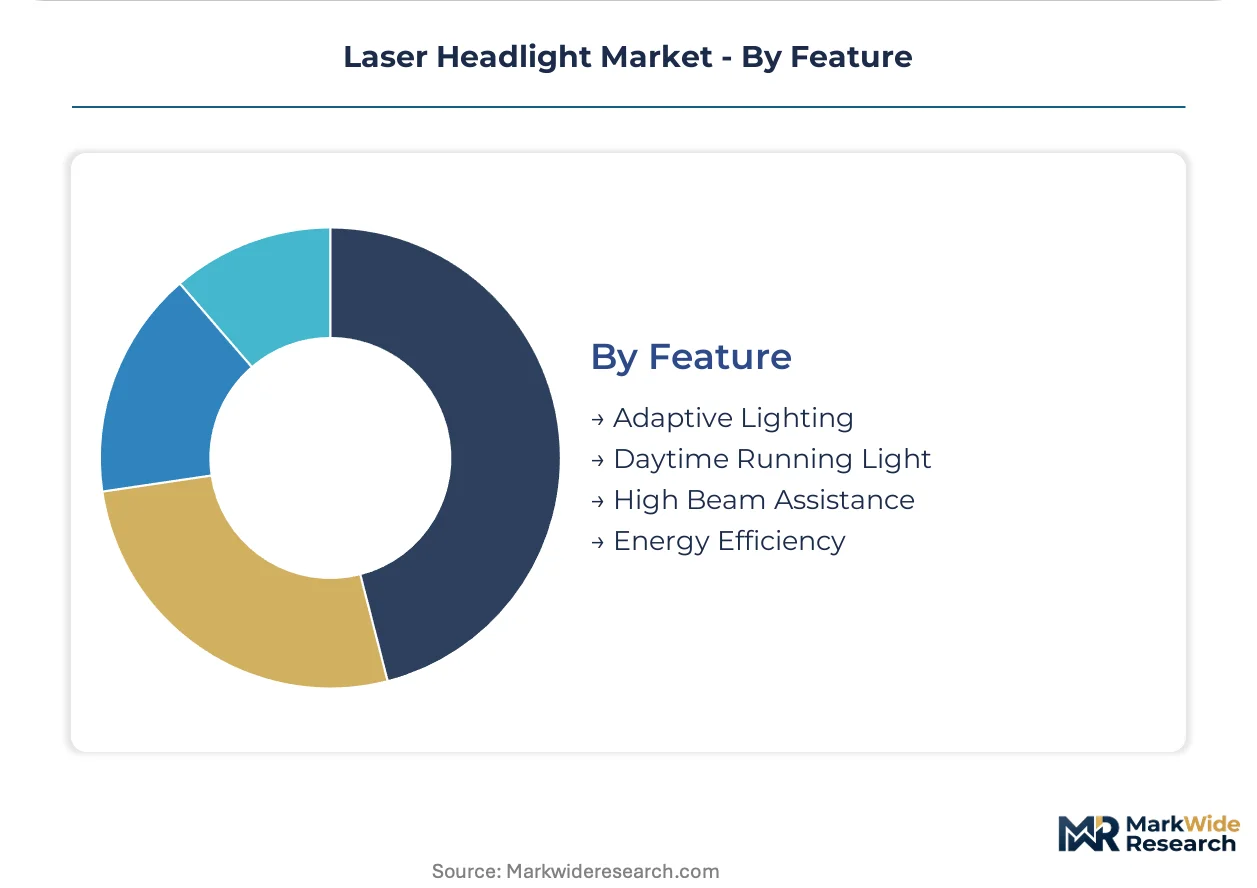
Adaptive lighting dominates engineering investment. High beam assistance is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diode laser module assembly clusters in German manufacturing corridors around Stuttgart and Ingolstadt, with Japanese precision optics producers and Australian mining equipment operators extending the geographic footprint.
Germany
Stuttgart and Ingolstadt manufacturing corridors concentrate cleanroom production for premium OEM factory-fit programs. KBA homologation requirements under ECE R149 mandate eye-safety interlock certification for pedestrian exposure scenarios. Bavarian Tier-1 suppliers negotiate multi-year gallium nitride wafer agreements directly with substrate manufacturers.
Japan
Premium passenger vehicle manufacturers accelerate solid-state laser validation for phosphor-free RGB adaptive beams. METI industrial standards govern automotive-qualified package reliability for thermal cycling resistance. Nagoya-area precision optics producers co-locate module assembly with headlamp integration lines.
United States
NHTSA Federal Motor Vehicle Safety Standard 108 compliance mandates glare-free adaptive system certification for highway safety. Long-haul freight operators specify laser high beams for nighttime visibility in western interstate corridors. Michigan-based engineering teams manage duplicate homologation investment for divergent EU type-approval paradigms.
Australia
Open-pit mining operators in Western Australia specify fiber laser architectures for dust-heavy extraction environments. TGA equipment safety frameworks govern aftermarket retrofit certification for glare-suppression lighting systems. Queensland construction equipment channels represent underpenetrated demand for heavy machinery retrofit.
South Korea
Automotive electronics producers develop integrated adaptive-beam software stacks for vehicle-to-infrastructure communication. MFDS automotive component standards address laser source classification for export market compliance. Seoul Capital Area module assemblers source blue-laser diode substrates through captive semiconductor partnerships.
Laser Headlight Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream controlling epitaxial growth and phosphor conversion. The supplier base concentrates around German and Japanese automotive electronics conglomerates with captive semiconductor sourcing capabilities. Three archetypes dominate: integrated Tier-1 module assemblers, gallium nitride substrate manufacturers, and adaptive-beam software developers. Competitive dynamics center on backward integration into wafer supply agreements and co-location of homologation testing with assembly operations.
Among German automotive suppliers, Hella GmbH & Co. KGaA and Continental AG exemplify the integrated Tier-1 archetype through their positions spanning module assembly and software integration. OSRAM Licht AG represents the substrate-specialist tier with its vertical ownership of gallium nitride epitaxy capabilities. These three entities anchor the competitive structure by controlling critical input cost curves and certification timelines.
| Leading Market Players |
|---|
| Hella GmbH & Co. KGaA |
| Continental AG |
| Valeo S.A. |
| Stanley Electric Co., Ltd. |
| ZKW Group |
| Koito Manufacturing Co., Ltd. |
| Robert Bosch GmbH |
| Hyundai Mobis |
| OSRAM Licht AG |
| Others |
Value Chain & Pricing Dynamics
Rotterdam-Antwerp corridor freight costs transmit directly into module pricing differentials, amplifying the leverage of Stuttgart and Ingolstadt cleanroom clusters while compressing margins for spot-market substrate purchasers. ECE R149 homologation investment requirements stratify pricing across certified and uncertified supplier tiers, forcing buyers to absorb premium positioning for pedestrian eye-safety interlock compliance.
Pricing Analysis
ECE R149 dictates the pricing tier structure across the laser headlight market, separating certified adaptive-beam platforms from baseline diode configurations. Three-tier pricing structure across premium, standard, and economy levels reflects homologation depth, with NHTSA self-certification pathways offering cost relief for US-bound programs. Cost compression in mid-market LED-competitive segments is intensifying because advanced thermal management narrows the performance gap. Fleet procurement teams at long-haul freight operators exhibit highest price sensitivity, while Stuttgart premium OEMs prioritize specification control over unit economics.
Supply Chain Analysis
Tariff exposure between China and Germany dominates supply chain risk calculus for gallium nitride substrate flows. Module assembly draws from Germany, Japan, and South Korea for automotive-qualified packaging, with blue-laser diode production anchored in Bavarian epitaxial growth partnerships. Single-source vulnerability concentrates in cerium-doped YAG phosphor conversion materials. Distribution runs through Tier-1 supplier co-location with headlamp integration lines, displacing traditional component spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Laser headlight adoption sits in early-cycle expansion, with EU General Safety Regulation mandates creating structural pull for adaptive beam integration across European premium fleets.
For Market Incumbents: Insulate module cost positions through captive gallium nitride wafer agreements that neutralize substrate price volatility. Accelerate cleanroom capacity addition in Ingolstadt corridors to compress ECE R149 certification timelines. LED thermal management advances threaten substitution in mid-market segments; counter with software-defined beam differentiation. For New Entrants and Emerging Players: Australian mining equipment aftermarket represents the most penetrable white-space target for fiber laser retrofit demand. Queensland construction channels offer secondary entry path with lower homologation barriers than automotive OEM programs. Pursue TGA equipment safety certification as the primary go-to-market anchor, leveraging dust-heavy extraction use cases for glare-suppression value demonstration. For Investors and Strategic Acquirers: ECE R149 addenda implementation reshapes the acquisition landscape toward homologation-capable module assemblers. Long-term viability favors entities with backward integration into epitaxial growth and parallel solid-state laser validation pipelines. Watch NHTSA beam-pattern rulemaking alignment with EU standards as the signal for global platform engineering cost normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year Wafer Supply Agreement | Captive gallium nitride sourcing locks in substrate cost curves against spot-market volatility. |
| Cleanroom Co-Location Expansion | Stuttgart corridor proximity compresses ECE R149 homologation timelines for European OEM programs. |
| Solid-State Laser Validation Investment | Phosphor-free RGB mixing pipelines position for next-generation adaptive highway beam specifications. |
| Vehicle-to-Infrastructure Software Integration | Continental AG-type adaptive-beam stacks capture intelligent highway system value pools. |
| Australian Aftermarket Channel Development | TGA-certified retrofit programs access mining operator premium pricing for glare-suppression systems. |
Study Parameters
A standing panel of Tier-1 supplier procurement directors, OEM platform engineers, and KBA homologation specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from vehicle production databases, IHS Markit registration data, SEC automotive supplier filings, and ECE R149 regulatory addenda. Bottom-up module shipment tallies triangulated against top-down premium vehicle content-per-vehicle estimates.
Scenario-bracketing framed analytical development across the projection horizon, with high-low adoption paths for solid-state laser penetration. Segmentation dimensions modeled include technology tier, vehicle class, OEM premium tier, and regional regulatory cluster. CAGRs derived from fitted diffusion curves against historical LED headlamp substitution patterns, with diode laser yield improvement curves and phosphor cost trajectories as core forecast inputs.
Practitioners should monitor NHTSA-EU regulatory divergence, gallium nitride substrate supply security, and LED lumen-per-watt efficiency thresholds for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive OEM Interior Coatings Market
Automotive Interior & Exterior
Automotive Seats Market
Automotive Interior & Exterior
Automotive Lighting Molds Market
Automotive Interior & Exterior
Europe Automotive Wrap Films Market
Automotive Interior & Exterior
United States Car Bumper Guard Market
Automotive Interior & Exterior
Automotive Heated Steering Wheel Market
Automotive Interior & Exterior
Automotive Smart Window Market
Automotive Interior & Exterior
Capacitive Touch Switch Panels for Vehicle Interiors Market
Automotive Interior & Exterior
Automotive Energy Absorption (EA) Pads Market
Automotive Interior & Exterior
Decorative Car Accessories Market
Automotive Interior & Exterior
Paint Protection Film Market
Automotive Interior & Exterior
Automotive Backlight Moldings Market
Automotive Interior & Exterior
Global Automotive Power Sliding Door Market
Automotive Interior & Exterior
Automotive Ambient Lighting Market
Automotive Interior & Exterior
Automotive Overhead Console Market
Automotive Interior & Exterior
Automotive Windshield Market