
 Automotive Energy Absorption (EA) Pads Market | 2026-2036
Automotive Energy Absorption (EA) Pads Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Energy Absorption (EA) Pads Market Analytics
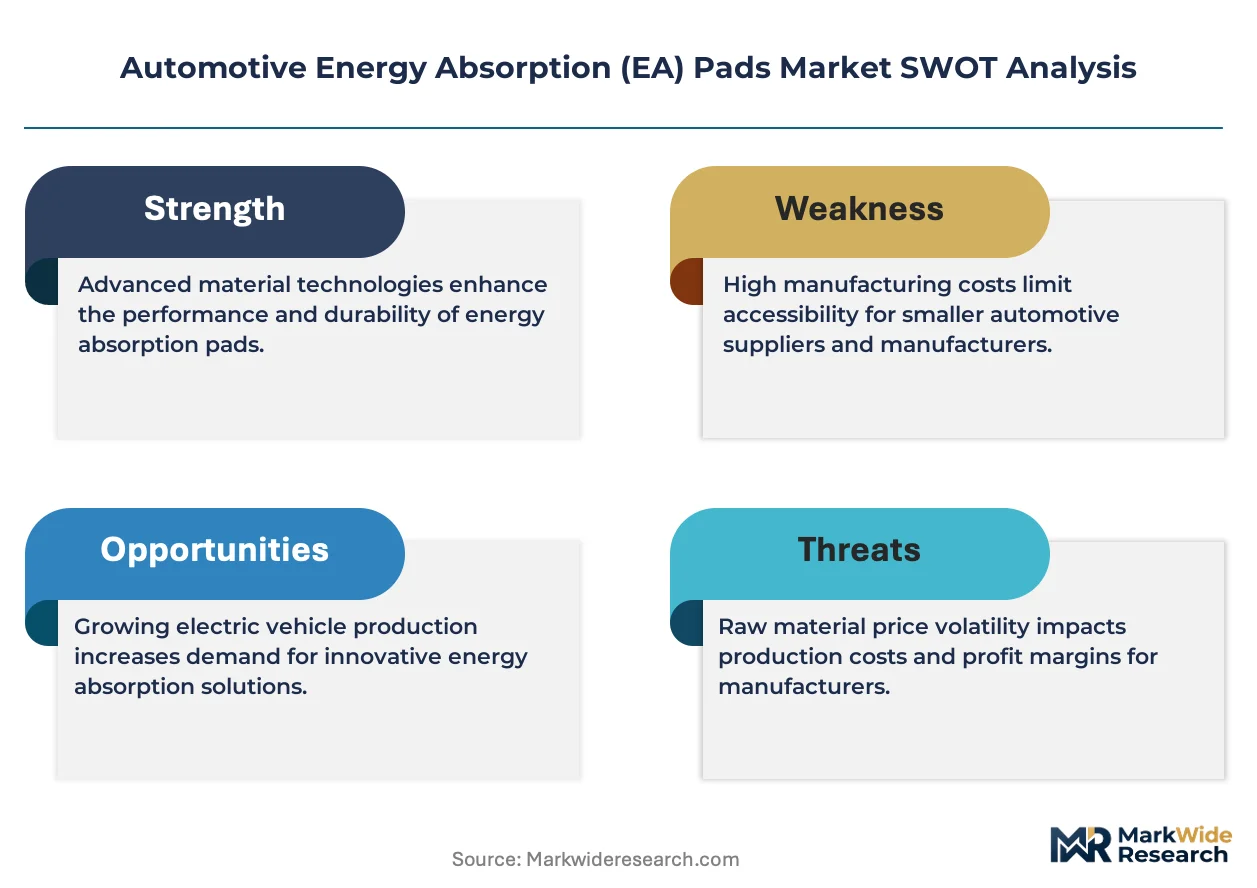
Automotive polymer engineering talent scarcity is redrawing competitive boundaries in energy absorption component supply. Bridgestone Corporation leverages its tire-to-pad materials science crossover to sustain formulation leadership in aramid-reinforced composites. The Oakwood Group anchors North American production capacity through vertically controlled foam fabrication facilities. THIEME GmbH & Co. KG dominates European precision molding for pedestrian protection systems, occupying a defensible niche in geometrically complex EA architectures.
Automotive Energy Absorption Pads are engineered cellular or solid structures—typically expanded polypropylene, polyurethane, or rubber-blend matrices with densities between 20 and 200 kg/m³—designed to convert kinetic impact energy into controlled deformation and heat dissipation during collision events. Compression molding remains the dominant fabrication route for high-volume bumper beam inserts, while injection molding gains share in intricate A-pillar and door trim applications where dimensional tolerance below 0.5 mm is required. Foam products command the largest volume share due to their cost-positioning in mass-market vehicle programs, though composite segments are expanding fastest as OEMs pursue mass reduction targets without sacrificing crash performance. Tier-1 Suppliers represent the most concentrated buyer channel, capturing direct engineering collaboration and multi-year supply agreements that lock out smaller competitors.
NHTSA maintains FMVSS 581 bumper integrity and pedestrian protection standards that mandate specific head-impact criteria for hood and fender assemblies, while EPA guidelines on volatile organic compound emissions constrain adhesive bonding processes used in multi-layer pad construction. The EU's General Safety Regulation and CE marking requirements for automotive components create parallel compliance obligations for suppliers serving European vehicle assemblers. Stakeholders must monitor evolving battery enclosure protection standards for electric vehicles, where EA pad integration into pack housings introduces new load-case specifications and thermal runaway containment requirements that will reshape material selection criteria and testing protocols.
Market Dynamics
Electric vehicle platform architectures are forcing a fundamental redesign of energy absorption pad placement and performance specifications, as battery enclosure protection introduces multi-axis load cases that legacy bumper-centric designs cannot satisfy.
Growth Catalysts
- NHTSA FMVSS 581 pedestrian protection mandates:Head-impact criteria for hood and fender assemblies compel OEMs to redesign front-end structures, expanding addressable pad volume per vehicle platform.
- Expanded polypropylene foam density tuning:Advanced bead-foam processing enables 15-40% mass reduction versus conventional polyurethane while maintaining compression-set performance, accelerating adoption in mass-market electric vehicle programs.
- German OEM engineering integration:BMW, Mercedes-Benz, and Volkswagen are embedding multi-material EA architectures into vehicle development cycles earlier, extending supplier involvement from 24 to 48 months pre-production.
Market Restraints
- Petrochemical feedstock volatility:Polypropylene and polyurethane precursor costs fluctuate with naphtha and propylene oxide pricing, compressing formulation margins for non-integrated compounders.
- European molding capacity concentration:Precision geometric molding for complex pedestrian protection systems clusters in southern Germany and northern Italy, creating geographic supply risk for programs requiring sub-0.5mm dimensional tolerance.
- Adhesive bonding regulatory friction:EPA volatile organic compound emission limits constrain multi-layer pad lamination processes, forcing capital-intensive solvent-free bonding equipment upgrades.
Strategic Opportunities
- India domestic vehicle production expansion:Maruti Suzuki and Tata Motors are localizing crash-structure engineering, creating opening for pad suppliers with BIS-certified testing capabilities and in-country compounding partnerships.
- Battery enclosure thermal runaway containment:EA pad integration into pack housings for electric vehicles introduces fire-resistant foam specifications that command 40-60% price premiums over conventional grades.
- Japan METI carbon-neutral vehicle roadmap:Biobased polyol feedstocks for polyurethane foams receive preferential procurement weighting in supplier scorecards, favoring compounders with certified renewable content.
Industry Challenges
- Polymer crash-simulation expertise scarcity:Finite element modeling talent for hyperelastic material behavior under dynamic strain rates concentrates at Tier-1 suppliers and specialized consultancies, limiting second-tier pad manufacturers' direct OEM access.
- Multi-physics certification timelines:Battery enclosure EA pads must simultaneously satisfy NHTSA crashworthiness, UL 2596 thermal propagation, and OEM-specific vibration durability protocols, extending validation cycles to 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Energy Absorption (EA) Pads Market |
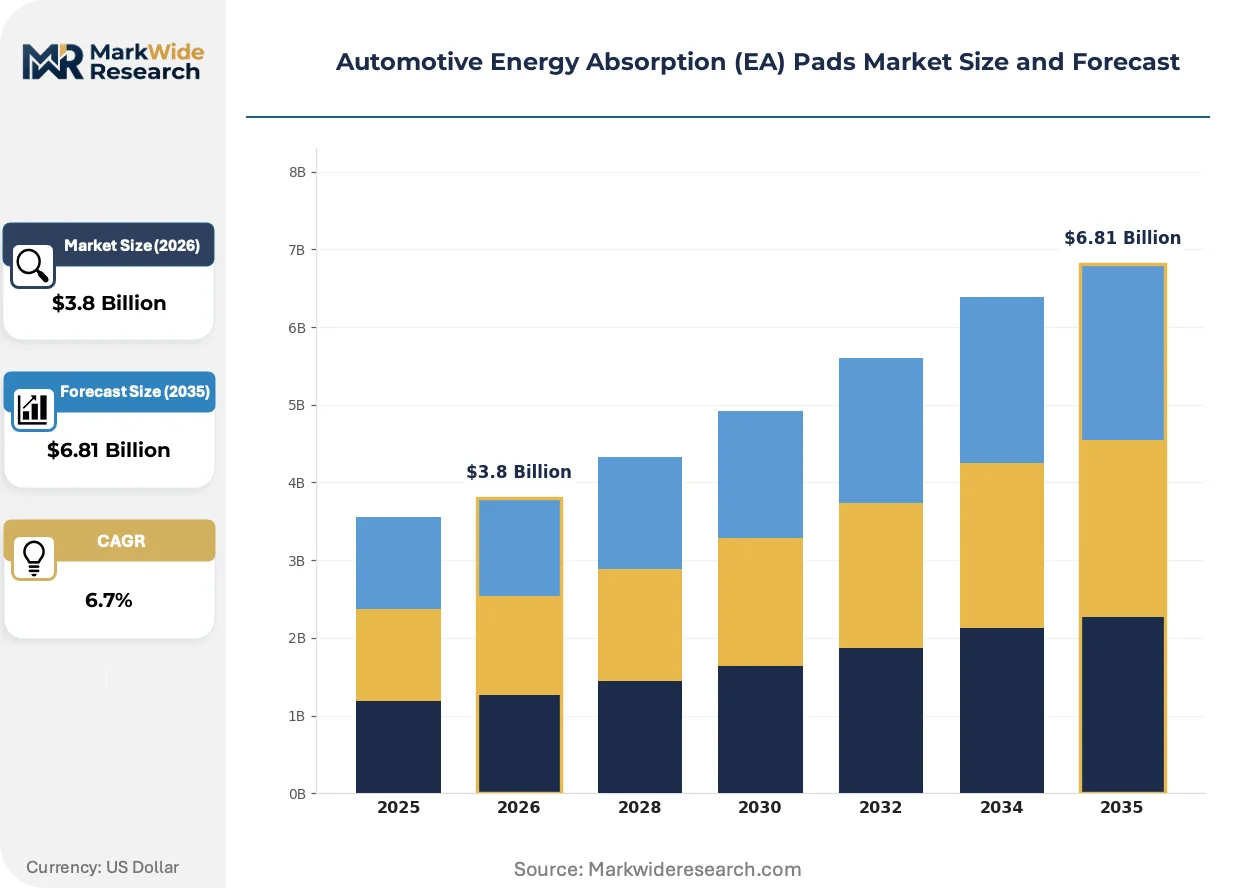
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam, Rubber, Composites, Metal Application: Crash Test, Vibration Damping, Sound Insulation, Energy Management End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Technology: Injection Molding, Compression Molding, Extrusion, 3D Printing |
| Companies Covered | Bridgestone Corporation, The Oakwood Group, THIEME GmbH & Co. KG, JSP (ARPRO), Coastal Automotive, UNO MINDA, Woodbridge Foam Corporation, Nagase America LLC, Kyoraku Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Energy Absorption (EA) Pads Market Evolving Landscape
Material science convergence with vehicle electrification is dissolving traditional boundaries between structural, thermal, and energy management functions in automotive padding systems.
Aramid-reinforced composite cores are fragmenting the high-performance segment that polyurethane foams previously dominated. Luxury electric vehicle platforms from German and South Korean OEMs are adopting these hybrid structures for battery pack side-impact rails. The technology is fragmenting supplier hierarchies by requiring compounders to master both textile handling and compression molding in integrated operations.
EU General Safety Regulation pedestrian protection phase-ins are tightening head-impact performance corridors for hood assemblies. The regulation forces redesign of hood inner-panel geometries and EA pad placement density maps. European A-segment and B-segment vehicle programs are most affected, with engineering teams compressing development cycles to meet 2024-2026 homologation deadlines.
Direct OEM engagement of specialty compounders is displacing traditional Tier-1 mediation in electric vehicle platform sourcing. Battery enclosure protection specifications require material-specific engineering collaboration that generic system integrators cannot provide. South Korean and Chinese electric vehicle manufacturers are most aggressive in this pattern, establishing two-year development partnerships with foam formulation specialists.
Automotive Energy Absorption (EA) Pads Market Segmentation
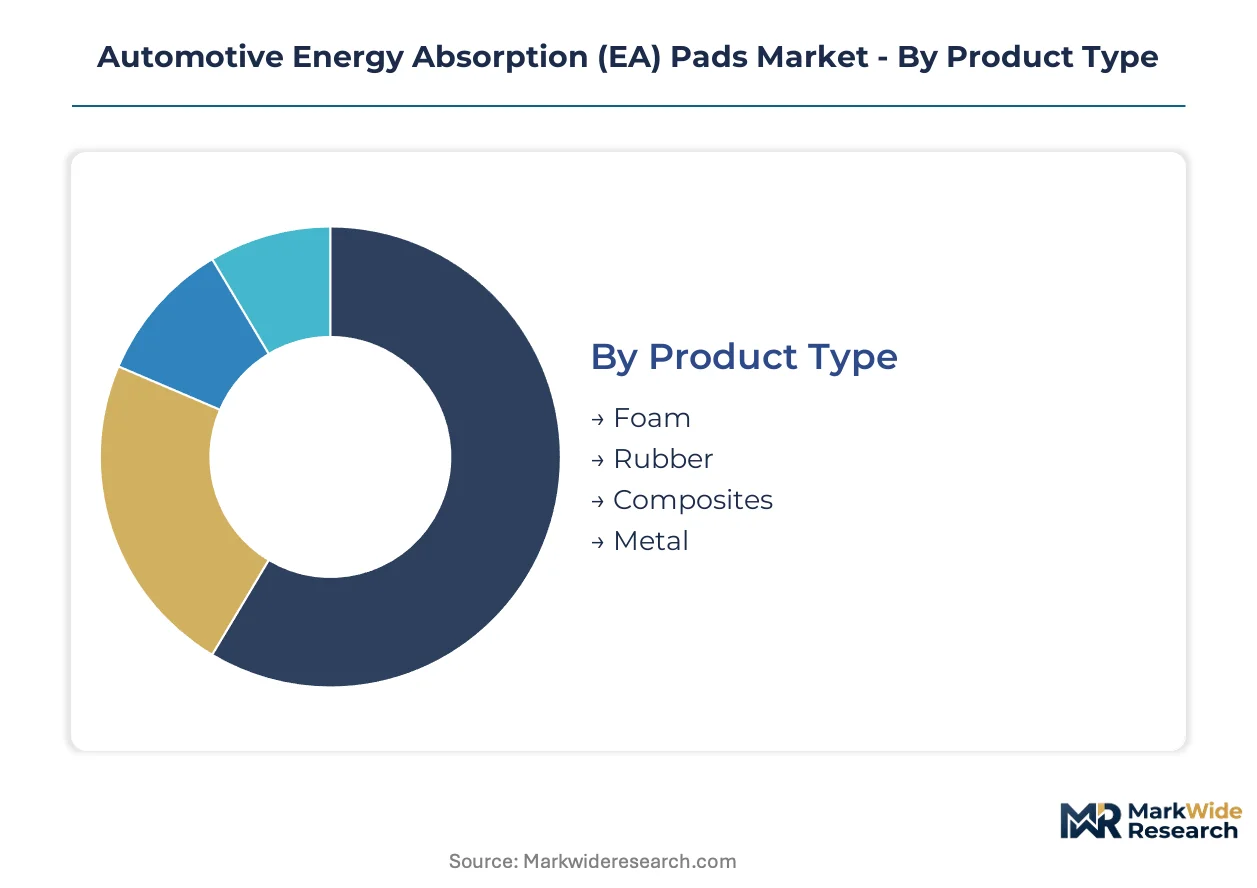
Energy absorption pad procurement patterns diverge sharply across product categories and buyer channels. OEM platform engineering decisions cascade through technology selection, application placement, and supplier tier engagement. Understanding these segment boundaries clarifies where formulation specialists capture margin versus where commodity competition dominates.
Product Type:
Domestic vehicle programs in Germany, the United States, and Japan anchor foam and rubber demand, while composite exports concentrate through South Korean and Chinese electric vehicle supply chains seeking advanced crash-performance specifications.
- Foam:Expanded polypropylene and polyurethane matrices with densities spanning 20-200 kg/m³ constitute the volume foundation. German OEMs—BMW, Mercedes-Benz, Volkswagen—specify multi-density foam stacks for pedestrian protection hood assemblies under tightening EU General Safety Regulation thresholds.
- Composites:Aramid-reinforced hybrid structures fragment the high-performance tier previously owned by polyurethane. South Korean luxury electric platforms integrate these for battery pack side-impact rails, requiring compounders to master textile handling alongside compression molding.
- Rubber:Natural and synthetic rubber blends serve vibration-damping applications in powertrain mounts and suspension bushings. Japanese vehicle assemblers favor these formulations for durability under cyclic loading.
- Metal:Aluminum honeycomb and steel crush structures supplement polymer pads in heavy-duty commercial vehicle bumpers. North American truck manufacturers specify these for FMVSS 581 compliance at elevated impact energies.
Foam commands the established base. The steepest expansion runs through composites.
Application:
Cost-tier stratification separates crash-test-grade specifications—demanding 18-24 month validation cycles—from vibration damping commodities with shorter procurement windows.
- Crash Test:Hood, bumper, and pillar pads engineered to NHTSA FMVSS 581 head-impact criteria and EU pedestrian protection corridors. German A-segment and B-segment programs compress development cycles to meet homologation deadlines.
- Energy Management:Battery enclosure protection for electric vehicles introduces multi-axis load cases and UL 2596 thermal propagation requirements. South Korean and Chinese manufacturers embed these pads into pack housings, commanding 40-60% price premiums over conventional grades.
- Vibration Damping:Powertrain and chassis isolation pads prioritize loss factor and temperature stability over crash performance. Mass-market vehicle programs source these through competitive tender.
- Sound Insulation:Acoustic treatment pads for cabin and hood applications. European OEMs integrate these with thermal management functions in electric vehicle architectures.
Crash test specifications absorb the deepest engineering resources. Energy management applications are climbing the fastest.
End User:
Customer-type concentration determines supplier access: Tier-1 integrators mediate legacy programs while direct OEM engagement accelerates in electric vehicle platform sourcing.
- Tier-1 Suppliers:System integrators—The Oakwood Group, THIEME GmbH—control multi-year supply agreements and direct OEM engineering collaboration. These relationships lock out smaller compounders from bumper beam and hood assembly programs.
- OEMs:Direct material specification by BMW, Mercedes-Benz, Volkswagen, and South Korean electric vehicle manufacturers bypasses traditional Tier-1 mediation for battery enclosure protection. Two-year development partnerships with foam formulation specialists replace generic sourcing.
- Vehicle Assemblers:Contract manufacturers and joint-venture operations in India and China localize crash-structure engineering, creating openings for suppliers with in-country testing capabilities.
- Aftermarket Providers:Replacement pad distributors serve collision repair and restoration markets. BIS-certified Indian suppliers target Maruti Suzuki and Tata Motors service networks.
Tier-1 suppliers retain the incumbent position. Direct OEM engagement is gaining share fastest.
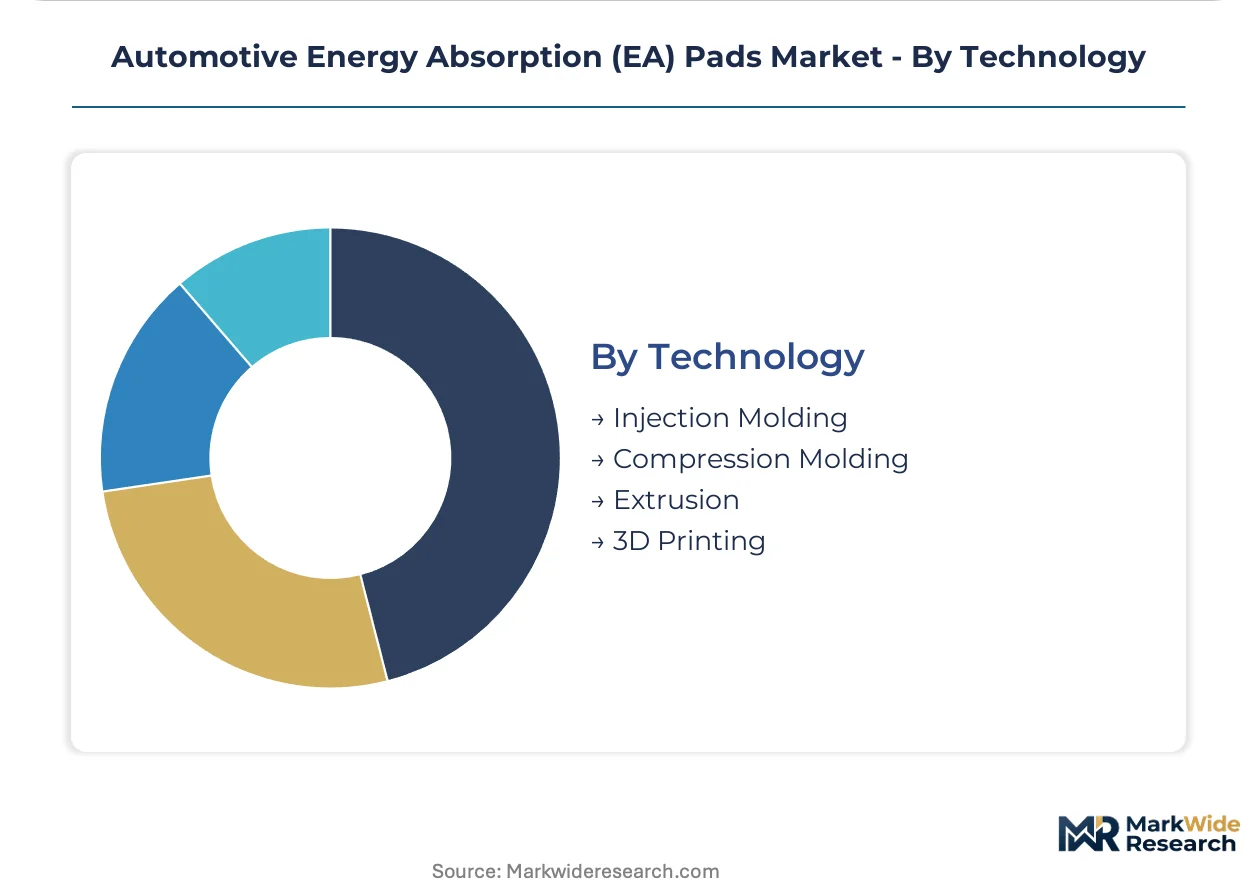
Technology:
Volume-maturity separation distinguishes high-throughput compression molding for bumper inserts from emerging 3D printing for geometrically complex A-pillar applications.
- Compression Molding:Dominant route for expanded polypropylene bead-foam bumper beam inserts. The Oakwood Group anchors North American capacity through in-house fabrication facilities.
- Injection Molding:Intricate A-pillar and door trim applications requiring dimensional tolerance below 0.5 mm. THIEME GmbH precision molding clusters in southern Germany and northern Italy.
- Extrusion:Continuous profile production for seal and gasket integration with energy absorption functions. Japanese compounders leverage this for hybrid structural-acoustic components.
- 3D Printing:Additive manufacturing for prototype validation and low-volume geometrically complex pedestrian protection architectures. South Korean OEMs pilot lattice structures for battery pack compression members.
Compression molding holds the volume base. Injection molding is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates pedestrian protection engineering while South Korea dominates battery enclosure specifications. The United States anchors commercial vehicle crashworthiness demand. Japan preserves rubber-formulation heritage for vibration damping. India localizes production for cost-sensitive domestic programs.
United States
NHTSA FMVSS 581 bumper integrity rules and tightening pedestrian protection thresholds compel hood and fender redesigns. EPA volatile organic compound limits constrain adhesive bonding processes in multi-layer pad lamination. Detroit-area Tier-1 suppliers anchor North American compression molding capacity for bumper beam inserts.
Germany
BMW, Mercedes-Benz, and Volkswagen embed multi-material EA architectures 48 months pre-production, extending supplier engineering cycles. EU General Safety Regulation pedestrian protection phase-ins force A-segment and B-segment hood inner-panel redesigns. Southern German precision molding clusters in Bavaria and Baden-Württemberg control geometrically complex pedestrian protection systems requiring sub-0.5mm tolerance.
South Korea
Luxury electric vehicle platforms adopt aramid-reinforced composite cores for battery pack side-impact rails, fragmenting high-performance supply tiers. Direct OEM engagement of specialty compounders displaces traditional Tier-1 mediation for battery enclosure specifications. Seoul Capital Area manufacturers pilot additive manufacturing for lattice-structured battery pack compression members.
Japan
METI carbon-neutral vehicle roadmap awards preferential procurement weighting to biobased polyol feedstocks for polyurethane foams. Nagoya and Osaka industrial corridors preserve rubber-blend formulation expertise for powertrain vibration damping under cyclic loading. JIS standards certification remains mandatory for domestic vehicle assembler qualification.
India
Maruti Suzuki and Tata Motors localize crash-structure engineering, creating openings for BIS-certified suppliers with in-country compounding partnerships. Automotive polymer engineering talent scarcity limits direct OEM access for second-tier pad manufacturers. Maharashtra and Gujarat vehicle assembly corridors concentrate domestic production expansion for cost-sensitive mass-market programs.
Automotive Energy Absorption (EA) Pads Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in automotive energy absorption pad supply. Tier-1 system integrators control multi-year supply agreements and direct OEM engineering collaboration, locking out smaller compounders from bumper beam and hood assembly programs. Specialist compounders occupy defensible niches in geometrically complex architectures and material-specific formulation. Dominant competitive moves include backward integration into captive foam fabrication and geographic expansion through BIS-certified Indian partnerships.
Within the integrated leader tier, Bridgestone Corporation and The Oakwood Group exemplify divergent strategic positions. Bridgestone leverages tire-to-pad materials science crossover to sustain formulation leadership in aramid-reinforced composites. The Oakwood Group anchors North American production capacity through in-house expanded polypropylene fabrication facilities. Among European precision specialists, THIEME GmbH & Co. KG occupies a defensible niche in geometrically complex pedestrian protection molding, with capability concentrated in southern Germany and northern Italy.
| Leading Market Players |
|---|
| Bridgestone Corporation |
| The Oakwood Group |
| THIEME GmbH & Co. KG |
| JSP (ARPRO) |
| Coastal Automotive |
| UNO MINDA |
| Woodbridge Foam Corporation |
| Nagase America LLC |
| Kyoraku Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between Tier-1 suppliers and German OEMs lock in both polypropylene foam supply access and price visibility across 48-month development cycles, insulating compounders from naphtha volatility while constraining spot-market participation by smaller manufacturers.
Pricing Analysis
Contract-based long-term offtake structures dominate procurement for bumper beam and hood assembly programs, with price differentiation resting on UL 2596 thermal certification tier and volume scale commitments. Cost compression in mass-market foam grades is intensifying because expanded polypropylene bead-foam processing spreads fixed capital across higher volumes. Tier-1 suppliers exhibit the lowest price sensitivity due to captive OEM relationships, while Indian vehicle assemblers drive aggressive tender competition for vibration-damping commodities.
Supply Chain Analysis
Just-in-time inventory strategies prevail among German precision molders serving pedestrian protection programs, whereas North American compounders maintain strategic stockpiles of propylene oxide precursors against petrochemical volatility. Supply concentrates in Germany, the United States, and South Korea, with raw material dependencies on naphtha-derived polypropylene, propylene oxide for polyurethane, and aramid fiber textiles. Single-source vulnerability runs through southern German geometric molding clusters for sub-0.5mm tolerance components. Distribution runs through Tier-1 system integrators mediating OEM engineering collaboration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Finite element modeling talent for hyperelastic polymer crash simulation concentrates at incumbent Tier-1 suppliers, leaving second-tier compounders without direct OEM access and creating acquisition premiums for specialists with certified simulation capabilities.
For Market Incumbents: Fortify backward integration into captive expanded polypropylene fabrication to defend margin position against petrochemical feedstock volatility. Secure BIS-certified testing partnerships in Maharashtra and Gujarat corridors before Maruti Suzuki and Tata Motors complete crash-structure localization. Prioritize UL 2596 thermal propagation certification investment for battery enclosure foam specifications commanding premium positioning.
For New Entrants and Emerging Players: BIS certification fast-track through Indian compounding partnerships opens the most penetrable white-space in cost-sensitive domestic vehicle programs. Target energy management applications for electric vehicle battery packs where 18-24 month validation cycles deter incumbent reallocation from bumper-centric programs. Establish direct OEM engineering collaboration with South Korean manufacturers bypassing traditional Tier-1 mediation.
For Investors and Strategic Acquirers: Capital is best deployed toward compounders with integrated aramid textile handling and compression molding capabilities, as luxury electric vehicle platforms fragment high-performance supply tiers. Long-term viability across the analysis window hinges on mastering multi-physics certification spanning NHTSA crashworthiness, UL 2596 thermal containment, and OEM vibration durability protocols. Watch for battery enclosure protection specification releases from South Korean and Chinese OEMs as inflection indicators for fire-resistant foam grade demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foam Fabrication | Captive expanded polypropylene production insulates Bridgestone and Oakwood from naphtha volatility compressing third-party compounder margins. |
| Multi-Physics Certification Investment | Simultaneous NHTSA, UL 2596, and OEM protocol validation extends engineering cycles but locks out competitors from battery enclosure specifications. |
| Geographic Expansion through Indian Partnerships | BIS-certified compounding collaborations in Maharashtra corridors capture Maruti Suzuki and Tata Motors localization programs. |
| Direct OEM Engagement Model | Bypassing Tier-1 mediation with South Korean electric vehicle manufacturers accelerates development partnerships for thermal runaway containment foams. |
| Aramid-Reinforced Composite Capability Buildout | Mastering textile handling alongside compression molding fragments high-performance tiers previously dominated by polyurethane specialists. |
Research Methodology
Desk research of vehicle production databases, IHS Markit registration data, and SEC filings from automotive suppliers preceded structured interviews with Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and polymer compounding technical directors. Bottom-up segment sizing across foam, composite, rubber, and metal product categories was cross-validated against top-down market value estimates derived from content-per-vehicle analysis and regional production forecasts.
Variance decomposition across vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster shaped the analytical framework. CAGRs were derived from logistic diffusion modeling of electric vehicle platform penetration and pedestrian protection regulation phase-ins. Industry-specific forecast inputs included NHTSA FMVSS 581 compliance timelines and EU General Safety Regulation homologation deadlines.
Decision-makers should treat outputs as directional under assumptions of steady petrochemical feedstock availability and continued electric vehicle platform expansion; material deviation would warrant model refresh. Revision becomes warranted when battery enclosure thermal runaway containment specifications cross adoption thresholds in mass-market vehicle programs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Display Market
Automotive Interior & Exterior
Automotive Fascia Market
Automotive Interior & Exterior
Interior Materials for Pet-Friendly Vehicle Cabins Market
Automotive Interior & Exterior
PVC and PU Leather for Automotive Market
Automotive Interior & Exterior
North America Automotive Interiors Market
Automotive Interior & Exterior
Automotive Airbag Fabric Market
Automotive Interior & Exterior
Automotive Fabric Market
Automotive Interior & Exterior
Impact-Modified PCR Plastics for Automotive Interiors Market
Automotive Interior & Exterior
Automotive Upholstery Market
Automotive Interior & Exterior
Global Automotive Carpeting Market
Automotive Interior & Exterior
Railway Interior Lighting Market
Automotive Interior & Exterior
Bumper Sticker Market
Automotive Interior & Exterior
Automotive Trim Market
Automotive Interior & Exterior
Automotive Interior Bovine Leather Market
Automotive Interior & Exterior
Automotive Floor Carpet Market
Automotive Interior & Exterior
Automotive Heated Seat Market