
 Automotive Dual Mass Flywheel Market | 2026-2036
Automotive Dual Mass Flywheel Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Dual Mass Flywheel Market Analysis
Commercial fleet operators is redrawing procurement priorities across the Automotive Dual Mass Flywheel landscape as vibration-dampening requirements intensify in heavy-duty segments. Schaeffler AG leverages its integrated bearing and damping expertise to sustain long-term supply relationships with European OEMs. ZF Friedrichshafen anchors its position through captive production of torsional vibration dampers for premium drivetrain platforms. Valeo SA competes on manufacturing scale across multiple continental production hubs.
An automotive dual mass flywheel is a torsional damping device comprising two independent masses connected by a spring and damper system, typically engineered with cast iron or steel housings and arc-spring carriers to isolate engine torque pulsations from the transmission input shaft. Its primary industrial purpose is to absorb crankshaft vibrations, protect synchronizers from fatigue failure, and enable downspeeding strategies that improve fuel economy in internal combustion powertrains. Dual mass flywheel configurations command the dominant share of OEM fitments for passenger vehicles due to their superior NVH suppression relative to single mass alternatives, while lightweight aluminum variants represent the fastest-growing material segment as automakers pursue gram-level mass reduction targets. Aftermarket suppliers occupy a mature, margin-compressed channel focused on replacement cycles for aging European and North American vehicle parc.
EPA tailpipe emissions rules, Euro 7 standards from the European Commission, and NHTSA fuel economy mandates collectively tighten the design envelope for driveline efficiency across all major automotive markets. These frameworks force suppliers to validate dual mass flywheel durability under extended start-stop cycling and mild-hybrid torque loading profiles. Stakeholders must monitor how powertrain electrification timelines alter the addressable volume for mechanical damping solutions in parallel hybrid architectures.
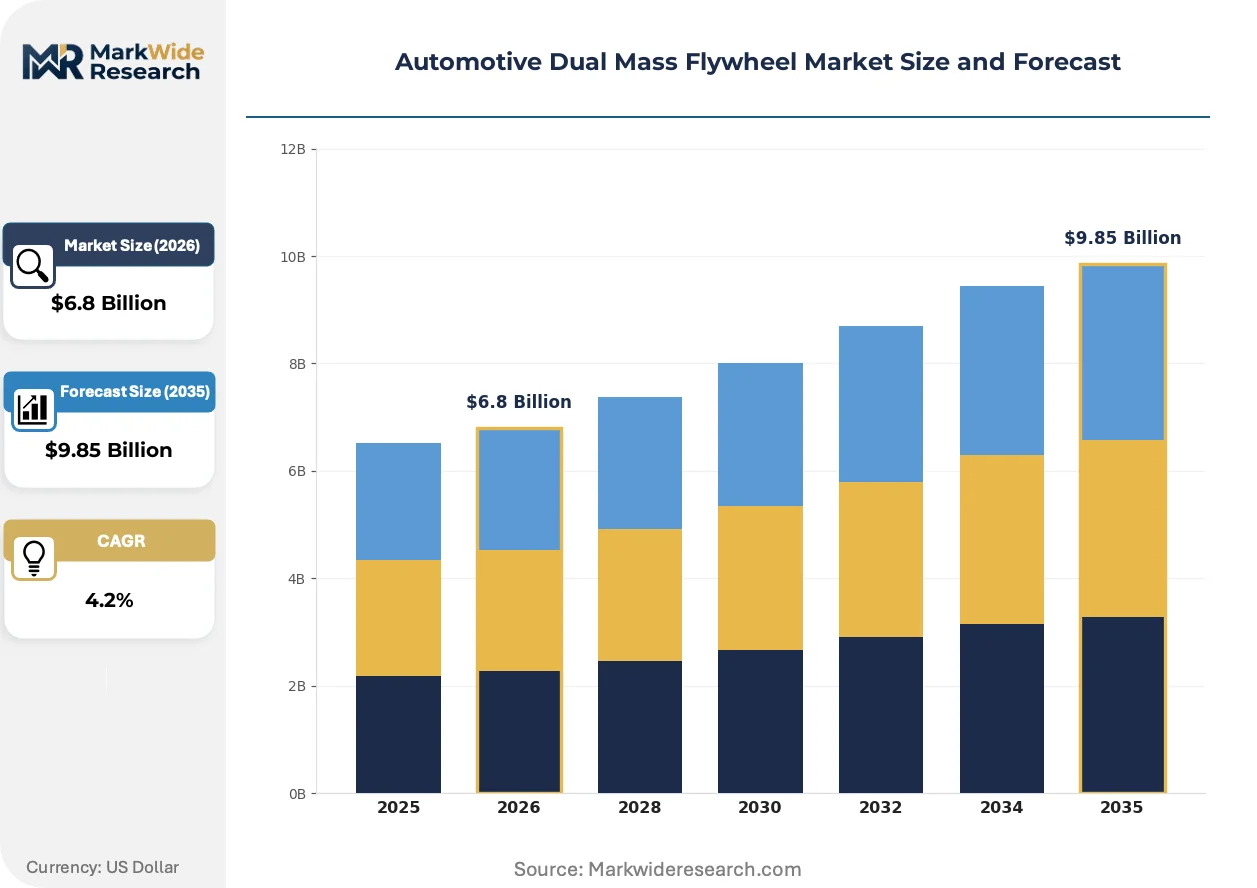
Market Dynamics
Powertrain electrification timelines are compressing the addressable window for mechanical torsional damping solutions as automakers accelerate mild-hybrid integration and full-electric platform development.
Growth Catalysts
- Euro 7 emissions mandates:The European Commission's tightened tailpipe standards force OEMs to adopt advanced NVH suppression technologies that enable engine downspeeding and fuel efficiency gains.
- Commercial fleet operators:Heavy-duty logistics providers in Germany and the United States are specifying dual mass flywheels to extend clutch service intervals and reduce driveline maintenance costs.
- Arc-spring damper systems:Next-generation spring carrier designs with optimized stiffness gradients improve torque pulsation isolation across broader engine load ranges.
Market Restraints
- Cast iron input cost volatility:Foundry-grade iron prices fluctuate with scrap metal markets and energy costs, compressing margin predictability for housing manufacturers.
- Supplier concentration in Baden-Württemberg:German component clusters create geographic risk exposure for OEMs dependent on just-in-time delivery of precision-machined arc-spring carriers.
- Battery-electric substitution:Pure electric powertrains eliminate crankshaft torque pulsations entirely, removing the functional need for mechanical damping devices in BEV architectures.
Strategic Opportunities
- P-series mild-hybrid architectures:Belt-integrated starter-generator systems in 48V configurations preserve dual mass flywheel relevance by maintaining internal combustion as primary torque source.
- Aftermarket channel digitization:Independent repair networks in Poland and Czech Republic are adopting platform-based procurement for replacement clutch kits with bundled flywheel assemblies.
- Lightweight aluminum variants:Magnesium-alloy housing developments target gram-level mass reduction quotas in premium passenger vehicle segments.
Industry Challenges
- NVH simulation talent scarcity:Finite element analysis specialists capable of modeling non-linear spring-damper behavior command premium compensation and extended recruitment cycles.
- Start-stop durability validation:Extended cycling protocols under EPA test procedures require accelerated wear testing infrastructure that strains R&D capital allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Dual Mass Flywheel Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.85 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Mass Flywheel, Dual Mass Flywheel, Lightweight Flywheel, Performance Flywheel Application: Passenger Vehicles, Commercial Vehicles, High-Performance Cars, Hybrid Vehicles Material: Steel, Aluminum, Carbon Fiber, Composite Materials End User: OEMs, Aftermarket Suppliers, Automotive Service Centers, Vehicle Assemblers |
| Companies Covered | AISIN SEIKI, American Axle & Manufacturing, Schaeffler AG, Linamar Corporation, LuK GmbH & Co. KG, ZF Friedrichshafen, EXEDY Globalparts, AmTech International, Valeo SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Dual Mass Flywheel Market Emerging Trajectories
Torsional damping architectures are fragmenting across competing powertrain strategies as electrification pressures force suppliers to defend mechanical solutions in hybrid niches.
Curved arc-spring carriers with variable-pitch coil geometries are decomposing the traditional uniform-spring design paradigm. Tier-1 suppliers serving premium German OEMs are adopting these configurations for 4-cylinder turbocharged engines. The technology is decomposing established procurement specifications by enabling single-platform coverage across multiple displacement classes.
EPA tailpipe emissions rules and NHTSA fuel economy mandates are tightening validation requirements for start-stop system durability. Suppliers must now certify dual mass flywheel performance across 300,000+ engine restart cycles. North American light-duty truck segments face the steepest compliance burden as these vehicles carry the highest torque loads.
Fleet procurement departments are consolidating supplier relationships around integrated powertrain module contracts rather than discrete component sourcing. Independent distributors serving European aftermarket channels face margin compression as captive OEM service networks capture replacement volume. This consolidation is most visible in German commercial vehicle parc where authorized dealer penetration exceeds 70 percent.
Automotive Dual Mass Flywheel Market Segmentation
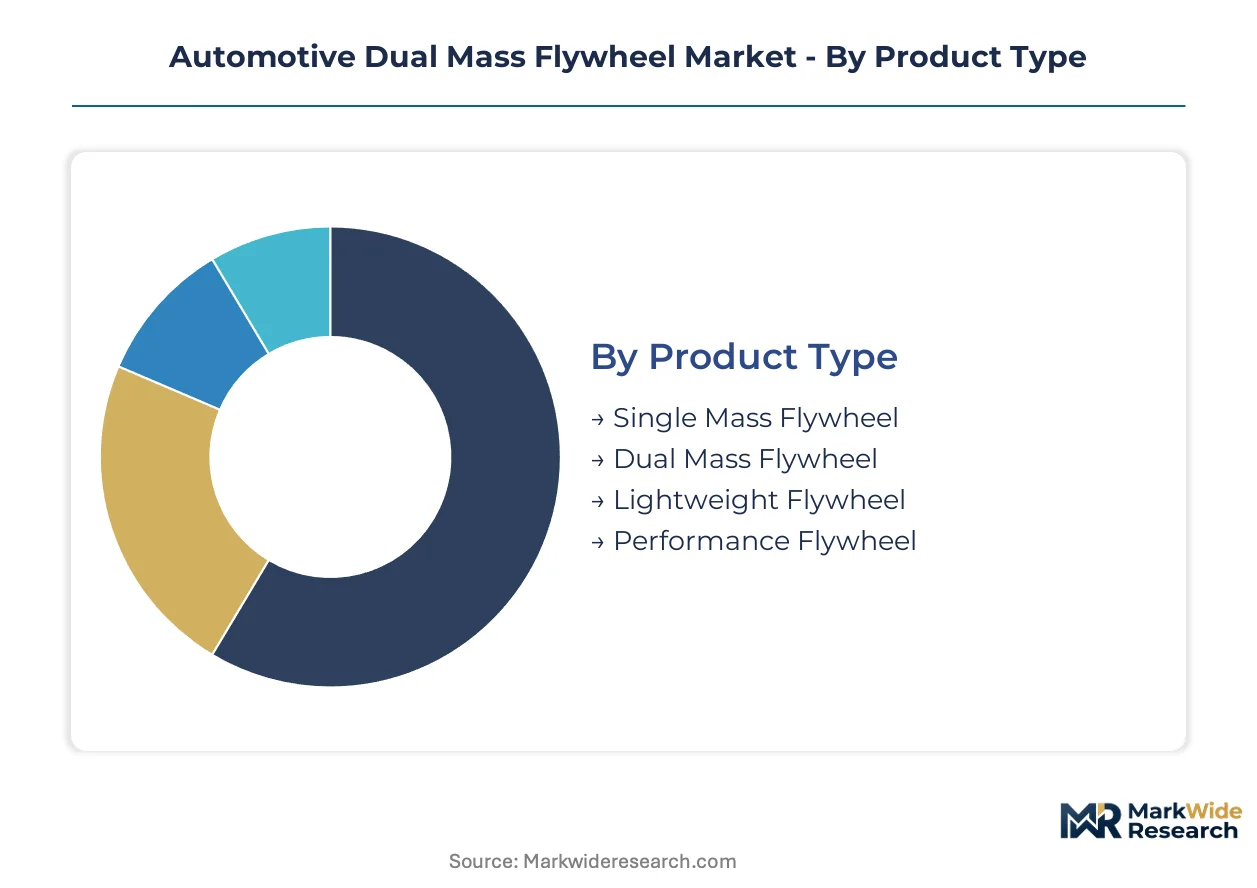
Dual mass flywheel procurement patterns fragment sharply across powertrain architectures and customer types. Material selection and application context determine which segments face immediate displacement risk from electrification versus sustained demand in combustion-dominant niches.
Product Type:
Battery-electric substitution pressures vary dramatically by flywheel architecture, with some configurations retaining functional relevance in hybrid powertrains while others face obsolescence.
- Dual Mass Flywheel:Spring-damper systems with arc-spring carriers isolate crankshaft torque pulsations from transmission input shafts. OEM fitments in German passenger vehicles sustain demand despite mild-hybrid torque loading complexities. EPA start-stop durability protocols now mandate 300,000+ cycle validation for this configuration.
- Single Mass Flywheel:Solid cast iron or steel discs without torsional damping elements suit cost-sensitive applications and motorsport retrofit markets. Eastern European aftermarket distributors in Poland and Czech Republic maintain inventory for aging vehicle parc replacement cycles.
- Lightweight Flywheel:Aluminum and magnesium alloy variants target gram-level mass reduction quotas in premium segments.
- Performance Flywheel:Competition-specification units prioritize rotational inertia reduction over NVH suppression for track applications.
Dual Mass Flywheel retains volume leadership; Lightweight Flywheel holds the steepest expansion curve.
Application:
Commercial fleet specifications diverge from passenger car procurement as duty cycles and torque loads reshape damping requirements.
- Passenger Vehicles:Four-cylinder turbocharged engines in compact and mid-size segments generate the highest unit volumes for torsional damping solutions. German OEMs specify arc-spring carriers with variable-pitch geometries to cover multiple displacement classes on single platforms.
- Commercial Vehicles:Heavy-duty logistics operators in Germany and the United States specify dual mass flywheels to extend clutch service intervals and reduce driveline maintenance costs in high-mileage operations.
- Hybrid Vehicles:P-series mild-hybrid architectures with belt-integrated starter-generator systems preserve mechanical damping relevance by maintaining internal combustion as primary torque source.
- High-Performance Cars:Premium drivetrain platforms prioritize NVH suppression alongside power density in six and eight-cylinder configurations.
Passenger Vehicles command the largest installed base; Hybrid Vehicles are expanding most quickly as 48V architectures proliferate.
Material:
Foundry cost structures and mass reduction mandates pull material selection in opposing directions across price tiers.
- Steel:High-strength alloy housings and spring carriers dominate OEM specifications for durability under cyclic loading. Scrap metal price volatility compresses margin predictability for foundry-dependent suppliers.
- Aluminum:Cast and forged aluminum variants target 15-30% mass reduction versus steel counterparts in premium passenger segments. Magnesium-alloy developments pursue further gram-level savings for automakers facing fleet CO2 compliance pressures.
- Carbon Fiber:Reinforced polymer composites serve niche motorsport and ultra-premium applications where rotational inertia minimization outweighs cost constraints.
- Composite Materials:Hybrid material constructions combining metal housings with polymer damping elements emerge in prototype validation phases.
Steel maintains cost-adjusted volume dominance; Aluminum is climbing the fastest on mass reduction mandates.
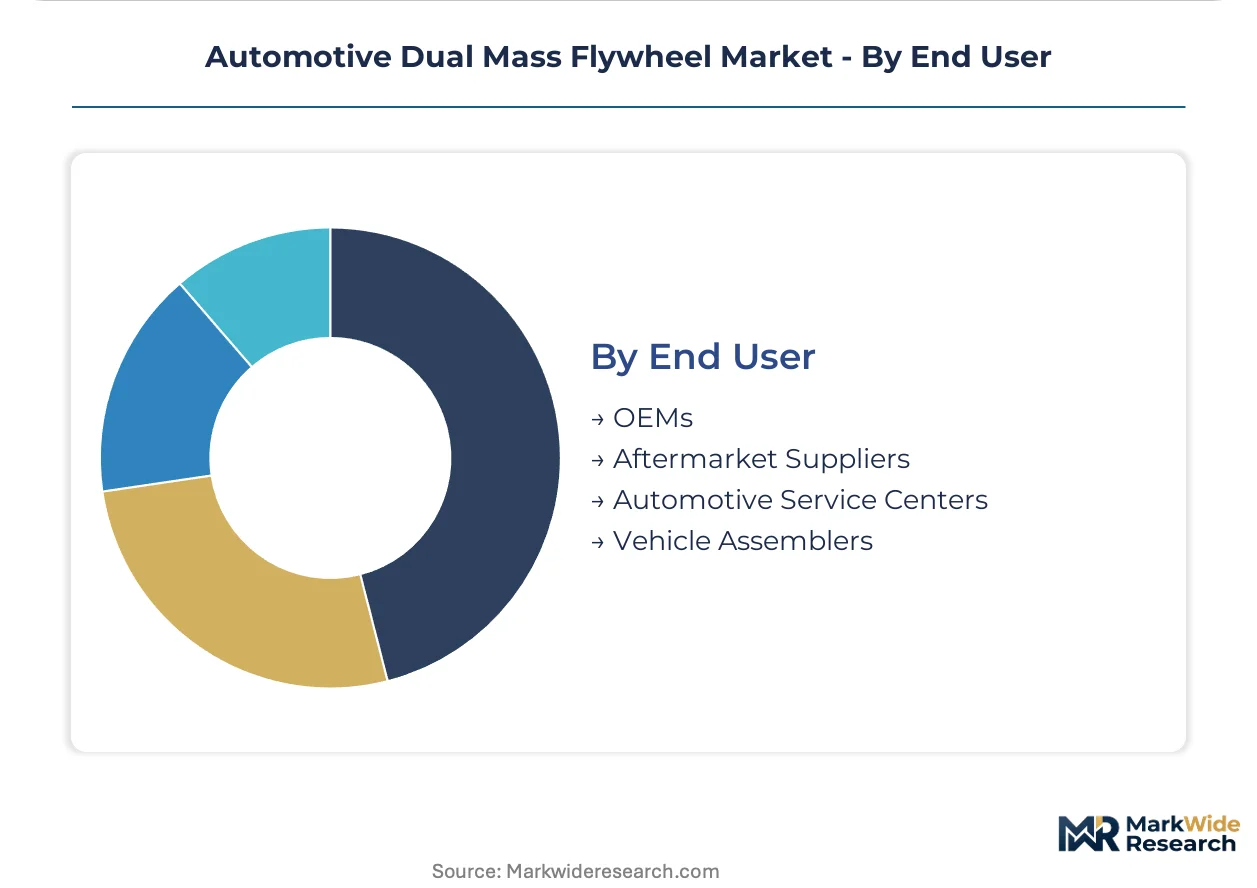
End User:
Channel consolidation and captive service network expansion reshape margin capture across the value chain.
- OEMs:Integrated powertrain module contracts consolidate procurement around Schaeffler AG and ZF Friedrichshafen for torsional vibration damper supply to German vehicle manufacturers. Just-in-time delivery requirements from Baden-Württemberg production clusters create geographic concentration risk.
- Aftermarket Suppliers:Independent distributors face margin compression as authorized dealer networks capture replacement volume in German commercial vehicle parc where dealer penetration exceeds 70 percent.
- Automotive Service Centers:Platform-based procurement adoption in Poland and Czech Republic enables bundled clutch kit sourcing with integrated flywheel assemblies.
- Vehicle Assemblers:Contract manufacturers and specialty vehicle builders source discrete damping components for low-volume production runs.
OEMs retain absolute volume leadership; Automotive Service Centers show the steepest procurement digitization trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput connects German component clusters to global OEM assembly plants, underwriting Europe's centrality to precision powertrain manufacturing. This maritime infrastructure supports just-in-time delivery of arc-spring carriers to vehicle plants across three continents.
Germany
Commercial fleet operators in heavy-duty logistics specify dual mass flywheels to extend clutch service intervals. Euro 7 standards from the European Commission mandate refined torsional damping for fuel efficiency gains. Baden-Württemberg production clusters concentrate captive supply relationships with premium drivetrain platforms.
United States
North American light-duty truck segments face steep EPA durability validation burdens for start-stop cycling. NHTSA fuel economy mandates compress design envelopes for driveline efficiency. Michigan and Ohio manufacturing corridors anchor heavy-duty clutch kit production for aging vehicle parc replacement.
China
Domestic OEMs integrate mild-hybrid architectures preserving mechanical damping relevance in 48V configurations. MIIT emissions protocols tighten validation requirements for torsional vibration suppression. Yangtze River Delta foundries supply cast iron housings amid scrap metal price volatility.
Japan
Premium passenger vehicle segments demand gram-level mass reduction in aluminum flywheel variants. METI efficiency standards accelerate lightweight alloy development timelines. Kanto region precision machining clusters prototype magnesium-alloy housing constructions.
India
Aftermarket distributors adopt platform-based procurement for bundled clutch kit assemblies. BIS quality standards govern replacement component certification for aging European vehicle imports. Maharashtra and Gujarat service networks digitize independent repair channel sourcing.
Automotive Dual Mass Flywheel Market Vendor Landscape
Concentration sits with integrated bearing and damping specialists serving German OEMs through captive production arrangements. Three structural tiers define competitive positioning: diversified automotive suppliers with powertrain module contracts, precision component specialists focused on arc-spring engineering, and regional aftermarket distributors serving replacement cycles. Strategic moves center on geographic expansion into Eastern European service networks and portfolio diversification toward lightweight aluminum variants.
Among Germany-based diversified suppliers, Schaeffler AG and ZF Friedrichshafen occupy positions anchoring torsional vibration damper supply to European vehicle manufacturers. Valeo SA represents the scale-driven archetype with manufacturing presence across multiple continental production hubs. These three entities exemplify how integrated powertrain module contracts consolidate procurement around suppliers capable of validating 300,000+ start-stop cycle durability under EPA protocols.
| Leading Market Players |
|---|
| AISIN SEIKI |
| American Axle & Manufacturing |
| Schaeffler AG |
| Linamar Corporation |
| LuK GmbH & Co. KG |
| ZF Friedrichshafen |
| EXEDY Globalparts |
| AmTech International |
| Valeo SA |
| Others |
Supply Flow & Price Mechanics
EPA start-stop durability protocols and Euro 7 emissions certification simultaneously gate supplier qualification and stratify pricing tiers in the Automotive Dual Mass Flywheel Market. OEMs demand 300,000+ cycle validation documentation that only integrated Tier 1 suppliers can provision, compressing margin capture for undifferentiated aftermarket distributors.
Pricing Analysis
Volume-discount tiering structures dominate procurement contracts for OEM powertrain modules, with premium pricing attached to arc-spring carriers validated under extended cycling protocols. Price differentiation hinges on certification grade and geographic delivery cost, with Baden-Württemberg production clusters commanding logistics premiums for just-in-time sequences. Pricing pressure stems from cast iron scrap volatility eroding foundry margins. Fleet operators in commercial vehicle segments exhibit highest price sensitivity, while premium passenger OEMs prioritize NVH performance over unit cost.
Supply Chain Analysis
Just-in-time inventory strategies predominate among German OEMs sourcing arc-spring carriers from Baden-Württemberg precision machining clusters, contrasting with strategic stockpiling preferences among Eastern European aftermarket distributors buffering against scrap metal price swings. Supply concentrates in Germany, China, and Japan, drawing from foundry-grade iron, high-strength steel alloys, and magnesium-alloy developments. Single-source vulnerability around arc-spring engineering talent creates structural risk. Distribution runs through captive OEM service networks in Germany and independent platform-based procurement channels in Poland and Czech Republic.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Automotive Dual Mass Flywheel Market faces high-growth disruption as powertrain electrification compresses the addressable window for mechanical damping solutions. Euro 7 standards and EPA tailpipe rules accelerate validation requirements that favor integrated suppliers with accelerated wear testing infrastructure.
For Market Incumbents: Compound defensive positioning through backward integration into arc-spring carrier machining and captive supply relationships with premium German OEMs. Extend R&D allocation toward magnesium-alloy housing developments targeting gram-level mass reduction mandates. Battery-electric substitution in passenger segments demands portfolio diversification into P-series mild-hybrid architectures preserving mechanical damping relevance. For New Entrants and Emerging Players: Differentiate on aftermarket digitization capabilities serving Poland and Czech Republic independent repair networks adopting platform-based procurement for bundled clutch kit assemblies. Target white-space in aluminum flywheel variants for premium Japanese passenger segments where METI efficiency standards accelerate lightweight alloy adoption. Pursue go-to-market partnerships with Yangtze River Delta foundries supplying cast iron housings amid domestic OEM mild-hybrid integration. For Investors and Strategic Acquirers: Euro 7 implementation reshapes the acquisition landscape toward suppliers with validated 300,000+ start-stop cycle durability certification. Long-term viability favors integrated powertrain module contractors over discrete component specialists as OEM procurement consolidates. Monitor battery-electric vehicle penetration rates in German passenger segments as the critical signal for mechanical damping demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Variable-pitch arc-spring designs enable single-platform coverage across multiple engine displacement classes for German OEMs. |
| Backward Integration | In-house production of precision-machined arc-spring carriers reduces geographic concentration risk in Baden-Württemberg clusters. |
| Geographic Manufacturing Footprint | Eastern European production hubs in Poland and Czech Republic capture aftermarket digitization growth in independent repair channels. |
| Long-term Supply Agreement | Integrated powertrain module contracts with Schaeffler AG and ZF Friedrichshafen consolidate procurement around validated durability suppliers. |
| Software-Defined Vehicle Investment | NVH simulation talent scarcity commands premium compensation, favoring suppliers with captive finite element analysis capabilities. |
Methodological Framework
A spread of perspectives from OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and foundry operations managers converged on the working assumptions underpinning this analysis. Primary fieldwork combined structured interviews with secondary validation from vehicle production databases, IHS Markit registration data, EPA certification filings, and Euro 7 regulatory documentation. Bottom-up segmentation modeling triangulated against top-down market sizing from trade flow analysis and customs records.
Segmentation dimensions modeled span vehicle class, propulsion architecture, material composition, and regional production cluster across the projection horizon. CAGRs derive from elasticity-adjusted volume projections incorporating powertrain electrification timelines and mild-hybrid adoption curves. Industry-specific forecast inputs include start-stop cycling intensity by vehicle segment and foundry capacity utilization rates in German component clusters.
Material uncertainties — battery-electric vehicle substitution velocity, scrap metal price volatility, and arc-spring engineering talent availability — sit outside the modeled envelope. Forecasts reflect assumptions about hybrid architecture persistence and regulatory durability protocol stability. Revision becomes warranted when BEV penetration in German passenger segments crosses thresholds that eliminate crankshaft torque pulsation damping requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Global Industrial Engine Market
Powertrain
Asia-Pacific Torque Vectoring Market
Powertrain
Power Transmission Gearbox Market
Powertrain
Automotive Belt Tensioner Pulley Market
Powertrain
Engines Market
Powertrain
Tachometer Market
Powertrain
Global Automotive Tappet Market
Powertrain
Mexico Electrically Powered Hydraulic Steering Market
Powertrain
Emission Control Catalyst for Small Engines Market
Powertrain
Transmission Mounting Brackets Market
Powertrain
Synchronizer for Dual-Clutch Transmissions (DCT) Market
Powertrain
Asia Pacific Automotive Engine Market
Powertrain
LNG Engine Market
Powertrain
Automatic Transmission Solenoid Pack Market
Powertrain
UAE Automotive Engine Oils Market
Powertrain
Automotive Engine Air Filter Market