
 Asia-Pacific Automotive Engine Oils Market | 2026-2036
Asia-Pacific Automotive Engine Oils Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Automotive Engine Oils Market Outlook
Fleet operator consolidation across Southeast Asia is recalibrating procurement patterns for bulk lubricant contracts. Shell plc leverages its integrated supply chain to sustain volume leadership across Indonesian and Thai commercial vehicle segments. China National Petroleum Corporation anchors its position through captive refinery capacity and state-backed fleet service partnerships. Idemitsu Kosan Co Ltd differentiates via high-performance synthetic formulations targeted at Japanese OEM specifications across the region.
Asia-Pacific automotive engine oils are formulated lubricants comprising base oils—typically Group II, III, or PAO synthetics—and additive packages containing detergents, dispersants, anti-wear agents, and viscosity index improvers, designed to reduce friction, dissipate heat, and prevent deposit formation in internal combustion engines. Synthetic formulations command expanding share as OEM drain intervals extend and turbocharged direct-injection engines proliferate across passenger vehicle parc. Quick lube services and fleet maintenance channels are capturing disproportionate growth in service-type segmentation, while DIY maintenance contracts in mature markets like Japan and Australia. Two-wheeler end-use segments in India and Vietnam continue consuming mineral and semi-synthetic volumes at scale, though upgrade trajectories vary by urban income tier.
Japan's METI enforces stringent fuel efficiency benchmarks that cascade into lubricant viscosity grade requirements, while China's SAMR and GB standards govern domestic product quality and import compliance. India's BIS certification mandates and proposed CAFE-equivalent regulations are elevating synthetic penetration in OEM fill and service-fill markets. Stakeholders must monitor regulatory divergence between national standards regimes and align formulation portfolios with the most restrictive jurisdiction in their supply footprint.
Market Dynamics
China's MIIT fuel economy standards and India's BIS lubricant quality mandates are compressing formulation cycles across the Asia-Pacific automotive engine oils market, forcing blenders to accelerate synthetic upgrade trajectories while managing base oil supply concentration risks.
Growth Catalysts
- Commercial fleet densification:Logistics network expansion in Indonesia and Vietnam is amplifying bulk lubricant purchasing volumes from state transport corporations and private operators.
- India's BIS certification mandate:Quality enforcement is elevating synthetic penetration in both OEM fill and service-fill channels across the northern industrial corridor.
- Turbocharged direct-injection proliferation:Japanese and Korean OEM specifications are extending drain intervals and demanding higher-performance additive packages.
Market Restraints
- Group III base oil supply concentration:Refinery capacity limitations in Northeast Asia create input cost volatility for synthetic blenders serving ASEAN markets.
- Japan's METI viscosity grade requirements:Stringent fuel efficiency benchmarks impose technical constraints on formulation flexibility for multi-grade product lines.
- Mineral oil substitution persistence:Two-wheeler parc in Vietnam and rural India continues absorbing lower-margin semi-synthetic and mineral volumes at scale.
Strategic Opportunities
- Quick lube channel expansion:Service-type segmentation in Thailand and Malaysia is capturing disproportionate growth as DIY maintenance contracts erode in mature markets.
- China's dual carbon goals:National decarbonization targets are creating regulatory tailwinds for low-viscosity, fuel-economy-certified formulations in domestic passenger vehicle segments.
- Fleet operator consolidation:Southeast Asian logistics integration is opening white space for multi-year bulk supply contracts with integrated maintenance service bundles.
Industry Challenges
- Additive package formulation expertise:Scarce tribology specialists capable of balancing detergent-dispersant ratios for extended drain interval specifications.
- Cross-border certification complexity:Divergent national standards regimes between China's GB standards, India's BIS, and Japan's JIS create compliance timeline friction for regional product portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Automotive Engine Oils Market |
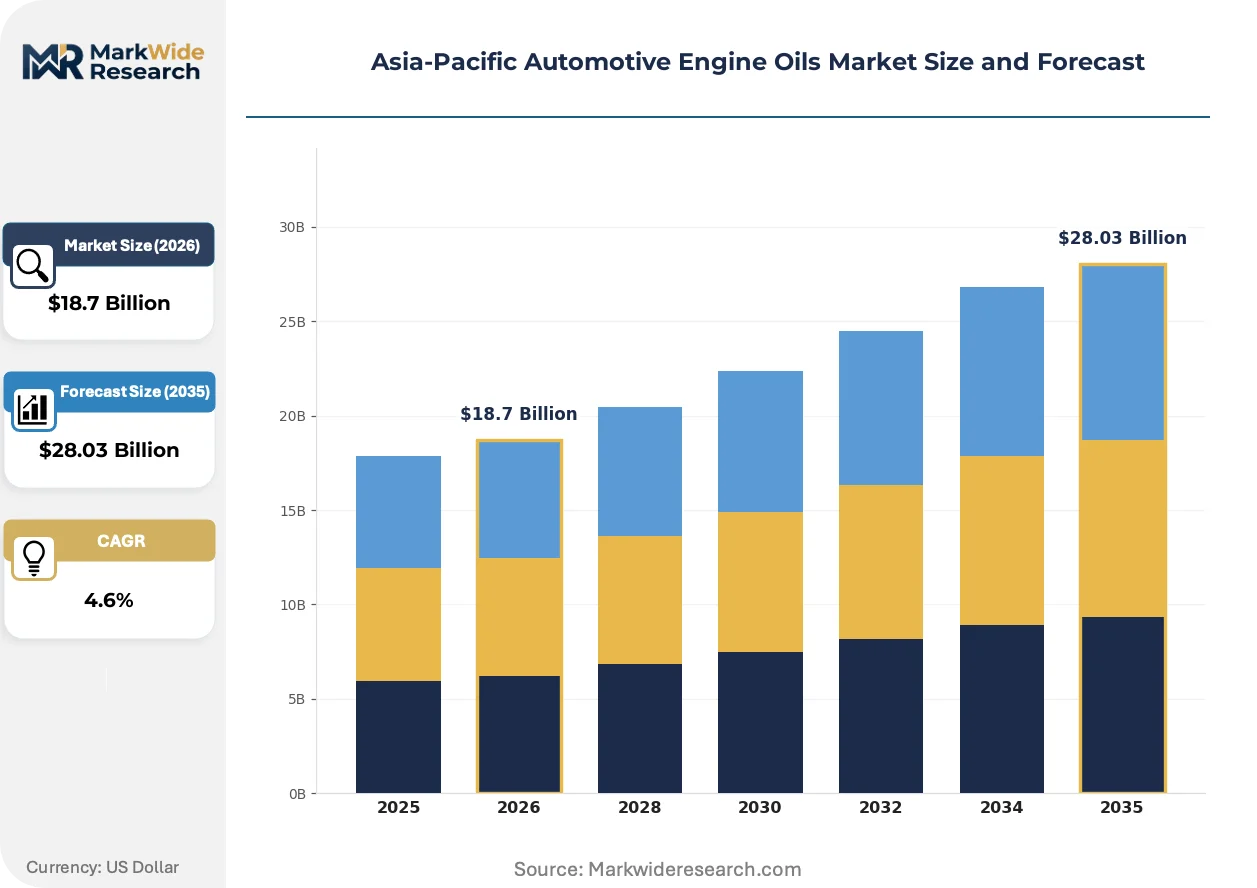
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic, Semi-Synthetic, Mineral, Additives End User: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Heavy-Duty Trucks Service Type: Quick Lube Services, Full-Service Oil Change, DIY Maintenance, Fleet Services Distribution Channel: Retail Stores, Online Platforms, Wholesalers, Service Stations |
| Companies Covered | ExxonMobil Corporation, Shell plc, BP Plc (Castrol), China National Petroleum Corporation, China Petroleum & Chemical Corporation, Indian Oil Corporation Limited, ENEOS Corporation, Idemitsu Kosan Co Ltd, TotalEnergies SE, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Automotive Engine Oils Market Strategic Shifts
Formulation chemistry and distribution architecture are undergoing parallel transformation across Asia-Pacific automotive lubricants, with synthetic base oil adoption, regulatory viscosity compression, and fleet procurement centralization as the dominant vectors.
Polyalphaolefin (PAO) synthetic base stocks are electrifying performance benchmarks for high-temperature stability and oxidative resistance in turbocharged gasoline direct-injection engines. Japanese OEM service-fill channels are absorbing these formulations at accelerated rates. The technology is electrifying competitive differentiation away from mineral-based volume plays toward specification-driven premium positioning.
India's proposed CAFE-equivalent regulations are mandating fuel economy improvements that cascade directly into SAE viscosity grade requirements for OEM factory fill. Domestic blenders must reformulate portfolios to meet both BIS certification and anticipated fleet efficiency targets. Passenger vehicle OEMs in Maharashtra and Tamil Nadu manufacturing clusters are pre-positioning 0W-20 and 5W-30 low-viscosity portfolios.
Fleet maintenance unbundling is fragmenting traditional distributor relationships as consolidated logistics operators in Indonesia and Vietnam negotiate direct blender contracts. Quick lube chains and captive fleet workshops are displacing general automotive repair channels for commercial vehicle lubricant dispensing. This pattern concentrates most visibly in Java's north coast corridor and Ho Chi Minh City's peripheral industrial zones.
Asia-Pacific Automotive Engine Oils Market Segmentation
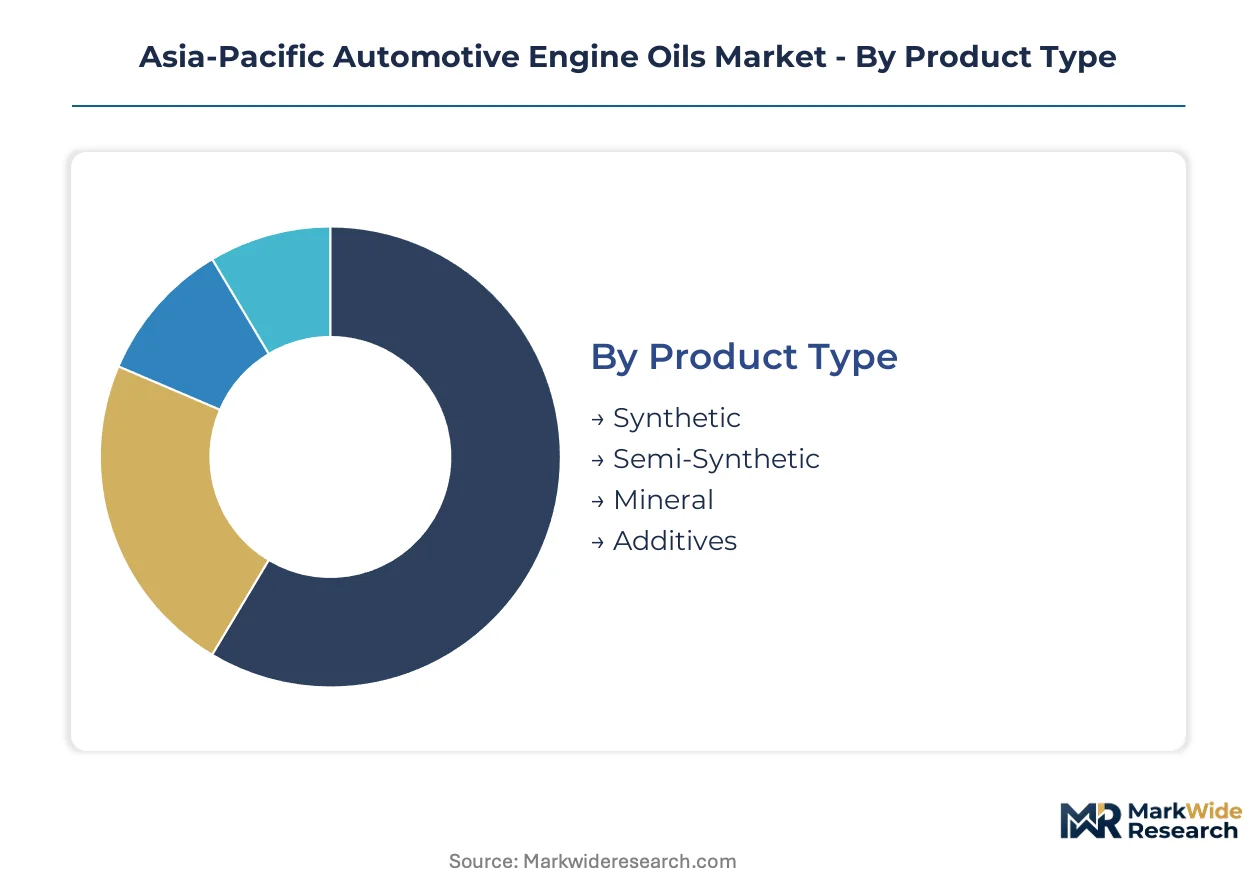
Formulation chemistry, service architecture, and procurement channel design create distinct competitive arenas across Asia-Pacific automotive lubricants. Each segment carries unique margin profiles and regulatory exposure that reshape blender portfolio priorities.
Product Type:
Base oil group classification and additive sophistication define performance tiers and OEM approval pathways across regional markets.
- Synthetic:Group III and PAO base stocks deliver thermal stability for turbocharged direct-injection engines. Japanese OEM specifications in Thailand and Malaysia are accelerating drain interval extensions beyond 15,000 kilometers. China's MIIT fuel economy standards cascade into low-viscosity synthetic mandates for domestic passenger vehicle production.
- Semi-Synthetic:Blended formulations balance cost and performance for mid-market vehicle parc. Indian state transport corporations in the northern industrial corridor are upgrading fleet specifications to semi-synthetic grades under BIS quality enforcement pressure.
- Mineral:Group I and II base oils serve price-sensitive two-wheeler maintenance in Vietnam's rural provinces and India's tier-3 cities.
- Additives:Detergent-dispersant packages and viscosity index improvers enable specification customization for regional climate variation.
Mature deployment sits with Mineral formulations. Newer deployment is concentrated in Synthetic grades.
End User:
Vehicle parc composition and utilization intensity drive lubricant consumption velocity and formulation requirements.
- Passenger Vehicles:Turbocharged gasoline direct-injection engines in Japanese and Korean OEM fleets demand extended drain interval specifications. Maharashtra and Tamil Nadu manufacturing clusters are pre-positioning 0W-20 and 5W-30 portfolios for anticipated CAFE-equivalent regulations.
- Commercial Vehicles:High-mileage logistics fleets in Indonesia's Java north coast corridor generate bulk lubricant purchasing at scale. Fleet operator consolidation is compressing distributor margins while extending contract durations.
- Two-Wheelers:Mineral and semi-synthetic volumes dominate Vietnam's urban delivery segments and India's rural commuter markets.
- Heavy-Duty Trucks:Long-haul operators across ASEAN highway networks require high-total-base-number formulations for soot management in modern diesel aftertreatment systems.
Volume concentration rests with Two-Wheelers. Margin expansion is shifting toward Commercial Vehicles.
Service Type:
Maintenance channel structure determines brand control, customer data access, and attach-rate economics for value-added services.
- Quick Lube Services:Thailand and Malaysia chains are capturing disproportionate growth as time-compressed urban consumers abandon traditional workshop relationships. Ho Chi Minh City's peripheral industrial zones show similar channel migration.
- Full-Service Oil Change:Integrated maintenance bundling persists in premium vehicle segments across Australian and Japanese mature markets.
- DIY Maintenance:Contracting share in Japan and Australia reflects vehicle complexity and warranty preservation requirements.
- Fleet Services:Captive workshops and direct blender contracts are displacing general automotive repair channels for consolidated logistics operators in Indonesia and Vietnam.
DIY Maintenance retains foothold in mature economies. Fleet Services are climbing the fastest across Southeast Asian logistics corridors.
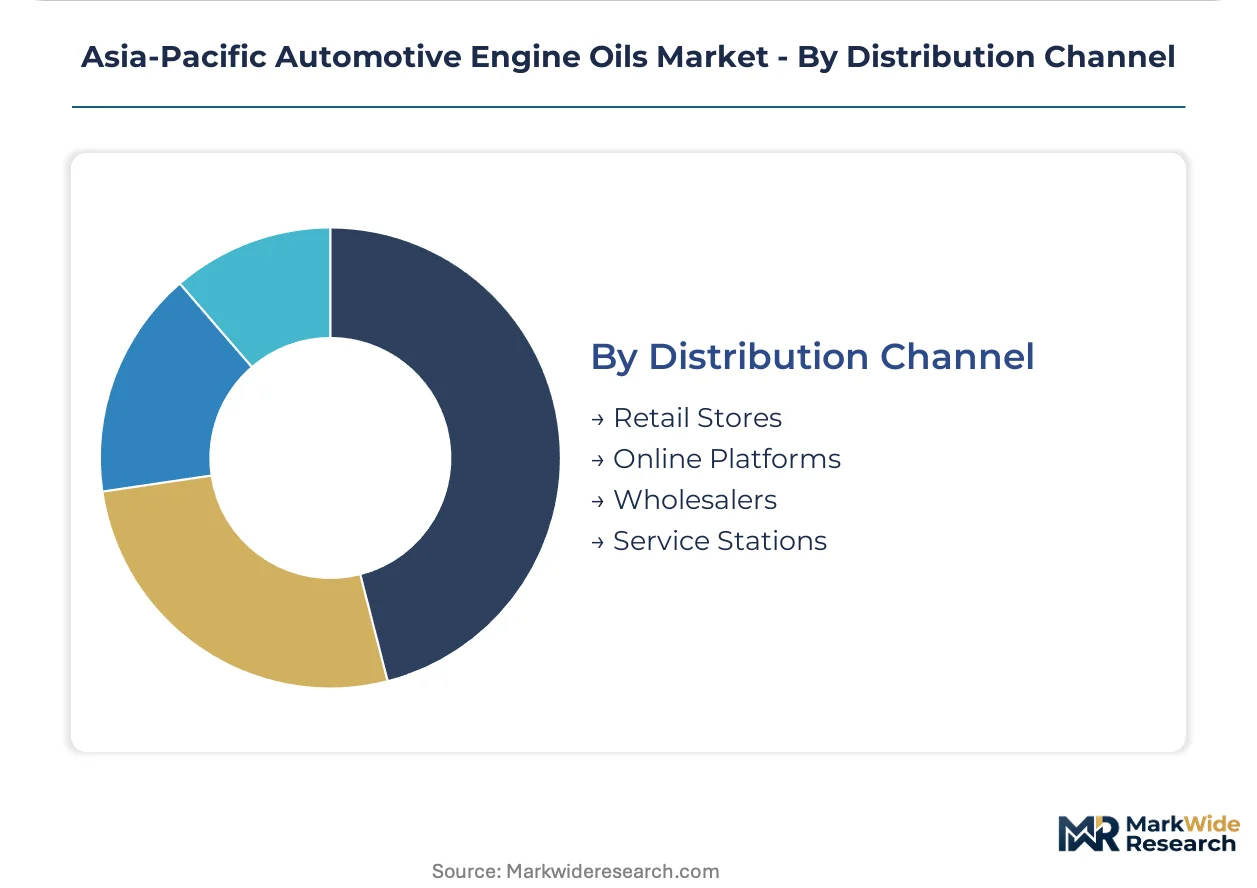
Distribution Channel:
Channel selection shapes working capital intensity, price transparency, and technical service attachment.
- Retail Stores:Branded lubricant presence in automotive parts chains serves enthusiast and warranty-conscious segments across Australian and Japanese markets.
- Online Platforms:E-commerce penetration in China's domestic market enables specification comparison and counterfeit verification through SAMR-mandated traceability systems.
- Wholesalers:Traditional distributor networks face margin compression as fleet procurement centralizes and quick lube chains negotiate direct supply.
- Service Stations:Petroleum retail networks leverage fuel-lubricant bundling in markets with concentrated national oil company presence.
Wholesalers retain volume leadership. Online Platforms are expanding most quickly in digitally mature markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's northern industrial corridor concentrates bulk lubricant procurement from state transport corporations and private fleet operators upgrading to synthetic formulations. China's passenger vehicle manufacturing clusters generate factory-fill demand aligned with MIIT fuel economy standards. Southeast Asian logistics networks in Indonesia and Vietnam are densifying commercial vehicle parc and amplifying service-fill volumes.
China
MIIT fuel economy standards are compressing formulation cycles for domestic OEM factory-fill. SAMR and GB standards govern product quality and import compliance. Yangtze River Delta and Pearl River Delta manufacturing clusters are pre-positioning 0W-20 and 5W-30 low-viscosity portfolios for anticipated fleet efficiency targets.
India
State transport corporations and private fleet operators in the northern industrial corridor are escalating synthetic penetration. BIS certification mandates elevate quality enforcement across OEM fill and service-fill channels. Maharashtra and Tamil Nadu passenger vehicle manufacturing clusters are upgrading formulation specifications ahead of proposed CAFE-equivalent regulations.
Japan
METI enforces stringent fuel efficiency benchmarks that cascade into lubricant viscosity grade requirements for domestic and export-oriented production. JIS standards govern technical specifications. Kanto and Kansai industrial zones absorb high-performance synthetic formulations through Japanese OEM service-fill channels at accelerated rates.
Indonesia
Commercial fleet densification across Java's north coast corridor generates bulk lubricant purchasing at scale from consolidated logistics operators. National infrastructure investment programs support highway network expansion. Jakarta and Surabaya metropolitan areas concentrate quick lube channel growth as fleet maintenance unbundles from traditional distributor relationships.
Vietnam
Two-wheeler parc in urban delivery segments and rural commuter markets continues consuming mineral and semi-synthetic volumes. Logistics network expansion amplifies heavy-duty truck lubricant demand. Ho Chi Minh City's peripheral industrial zones show concentrated channel migration toward fleet services and captive workshop arrangements.
Asia-Pacific Automotive Engine Oils Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue specification-driven premium positioning through synthetic formulation expertise. The vendor base organizes around three archetypes: integrated national oil companies with captive refinery capacity, multinational lubricant specialists with OEM approval portfolios, and regional blenders serving price-sensitive mineral segments. Competitive dynamics center on M&A activity consolidating Southeast Asian distribution networks and strategic partnerships securing additive package technology licensing.
Within the integrated national oil company tier, China National Petroleum Corporation and China Petroleum & Chemical Corporation anchor positions through captive refinery capacity and state-backed fleet service partnerships. Among multinational specialists, Shell plc and ExxonMobil Corporation exemplify volume leadership strategies leveraging integrated supply chains across Indonesian and Thai commercial vehicle segments. Idemitsu Kosan Co Ltd occupies a position representing high-performance synthetic formulation differentiation targeted at Japanese OEM specifications.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Shell plc |
| BP Plc (Castrol) |
| China National Petroleum Corporation |
| China Petroleum & Chemical Corporation |
| Indian Oil Corporation Limited |
| ENEOS Corporation |
| Idemitsu Kosan Co Ltd |
| TotalEnergies SE |
| Others |
Value Chain & Pricing Dynamics
Tribology specialists concentrated in Japan's Kanto and Kansai industrial zones command wage premiums that compress margins on high-performance additive packages, widening the spread between mineral-based economy formulations and synthetic premium tiers across ASEAN markets.
Pricing Analysis
Volume concentration in mineral and semi-synthetic grades serving Vietnam's two-wheeler parc and India's rural commuter markets compresses realized margins, while synthetic formulations for Japanese OEM specifications in Thailand and Malaysia sustain premium-mid-economy pricing differentiation. Price differentiation hinges on BIS certification grade and volume scale of fleet procurement contracts. Pricing pressure stems from Group III base oil supply concentration in Northeast Asian refineries. State transport corporations in India's northern industrial corridor exhibit highest price sensitivity; Japanese OEM service-fill channels show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Group III base oil output from South Korean and Japanese refineries feeding ASEAN synthetic blenders. Formulation chemistry draws from additive packages sourced from Germany, the United States, and Japan. Logistics chokepoints at Singapore's port hub concentrate risk for regional distribution. Distribution runs through petroleum retail networks with fuel-lubricant bundling in markets with dominant national oil company presence, supplemented by direct blender contracts with consolidated fleet operators in Indonesia and Vietnam.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific automotive engine oils represent a consolidation play as BIS certification mandates and MIIT fuel economy standards force sub-scale blenders into exit or acquisition.
For Market Incumbents: Cement position through captive refinery capacity expansion in Northeast Asia and additive package technology licensing from Japanese tribology specialists. Threat from emerging regional blenders with state-backed fleet service partnerships demands preemptive channel control in Indonesia's Java north coast corridor. Backward integration into Group III base oil supply is the critical lever. For New Entrants and Emerging Players: E-commerce platforms with SAMR-mandated traceability systems offer the lowest-friction route into China's domestic market. White space sits with quick lube chain supply in Thailand and Malaysia, and direct fleet contracts in Vietnam's Ho Chi Minh City peripheral industrial zones. Pursue specification-driven premium positioning through PAO synthetic formulations rather than mineral volume plays. For Investors and Strategic Acquirers: Re-rating potential sits with mid-cap blenders possessing BIS-certified portfolios and established OEM relationships given India's proposed CAFE-equivalent regulations. Long-term viability centers on synthetic formulation expertise transferable across Japanese, Korean, and Chinese OEM specifications. Watch for fleet operator consolidation announcements in Indonesia and Vietnam as inflection signals for multi-year contract availability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Supply | Captive Group III capacity insulates blenders from Northeast Asian refinery volatility. |
| Quick Lube Channel Expansion | Thailand and Malaysia chains displace traditional workshops with time-compressed service models. |
| BIS Certification Investment | Quality enforcement in India's northern corridor elevates compliant blenders above mineral competitors. |
| Fleet Service Partnership | Direct contracts with Indonesian logistics operators compress distributor margins and extend durations. |
| Low-Viscosity Portfolio Repositioning | 0W-20 and 5W-30 formulations align with MIIT standards in China's Yangtze River Delta clusters. |
Study Parameters
Trade publications, refinery capacity databases, and national standards filings formed the secondary backbone, supplemented by primary interviews with lubricant blending plant managers, procurement leads at Indian state transport corporations, additive package R&D directors, and quick lube chain operations heads. Customs data on base oil imports and BIS certification registries provided volume anchors. Bottom-up and top-down triangulation reconciled channel-level consumption estimates with OEM factory-fill projections.
Bottom-up modeling aggregated fleet operator procurement patterns, quick lube chain throughput, and retail channel sell-through across the projection horizon. Top-down validation cross-checked against vehicle parc expansion and drain interval extension assumptions. Segmentation dimensions spanned formulation chemistry, service architecture, vehicle class, and regional regulatory cluster. CAGRs derived from slope analysis of base oil demand curves and OEM specification migration timelines.
Inputs from refinery utilization reports and fleet operator contract disclosures were available through the study window; gaps in informal two-wheeler service channel data introduce uncertainty bands around Vietnam and India's rural volume estimates. Forecasts reflect assumptions on regulatory implementation pacing and synthetic substitution elasticity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Clutch Slave Cylinder Market
Powertrain
Torque Limiter Market
Powertrain
Automotive Turbocharger Market
Powertrain
Global Hydrogen Combustion Engine Market
Powertrain
Automotive Vacuum Pump Market
Powertrain
Internal Combustion Engine Market
Powertrain
Automotive Camless Engine Market
Powertrain
Russia Electro Hydraulic Power Steering Market
Powertrain
Automotive Cylinder Block Market
Powertrain
Automotive Turbo-Compounding System Market
Powertrain
Engine Actuators Market
Powertrain
Turbocharger Actuators Market
Powertrain
Automotive Coil Spring Market
Powertrain
Power Transmission Gearbox Market
Powertrain
Tuning Box Market
Powertrain
Italy Electro Hydraulic Power Steering Market