
 Emission Control Catalyst for Small Engines Market | 2026-2036
Emission Control Catalyst for Small Engines Market Size, Share, and Industry Trends Forecast 2026-2036
Emission Control Catalyst for Small Engines Market Foresight
The buyer base for emission control catalysts is broadening beyond traditional automotive OEMs into lawn equipment and marine engine manufacturers. BASF leverages its substrate coating expertise to serve this expanding customer set. Johnson Matthey anchors its position through advanced three-way catalyst formulations optimized for sub-1-liter displacements. Tenneco competes with vertically integrated manufacturing from raw material sourcing to canister assembly.
An emission control catalyst for small engines is a coated ceramic or metallic substrate containing platinum-group metals that accelerates oxidation of carbon monoxide and hydrocarbons while reducing nitrogen oxides in exhaust streams below 19 kW. These systems operate at lower temperatures than heavy-duty catalysts and must withstand thermal shock from intermittent engine cycles. Three-way catalysts dominate value capture due to their simultaneous NOx, CO, and HC reduction capability across automotive and power generator applications. Diesel oxidation catalysts sustain steady demand in compact marine propulsion where lean-burn architectures preclude three-way operation. Selective catalytic reduction systems remain nascent in this power class but attract R&D investment for future regulatory thresholds.
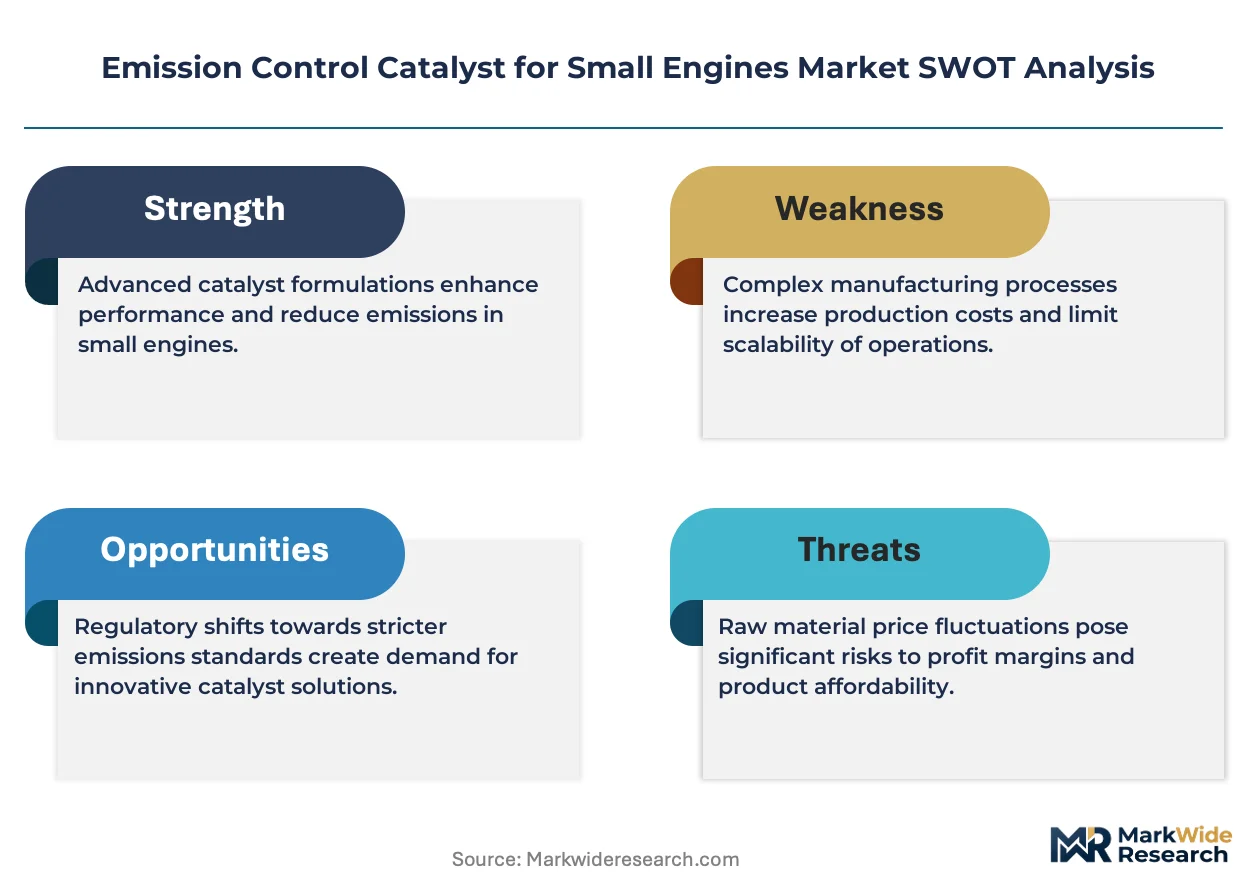
The EPA administers emission certification for small spark-ignition and compression-ignition engines under 40 CFR Part 90 and Part 1039, mandating phased reductions in hydrocarbon and particulate matter. California ARB imposes supplemental Tier 4 standards that OEMs must meet for products sold within the state, effectively setting a de facto national benchmark. The EU F-Gas Regulation and Stage V standards for non-road mobile machinery shape export design requirements for catalyst suppliers serving European lawn equipment manufacturers. Stakeholders must monitor how state-level zero-emission mandates for outdoor power equipment redirect R&D budgets away from catalyst optimization toward electrification pathways.
Market Dynamics
EPA Phase 3 emission standards are compressing hydrocarbon limits for spark-ignition engines below 19 kW, forcing lawn equipment OEMs to abandon oxidation-only catalysts in favor of platinum-group metal formulations that operate across intermittent thermal cycles.
Growth Catalysts
- California ARB Tier 4 standards:These supplemental rules for non-road engines create a de facto national benchmark that OEMs must meet for products sold within the state, expanding addressable catalyst volume.
- Platinum-rhodium-palladium formulations:Advanced three-way catalyst designs now deliver simultaneous NOx, CO, and HC reduction in sub-1-liter displacements, opening marine and power generator applications previously served by oxidation-only systems.
- Export design convergence:EU Stage V standards for non-road mobile machinery compel catalyst suppliers to engineer single-SKU solutions that satisfy both US and European certification requirements.
Market Restraints
- Platinum-group metal price volatility:Palladium and rhodium spot markets expose catalyst manufacturers to input cost swings that compress margin buffers on fixed-price OEM contracts.
- Substrate supply concentration:Ceramic honeycomb production clusters in Germany and Japan, creating geographic single-source risk for North American catalyst coaters.
- Zero-emission equipment mandates:California and New York state-level bans on gasoline-powered outdoor power equipment redirect OEM R&D budgets toward battery-electric platforms rather than catalyst optimization.
Strategic Opportunities
- Compact marine propulsion:Diesel oxidation catalysts sustain steady demand in lean-burn outboard engines where three-way architectures cannot operate, offering a defensible niche as spark-ignition applications electrify.
- Selective catalytic reduction miniaturization:urea-based SCR systems for sub-19 kW engines attract development investment ahead of anticipated future NOx thresholds.
- Aftermarket service channels:Independent repair networks for lawn equipment present a direct-to-installer route that bypasses consolidated OEM procurement desks.
Industry Challenges
- Thermal shock engineering:Catalyst substrates must withstand rapid temperature swings from intermittent small-engine operation without coating delamination, demanding specialized ceramic formulation expertise.
- Dual-certification complexity:Engineers must reconcile EPA 40 CFR Part 90 test cycles with EU Stage V measurement protocols within compressed product development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Emission Control Catalyst for Small Engines Market |
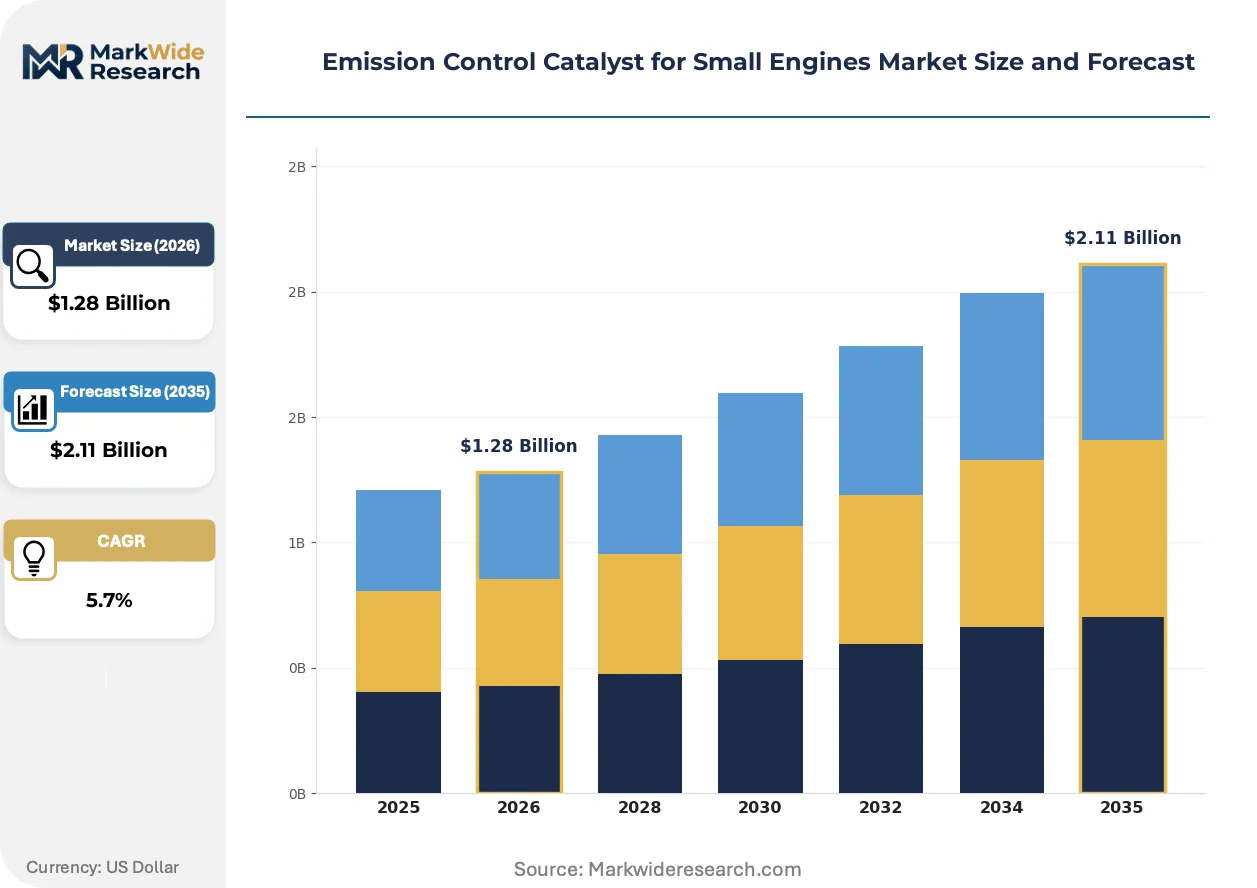
| Market Size in 2026 | $1.28 Billion |
| Market Size in 2035 | $2.11 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Three-way Catalysts, Diesel Oxidation Catalysts, Lean NOx Traps, Selective Catalytic Reduction Systems Technology: Substrate Coating, Active Metal Components, Catalyst Formulation, Support Material Application: Automotive, Lawn Equipment, Marine Engines, Power Generators End User: OEMs, Aftermarket Suppliers, Fleet Operators, Distributors |
| Companies Covered | Cataler Corporation, Tenneco, BASF, Cormetech, Heraeus, Johnson Matthey, Clariant, NGK Insulators, Umicore, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emission Control Catalyst for Small Engines Market Shifts & Advancements
Platinum-group metal chemistry and ceramic substrate engineering are converging to enable three-way catalyst performance in thermal regimes previously considered too cold for effective NOx reduction. These material advances are unifying product architectures across lawn, marine, and power generation applications.
Washcoat formulations incorporating ceria-zirconia mixed oxides is unifying low-temperature light-off performance with high-temperature durability. Lawn equipment OEMs are adopting these substrates at accelerated pace to meet 2024-2025 EPA certification deadlines. The technology is unifying previously separate oxidation and reduction catalyst components into single-canister designs that reduce exhaust system weight and packaging volume.
California ARB is advancing zero-emission mandates for handheld and walk-behind equipment on faster timelines than federal rules, compressing the commercial window for catalyst-dependent products. OEMs are responding by bifurcating R&D portfolios between near-term catalyst compliance and long-term electrification. The tension forces catalyst suppliers to defend existing revenue streams while managing declining addressable market assumptions.
Equipment fleet operators are consolidating procurement decisions at regional distributor level rather than individual dealer level, compressing supplier negotiation leverage. This channel concentration displaces fragmented purchasing patterns that previously allowed catalyst manufacturers to price discriminate across customer tiers. The shift is most visible in commercial landscaping services across the southeastern United States, where national rental chains now specify catalyst performance requirements directly.
Emission Control Catalyst for Small Engines Market Segmentation
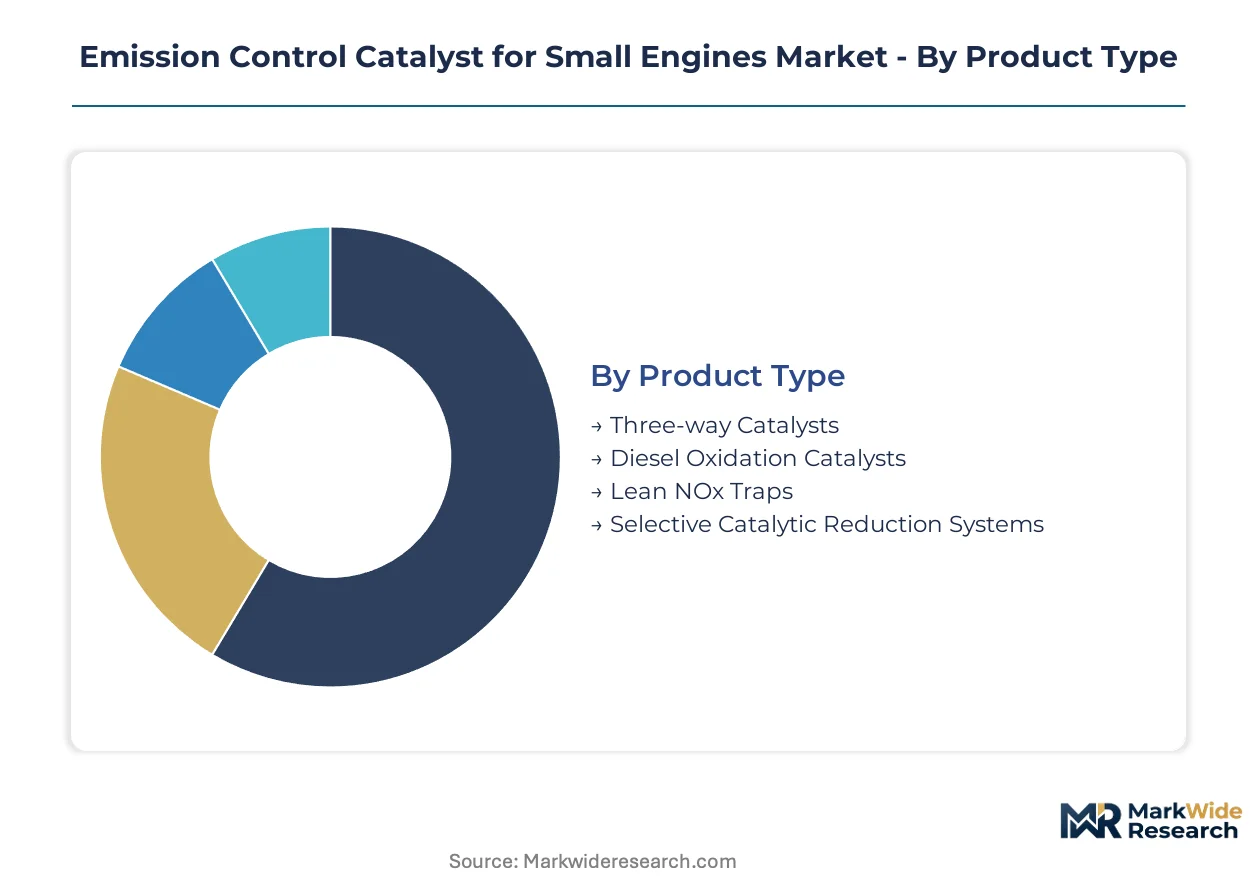
Segmentation in emission control catalysts for small engines reveals how regulatory pressure and thermal engineering constraints fragment demand across incompatible technology architectures. Catalyst suppliers must maintain parallel production lines for oxidation-only, three-way, and emerging SCR formulations while serving divergent customer procurement patterns.
Product Type:
Volume production concentrates in three-way formulations, while premium pricing attaches to systems addressing lean-burn combustion challenges.
- Three-way Catalysts:Platinum-rhodium-palladium formulations on ceramic honeycomb substrates enable simultaneous NOx, CO, and HC reduction in stoichiometric spark-ignition engines below 19 kW. Demand clusters in California-compliant lawn equipment and portable generators where EPA Phase 3 hydrocarbon limits have eliminated oxidation-only alternatives.
- Diesel Oxidation Catalysts:Palladium-promoted alumina washcoats accelerate CO and hydrocarbon oxidation without NOx reduction capability, serving lean-burn marine outboards and compact diesel power units. Steady order flow persists from European Stage V non-road machinery exports and commercial marine fleets operating in EPA-regulated waterways.
- Lean NOx Traps:Periodic regeneration architectures store and release nitrogen oxides through barium-based sorbents.
- Selective Catalytic Reduction Systems:Urea-dosing miniaturization for sub-19 kW engines attracts pre-commercial development investment.
Mature deployment sits with three-way catalysts. Newer deployment is concentrated in selective catalytic reduction systems.
Technology:
Process control separates commodity coaters from specialists capable of precise platinum-group metal dispersion.
- Substrate Coating:Precision-controlled washcoat deposition onto cordierite or metallic honeycomb structures determines active surface area and thermal durability. German and Japanese ceramic substrate suppliers dominate upstream supply, forcing North American coaters to manage inventory exposure across ocean freight timelines.
- Active Metal Components:Platinum, palladium, and rhodium loading specifications vary by emission certification tier rather than engine displacement alone. California ARB Tier 4 and federal EPA small-engine rules create dual-track procurement where metal loadings diverge for otherwise identical engine platforms.
- Catalyst Formulation:Ceria-zirconia oxygen storage components enable low-temperature light-off performance.
- Support Material:Gamma-alumina and alternative oxide carriers stabilize metal dispersion under thermal shock.
Established production anchors substrate coating. Emerging capability investment flows toward active metal component optimization.
Application:
Customer concentration differs sharply between seasonal consumer purchases and year-round commercial fleet operations.
- Lawn Equipment:Walk-behind mowers, riding tractors, and handheld power tools generate the largest catalyst volume as EPA Phase 3 compliance deadlines force oxidation-catalyst retrofits. California zero-emission mandates for handheld equipment compress the commercial window, accelerating near-term demand before anticipated electrification displacement.
- Marine Engines:Outboard and inboard propulsion systems in recreational and light-commercial vessels operate under Coast Guard and EPA marine certification. Diesel oxidation catalysts sustain demand in lean-burn architectures where three-way operation is thermodynamically impossible, offering a defensible niche as spark-ignition applications face electrification pressure.
- Power Generators:Portable and standby units for residential and commercial backup power.
- Automotive:Auxiliary power units and niche vehicle applications below standard automotive displacement thresholds.
Volume concentration rests with lawn equipment. Technology complexity concentrates in marine engines.
End User:
Procurement leverage varies from consolidated OEM engineering specifications to fragmented distributor price negotiations.
- OEMs:Briggs & Stratton, Honda Power Equipment, and Toro specify catalyst performance requirements directly, consolidating procurement decisions at corporate engineering level. These customers demand dual-certification engineering for simultaneous EPA and EU compliance, compressing supplier margins through volume guarantees and technical support obligations.
- Aftermarket Suppliers:Independent repair networks and parts distributors serve equipment beyond warranty periods, purchasing catalysts as replacement canisters or core substrates for recoating. This channel bypasses OEM procurement desks but requires inventory breadth across obsolete and current engine platforms.
- Fleet Operators:Commercial landscaping and rental chains specify performance directly to distributors.
- Distributors:Regional parts wholesalers aggregate demand from dealer networks.
Contract security aligns with OEMs. Margin expansion opportunity sits with aftermarket suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platinum-group metal refining clusters in South Africa and Russia shape raw-material access for catalyst coaters worldwide. These feedstock localities determine cost structures for manufacturers serving lawn equipment and marine engine OEMs across North America, Europe, and Asia-Pacific.
United States
California ARB Tier 4 standards and EPA 40 CFR Part 90 rules create the strictest compliance environment globally for spark-ignition engines below 19 kW. The Los Angeles Basin and Central Valley host testing facilities where OEMs validate catalyst formulations for nationwide certification. Lawn equipment manufacturers in Wisconsin and Illinois accelerate platinum-rhodium-palladium adoption ahead of 2024-2025 deadlines.
Germany
Ceramic honeycomb substrate production concentrates in industrial regions supplying European coaters with cordierite structures. EU Stage V standards for non-road mobile machinery compel dual-certification engineering for export-bound lawn equipment. The Stuttgart and Munich metropolitan areas anchor R&D investment in ceria-zirconia washcoat formulations optimized for intermittent small-engine thermal cycles.
Japan
Metallic substrate manufacturing expertise supports precision coating operations for compact marine propulsion systems. METI industrial standards align with EPA marine certification requirements for outboard engines exported to North American markets. The Nagoya industrial corridor houses production facilities serving both domestic power equipment OEMs and US-bound export volumes.
China
Domestic lawn equipment manufacturing scales to serve Asia-Pacific demand as GB standards for non-road engines tighten hydrocarbon limits. The Yangtze River Delta hosts catalyst coating operations supplying both local OEMs and European export customers. Zhejiang and Jiangsu provinces concentrate small-engine production requiring oxidation-catalyst retrofits for emerging compliance deadlines.
India
Power generator manufacturing for residential backup applications drives catalyst demand as BIS emission norms extend to sub-19 kW engines. The Pune-Nashik industrial belt houses small-engine OEMs evaluating three-way catalyst architectures for stoichiometric gasoline platforms. Maharashtra-based fabricators face pricing pressure from platinum-group metal volatility while scaling coating capacity.
Emission Control Catalyst for Small Engines Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue selective catalytic reduction miniaturization for future regulatory thresholds. The vendor base separates into substrate specialists, formulation chemists, and vertically integrated canister assemblers. Three archetypes dominate: precious metal traders backward-integrated into coating, ceramic honeycomb manufacturers forward-integrated into catalyst production, and automotive catalyst suppliers extending into small-engine adjacent markets. Competitive moves concentrate on dual-certification engineering capabilities and geographic proximity to lawn equipment OEM engineering centers.
Within the precious metal chemistry tier, Johnson Matthey and BASF exemplify formulation expertise extending from automotive into sub-1-liter displacement applications. Tenneco anchors the vertically integrated archetype through captive canister assembly operations. These three entities represent distinct strategic positions: Johnson Matthey occupies the advanced three-way catalyst specialization; BASF leverages substrate coating scale; Tenneco integrates raw material sourcing through finished exhaust system delivery.
| Leading Market Players |
|---|
| Cataler Corporation |
| Tenneco |
| BASF |
| Cormetech |
| Heraeus |
| Johnson Matthey |
| Clariant |
| NGK Insulators |
| Umicore |
| Others |
Supply & Pricing Matrix
Captive coating operations at BASF and Johnson Matthey anchor supply positions while compressing margin buffers for independent coaters competing on raw material pass-through. OEM procurement desks exploit this asymmetry to extract volume guarantees on fixed-price contracts that expose suppliers to platinum-group metal volatility.
Pricing Analysis
Warranty and technical service bundling separates premium three-way catalyst suppliers from commodity oxidation-catalyst vendors serving aftermarket channels. Pricing stratifies across California ARB Tier 4 certification, federal EPA compliance, and uncertified replacement tiers, with metal loading specifications driving differentiation. Cost compression in standard-grade formulations is intensifying because lawn equipment OEMs consolidate procurement at corporate engineering level. Fleet operators and rental chains exhibit highest price sensitivity due to volume scale, while marine engine manufacturers accept premium positioning for thermal shock durability.
Supply Chain Analysis
Dual-sourcing mandates from Briggs & Stratton and Honda Power Equipment force coaters to qualify ceramic substrates from both German and Japanese suppliers simultaneously. Cordierite honeycomb production draws from Germany and Japan, while platinum-group metal refining rests on South Africa and Russia. Single-source vulnerability concentrates in ocean freight timelines for ceramic substrates. Distribution runs through OEM direct procurement desks for original equipment and regional parts wholesalers for aftermarket replacement canisters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market occupies a technology-transition phase as three-way catalyst architectures displace oxidation-only designs across sub-1-liter spark-ignition engines.
For Market Incumbents: Deepen captive substrate coating capacity in Wisconsin and Illinois to defend against platinum-group metal price volatility eroding fixed-price contract margins. Secure dual-certification engineering capabilities for simultaneous EPA and EU Stage V compliance to maintain OEM specification control. For New Entrants and Emerging Players: Enter via compact marine propulsion diesel oxidation catalysts where lean-burn architectures preclude three-way operation and electrification pressure remains muted. Target aftermarket service channels for independent repair networks as a direct-to-installer route bypassing consolidated OEM procurement. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by automotive catalyst suppliers extending into small-engine adjacent markets. Five-to-ten year viability hinges on regulatory enforcement durability against electrification displacement. Watch California ARB zero-emission mandate expansion timelines as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Ceria-Zirconia Washcoat Investment | Enables low-temperature light-off performance for EPA Phase 3 compliance deadlines. |
| Dual-Certification Engineering | Reconciles EPA 40 CFR Part 90 test cycles with EU Stage V protocols for single-SKU solutions. |
| Backward Integration into Substrate Coating | Captures margin from ceramic honeycomb supply concentration in Germany and Japan. |
| Aftermarket Channel Development | Bypasses consolidated OEM procurement desks through independent repair network relationships. |
| SCR Miniaturization R&D | Positions for anticipated future NOx thresholds in sub-19 kW engine classes. |
Research Methodology
Document review covered EPA certification filings, EU Stage V technical documentation, and platinum-group metal trade flow data, complemented by interviews with catalyst formulation chemists, lawn equipment OEM procurement directors, and marine engine compliance engineers. Secondary validation drew from customs records, SEC 10-K disclosures by listed suppliers, and automotive catalyst production databases. Bottom-up volume estimates triangulated against top-down market sizing across product type, application, and end user segments.
Cross-referencing historical platinum-group metal price elasticities with expert panel inputs on regulatory enforcement probabilities shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include catalyst architecture, engine displacement class, certification tier, and regional regulatory cluster. CAGRs derived from regression analysis of historical adoption curves applied to phased compliance deadlines. Industry-specific inputs incorporated thermal shock engineering constraints and intermittent engine cycle duty profiles.
Revisions become necessary when California ARB accelerates zero-emission mandates or EPA relaxes small-engine hydrocarbon limits materialize. Deviation in platinum-group metal spot market volatility would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Powertrain Components Market
Powertrain
Car Oil Filter Market
Powertrain
Automotive Brake Booster Market
Powertrain
Global Automotive Electric Drivetrain System Market
Powertrain
Global Automotive Engine Pulley Market
Powertrain
South Korea Electro Hydraulic Power Steering Market
Powertrain
Clutch Market
Powertrain
Global Industrial Engine Market
Powertrain
Global Automotive Torque Converter Market
Powertrain
Automotive Power Distribution Block Market
Powertrain
Internal Combustion Engine Market
Powertrain
Automotive Engine Cylinder Block Market
Powertrain
Diesel Particulate Filter (DPF) Market
Powertrain
Natural Gas Engines Market
Powertrain
LNG Engine Market
Powertrain
Global Automotive Tappet Market