
 Singapore Chemical Logistics Market | 2026-2036
Singapore Chemical Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Chemical Logistics Market Insights
Market Context
Southeast Asia is tilting toward integrated chemical supply chain hubs, with Singapore capturing upstream flows from Indonesian and Malaysian production zones. DHL leverages its temperature-controlled network to serve pharmaceutical clients across ASEAN. Kuehne+Nagel anchors its regional headquarters in Singapore to coordinate maritime and air freight corridors. PSA Chemical Logistics dominates the port-centric storage and transshipment segment through its Jurong Island terminal infrastructure.
Technical Definition and Segments
Chemical logistics encompasses the specialized transportation, warehousing, and handling of hazardous and non-hazardous chemical substances under controlled temperature, pressure, and containment parameters, utilizing UN-certified packaging, double-hulled tankers, and automated inventory systems to prevent contamination, spillage, or reactive incidents during multimodal transit. The primary commercial purpose centers on maintaining product integrity and regulatory compliance while optimizing inventory velocity for manufacturers and distributors. Maritime delivery mode carries the heaviest volume throughput given Singapore's port infrastructure, while specialty chemicals command premium margin pools due to stringent handling protocols and smaller batch requirements. Bulk chemicals represent the mature, high-volume baseline segment where price competition intensifies and operational scale determines profitability.
Regulatory Frame
Singapore's Workplace Safety and Health Council, the National Environment Agency, and the Maritime and Port Authority collectively enforce chemical storage limits, discharge controls, and dangerous goods handling certifications that shape facility design and operational expenditure for logistics providers. These frameworks elevate compliance costs but simultaneously create barriers that favor established operators with certified infrastructure over new entrants. Stakeholders must monitor evolving carbon accounting rules for Scope 3 emissions across chemical supply chains, as Singapore advances its national sustainability disclosure requirements in alignment with broader ASEAN green taxonomy developments.
Market Dynamics
Jurong Island's petrochemical cluster concentration is tightening storage capacity and forcing logistics providers to densify operations through automation and vertical stacking systems.
Growth Catalysts
- Workplace Safety and Health Act enforcement:Singapore's tightened storage compliance standards are accelerating facility upgrades and consolidating demand toward certified operators with advanced containment infrastructure.
- Pharmaceutical manufacturing expansion:Specialty chemicals handling protocols are attracting biologics producers who require temperature-controlled distribution networks anchored in Singapore's port infrastructure.
- ASEAN upstream flows:Indonesian and Malaysian production zones are routing more chemical volumes through Singaporean transshipment hubs, deepening the island's role as a regional consolidation point.
Market Restraints
- Land scarcity:Singapore's limited industrial land availability is compressing warehouse footprints and elevating per-square-meter storage costs above regional competitors.
- Specialized tankage concentration:A small pool of certified providers controls Jurong Island's hazardous liquid storage, creating bottleneck risks during demand surges.
- Carbon accounting compliance:Emerging Scope 3 disclosure requirements are forcing logistics operators to invest in emissions tracking systems without immediate revenue recovery mechanisms.
Strategic Opportunities
- Bio-based chemical logistics:Singapore's national sustainability disclosure alignment with ASEAN green taxonomy developments is creating premium service tiers for low-carbon supply chain certification.
- Digital twin integration:Convergence of IoT sensor networks with predictive analytics platforms is enabling real-time inventory optimization for pharmaceutical clients with batch-level traceability requirements.
- Peninsular Malaysia corridor:Underdeveloped cross-border chemical rail and pipeline infrastructure presents first-mover advantages for multimodal operators establishing Johor-Singapore linkages.
Industry Challenges
- Hazmat certification pipelines:Singapore's dangerous goods handling certifications face extended training timelines, constraining workforce scaling for specialty chemicals operations.
- Legacy system integration:Automated inventory systems require costly retrofitting to interface with incumbent warehouse management platforms used by established petrochemical traders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Chemical Logistics Market |
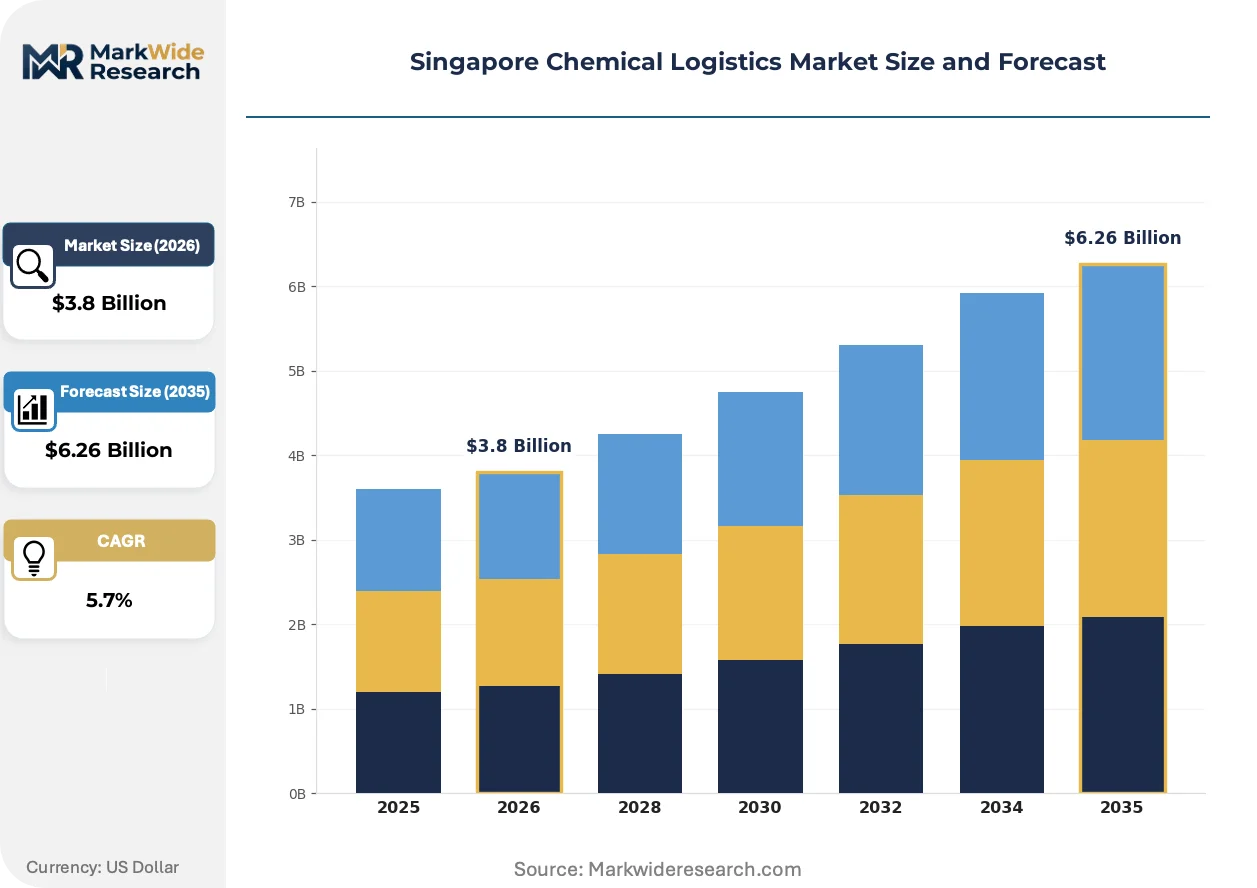
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Specialty Chemicals, Agrochemicals, Petrochemicals, Bulk Chemicals Packaging Type: Drums, IBCs, Bags, Containers Delivery Mode: Overland, Maritime, Air Freight, Rail End User: Manufacturing, Pharmaceuticals, Agriculture, Construction |
| Companies Covered | ALPS Global Logistics, Bertschi Singapore Pte Ltd, DHL, Kuehne+Nagel, PSA Chemical Logistics, Koyo Kaiun Co., Ltd., Iino Singapore Pte Ltd, Fairfield Chemical Carriers, MCL Logistics Asia Pte Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Chemical Logistics Market Trends and Innovations
Digital infrastructure is compressing decision cycles across Singapore's chemical logistics value chain, with automation and predictive systems displacing manual coordination layers.
Digital twin platforms are virtualizing warehouse operations and tank farm management, creating real-time simulations of temperature, pressure, and inventory flows. Pharmaceutical manufacturers with biologics portfolios are adopting these systems fastest, requiring batch-level environmental traceability. The technology is virtualizing traditional physical inspection protocols and enabling remote compliance auditing.
Singapore's Workplace Safety and Health Council is mandating enhanced containment infrastructure certifications for hazardous chemicals storage facilities. Industrial consequence includes accelerated capital deployment toward double-walled tankage and automated leak detection systems. Specialty chemicals handlers with pharmaceutical contracts are absorbing these costs fastest to maintain audit readiness.
Consolidated procurement models are displacing fragmented spot contracting among ASEAN chemical distributors. Large pharmaceutical manufacturers are centralizing logistics spend through multi-year service agreements with integrated temperature-controlled network operators. This concentration is most visible in Singapore's biologics corridor, where single-source logistics partnerships are becoming standard.
Singapore Chemical Logistics Market Segmentation
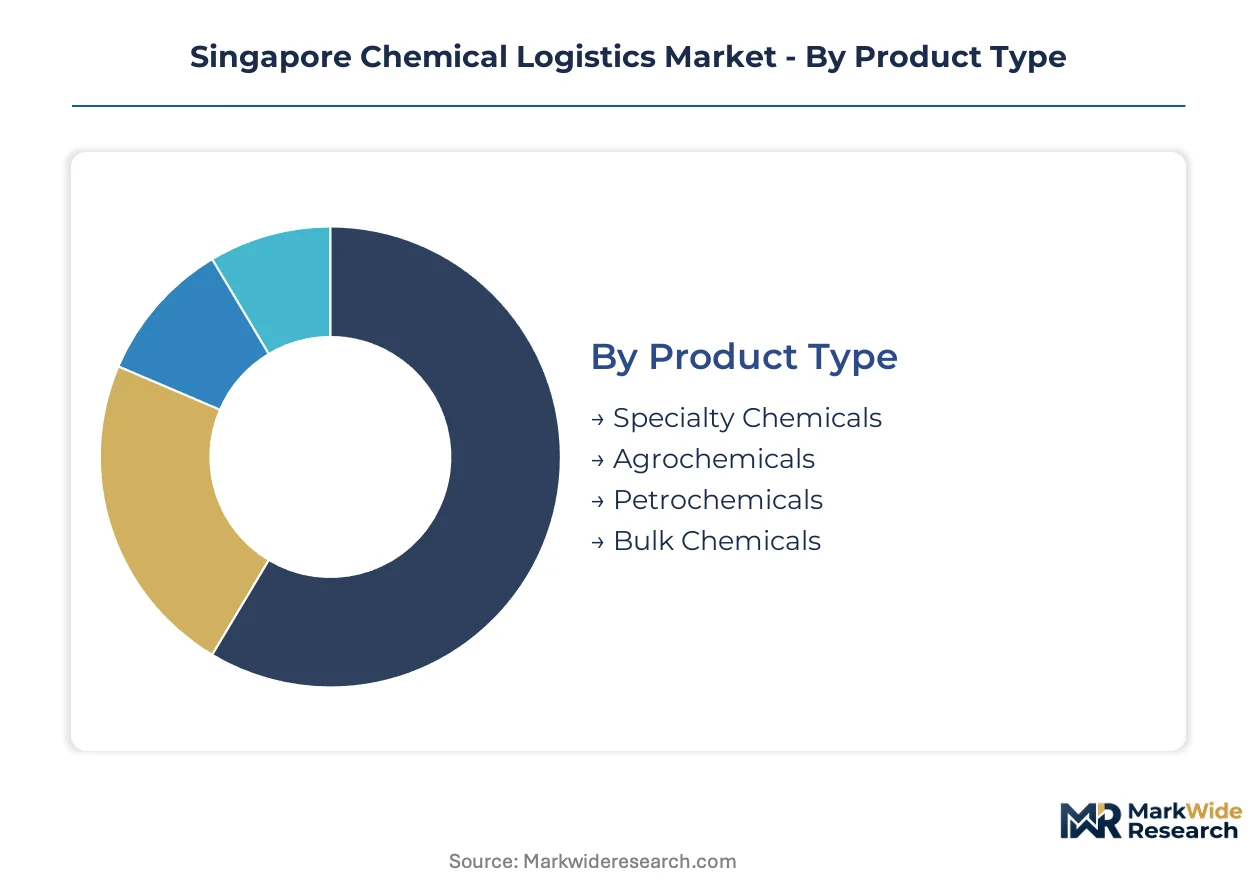
Singapore's chemical logistics segmentation reflects the island's dual role as a high-volume petrochemical transshipment hub and a precision pharmaceutical distribution gateway. Each dimension carries distinct infrastructure requirements, certification burdens, and margin structures that shape provider specialization.
Product Type:
The use-case spectrum spans commodity-scale bulk movements to batch-sensitive specialty handling, with each tier demanding differentiated containment protocols and workforce certifications.
- Specialty Chemicals:High-purity substances requiring temperature-controlled environments, UN-certified packaging, and batch-level traceability systems. Pharmaceutical manufacturers in Singapore's biologics corridor are consolidating procurement through multi-year service agreements with certified handlers, absorbing premium costs for audit-ready infrastructure.
- Petrochemicals:Large-volume hydrocarbon derivatives moving through Jurong Island's tank farm network under Maritime and Port Authority discharge controls. PSA Chemical Logistics anchors regional throughput through dedicated terminal infrastructure, though land scarcity is compressing expansion footprints and elevating per-cubic-meter storage economics.
- Agrochemicals:Pesticide and fertilizer compounds regulated under National Environment Agency storage limits for hazardous runoff prevention.
- Bulk Chemicals:Standardized industrial feedstocks where operational scale determines profitability and price competition intensifies.
Established volume favors petrochemicals; emerging adoption favors specialty chemicals.
Packaging Type:
Container geometry and material specification directly determine handling automation compatibility and regulatory compliance pathways across Singapore's dense warehouse footprint.
- IBCs:Intermediate bulk containers optimize cubic efficiency for liquid specialty chemicals and enable forklift-automated stacking in vertical warehouse configurations. Pharmaceutical clients demand stainless-steel IBC variants with integrated temperature monitoring for biologics distribution.
- Drums:Steel and fiber drums remain the workhorse for hazardous liquid chemicals requiring double-walled containment certifications under Workplace Safety and Health Council mandates.
- Containers:ISO tank containers dominate maritime transshipment corridors, with Jurong Island operators retrofitting fleets for carbon accounting traceability.
- Bags:Flexible intermediate bulk sacks handle powdered agrochemicals and construction chemicals with lower per-unit handling costs.
Maritime throughput concentrates in containers; pharmaceutical precision drives IBC specification upgrades.
Delivery Mode:
Modal selection balances speed requirements against Singapore's geographic constraints and cross-border infrastructure limitations.
- Maritime:Double-hulled tankers and chemical tank containers carry the heaviest volume throughput through Singapore's port infrastructure, anchored by PSA's terminal network.
- Overland:Truck fleets serve Jurong Island's petrochemical cluster and last-mile pharmaceutical distribution, constrained by land scarcity and elevated per-kilometer costs.
- Air Freight:Temperature-controlled cargo commands premium positioning for pharmaceutical time-sensitive biologics, with Changi Airport's cold chain infrastructure serving ASEAN manufacturing.
- Rail:Underdeveloped cross-border chemical rail infrastructure presents expansion constraints, though Johor-Singapore linkages offer first-mover construction opportunities.
Volume gravity centers on maritime; air freight captures the steepest expansion trajectory from pharmaceutical demand.
End User:
Customer-type differentiation separates commodity-scale procurement patterns from compliance-intensive specialty requirements.
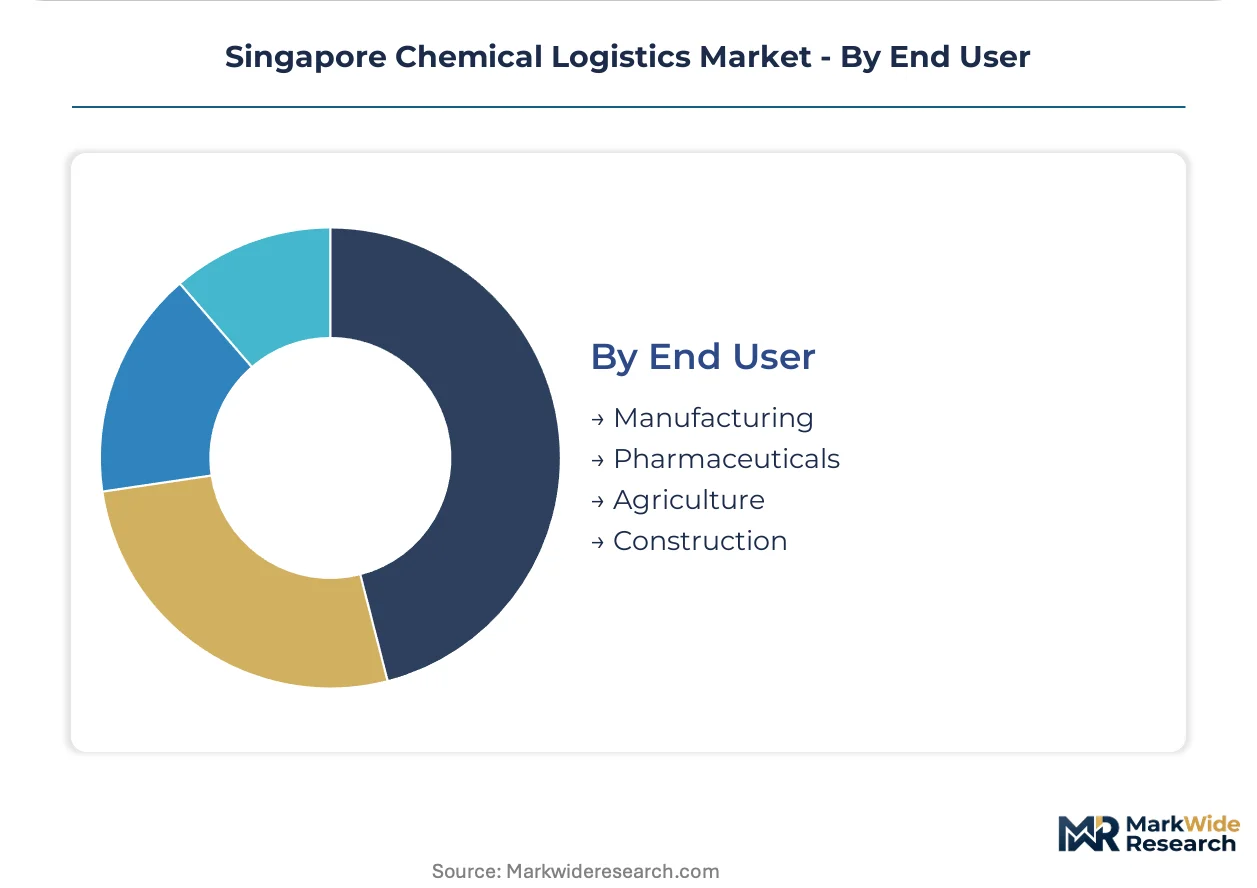
- Pharmaceuticals:Biologics producers require batch-level environmental traceability, digital twin integration, and temperature-controlled network coverage. Singapore's Workplace Safety and Health Act enforcement is accelerating facility upgrades among handlers serving this segment.
- Manufacturing:Industrial chemical consumers span electronics, automotive, and precision engineering sectors with standardized bulk procurement cycles.
- Agriculture:Agrochemical distributors face National Environment Agency discharge controls and seasonal demand volatility.
- Construction:Adhesives, sealants, and coatings move through less stringent handling protocols with price-sensitive procurement.
Compliance investment concentrates in pharmaceuticals; volume scale concentrates in manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesian and Malaysian chemical producers route upstream flows through Singaporean transshipment hubs, while Vietnam and Thailand are building captive port capacity to reduce dependency on Singaporean intermediation. This consumption-mix differential shapes competitive positioning across Southeast Asia's chemical logistics corridor.
Indonesia
Bontang and Balikpapan petrochemical complexes generate substantial liquid bulk volumes requiring temperature-controlled maritime transit. The country's national environmental regulator enforces hazardous discharge protocols under the Ministry of Environment and Forestry's wastewater standards. These production clusters are deepening ties with Singaporean tank farm operators to secure ISO tank container positioning for ASEAN distribution.
Malaysia
Pengerang Integrated Complex and Kertih petrochemical zones feed specialty chemicals and olefins into Singapore's Jurong Island storage network. The Department of Environment administers scheduled waste regulations that mandate double-walled containment for cross-border chemical movements. Johor's southern corridor is emerging as a rail interconnection testbed for multimodal chemical logistics between the two countries.
Vietnam
Ba Ria-Vung Tau province and Hai Phong are attracting pharmaceutical manufacturing investments that demand cold chain chemical distribution. The Ministry of Health's pharmaceutical import licensing framework is tightening documentation requirements for active pharmaceutical ingredient logistics. Cai Mep deepwater port is expanding dedicated chemical berth capacity to capture transshipment volumes that currently flow through Singapore.
Thailand
Rayong's Map Ta Phut industrial estate anchors petrochemical production with growing biologics manufacturing co-location. The Food and Drug Administration's hazardous substance control regulations are aligning with ASEAN harmonization initiatives for chemical handling certification. Eastern Economic Corridor infrastructure investments include automated chemical warehousing designed to reduce Bangkok-Singapore routing dependency.
Philippines
Batangas and Cebu chemical processing zones serve domestic manufacturing with limited export-oriented specialty chemicals capacity. The Department of Environment and Natural Resources' hazardous waste management regulations are elevating compliance costs for international logistics providers. Manila Bay port congestion is pushing chemical importers toward Singaporean consolidation for just-in-time delivery scheduling.
Singapore Chemical Logistics Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. Singapore's chemical logistics market structures around three distinct player archetypes: global integrated forwarders with temperature-controlled network coverage, port-centric storage specialists with Jurong Island terminal access, and regional niche operators with hazardous materials certification depth. Consolidation pressure is accelerating as land scarcity forces automation investments that favor capital-rich incumbents. Dominant competitive moves include facility densification through vertical stacking systems and multi-year service agreement procurement with pharmaceutical manufacturers.
Within the global integrated tier, DHL and Kuehne+Nagel represent archetypal network operators anchoring regional headquarters in Singapore to coordinate maritime-air multimodal coverage. PSA Chemical Logistics occupies a distinct position as the port-centric storage specialist dominating Jurong Island's tank farm and transshipment infrastructure. Among regional hazardous materials specialists, Bertschi Singapore Pte Ltd and ALPS Global Logistics exemplify certification-heavy operators serving pharmaceutical and specialty chemicals segments with UN-certified handling protocols.
| Leading Market Players |
|---|
| ALPS Global Logistics |
| Bertschi Singapore Pte Ltd |
| DHL |
| Kuehne+Nagel |
| PSA Chemical Logistics |
| Koyo Kaiun Co., Ltd. |
| Iino Singapore Pte Ltd |
| Fairfield Chemical Carriers |
| MCL Logistics Asia Pte Ltd |
| Others |
Pricing and Supply Chain Analysis
Jurong Island's tank farm concentration compresses available storage capacity and transfers pricing power toward certified operators with hazardous liquid containment infrastructure. Singapore's land scarcity elevates per-cubic-meter storage economics above regional competitors in Malaysia and Indonesia, forcing buyers to absorb premium rates for audit-ready facilities.
Pricing Analysis
Singapore commands a 15-25% price premium over Peninsular Malaysia for equivalent hazardous chemical storage, reflecting land scarcity and regulatory compliance costs. Three-tier pricing structure across certified premium, standard compliance, and commodity bulk levels separates pharmaceutical-grade handlers from petrochemical traders. Cost compression in the bulk chemicals tier is intensifying because Indonesian producers are expanding captive port capacity. Pharmaceutical manufacturers exhibit the lowest price sensitivity, absorbing premium costs for temperature-controlled networks with batch-level traceability.
Supply Chain Analysis
Extended payment terms from 30 to 60 days are becoming standard among Jurong Island tank farm operators seeking to lock in pharmaceutical contracts. Supply concentrates in Singapore, Malaysia, and Indonesia, with Indonesian Bontang complexes and Malaysian Pengerang feeds anchoring upstream flows. The supply chain draws from specialty chemical feedstocks, ISO tank container fleets, and automated warehouse management platforms. Single-source vulnerability around Jurong Island's certified tankage creates bottleneck exposure during demand surges. Distribution runs through maritime-dominated corridors with PSA terminal infrastructure anchoring transshipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Singapore's chemical logistics sector is entering a cyclical upswing driven by pharmaceutical manufacturing expansion across ASEAN. Biologics producers are consolidating procurement through multi-year agreements, creating contracted revenue visibility for handlers with temperature-controlled infrastructure.
For Market Incumbents: Entrench market position by accelerating automation investments in vertical stacking systems that maximize cubic efficiency on constrained Jurong Island footprints. Secure backward integration into Johor-Singapore rail linkages before infrastructure completion locks in first-mover terminal access. Defend against emerging Malaysian port competition by embedding digital twin platforms that pharmaceutical clients require for batch-level environmental traceability.
For New Entrants and Emerging Players: Pursue specialty chemicals handling certifications that established operators cannot scale quickly due to Singapore's extended hazmat training timelines. Target the agrochemicals segment where National Environment Agency discharge controls have elevated compliance costs beyond the appetite of commodity traders. Lead with integrated cold chain offerings for Vietnam-bound pharmaceutical distribution as Cai Mep port capacity remains underdeveloped for chemical berths.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming logistics subsidiaries that lack pharmaceutical-grade certification depth. The five-to-ten year viability thesis rests on Singapore's irreplaceable position as ASEAN's regulatory-compliant consolidation hub despite land constraints. Monitor Johor-Singapore rail project milestones as the inflection signal for multimodal operator valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tankage Infrastructure | Captive storage assets on Jurong Island lock in pharmaceutical contract renewals against Malaysian port competition. |
| Digital Twin Platform Deployment | Virtualized warehouse operations enable remote compliance auditing that Singapore's Workplace Safety and Health Council mandates. |
| Johor-Singapore Rail Interconnection | First-mover multimodal positioning captures cross-border chemical flows before Pengerang-Kertih corridor matures. |
| Green Certification Program Launch | Low-carbon supply chain tiers align with ASEAN green taxonomy developments and pharmaceutical ESG procurement criteria. |
| Long-term Pharmaceutical Service Agreement | Multi-year contracts with biologics manufacturers absorb automation capital costs and stabilize utilization rates. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across Singapore's chemical logistics corridor, including pharmaceutical procurement directors, Jurong Island terminal managers, hazardous materials certification trainers, and ASEAN regional logistics coordinators. Secondary validation drew from Maritime and Port Authority discharge records, National Environment Agency storage compliance filings, Workplace Safety and Health Council incident databases, and customs trade flow data. Bottom-up facility capacity assessments were triangulated against top-down ASEAN chemical production estimates.
Calibration against historical capacity utilization rates and pharmaceutical manufacturing investment announcements anchored the projection framework across the analysis window. Segmentation modeling incorporated product type tiers, packaging format specifications, delivery mode shares, and end-use industry concentration. CAGRs were derived from trend extrapolation of certified storage capacity expansion against demand growth from biologics manufacturing. Industry-specific inputs included ISO tank container fleet deployment schedules and digital twin adoption curves among pharmaceutical handlers.
Sensitivities concentrate around Malaysian and Vietnamese port capacity expansion timelines, ASEAN harmonization of carbon accounting rules, and pharmaceutical manufacturing relocation patterns. Forecasts reflect assumptions regarding sustained Workplace Safety and Health Act enforcement intensity and continued Indonesian upstream production growth. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Terminal Tractors Market
Logistics and Shipping
Central and Eastern Europe Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
North America Logistics Automation Market
Logistics and Shipping
Flat Rack Containers Market
Logistics and Shipping
Malaysia Road Freight Transport Market
Logistics and Shipping
Chile Air Freight Transport Market
Logistics and Shipping
United States Air Freight Market
Logistics and Shipping
Qatar Freight and Logistics Market
Logistics and Shipping
Japan Dangerous Goods Logistics Market
Logistics and Shipping
Asia Pacific Sea Freight Forwarding Market
Logistics and Shipping
Indonesia Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Middle East Freight Forwarding Market
Logistics and Shipping
India Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Australia Freight and Logistics Market
Logistics and Shipping
United States Cold Chain Logistics Market
Logistics and Shipping
Air Cargo Container Market