
 Powertrain Domain Control Unit Platforms Market | 2026-2036
Powertrain Domain Control Unit Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
Powertrain Domain Control Unit Platforms Market Insights
The split between premium integrated domain controllers and commodity microcontroller units is recalibrating procurement strategies across automotive supply chains. Bosch leverages in-house semiconductor capacity to anchor high-margin integrated platforms for electric vehicle programs. Continental competes through specialized FlexRay and Ethernet gateway solutions that sustain technology leadership in hybrid power management applications. Texas Instruments navigates cost-sensitive transmission management segments with scalable microcontroller portfolios that dominate price-competitive OEM bids.
Powertrain Domain Control Unit Platforms consolidate engine, motor, and transmission control functions into centralized compute modules that process real-time torque requests through ASIL-D safety-rated architectures operating at sub-10 millisecond loop times. These systems serve the primary commercial purpose of reducing wiring harness complexity while enabling over-the-air calibration updates across internal combustion, hybrid, and electric vehicle architectures. Integrated Domain Controller deployments lead in electric vehicle drive control applications where margin pools concentrate around thermal-coordinated inverter management. Distributed ECU architectures retain structural relevance in legacy internal combustion engine control programs where OEMs prioritize incremental retrofit compatibility over full platform redesigns.
The EPA tailpipe standards and NHTSA fuel economy mandates in the United States force OEMs toward domain-consolidated powertrain electronics that cut parasitic electrical losses. EMA and REACH compliance in Europe restricts hazardous substances in PCB assemblies and shapes supplier qualification thresholds for controller manufacturing. China's MIIT new energy vehicle mandates and GB standards for electromagnetic compatibility dictate architecture choices for market access. Stakeholders must monitor how software-defined vehicle roadmaps from OEMs reshape hardware procurement specifications for domain controller suppliers.
Market Dynamics
Domain consolidation is compressing distributed ECU architectures into centralized compute modules as automakers chase wiring harness reduction and over-the-air update capability across powertrain systems.
Growth Catalysts
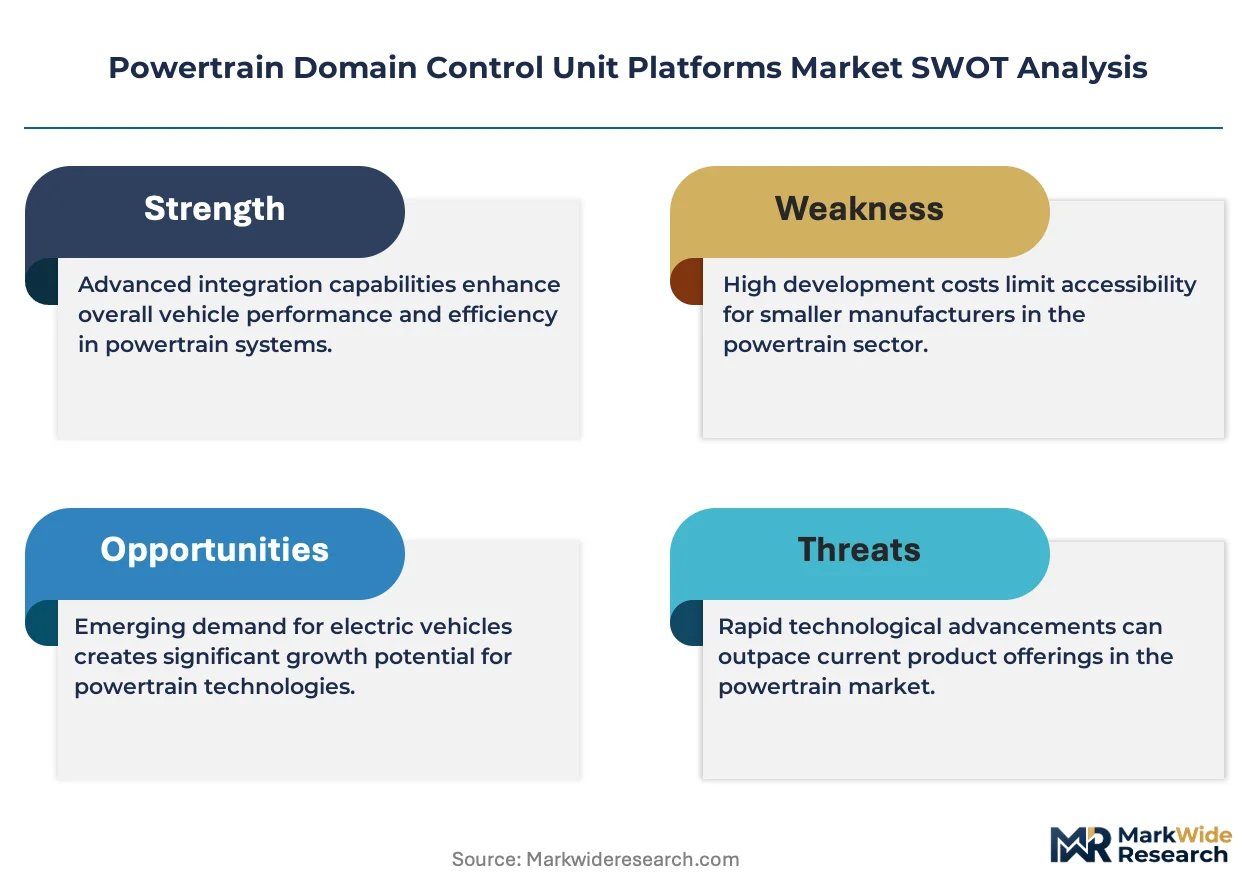
- EU Green Deal:Binding emissions targets force OEMs toward integrated domain controllers that optimize thermal management across electric drivetrains.
- China MIIT mandates:New energy vehicle production quotas accelerate procurement of ASIL-D rated powertrain controllers for domestic EV programs.
- Silicon carbide inverter integration:Wide-bandgap semiconductors demand centralized control architectures capable of sub-10 millisecond torque loop closure.
Market Restraints
- Automotive-grade silicon shortages:Foundry capacity constraints in Taiwan and South Korea create 40-52 week lead times for safety-rated microcontrollers.
- ASIL-D certification costs:Functional safety validation for powertrain domain controllers requires 18-24 month development cycles that lock out mid-tier suppliers.
- Legacy powertrain service obligations:Internal combustion engine platforms demand continued ECU production through 2035, fragmenting R&D budgets across dual architectures.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for advanced automotive electronics attract controller suppliers to establish local assembly for domestic EV manufacturers.
- Software-defined vehicle roadmaps:Hardware abstraction layers enable controller suppliers to capture recurring revenue through firmware licensing rather than one-time hardware sales.
- Vehicle-to-grid integration:Bidirectional charging protocols create demand for powertrain controllers capable of grid-synchronized power flow management.
Industry Challenges
- Functional safety engineering talent:ISO 26262 certified systems architects command premium compensation that strains mid-size supplier payroll structures.
- Legacy powertrain integration:Controller suppliers must maintain backward compatibility with 1990s-era CAN bus protocols while delivering Ethernet backbone performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Powertrain Domain Control Unit Platforms Market |
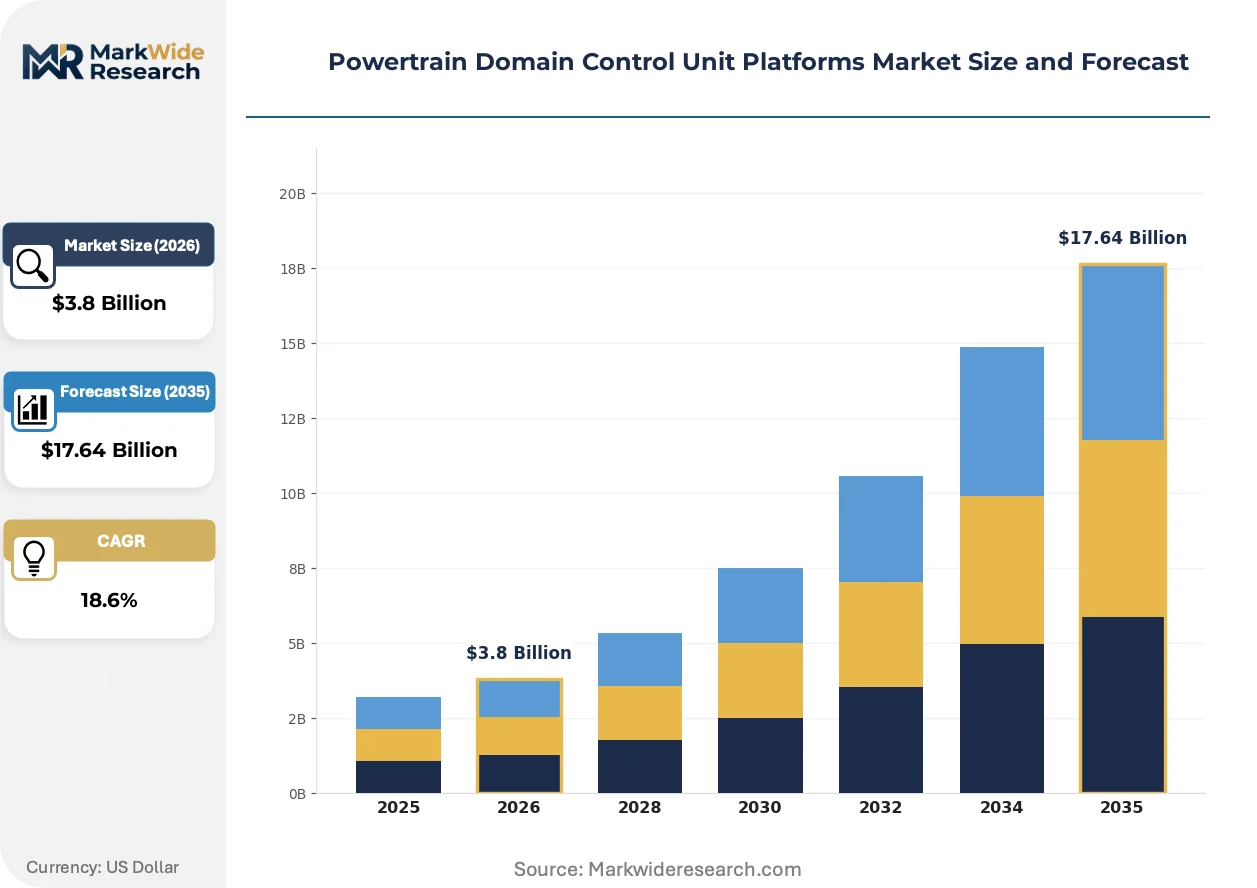
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Centralized ECU, Distributed ECU, Integrated Domain Controller, Microcontroller Unit Technology: Controller Area Network, FlexRay, Ethernet, CAN FD, LIN Application: Internal Combustion Engine Control, Hybrid Power Management, Electric Vehicle Drive Control, Transmission Management End User: OEMs, Tier-1 Suppliers, Vehicle Assembler, Aftermarket Providers |
| Companies Covered | Bosch, Continental, Denso, ZF Friedrichshafen, NXP Semiconductors, Renesas Electronics, Infineon Technologies, STMicroelectronics, Texas Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Powertrain Domain Control Unit Platforms Market Trends and Innovations
Powertrain electronics are pivoting from hardware-centric value capture toward software-defined architectures that enable continuous calibration optimization throughout vehicle life cycles.
Zonal E/E architectures are electrifying traditional powertrain control hierarchies by consolidating motor, inverter, and battery management into single domain controllers. Tier 1 suppliers in Germany and China are adopting these platforms for 800-volt electric vehicle programs. The shift is electrifying margin pools away from discrete ECU suppliers toward integrated system architects capable of thermal-electrical-mechanical co-design.
EPA tailpipe standards and NHTSA fuel economy mandates in the United States are forcing powertrain controller specifications toward lower parasitic loss designs. OEM procurement teams now require sub-5 watt standby consumption for domain controllers in hybrid applications. The regulatory pressure is compressing supplier development timelines and favoring semiconductor partners with in-house automotive packaging capability.
Fleet operators and mobility providers are consolidating controller procurement through long-term supply agreements that bundle hardware, software, and predictive maintenance services. Traditional spot-market component purchasing is losing share to outcome-based contracts in North American and European commercial vehicle segments. This restructuring concentrates buying power among large fleet aggregators and squeezes pricing flexibility for smaller controller suppliers serving fragmented aftermarket channels.
Powertrain Domain Control Unit Platforms Market Segmentation
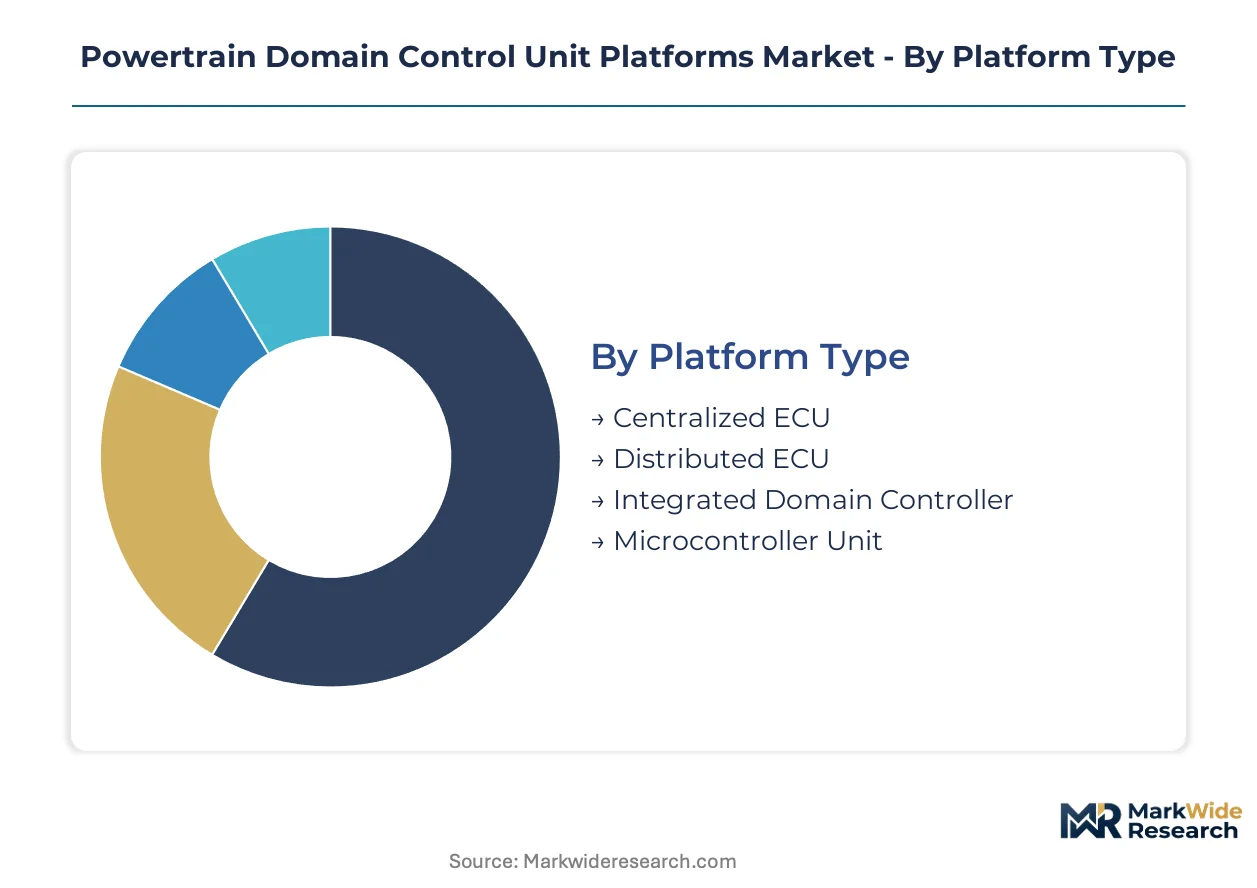
Powertrain domain controller procurement splits sharply between legacy internal combustion retrofit programs and ground-up electric vehicle architectures. Tier-1 suppliers and OEMs negotiate entirely different specification bundles depending on which platform generation they are sourcing. The segmentation below tracks how these procurement fault lines concentrate margin pools and technical risk across supply tiers.
Platform Type:
Replacement cycles for powertrain electronics accelerate as OEMs migrate from distributed ECU architectures toward consolidated domain controllers that reduce wiring harness complexity and enable over-the-air calibration.
- Centralized ECU:Single compute modules consolidating multiple powertrain functions through high-performance multicore processors running AUTOSAR Adaptive stacks. Demand concentrates in German premium OEM programs where ASIL-D safety ratings and sub-10 millisecond loop times justify premium silicon sourcing despite foundry lead times stretching 40-52 weeks.
- Integrated Domain Controller:Unified thermal-electrical-mechanical control platforms coordinating motor, inverter, and battery management through zonal E/E architectures. Chinese EV manufacturers in Shenzhen and Shanghai drive procurement volumes as MIIT new energy vehicle mandates tighten and domestic OEMs pursue 800-volt platform differentiation.
- Distributed ECU:Discrete engine, transmission, and motor controllers linked through legacy CAN bus networks. Remains entrenched in North American light truck and commercial vehicle programs where EPA tailpipe compliance timelines allow incremental hardware refreshes rather than full platform redesigns.
- Microcontroller Unit:Cost-optimized single-chip solutions for transmission solenoid control and basic engine management. Dominates Indian and Southeast Asian OEM bids where PLI scheme incentives attract local assembly but price sensitivity constrains semiconductor feature sets.
Volume placements concentrate in Distributed ECU architectures serving legacy internal combustion programs; the faster expansion belongs to Integrated Domain Controllers capturing electric vehicle drive control margin pools.
Technology:
Communication protocol selection locks suppliers into multi-year development cycles where backward compatibility requirements clash with bandwidth demands for real-time torque coordination.
- Ethernet:Gigabit-capable backbone networks enabling deterministic data transfer for camera-fed powertrain optimization and predictive thermal management. German and Chinese OEMs specify automotive-grade Ethernet for premium EV programs where zonal architectures demand 100-microsecond latency guarantees.
- CAN FD:Enhanced Controller Area Network protocol doubling bit rates while preserving physical layer compatibility with legacy installations. Hybrid power management applications in European and Japanese OEM programs favor CAN FD for its bridge technology status during multi-year platform transitions.
- FlexRay:Time-triggered deterministic bus architecture sustaining technology leadership in transmission control and brake-by-wire coordination. Continental and Bosch leverage FlexRay expertise to defend hybrid system market positions where timing precision exceeds Ethernet cost advantages.
- Controller Area Network:Established 500 kbps protocol dominating internal combustion engine control and basic transmission management. Retains structural relevance through 2035 service obligations for legacy powertrain platforms across North American and European aftermarket channels.
- LIN:Low-cost single-master-multiple-slave bus for sensor clusters and actuator control in cost-sensitive transmission applications. Prevails in Indian and Brazilian OEM programs where microcontroller unit economics dominate procurement specifications.
Procurement volumes cluster around CAN and CAN FD for their retrofit compatibility; Ethernet is climbing the fastest as 800-volt EV architectures demand backbone bandwidth for thermal-coordinated inverter management.
Application:
Application-specific controller demand diverges between regions tightening emissions standards and those preserving internal combustion manufacturing capacity for export markets.
- Electric Vehicle Drive Control:Integrated motor-inverter-battery management systems operating at 400-800 volt architectures with silicon carbide power stages. Chinese OEMs in BYD and NIO supply chains drive procurement concentration as MIIT production quotas and dual carbon goals accelerate domestic EV program launches.
- Hybrid Power Management:Dual-mode controllers coordinating internal combustion and electric torque blending through predictive energy management algorithms. European OEMs prioritize hybrid applications to meet EU Green Deal interim targets while preserving existing engine manufacturing assets.
- Internal Combustion Engine Control:Traditional ECU architectures managing fuel injection, ignition timing, and emissions aftertreatment. Retains procurement volume in North American light truck segments where NHTSA fuel economy mandates allow compliance through mild-hybridization rather than full electrification.
- Transmission Management:Clutch control, gear selection, and torque converter lockup modules for multi-speed automatic and dual-clutch transmissions. German transmission specialists specify ASIL-D rated controllers for 8+ speed architectures serving premium internal combustion and hybrid applications.
Contract awards concentrate in Internal Combustion Engine Control for legacy program continuity; Electric Vehicle Drive Control shows the steepest expansion trajectory as OEMs reallocate R&D budgets toward dedicated BEV platforms.
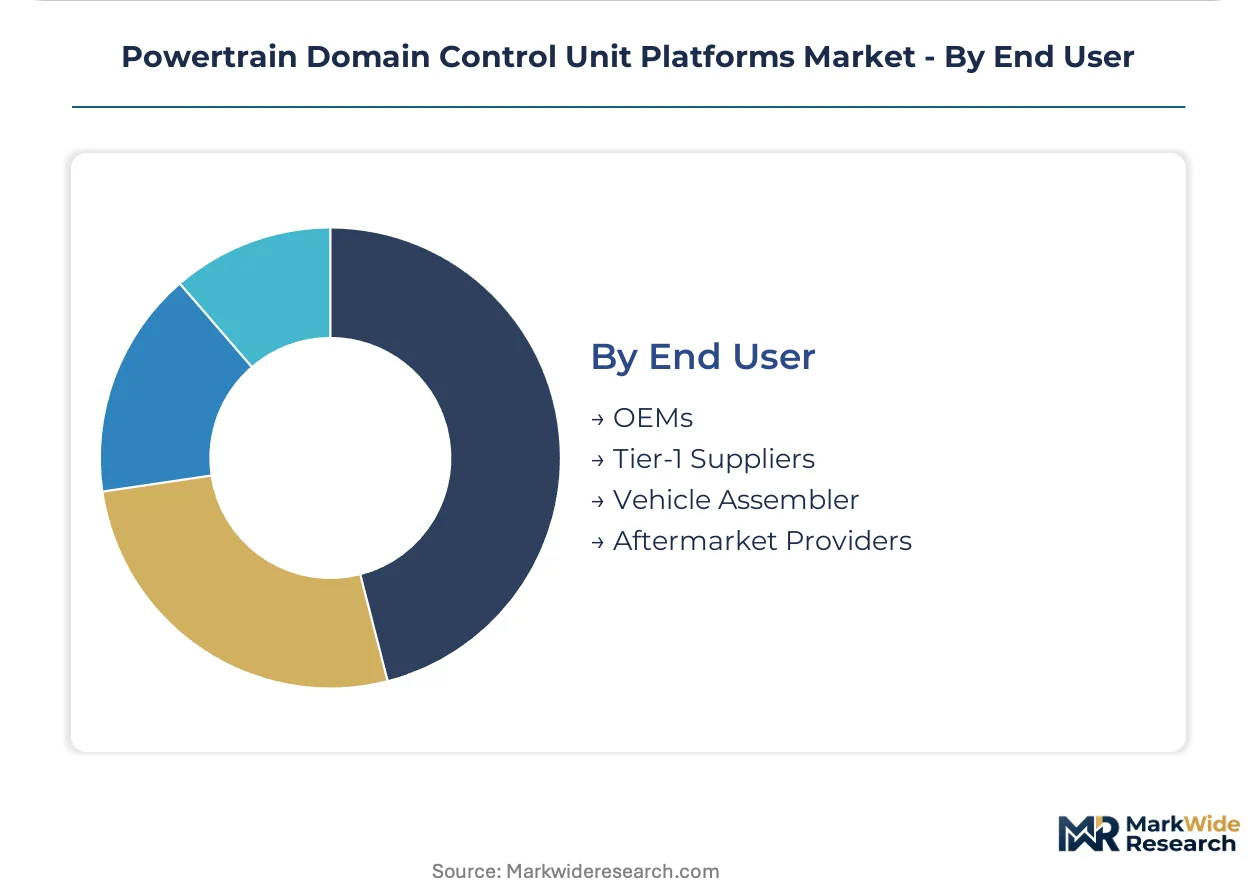
End User:
End-user procurement authority is consolidating as OEMs internalize domain controller specification power and squeeze Tier-1 margins through direct semiconductor negotiations.
- OEMs:Vehicle manufacturers specifying proprietary controller architectures and directly contracting semiconductor foundries for safety-rated silicon. Volkswagen, BMW, and BYD exercise growing procurement leverage to bypass traditional Tier-1 markups on integrated domain controllers.
- Tier-1 Suppliers:Bosch, Continental, and Denso supplying complete controller hardware-software stacks to OEMs lacking in-house powertrain electronics capability. Defend market position through ASIL-D certification assets and long-term service agreements spanning 15-year vehicle lifecycles.
- Vehicle Assemblers:Contract manufacturers and joint venture operations executing controller integration for regional market access. Indian and Southeast Asian assembly operations rely on Tier-1 and OEM direct supply for powertrain electronics meeting local content requirements.
- Aftermarket Providers:Remanufacturing and replacement controller suppliers serving legacy internal combustion service obligations. Fragmented channel structure faces margin compression as OEMs restrict calibration access and over-the-air update capability.
Revenue concentration sits with Tier-1 Suppliers for their certification and integration assets; OEM direct procurement is gaining share fastest as software-defined vehicle roadmaps demand hardware-software co-development control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors powertrain controller procurement through its concentration of German premium OEM headquarters and Tier-1 engineering centers. Regional demand splits between legacy internal combustion service obligations and 800-volt electric vehicle platform launches.
Germany
Baden-Württemberg and Bavaria host Bosch and Continental engineering centers that specify ASIL-D rated domain controllers for European OEM programs. KBA type-approval processes enforce functional safety validation standards that extend development cycles. Munich-based BMW and Stuttgart-based Porsche procurement teams directly negotiate silicon foundry contracts, bypassing traditional Tier-1 markups.
China
Shenzhen and Shanghai EV manufacturers drive integrated domain controller volumes as MIIT production quotas tighten. Dual carbon goals and GB standards for electromagnetic compatibility dictate architecture choices for domestic market access. BYD and NIO supply chains in the Yangtze River Delta concentrate procurement around 800-volt silicon carbide inverter coordination.
United States
Michigan-based OEM engineering centers specify controllers for light truck and commercial vehicle programs where NHTSA fuel economy mandates allow mild-hybrid compliance paths. EPA tailpipe standards force lower parasitic loss designs with sub-5 watt standby consumption requirements. Detroit-area Tier-1 suppliers defend positions through long-term service agreements spanning 15-year vehicle lifecycles.
India
Tamil Nadu and Maharashtra assembly operations rely on PLI scheme incentives to localize controller production for domestic EV manufacturers. BIS certification requirements and DGFT import substitution policies shape supplier qualification thresholds. Bangalore-based engineering centers develop cost-optimized microcontroller solutions for transmission management in price-sensitive OEM bids.
Japan
Nagoya-centered Toyota and Denso operations sustain hybrid power management controller demand through METI-supported electrification roadmaps. JIS standards and PMDA-aligned quality systems enforce rigorous supplier qualification. Yokohama-based engineering teams coordinate FlexRay-based transmission control architectures serving premium internal combustion and hybrid applications.
Powertrain Domain Control Unit Platforms Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a tiered structure where ASIL-D certification assets concentrate procurement leverage among established players. The vendor base splits between integrated system architects capturing electric vehicle margin pools and discrete ECU suppliers defending legacy internal combustion positions. Two strategic archetypes dominate: semiconductor foundries with in-house automotive packaging capability, and Tier-1 integrators leveraging long-term OEM relationships. Competitive moves center on direct silicon sourcing negotiations and firmware licensing transitions toward recurring revenue models.
Among European-based semiconductor suppliers, Infineon Technologies and NXP Semiconductors exemplify the foundry-integrated archetype with automotive-grade silicon capacity. Bosch represents the Tier-1 systems integrator position, while Texas Instruments occupies a position bridging cost-optimized microcontroller portfolios and scalable domain controller platforms. These three anchors illustrate how procurement authority is consolidating around players capable of hardware-software co-development and functional safety certification.
| Leading Market Players |
|---|
| Bosch |
| Continental |
| Denso |
| ZF Friedrichshafen |
| NXP Semiconductors |
| Renesas Electronics |
| Infineon Technologies |
| STMicroelectronics |
| Texas Instruments |
| Others |
Pricing and Supply Chain Analysis
German premium OEM procurement teams concentrate buying power through direct silicon foundry negotiations, anchoring value-based pricing models that tie controller costs to vehicle program thermal performance outcomes rather than discrete hardware unit pricing.
Pricing Analysis
Value-based pricing anchored to thermal-coordinated inverter performance outcomes dominates German and Chinese OEM procurement, separating premium ASIL-D certified domain controllers from cost-optimized microcontroller units through certification grade and software abstraction layer bundling. Price differentiation stems from functional safety validation depth and foundry partnership tier, with Tier-1 integrators facing margin compression as OEMs bypass traditional hardware markups. Cost compression in microcontroller segments is intensifying because Indian and Southeast Asian OEM bids prioritize local PLI scheme compliance over feature expansion. Fleet operators and mobility providers exhibit lowest price sensitivity through outcome-based service contracts, while aftermarket remanufacturers face acute pricing pressure from restricted calibration access.
Supply Chain Analysis
Automotive-grade silicon supply rests on foundry capacity in Taiwan, South Korea, and the United States, with wafer processing and advanced packaging creating dependencies on photoresist chemicals, copper interconnect substrates, and rare earth magnet materials for motor-inverter integration. Single-source vulnerability concentrates in 40-52 week lead time safety-rated microcontroller supply from concentrated foundry locations, compounded by EPA and REACH substance restrictions qualifying alternative suppliers. Distribution runs through Tier-1 integrator assembly hubs in Germany, China, and Mexico serving regional OEM manufacturing footprints with just-in-time sequencing for powertrain platform launches.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Powertrain domain controllers are transitioning from distributed ECU architectures to zonal integrated platforms, with silicon carbide inverter coordination replacing legacy CAN-based motor control as the dominant technology anchor.
For Market Incumbents: Hedge against OEM direct procurement encroachment by deepening ASIL-D certification assets and securing long-term silicon supply agreements with Taiwan and South Korea foundries. Defend hybrid power management positions through FlexRay protocol continuity investments while building firmware licensing revenue streams that reduce hardware margin dependence. For New Entrants and Emerging Players: Direct-to-OEM software licensing platforms offer the most penetrable route into German and Chinese EV programs seeking hardware abstraction layer independence from incumbent Tier-1 markups. Target Indian PLI scheme beneficiaries with cost-optimized microcontroller solutions for transmission management, leveraging Bangalore engineering partnerships to bypass 18-24 month ASIL-D validation barriers. For Investors and Strategic Acquirers: The window for entry favors semiconductor foundries with in-house automotive packaging capability and ISO 26262 certified engineering teams capable of hardware-software co-development. Watch MIIT production quota enforcement and EU Green Deal interim target tightening as inflection indicators for integrated domain controller demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Inverter Integration | Centralized control architectures from Infineon and STMicroelectronics enable sub-10 millisecond torque loop closure for 800-volt platforms. |
| ASIL-D Certification Investment | Bosch and Continental leverage functional safety validation assets to lock out mid-tier competitors from premium OEM programs. |
| Software-Defined Vehicle Partnership | NXP Semiconductors captures recurring firmware licensing revenue through hardware abstraction layer standardization. |
| India PLI Scheme Localization | Tamil Nadu assembly operations attract controller suppliers with production-linked incentives for domestic EV manufacturers. |
| Vehicle-to-Grid Protocol Development | Bidirectional charging integration creates demand for grid-synchronized power flow management in Chinese and European markets. |
Research Methodology
Document review covered SEC 10-K filings from semiconductor suppliers, EPA tailpipe standard dockets, and MIIT new energy vehicle production databases, complemented by interviews with Tier-1 supplier procurement directors, OEM platform engineers, and aftermarket distribution channel managers. Secondary validation drew from vehicle production registries, customs trade data for automotive electronics, and IHS Markit powertrain architecture forecasts. Bottom-up controller shipment estimates triangulated against top-down OEM program spend allocations across the analysis window.
Cross-referencing historical production ramp patterns with expert panel input on platform transition timelines shaped the analytical framework, modeling segmentation across propulsion architecture, vehicle class, content per vehicle, OEM tier, and regional production cluster. CAGRs derived from weighted average of technology adoption curves and regulatory compliance deadline clustering, incorporating silicon carbide penetration rates and zonal E/E architecture migration timelines as automotive-specific forecast inputs.
The model holds under steady regulatory enforcement of EU Green Deal and MIIT production quotas; deviation in foundry capacity expansion or automotive-grade silicon allocation would shift volume and value trajectories. A small set of triggers—Taiwan semiconductor export restrictions, ASIL-D certification backlog accumulation, and OEM software-defined vehicle roadmap acceleration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Water Pump Market
Powertrain
Automotive Power Modules Market
Powertrain
Racing Clutches Market
Powertrain
Plug-In Hybrid Electric Vehicle Powertrain Market
Powertrain
Clutch Market
Powertrain
Automotive Coil Spring Market
Powertrain
Iridium Spark Plug Market
Powertrain
Global Automotive Clutch Pedals Market
Powertrain
Automotive Counter Shaft Market
Powertrain
Automotive Vacuum Pump Market
Powertrain
Power Seat Adjustment Motor Market
Powertrain
Automotive TCU Market
Powertrain
Automotive Park Brake Lever (Handbrake) Market
Powertrain
Electrically Powered Hydraulic Steering Market
Powertrain
Mechanical Reciprocating Engine Market
Powertrain
Japan Automotive Engine Oils Market