
 Automotive Plastic Components Market | 2026-2036
Automotive Plastic Components Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Plastic Components Market Analytics
Market Dynamics
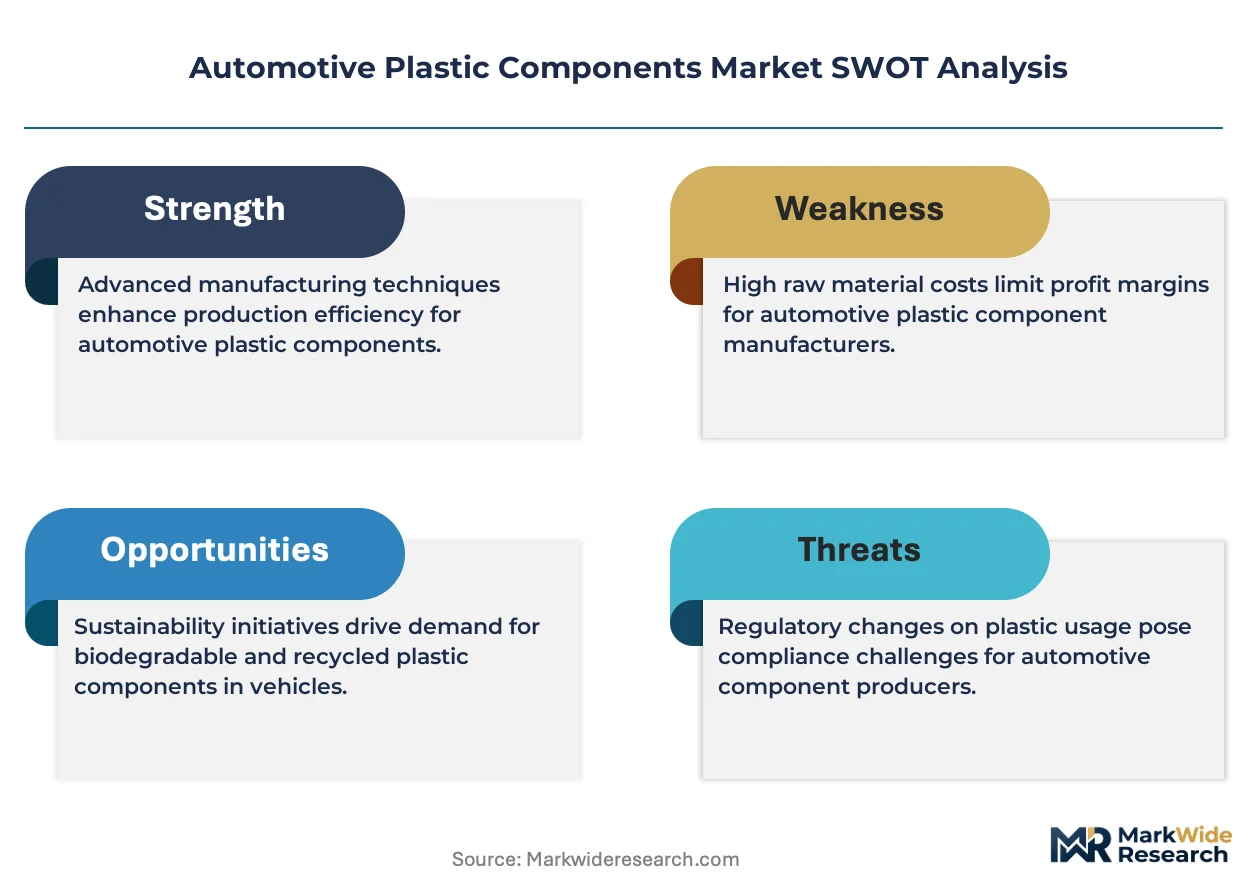
Tier-1 supplier networks is rewriting procurement geography as OEMs consolidate vendor bases across multiple continents. BASF SE leverages its Ludwigshafen integrated complexes to sustain captive polymer supply for bumper and dashboard programs. Covestro AG anchors European polycarbonate demand through specialized glazing and interior applications. Magna International, Inc. competes on manufacturing scale by operating injection molding footprints adjacent to major vehicle assembly plants in North America and Asia.
Product and Technology Landscape
Automotive plastic components encompass engineered polymer parts manufactured through injection molding, blow molding, and thermoforming processes to achieve weight reduction targets of 30-50% versus comparable metal assemblies. These components serve critical functions spanning structural reinforcement, occupant protection, aerodynamic optimization, and interior cabin integration across passenger and commercial vehicle platforms. Polypropylene dominates material consumption by volume owing to its cost-position and recyclability profile in bumper and door panel applications. Polycarbonate captures premium margin pools in headlamp lenses and panoramic roof modules where optical clarity and impact resistance command specification premiums. Injection molding remains the foundational manufacturing stage, though blow molding expands fastest in fluid handling and air duct applications.
Regulatory Environment and Outlook
EPA fuel economy standards, EU REACH chemical restrictions, and China's GB standards for automotive materials collectively mandate recycled content thresholds and restrict specific plasticizer chemistries across supply chains. ECHA substance evaluations and California Air Resources Board rules are forcing reformulation of interior trim compounds to reduce VOC emissions and enable closed-loop recovery. Stakeholders must monitor evolving extended producer responsibility frameworks and polymer-specific recycling infrastructure investments to secure compliant material sourcing.
Market Dynamics
Electric vehicle platform architectures are compressing component counts while demanding higher thermal management performance from polymer assemblies, forcing material suppliers to recalibrate formulation roadmaps around battery enclosure specifications.
Growth Catalysts
- EU REACH chemical compliance:Recycled content mandates in automotive plastics are accelerating closed-loop material flows across European supplier networks.
- Injection molding automation:Robotic cell integration is collapsing cycle times for bumper and dashboard production runs.
- China's Yangtze River Delta:Dense clustering of EV final assembly plants is pulling regional polymer compounders into just-in-sequence supply arrangements.
Market Restraints
- Propylene feedstock volatility:Crude oil and naphtha price swings transmit directly into polypropylene pellet costs, squeezing converter margins.
- German chemical corridor concentration:BASF SE and Covestro AG anchor European polymer supply, creating geographic single-source exposure for Tier-1 molders.
- Metal substitution limits:Structural load-bearing applications in chassis and suspension retain steel and aluminum specifications due to fatigue resistance requirements.
Strategic Opportunities
- India's PLI scheme for auto components:Production-linked incentives are attracting foreign polymer processors to establish compounding operations near Chennai and Pune assembly hubs.
- Biopolymer glazing modules:Polycarbonate replacement with bio-based alternatives in panoramic roof applications opens premium positioning for sustainability-certified OEM programs.
- California SB 54 implementation:Extended producer responsibility frameworks create first-mover advantage for suppliers with verified closed-loop recycling infrastructure.
Industry Challenges
- Multi-material bonding expertise:Adhesive and welding process engineers command premium wages as OEMs specify polymer-to-metal hybrid assemblies.
- GB standard certification timelines:China's automotive material approval protocols extend product qualification cycles by 8-14 months versus comparable EU processes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Plastic Components Market |
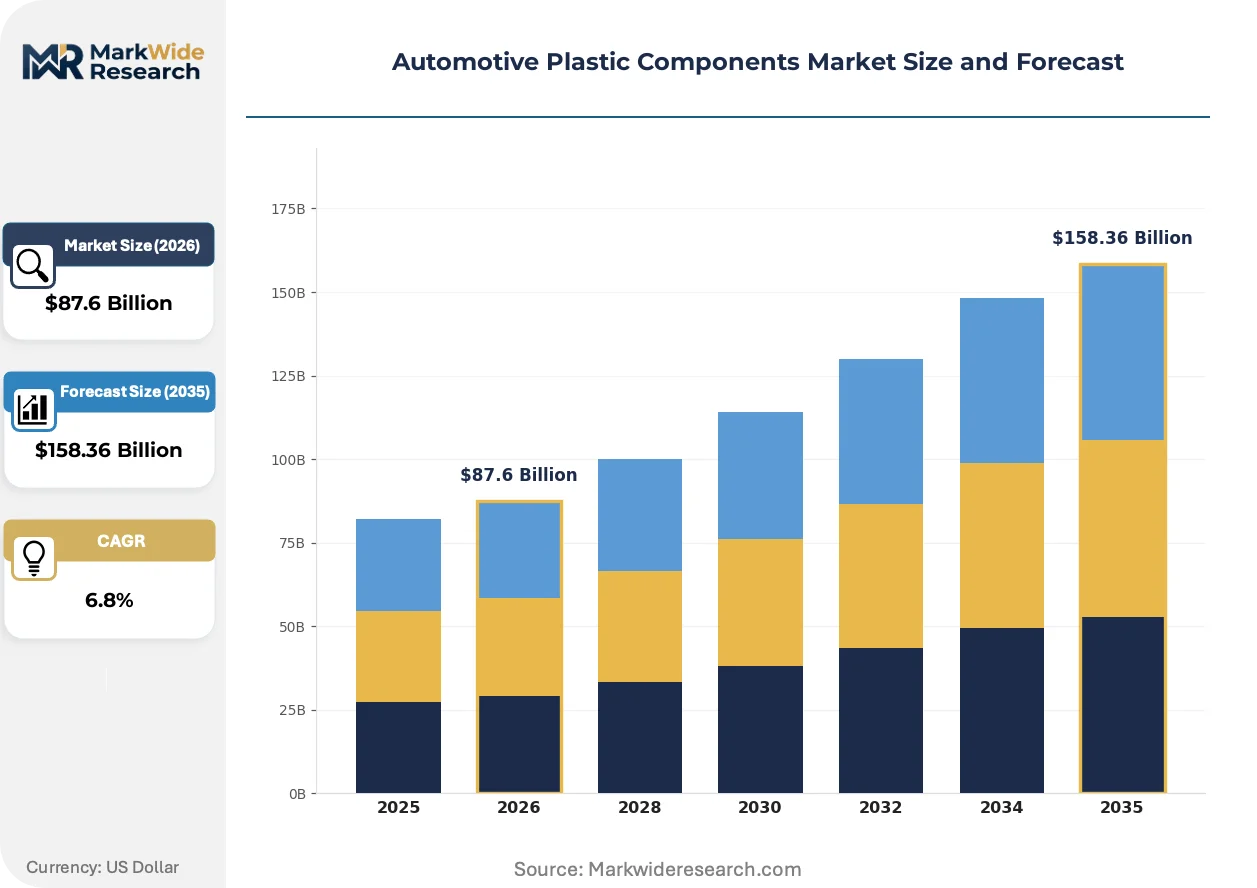
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $158.36 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bumpers, Dashboards, Door Panels, Instrument Panels Material: Polypropylene, Polycarbonate, ABS, Nylon End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Manufacturing Stage: Injection Molding, Blow Molding, Extrusion, Thermoforming |
| Companies Covered | BASF SE, DuPont, Covestro AG, SABIC, LyondellBasell Industries Holdings BV, LG Chem, TOYODA GOSEI Co., Ltd, Magna International, Inc., Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Plastic Components Market Evolving Landscape
Physical foaming technologies and in-mold decoration processes are redrawing the boundary between structural performance and aesthetic integration in automotive interiors.
MuCell microcellular foam injection is collapsing the weight penalty of solid polymer sections while maintaining Class A surface finish requirements. European luxury OEMs are adopting the process for door panels and instrument carriers at accelerated qualification schedules. The technology is collapsing the traditional trade-off between structural rigidity and mass reduction targets.
EPA fuel economy standards are tightening fleet-average requirements, pushing OEMs to specify lighter polymer alternatives in non-structural applications. The regulatory pressure is compressing metal content in closure panels and seat structures. North American truck and SUV platforms are most affected, with engineering teams accelerating thermoplastic composite trials.
Fleet procurement departments are consolidating vendor bases from 40-plus suppliers to 8-12 strategic partners per vehicle program. Tier-1 molders are responding by offering design-to-manufacture bundles that subsume Tier-2 polymer sourcing. The concentration is most visible in Germany's automotive corridor, where Magna International and similar integrators are capturing expanded scope contracts.
Automotive Plastic Components Market Segmentation
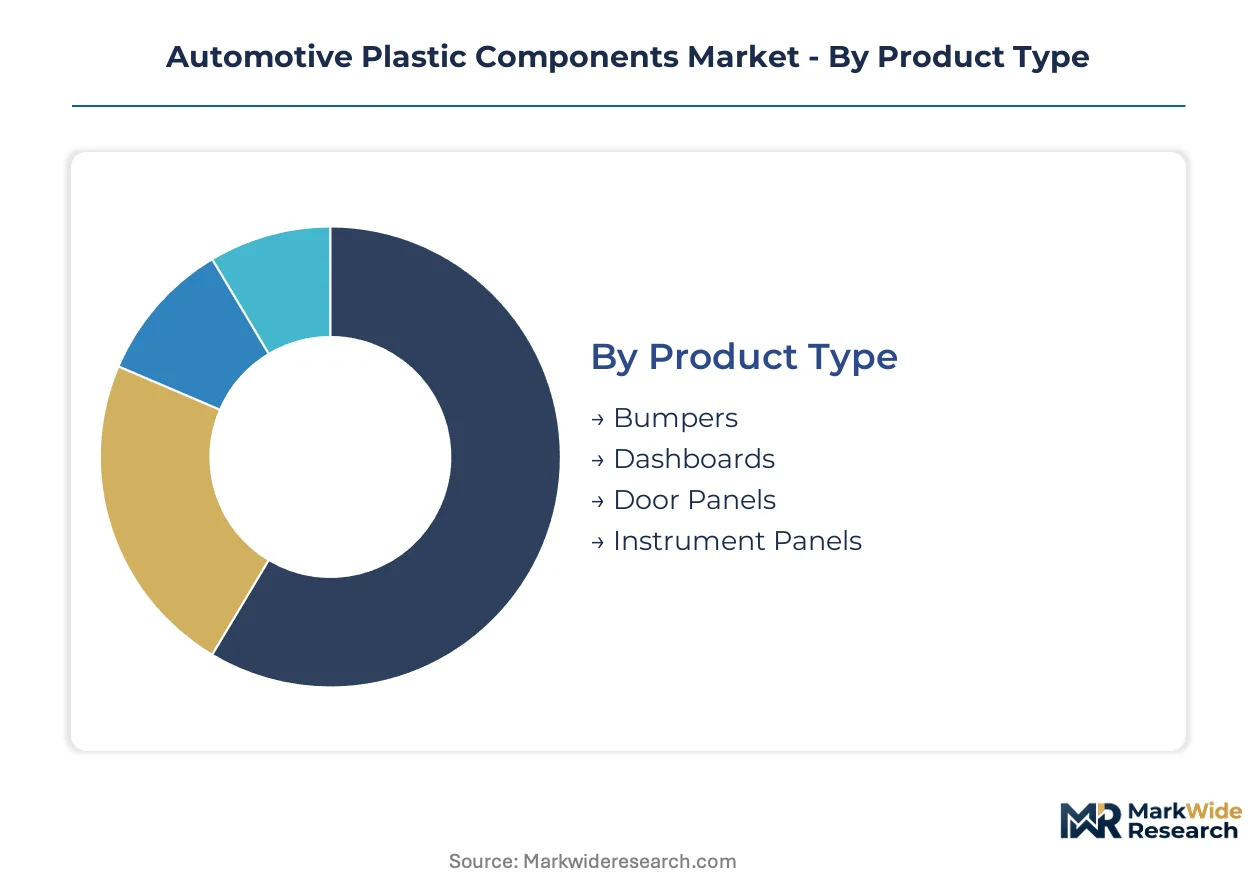
Segmentation in automotive plastics reveals divergent investment cycles across product categories. Material specifications and manufacturing processes lock in distinct margin profiles and qualification timelines that reshape supplier prioritization.
Product Type:
Bumpers and dashboards turn on 4-6 year model cycles, while instrument panels refresh slower at 7-9 year intervals. Door panels occupy the middle ground with mid-cycle facelifts driving partial redesigns.
- Bumpers:Large-format polypropylene assemblies integrate pedestrian impact absorption structures and active aerodynamic elements. German OEMs specify these in Ludwigshafen-supplied compounds for integrated sensor mounting.
- Dashboards:Complex multi-component modules combining structural carriers, soft-touch skins, and decorative foils demand longest mold development cycles. China's Yangtze River Delta EV plants are pulling regional tooling investment toward integrated cockpit designs.
- Door Panels:MuCell foaming is collapsing weight targets in European luxury applications while maintaining Class A surface requirements.
- Instrument Panels:Cross-car beam integration with HVAC ducting creates specification stickiness that extends platform lifecycles.
Bumpers dominate installed base by unit volume. Dashboards are where expansion concentrates as cockpit digitization drives material upgrade cycles.
Material:
Cost tiers separate commodity thermoplastics from engineered polymers with thermal management capabilities. Battery enclosure specifications are forcing reformulation roadmaps across all material classes.
- Polypropylene:Lowest density among structural thermoplastics enables 30-50% weight reduction versus metal alternatives. Recyclability profile aligns with EU REACH recycled content mandates, though propylene feedstock volatility squeezes converter margins.
- Polycarbonate:Optical clarity above 90% light transmission captures premium positioning in headlamp lenses and panoramic roof modules. Covestro AG anchors European supply through specialized glazing grades with enhanced UV stabilization.
- ABS:Balanced impact and aesthetic properties sustain interior trim specifications where metallic finishes command specification premiums.
- Nylon:High-temperature resistance above 150°C positions polyamide grades in under-hood fluid handling and powertrain proximity applications.
Polypropylene dominates installed base by volume tonnage. Polycarbonate is where expansion concentrates as glazing integration accelerates.
End User:
Procurement consolidation is collapsing vendor counts from 40-plus suppliers toward 8-12 strategic partners per vehicle program. Design-to-manufacture bundles are subsuming traditional Tier-2 polymer sourcing relationships.
- OEMs:Direct material specification authority concentrates in Volkswagen Group, Toyota, and BYD procurement organizations with captive polymer engineering capabilities.
- Tier-1 Suppliers:Magna International and similar integrators capture expanded scope contracts bundling molding, assembly, and sequencing logistics adjacent to final assembly plants.
- Aftermarket Providers:Crash repair specifications follow OEM release schedules with 18-24 month lag cycles.
- Vehicle Assemblers:Contract manufacturing arrangements in Mexico's Bajío cluster outsource component procurement to platform licensors.
Tier-1 suppliers dominate installed base by contract value. OEM direct sourcing is where expansion concentrates as platform architectures simplify.
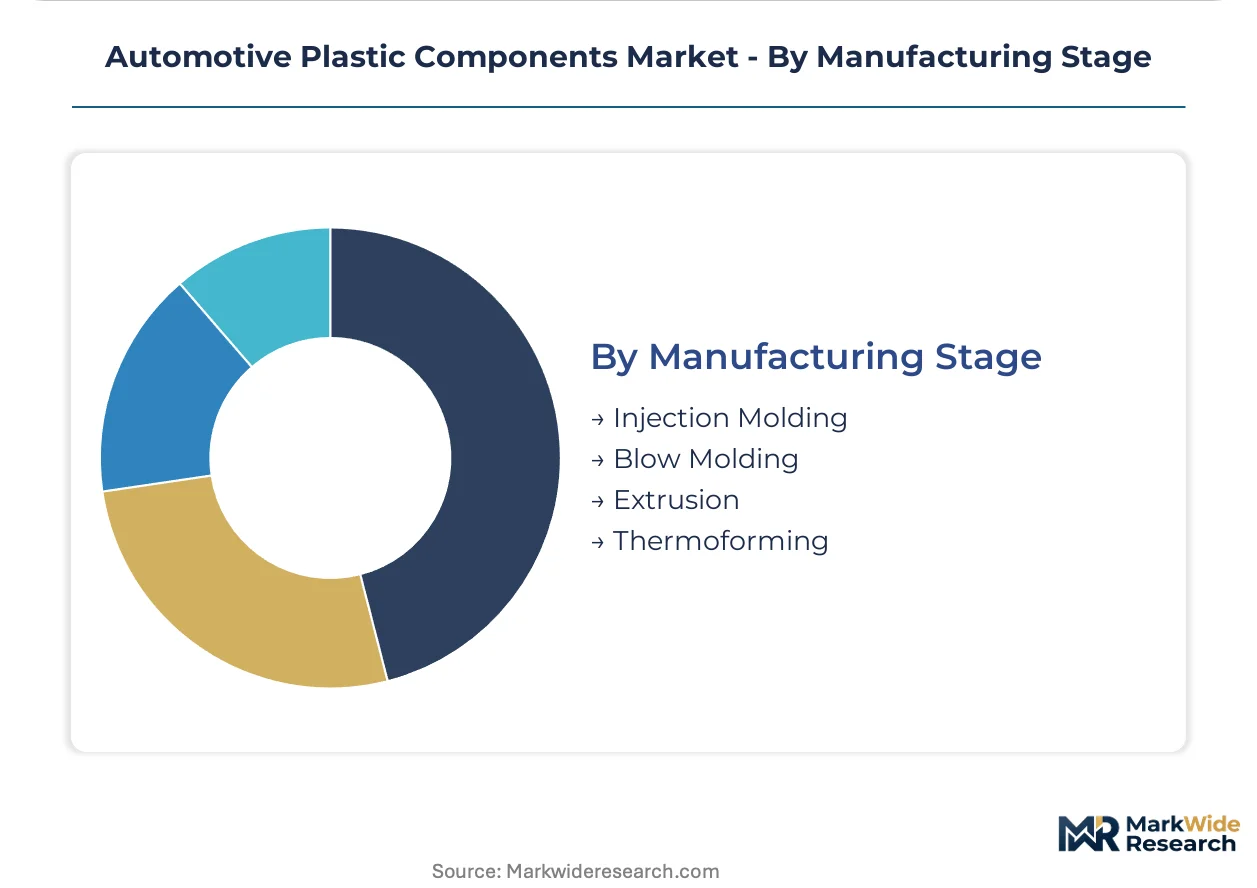
Manufacturing Stage:
Automation intensity varies dramatically across process types. Robotic cell integration is collapsing cycle times most aggressively in injection molding while blow molding expands fastest in new application areas.
- Injection Molding:Foundational process for 70% plus of automotive plastic component mass. European suppliers are adopting MuCell microcellular foam to collapse weight penalties while maintaining surface finish requirements.
- Blow Molding:Hollow part formation enables fluid handling ducts and air intake manifolds with integrated functional geometries. Expansion is climbing the fastest as thermal management complexity increases in battery electric platforms.
- Extrusion:Continuous profile production sustains sealing systems and weatherstrip specifications with limited design flexibility.
- Thermoforming:Lower tooling costs support lower-volume interior trim applications with moderate structural demands.
Injection molding dominates installed base by revenue contribution. Blow molding is where expansion concentrates as HVAC and battery thermal systems proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German compounders command pricing premiums that Mexican converters struggle to match, creating a persistent arbitrage window for battery enclosure materials shipped across the Atlantic.
United States
EPA fuel economy standards are compressing metal content in truck and SUV platforms, forcing Detroit engineering teams toward thermoplastic composite trials. California's SB 54 extended producer responsibility framework is mandating verified closed-loop recycling infrastructure for suppliers serving West Coast assembly plants. The Detroit-Windsor corridor anchors North American polymer compounding capacity, with Tier-1 molders consolidating vendor bases to 8-12 strategic partners per vehicle program.
Germany
Ludwigshafen's integrated chemical complexes sustain captive polymer supply for bumper and dashboard specifications across Volkswagen Group platforms. EU REACH chemical restrictions are forcing reformulation of interior trim compounds to reduce VOC emissions and enable closed-loop recovery. The automotive corridor spanning Baden-Württemberg through Lower Saxony concentrates BASF SE and Covestro AG polymer engineering capabilities adjacent to OEM technical centers.
China
GB standards for automotive materials are extending product qualification cycles by 8-14 months versus comparable EU processes, creating compliance friction for foreign suppliers. The Yangtze River Delta manufacturing belt is pulling regional polymer compounders into just-in-sequence supply arrangements with dense EV final assembly clusters. Shanghai and surrounding Jiangsu province municipalities are capturing expanded scope contracts as platform architectures simplify component counts.
Mexico
Propylene feedstock volatility transmits directly into polypropylene pellet costs, squeezing converter margins in the Bajío assembly cluster. Contract manufacturing arrangements in Guanajuato and Querétaro outsource component procurement to platform licensors with limited direct material specification authority. The country's national automotive regulator maintains alignment with US NHTSA standards, smoothing cross-border supply chain integration for Tier-1 molders operating dual footprints.
India
Production-linked incentive schemes for auto components are attracting foreign polymer processors to establish compounding operations near Chennai and Pune assembly hubs. The country's national automotive material approval protocols create qualification bottlenecks that extend market entry timelines for European compounders. Maharashtra and Tamil Nadu state industrial corridors are capturing expanded injection molding capacity as OEM procurement departments consolidate vendor bases.
Automotive Plastic Components Market Competitive Landscape
Integrated chemical conglomerates and specialized automotive suppliers split the market along formulation depth versus manufacturing proximity fault lines. BASF SE and Covestro AG anchor European polymer supply through Ludwigshafen integrated complexes, while Magna International competes on manufacturing scale adjacent to major vehicle assembly plants. Three strategic archetypes dominate: captive polymer producers with backward integration into feedstock, Tier-1 integrators bundling molding with sequencing logistics, and regional compounders serving just-in-time delivery windows. Competitive moves concentrate on capacity expansion in battery enclosure grades and strategic partnerships around MuCell microcellular foam licensing.
Within the integrated chemical tier, BASF SE and Covestro AG exemplify formulation-led positioning through specialized glazing and interior applications. Among diversified materials conglomerates, DuPont and SABIC occupy positions spanning engineered polymers across multiple industrial end-uses. At the manufacturing-scale end, Magna International, Inc. and Continental AG represent Tier-1 integrators capturing expanded scope contracts by operating injection molding footprints adjacent to final assembly plants in North America, Europe, and Asia.
| Leading Market Players |
|---|
| BASF SE |
| DuPont |
| Covestro AG |
| SABIC |
| LyondellBasell Industries Holdings BV |
| LG Chem |
| TOYODA GOSEI Co., Ltd |
| Magna International, Inc. |
| Continental AG |
| Others |
Value Network & Pricing Analysis
Ludwigshafen's integrated chemical complexes anchor European polymer supply, granting BASF SE and Covestro AG substantial leverage over pricing for bumper-grade polypropylene and polycarbonate glazing compounds. This concentration of formulation expertise in Germany's automotive corridor compresses margin flexibility for Tier-1 molders operating in Mexico's Bajío cluster and China's Yangtze River Delta.
Pricing Analysis
Configured-to-order pricing for battery enclosure grades commands substantial premiums over standard polypropylene bumper compounds, reflecting thermal management certification requirements and low-volume production runs. Price differentiation hinges on EU REACH compliance verification and automotive OEM brand tier, with Volkswagen Group and BYD specifications carrying distinct valuation bands. Cost compression in commodity polypropylene is intensifying because propylene feedstock volatility transmits directly from naphtha markets. Fleet procurement departments at volume OEMs exhibit highest price sensitivity, while luxury EV platforms prioritize performance over unit economics.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities have become standard negotiating instruments as Tier-1 integrators consolidate vendor bases from 40-plus suppliers toward 8-12 strategic partners per vehicle program. Geographic supply concentration centers on Germany, China, and Mexico, with Ludwigshafen, the Yangtze River Delta, and the Bajío cluster hosting the majority of compounding and molding capacity. Raw material dependencies draw from crude oil derivatives, naphtha crackers, and specialized additive packages for UV stabilization and flame retardancy. Single-source vulnerability persists around Covestro AG's polycarbonate glazing grades for panoramic roof modules. Distribution runs through just-in-sequence logistics networks adjacent to final assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized multi-material bonding expertise and MuCell microcellular foam process engineering represent acute capability gaps that constrain supplier expansion. The market rewards firms that can bridge polymer-to-metal hybrid assembly requirements while maintaining Class A surface finishes.
For Market Incumbents: Insulate formulation leadership by deepening captive supply of battery enclosure grades and securing exclusive MuCell licensing arrangements with equipment suppliers. BASF SE and Covestro AG should accelerate backward integration into recycled feedstock streams to preempt EU REACH recycled content mandates. Capacity addition in India's Tamil Nadu corridor captures production-linked incentive flows while hedging against German chemical corridor concentration risk. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-supported auto component ecosystem by partnering with Chennai and Pune assembly hubs for compounding operations. Biopolymer glazing modules for panoramic roof applications present the most penetrable white space, as sustainability-certified OEM programs seek polycarbonate alternatives. A go-to-market angle emphasizing closed-loop recycling infrastructure alignment with California SB 54 unlocks West Coast supply contracts. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because Tier-1 integrators bundling molding with sequencing logistics are capturing expanded scope contracts at the expense of fragmented regional compounders. Acquisition targets should display vertical integration into polymer formulation or proprietary thermal management material grades. The signal to watch is battery platform architecture standardization, which would collapse component counts and shift margin pools toward enclosure specialists.| Strategic Initiative | Industry Significance |
|---|---|
| MuCell Microcellular Foam Licensing | European luxury OEMs adopting MuCell for door panels collapse weight penalties while maintaining Class A surface requirements. |
| Battery Enclosure Grade Capacity Expansion | Thermal management specifications for EV platforms force reformulation roadmaps across all polymer classes. |
| Closed-Loop Recycling Infrastructure Investment | California SB 54 extended producer responsibility frameworks create first-mover advantage for verified recovery systems. |
| Backward Integration into Recycled Feedstock | EU REACH recycled content mandates accelerate captive material flows across European supplier networks. |
| Geographic Manufacturing Footprint in India | PLI scheme incentives attract foreign polymer processors to compounding operations near Chennai and Pune hubs. |
Research Methodology
A standing panel of Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and polymer compounder technical directors provided ongoing calibration across the research cycle. Primary interviews with these stakeholders combined with secondary validation from vehicle production databases, IHS Markit registration data, customs and trade flow records, and SEC filings from listed chemical conglomerates. Bottom-up modeling of injection molding, blow molding, and thermoforming capacity triangulated against top-down demand estimates from vehicle platform specifications.
Scenario-bracketing across conservative, baseline, and accelerated EV penetration assumptions anchored the analytical framework throughout the projection horizon. Segmentation dimensions modeled encompassed product type, material grade, end-user category, and manufacturing process, with additional granularity around propulsion architecture and regional production cluster. CAGRs derived from fitted growth curves incorporating battery electric platform rollout schedules, regulatory compliance timelines, and polymer substitution elasticities in metal replacement applications.
Stress conditions across propylene feedstock volatility, EU REACH enforcement intensity, and GB standard certification delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EV adoption trajectories and recycling infrastructure buildout. Macroeconomic contraction, regulatory acceleration beyond modeled timelines, or breakthrough metal substitution technologies would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Sheet Metal Components Market
Automotive Components
Asia Pacific Automotive Actuators Market
Automotive Components
Global Automotive Active Body Panel Market
Automotive Components
Automotive Sensor Cleaning System Market
Automotive Components
Automotive Resonator Market
Automotive Components
Automotive Carbon Fiber Market
Automotive Components
Global Automotive Noise Filter Market
Automotive Components
Automotive Key Market
Automotive Components
GCC Automotive Lubrication Services Market
Automotive Components
Automotive Differential Market
Automotive Components
Automotive Active Bonnet Market
Automotive Components
Automotive Tie Rod Market
Automotive Components
Asia-Pacific Automotive Plastics Market
Automotive Components
Automotive Carbon Brake Rotor Market
Automotive Components
Remote Automotive Exhaust Sensing Market
Automotive Components
Russia Automotive Pneumatic Actuators Market