
 Automotive Light Bars Market | 2026-2036
Automotive Light Bars Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Light Bars Market Analysis
The specialty automotive lighting distribution channel is fragmenting as direct-to-consumer platforms and installer networks pull volume away from traditional brick-and-mortar retailers. Baja Designs leverages its desert racing heritage to sustain premium positioning among off-road professionals. KC HiLites anchors its presence through deep relationships with Jeep and Toyota 4x4 communities. Vision X Lighting competes aggressively in the commercial mining and agricultural fleet segment with heavy-duty ingress protection ratings.
Automotive light bars are linear arrays of high-intensity emitters—typically LED dies mounted on aluminum substrates with polycarbonate or tempered glass lenses—engineered to project controlled beam patterns for forward illumination beyond standard headlamp reach. LED light bars now dominate product mix due to thermal efficiency exceeding 130 lumens per watt and operating lifespans surpassing 50,000 hours. Aftermarket installation generates the highest margin pools as consumers self-install or use independent shops, while OEM installation remains concentrated in factory off-road packages for trucks and SUVs. Halogen light bars persist in price-sensitive emerging markets but face displacement as LED module costs decline.
The EPA enforces energy efficiency benchmarks that indirectly shape electrical system load requirements, while NHTSA governs on-road photometric compliance and glare limits that determine which light bars qualify for highway-legal status. Australia's Design Rules under the Department of Infrastructure impose additional electromagnetic compatibility and vibration standards that filter non-compliant imports. Stakeholders must monitor evolving state-level tint and auxiliary lighting statutes in the United States, where patchwork enforcement creates compliance complexity for interstate sellers.
Market Dynamics
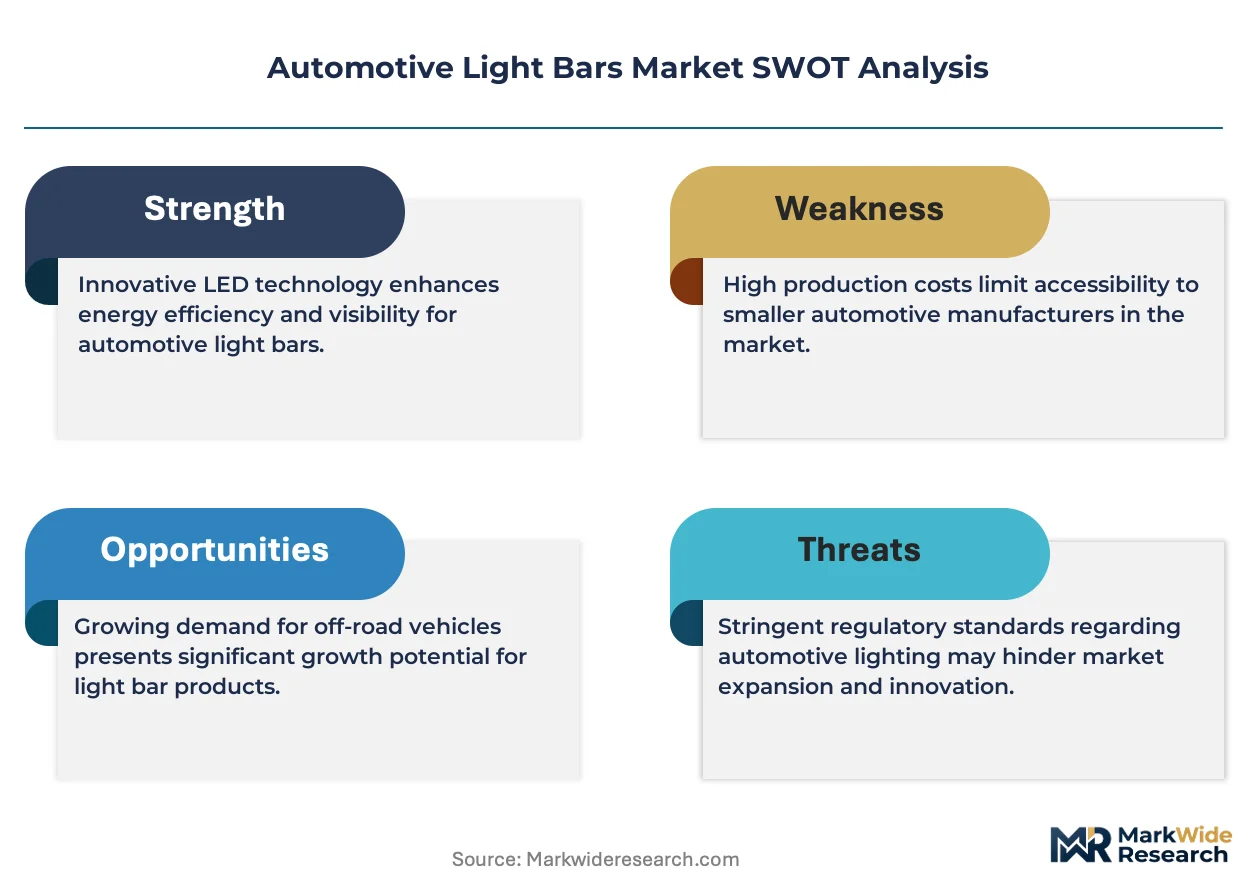
LED thermal efficiency gains are compressing halogen residual demand while NHTSA glare-limit enforcement filters highway-legal product portfolios, creating a bifurcation between compliant OEM-fitment and restricted off-road-only channels.
Growth Catalysts
- Adventure tourism expansion:Off-road vehicle enthusiasts in Australia and the southwestern United States are upgrading factory lighting with high-output auxiliary arrays for unsealed terrain navigation.
- NHTSA photometric standardization:Federal glare limits are consolidating demand around certified manufacturers capable of laboratory beam-pattern validation, raising barriers for uncertified imports.
- LED lumen-per-watt trajectories:Die-level efficiency above 130 lumens per watt is reducing electrical system load constraints, enabling broader fitment across compact vehicle segments.
Market Restraints
- Aluminum substrate cost volatility:Thermal management hardware depends on extruded aluminum pricing, which fluctuates with energy-intensive smelting economics.
- Polycarbonate lens supply concentration:Optical-grade polycarbonate production clusters in East Asian petrochemical corridors, exposing buyers to freight and tariff friction.
- On-road usage restrictions:State-level auxiliary lighting statutes in the United States create interstate commerce complexity for distributors serving multiple jurisdictions.
Strategic Opportunities
- Mining fleet electrification:Australian and Chilean open-pit operations are retrofitting autonomous haul trucks with high-durability LED bars for 24-hour visibility.
- Direct-to-consumer platform expansion:Installer networks and specialized e-commerce portals are capturing margin pools previously held by brick-and-mortar automotive retailers.
- IP67+ ingress protection standardization:Heavy-duty sealing ratings are opening specification windows in agricultural and marine applications where pressure-wash exposure is routine.
Industry Challenges
- Optical engineering talent scarcity:Compound reflector design and beam-pattern simulation require specialized photometric expertise concentrated in automotive lighting supplier bases.
- Multi-jurisdiction certification timelines:Simultaneous EPA energy-efficiency documentation, NHTSA photometric filing, and electromagnetic compatibility testing extend product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Light Bars Market |
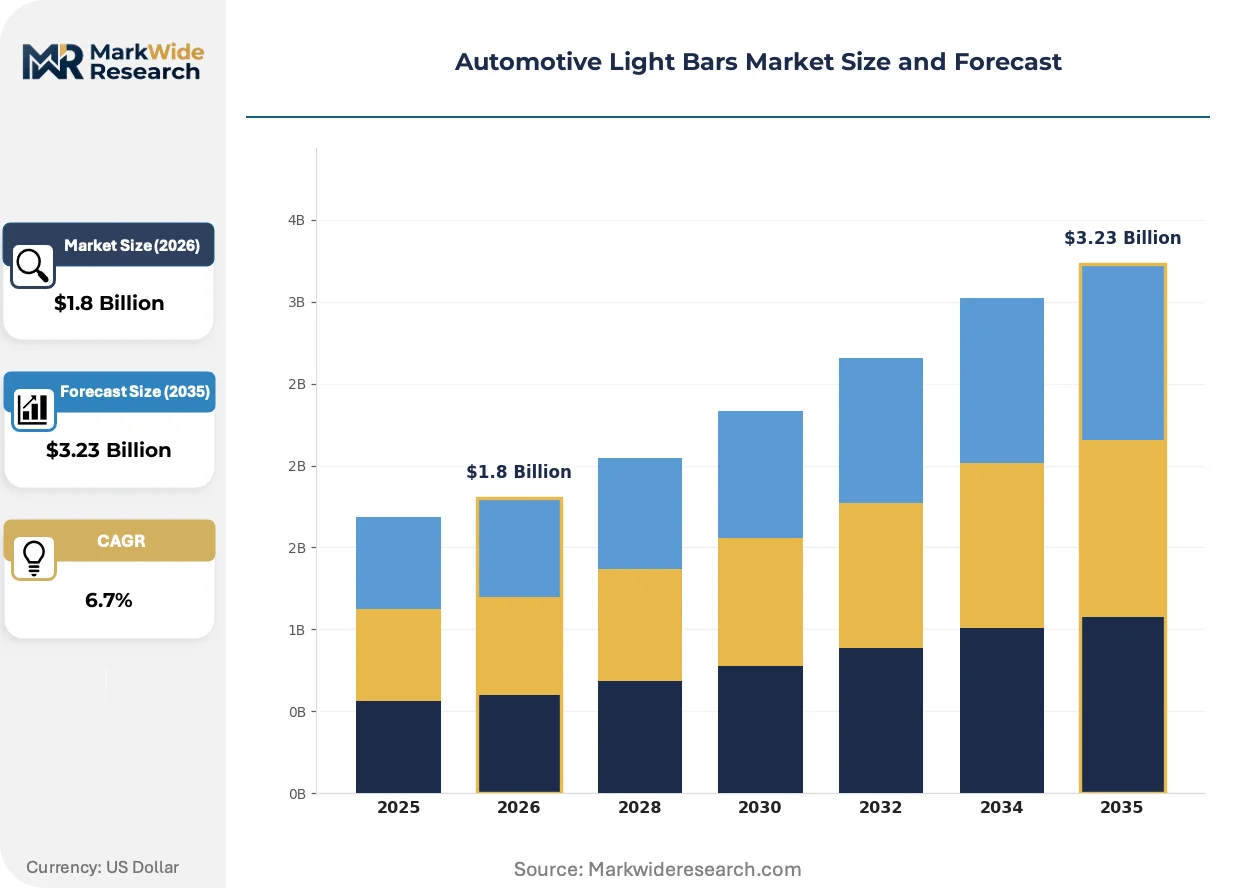
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED Light Bars, Halogen Light Bars, Xenon Light Bars, OLED Light Bars Installation Type: On-Road, Off-Road, OEM Installation, Aftermarket Installation Power Source: Electrical, Solar, Battery-Powered, Hybrid Vehicle Type: SUVs, Trucks, Vans, ATVs |
| Companies Covered | LightFORCE, STEDI, Baja Designs, KC HiLites, Vision X Lighting, Rigid Industries, Ironman 4x4, Cali Raised LED, Black Oak LED, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Light Bars Market Emerging Trajectories
Digital beam control architectures are replacing fixed-optic mechanical designs, enabling software-defined illumination patterns that adapt to terrain and traffic conditions without hardware swaps.
Chip-on-board LED packaging is virtualizing traditional discrete-diode array layouts, consolidating multiple emitters onto single thermal substrates. Off-road racing teams and expedition vehicle builders are adopting these compact modules for weight-critical applications. The technology is virtualizing supplier tier structures by collapsing optical, thermal, and electrical subsystems into integrated module sourcing.
Australia's Design Rules under the Department of Infrastructure are tightening electromagnetic compatibility and vibration resistance thresholds for auxiliary lighting imports. Non-compliant shipments face border detention, redirecting procurement toward certified domestic distributors. Mining fleet operators in Western Australia are prioritizing Design Rules-compliant inventory to avoid operational downtime from customs delays.
Consumer preference is consolidating around self-installation and independent shop fitment rather than dealership service departments. Aftermarket channels in the United States are capturing volume from traditional automotive retailers by offering video-guided installation support and modular wiring harness compatibility. This behavioral pivot is most pronounced in Texas, Arizona, and Colorado, where truck ownership rates and off-road recreation participation overlap.
Automotive Light Bars Market Segmentation
Automotive light bar segmentation reveals how technical specifications, regulatory constraints, and end-use environments fragment procurement patterns across vehicle fleets and consumer upgrade cycles. Understanding these divides exposes where margin pools concentrate and which technology transitions are compressing legacy demand.
Product Type:
Use-case spectrum spans mining haul trucks requiring thermal endurance through price-sensitive emerging-market fleets still running legacy optics.
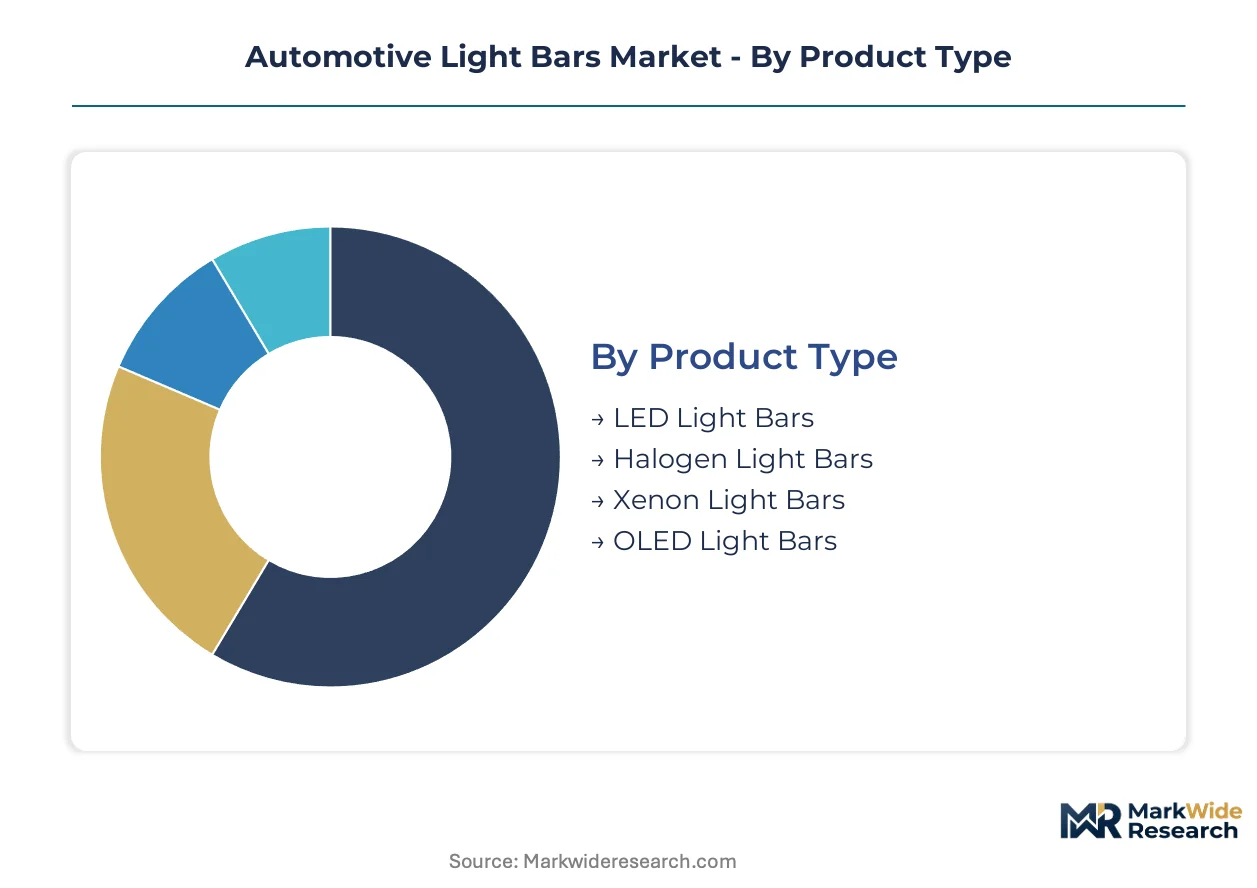
- LED Light Bars:Aluminum-substrate arrays with polycarbonate lenses achieve die-level efficiency above 130 lumens per watt and operating lifespans surpassing 50,000 hours. Mining operators in Western Australia and Chilean open-pit sites specify these for 24-hour autonomous haul truck visibility where maintenance access is costly.
- Halogen Light Bars:Tungsten-filament technology in stamped steel housings persists where upfront cost outweighs lifecycle economics. Demand concentrates in Southeast Asian commercial vehicle aftermarket channels where electrical system upgrades are capital-constrained.
- Xenon Light Bars:High-intensity discharge arc sources deliver superior candela output but require ballast hardware and warm-up latency.
- OLED Light Bars:Organic emitter panels enable conformal surface mounting for aesthetic integration on luxury SUVs and show vehicles.
The dominant share belongs to LED Light Bars, while OLED Light Bars is closing the gap fastest.
Installation Type:
Channel economics separate certified highway-legal fitment from restricted off-road-only supply chains with divergent margin structures.
- Aftermarket Installation:Self-installation and independent shop fitment capture the highest margin pools as consumers bypass dealership service departments. Video-guided installation support and modular wiring harness compatibility drive volume concentration in Texas, Arizona, and Colorado where truck ownership and off-road recreation overlap.
- OEM Installation:Factory off-road packages for trucks and SUVs integrate light bars into bumper and roof-rail architectures during assembly. NHTSA photometric compliance and glare-limit validation requirements filter supplier qualification to certified manufacturers with laboratory beam-pattern capabilities.
- On-Road:Highway-legal auxiliary lighting requires federal photometric certification and state-level statute alignment.
- Off-Road:Unrestricted output arrays for closed-course and private-land use operate outside NHTSA jurisdiction.
Aftermarket Installation commands the largest volume position, while OEM Installation is expanding most quickly as factory off-road packages proliferate.
Power Source:
Electrical system load constraints and fleet electrification roadmaps are reshaping how auxiliary lighting draws energy.
- Electrical:Hardwired 12V and 24V integration with vehicle alternator systems dominates commercial and consumer applications. LED thermal efficiency gains are reducing alternator load constraints and enabling broader fitment across compact vehicle segments.
- Battery-Powered:Lithium-ion cell packs with magnetic or clamp mounting serve temporary and rental fleet applications. Agricultural contractors in seasonal harvest windows specify these for rapid equipment reconfiguration without electrical system modification.
- Solar:Photovoltaic panel integration targets remote-area vehicles with extended stationary operation.
- Hybrid:Dual-source architectures combine alternator charging with battery buffering for high-output intermittent use.
Electrical retains the dominant installation base, though Battery-Powered is gaining share fastest among seasonal and rental fleet operators.
Vehicle Type:
Chassis architecture and duty-cycle intensity determine beam-pattern requirements and mounting hardware specifications.
- Trucks:Full-size and heavy-duty pickup platforms with factory tow packages and off-road trim levels anchor OEM installation volume. Baja Designs and KC HiLites cultivate deep specification relationships with Ford, GM, and Stellantis fleet purchasing departments.
- SUVs:Body-on-frame and unibody architectures with roof-rail and grille-mount compatibility support consumer upgrade cycles. Adventure tourism expansion in the southwestern United States drives aftermarket array installation for unsealed terrain navigation.
- ATVs:All-terrain vehicle applications prioritize weight minimization and impact resistance for recreational and utility use.
- Vans:Commercial delivery and passenger transport configurations require discrete mounting and reduced glare for on-road compliance.
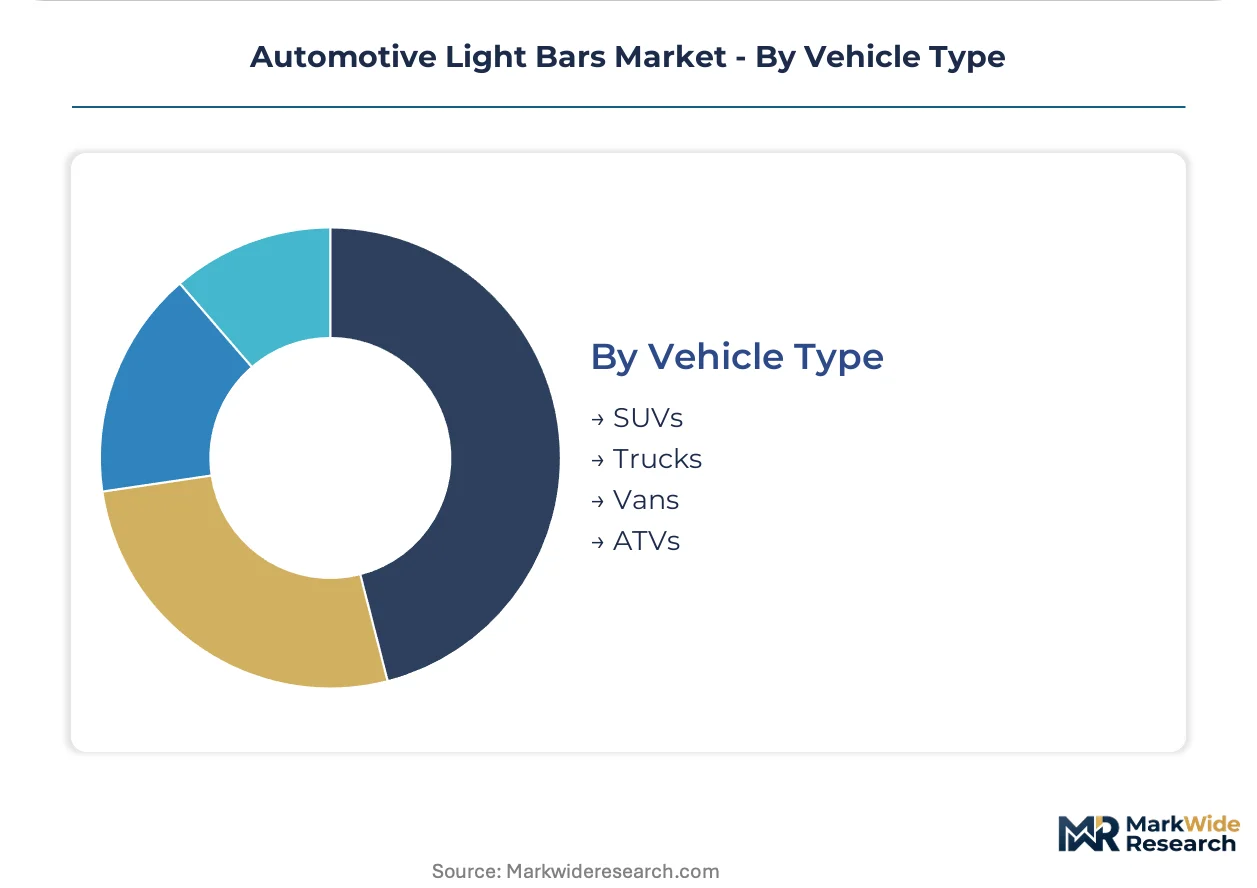
Trucks hold the dominant share by installation volume, while SUVs are climbing the fastest as factory off-road packages broaden across mid-size platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Melbourne anchors Australia's import throughput for auxiliary lighting hardware, while the Trans-Australian Railway enables inland distribution to mining corridors. These infrastructure assets sustain the country's position as the most concentrated demand center for heavy-duty LED arrays.
Australia
Mining fleet operators in Western Australia's Pilbara region and Queensland's Bowen Basin specify Design Rules-compliant LED bars for autonomous haul truck visibility. The Department of Infrastructure enforces electromagnetic compatibility and vibration standards that filter non-compliant imports at border checkpoints. Perth-based distributors maintain certified inventory buffers to avoid customs detention delays for Pilbara site operators.
United States
Texas, Arizona, and Colorado drive aftermarket volume through overlapping truck ownership and off-road recreation participation. NHTSA photometric certification requirements and state-level auxiliary lighting statutes create interstate commerce complexity for distributors. Detroit's supplier corridor hosts beam-pattern validation laboratories that filter highway-legal product portfolios for Ford, GM, and Stellantis factory off-road packages.
Chile
Open-pit copper mining in the Atacama Desert sustains demand for thermal-endurance LED arrays on 24-hour autonomous haul trucks. The country's mining regulator mandates visibility equipment standards for large-scale extraction operations. Antofagasta serves as the procurement hub where fleet operators coordinate heavy-duty lighting retrofits for Escondida and Chuquicamata sites.
Germany
Automotive lighting engineering talent concentrates around Munich and Stuttgart supplier corridors, feeding optical simulation and compound reflector design capabilities. KBA type-approval processes govern auxiliary lighting fitment for highway-legal applications across EU member states. Bavaria's technical universities supply photometric specialists to Tier-1 lighting system integrators.
South Africa
Platinum and gold mining operations in the Bushveld Igneous Complex require high-durability auxiliary lighting for underground and open-pit extraction. The country's national automotive regulator enforces SABS standards for electromagnetic compatibility and ingress protection. Johannesburg-based distributors serve as the regional logistics node for mining fleet procurement across Southern Africa.
Automotive Light Bars Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying thermal substrates, optical-grade polycarbonate, and LED dies. The vendor base arranges across three tiers: desert racing heritage brands sustaining premium positioning, commercial fleet specialists competing on ingress protection ratings, and price-oriented fabricators serving emerging-market residual demand. Two dominant competitive moves are reshaping positioning: direct-to-consumer platform expansion capturing margin pools from traditional retailers, and IP67+ sealing standardization opening specification windows in agricultural and marine applications.
Within the heritage-positioned tier, Baja Designs and KC HiLites exemplify racing-credibility anchoring among off-road professionals and 4x4 community enthusiasts. Vision X Lighting occupies a position representing the commercial fleet specialist archetype, with naming conventions suggesting heavy-duty specification focus. These three entities illustrate how competitive positioning fragments across use-case specialization rather than converging on undifferentiated scale.
| Leading Market Players |
|---|
| LightFORCE |
| STEDI |
| Baja Designs |
| KC HiLites |
| Vision X Lighting |
| Rigid Industries |
| Ironman 4x4 |
| Cali Raised LED |
| Black Oak LED |
| Others |
Supply Flow & Price Mechanics
Tariff exposure on optical-grade polycarbonate imports from East Asian petrochemical corridors compresses margin pools for distributors serving multiple North American jurisdictions while simultaneously forcing procurement diversification toward certified Australian and German suppliers. This input-cost volatility propagates through three distinct pricing tiers that separate racing-heritage premium brands from commercial fleet specialists and price-oriented fabricators.
Pricing Analysis
Volume-discount tiering structures stratify across premium, standard, and economy levels based on certification grade and after-sales service bundling. NHTSA photometric compliance and glare-limit validation create price premiums for highway-legal product portfolios, while uncertified off-road-only arrays compete on unit economics. Cost compression in the economy tier intensifies because LED module cost declines displace residual halogen demand. Mining fleet operators in Western Australia exhibit the least price sensitivity due to downtime costs from customs detention, whereas Southeast Asian commercial vehicle aftermarket channels remain highly price-sensitive.
Supply Chain Analysis
Extended payment terms from East Asian polycarbonate suppliers strain working capital for North American distributors managing multi-jurisdiction inventory buffers. Manufacturing concentrates in China, South Korea, and Taiwan for LED dies and aluminum substrates, while optical-grade lens production clusters in Japanese and German petrochemical corridors. Single-source vulnerability runs through concentrated polycarbonate supply channels exposed to freight friction and tariff escalation. Distribution runs through direct-to-consumer platforms and installer networks that capture margin pools from traditional brick-and-mortar automotive retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating around direct-to-consumer platforms and mining fleet procurement departments that demand certified compliance documentation, fragmenting traditional distributor influence.
For Market Incumbents: Entrench specification relationships with Ford, GM, and Stellantis platform engineering teams through NHTSA-certified beam-pattern validation capabilities. Deepen backward integration into aluminum substrate sourcing to buffer against smelting energy-cost volatility. Racing-heritage brands face displacement from commercial fleet specialists competing on IP67+ ingress protection ratings.
For New Entrants and Emerging Players: Pursue agricultural and marine applications where pressure-wash exposure drives specification windows for heavy-duty sealing ratings. Battery-powered temporary mounting systems for seasonal rental fleets represent the most penetrable segment. Installer network partnerships with video-guided installation support offer the lowest customer acquisition friction.
For Investors and Strategic Acquirers: The market sits at a certification-consolidation phase that favors vertically integrated manufacturers with captive laboratory beam-pattern capabilities. Long-term viability over the next decade hinges on electromagnetic compatibility and vibration resistance testing infrastructure. Watch for Australian Design Rules enforcement intensity as an inflection indicator for compliant inventory valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| IP67+ Sealing Certification Investment | Australian mining fleet operators prioritize Design Rules-compliant inventory to avoid customs detention delays. |
| Direct-to-Consumer Platform Expansion | Installer networks in Texas, Arizona, and Colorado capture margin pools from traditional automotive retailers. |
| Backward Integration into Aluminum Substrates | Thermal management hardware sourcing buffers against energy-intensive smelting cost volatility. |
| NHTSA Photometric Laboratory Investment | Beam-pattern validation capabilities filter highway-legal product portfolios for OEM qualification. |
| Battery-Powered Product Line Development | Agricultural contractors in seasonal harvest windows specify rapid equipment reconfiguration without electrical modification. |
Methodological Framework
A spread of perspectives from aftermarket distributor procurement managers, OEM platform engineers, mining fleet maintenance directors, and optical-grade polycarbonate suppliers converged on the working assumptions. Primary interviews combined with secondary validation against NHTSA photometric filing databases, EPA energy-efficiency documentation, Australian Department of Infrastructure Design Rules, and vehicle production registration data. Bottom-up segmentation triangulation across product type, installation channel, and vehicle application anchored value estimates against top-down macroeconomic indicators.
Demand-supply-balance framing modeled consumption intensity across the projection horizon by vehicle class, propulsion architecture, content per vehicle, and regional regulatory cluster. CAGRs derived from segment-level growth trajectories weighted by mining fleet electrification roadmaps, adventure tourism participation rates, and LED lumen-per-watt efficiency curves. Forecast inputs incorporated state-level auxiliary lighting statute evolution and aluminum smelting energy-cost volatility assumptions.
Sensitivities concentrate around NHTSA glare-limit enforcement intensity, Australian customs detention rates for non-compliant imports, and polycarbonate tariff schedule adjustments. Forecasts reflect documented assumptions about certification timeline compression and thermal efficiency improvement trajectories. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Polycarbonate Glazing Market
Automotive Components
North America Automotive Bearing Market
Automotive Components
Automotive Tailgate Market
Automotive Components
Automotive Distributor O Ring Market
Automotive Components
Automotive Pedals Market
Automotive Components
Egypt Commercial Vehicles Lubricants Market
Automotive Components
Automotive Active Suspension System Market
Automotive Components
Automotive Gear Shifter Market
Automotive Components
Automobile Accessories Market
Automotive Components
Asia Pacific Automotive Bearing Market
Automotive Components
Automotive Connecting Rod Bearing Market
Automotive Components
Automotive Hubcaps Market
Automotive Components
Automotive Carbon Fiber Composites Parts Market
Automotive Components
India Automotive Airfilters Market
Automotive Components
Automotive V-Belts Market
Automotive Components
US Automotive Composites Market