
 Float Glass for Automotive Market | 2026-2036
Float Glass for Automotive Market Size, Share, and Industry Trends Forecast 2026-2036
Float Glass for Automotive Market Insights
Europe's F-Gas Regulation is restructuring the cost-of-entry calculus for coated glass suppliers serving OEMs with refrigerant-intensive manufacturing footprints. AGC Inc. leverages its integrated chemical-glass complex in Belgium to sustain low-emissivity output without third-party coating dependencies. Saint-Gobain anchors European supply through its dedicated automotive float lines in Germany and France. Fuyao Glass Industry Group Co., Ltd. dominates aftermarket replacement channels across North America while competing aggressively for EV platform contracts with Detroit Three automakers.
Float glass for automotive consists of soda-lime silica sheet produced via the Pilkington process, typically achieving thicknesses between 2.1 mm and 6 mm, then subjected to thermal or chemical strengthening to meet ECE R43 fragmentation standards for occupant safety. The technology dimension splits between laminated glass, which commands premium positioning in windshield applications due to interlayer acoustic and HUD compatibility requirements, and tempered glass, which occupies cost-optimized volume in side and rear window programs where single-pane construction satisfies regulatory thresholds.
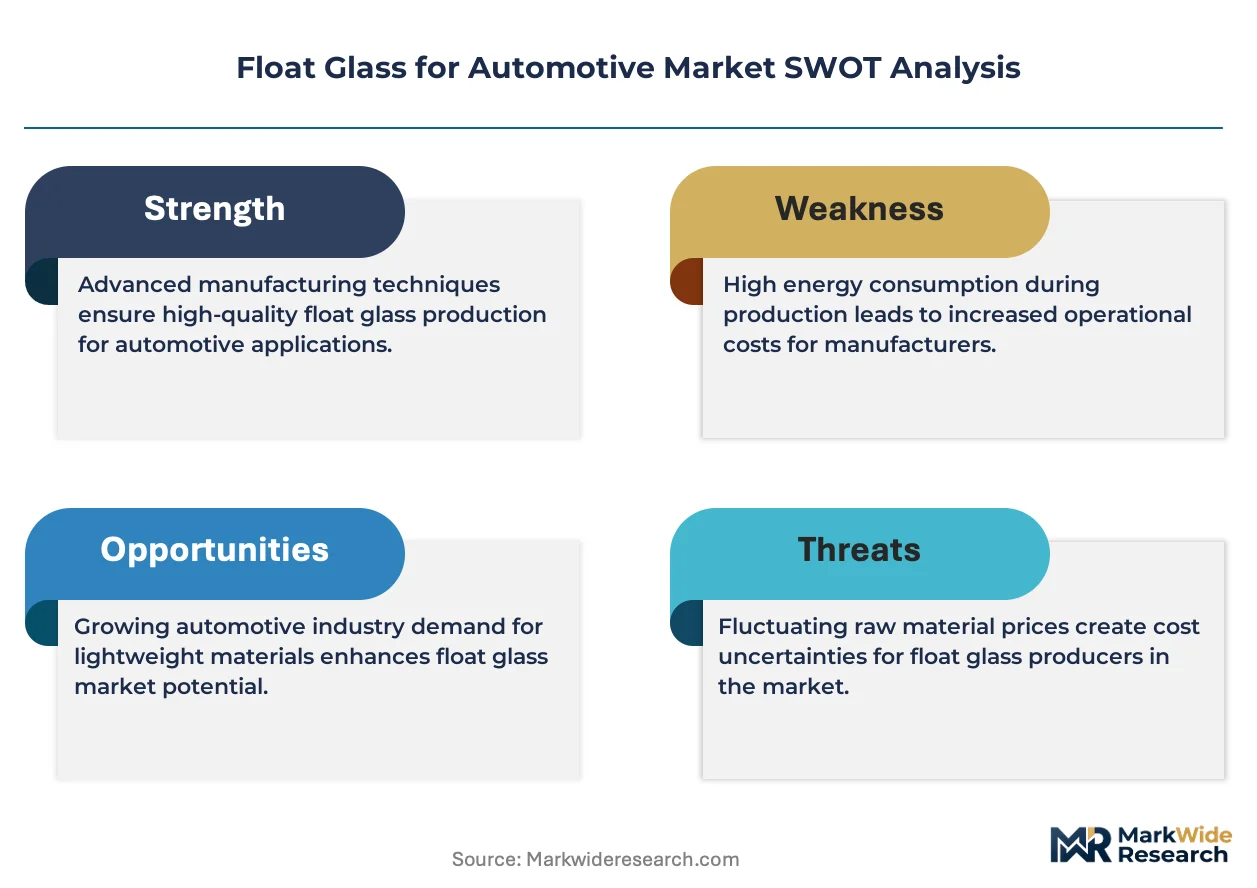
NHTSA's FMVSS 205 and ECE R43 define optical clarity and impact resistance baselines that all suppliers must navigate, while China's GB 9656 strengthens domestic content rules for glass installed on vehicles produced within its territory. OEMs, as the dominant end-user channel, control specification lock-in through platform-level design cycles that extend across multiple model years. Stakeholders must monitor how smart glass electrification requirements reshape lamination complexity and whether coating suppliers can decarbonize processes ahead of tightening EU Green Deal implementation timelines.
Market Dynamics
Electric vehicle platform proliferation is compressing windshield specification cycles from five years to eighteen months, forcing float glass suppliers to accelerate laminated interlayer innovation while managing furnace reconfiguration costs.
Growth Catalysts
- Panoramic roof penetration:EV manufacturers specify oversized laminated assemblies exceeding three square meters, multiplying glass area per vehicle platform. NHTSA's FMVSS 205 compliance for optical distortion remains mandatory.
- EU F-Gas Regulation:The phasedown of fluorinated greenhouse gases in coating processes is redirecting capital toward sputtered silver oxide alternatives. REACH-compliant low-emissivity formulations now dominate OEM tender requirements.
- Head-up display compatibility:Wedge-shaped PVB interlayers with precisely controlled optical wedges are becoming standard in premium vehicle segments. HUD projection clarity requirements specify sub-0.5 mrad angular deviation tolerance.
Market Restraints
- Natural gas cost volatility:Float furnace operations consume 5-7 GJ per ton of glass; European suppliers face TTF-indexed energy exposure compressing margin visibility.
- Tin bath supply concentration:High-purity tin refining capacity clusters in Southeast Asian smelters, creating single-source fragility for Pilkington process operations.
- Silica sand quality degradation:Lower iron content requirements for automotive optical clarity strain high-purity deposit availability in North American quarries.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for advanced automotive components now explicitly cover tempered and laminated glass manufacturing facilities. Domestic OEMs seek localized windshield supply.
- Electrochromic integration:Convergence of suspended particle device films with standard lamination lines enables smart dimming roof assemblies without dedicated module suppliers.
- Aftermarket consolidation:Insurance-driven preferred supplier networks are displacing fragmented independent glass shops in North American collision repair channels.
Industry Challenges
- Optical metrology talent scarcity:Qualified engineers capable of calibrating laser-based wedge angle measurement systems command premium compensation in Germany and Japan.
- ECE R43 homologation timelines:Fragmentation test certification for new thickness variants requires six to nine months of documented sampling across climate conditions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Float Glass for Automotive Market |
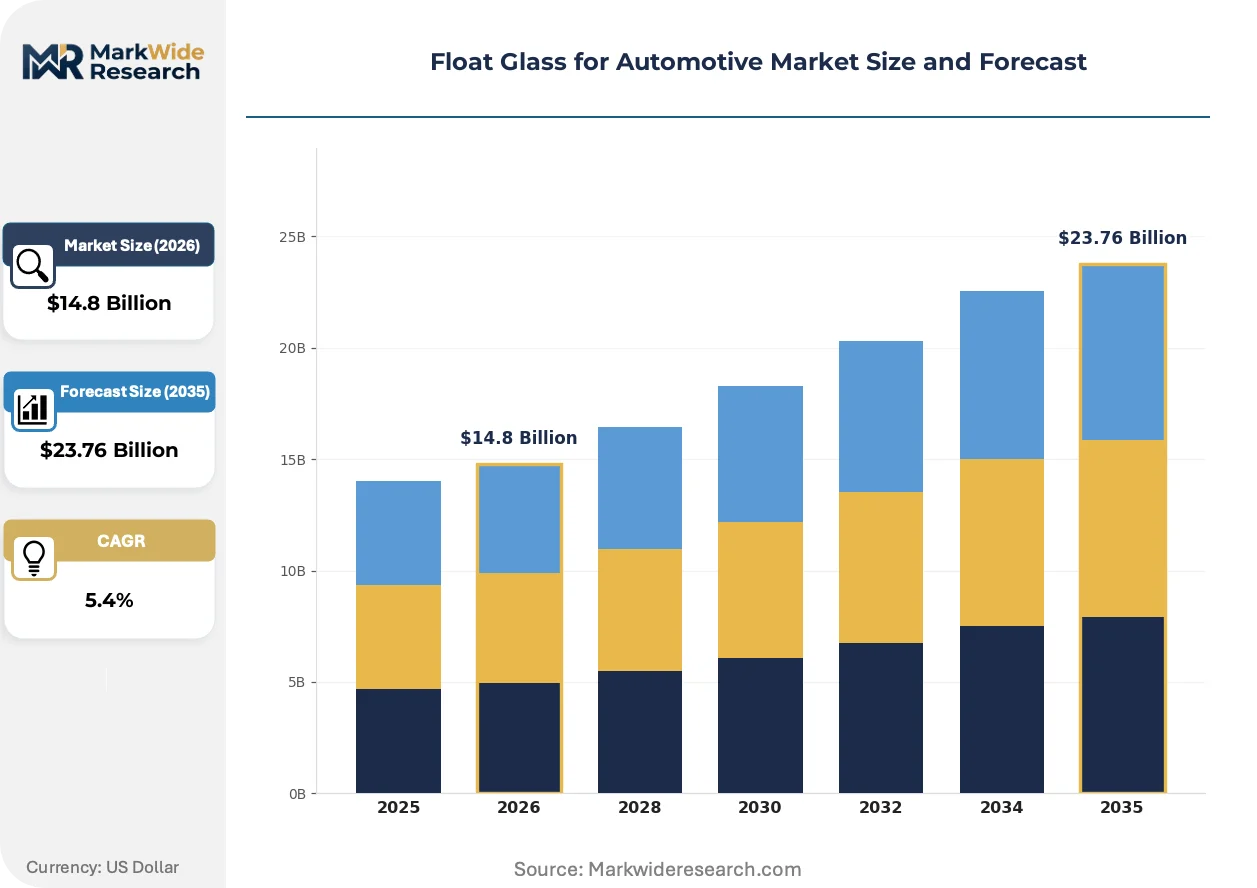
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $23.76 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Windshield, Side Windows, Rear Windows, Sunroof Application: Passenger Cars, Commercial Vehicles, SUVs, Electric Vehicles End User: OEMs, Aftermarket Providers, Dealerships, Fleet Operators Technology: Laminated Glass, Tempered Glass, Coated Glass, Smart Glass |
| Companies Covered | AGC Inc., Saint-Gobain, Fuyao Glass Industry Group Co., Ltd., Nippon Sheet Glass Co., Ltd., Xinyi Glass Holdings Limited, Guardian Industries, Central Glass Co., Ltd., Corning Incorporated, Sisecam, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Float Glass for Automotive Market Trends and Innovations
Automotive glazing is transitioning from passive barrier components to active interface elements, with thermal management, connectivity, and structural integration now co-equal design priorities alongside optical performance.
Embedded antenna glass is decentralizing RF subsystem architecture by integrating 5G, V2X, and GNSS radiating elements directly within laminated windshields. Tier 1 telematics suppliers are adopting these assemblies to eliminate roof-mounted shark fin modules. This convergence is compressing supplier tiers and forcing glass manufacturers to develop in-house electromagnetic simulation capabilities.
Europe's F-Gas Regulation is mandating fluorinated gas elimination from magnetron sputtering operations by 2030. Coating suppliers are retrofitting production lines with closed-loop argon recovery systems. Low-emissivity glass procurement specifications from Stuttgart and Munich-based OEMs now require documented F-gas-free process certification.
Direct OEM contracting is displacing traditional Tier 1 glazing integrators for EV platform launches. BYD, NIO, and Tesla Shanghai negotiate multi-year supply agreements specifying furnace-dedicated capacity. This concentration is visible across China's eastern manufacturing corridor where glass plants co-locate with vehicle assembly operations.
Float Glass for Automotive Market Segmentation
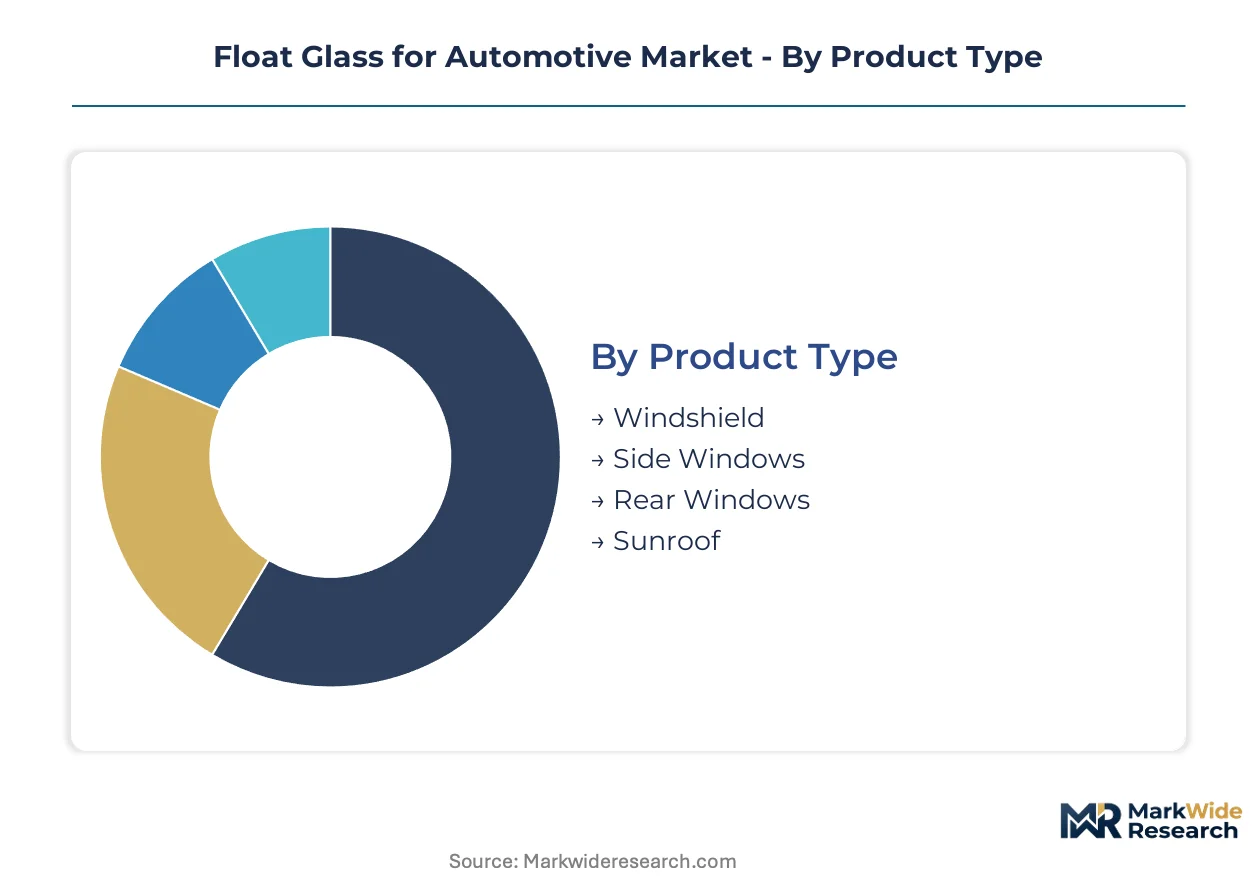
Float glass for automotive segments along four intersecting dimensions that determine furnace configuration, coating investment, and customer contracting terms. Product type and technology choices lock in capital intensity for suppliers, while application and end-user channels dictate margin structures and inventory cycles.
Product Type:
Windshield and sunroof assemblies demand laminated construction with interlayer integration, while side and rear windows accommodate simpler tempered formats that reduce unit costs.
- Windshield:Laminated soda-lime silica with PVB interlayers meeting ECE R43 optical distortion standards. OEMs in Germany and Japan specify wedge-shaped profiles for HUD compatibility, compressing specification cycles to eighteen months.
- Sunroof:Oversized laminated panels exceeding three square meters, predominantly specified by EV manufacturers for panoramic roof assemblies. NHTSA FMVSS 205 compliance for optical clarity remains mandatory across all configurations.
- Side Windows:Tempered single-pane construction optimized for cost-sensitive volume programs.
- Rear Windows:Tempered glass with integrated defogging elements, standard across passenger and commercial vehicle platforms.
Windshield leads volumes today; sunroof is gaining share fastest.
Application:
Passenger car platforms generate baseline demand curves, while electric vehicle programs are rewriting glass area specifications and procurement timelines.
- Electric Vehicles:Panoramic roof penetration and expanded windshield areas multiply glass content per platform. Tesla Shanghai, NIO, and BYD anchor supply contracts through China's eastern manufacturing corridor.
- Passenger Cars:Conventional internal combustion platforms with standardized glazing footprints and five-year specification cycles.
- SUVs:Larger surface areas and premium positioning drive laminated content above segment averages.
- Commercial Vehicles:Cost-optimized tempered glass dominates, with durability specifications exceeding passenger car requirements.
Passenger cars retain the largest installed base; electric vehicles show the steepest expansion trajectory.
End User:
OEMs control specification lock-in through platform-level design cycles, while aftermarket channels respond to insurance-driven consolidation trends.
- OEMs:Direct contracting for furnace-dedicated capacity, with multi-year agreements specifying thickness variants and coating requirements. Platform design cycles extend across multiple model years.
- Aftermarket Providers:Insurance-preferred supplier networks displacing independent glass shops across North American collision repair channels.
- Dealerships:Warranty-backed replacement services tied to brand-certified glass sourcing.
- Fleet Operators:Volume procurement with standardized specifications and extended service interval requirements.
OEMs dominate value capture; aftermarket providers are consolidating fastest.
Technology:
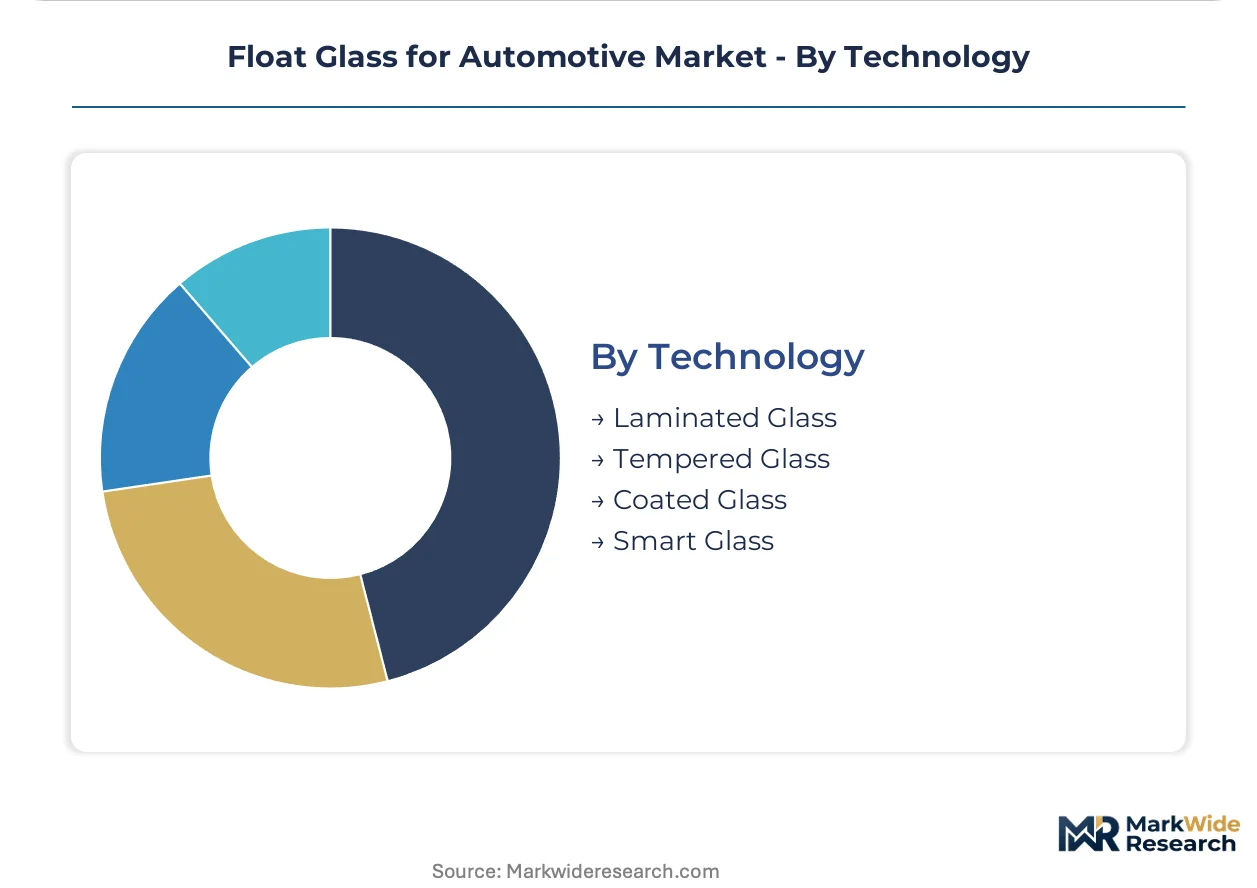
Laminated and tempered formats split the market by safety function, while coating and smart glass technologies are attracting capital for thermal management and connectivity integration.
- Laminated Glass:PVB interlayer construction for windshield and sunroof applications. Acoustic dampening and HUD wedge profiles command premium positioning in premium vehicle segments.
- Smart Glass:Electrochromic and suspended particle device films converging with standard lamination lines. Embedded antenna integration for 5G and V2X is compressing supplier tiers.
- Tempered Glass:Thermal strengthening for side and rear window programs, occupying cost-optimized volume positions.
- Coated Glass:Low-emissivity formulations with sputtered silver oxide alternatives replacing fluorinated processes under EU F-Gas Regulation timelines.
Tempered glass maintains volume leadership; smart glass is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Glass furnace engineers and optical metrology specialists cluster in Germany, Japan, and China's eastern corridor, anchoring regional production capabilities and R&D intensity for automotive glazing systems.
China
EV platform launches from NIO, BYD, and Tesla Shanghai are compressing windshield specification cycles to eighteen months. GB 9656 domestic content rules strengthen localization requirements for glass installed on vehicles produced within Chinese territory. The Yangtze River Delta manufacturing corridor concentrates furnace-dedicated capacity alongside vehicle assembly operations.
Germany
Stuttgart and Munich-based OEMs now mandate F-gas-free low-emissivity coating certifications in procurement specifications. KBA homologation requirements for ECE R43 fragmentation standards maintain rigorous optical clarity thresholds. The Baden-Württemberg industrial belt hosts dedicated automotive float lines serving premium vehicle programs.
United States
Detroit Three automakers are expanding laminated glass procurement for electric vehicle panoramic roof assemblies. NHTSA FMVSS 205 compliance for optical distortion remains mandatory across all configurations. The Great Lakes manufacturing region anchors tempered glass production for cost-optimized side and rear window programs.
Japan
Precision wedge-shaped PVB interlayer development for HUD compatibility concentrates among optical engineering specialists in Nagoya and Tokyo. METI industrial policy supports advanced materials R&D for smart glass electrification. The Chubu region maintains specialized lamination capabilities for sub-0.5 mrad angular deviation tolerances.
India
Domestic OEMs are seeking localized windshield supply under PLI scheme incentives for advanced automotive components. BIS standards alignment with ECE R43 optical requirements streamlines homologation pathways. The Tamil Nadu and Maharashtra manufacturing corridors attract tempered and laminated glass facility investments.
Float Glass for Automotive Market Competitive Landscape
The competitive structure tilts toward integrated chemical-glass complexes with captive coating capabilities. Three to five multinational suppliers control premium-tier OEM contracts through furnace-dedicated capacity arrangements. Two strategic archetypes dominate: vertically integrated material-science conglomerates with in-house chemical operations, and specialized automotive glazing fabricators with regional cost advantages. Capacity expansion and strategic partnerships represent the dominant competitive moves, as suppliers secure multi-year platform agreements before furnace reconfiguration cycles conclude.
Within the integrated materials tier, AGC Inc. and Saint-Gobain exemplify archetypes leveraging chemical-glass complexes to sustain low-emissivity output without third-party dependencies. Fuyao Glass Industry Group Co., Ltd. occupies a position among specialized automotive fabricators competing aggressively for EV platform contracts while dominating aftermarket replacement channels across North America.
| Leading Market Players |
|---|
| AGC Inc. |
| Saint-Gobain |
| Fuyao Glass Industry Group Co., Ltd. |
| Nippon Sheet Glass Co., Ltd. |
| Xinyi Glass Holdings Limited |
| Guardian Industries |
| Central Glass Co., Ltd. |
| Corning Incorporated |
| Sisecam |
| Others |
Pricing and Supply Chain Analysis
Detroit Three automakers and premium German OEMs concentrate procurement power through multi-year furnace-dedicated contracts, locking in contract-based long-term offtake pricing that insulates volume buyers from spot volatility in natural gas-indexed float furnace operations.
Pricing Analysis
Service bundling separates glass supply from installation and calibration support, with OEMs paying premium rates for wedge-shaped PVB interlayer integration and HUD compatibility testing while aftermarket channels absorb unbundled glass-only pricing. Price differentiation rests on certification tier—ECE R43 homologation commands premium positioning over FMVSS 205 baseline compliance—and volume scale, with platform-level agreements securing dedicated furnace slots. Cost compression in European laminated glass is intensifying because TTF-indexed energy exposure erodes margin visibility. Fleet operators and commercial vehicle buyers exhibit highest price sensitivity; premium EV manufacturers show lowest sensitivity due to specification lock-in for panoramic roof assemblies.
Supply Chain Analysis
Freight economics favor co-location of float furnace operations with vehicle assembly plants, compressing logistics costs for oversized laminated panels exceeding three square meters. Manufacturing gravity centers on China, Germany, and the United States, with the Yangtze River Delta, Baden-Württemberg, and Great Lakes regions hosting dedicated automotive float lines. High-purity tin refining capacity clusters in Southeast Asian smelters, creating single-source fragility for Pilkington process operations dependent on molten tin bath chemistry. Silica sand quality degradation in North American quarries strains optical clarity requirements. Distribution runs through direct OEM contracting channels that displace traditional Tier 1 glazing integrators for EV platform launches.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between European F-Gas Regulation compliance costs and China's GB 9656 domestic content incentives, with furnace reconfiguration capital deploying toward jurisdictions minimizing regulatory burden per ton of coated output.
For Market Incumbents: Anticipate specification cycle compression from five years to eighteen months by securing optical metrology talent in Germany and Japan before wage premiums escalate further. Defensive positioning requires backward integration into sputtered silver oxide coating capabilities to eliminate fluorinated gas dependencies ahead of EU Green Deal enforcement. Capacity addition in India's Tamil Nadu corridor captures PLI scheme incentives while serving localized windshield demand from domestic OEMs. For New Entrants and Emerging Players: Digital procurement platforms for aftermarket replacement glass offer the lowest barrier to entry, displacing fragmented independent shops through insurance-preferred supplier network aggregation. White-space targets include electrochromic smart glass integration for EV panoramic roof programs and embedded antenna laminates for 5G telematics convergence. The most penetrable segment is India's domestic OEM supply base, where BIS standards alignment streamlines homologation. A direct contracting go-to-market angle with EV-native manufacturers bypasses entrenched Tier 1 glazing integrator relationships. For Investors and Strategic Acquirers: Chemical-glass conglomerates are the most active acquirer in this space, seeking captive coating capabilities to eliminate third-party dependencies. Long-term viability over the next decade hinges on decarbonization pathway execution and smart glass electrification readiness. Acquisition targets should display integrated low-emissivity production and furnace-dedicated capacity arrangements with NIO, BYD, or Tesla Shanghai. The critical inflection signal to monitor is OEM procurement specification language mandating F-gas-free process certification, which would accelerate stranded asset risk for non-compliant coating operations.| Strategic Initiative | Industry Significance |
|---|---|
| Furnace-Dedicated Capacity Expansion | AGC Inc. and Saint-Gobain secure multi-year platform agreements with Tesla Shanghai and BYD before specification cycles conclude. |
| Backward Integration into Coating Chemicals | Integrated chemical-glass complexes eliminate REACH compliance vulnerabilities and fluorinated gas supply chain dependencies. |
| Smart Glass Electrification Partnership | Convergence of suspended particle device films with standard lamination lines enables dimming roof assemblies without module suppliers. |
| India PLI Scheme Facility Investment | Tamil Nadu and Maharashtra corridors attract tempered and laminated glass manufacturing to serve domestic OEM localization requirements. |
| Aftermarket Consolidation Acquisition | Insurance-driven preferred supplier networks displace independent glass shops across North American collision repair channels. |
Research Methodology
Direct dialogue with OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, float furnace operations managers, and optical metrology specialists grounded qualitative assessments of specification cycle compression and wedge angle tolerance requirements. Secondary validation drew from vehicle production databases, IHS Markit registration data, SEC 10-K filings from integrated glass-chemical conglomerates, and ECE R43 homologation records. Bottom-up and top-down triangulation reconciled furnace capacity utilization rates with platform-level glass content assumptions across electric vehicle and internal combustion architectures.
Bottom-up modeling aggregated content-per-vehicle estimates across windshield, sunroof, side window, and rear window applications, segmented by laminated versus tempered technology, passenger car versus SUV versus commercial vehicle class, and OEM tier positioning. Top-down analysis calibrated aggregate market expansion against vehicle production forecasts and panoramic roof penetration trajectories. CAGRs were derived from slope-consistent growth trajectory fitting across the analysis window, with inputs including natural gas cost volatility scenarios, silica sand quality degradation curves, and tin bath supply concentration risk factors.
The model assumes a particular technology adoption path; alternative pathways for electrochromic smart glass integration or embedded antenna laminate convergence would alter the outlook for traditional glazing supplier margins. Forecasts reflect assumptions about ECE R43 homologation timeline stability and F-Gas Regulation enforcement sequencing. Stakeholders should weight assumptions against their own operating context, particularly regarding furnace reconfiguration cycle timing and optical metrology talent availability in target geographies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Asia-Pacific Automotive Interior Materials Market
Automotive Interior & Exterior
Automotive Advanced Seating System Market
Automotive Interior & Exterior
Automotive Door Impact Bars Market
Automotive Interior & Exterior
Automotive Smart Faceplate Market
Automotive Interior & Exterior
Global Cabin Air Heater Market
Automotive Interior & Exterior
Brazil Automotive Flooring Market
Automotive Interior & Exterior
Automotive Sealants Market
Automotive Interior & Exterior
Vehicle Interior Air Quality Sensor Platforms Market
Automotive Interior & Exterior
Automotive Lighting Market
Automotive Interior & Exterior
Bonnet Lock Plate and Latch Market
Automotive Interior & Exterior
All Plastic Front End Module Market
Automotive Interior & Exterior
Decorative Car Accessories Market
Automotive Interior & Exterior
Automotive Exterior Trim Parts Market
Automotive Interior & Exterior
Train Seat Materials Market
Automotive Interior & Exterior
Automotive Interior Cleaner Market
Automotive Interior & Exterior
Automotive Upholstery Market