
 Automotive Exhaust Components Aftermarket Market | 2026-2036
Automotive Exhaust Components Aftermarket Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Exhaust Components Aftermarket Market Analysis
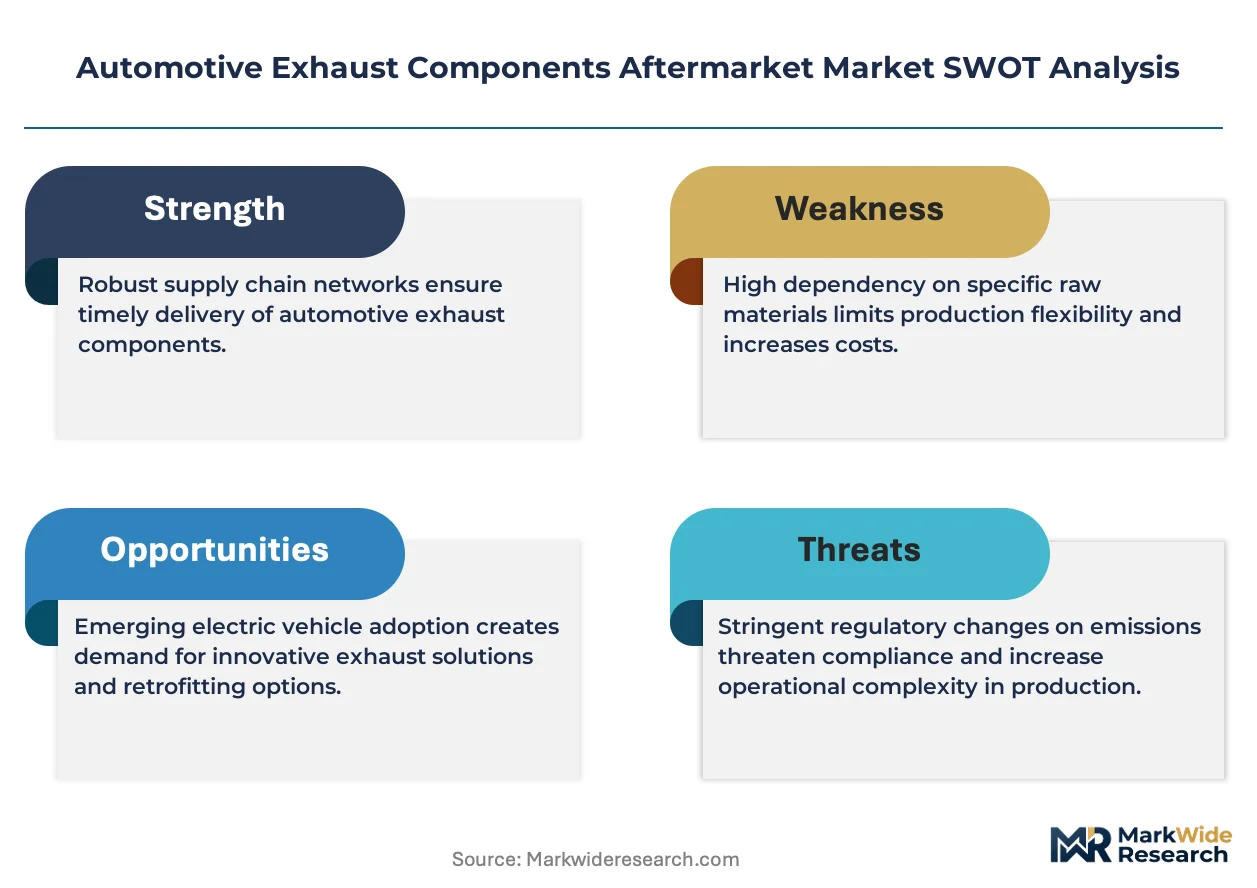
The capability gap between vertically integrated exhaust system producers and parts-only assemblers is collapsing as emission testing protocols tighten. Tenneco Inc. leverages its integrated emissions control manufacturing to sustain cost advantages across North American service networks. FORVIA Faurecia anchors its position through ceramic substrate technology leadership in catalytic converter architectures. Eberspächer competes via thermal management specialization that extends product lifecycle performance under severe duty cycles.
Automotive exhaust components encompass emission control devices, gas routing hardware, and acoustic attenuation systems fabricated from ferritic and austenitic stainless steels, with wall thicknesses typically ranging from 0.8 to 2.0 millimeters to withstand thermal cycling above 800°C while maintaining corrosion resistance. Mufflers and resonators dominate volume throughput as mature replacement categories with predictable failure modes tied to perforation and baffle degradation. Catalytic converters command premium margin pools due to platinum group metal content and escalating theft-driven replacement demand. Headers occupy a performance-oriented niche where stainless steel construction differentiates premium offerings from standard carbon steel alternatives in the enthusiast segment.
EPA tailpipe standards and California Air Resources Board zero-emission vehicle mandates reshape aftermarket demand by accelerating retirement of non-compliant platforms while preserving replacement urgency for remaining internal combustion fleets. The EU F-Gas Regulation and REACH substance restrictions constrain material formulations available to European suppliers, forcing reformulation of gasket and coating chemistries. Stakeholders must monitor the divergence between regulatory compliance investments and the shrinking window for internal combustion aftermarket profitability as electrification thresholds approach.
Market Dynamics
EPA emissions enforcement and California Air Resources Board zero-emission mandates are compressing the operational window for internal combustion aftermarket profitability while simultaneously accelerating replacement urgency for compliant fleet vehicles.
Growth Catalysts
- Commercial fleet replacement cycles:Fleet operators across the United States face accelerated exhaust system replacement schedules as EPA roadside enforcement intensifies and non-compliant vehicles face operational restrictions.
- Catalytic converter theft surge:Platinum group metal prices and insufficient scrap metal tracking infrastructure are generating unprecedented replacement demand for catalytic converters in urban markets.
- China's aging vehicle parc:Exhaust system replacement thresholds in China have exceeded critical mass as vehicles from the 2010-2015 manufacturing boom reach end-of-life component failure rates.
Market Restraints
- Platinum group metal volatility:Palladium and rhodium price swings compress margin predictability for catalytic converter remanufacturers and create inventory valuation risk.
- Supplier concentration in ceramic substrates:Three specialized producers control high-cell-density cordierite supply, creating single-source vulnerability for secondary market catalytic converter assemblers.
- Electrification substitution timeline:Battery electric vehicle penetration is eliminating exhaust system content entirely from new vehicle production, shrinking the long-term addressable base.
Strategic Opportunities
- India's enforcement gap closure:Bharat Stage VI implementation is creating first-time emissions compliance infrastructure and aftermarket service network demand in tier-2 and tier-3 cities.
- Thermal management convergence:Integration of exhaust heat recovery with hybrid powertrain thermal systems opens specialized component opportunities for suppliers with ferritic stainless steel forming expertise.
- Direct-to-fleet digital procurement:National fleet operators are consolidating supplier relationships through integrated maintenance platforms, bypassing traditional jobber distribution.
Industry Challenges
- Welding automation skill scarcity:TIG welding of thin-wall austenitic stainless steel for performance headers requires specialized technician certification that vocational programs have not scaled to meet demand.
- Homologation timeline compression:EPA and CARB certification cycles for new substrate formulations are extending beyond product development windows, delaying market entry.
- Legacy fleet data fragmentation:Exhaust system failure prediction for mixed-age commercial fleets lacks standardized telematics integration, preventing predictive maintenance model deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Exhaust Components Aftermarket Market |
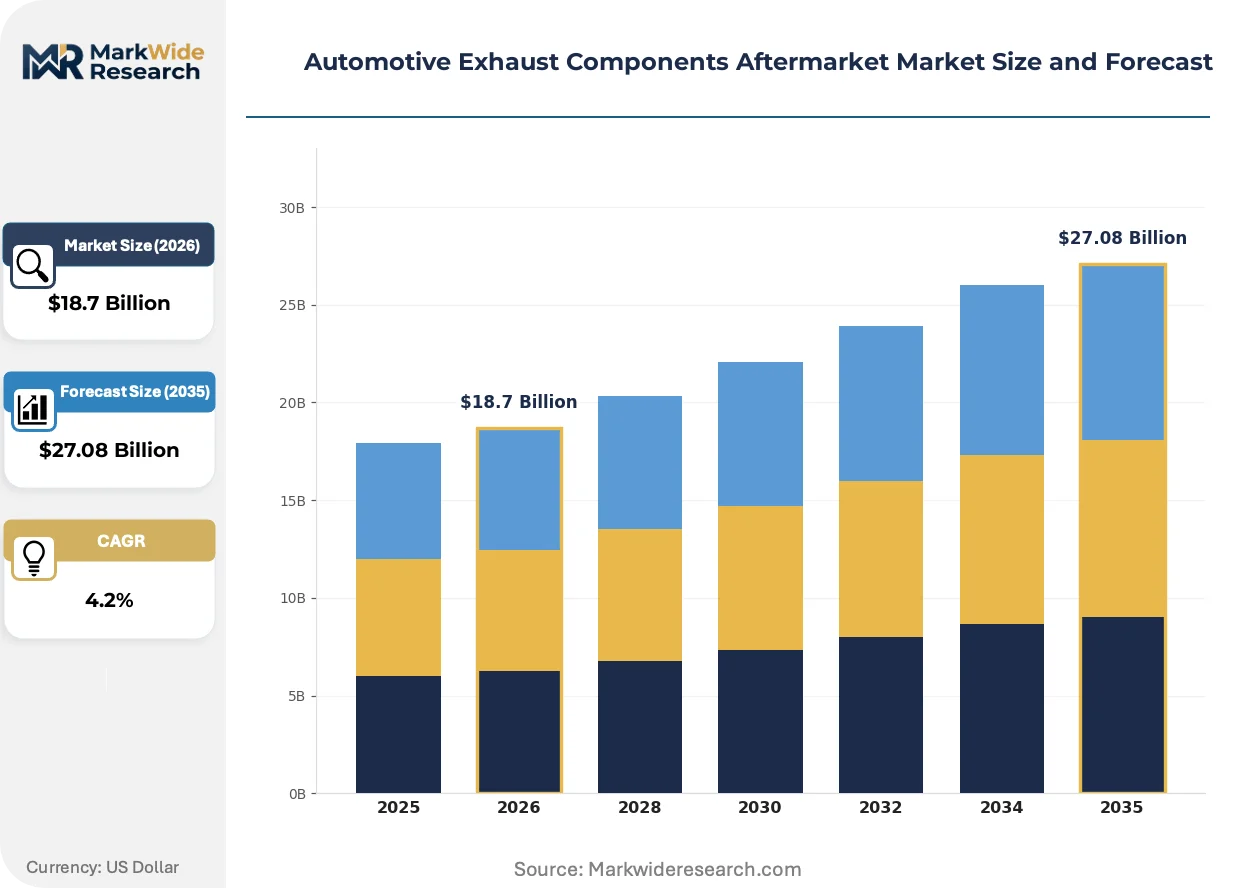
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $27.08 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mufflers, Catalytic Converters, Exhaust Pipes, Headers Material: Stainless Steel, Carbon Steel, Aluminum, Alloy End User: Service Centers, Retailers, Distributors, Individual Consumers Sales Channel: Online, Retail Stores, Wholesale, Marketplaces |
| Companies Covered | Tenneco Inc., FORVIA Faurecia, Continental AG, Eberspächer, FUTABA INDUSTRIAL CO., LTD, Bosal, Boysen, Sejong Industrial Co., Ltd, Yutaka Giken Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Exhaust Components Aftermarket Market Emerging Trajectories
Emissions testing protocol sophistication and material science advances are bifurcating the competitive landscape between integrated system producers and component assemblers. Three developments are reshaping aftermarket structure.
Advanced ceramic substrate architectures with higher cell density and thinner walls are fragmenting the catalytic converter value chain. Performance-oriented vehicle owners and commercial fleet managers are adopting these substrates for improved conversion efficiency. The technology is fragmenting procurement patterns as buyers bypass traditional remanufacturers to source directly from substrate specialists.
REACH substance restrictions and EU F-Gas Regulation are forcing reformulation of gasket materials and coating chemistries across European supply chains. Manufacturers must validate alternative elastomer compounds and ceramic fiber formulations without performance degradation. Aftermarket suppliers serving Germany and France are absorbing extended R&D cycles to maintain CE marking compliance.
Fleet maintenance departments are consolidating supplier relationships through integrated procurement platforms that bundle exhaust components with brake and driveline categories. Independent repair shops and regional distributors are losing share to direct manufacturer relationships with national fleet operators. This concentration is most visible in the United States where telematics-enabled maintenance scheduling is compressing traditional distribution layers.
Automotive Exhaust Components Aftermarket Market Segmentation
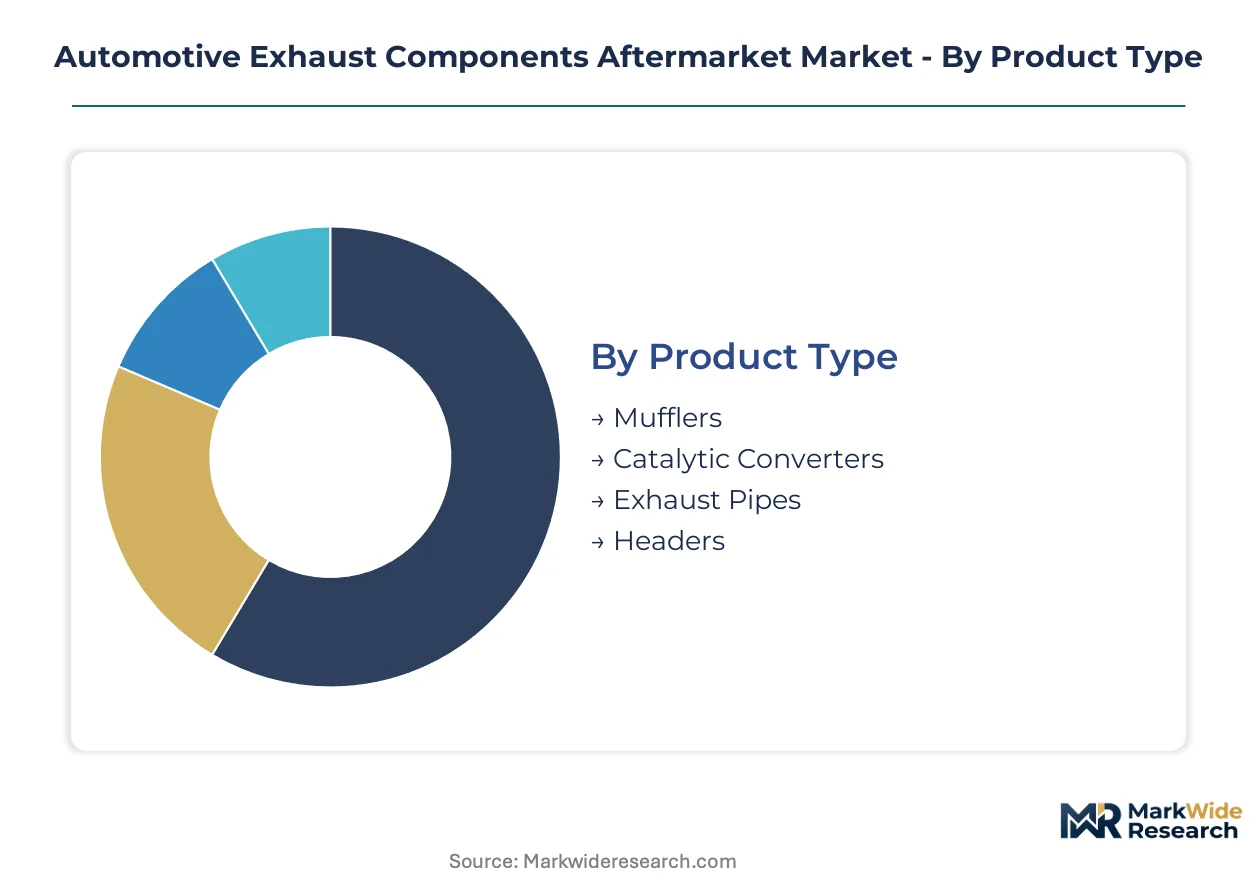
Exhaust component substitution pressures vary sharply across product categories as electrification timelines compress the addressable window for some segments while tightening emissions enforcement amplifies replacement urgency for others. Material selection and channel configuration determine margin resilience as supplier consolidation accelerates.
Product Type:
Electrification substitution threat concentrates most intensely on acoustic attenuation hardware while emission control devices face regulatory-driven demand spikes before eventual phase-out.
- Mufflers:Acoustic attenuation systems fabricated from ferritic stainless steel with perforated internal baffles and fiberglass packing. Fleet replacement demand concentrates in California and Texas where EPA roadside enforcement has intensified operational compliance requirements.
- Catalytic Converters:Ceramic substrate-based emission control devices incorporating platinum group metal catalysts. Theft-driven replacement volume in Chicago, Los Angeles, and Houston has created unprecedented secondary market demand that outpaces traditional wear-based failure cycles.
- Exhaust Pipes:Gas routing hardware connecting manifold to tailpipe termination, typically 1.5-3.0 inch diameter.
- Headers:Performance-oriented manifold replacements fabricated from TIG-welded austenitic stainless steel for enthusiast applications.
Mufflers retain volume leadership; catalytic converters hold the steepest expansion curve.
Material:
Cost tier stratification separates premium corrosion-resistant formulations from commodity carbon steel alternatives as thermal cycling requirements intensify under stop-start hybrid operation.
- Stainless Steel:Ferritic and austenitic grades (409, 304, 316) with 0.8-2.0mm wall thickness for thermal fatigue resistance above 800°C. Commercial fleet procurement in the United States specifies 409-grade aluminized variants for cost-optimized replacement cycles.
- Carbon Steel:Low-alloy formulations with aluminized or ceramic coating for oxidation protection in price-sensitive replacement applications.
- Aluminum:Lightweight extrusions limited to low-temperature sections and heat shield applications.
- Alloy:High-nickel content formulations for extreme duty commercial applications and performance headers.
Stainless steel dominates replacement volume; alloy formulations gain share fastest in severe-duty segments.
End User:
Customer type concentration is fragmenting as national fleet operators bypass traditional distribution layers through direct procurement platforms.
- Service Centers:Professional installation facilities with EPA-certified technicians and emissions testing equipment. Demand concentrates in metropolitan clusters where CARB enforcement infrastructure is densest.
- Retailers:Auto parts chains stocking replacement inventory for walk-in professional and DIY customers.
- Distributors:Regional warehouse operations serving independent repair shops with consolidated brake, driveline, and exhaust categories.
- Individual Consumers:Enthusiast and DIY segments sourcing performance headers and direct-fit replacement components.
Service centers retain volume leadership; individual consumers show the steepest channel shift toward digital procurement.
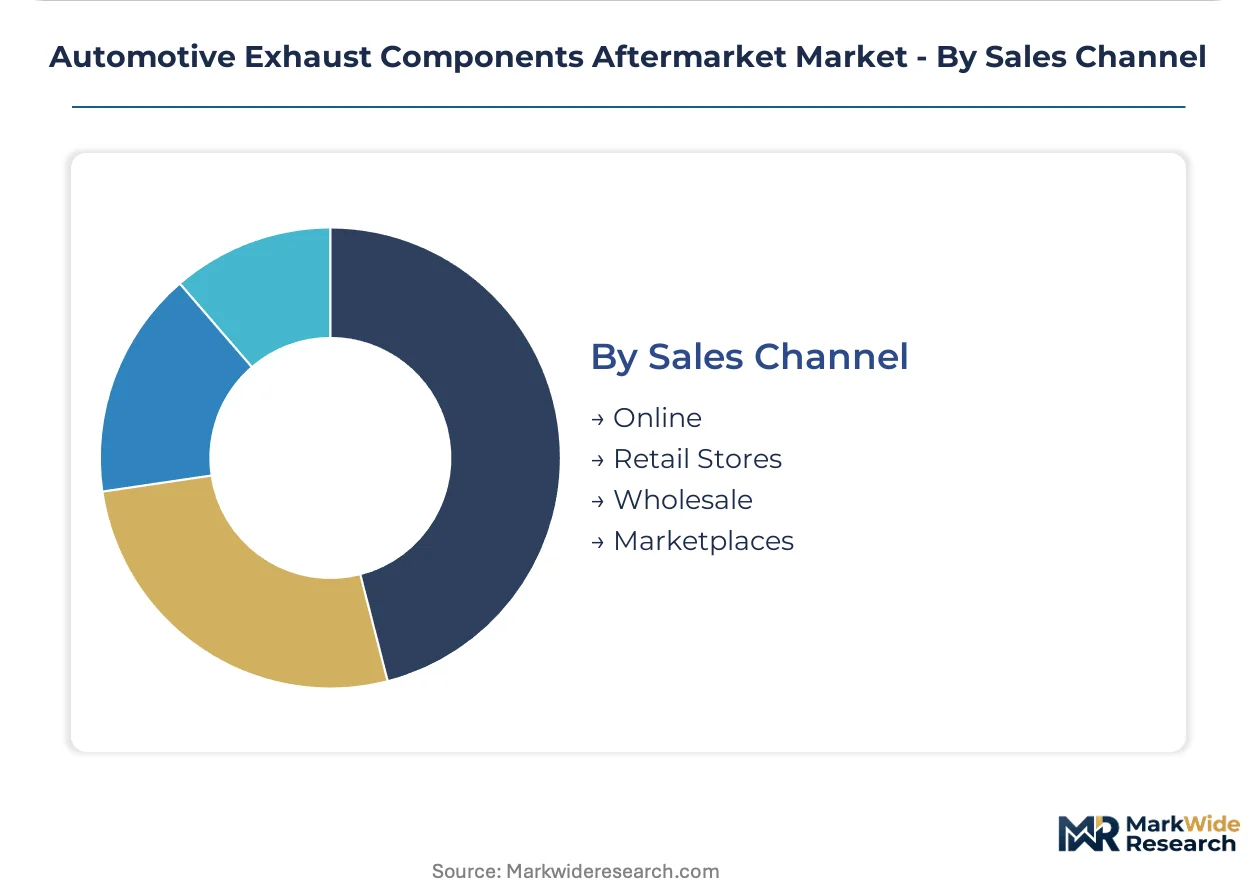
Sales Channel:
Channel maturity varies by buyer sophistication, with commercial fleet procurement migrating fastest toward integrated maintenance platforms.
- Online:Direct-to-installer and direct-to-consumer platforms with VIN-matched fitment databases. Fleet procurement consolidation in the United States is compressing traditional jobber layers.
- Retail Stores:Physical counter locations with same-day inventory availability for emergency replacement.
- Wholesale:Volume pricing tiers for multi-location service center chains and fleet maintenance departments.
- Marketplaces:Third-party platforms aggregating remanufactured and aftermarket inventory with competitive price transparency.
Retail stores retain volume leadership; online channels show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany where integrated emission control manufacturers command premium positioning, while Chinese suppliers compete on volume throughput across standardized muffler and pipe categories. This asymmetry shapes procurement patterns as fleet operators balance compliance assurance against unit economics.
United States
Commercial fleet replacement demand concentrates in California and Texas where EPA roadside enforcement infrastructure has intensified operational compliance requirements. CARB zero-emission mandates and federal tailpipe standards accelerate retirement timelines for non-compliant platforms while preserving replacement urgency for remaining internal combustion fleets. Chicago, Los Angeles, and Houston have emerged as theft-driven catalytic converter replacement hotspots.
Germany
REACH substance restrictions and EU F-Gas Regulation force reformulation of gasket materials and coating chemistries across domestic supply chains. ECHA compliance timelines extend R&D cycles for aftermarket suppliers serving the German and French markets. The Baden-Württemberg industrial corridor hosts specialized ceramic substrate producers and ferritic stainless steel forming operations.
China
Vehicles from the 2010-2015 manufacturing boom have reached end-of-life component failure rates, concentrating exhaust system replacement demand in tier-2 and tier-3 cities. MEE enforcement of emission standards tightens compliance windows for aging commercial fleets. The Yangtze River Delta manufacturing cluster supplies both domestic aftermarket channels and export-oriented remanufacturers.
India
Bharat Stage VI implementation creates first-time emissions compliance infrastructure and aftermarket service network demand beyond metropolitan centers. The country's national automotive regulator has accelerated inspection protocol deployment in tier-2 cities. Maharashtra and Gujarat host emerging fabrication capacity serving both domestic replacement and export markets.
Japan
Hybrid powertrain thermal management requirements sustain specialized demand for exhaust heat recovery components as stop-start cycling intensifies thermal fatigue. METI guidelines on material efficiency influence supplier qualification standards for domestic aftermarket channels. The Nagoya industrial corridor maintains concentration in precision-formed austenitic stainless steel header production.
Automotive Exhaust Components Aftermarket Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the exhaust components aftermarket. Integrated emission control manufacturers with captive substrate production sustain margin advantages in catalytic converter categories, while parts-only assemblers compete on price across mature muffler and pipe segments. Three archetypes dominate: vertically integrated system producers, specialized thermal management fabricators, and regional volume assemblers. Competitive moves concentrate on backward integration into ceramic substrate supply and direct-to-fleet procurement platform development.
Among the integrated system tier, Tenneco Inc. and FORVIA Faurecia exemplify archetypes combining emission control manufacturing with service network penetration. Eberspächer occupies a position within the thermal management specialization vector. Continental AG represents the diversified automotive supplier archetype with exhaust components nested within broader powertrain portfolios. These companies anchor the competitive structure without exhausting the vendor landscape.
| Leading Market Players |
|---|
| Tenneco Inc. |
| FORVIA Faurecia |
| Continental AG |
| Eberspächer |
| FUTABA INDUSTRIAL CO., LTD |
| Bosal |
| Boysen |
| Sejong Industrial Co., Ltd |
| Yutaka Giken Company Limited |
| Others |
Supply Flow & Price Mechanics
Scale economies in ceramic substrate production concentrate pricing power among three specialized cordierite manufacturers, compressing margin pools for secondary market assemblers while elevating cost floors for theft-driven catalytic converter replacement cycles. This concentration forces parts-only suppliers toward carbon steel muffler commoditization as EPA enforcement intensifies fleet procurement of certified emission control devices.
Pricing Analysis
The customization-premium spread separates TIG-welded austenitic stainless steel headers from aluminized carbon steel direct-fit replacements across three distinct pricing tiers. Certification grade differentiation—EPA-compliant substrates versus uncertified alternatives—drives price stratification alongside volume scale discounts for national fleet operators. Pricing pressure stems from platinum group metal volatility compressing remanufacturer margins, with commercial fleet buyers exhibiting highest price sensitivity against enthusiast segments accepting stainless steel premiums for performance applications.
Supply Chain Analysis
China and Germany anchor exhaust component fabrication, with the Yangtze River Delta supplying standardized muffler volumes and Baden-Württemberg hosting specialized ferritic stainless steel forming operations. Raw material dependencies center on Indonesian nickel for high-alloy formulations, South African platinum group metals for catalytic substrates, and Ukrainian ferrochrome for corrosion-resistant grades. Single-source vulnerability concentrates in high-cell-density cordierite supply. Distribution runs through integrated fleet procurement platforms that are compressing traditional jobber layers across North American markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must navigate battery electric vehicle substitution eliminating exhaust system content entirely from new vehicle production, compressing the long-term addressable base while regulatory enforcement preserves near-term replacement urgency for internal combustion fleets.
For Market Incumbents: Compound defensive positioning through backward integration into ceramic substrate supply and captive production of high-cell-density cordierite architectures. Secure EPA certification pipelines ahead of homologation timeline extensions that are delaying competitor market entry. Prioritize direct-to-fleet digital procurement platform development to bypass eroding jobber distribution layers as national operators consolidate supplier relationships. For New Entrants and Emerging Players: EPA fast-track certification for Bharat Stage VI-compliant substrates in India's tier-2 cities offers the most penetrable white-space opportunity. Target thermal management component supply for hybrid powertrain heat recovery systems where stop-start cycling intensifies replacement frequency. Deploy direct-installer platforms with VIN-matched fitment databases to circumvent entrenched distribution incumbents in theft-driven urban replacement markets. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated emission control manufacturers with captive substrate production and fleet service network penetration. Long-term viability concentrates on suppliers with hybrid thermal management expertise that extends relevance beyond pure internal combustion phase-out. Monitor battery electric vehicle penetration thresholds as the critical inflection signal for portfolio reweighting away from acoustic attenuation hardware toward emission control device specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Substrate Backward Integration | Captive cordierite supply secures margin pools against three-producer concentration risk. |
| Direct-to-Fleet Digital Procurement | Bypasses traditional jobber layers as national operators consolidate maintenance platforms. |
| Hybrid Thermal Management Expansion | Extends product relevance through exhaust heat recovery integration with stop-start powertrains. |
| India BS-VI Certification Fast-Track | First-mover positioning in tier-2 city emissions compliance infrastructure deployment. |
| Platinum Group Metal Hedging Programs | Stabilizes inventory valuation against palladium and rhodium price volatility compression. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EPA enforcement databases, vehicle registration records, and platinum group metal exchange data. Primary interviews engaged Tier 1 supplier procurement officers, aftermarket distributor operations heads, commercial fleet maintenance directors, and ceramic substrate manufacturing engineers. Secondary validation drew from EPA roadside inspection reports, California BAR emissions testing records, and customs trade flows for stainless steel exhaust tubing. Bottom-up unit economics triangulated against top-down market sizing across product category and regional clusters.
Segmentation dimensions modeled include product type, material grade, end-user archetype, and sales channel configuration across the projection horizon. Vehicle parc aging curves and regulatory enforcement intensity indices informed replacement demand modeling. CAGRs derived from regression analysis of historical replacement cycles against fleet turnover dynamics and electrification substitution timelines. Hybrid powertrain penetration rates and commercial fleet telematics adoption served as industry-specific forecast inputs.
Underlying assumptions cover EPA enforcement continuity, platinum group metal price band stability, and cordierite supply concentration persistence, with deviation risk concentrated in accelerated battery electric vehicle adoption and unilateral tariff imposition on Chinese stainless steel imports. Recalibration cycles align with material shifts in EPA rulemaking, CARB zero-emission mandate revisions, and Bharat Stage VI enforcement deployment milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Headlight Bulb Market
Automotive Components
North America Automotive Intercooler Market
Automotive Components
Global Automotive Gearbox Market
Automotive Components
South Korea Automotive Pneumatic Actuators Market
Automotive Components
Global Automotive Interior Component Market
Automotive Components
Automotive Active Grille Shutter Actuator Gear Market
Automotive Components
Automotive Skid Plate Market
Automotive Components
France Automotive Market
Automotive Components
Japan Automotive Composites Market
Automotive Components
Automotive Transaxle Market
Automotive Components
Auto Fender Market
Automotive Components
Automotive Brake Tube Market
Automotive Components
Automobile Accessories Market
Automotive Components
Global Automotive Fifth Wheel Coupling Market
Automotive Components
Automotive Steering Column Market
Automotive Components
Europe Automotive Glass Market