
 Automotive Active Grille Shutter Actuator Gear Market | 2026-2036
Automotive Active Grille Shutter Actuator Gear Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Active Grille Shutter Actuator Gear Market Insights
OEM-direct supply contracts for active grille shutter actuator gears is tilting toward vertically integrated tier-1 systems houses with in-house gear production capability. Magna International leverages its full-stack shutter module expertise to capture multi-year platform awards from Detroit and European OEMs. Valeo sustains competitive position through dedicated R&D centers in France and China focused on brushless motor integration. Denso Corporation anchors its share in the Japanese domestic market through captive supply relationships with Toyota and Honda powertrain divisions.
Automotive active grille shutter actuator gears are precision-machined or powder-metal components, typically fabricated from engineered polymers or sintered steel alloys, that translate rotary motor output into linear vane movement across vehicle front-end openings. These gears must maintain dimensional stability across temperature swings from minus forty to one hundred twenty degrees Celsius while resisting corrosion from road salt and chemical exposure. Electric actuator configurations lead the product type landscape due to superior response precision and software controllability, while brushless motor technology is gaining fastest adoption because of its extended duty cycle life and reduced electromagnetic interference. Hydraulic actuator demand remains concentrated in heavy-duty commercial applications where torque requirements exceed electric alternatives.
The EPA's Corporate Average Fuel Economy standards and the EU Green Deal's fleet CO2 targets directly mandate active aerodynamic technologies that reduce highway drag coefficients. NHTSA safety regulations intersect with these efficiency rules by requiring reliable fail-safe positioning that prevents engine overheating during actuator malfunction. China's MIIT administers parallel new energy vehicle efficiency standards that incorporate active grille shutters into whole-vehicle energy consumption ratings. Stakeholders must monitor how battery electric vehicle platform architectures eliminate traditional engine cooling needs while introducing thermal management requirements for battery packs and electric motors.
Market Dynamics
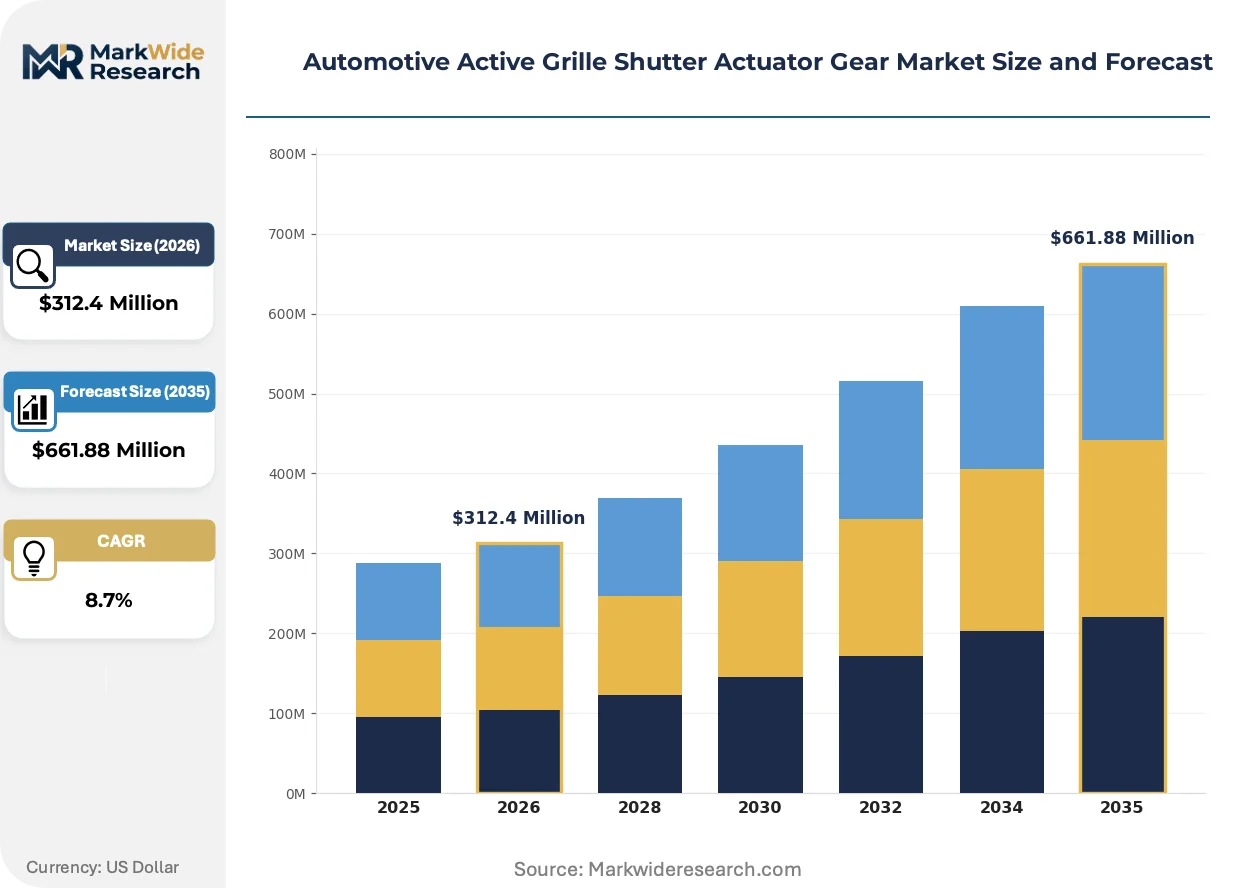
The Automotive Active Grille Shutter Actuator Gear Market is being fundamentally restructured by the migration from brushed to brushless motor architectures, which demands tighter gear tolerances and new thermal management protocols across supplier tiers.
Growth Catalysts
- EU F-Gas Regulation:Stringent fluorinated gas restrictions compel OEMs to prioritize electric actuation over pneumatic alternatives, directly expanding precision gear demand for thermal management systems.
- MIIT efficiency mandates:China's whole-vehicle energy consumption ratings now incorporate active aerodynamics, accelerating platform-level adoption across domestic and joint-venture vehicle programs.
- Powder metallurgy advances:Sintered steel alloy processing improvements enable complex helical gear geometries at production scales previously restricted to machined components.
Market Restraints
- Neodymium price volatility:Rare-earth magnet cost swings for brushless motors compress tier-2 gear supplier margins and destabilize long-term contract pricing.
- Supplier concentration in Aichi Prefecture:Japanese domestic captive supply relationships limit market access for independent gear specialists seeking platform awards with Toyota and Honda.
- Temperature cycling durability:Engineered polymer gears face premature fatigue failure in markets with extreme diurnal temperature swings exceeding eighty degrees Celsius.
Strategic Opportunities
- Battery electric vehicle thermal management:Front-end cooling requirements for battery packs and electric motors create new vane actuation applications independent of traditional engine cooling.
- India's PLI scheme for automotive components:Production-linked incentives attract gear manufacturing investment to serve emerging domestic OEM assembly corridors.
- Brushless motor-integrated controller convergence:Smart actuator modules combining position sensing, motor control, and gear reduction into single housings command premium positioning.
Industry Challenges
- Multi-physics simulation expertise:Gear suppliers lack sufficient thermal-mechanical coupled analysis capability to validate designs across the full automotive temperature envelope.
- ISO 26262 functional safety certification:Fail-safe positioning requirements for engine overheating protection extend development timelines and testing expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Active Grille Shutter Actuator Gear Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Actuator, Hydraulic Actuator, Pneumatic Actuator, Manual Actuator Technology: Stepper Motor, DC Motor, Brushless Motor, Linear Actuator End User: OEM Suppliers, Tier-1 Providers, Vehicle Assemblers, Aftermarket Distributors Application: Fuel Efficiency Enhancement, Aerodynamic Control, Engine Cooling Management, Emission Reduction |
| Companies Covered | Magna International, Valeo, Röchling Automotive, SRG Global, Shape Corporation, HBPO, Techniplas, Denso Corporation, Aisin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Active Grille Shutter Actuator Gear Market Trends and Innovations
Digital integration across actuator systems is compressing development cycles and enabling predictive maintenance models that were previously impractical for mechanical components. Three converging developments are restructuring competitive requirements.
Brushless DC motor technology is digitizing actuator control architectures by replacing mechanical commutation with electronic switching, enabling software-defined vane positioning algorithms. Passenger vehicle OEMs in Germany and Japan are specifying these configurations for next-generation platform awards. The shift is digitizing supply chain relationships as gear suppliers must now integrate with motor-controller firmware development cycles.
The EPA's Corporate Average Fuel Economy standards and parallel EU Green Deal fleet CO2 targets mandate active aerodynamic deployment across light-duty vehicle segments. These frameworks compress design-to-production timelines by requiring upfront validation of drag reduction claims. Heavy-duty commercial applications face the steepest compliance cost escalation, driving hydraulic-to-electric conversion programs.
Fleet procurement departments are consolidating supplier relationships around full-stack module providers capable of warranting complete shutter-actuator-gear subsystems. Tier-1 systems houses with in-house gear production capability are displacing independent component specialists in platform sourcing decisions. This concentration is most visible in Detroit and Stuttgart, where multi-year single-source contracts now dominate award structures.
Automotive Active Grille Shutter Actuator Gear Market Segmentation
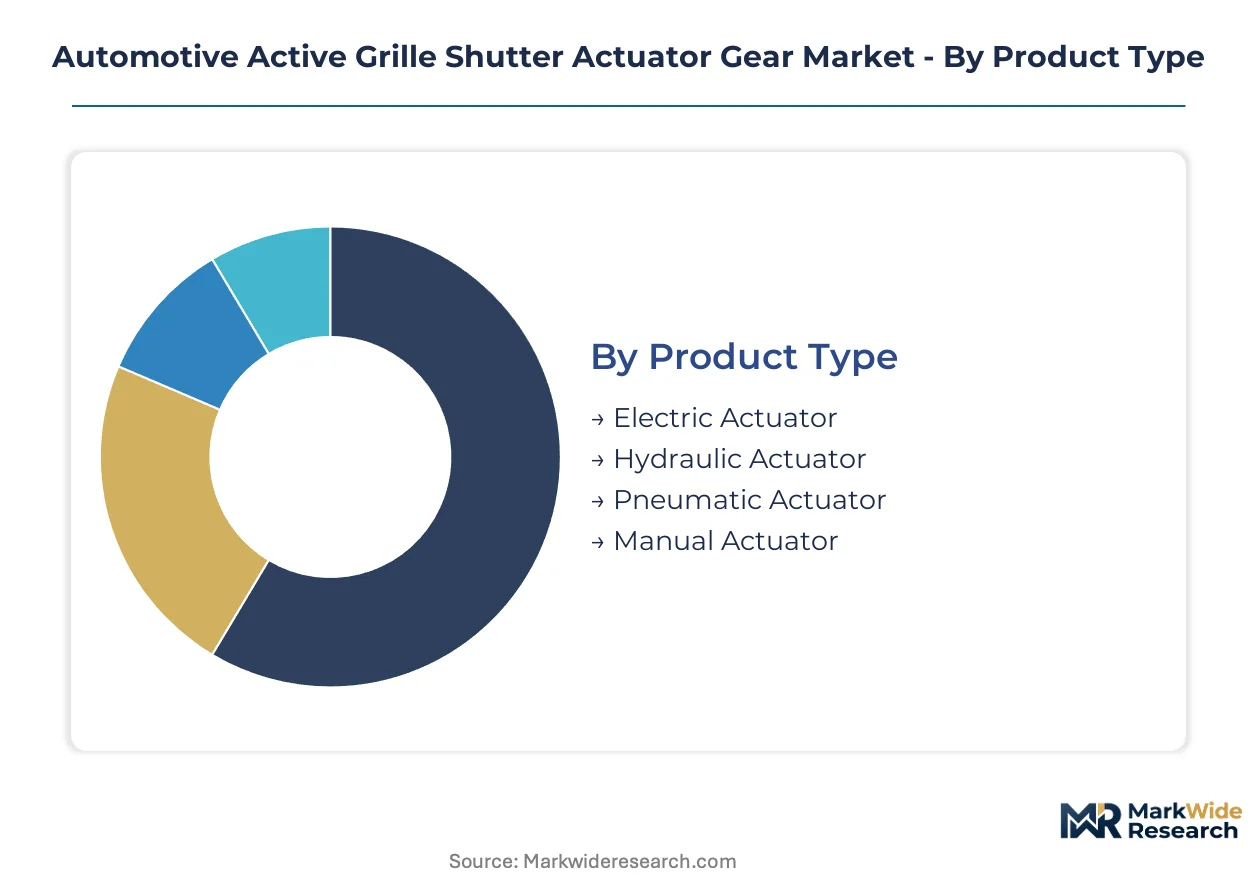
Active grille shutter actuator gears serve divergent thermal management architectures across vehicle platforms, with motor technology and supply chain position dictating specification requirements. Segmentation reveals how precision gear demand fragments across electric, hydraulic, and legacy pneumatic actuation systems.
Product Type:
Actuator configurations span from software-controllable electric systems to mechanical manual alternatives, each imposing distinct gear precision and material specifications.
- Electric Actuator:Brushless and brushed DC motor architectures demand helical or spur gears with tight backlash tolerances to enable millimeter-scale vane positioning accuracy. Passenger vehicle OEMs in Germany and Japan specify these for next-generation platform awards where EPA Corporate Average Fuel Economy compliance requires precise aerodynamic control.
- Hydraulic Actuator:High-torque fluid-power systems utilize hardened steel rack-and-pinion or worm gear configurations to overcome pneumatic force limitations in heavy-duty commercial applications. Demand concentrates in North American long-haul truck programs where cooling loads exceed electric motor torque density.
- Pneumatic Actuator:Compressed-air systems with polymer composite gears persist in cost-sensitive emerging market vehicle programs where electronic control sophistication remains limited.
- Manual Actuator:Cable-driven mechanical gears serve aftermarket replacement and budget vehicle segments requiring minimal electronic integration.
The dominant share belongs to Electric Actuator, while Hydraulic Actuator is closing the gap fastest in commercial vehicle electrification programs.
Technology:
Motor technology selection determines gear loading profiles, thermal envelopes, and controller integration complexity across supplier tiers.
- Brushless Motor:Electronically commutated architectures with rare-earth rotor magnets generate minimal electrical noise and sustain extended duty cycles, demanding gears with superior fatigue resistance under cyclic thermal stress. Tier-1 suppliers in Aichi Prefecture and Stuttgart prioritize these configurations for premium platform sourcing.
- DC Motor:Brushed commutator designs with simpler controller requirements utilize standard powder-metal gears, serving mid-market vehicle programs where cost positioning outweighs efficiency optimization.
- Stepper Motor:Discrete-position control suits basic open-close shutter functions without continuous modulation capability.
- Linear Actuator:Direct screw-drive mechanisms eliminate rotary-to-linear gear conversion in specialized battery electric vehicle thermal management applications.
Brushless Motor commands the technology mix, with DC Motor retaining volume in emerging market cost-optimized platforms.
End User:
Supply chain position dictates gear specification authority, with captive tier-1 relationships limiting independent component supplier market access.
- Tier-1 Providers:Full-stack shutter module manufacturers with in-house gear production capability—Magna International, Valeo, Denso Corporation—warrant complete actuator-gear subsystems and capture multi-year single-source platform awards from Detroit and European OEMs.
- OEM Suppliers:Captive powertrain divisions at Toyota and Honda maintain vertical control over gear sourcing through dedicated supplier development programs in Japan.
- Vehicle Assemblers:Direct procurement from gear specialists occurs in low-volume specialty vehicle programs with unique packaging constraints.
- Aftermarket Distributors:Independent service channels source replacement gears for collision repair and wear-item replacement outside warranty periods.
Tier-1 Providers hold structural advantage in platform sourcing decisions, while Aftermarket Distributors face margin compression from consolidated OEM service networks.
Application:
Functional deployment of active grille shutters spans efficiency optimization, thermal protection, and emissions compliance with varying gear durability requirements.
- Fuel Efficiency Enhancement:Highway drag reduction through adaptive vane closure demands rapid-response gear trains capable of position transitions within seconds of speed changes. EU Green Deal fleet CO2 targets mandate these systems across light-duty segments, with Germany and France leading enforcement stringency.
- Engine Cooling Management:Fail-safe gear positioning prevents thermal damage during actuator malfunction, requiring mechanical redundancy or spring-return mechanisms that satisfy NHTSA safety regulations.
- Aerodynamic Control:Fine-grained vane angle modulation for stability management imposes precision gear tolerances previously restricted to aerospace applications.
- Emission Reduction:Cold-start thermal management accelerates catalyst light-off through controlled airflow restriction, supporting EPA Tier 3 and Euro 7 compliance timelines.
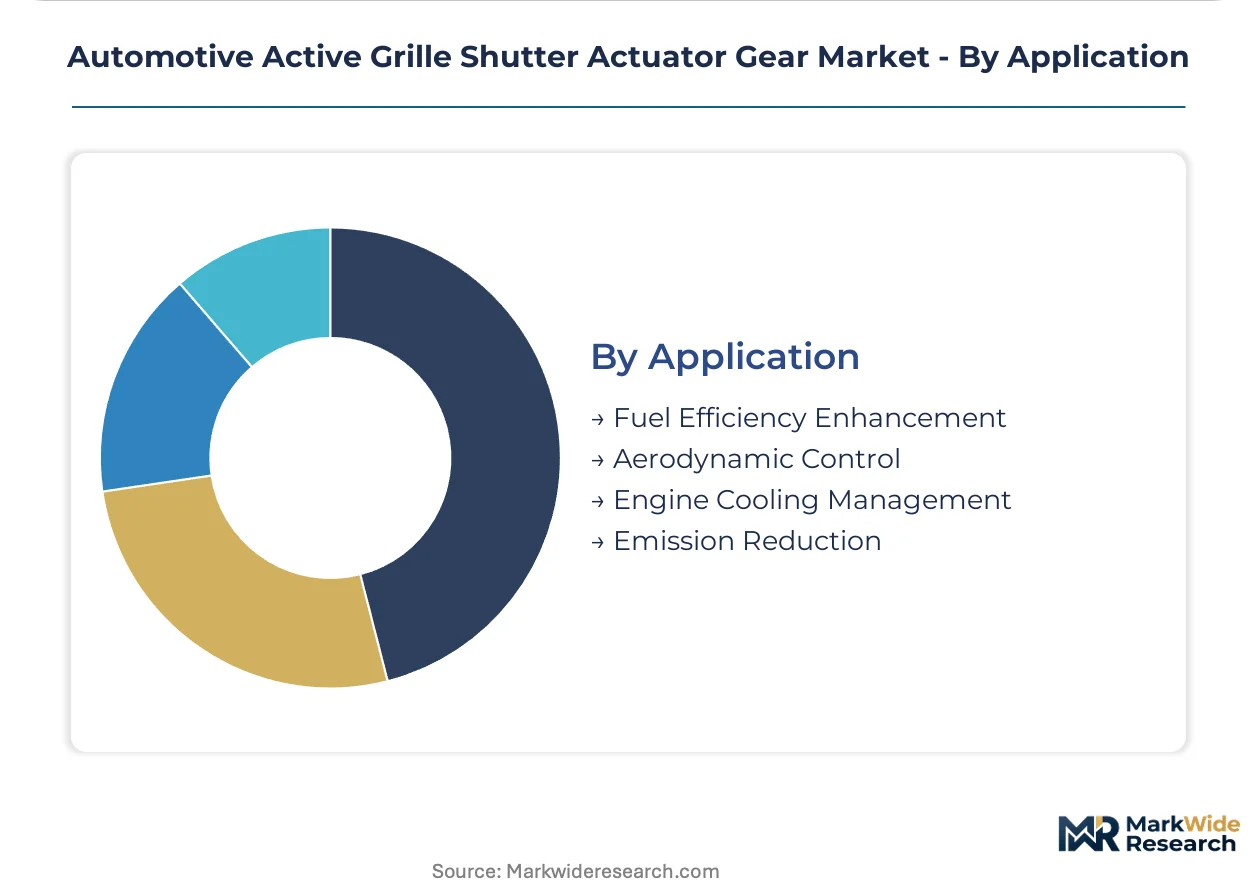
Fuel Efficiency Enhancement drives volume deployment, while Engine Cooling Management is gaining specification weight fastest under tightening functional safety standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's automotive logistics infrastructure anchors European supply chain flows for precision gear components, while the Trans-Siberian rail corridor links Asian manufacturing clusters to continental assembly plants.
Germany
Stuttgart's OEM engineering centers drive specification authority for brushless motor-integrated gear modules. The EU F-Gas Regulation mandates electric actuation systems across thermal management platforms. Supplier concentration in Baden-Württemberg and Bavaria captures multi-year platform awards from domestic premium vehicle manufacturers.
Japan
Aichi Prefecture's captive tier-1 networks limit independent gear specialist access to Toyota and Honda powertrain divisions. METI efficiency standards accelerate active aerodynamics adoption across domestic vehicle programs. Nagoya-based manufacturing corridors concentrate precision machining capacity for helical gear geometries.
United States
Detroit's platform sourcing decisions favor full-stack shutter module providers with in-house gear production. EPA Corporate Average Fuel Economy standards mandate drag reduction technologies across light-duty segments. Michigan and Ohio assembly corridors anchor tier-1 supplier investment in electric actuator manufacturing.
China
MIIT whole-vehicle energy consumption ratings incorporate active grille shutters into new energy vehicle efficiency calculations. The Yangtze River Delta manufacturing belt concentrates domestic gear fabrication capacity for joint-venture OEM programs. Shanghai and Jiangsu province clusters serve expanding electric vehicle platform volumes.
India
PLI scheme production-linked incentives attract gear manufacturing investment to emerging domestic OEM assembly corridors. BIS automotive component standards align with international thermal management specifications. Tamil Nadu and Maharashtra industrial corridors develop supplier ecosystems for passenger vehicle electrification programs.
Automotive Active Grille Shutter Actuator Gear Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying precision-machined or powder-metal gear geometries to module assemblers. The market structure tilts toward consolidated tier-1 relationships with captive gear production capability displacing independent component sourcing. Two strategic archetypes dominate: full-stack shutter module manufacturers warranting complete actuator-gear subsystems, and specialized gear fabricators serving aftermarket replacement channels. Competitive moves concentrate on backward integration into motor-controller firmware development and geographic expansion toward emerging OEM assembly corridors.
Among North American platform integrators, Magna International and Shape Corporation exemplify the full-stack archetype with system-level sourcing authority. Valeo anchors European competitive positioning through dedicated R&D infrastructure. Denso Corporation represents Japanese captive supply relationships that limit independent specialist market access. These three entities collectively illustrate how geographic clustering around major vehicle assembly corridors determines platform award distribution.
| Leading Market Players |
|---|
| Magna International |
| Valeo |
| Röchling Automotive |
| SRG Global |
| Shape Corporation |
| HBPO |
| Techniplas |
| Denso Corporation |
| Aisin Corporation |
| Others |
Pricing and Supply Chain Analysis
Neodymium price volatility in rare-earth magnet supply chains compresses tier-2 gear supplier margins and simultaneously widens pricing tier spreads between brushless motor-integrated modules and commodity electric actuator configurations. This input-cost instability forces procurement departments to renegotiate contract structures annually, reshaping supplier relationships toward captive sourcing arrangements that internalize magnet price risk.
Pricing Analysis
Volume-discount tiering structures separate multi-year platform awards from spot procurement, with premium brushless motor-integrated modules commanding position-based premiums over standard DC motor configurations. Price differentiation hinges on ISO 26262 functional safety certification grade and backward integration depth into motor-controller firmware development. Cost compression in the mid-market tier is intensifying because powder metallurgy advances reduce helical gear production costs. Fleet procurement departments at volume OEMs exhibit highest price sensitivity, while premium vehicle manufacturers prioritize fail-safe positioning reliability over unit cost.
Supply Chain Analysis
Extended payment terms from Detroit and Stuttgart OEMs force tier-2 gear fabricators to utilize supply-chain finance facilities anchored by tier-1 systems houses. Manufacturing concentrates in Germany, Japan, and the Yangtze River Delta corridor, with sintered steel alloy feedstock drawing from Austrian and Chinese powder metallurgy specialists. Single-source vulnerability persists in rare-earth magnet supply from Chinese processing facilities. Distribution runs through tier-1 module assemblers who warrant complete shutter-actuator-gear subsystems to vehicle assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from cyclical compression in internal combustion platform volumes, with battery electric vehicle thermal management requirements now driving replacement demand for front-end actuation systems.
For Market Incumbents: Pre-empt displacement by captive tier-1 gear production through exclusive multi-year platform awards with emerging Chinese OEMs expanding electric vehicle output. Secure neodymium supply agreements with Australian and Canadian rare-earth processors to insulate margin structures from Chinese export restriction volatility. Deepen backward integration into brushless motor controller firmware development to capture smart actuator module premiums.
For New Entrants and Emerging Players: India's underpenetrated supplier ecosystem for precision-machined helical gears offers white-space access through PLI scheme manufacturing incentives. Target aftermarket replacement channels for collision repair gears where consolidated OEM service networks have not yet captured full coverage. Pursue joint development programs with domestic Indian OEMs launching passenger vehicle electrification platforms as the most penetrable entry vector.
For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors tier-2 gear specialists with powder metallurgy expertise and ISO 26262 certification infrastructure. Long-term viability hinges on positioning for battery electric vehicle thermal management applications independent of traditional engine cooling demand. Monitor MIIT enforcement stringency on whole-vehicle energy consumption ratings as the inflection signal for platform-level adoption acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Brushless Motor-Integrated Module Development | Captures premium positioning through software-defined vane control algorithms specified by German OEMs. |
| Powder Metallurgy Capacity Expansion | Enables complex helical gear geometries at production scales previously restricted to machined components. |
| ISO 26262 Functional Safety Certification | Satisfies NHTSA fail-safe requirements for engine overheating protection in platform sourcing decisions. |
| Geographic Manufacturing Footprint in India | Accesses PLI scheme incentives serving emerging domestic OEM assembly corridors in Tamil Nadu. |
| Rare-Earth Magnet Supply Agreement | Insulates margin structures from neodymium price volatility through Australian and Canadian sourcing. |
Research Methodology
Cross-validation between OEM platform engineering documentation and tier-1 supplier production schedules anchors the qualitative findings on specification timelines and award volumes. Primary interviews with Tier 1 supplier procurement managers, OEM thermal system architects, aftermarket distribution channel heads, and powder metallurgy plant engineers combined with secondary validation from vehicle production databases, IHS Markit registration data, MIIT efficiency disclosure filings, and SEC 10-K supplier segment reporting. Bottom-up gear unit demand modeling triangulates against top-down thermal management system value projections.
Calibration against historical platform award cycles and announced OEM electrification roadmaps shapes the analytical framework across the projection horizon. Segmentation dimensions include actuator configuration, motor technology, supply chain position, vehicle propulsion architecture, and regional production cluster. CAGRs derive from gear content-per-vehicle trajectories mapped to vehicle assembly volume forecasts, with brushless motor adoption curves and battery electric vehicle platform ramp schedules as critical automotive-specific inputs.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by Chinese domestic tier-1 suppliers would shift outcomes toward consolidated captive sourcing. Macroeconomic deviation in automotive production volumes, regulatory acceleration in EU F-Gas enforcement, or technological disruption in solid-state battery thermal management would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Hardware Market
Automotive Components
North America Automotive Intercooler Market
Automotive Components
France Automotive Market
Automotive Components
Europe Automotive Bearing Market
Automotive Components
Global Automotive Components Forging Market
Automotive Components
Automotive Aftermarket for Brake Components Market
Automotive Components
India Automotive Sunroof Market
Automotive Components
Argentina Automotive Composites Market
Automotive Components
Europe Automotive Glass Market
Automotive Components
Asia Pacific Automotive Bearing Market
Automotive Components
Global Automotive Window Regulator Market
Automotive Components
Global Automotive Fifth Wheel Coupling Market
Automotive Components
Automotive Pedals Market
Automotive Components
Brake Cooling Duct and Hose Market
Automotive Components
Global Automotive Interior Plastic Components Market
Automotive Components
Automotive Brake Pads Market