
 Auto Fender Market | 2026-2036
Auto Fender Market Size, Share, and Industry Trends Forecast 2026-2036
Auto Fender Market Insights
Crash-grade dent resistance is unwinding legacy commodity pricing in auto fenders. Magna International leverages its North American stamping footprint to supply structural aluminum closures for light-truck programs. Thyssenkrupp anchors European OEM relationships through precision hot-forming capabilities that reduce panel thickness without sacrificing impact performance. Plastic Omnium competes in the plastic fender segment with injection-molded solutions that integrate sensor housings for advanced driver-assistance systems.
An auto fender is a stamped or molded body panel that spans the wheel well, typically fabricated from cold-rolled steel, 5000- or 6000-series aluminum, or reinforced thermoplastic olefin, and engineered to absorb minor collision energy while protecting wheel-assembly components from road debris. Front fender demand leads volume due to higher damage frequency and integrated headlamp mounting complexity, while aluminum material adoption grows fastest as OEMs pursue mass reduction targets for battery-electric architectures. Carbon fiber occupies a narrow premium tier serving low-volume performance coupes where tooling amortization tolerates higher per-unit costs.
NHTSA Federal Motor Vehicle Safety Standards govern fender intrusion resistance and pedestrian impact geometry in the United States, while ECE R42 and EU pedestrian-protection directives shape European panel design and material selection. China's GB standards on vehicle exterior projections and SAMR quality-certification requirements influence supplier qualification timelines for domestic OEM programs. Stakeholders must monitor how evolving crash-test protocols and material-carbon-accounting rules will reshape capital allocation between steel, aluminum, and polymer fender platforms.
Market Dynamics
Crash-grade dent resistance standards are unwinding legacy commodity pricing in auto fenders, forcing material upgrades from cold-rolled steel toward aluminum and polymer composites across OEM stamping programs.
Growth Catalysts
- EU REACH compliance on material recyclability:European regulators are redirecting supplier capital toward aluminum and polymer composite stamping operations, accelerating replacement of legacy steel tooling.
- Electric vehicle platform procurement:OEMs are compressing fender replacement cycles through modular battery-electric architectures that demand lighter closure panels.
- China's localized stamping expansion:Domestic automakers are scaling SUV and crossover portfolios with captive stamping operations, concentrating demand in Shanghai and Guangzhou manufacturing clusters.
Market Restraints
- Aluminum price volatility:Input cost swings for 5000- and 6000-series aluminum sheet are compressing margins for stampers locked into fixed-price OEM contracts.
- Hot-forming equipment concentration:Precision press capacity for high-strength aluminum remains concentrated among German and Austrian tooling suppliers, creating single-source risk.
- Steel substitution ceiling:Cold-rolled steel retains cost advantage in economy vehicle segments below battery-electric price thresholds, slowing material transition in mass-market platforms.
Strategic Opportunities
- Sensor-integrated polymer fenders:Injection-molded solutions that embed radar and lidar housings for advanced driver-assistance systems are opening white space in premium crossover segments.
- India's PLI scheme for auto components:Production-linked incentives are attracting stamping joint ventures to serve Maruti Suzuki and Tata Motors expansion programs.
- Carbon accounting alignment:EU Green Deal material-passport requirements are creating first-mover advantage for suppliers with verified low-carbon aluminum supply chains.
Industry Challenges
- Hot-forming technician scarcity:Precision aluminum stamping requires specialized die maintenance and thermal process control skills that outpace vocational training output in North American manufacturing regions.
- Multi-material joining certification:OEM weld-bond specifications for steel-aluminum hybrid closures are extending supplier qualification timelines by 8-14 months.
- Legacy ERP integration:Tier-2 stampers face data architecture friction when connecting real-time thickness gauging systems to OEM production-scheduling platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Auto Fender Market |
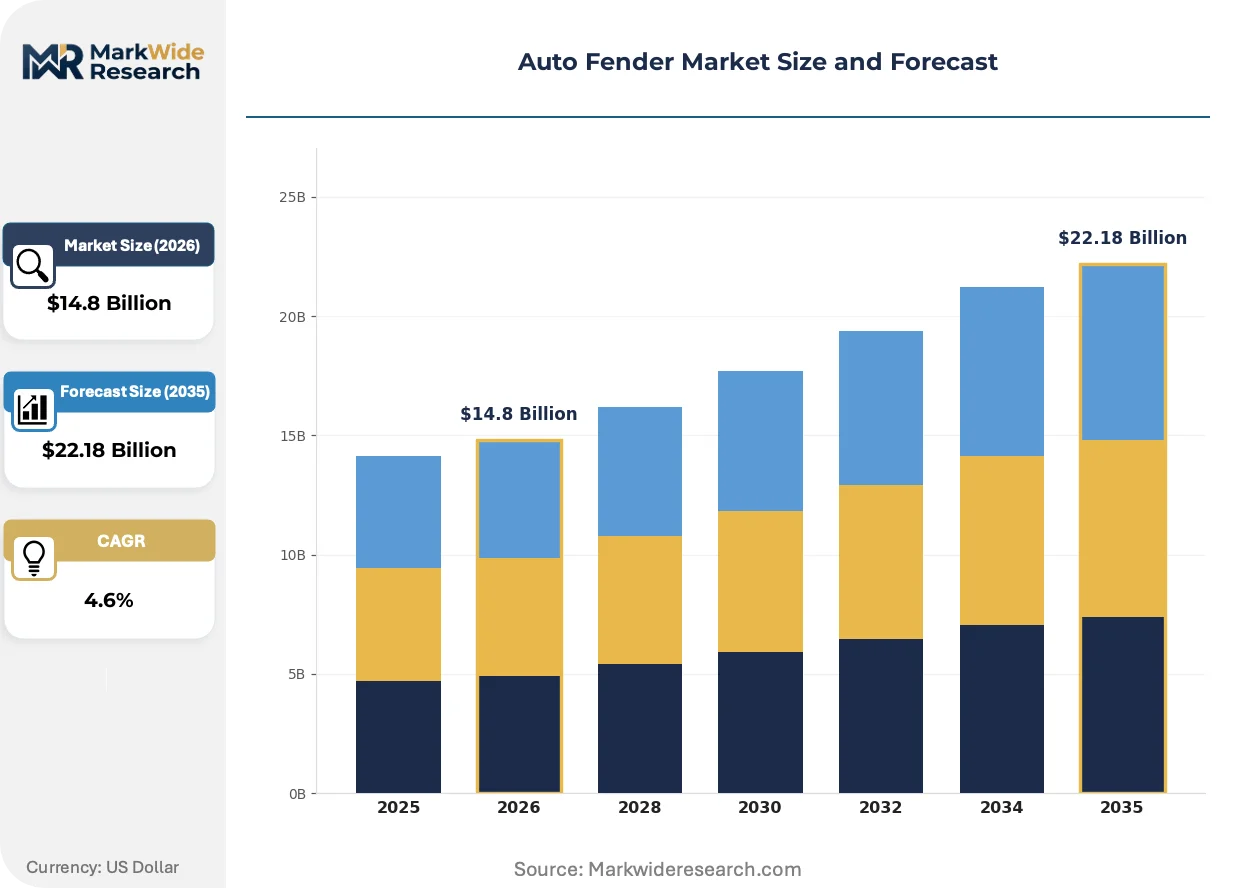
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Front Fender, Rear Fender, Wheel Arch, Quarter Panel Material: Steel, Aluminum, Plastic, Carbon Fiber Vehicle Type: SUV, Sedan, Pickup, Coupe Installation Type: OEM, Aftermarket, Replacement, Custom |
| Companies Covered | Plastic Omnium, Magna International, Sungwoo Hitech, Thyssenkrupp, Futaba Industrial, Faurecia, Flex-N-Gate Corporation, Tata AutoComp Systems, Hitachi Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Auto Fender Market Trends and Innovations
Material science advances and regulatory carbon-accounting mandates are actively restructuring supplier competitiveness, compressing the window for legacy steel-dominant operations to pivot toward aluminum and composite platforms.
Hot-stamped aluminum-silicon coated sheet is decomposing traditional cold-rolled steel's lock on structural fender applications. Battery-electric vehicle programs at Ford and Volkswagen are adopting these panels for front closure assemblies. The technology is decomposing commodity pricing structures by forcing dedicated press investments that smaller stampers cannot amortize.
Europe's ECE R42 pedestrian-impact directive is tightening intrusion-resistance testing protocols for front fender geometry. OEM engineering teams are redesigning panel curvature and material thickness to absorb leg-impact energy without sacrificial deformation zones. The regulation is accelerating aluminum adoption in European C-segment and D-segment vehicle platforms while delaying new steel-intensive model approvals.
Fleet procurement departments are consolidating supplier panels through platform-commonality mandates that span multiple nameplates. General Motors and Stellantis are reducing unique fender SKUs by 40 percent through shared stamping dies across SUV lines. This concentration is most visible in North American light-truck programs where annual volumes justify dedicated aluminum press lines.
Auto Fender Market Segmentation
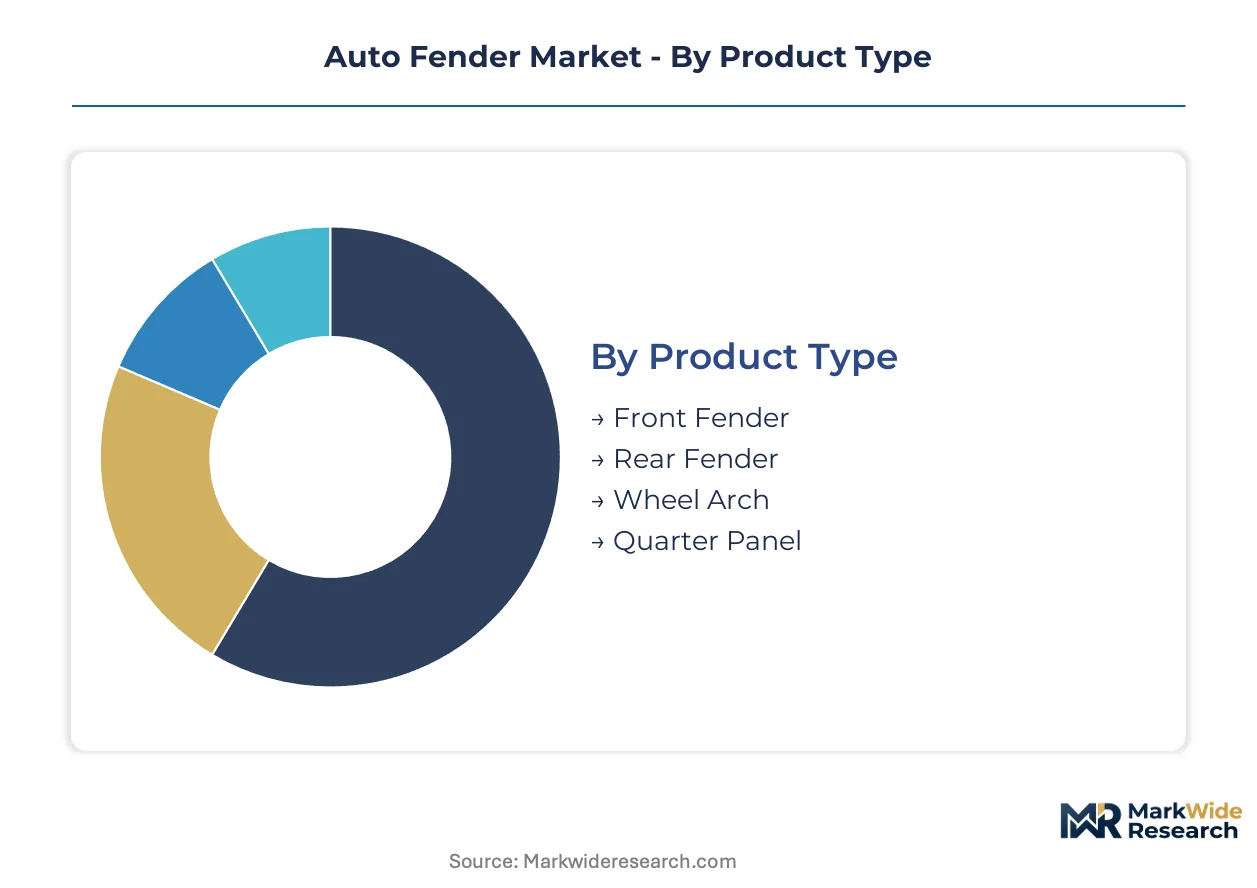
Auto fender segmentation reveals how material substitution pressures and platform electrification are fragmenting procurement strategies across OEM stamping programs. Understanding these divisions exposes where supplier margins compress and where technology premiums command pricing power.
Product Type:
Front fenders face the most intense substitution threat from aluminum and polymer composites as crash-grade dent resistance standards escalate replacement frequency.
- Front Fender:Cold-rolled steel and aluminum-silicon coated sheet dominate structural assemblies that integrate headlamp mounting brackets and pedestrian-impact energy absorption zones. Battery-electric platforms at Ford and Volkswagen are accelerating aluminum adoption here to offset battery mass.
- Rear Fender:These panels experience lower damage frequency but higher styling complexity for coupe and SUV silhouettes. Stamping operations in China's Guangzhou cluster concentrate rear fender volume for domestic crossover portfolios.
- Wheel Arch:Thermoplastic olefin solutions from Plastic Omnium compete in this segment through injection-molded durability against gravel spray.
- Quarter Panel:Structural integration with roof pillars and door apertures restricts material flexibility to high-strength steel and aluminum.
Front fenders retain volume leadership; aluminum-intensive front fender variants hold the steepest expansion curve.
Material:
Cost tier stratification determines competitive intensity, with premium materials commanding dedicated press investments that smaller stampers cannot amortize.
- Steel:Cold-rolled and high-strength low-alloy grades persist in economy vehicle segments below battery-electric price thresholds. Thyssenkrupp's precision hot-forming capabilities reduce panel thickness without sacrificing impact performance.
- Aluminum:5000- and 6000-series sheet is displacing steel in structural closures as OEMs pursue mass reduction targets. Magna International leverages its North American stamping footprint to supply aluminum closures for light-truck programs.
- Plastic:Reinforced thermoplastic olefin integrates sensor housings for advanced driver-assistance systems in premium crossovers.
- Carbon Fiber:Narrow premium tier serves low-volume performance coupes where tooling amortization tolerates higher per-unit costs.
Steel retains absolute volume leadership; aluminum holds the steepest expansion curve.
Vehicle Type:
Application-specific durability requirements and styling complexity create divergent material specifications across platform architectures.
- SUV:Higher ride heights and wider wheel arches demand enhanced dent resistance, favoring aluminum and high-strength steel combinations. China's domestic automakers are scaling SUV portfolios with localized stamping operations in Shanghai.
- Sedan:Lower beltlines and integrated aerodynamic profiles prioritize weight reduction through aluminum front closures.
- Pickup:Fleet procurement consolidation through platform-commonality mandates spans multiple nameplates, concentrating volume in North American light-truck programs.
- Coupe:Premium styling tolerates carbon fiber and aluminum premiums for low-volume production.
SUVs retain volume leadership; electric pickup variants hold the steepest expansion curve.
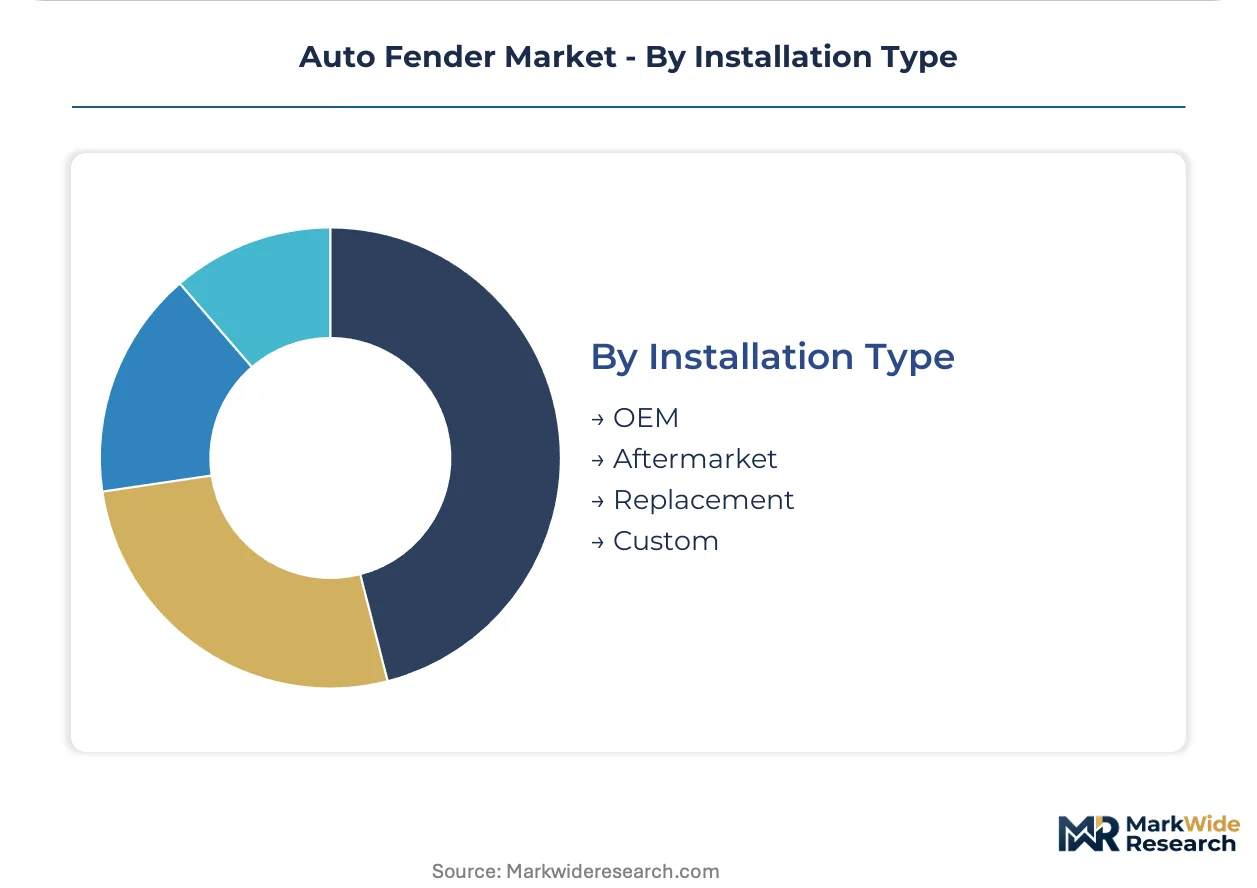
Installation Type:
Customer type fragmentation separates captive OEM supply from independent aftermarket channels with divergent certification requirements.
- OEM:Original equipment procurement demands weld-bond specifications for steel-aluminum hybrid closures, extending supplier qualification timelines. NHTSA Federal Motor Vehicle Safety Standards govern intrusion resistance and pedestrian impact geometry.
- Aftermarket:Independent distributors source certified replacement panels through secondary stamping networks.
- Replacement:Insurance-driven demand concentrates in collision repair networks with standardized fitment requirements.
- Custom:Specialty fabricators serve restoration and performance modification segments with limited volume scale.
OEM channels retain volume leadership; sensor-integrated replacement panels hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German aluminum sheet exports supply stamping operations across Czech and Hungarian assembly plants serving Volkswagen Group battery-electric platforms. This trade corridor reflects broader European supply chain reconfiguration as REACH compliance redirects procurement toward recyclable closure materials.
United States
Ford and General Motors are consolidating light-truck fender programs through platform-commonality mandates spanning multiple SUV nameplates. NHTSA Federal Motor Vehicle Safety Standards govern intrusion resistance and pedestrian impact geometry for all structural closures. Detroit-area stamping clusters concentrate aluminum press investments to serve electric pickup architectures at scale.
China
Domestic automakers BYD and Geely are expanding SUV and crossover portfolios with localized stamping operations. SAMR quality-certification requirements and GB standards on vehicle exterior projections shape supplier qualification timelines. Shanghai and Guangzhou manufacturing clusters host captive stamping facilities serving battery-electric platform demand.
Germany
Thyssenkrupp anchors European OEM relationships through precision hot-forming capabilities for high-strength aluminum closures. EU REACH compliance on material recyclability redirects supplier capital toward aluminum and polymer composite operations. Bavarian and North Rhine-Westphalia tooling corridors concentrate press capacity for structural fender applications.
India
Maruti Suzuki and Tata Motors expansion programs are attracting stamping joint ventures under the PLI scheme for auto components. BIS certification requirements govern material specifications for domestic OEM supply. Tamil Nadu and Gujarat manufacturing belts concentrate new press installations serving compact SUV platform demand.
Japan
Futaba Industrial and Hitachi Chemical operations supply precision-stamped closures for Toyota and Honda hybrid architectures. METI industrial policy supports lightweight material adoption through technology licensing frameworks. Kanto and Chubu regional clusters maintain die engineering expertise for complex curvature fender geometries.
Auto Fender Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity tiers, creating a bifurcated structure where scale-driven stampers amortize dedicated aluminum press lines while regional fabricators serve aftermarket replacement demand. The vendor base stratifies into three archetypes: integrated Tier-1 suppliers with captive OEM relationships, mid-scale specialists focused on hot-forming capabilities, and regional stampers serving secondary distribution channels. Dominant competitive moves include capacity expansion in aluminum press infrastructure and strategic partnerships for sensor-integrated polymer tooling.
Within the integrated Tier-1 tier, Magna International and Thyssenkrupp exemplify scale-driven positioning through North American and European stamping footprints respectively. Plastic Omnium occupies a distinct specialization vector in polymer composite solutions. Sungwoo Hitech represents the Asia-Pacific fabrication archetype with Korean corporate structure. These three anchors demonstrate how geographic origin and organizational form correlate with strategic positioning across material platforms.
| Leading Market Players |
|---|
| Plastic Omnium |
| Magna International |
| Sungwoo Hitech |
| Thyssenkrupp |
| Futaba Industrial |
| Faurecia |
| Flex-N-Gate Corporation |
| Tata AutoComp Systems |
| Hitachi Chemical |
| Others |
Pricing and Supply Chain Analysis
Long-term fixed-price contracts with take-or-pay clauses lock in aluminum sheet access for North American stampers while exposing them to margin compression when LME prices spike. This structure concentrates pricing power among German and Austrian tooling suppliers who control precision hot-forming capacity for crash-grade fender applications.
Pricing Analysis
Steel-to-aluminum technology-generation pricing gaps are widening as battery-electric platforms demand lighter closure panels. Three-tier pricing structure across premium aluminum, standard high-strength steel, and economy cold-rolled grades reflects certification complexity for ECE R42 pedestrian-impact compliance. Price differentiation hinges on hot-forming equipment access and OEM weld-bond qualification status. Margins are tightening in steel-intensive tiers as Chinese domestic automakers localize stamping operations and compress procurement premiums.
Supply Chain Analysis
Inventory buffers for 5000-series aluminum sheet have compressed to six-week lead times at Shanghai and Guangzhou manufacturing clusters, exposing just-in-time stamping operations to LME volatility. German and Austrian press manufacturers anchor supply for high-strength aluminum forming equipment, while Chinese domestic automakers draw from localized coil processing. Single-source vulnerability concentrates in precision hot-forming die engineering. Distribution runs through captive OEM supply chains and independent aftermarket distributors serving collision repair networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Auto fender procurement is a substitution defense where aluminum and polymer composite platforms threaten legacy steel-dominant stampers. Incumbents must navigate compressed replacement cycles driven by modular battery-electric architectures.
For Market Incumbents: Compound aluminum press capacity in Detroit-area and Bavarian manufacturing corridors to amortize dedicated equipment investments across multi-nameplate programs. Deepen backward integration into 6000-series aluminum coil supply through long-term offtake agreements with German sheet exporters. This defends against margin erosion from spot-market price volatility and single-source tooling risk. For New Entrants and Emerging Players: Lead with sensor-integrated polymer fender solutions for premium crossover segments where injection-molded radar housings command technology premiums. India's PLI scheme for auto components offers the most penetrable geography for stamping joint ventures serving Maruti Suzuki and Tata Motors expansion. Target aftermarket replacement channels with certified aluminum panels that bypass OEM weld-bond qualification timelines. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale hot-forming specialists with verified low-carbon aluminum supply chains and existing European OEM relationships. Long-term viability hinges on positioning ahead of EU Green Deal material-passport requirements that will disqualify high-carbon steel stampers. Watch for NHTSA pedestrian-impact rulemaking revisions as the inflection signal for accelerated aluminum adoption in US light-truck programs.| Strategic Initiative | Industry Significance |
|---|---|
| Aluminum Press Capacity Expansion | Amortizes dedicated equipment across Ford and Volkswagen battery-electric platform volumes. |
| Hot-Forming Equipment Partnership | Secures precision press access from German and Austrian tooling suppliers for ECE R42 compliance. |
| Sensor-Integrated Polymer Development | Captures ADAS integration premiums in Plastic Omnium's injection-molded fender segment. |
| Low-Carbon Aluminum Supply Agreement | Aligns with EU REACH compliance and Green Deal material-passport requirements. |
| India PLI Joint Venture | Positions for Maruti Suzuki and Tata Motors compact SUV stamping demand in Tamil Nadu. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and hot-forming equipment specialists; and secondary validation through vehicle production databases, IHS Markit registration data, SEC filings from listed stampers, and aluminum trade flow records. Bottom-up triangulation across regional manufacturing clusters and top-down reconciliation against OEM platform rollouts anchored volume estimates.
Across the projection horizon, the analytical framework modeled segmentation dimensions including vehicle class, propulsion architecture, material platform, and regional production cluster. CAGRs were derived from production-weighted growth rates across battery-electric and internal combustion platforms. Forecast inputs incorporated OEM platform-commonality mandates, REACH compliance timelines, and aluminum price trajectory assumptions.
Forecasts assume regulatory continuity in EU REACH, NHTSA Federal Motor Vehicle Safety Standards, and China SAMR certification regimes; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Global Automotive Noise Filter Market
Automotive Components
Automotive Steering Column Market
Automotive Components
Germany Automotive Composites Market
Automotive Components
Automotive Regenerative Braking System Market
Automotive Components
Automotive Silencer Market
Automotive Components
Global Automotive Acoustic Materials Market
Automotive Components
Global Automotive Components Forging Market
Automotive Components
Automotive Carbon Thermoplastic Market
Automotive Components
Automotive Buffers Market
Automotive Components
Automotive Ignition Box Market
Automotive Components
Argentina Automotive Composites Market
Automotive Components
Italy Automotive Sunroof Market
Automotive Components
Off-Highway Actuators Market
Automotive Components
Automotive Actuators Market
Automotive Components
Automotive Headlight Bulb Market
Automotive Components
Europe Automotive Relay Market