
 Automotive Brake Tube Market | 2026-2036
Automotive Brake Tube Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Brake Tube Market Outlook
EU REACH restrictions on hexavalent chromium coatings is consolidating supplier compliance costs around electroplating alternatives and stainless steel substrates. Continental AG leverages its integrated brake systems division to sustain captive tube demand across European OEM programs. TI Fluid Systems anchors its position through thermal management adjacencies that share manufacturing lines with brake tubing. Nichirin Co., Ltd. specializes in coated steel tube architectures for Asian OEM export platforms.
Automotive brake tubes are pressure-bearing conduits manufactured from double-walled low-carbon steel, stainless steel, or polymer-composite materials, typically rated for burst pressures exceeding 1,100 bar to transmit hydraulic force from master cylinders to wheel calipers. Metal tubing retains dominant share in heavy-duty applications where thermal cycling resistance outweighs weight penalties, while composite tubing segments gain traction in electric vehicle platforms seeking mass reduction. Passenger vehicle applications generate the largest volume base, though commercial vehicle replacement cycles sustain higher aftermarket margins per unit for independent repair networks.
NHTSA's Federal Motor Vehicle Safety Standard 106 governs brake hose and tubing performance in the United States, while ECE R90 harmonizes type-approval requirements across European member states and China's SAMR enforces GB/T 7127 standards for automotive rubber and metal tubing. These frameworks mandate burst strength, corrosion resistance, and volumetric expansion thresholds that directly determine material selection and testing overhead for suppliers. Stakeholders must monitor how brake-by-wire adoption thresholds alter hydraulic tube content per vehicle and whether aftermarket inventory models adapt to extended electric vehicle service intervals.
Market Dynamics
Brake-by-wire migration is compressing hydraulic content per vehicle while simultaneously elevating performance specifications for remaining tube architectures in hybrid platforms.
Growth Catalysts
- Regenerative braking integration:Hybrid and electric platforms from Toyota, BYD, and Volkswagen retain hydraulic backup systems requiring high-pressure tubing rated for 1,100+ bar burst thresholds.
- EU REACH chromium restrictions:The ban on hexavalent chromium coatings is accelerating electroplating alternative adoption across Continental European supplier parks.
- Stuttgart-Wolfsburg corridor concentration:Tier 1 brake system integrators cluster in southern and central Germany, creating dense procurement networks for precision tubing.
Market Restraints
- Steel alloy price volatility:Low-carbon steel and stainless steel input costs fluctuate with energy-intensive European smelter output constraints.
- Single-source electroplating dependency:Hexavalent chromium alternatives require specialized European surface treatment facilities with limited redundant capacity.
- Polymer-composite thermal ceiling:Composite tubing substitutes face temperature limitations above 150°C in heavy-duty brake applications.
Strategic Opportunities
- Indian commercial vehicle aftermarket:Tata Motors and Ashok Leyland service networks generate replacement demand for corrosion-resistant tubing in monsoon climates.
- China NEV export platforms:GB/T 7127 compliance requirements for automotive tubing create specification premiums for certified suppliers.
- Stainless steel-polymer hybrid architectures:Converging metal-composite manufacturing lines enable thermal management diversification for brake and battery cooling systems.
Industry Challenges
- Dual certification timelines:Suppliers must parallel-track NHTSA FMVSS 106 and ECE R90 approvals for transatlantic OEM programs, extending validation cycles.
- Legacy hydraulic integration:Brake-by-wire retrofits into existing vehicle architectures require custom tube routing that conflicts with standardized module designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Brake Tube Market |
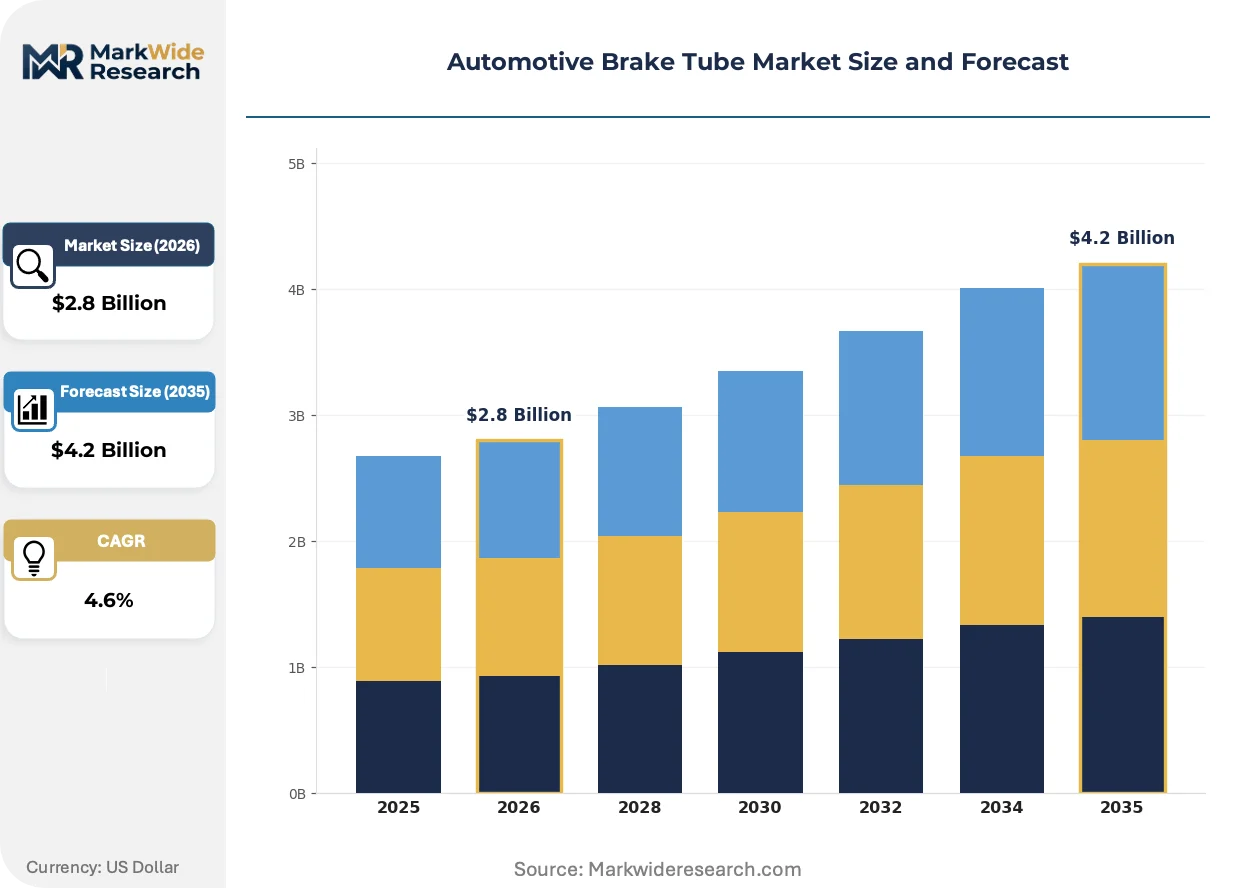
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal Tubing, Rubber Tubing, Composite Tubing, Flexible Tubing Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Heavy Machinery End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Repair Shops Installation Type: Original Equipment, Replacement, Manufacturers, Modifications |
| Companies Covered | Parker Hannifin Corporation, Sumitomo Riko Company Limited, Eaton Corporation, Nichirin Co., Ltd., TI Fluid Systems, Continental AG, Gates Corporation, Delphi Technologies, Bundy Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Brake Tube Market Strategic Shifts
Material science advances and regulatory chemistry bans are forcing simultaneous redesign of substrate alloys and protective coatings across brake tube supply chains.
Multi-layer polymer-composite tubing is converging with electric vehicle thermal management requirements. BMW and Hyundai-Kia platforms specify mass-reduced conduits that share manufacturing infrastructure with battery cooling lines. This convergence is compressing supplier equipment utilization rates as brake-dedicated capacity absorbs adjacent thermal product demand.
ECHA's REACH Annex XVII chromium(VI) restrictions are eliminating hexavalent electroplating from European brake component supply chains. Surface treatment providers must retrofit lines with trivalent chromium or zinc-nickel alternatives at capital-intensive scale. German Tier 1 suppliers face the steepest compliance timelines given their integrated captive plating operations.
Fleet operators are consolidating aftermarket procurement through authorized service networks rather than independent distributors. European commercial vehicle lessors now mandate OEM-certified tubing for warranty compliance, displacing generic replacement inventory. This channel compression is most visible in Germany's dense logistics corridor connecting Rotterdam to Milan.
Automotive Brake Tube Market Segmentation
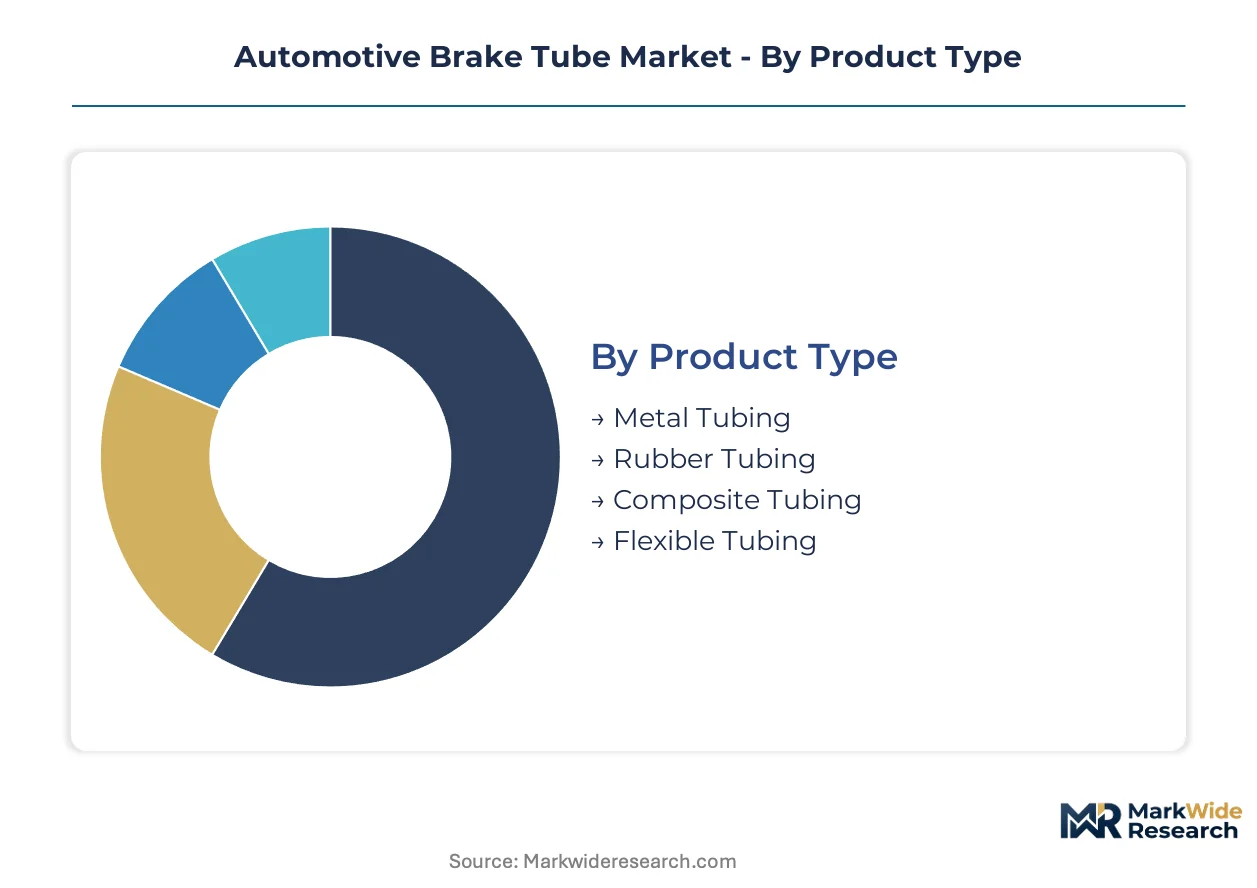
Brake tube procurement splits sharply between standardized OEM supply and customized aftermarket replacement, with material selection and installation protocols diverging across vehicle platforms. Understanding these fault lines exposes where margin pools concentrate and where specification premiums command pricing power.
Product Type:
Standardization dominates metal architectures while composite formulations demand application-specific customization.
- Metal Tubing:Double-walled low-carbon and stainless steel constructions rated for 1,100+ bar burst pressures anchor heavy-duty commercial fleets. Demand concentrates in Germany's Stuttgart-Wolfsburg corridor where Tier 1 integrators specify corrosion-resistant substrates for ECE R90 compliance.
- Composite Tubing:Multi-layer polymer architectures reduce mass by 40-60% versus steel equivalents for electric vehicle platforms. Hyundai-Kia and BMW specify these conduits where thermal management lines share manufacturing infrastructure with battery cooling systems.
- Rubber Tubing:Reinforced elastomer constructions serve flex-connection points in suspension travel zones.
- Flexible Tubing:Corrugated stainless or polymer assemblies accommodate chassis dynamics in off-road and commercial applications.
Most installed capacity flows through Metal Tubing. Expansion is steepest in Composite Tubing.
Application:
Volume tiers separate high-unit passenger production from margin-rich commercial replacement cycles.
- Passenger Vehicles:Global OEM platforms generate the largest absolute unit demand, though brake-by-wire migration is compressing hydraulic content per vehicle. Toyota and Volkswagen hybrid architectures retain high-pressure backup systems sustaining tube specifications.
- Commercial Vehicles:Extended service intervals and severe-duty thermal cycling create aftermarket premium pricing. Tata Motors and Ashok Leyland service networks in India drive corrosion-resistant replacement demand through monsoon climate exposure.
- Two-Wheelers:Cost-optimized single-wall steel tubing dominates emerging market production.
- Heavy Machinery:Custom-bent rigid lines serve construction and mining equipment with non-standard chassis geometries.
Passenger Vehicles absorb the greatest production volume. Commercial Vehicles generate the steepest per-unit margin expansion.
End User:
Procurement concentration distinguishes captive OEM supply from fragmented aftermarket channels.
- OEMs:Continental AG and TI Fluid Systems anchor direct supply relationships with specification control over material substrates and surface treatments. REACH chromium restrictions are forcing simultaneous redesign of substrate alloys and protective coatings across these supply chains.
- Aftermarket Providers:Fleet operators are consolidating procurement through authorized service networks for warranty compliance, displacing generic inventory in Europe's Rotterdam-Milan logistics corridor.
- Vehicle Assemblers:Contract manufacturers source pre-bent tube assemblies from Tier 2 specialists.
- Repair Shops:Independent service points stock universal-fit coiled tubing for field fabrication.
OEMs command the densest supplier relationships. Aftermarket Providers are gaining share fastest through fleet channel consolidation.
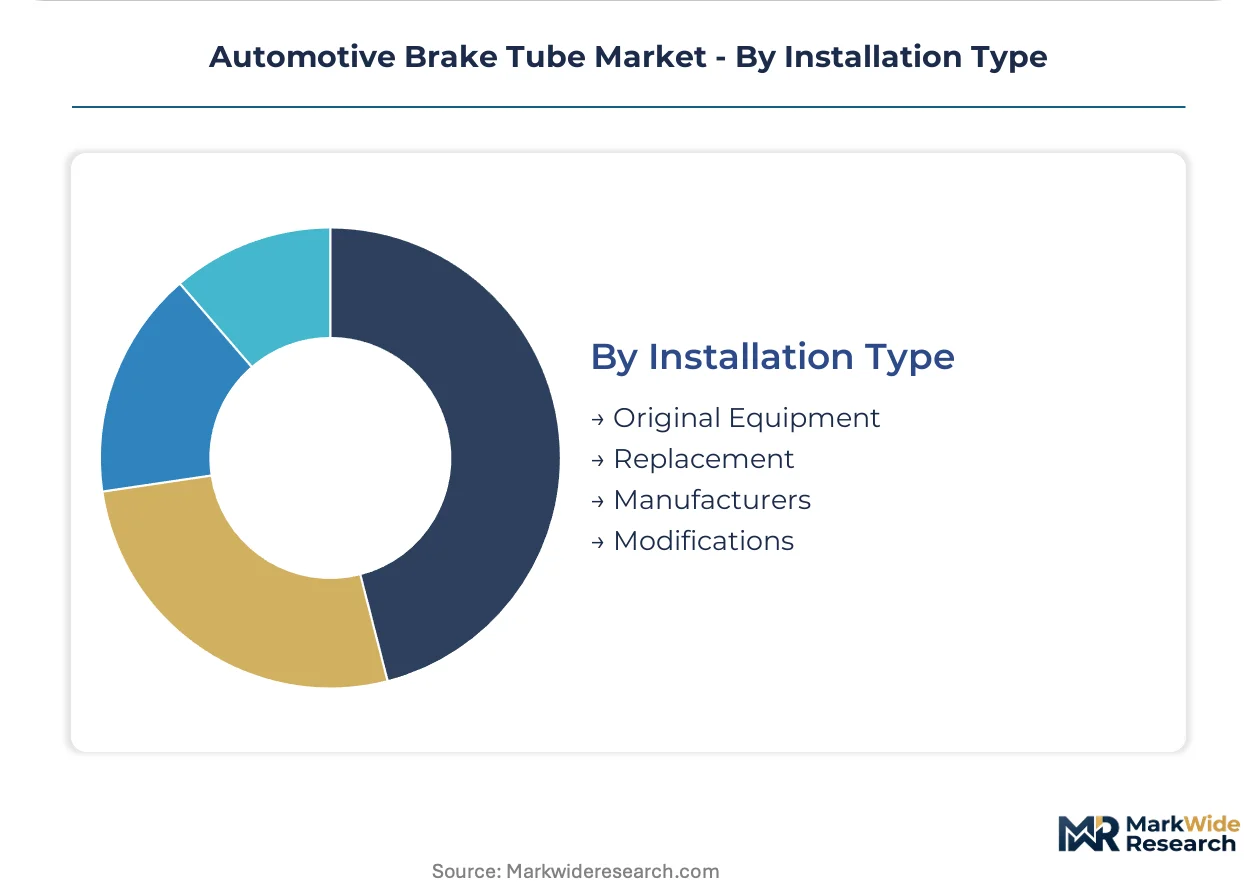
Installation Type:
Original specification rigor contrasts with replacement flexibility in field installation protocols.
- Original Equipment:Factory-installed lines undergo NHTSA FMVSS 106 and ECE R90 parallel certification, extending validation timelines for transatlantic programs. Dual certification requirements compress supplier qualification bandwidth.
- Replacement:Service networks increasingly mandate OEM-certified tubing for warranty compliance, narrowing generic substitution in European commercial vehicle lessor fleets.
- Manufacturers:Tier 2 fabricators produce pre-formed assemblies for module integration.
- Modifications:Custom builders and motorsport applications specify braided stainless or AN-fitted configurations.
Original Equipment absorbs the majority of precision-forming capacity. Replacement installations are expanding most quickly through fleet compliance mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision tubing engineers and metallurgical specialists cluster around Stuttgart and Wolfsburg in Germany, China's Yangtze River Delta automotive corridor, and the Detroit-to-Toronto supplier belt, anchoring global brake tube production capacity.
Germany
Stuttgart-Wolfsburg corridor concentration sustains captive demand from Continental AG and Bosch brake system integrators. ECHA's REACH Annex XVII chromium(VI) restrictions force simultaneous substrate and coating redesign across integrated supplier parks. Surface treatment facilities in Baden-Württemberg retrofit electroplating lines for trivalent chromium alternatives.
China
BYD and CATL electric vehicle platforms expand procurement for regenerative braking backup systems. SAMR enforces GB/T 7127 standards for automotive rubber and metal tubing compliance. Yangtze River Delta clusters around Shanghai and Suzhou concentrate certified tubing capacity for NEV export programs.
United States
Detroit Three automakers and Tesla retain hydraulic architectures in hybrid platforms. NHTSA's Federal Motor Vehicle Safety Standard 106 governs brake hose and tubing performance thresholds. Michigan-Ohio supplier corridors bend pre-formed assemblies for module integration.
India
Tata Motors and Ashok Leyland commercial vehicle service networks generate replacement demand. BIS standards align with ECE R90 frameworks for type-approval harmonization. Maharashtra and Tamil Nadu manufacturing belts produce corrosion-resistant tubing for monsoon climate exposure.
Japan
Toyota hybrid platforms sustain high-pressure tubing specifications for dual braking systems. METI industrial standards coordinate with JIS automotive tubing requirements. Aichi Prefecture supplier networks feed precision tube assemblies to domestic OEM programs.
Automotive Brake Tube Market Competitive Environment
The competitive structure tilts toward integrated brake system suppliers with captive tubing demand. Tier 1 integrators cluster around German automotive corridors and Asian OEM supply chains. Three archetypes dominate: full-system integrators with in-house tube fabrication, specialized fluid management suppliers leveraging thermal management adjacencies, and dedicated tubing specialists serving export platforms. Consolidation pressure and coating technology transitions drive M&A activity and electroplating line retrofits.
Within the integrated-system tier, Continental AG and TI Fluid Systems exemplify archetypes combining brake tubing with broader fluid or thermal portfolios. Nichirin Co., Ltd. occupies a specialist position among coated steel tube fabricators serving Asian OEM export programs. These three anchors demonstrate how geographic clustering around Stuttgart, Shanghai-adjacent corridors, and Japanese industrial belts shapes competitive positioning without requiring vertical integration into raw material smelting.
| Leading Market Players |
|---|
| Parker Hannifin Corporation |
| Sumitomo Riko Company Limited |
| Eaton Corporation |
| Nichirin Co., Ltd. |
| TI Fluid Systems |
| Continental AG |
| Gates Corporation |
| Delphi Technologies |
| Bundy Group |
| Others |
Value Chain & Pricing Dynamics
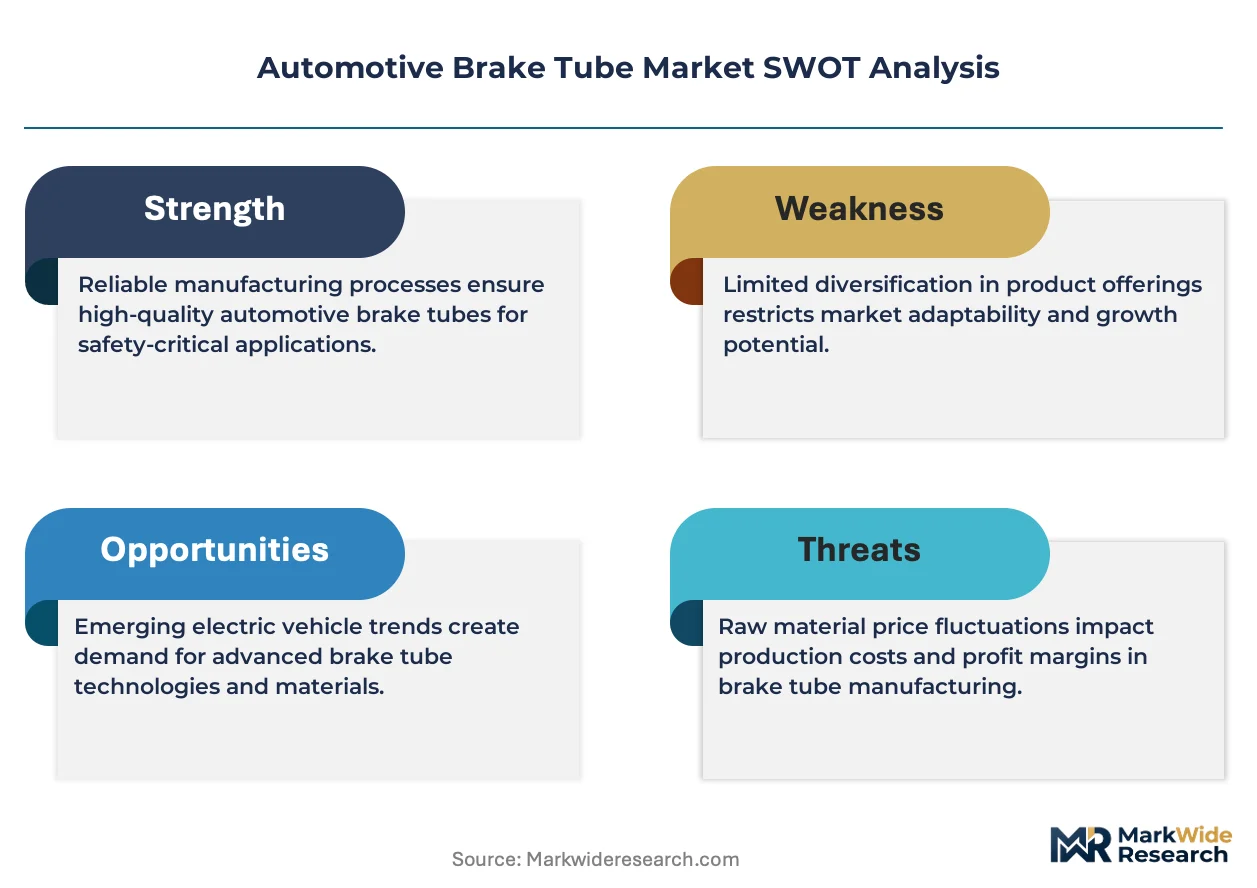
Electroplating line retrofits for REACH-compliant trivalent chromium alternatives are simultaneously elevating capital expenditure thresholds and consolidating supplier bargaining power around Baden-Württemberg surface treatment facilities with redundant capacity. This technology transition compresses margin pools for tube fabricators without captive plating operations while rewarding integrated Tier 1 suppliers with specification control over both substrate alloys and protective coatings.
Pricing Analysis
Bundled tube-and-coating service packages command premiums over unbundled procurement where fabricators source surface treatment from third-party job shops. Three-tier pricing structure across OEM-certified, aftermarket-branded, and generic replacement levels separates specification-grade stainless steel architectures from commodity low-carbon alternatives. Cost compression in the generic replacement tier is intensifying because fleet operators are consolidating procurement through authorized service networks for warranty compliance. Aftermarket distributors serving independent repair shops exhibit the highest price sensitivity, while OEM direct supply relationships demonstrate the lowest.
Supply Chain Analysis
Reverse-logistics flows for brake tube remanufacturing remain underdeveloped, though European commercial vehicle lessors are piloting core-return programs for stainless steel rigid lines. Supply concentrates in Germany, China, and Japan where precision forming capacity clusters around Stuttgart, Shanghai-Suzhou corridors, and Aichi Prefecture. Raw material dependencies draw from European stainless steel smelters, Chinese low-carbon steel mills, and Japanese specialty alloy producers. Single-source electroplating vulnerability in Continental European supplier parks creates structural risk given limited redundant capacity for hexavalent chromium alternatives. Distribution runs through Tier 1 brake system integrators with captive tube demand, bypassing independent distributors in OEM channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through coating technology transitions that eliminate commodity competitors unable to fund electroplating line retrofits, while premium-tier shifts toward stainless steel-polymer hybrid architectures capture thermal management adjacencies.
For Market Incumbents: Lock in specification control by retrofitting captive electroplating lines for trivalent chromium alternatives before REACH enforcement timelines compress, while simultaneously securing long-term offtake agreements with Yangtze River Delta NEV export platforms. The threat of brake-by-wire adoption eliminating hydraulic content per vehicle makes thermal management line diversification the critical capacity-redeployment lever. For New Entrants and Emerging Players: Enter via India's commercial vehicle aftermarket where Tata Motors and Ashok Leyland service networks generate replacement demand for corrosion-resistant tubing in monsoon climates, with regulatory alignment between BIS and ECE R90 standards lowering certification barriers. The most penetrable segment is authorized fleet service networks displacing generic inventory, with go-to-market execution anchored through direct partnerships with commercial vehicle lessors in the Rotterdam-Milan logistics corridor. For Investors and Strategic Acquirers: Valuations sit cheapest among dedicated tubing specialists without thermal management adjacencies, as these assets face stranded capacity risk from brake-by-wire migration. Long-term viability across the analysis window hinges on manufacturing line flexibility to absorb battery cooling system demand. The signal to watch is OEM platform decisions on regenerative braking backup architectures that determine hydraulic tube content per vehicle.| Strategic Initiative | Industry Significance |
|---|---|
| Electroplating Line Retrofit | Baden-Württemberg surface treatment facilities gain specification control as REACH deadlines eliminate competitors without capital access. |
| Thermal Management Diversification | BMW and Hyundai-Kia platform convergence enables brake-dedicated capacity to absorb adjacent battery cooling demand. |
| NEV Export Platform Certification | GB/T 7127 compliance creates specification premiums for suppliers serving BYD and CATL electric vehicle programs. |
| Fleet Channel Consolidation | European commercial vehicle lessors mandate OEM-certified tubing, displacing generic inventory in authorized service networks. |
| Stainless Steel-Polymer Hybrid Development | Multi-layer architectures reduce mass by 40-60% versus steel equivalents while retaining burst pressure ratings for hybrid platforms. |
Study Parameters
Bottom-up vehicle production modeling reconciled against top-down supplier capacity tracking forms the analytical core, combining primary interviews with Tier 1 brake system procurement officers, OEM platform engineers, aftermarket distributors, and surface treatment facility operators with secondary validation from vehicle registration databases, customs trade records, SEC filings of listed automotive suppliers, and regulatory filing repositories including NHTSA FMVSS 106 documentation and ECHA REACH Annex XVII amendments. This triangulation approach cross-checks unit volume assumptions against fabrication capacity utilization rates reported across German, Chinese, and Japanese supplier clusters.
Historical trendline analysis of brake tube content per vehicle across hybrid, electric, and internal combustion platforms informs the projection framework, with segmentation dimensions spanning propulsion architecture, vehicle class, material substrate, and regional production cluster. CAGRs were derived from regression analysis of installation rates against vehicle production forecasts, incorporating inputs from brake-by-wire adoption curves, regenerative braking system penetration, and thermal management line convergence trends observed across BMW and Hyundai-Kia manufacturing specifications.
Inputs from OEM procurement databases and Tier 1 supplier disclosures were available through the study window; gaps in aftermarket channel inventory turnover data introduce uncertainty bands around replacement cycle assumptions. Forecasts reflect documented assumptions regarding REACH enforcement timelines and NEV export platform growth trajectories, with revision triggers including accelerated brake-by-wire adoption thresholds and raw material price volatility in European steel smelter output. Practitioners should monitor ECHA regulatory guidance updates and OEM platform engineering decisions on hydraulic backup architectures for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
North America Automotive Glass Market
Automotive Components
Asia-Pacific Automotive Composites Market
Automotive Components
Global Automotive Interior Plastic Components Market
Automotive Components
Automotive Lightweighting Market
Automotive Components
Asia-Pacific Heat Shrink Tubing for Automotive Market
Automotive Components
Global Automotive Condenser Market
Automotive Components
Germany Automotive Composites Market
Automotive Components
Automotive Air Deflector Market
Automotive Components
Global Automotive Brake Components Market
Automotive Components
Automotive Headliners Market
Automotive Components
Automotive Key Market
Automotive Components
Automotive Filters Market
Automotive Components
Global Automotive Selector Lever Market
Automotive Components
Automotive Carbon Brake Rotor Market
Automotive Components
Global Automotive Window Regulator Market
Automotive Components
Global Automotive Active Body Panel Market