
 Global Automotive Interior Component Market | 2026-2036
Global Automotive Interior Component Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Interior Component Market Analysis
Automotive mechatronics talent is bifurcating the supplier landscape into electronics-capable integrators and traditional trim specialists. Continental AG leverages its embedded software depth to compete in smart cockpit modules. Lear Corporation anchors North American seating supply through backward integration into foam and frame manufacturing. Toyota Boshoku dominates Japanese OEM channels with just-in-time interior sequencing capabilities.
Automotive interior components encompass the cabin assemblies, surface treatments, and functional modules that define occupant environment, safety integration, and human-machine interface within a vehicle. Dashboard assemblies incorporate injection-molded ABS-PC blends with soft-touch thermoplastic olefin overlays, while seat systems integrate multi-density polyurethane foam with steel or composite frames to manage crash energy and ergonomic adjustment. Plastic material formulations lead volume consumption across console and door trim applications, though leather upholstery commands disproportionate margin contribution in luxury segments. Smart Interiors technology is displacing conventional switchgear as capacitive controls and haptic feedback modules penetrate mainstream vehicle classes.
EPA fuel economy standards in the United States, ECHA REACH substance restrictions in Europe, and China's MIIT new energy vehicle mandates collectively redirect material choices toward lower-VOC emissions and reduced mass. NHTSA safety protocols for interior head impact and flammability further constrain design freedom while creating compliance barriers for new entrants. Stakeholders must monitor regulatory divergence between major automotive markets to avoid redundant homologation costs and stranded tooling investments.
Market Dynamics
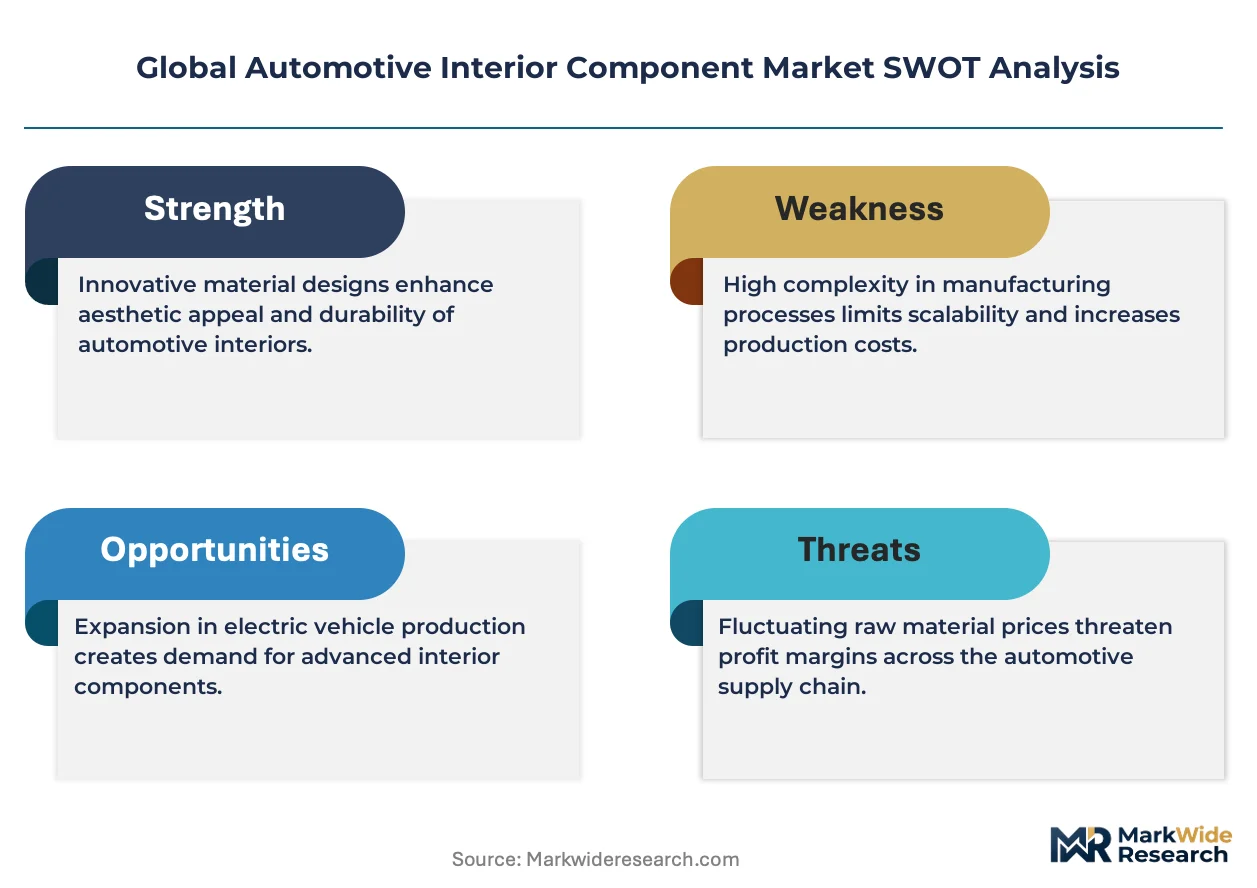
Electric vehicle platform architectures are compressing development cycles and forcing interior suppliers to abandon legacy combustion-era cabin layouts. The shift from internal combustion to battery-electric powertrains eliminates transmission tunnels and engine compartments, enabling flat-floor designs that redistribute spatial priorities across seating, storage, and human-machine interface zones.
Growth Catalysts
- MIIT new energy vehicle mandates:China's production quotas for zero-emission vehicles accelerate demand for lightweight, modular interior systems that maximize cabin space efficiency in battery-dense platforms.
- Capacitive haptic interfaces:Touch-sensitive control surfaces with programmable feedback are replacing mechanical switchgear across mainstream vehicle segments, reducing part counts while enabling over-the-air feature updates.
- Germany's premium OEM cluster:Stuttgart, Munich, and Wolfsburg concentrate engineering specifications that propagate globally, creating pull-through demand for advanced seating and cockpit modules.
Market Restraints
- Polyurethane foam feedstock volatility:Seating manufacturers face margin compression from propylene oxide and TDI price swings tied to petrochemical supply disruptions.
- Tooling amortization burden:Interior component molds require 500,000+ unit volumes to break even, locking suppliers into long-cycle commitments with limited flexibility for design changes.
- ECHA REACH substance restrictions:Phased bans on certain flame retardants and plasticizers force reformulation of dashboard and door trim materials, extending validation timelines by 18-24 months.
Strategic Opportunities
- India's passenger vehicle localization:The PLI scheme for automotive components creates incentives for domestic production of seat frames, headliners, and center consoles previously imported from East Asia.
- Biometric cabin personalization:Integration of facial recognition and vital sign monitoring enables subscription-based comfort profiles, opening recurring revenue streams beyond hardware sales.
- Closed-loop textile recycling:EU Green Deal circular economy requirements position post-consumer polyester and nylon recovery as a compliance-driven service differentiator for carpet and upholstery suppliers.
Industry Challenges
- Embedded software integration:Mechanical trim suppliers lack firmware development capabilities required for smart surface contracts, forcing expensive talent acquisition or partnership dependency.
- Homologation divergence:NHTSA head impact criteria, ECE flammability protocols, and GB standards for VOC emissions create conflicting test matrices that multiply certification costs for global programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Interior Component Market |
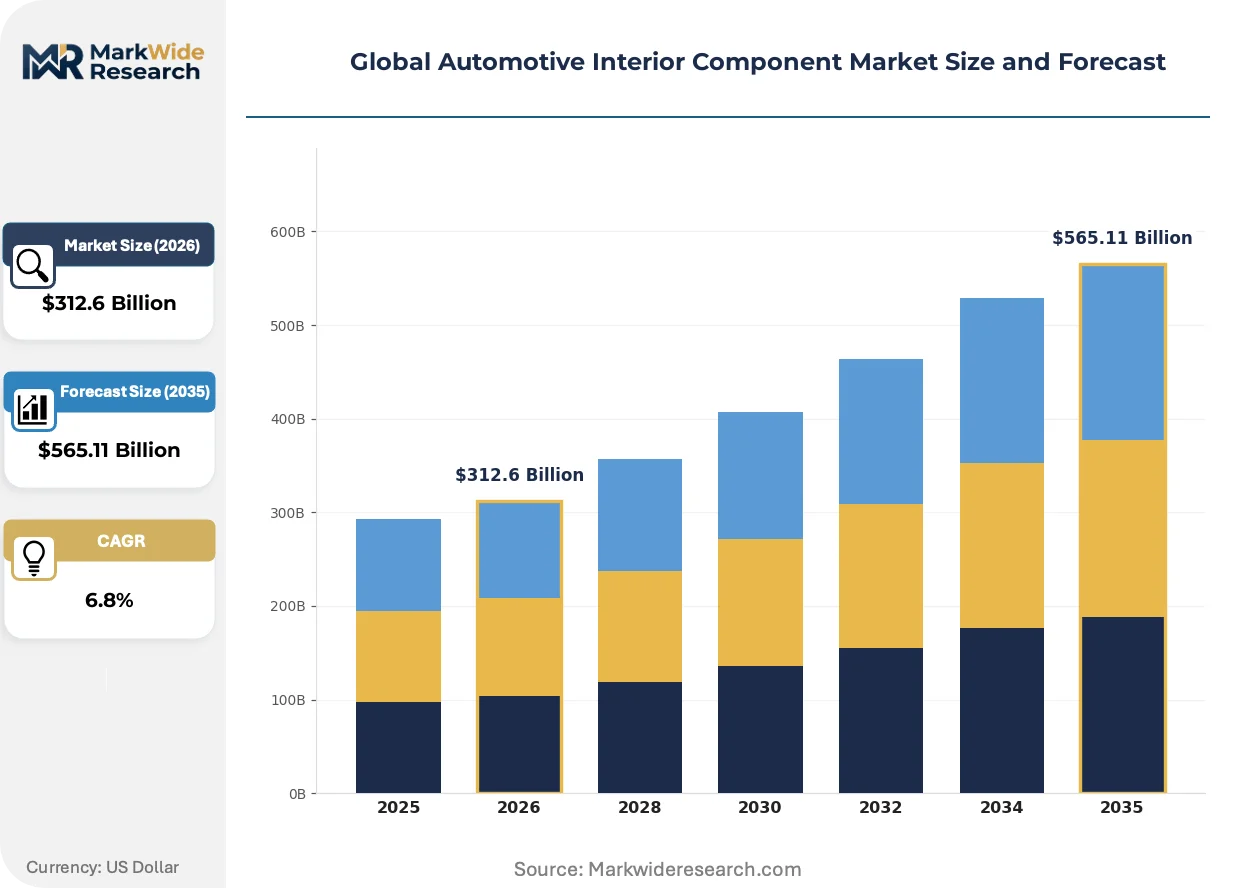
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $565.11 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Dashboard, Seats, Door Trims, Console Material: Plastic, Leather, Fabric, Metal End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Technology: Smart Interiors, Custom Manufacturing, Eco-Friendly Materials, Modular Design |
| Companies Covered | Magna International, Continental AG, FORVIA (Faurecia), Asahi Kasei Corporation, Toyota Boshoku Corporation, Lear Corporation, Yanfeng Automotive Interiors, Grupo Antolin, Adient, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Interior Component Market Emerging Trajectories
Active material substitution and software-defined cabin experiences are collapsing traditional boundaries between automotive tiers. The convergence of consumer electronics interaction paradigms with safety-critical vehicle systems is creating new competitive vectors around update velocity and personalization depth.
Structural thermoplastic composites are supplanting steel and aluminum in seat frames and load-bearing trim substrates. BMW and Polestar specifications now specify carbon-fiber-reinforced polyamide for front seat structures, cutting mass by 40 percent versus stamped metal. This material transition is compressing the supplier base to plastics compounders with automotive crash simulation expertise.
REACH substance restrictions are forcing wholesale reformulation of soft-touch surfaces across European production. ECHA's 2023-2025 restriction roadmap targets short-chain chlorinated paraffins and certain organophosphates used in dashboard skins, compelling suppliers to validate bio-based alternatives like castor-oil-derived polyols. German OEMs are responding by consolidating qualified material libraries and extending supplier development programs to smaller compounders.
Fleet operators and mobility-as-a-service providers are unbundling interior durability from initial vehicle purchase. Ride-hailing companies in California and Texas now specify commercial-grade seat fabrics and reinforced trim substrates with separate wear warranties, shifting specification authority from OEM brand teams to fleet procurement departments with total-cost-of-ownership models. This buyer concentration is compressing supplier margins while extending contract durations.
Global Automotive Interior Component Market Segmentation
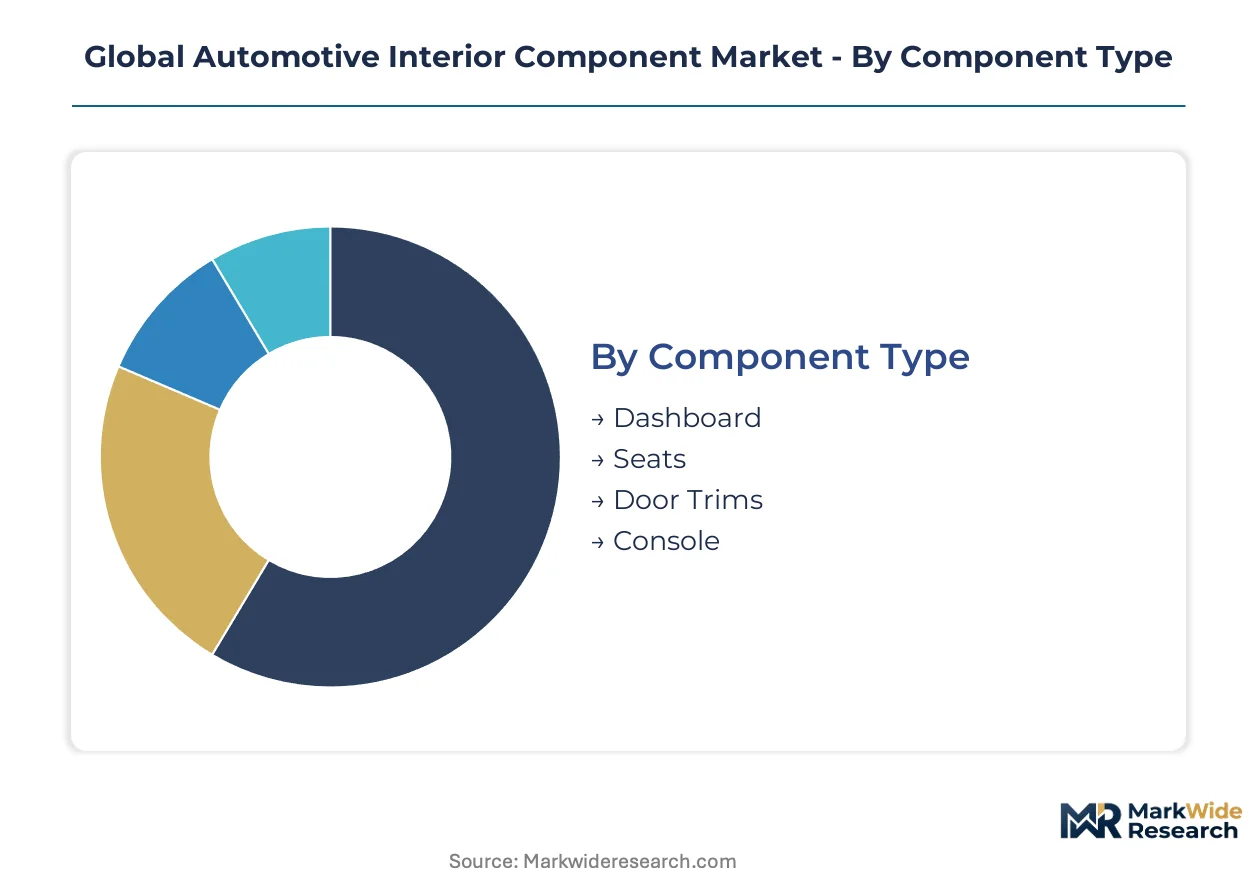
Interior component segmentation reveals how regulatory pressure and electrification reshape procurement priorities across material classes and integration technologies. Suppliers must align capabilities with divergent compliance regimes while capturing platform-standardization benefits.
Component Type:
ECHA REACH substance restrictions and NHTSA head-impact protocols create divergent specification burdens across cabin zones, forcing tiered compliance investment.
- Seats:Multi-density polyurethane foam bonded to steel or composite frames manages crash energy and ergonomic adjustment. German OEM specifications for carbon-fiber-reinforced polyamide frames are propagating to China and United States assembly plants, compressing supplier qualification timelines.
- Dashboard:Injection-molded ABS-PC blends with soft-touch thermoplastic olefin overlays integrate capacitive haptic interfaces. REACH-driven reformulation of flame retardants and plasticizers extends European validation cycles, locking compounders into 18-24 month development commitments.
- Door Trims:Substrate-panel assemblies with fabric or synthetic skin coverings. MIIT new energy vehicle mandates favor lightweight designs that maximize cabin space in battery-dense platforms.
- Console:Center-mounted storage and control housings. Flat-floor EV architectures redistribute spatial priorities toward expanded console volumes.
Established volume favors seats; emerging adoption favors dashboard haptic integration.
Material:
Cost tier stratification separates luxury margin capture from mass-market volume throughput.
- Plastic:Volume leader across console and door trim applications with formulation flexibility for VOC compliance. Polypropylene and ABS-PC blends dominate, though propylene oxide and TDI feedstock volatility compresses seating manufacturer margins.
- Leather:Upholstery commands disproportionate margin contribution in premium segments. BMW and Mercedes-Benz specifications drive hide selection and tanning chemistry standards that propagate globally.
- Fabric:Polyester and nylon textiles for seat inserts and headliners. EU Green Deal circular economy requirements position closed-loop recycling as a compliance-driven service differentiator.
- Metal:Stamped steel and aluminum in structural frames, now supplanted by thermoplastic composites in mass reduction programs. Tooling amortization demands 500,000+ unit volumes to break even.
Premium positioning favors leather; steepest expansion trajectory favors bio-based plastic alternatives.
End User:
Customer type concentration determines contract duration, specification authority, and margin structure.
- OEMs:Brand teams in Stuttgart, Munich, and Wolfsburg propagate engineering specifications that tier-1 suppliers must replicate across global assembly footprints. Just-in-time sequencing capabilities separate qualified integrators from component vendors.
- Tier-1 Suppliers:Lear Corporation and Continental AG anchor purchasing power through backward integration into foam, frame, and embedded software production. Embedded firmware requirements now exclude pure mechanical trim specialists from smart surface contracts.
- Vehicle Assemblers:Contract manufacturers and emerging EV platforms with modular sourcing strategies. Compressed development cycles favor suppliers with crash simulation and rapid tooling capabilities.
- Aftermarket Providers:Fleet operators and mobility-as-a-service providers now specify commercial-grade durability with separate wear warranties. Buyer concentration shifts specification authority to procurement departments with total-cost-of-ownership models.
Specification control favors OEMs; contract duration extension favors fleet-facing aftermarket procurement.
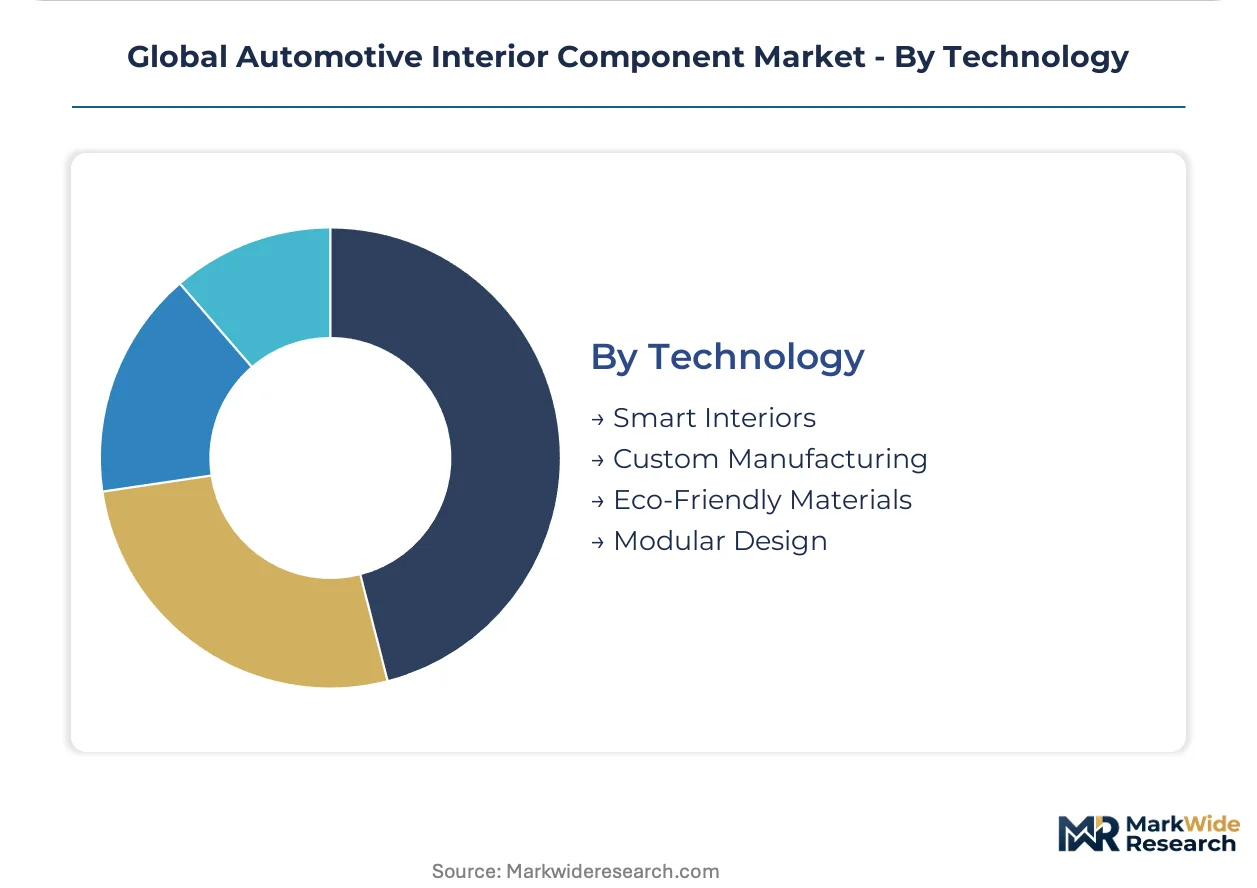
Technology:
Integration maturity separates proven production systems from pilot-phase revenue.
- Smart Interiors:Capacitive controls and haptic feedback modules displace mechanical switchgear. Over-the-air update capability requires firmware development competencies that mechanical suppliers must acquire through expensive talent recruitment.
- Modular Design:Platform-standardized subassemblies reduce part counts and enable configuration flexibility. Flat-floor EV architectures compress legacy combustion-era cabin layouts.
- Eco-Friendly Materials:Castor-oil-derived polyols and bio-based alternatives replace restricted substances. German OEMs consolidate qualified material libraries and extend supplier development programs to smaller compounders.
- Custom Manufacturing:Low-volume personalization for luxury and limited-production vehicles. Biometric cabin personalization enables subscription-based comfort profiles beyond hardware sales.
Production scale favors modular design; recurring revenue potential favors biometric-enabled smart interiors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China, Germany, and the United States each deploy automotive interior components toward distinct priorities—battery platform space efficiency, premium material compliance, and fleet durability respectively—creating divergent specification requirements for suppliers serving multiple assembly footprints.
China
MIIT production quotas for new energy vehicles compress development timelines for lightweight cabin architectures that maximize interior volume around battery packs. GB standards for VOC emissions constrain adhesive and foam formulations used in seating and dashboard applications. Shanghai and Guangzhou assembly corridors concentrate purchasing authority for smart cockpit modules among domestic EV platforms.
Germany
ECHA REACH substance restrictions force 18-24 month reformulation cycles for soft-touch dashboard materials and flame-retardant seating components. Stuttgart, Munich, and Wolfsburg propagate engineering specifications for carbon-fiber-reinforced polyamide seat frames that tier-1 suppliers replicate across global footprints. The KBA type-approval process adds validation layers for biometric-enabled cabin systems.
United States
NHTSA head-impact protocols and EPA fuel economy standards redirect material selection toward lower-mass, crash-compliant interior substrates. Fleet operators in California and Texas now specify commercial-grade seat fabrics with separate wear warranties, shifting specification authority from OEM brand teams to procurement departments. Michigan and Tennessee assembly clusters anchor North American seating supply chains.
Japan
METI carbon-neutrality roadmaps accelerate adoption of bio-based polyols derived from castor oil for dashboard and door trim applications. Toyota Boshoku's just-in-time sequencing capabilities dominate supply relationships with domestic OEMs. The Nagoya industrial corridor concentrates engineering expertise for compact vehicle interior packaging.
India
PLI scheme incentives for automotive components create domestic production mandates for seat frames, headliners, and center consoles previously imported from East Asia. BIS quality certification requirements extend validation timelines for imported material formulations. Maharashtra and Tamil Nadu manufacturing corridors concentrate foreign OEM assembly investments driving tier-1 supplier localization.
Global Automotive Interior Component Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with electronics-capable integrators separating from pure mechanical trim suppliers. The market structure rewards backward integration into foam, frame, and embedded software production while penalizing standalone component vendors. Three archetypes dominate: full-system integrators with firmware depth, material specialists with compounder relationships, and sequencing logistics providers with OEM-proximate assembly. Competitive moves concentrate on M&A for software capabilities and capacity expansion in battery-electric platform supply.
Among the integrated tier, Continental AG and Lear Corporation exemplify the electronics-capable archetype through embedded software depth and captive foam production respectively. Toyota Boshoku occupies a position within the sequencing logistics tier through just-in-time interior assembly capabilities. These three entities represent the competitive standard against which mid-cap specialists benchmark vertical integration and OEM channel access.
| Leading Market Players |
|---|
| Magna International |
| Continental AG |
| FORVIA (Faurecia) |
| Asahi Kasei Corporation |
| Toyota Boshoku Corporation |
| Lear Corporation |
| Yanfeng Automotive Interiors |
| Grupo Antolin |
| Adient |
| Others |
Supply Flow & Price Mechanics
Eighteen-month tooling lead times for interior component molds concentrate pricing power among suppliers with captive frame and foam production, while buyers face take-or-pay commitments that lock in volumes above 500,000 units. This structural rigidity amplifies margin pressure when propylene oxide and TDI feedstock costs spike, forcing compounders to absorb volatility or renegotiate long-cycle contracts.
Pricing Analysis
Long-term offtake agreements dominate procurement relationships between German OEMs and seating suppliers, with spot purchasing limited to aftermarket fleet operators seeking commercial-grade durability warranties. Price differentiation separates carbon-fiber-reinforced polyamide frame specifications from stamped steel alternatives, while REACH compliance certification adds a premium tier for European-bound production. Cost compression in mass-market seating is intensifying as Indian PLI localization mandates redirect volume toward domestic compounders with lower labor absorption. Fleet procurement departments exhibit the highest price sensitivity due to total-cost-of-ownership modeling, whereas luxury OEM brand teams prioritize material pedigree over unit economics.
Supply Chain Analysis
Inventory buffers of 45-60 days for polyurethane foam precursors expose seating manufacturers to propylene oxide supply disruptions from Gulf Coast petrochemical clusters. Manufacturing concentration in China, Germany, and Mexico feeds just-in-time sequencing networks for battery-electric platform assembly, with raw material dependencies on Saudi Arabian petrochemicals, Brazilian castor oil for bio-based polyols, and South Korean carbon fiber. Single-source vulnerability in specialized TDI isocyanate production creates chokepoint risk for multi-density foam formulations. Distribution runs through OEM-proximate sequencing centers in Stuttgart, Shanghai, and Detroit rather than centralized warehousing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart cockpit module penetration sits below 35% in mass-market vehicle classes, creating runway for capacitive haptic interface adoption as EV platforms compress development cycles and enable over-the-air feature expansion.
For Market Incumbents: Compound firmware development capabilities through targeted recruitment of embedded software engineers or acquisition of haptic feedback specialists, as mechanical trim suppliers without smart surface competencies face exclusion from dashboard contracts. Extend supplier development programs to smaller bio-based compounders in Europe to secure qualified material libraries ahead of REACH restriction deadlines. Backward integration into foam production anchors margin defense against propylene oxide volatility.
For New Entrants and Emerging Players: ECE flammability certification fast-track positions specialized compounders to capture reformulation demand as ECHA phased bans on chlorinated paraffins invalidate incumbent formulations. Target India's PLI scheme corridors in Maharashtra and Tamil Nadu for seat frame and headliner production previously imported from East Asia. Pursue fleet procurement relationships in California and Texas with commercial-grade durability warranties as specification authority shifts from OEM brand teams.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because electronics-capable integrators with embedded software depth command valuation premiums over pure mechanical trim specialists, and the supplier base is bifurcating toward extinction for non-integrators. Acquire mid-cap sequencing logistics providers with OEM-proximate assembly capabilities in Nagoya or Guangzhou. Monitor MIIT new energy vehicle mandate enforcement as the signal for inflection in lightweight cabin architecture demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces part counts for flat-floor EV architectures across BMW and Polestar specifications. |
| Battery Supply Agreement | Secures lithium allocation for lightweight seat frame production in battery-dense platforms. |
| Software-Defined Vehicle Investment | Enables over-the-air haptic interface updates through Continental AG firmware capabilities. |
| Geographic Manufacturing Footprint | Localizes production in India PLI corridors to replace East Asian seat frame imports. |
| Charging Infrastructure Partnership | Aligns cabin space efficiency with fleet operator dwell-time requirements in California markets. |
Methodological Framework
Cross-validation between OEM platform engineering disclosures and Tier 1 supplier procurement data anchors the qualitative findings on smart cockpit adoption timelines. Primary interviews with seating program directors, dashboard compounder technical leads, and fleet procurement officers in Stuttgart, Shanghai, and Detroit were synthesized with secondary validation from vehicle production databases, IHS Markit registration data, ECHA substance restriction filings, and MIIT new energy vehicle quota announcements. Bottom-up content-per-vehicle estimates and top-down OEM purchasing budget analysis were triangulated to reconcile segmentation outputs.
Sensitivity analysis around propulsion architecture mix and REACH compliance cost pass-through informs the analytical framework across the projection horizon. Segmentation dimensions modeled include vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs were derived from regression against historical platform launch cadences and forward-looking battery-electric penetration assumptions. Industry-specific forecast inputs encompass tooling amortization schedules and homologation timeline divergence between NHTSA, ECE, and GB standards.
Decision-makers should treat outputs as directional under sustained MIIT mandate enforcement and stable petrochemical feedstock availability; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Metal Market
Automotive Components
Automotive Cast Iron Cylinder Head Market
Automotive Components
Automotive Interconnecting Shaft Market
Automotive Components
Automotive Actuators Market
Automotive Components
United States Aftermarket Automotive Parts and Components Market
Automotive Components
Automotive Carbon Thermoplastic Market
Automotive Components
Global Automotive Mats Market
Automotive Components
MEMS Automobile Sensors Market
Automotive Components
Russia Automotive Electric Actuators Market
Automotive Components
South Korea Automotive Pneumatic Actuators Market
Automotive Components
South Korea Automotive Sunroof Market
Automotive Components
Automotive Front-End Module (FEM) Market
Automotive Components
Automotive Gudgeon Pin Market
Automotive Components
US Automotive Composites Market
Automotive Components
Automotive Pedals Market
Automotive Components
Automotive Filters Market