
 Aftermarket Automotive Parts & Components Market | 2026-2036
Aftermarket Automotive Parts & Components Market Size, Share, and Industry Trends Forecast 2026-2036
Aftermarket Automotive Parts & Components Market Insights
Skilled technician shortages across North America and Europe are redrawing competitive dynamics in the aftermarket automotive parts & components landscape. Robert Bosch GmbH leverages its diagnostic equipment ecosystem to anchor service bay loyalty and recurring parts pull-through. Continental AG competes through sensor-integrated brake and chassis modules that sustain premium positioning in repair shops. Denso Corporation specializes in thermal and powertrain components, extending its OEM heritage into trusted replacement channels.
Aftermarket automotive parts & components encompass replacement and upgrade products manufactured to original or equivalent specifications for vehicles post-initial sale, including friction materials with defined wear coefficients, filtration media rated to ISO 4548-12 standards, and battery chemistries optimized for cyclic durability in temperature-extreme operating conditions. These components restore or enhance vehicle performance, safety, and emissions compliance throughout extended service lifecycles. Brakes and filters occupy mature, high-frequency replacement cycles with stable margin pools anchored by regulatory inspection mandates. Batteries are accelerating fastest as electrification expands, particularly for start-stop and mild-hybrid architectures requiring enhanced cyclic durability. Suspension kits concentrate margin in specialized performance and commercial fleet segments where load ratings and durability specifications exceed baseline OE fitments.
The EPA enforces emissions compliance for replacement catalytic converters under Clean Air Act Section 203, while NHTSA's Federal Motor Vehicle Safety Standards govern brake system performance and crashworthiness of structural replacement parts. CARB operates parallel certification requirements that shape product design for California and the fourteen states adopting its standards. Stakeholders must monitor the tension between right-to-repair legislation advancing in multiple U.S. states and OEM strategies to restrict diagnostic access and parts authentication protocols.
Market Dynamics
Fleet operators are compressing vehicle replacement cycles while extending preventive maintenance intervals, creating sustained demand for high-turnover consumables like brake friction materials and filtration media calibrated to OEM wear specifications.
Growth Catalysts
- EPA Clean Air Act Section 203:Mandatory emissions compliance for replacement catalytic converters sustains certified aftermarket manufacturing capacity and prevents low-cost uncertified imports from capturing volume.
- Start-stop and mild-hybrid architectures:Enhanced cyclic durability requirements for absorbed glass mat and lithium-ion battery chemistries are expanding addressable aftermarket revenue per vehicle.
- Sun Belt states:Aging vehicle fleets in Texas, Florida, and Arizona concentrate replacement demand for thermal management and undercarriage components exposed to extreme temperature cycling.
Market Restraints
- Rare earth and platinum group metal volatility:Palladium and rhodium price swings embedded in catalytic converter substrate costs compress margin predictability for exhaust component manufacturers.
- Consolidated OE supplier networks:Tier-1 brake and chassis module producers in Germany and Japan control sensor-integrated replacement channels, limiting independent aftermarket access to diagnostic protocols.
- Right-to-repair legislative friction:OEM restrictions on diagnostic access and parts authentication protocols in multiple U.S. states create compliance complexity for independent repair shops.
Strategic Opportunities
- India's expanding vehicle parc:Second and third ownership cycles for compact passenger vehicles and two-wheelers create underpenetrated demand for friction materials and filtration media priced below premium OE-equivalent tiers.
- Sensor-integrated predictive maintenance:Convergence of telematics platforms with brake wear indicators and oil condition monitoring enables subscription-based parts replenishment before failure.
- California CARB certification reciprocity:Fourteen adopting states create regulatory tailwind for manufacturers holding California emissions compliance, reducing SKU proliferation versus fifty-state fragmentation.
Industry Challenges
- Diagnostic technician certification gaps:Advanced driver assistance system calibration and sensor-integrated brake module servicing require training pipelines that community colleges and vocational programs have not scaled to match demand.
- Multi-material joining complexity:Aluminum-intensive vehicle structures and carbon fiber reinforced plastic body panels demand specialized repair equipment and adhesive bonding protocols that collision shops must capital-deploy to remain insurable.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aftermarket Automotive Parts & Components Market |
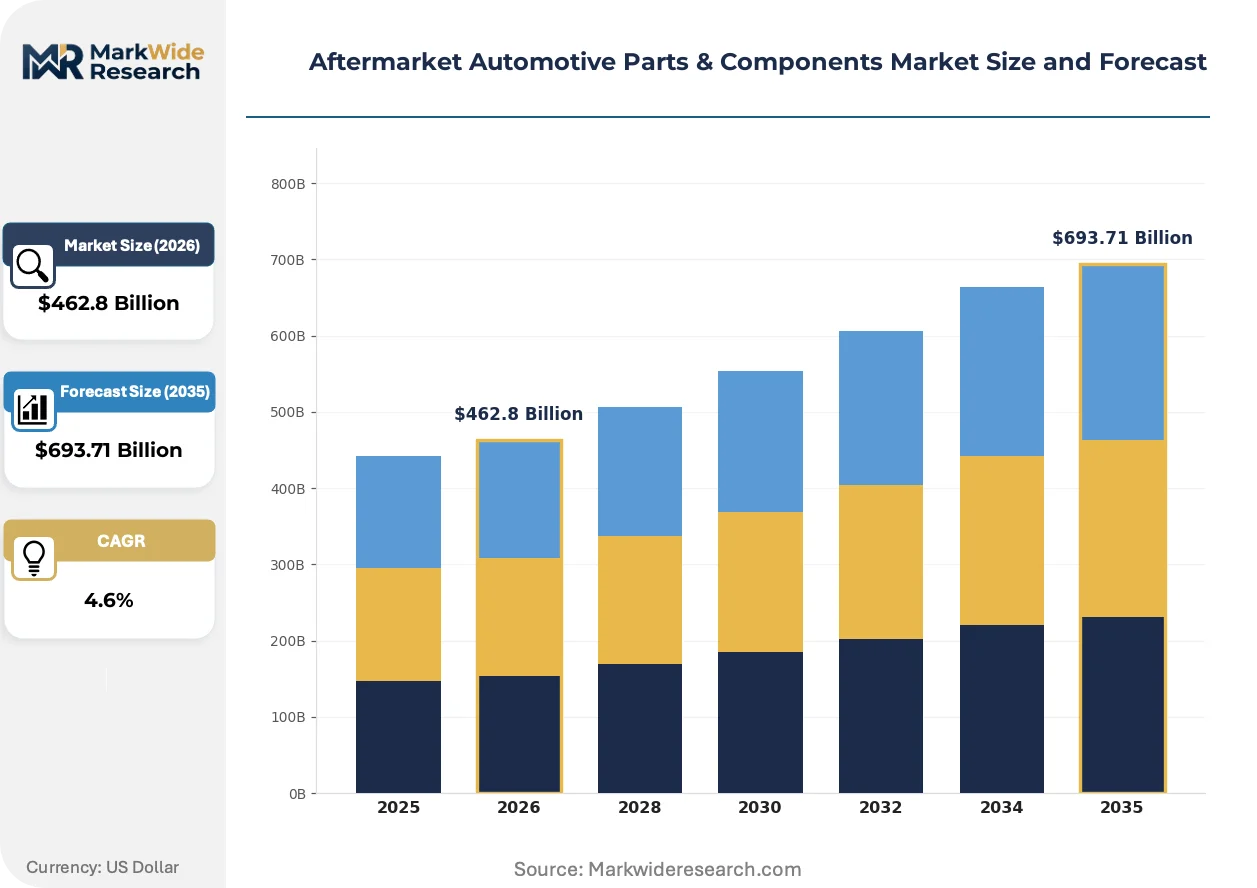
| Market Size in 2026 | $462.8 Billion |
| Market Size in 2035 | $693.71 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brakes, Filters, Batteries, Suspension Kits Technology: Electric, Hybrid, Conventional, Advanced Driver Assistance Systems End User: DIY Consumers, Repair Shops, Fleet Operators, Dealerships Distribution Channel: Online Retail, Specialty Stores, Wholesalers, Direct Sales |
| Companies Covered | Robert Bosch GmbH, Continental AG, ZF Friedrichshafen AG, Denso Corporation, Magna International Inc., Valeo SA, Aisin Seiki Co. Ltd., Tenneco Inc., Advance Auto Parts Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aftermarket Automotive Parts & Components Market Trends and Innovations
Digital commerce platforms and connected vehicle data streams are restructuring how replacement parts are specified, priced, and delivered to service bays and DIY installers.
Modular brake-by-wire architectures are decomposing traditional hydraulic systems into electromechanical corner units with integrated position sensing. Commercial fleet operators in Germany and the Netherlands are piloting these configurations for regenerative braking optimization. The technology is decomposing established aftermarket revenue pools tied to master cylinders, brake lines, and conventional friction hardware.
REACH Annex XVII restrictions on hexavalent chromium in surface treatments are forcing coating substitutions for suspension components and fasteners sold into EU member states. Manufacturers are migrating to trivalent chromium and zinc-nickel alternatives that meet corrosion resistance specifications without SVHC classification. Brake and chassis suppliers with integrated European finishing capacity are capturing specification-driven preference shifts.
Fleet procurement teams are consolidating supplier relationships around integrated brake, filtration, and battery maintenance programs with guaranteed uptime clauses. Independent repair chains in the United States are responding with subscription-based preventive maintenance bundles that lock in parts volume. This concentration is most visible in last-mile delivery and ride-hail vehicle pools operating on compressed replacement cycles.
Aftermarket Automotive Parts & Components Market Segmentation
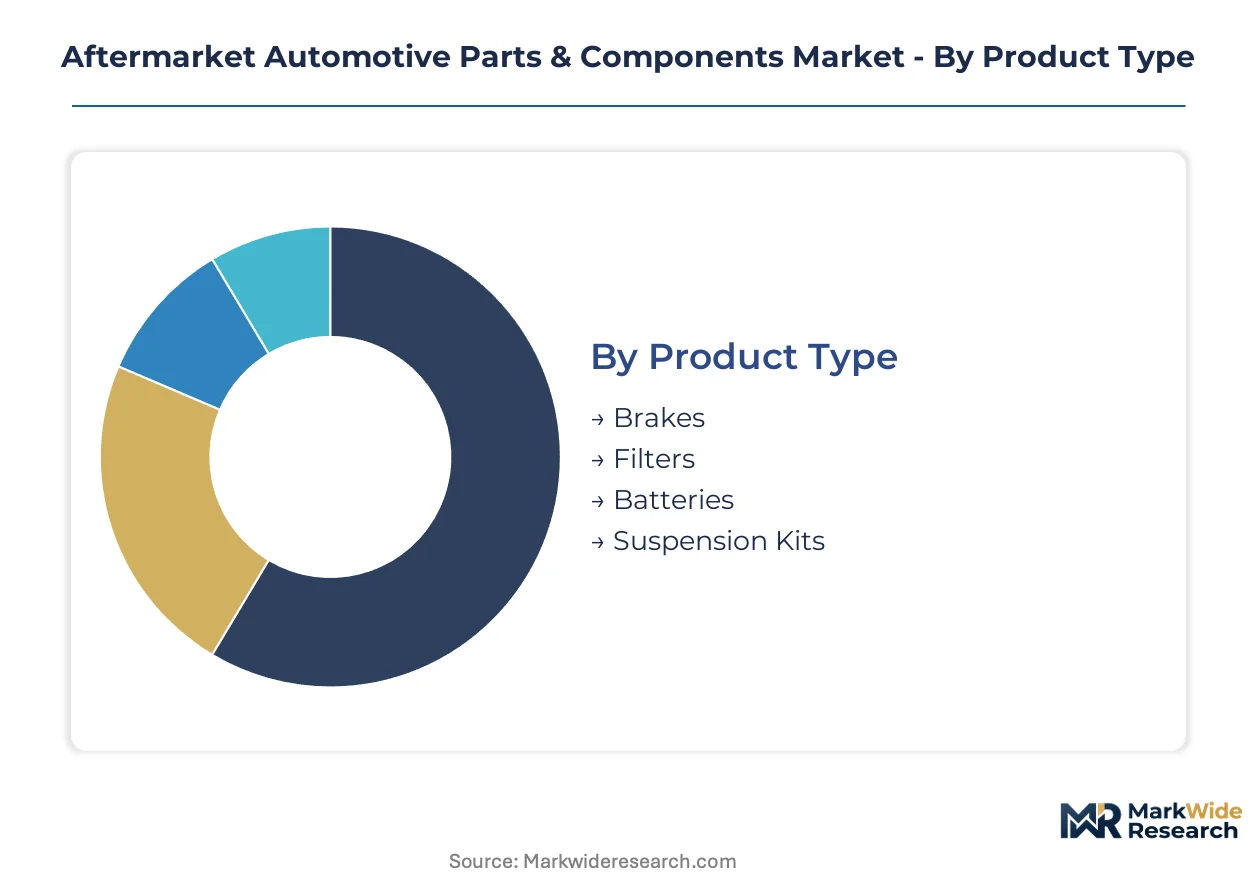
Aftermarket automotive parts & components segment along four critical dimensions that determine pricing power, channel strategy, and regulatory exposure. Product type dictates replacement frequency and margin structure. Technology alignment shapes compatibility requirements and technician training intensity. End user preferences fragment procurement patterns between price-sensitive DIY installers and uptime-guaranteed fleet operators. Distribution channel selection determines geographic reach and inventory velocity.
Product Type:
Brake friction materials and filtration media concentrate manufacturing in Mexico, Poland, and China for export to North American and European service bays. Suspension kits and battery assemblies retain stronger domestic production footprints due to weight-driven logistics economics and hazmat handling requirements.
- Brakes:Friction materials engineered to SAE J661 wear coefficients and FMVSS 135 performance standards. Demand clusters in Texas, Florida, and Arizona where heat-cycling accelerates pad deterioration in aging Sun Belt fleets.
- Filters:Filtration media rated to ISO 4548-12 and ISO 5011 dust capacity specifications for oil, air, and cabin applications. Fleet preventive maintenance programs in Germany and the Netherlands sustain volume pull-through with compressed replacement intervals.
- Batteries:Absorbed glass mat and lithium-ion chemistries optimized for start-stop and mild-hybrid cyclic durability.
- Suspension Kits:Load-rated coil spring and shock absorber assemblies for commercial and performance applications.
Brakes hold the largest share; momentum sits with batteries as electrification architectures expand cyclic durability requirements.
Technology:
Conventional internal combustion systems dominate current aftermarket revenue but face displacement pressure. Electric and hybrid architectures are fragmenting component compatibility matrices and forcing technician reskilling investments.
- Electric:Battery thermal management components and regenerative braking hardware with specialized service protocols. California CARB certification requirements and fourteen adopting states create regulatory tailwind for emissions-compliant replacement parts.
- Hybrid:Dual-powertrain service parts spanning high-voltage battery modules and integrated starter-generator units. Repair shops in Japan and South Korea lead adoption curves due to earlier hybrid fleet penetration.
- Conventional:Established friction, filtration, and ignition components with standardized replacement procedures.
- Advanced Driver Assistance Systems:Sensor calibration equipment and camera module replacements requiring OEM diagnostic access.
Conventional technology retains volume leadership; electric architectures are climbing the fastest as OEM electrification roadmaps compress conventional vehicle parc growth.
End User:
Procurement authority fragments across price-sensitive individual installers, margin-pressed independent shops, and consolidated fleet operators with guaranteed uptime contracts.
- DIY Consumers:Price-driven purchasers of brake pads, filters, and batteries through retail channels with standardized fitment databases.
- Repair Shops:Bay-capacity-constrained buyers prioritizing same-day parts availability and warranty claim support.
- Fleet Operators:Volume-contracted purchasers of preventive maintenance bundles with telematics-integrated replenishment scheduling. Last-mile delivery pools in the United States and long-haul operators in Germany anchor demand concentration.
- Dealerships:OEM-captive service channels with proprietary diagnostic access and parts authentication protocols.
Fleet operators command the steepest expansion trajectory; repair shops retain transaction volume leadership.
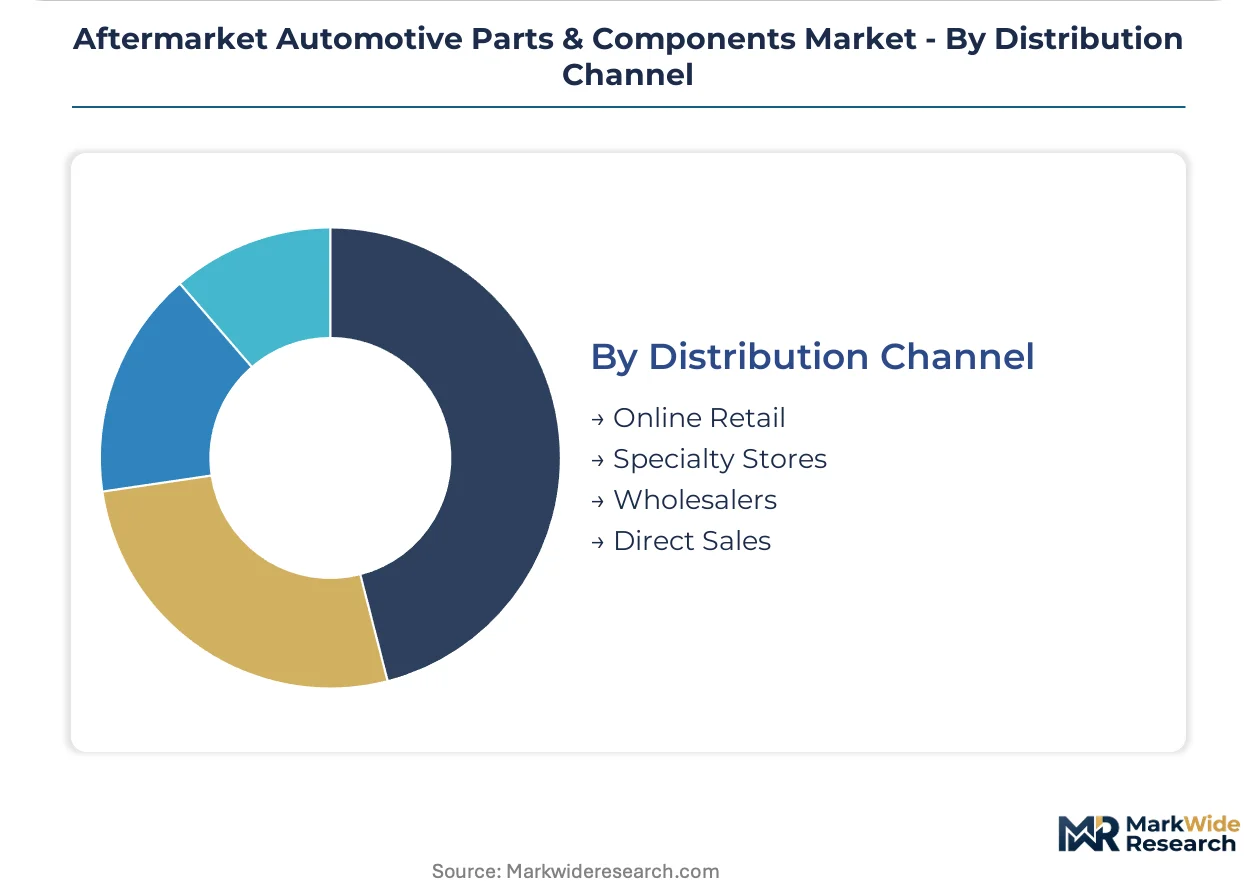
Distribution Channel:
Channel selection determines working capital intensity and geographic coverage radius. Digital platforms are compressing traditional wholesale hierarchies.
- Online Retail:Fitment-matched e-commerce platforms with VIN-specific cataloging and next-day delivery promises. Amazon and specialized automotive marketplaces in the United States and Germany capture DIY and small-shop volume migration.
- Specialty Stores:Counter-staffed locations with technical consultation and same-day pickup for professional installers.
- Wholesalers:Regional distribution networks with inventory consignment programs for high-volume repair chains.
- Direct Sales:Manufacturer-to-fleet contracts bypassing distributor markups for brake, filtration, and battery maintenance programs.
Wholesalers retain share leadership; online retail is gaining share fastest as VIN-accurate fitment algorithms reduce return rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: fleet-heavy markets emphasize uptime-guaranteed maintenance bundles, while DIY-dominant regions prioritize retail availability and price transparency. Regulatory stringency and vehicle parc age further differentiate procurement priorities.
United States
Sun Belt states concentrate replacement demand for thermal management and undercarriage components exposed to extreme temperature cycling. EPA Clean Air Act Section 203 enforcement sustains certified aftermarket manufacturing capacity for catalytic converters. Texas, Florida, and Arizona anchor aging vehicle fleet density with high per-capita car ownership driving brake friction and filtration pull-through.
Germany
Commercial fleet operators compress replacement cycles while demanding integrated brake, filtration, and battery maintenance programs. KBA vehicle inspection mandates sustain stable margin pools for safety-critical components. The Ruhr industrial corridor and Stuttgart region concentrate sensor-integrated brake module production and diagnostic equipment manufacturing.
China
Expanding vehicle parc in second and third ownership cycles creates demand for friction materials and filtration media priced below premium OE-equivalent tiers. MIIT emissions standards and GB certification requirements shape product design for domestic replacement channels. Yangtze River Delta manufacturing clusters dominate brake friction and filtration media export production.
India
Compact passenger vehicle and two-wheeler aftermarket penetration remains underdeveloped relative to vehicle parc scale. BIS quality certification and state-level vehicle fitness regulations create compliance thresholds for organized replacement channels. Maharashtra and Gujarat industrial corridors concentrate friction material and filtration media manufacturing for domestic and export markets.
Japan
Hybrid fleet penetration leads global adoption curves, sustaining specialized service parts demand for high-voltage battery modules and integrated starter-generator units. METI energy efficiency regulations and JIS standards govern replacement component specifications. Kansai and Chubu regions anchor thermal and powertrain component production extending OEM heritage into trusted replacement channels.
Aftermarket Automotive Parts & Components Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding diagnostic protocol access and sensor-integrated module supply. The middle tier fragments across regional brake friction, filtration media, and battery chemistry specialists. Two strategic archetypes dominate: OE-heritage suppliers leveraging OEM trust into replacement channels, and independent specialists competing on price-accessible fitment coverage. Competitive moves concentrate on M&A for diagnostic capability acquisition and geographic expansion into underpenetrated vehicle parc markets.
Among Germany-based integrated suppliers, Robert Bosch GmbH and Continental AG exemplify the OE-heritage archetype with diagnostic equipment ecosystems anchoring service bay loyalty. ZF Friedrichshafen AG occupies a position within the chassis and driveline specialist tier. Japanese manufacturers Denso Corporation and Aisin Seiki Co., Ltd. represent thermal and powertrain component heritage extending into replacement channels. North American distributors Advance Auto Parts Inc. and Tenneco Inc. sit within the scale-driven retail and exhaust component segments respectively, while Magna International Inc. and Valeo SA exemplify diversified global supply positioning across multiple product categories.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| ZF Friedrichshafen AG |
| Denso Corporation |
| Magna International Inc. |
| Valeo SA |
| Aisin Seiki Co. Ltd. |
| Tenneco Inc. |
| Advance Auto Parts Inc. |
| Others |
Pricing and Supply Chain Analysis
Ninety-day inventory cycles for brake friction materials and filtration media concentrate margin pressure on distributors serving independent repair shops. Fleet procurement teams exploit this working capital intensity to extract volume discounts, while specialty stores defend position through same-day availability premiums.
Pricing Analysis
Long-term offtake contracts dominate fleet procurement of brake, filtration, and battery maintenance bundles, compressing spot-market premiums for independent distributors. Price differentiation rests on CARB certification tier and OEM-equivalent quality grade, with California-compliant catalytic converters commanding sustained premiums over uncertified alternatives. Cost compression in economy-tier filtration media intensifies due to Yangtze River Delta manufacturing overcapacity. DIY consumers exhibit highest price sensitivity; fleet operators with guaranteed uptime clauses demonstrate lowest.
Supply Chain Analysis
Sixty-day lead times for sensor-integrated brake modules from Germany and Japan constrain independent aftermarket access to diagnostic protocols. Manufacturing concentrates in Mexico for North American brake friction, Poland for European filtration media, and China for economy-tier components. Raw material dependencies span palladium and rhodium for catalytic substrates, rare earth elements for battery chemistries, and high-grade steel alloys for chassis components. Single-source vulnerability around Tier 1 sensor-integrated modules creates supply risk. Distribution runs through regional wholesalers with inventory consignment programs for high-volume repair chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
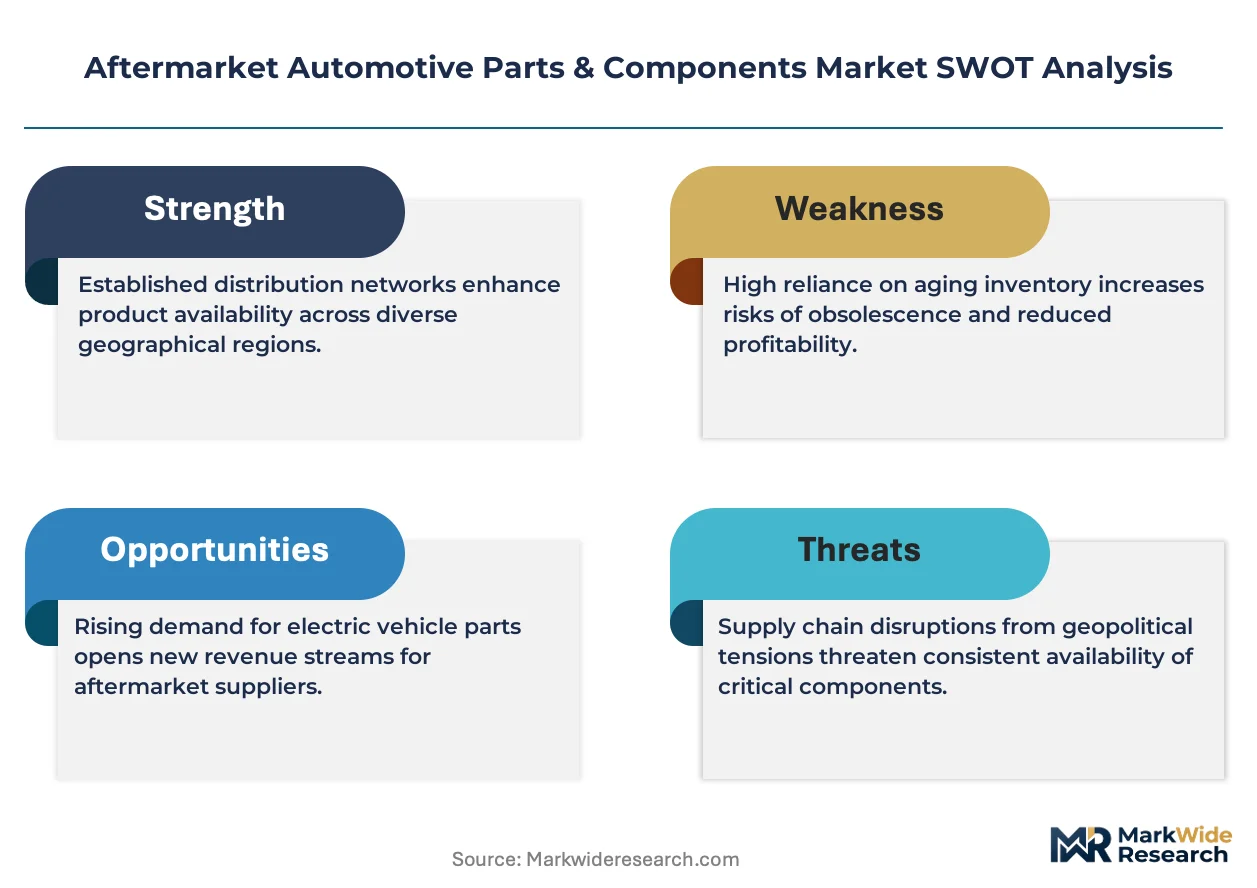
Fragmentation across electrification architectures and right-to-repair legislative friction creates niche opportunities for specialized entrants. Technician certification gaps and diagnostic access restrictions fragment competitive dynamics.
For Market Incumbents: Secure diagnostic protocol licensing from sensor-integrated module producers to anchor service bay loyalty against emerging telematics-based predictive maintenance entrants. Expand captive supply of battery thermal management components through backward integration into lithium-ion cell assembly. Invest in CARB certification reciprocity to reduce SKU proliferation across fourteen adopting states.
For New Entrants and Emerging Players: Predictive maintenance software integration for independent repair shops represents an underserved service layer where incumbents under-serve. Target India's compact passenger vehicle and two-wheeler aftermarket with friction materials priced below premium OE-equivalent tiers. Pursue direct-to-fleet digital platforms with VIN-accurate fitment algorithms to bypass traditional wholesale markups.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because diagnostic capability scarcity and sensor-integrated module access concentrate competitive advantage among OE-heritage suppliers. Acquisition targets include regional brake friction specialists with integrated finishing capacity and telematics-enabled predictive maintenance platforms. Watch EPA enforcement intensity against uncertified catalytic converter imports as inflection indicator for certified aftermarket manufacturing capacity valuation.
| Strategic Initiative | Industry Significance |
|---|---|
| Diagnostic Protocol Licensing Agreement | Secures OEM-equivalent service bay access for sensor-integrated brake and chassis modules. |
| CARB Certification Expansion | Unlocks fourteen-state regulatory reciprocity, reducing exhaust component SKU complexity. |
| Predictive Maintenance Platform Launch | Converges telematics with brake wear indicators for subscription-based parts replenishment. |
| Backward Integration into Battery Cell Assembly | Captures margin pool from start-stop and mild-hybrid cyclic durability demand expansion. |
| Direct-to-Fleet Digital Channel Development | Bypasses wholesale markups through VIN-accurate e-commerce with guaranteed uptime contracts. |
Research Methodology
Operator-level perspectives from aftermarket distributors, fleet procurement managers, independent repair shop owners, and Tier 1 supplier platform engineers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through EPA enforcement disclosures, NHTSA FMVSS compliance databases, IHS Markit vehicle registration data, and CARB certification records. Bottom-up segmentation modeling triangulated against top-down macroeconomic drivers.
Sensitivity analysis across palladium price volatility scenarios and right-to-repair legislative adoption timelines informed projection robustness. The analytical framework modeled product type, technology alignment, end user archetype, and distribution channel dimensions across the analysis window. CAGRs derived from vehicle parc aging curves, electrification penetration rates, and regulatory compliance cost pass-through assumptions. Forecast inputs incorporated fleet replacement cycle compression and technician certification pipeline constraints.
Forecasts assume regulatory continuity in EPA Clean Air Act enforcement and California CARB standards; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
South Korea Automotive Pneumatic Actuators Market
Automotive Components
Iran Automotive Lubricants Market
Automotive Components
Japan Automotive Composites Market
Automotive Components
Global Automotive Plastic Compounding Market
Automotive Components
Automotive Carbon Fiber Market
Automotive Components
India Automotive Sunroof Market
Automotive Components
Asia-Pacific Heat Shrink Tubing for Automotive Market
Automotive Components
Brazil Automotive Composites Market
Automotive Components
Automotive Rear End Module Market
Automotive Components
France Automotive Market
Automotive Components
Japan Automotive Actuators Market
Automotive Components
Italy Automotive Actuators Market
Automotive Components
India Automotive Glass Fiber Composites Market
Automotive Components
Europe Automotive Glass Market
Automotive Components
Platinum Automotive Catalyst Market
Automotive Components
North America Heat Shrink Tubing for Automotive Market