
 Automotive Embedded Telematics Market | 2026-2036
Automotive Embedded Telematics Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Embedded Telematics Market Intelligence
A shift from single-source to multi-source procurement for telematics control units is recalibrating supply chain dynamics for automotive OEMs. This environment allows specialists like Geotab to focus on fleet management software solutions. Meanwhile, established Tier 1 suppliers such as Robert Bosch GmbH leverage their deep automotive systems integration expertise. Continental AG competes by offering end-to-end hardware and software platforms that combine its own components with connectivity services.
Automotive embedded telematics refers to the factory-installed systems that integrate telecommunications and vehicle data processing. These systems typically feature a Telematics Control Unit (TCU) connected to the vehicle's CAN bus to transmit real-time diagnostic and location data. While fleet management applications drive significant volume, the adoption of 5G technology is enabling growth in latency-sensitive services. Usage-based insurance represents the fastest-growing application, creating new revenue models for OEMs and insurance companies.
Regulatory mandates are a primary market catalyst. The European Union's eCall regulation requires automatic emergency response systems, while in the United States, NHTSA rules govern the use of event data recorders. In China, MIIT standards for connected vehicles shape hardware and data protocols. Consequently, navigating the fragmented landscape of data privacy and ownership will be a critical determinant of long-term value capture for all stakeholders.
Market Dynamics
The central dynamic in the automotive embedded telematics market is the tension between hardware commoditization and software-driven value creation. As Telematics Control Units become more standardized, competitive differentiation is shifting towards the data analytics platforms, connected services, and application ecosystems built upon them.
Growth Catalysts
- Regulatory Mandates:Government regulations, such as the European Union's eCall system for automatic emergency calls and China's MIIT standards for intelligent connected vehicles, create a compulsory baseline for telematics adoption in new vehicles.
- 5G Network Deployment:The transition from LTE to 5G connectivity reduces latency and increases bandwidth, enabling more sophisticated vehicle-to-everything (V2X) communication, high-definition map updates, and complex in-vehicle infotainment services.
- Usage-Based Insurance (UBI):The expansion of UBI models provides a direct monetization path for telematics data, incentivizing both consumers and commercial fleet operators to adopt vehicles equipped with data-logging capabilities for potential premium reductions.
Market Restraints
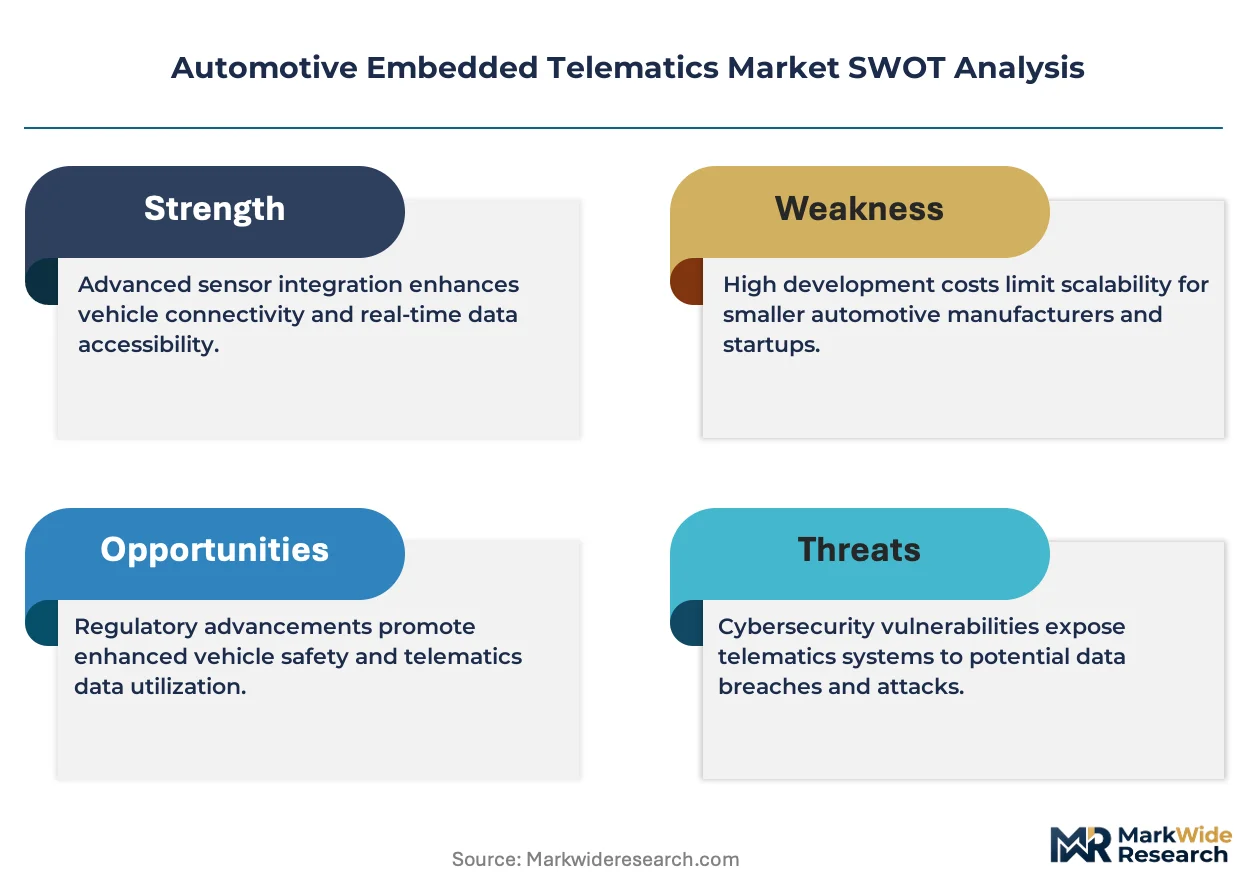
- High Integration Costs:The initial capital expenditure and engineering complexity required to integrate embedded telematics systems with a vehicle's core electronic architecture and CAN bus remain a significant barrier for some automotive OEMs.
- Data Privacy and Security Concerns:Navigating complex data protection regulations like Europe's GDPR creates compliance burdens, while the risk of cybersecurity breaches can erode consumer trust and expose manufacturers to significant liability.
- Lack of V2X Standardization:The absence of a single, globally accepted communication standard for vehicle-to-everything (V2X) technology fragments the market and slows the development of interoperable safety and traffic management applications.
Strategic Opportunities
- Predictive Maintenance Services:Monetizing vehicle diagnostic data by offering predictive maintenance and remote diagnostics services to commercial fleet owners and individual consumers represents a significant recurring revenue opportunity for OEMs.
- ADAS and Telematics Convergence:Integrating telematics data with Advanced Driver-Assistance Systems (ADAS) can create more sophisticated safety features, such as real-time hazard warnings based on data from other vehicles or infrastructure.
- Emerging Market Fleet Management:Significant white space exists in developing economies like Brazil and India, where the formalization of logistics and transportation sectors is driving demand for fleet management solutions for the first time.
Industry Challenges
- Legacy System Integration:A primary operational hurdle is the difficulty of integrating modern, cloud-native telematics platforms with the legacy IT systems and entrenched vehicle electrical architectures prevalent at many established automotive manufacturers.
- Fragmented Data Sovereignty Rules:Managing vehicle data across borders requires navigating a complex patchwork of national data localization and sovereignty laws, complicating the architecture of global connected service platforms.
- Automotive Software Talent Gap:A persistent shortage of software engineers who possess dual expertise in embedded automotive systems and cloud-scale data processing constrains the pace of innovation for vehicle manufacturers and Tier 1 suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Embedded Telematics Market |
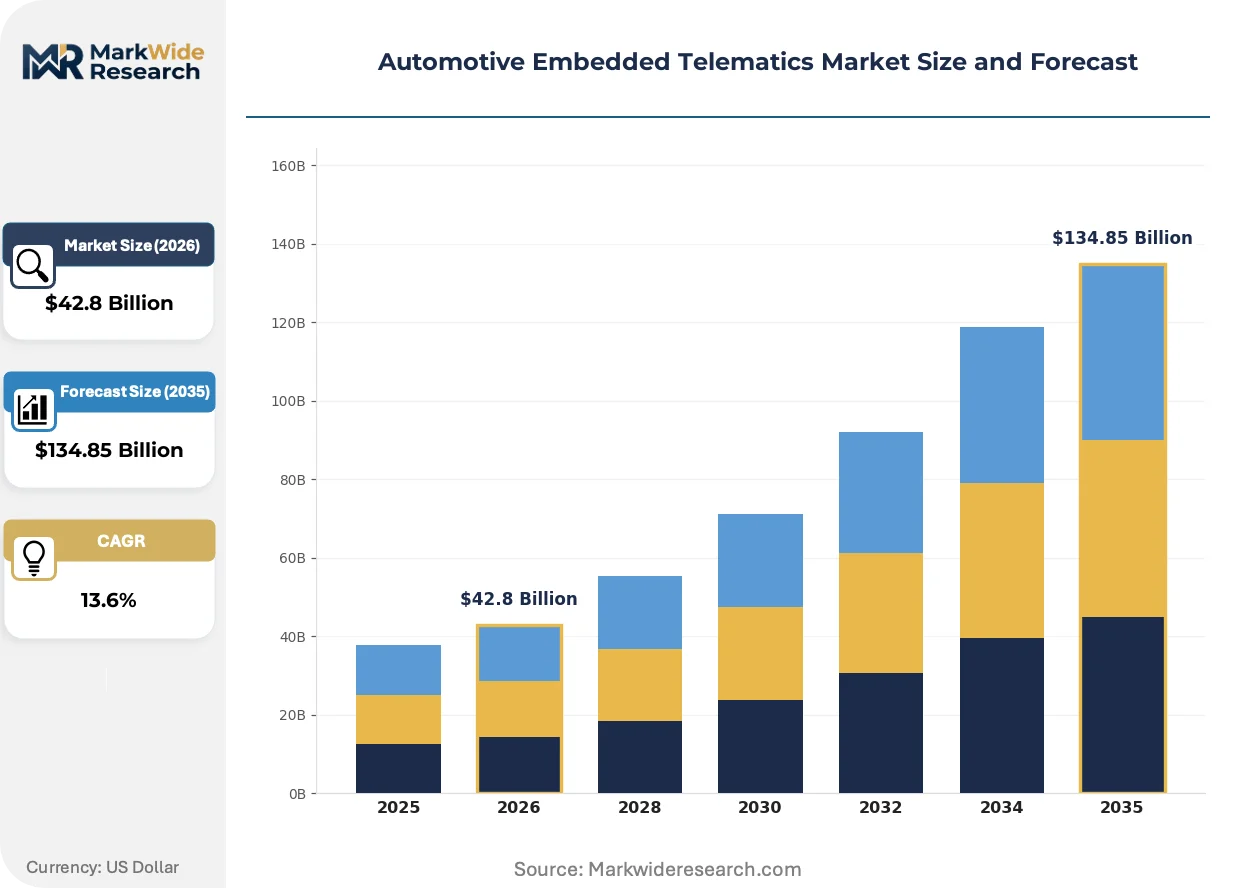
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $134.85 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: GPS Navigation, Fleet Management, Remote Diagnostics, Vehicle Tracking Technology: LTE, 5G, Bluetooth, Short-Range Communication Application: Insurance Telematics, Smart Parking, Usage-Based Insurance, Driver Behavior Monitoring End User: OEMs, Fleet Operators, Insurance Companies, Aftermarket Providers |
| Companies Covered | Continental AG, TomTom, LG Electronics, Verizon Connect, Geotab, HARMAN International, Robert Bosch GmbH, AT&T, Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Embedded Telematics Market Strategic Shifts & Innovations
Software-defined functionality and data monetization are fundamentally altering the market's structure. The focus is shifting from the hardware unit itself to the ecosystem of services, such as predictive maintenance and usage-based insurance, that connectivity enables for OEMs and fleet operators.
The Telematics Control Unit (TCU) is evolving from a simple connectivity gateway to a powerful onboard computing node. Automotive OEMs and commercial fleet operators are adopting these more capable units to support increasingly complex applications. This technological shift is expanding into the domain of edge computing, allowing for real-time data processing within the vehicle for functions like driver behavior analysis and immediate component health alerts.
Rules from the United States' National Highway Traffic Safety Administration (NHTSA) governing the function of event data recorders (EDRs) are influencing system design. This forces manufacturers to standardize data capture protocols related to vehicle dynamics before, during, and after a crash event. The commercial vehicle segment is most affected, engineering telematics systems not only for compliance but also to use the granular data for accident reconstruction and insurance liability assessment.
A transition away from single-supplier hardware agreements toward a multi-source model for telematics components is gaining momentum. This approach unbundles the hardware from the software layer, permitting OEMs to select best-in-class TCUs while developing proprietary service platforms. This pattern is most pronounced in Europe and North America, where automakers are building unique digital ecosystems to avoid vendor lock-in and foster brand loyalty.
Automotive Embedded Telematics Market Segmentation
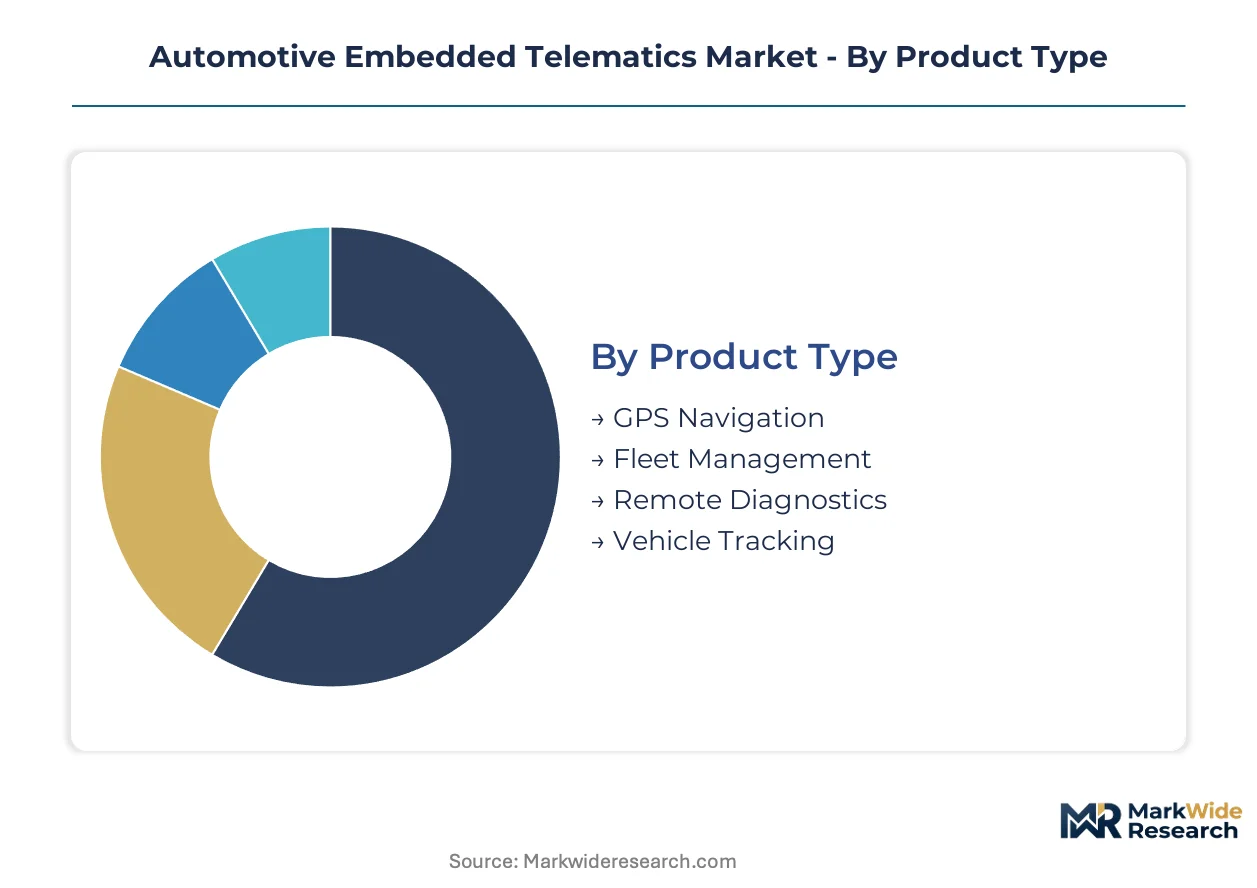
The automotive embedded telematics market comprises diverse segments, each presenting unique value propositions and operational complexities. Understanding these distinctions helps stakeholders identify areas of concentrated demand and emerging opportunities across the connected vehicle ecosystem.
Product Type:
Segments within product type exhibit varied capital requirements, with some demanding substantial upfront investment in hardware and infrastructure.
- Fleet Management:These solutions provide commercial operators with tools for route optimization, asset tracking, and driver behavior monitoring, requiring robust back-end platforms and extensive data processing capabilities. Demand concentrates in the commercial logistics sectors of China and the United States, driven by operational efficiency mandates.
- Remote Diagnostics:Systems that monitor vehicle health and performance remotely, transmitting fault codes and maintenance alerts to manufacturers or service centers, demand sophisticated sensor integration and secure data transmission. This segment sees significant demand from European automotive OEMs seeking to enhance after-sales service and reduce warranty costs.
- GPS Navigation:Integrated in-vehicle systems provide real-time mapping, turn-by-turn directions, and traffic updates, supporting both consumer and commercial vehicle operations.
- Vehicle Tracking:These systems enable real-time location monitoring and historical route analysis, primarily used for asset security, theft recovery, and logistics coordination.
Fleet Management solutions absorb the bulk of installed capacity; Remote Diagnostics is expanding most quickly.
Technology:
Technology choices for telematics systems often depend on the specific application's data throughput and latency requirements.
- 5G:This next-generation cellular technology offers ultra-low latency and high bandwidth, enabling advanced vehicle-to-everything (V2X) communication, over-the-air software updates, and high-definition mapping services. European automotive manufacturers are investing heavily in 5G for future autonomous driving features.
- LTE:Long-Term Evolution (4G) remains the foundational connectivity standard for most embedded telematics systems, providing reliable data transmission for services like eCall, basic navigation, and remote diagnostics. North American markets widely deploy LTE for current generation connected car services.
- Bluetooth:Short-range wireless technology connects in-vehicle devices such as smartphones and wearables to the telematics unit for hands-free communication and infotainment.
- Short-Range Communication:Technologies like Wi-Fi and DSRC (Dedicated Short Range Communications) facilitate vehicle-to-vehicle (V2V) and vehicle-to-infrastructure (V2I) communication over limited distances for safety and traffic management.
5G technology garners substantial investment for next-generation V2X applications; LTE maintains its foundational role for many existing telematics services.
Application:
Application segments cater to distinct customer needs, ranging from individual vehicle owners to large commercial enterprises.
- Usage-Based Insurance:This application collects driving data (e.g., mileage, speed, braking patterns) to personalize insurance premiums, creating new revenue models for insurers and OEMs. Consumer adoption is gaining momentum in the United States and the United Kingdom due to potential cost savings.
- Insurance Telematics:A broader category encompassing data collection for risk assessment, claims processing, and anti-theft services, often mandated or offered as a value-add by insurance providers. European insurance companies are actively integrating these systems to refine actuarial models.
- Smart Parking:Telematics-enabled systems guide drivers to available parking spaces, reduce congestion, and facilitate automated payment, primarily deployed in urban environments.
- Driver Behavior Monitoring:Applications track and analyze driver performance metrics to promote safer driving habits, reduce fuel consumption, and assess training needs, particularly for commercial fleets.
Growth in Usage-Based Insurance is driven by monetization opportunities for OEMs and insurers; Insurance Telematics follows closely with broader adoption.
End User:
End-user segments concentrate demand based on fleet size, regulatory compliance, and service integration capabilities.
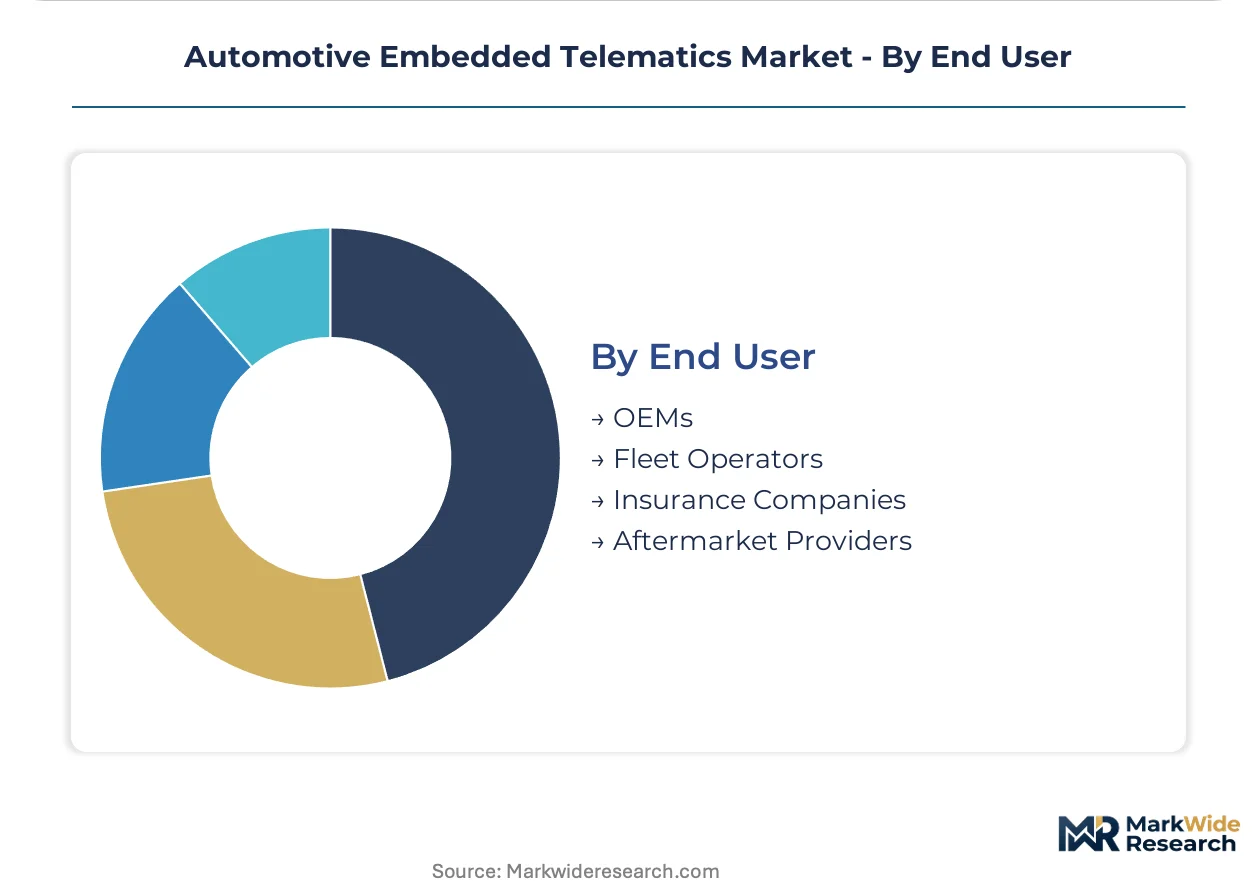
- Fleet Operators:Commercial entities managing vehicle fleets for logistics, transportation, and field services are primary adopters of telematics for operational efficiency, compliance, and asset management. The formalization of logistics in India and Brazil is fueling this segment's expansion.
- OEMs:Automotive Original Equipment Manufacturers integrate telematics systems at the factory level to enable connected services, enhance brand loyalty, and gather vehicle performance data. German and Japanese automotive giants lead in leveraging telematics for service differentiation.
- Insurance Companies:These firms utilize telematics data for risk assessment, premium calculation, and claims management, creating new product offerings based on driver behavior.
- Aftermarket Providers:Independent companies offer telematics solutions that can be installed in vehicles post-purchase, catering to older vehicle models or specific niche applications not covered by OEM offerings.
The largest volumes are recorded by Fleet Operators; Insurance Companies show substantial future potential for data-driven services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's significant demand concentration anchors the global automotive embedded telematics market, driven by its expansive automotive manufacturing base and government-led intelligent connected vehicle initiatives. This emphasis on domestic production and technological advancement positions China as a critical growth engine for telematics solutions. Other major economies also contribute substantially through regulatory mandates and technological adoption.
United States
Demand for embedded telematics in the United States stems from commercial fleet management solutions and the expanding usage-based insurance sector. NHTSA rules govern the use of event data recorders, influencing system design for accident reconstruction and liability assessment. Detroit, Michigan, continues as a hub for automotive innovation, with OEMs investing in advanced telematics integration for new vehicle models.
Germany
Germany's automotive industry drives strong demand for embedded telematics, particularly for advanced remote diagnostics and 5G connectivity for future autonomous driving features. The European Union's eCall regulation mandates automatic emergency response systems, ensuring a baseline adoption for all new vehicles. Stuttgart and Munich host major automotive manufacturers and Tier 1 suppliers, fostering collaboration on next-generation telematics platforms.
China
China exhibits concentrated demand for embedded telematics, propelled by government initiatives for intelligent connected vehicles and the rapid growth of its domestic automotive market. MIIT standards for connected vehicles shape hardware and data protocols, creating a unique regulatory landscape. Major automotive production centers like Shanghai and Chongqing are key areas for telematics system deployment and innovation.
Japan
Japan's automotive sector prioritizes telematics for enhancing in-vehicle infotainment, navigation, and advanced driver-assistance systems (ADAS). METI standards influence the development of connected car technologies, promoting safety and efficiency. Tokyo and Nagoya serve as critical centers for automotive R&D and manufacturing, integrating sophisticated telematics solutions into vehicle designs.
India
India's demand for automotive embedded telematics is accelerating, primarily driven by the formalization of its logistics sector and the need for efficient fleet management. The country's regulatory bodies are increasingly focusing on vehicle safety and data standards, influencing telematics adoption. Major automotive manufacturing hubs such as Chennai and Pune are seeing increased integration of telematics systems in commercial and passenger vehicles.
Automotive Embedded Telematics Market Key Industry Players
Global majors compete with regional champions across the automotive embedded telematics market, creating a landscape characterized by both consolidation in core hardware and fragmentation in software services. The market structure features established Tier 1 automotive suppliers, specialized software providers, and telecommunications companies. Competitive differentiation often stems from deep systems integration expertise or agile software development capabilities, with key competitive moves including strategic partnerships and portfolio diversification.
Specialists in connected car platforms like Continental AG and Robert Bosch GmbH exemplify the deep automotive systems integration expertise required to deliver end-to-end hardware and software solutions. Geotab, a Canadian company, represents the focused software-as-a-service providers, concentrating on fleet management software solutions. These players anchor different segments of the value chain, from foundational hardware to sophisticated data analytics platforms, demonstrating varied approaches to capturing market share within this evolving industry.
| Leading Market Players |
|---|
| Continental AG |
| TomTom |
| LG Electronics |
| Verizon Connect |
| Geotab |
| HARMAN International |
| Robert Bosch GmbH |
| AT&T |
| Denso Corporation |
Cost & Logistics Intelligence
China's dual carbon goals, driving demand for efficient fleet management solutions, gate both qualified supply of advanced telematics systems and premium-tier pricing access for compliant hardware and software. This regulatory push incentivizes manufacturers to integrate telematics for route optimization and reduced emissions. Such mandates influence procurement decisions and pricing strategies across the automotive embedded telematics value chain.
Pricing Analysis
Warranty and service bundling significantly shapes pricing within the automotive embedded telematics market, influencing what is included versus unbundled in core offerings. Subscription-based SaaS models dominate for software-driven services like predictive maintenance and fleet management. Price differentiation stems from the level of after-sales service integration and customization for specific fleet sizes or OEM requirements. Pricing softness arises from hardware commoditization, particularly for standard Telematics Control Units. Commercial fleet operators exhibit higher price sensitivity compared to automotive OEMs, who prioritize brand loyalty and feature differentiation.
Supply Chain Analysis
Semiconductor component supply for Telematics Control Units (TCUs) primarily rests on Asian manufacturers, particularly in Taiwan and South Korea, with significant assembly in China. Key raw material dependencies include specialized connectivity modules (5G/LTE) and sensor arrays for data collection. Single-source vulnerability for critical components presents a structural risk, though the industry is transitioning towards a multi-source procurement model for TCUs. Distribution runs through direct sales channels to automotive OEMs for factory-installed systems and through independent aftermarket providers for post-purchase installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive embedded telematics market is rapidly becoming a vertical-integration race, with players actively pursuing software-defined functionality as a key upstream lever. This shift allows for greater control over service offerings and data monetization, driving strategic investment across the value chain.
For Market Incumbents:
Anticipate continued hardware commoditization by deepening automotive systems integration expertise and investing in proprietary software platforms. Focus R&D on edge computing capabilities within TCUs to enable real-time data processing and advanced V2X applications. Develop comprehensive ecosystem partnerships to counter the talent gap in embedded software engineering. This strategy mitigates margin pressure from standardized hardware and enhances differentiation through unique service offerings.
For New Entrants and Emerging Players:
Aftermarket providers represent a penetrable segment, offering significant white-space opportunities in emerging markets like India and Brazil for fleet management solutions. Target specialized usage-based insurance (UBI) applications by leveraging advanced data analytics for niche segments. A SaaS-based go-to-market angle, focusing on flexible subscription models, can attract small to medium-sized fleet operators seeking cost-effective telematics. Focus on specific regional regulatory compliance to gain a competitive edge.
For Investors and Strategic Acquirers:
Standardization of V2X communication protocols is the leading indicator that will unlock significant long-term value in the automotive embedded telematics market over the next five to ten years. Target acquisition archetypes include specialized software-as-a-service providers with robust data analytics capabilities or developers of cutting-edge V2X technology. Look for firms with strong intellectual property in connected services or those addressing critical cybersecurity challenges. This approach capitalizes on the market's shift towards software-driven monetization.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Enhances in-vehicle computing capabilities for advanced applications and future autonomous driving features. |
| Platform Standardization | Reduces development costs for automotive OEMs and fosters interoperability across diverse telematics systems. |
| Strategic Partnership | Integrates connectivity services with automotive systems for end-to-end solutions, leveraging complementary expertise. |
| Acquisition of Specialist Firm | Expands expertise in data analytics or specific V2X technologies, accelerating portfolio diversification. |
| Geographic Manufacturing Footprint | Optimizes supply chain resilience for critical components like TCUs, mitigating geopolitical risks. |
Research Approach
Document review covered vehicle production databases, IHS Markit registration data, government regulatory documents from NHTSA and MIIT, and financial filings of public companies, complemented by interviews with OEM platform engineers, fleet managers, insurance actuaries, and Tier 1 supplier R&D leads. This primary research provided qualitative insights into market dynamics and technological trends. The data was triangulated using both bottom-up and top-down approaches to ensure accuracy and completeness of market sizing.
Forecasted volume and value outputs were generated through a proprietary analytical framework applied across the analysis window, integrating historical data with projected market growth factors. Key segmentation dimensions modeled included product type, technology, application, end user, and regional regulatory frameworks. Compound Annual Growth Rates (CAGRs) were derived from a comprehensive assessment of market drivers, restraints, and strategic opportunities. Industry-specific forecast inputs included 5G network deployment rates and regulatory mandate timelines.
Caveats apply where geopolitical disruptions affecting semiconductor supply or rapid shifts in data privacy regulations could materially shift the outlook for the automotive embedded telematics market. Forecasts reflect assumptions documented through extensive primary and secondary research. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Telematics-Linked Fleet Battery Health Management Systems Market
Telematics and Infotainment
C-V2X OBU Market
Telematics and Infotainment
Europe Commercial Telematics Market
Telematics and Infotainment
Global Vehicle Fleet Communication Market
Telematics and Infotainment
In-Taxi Digital Signage Market
Telematics and Infotainment
Telematics and Connectivity Control Unit Systems Market
Telematics and Infotainment
Global Car Digital Cockpit Market
Telematics and Infotainment
Intelligent Transport Systems (ITS) Market
Telematics and Infotainment
Europe Dashboard Camera Market
Telematics and Infotainment
Mobile Resource Management (MRM) Market
Telematics and Infotainment
Global Car Sharing Telematics Market
Telematics and Infotainment
Asia Pacific Automotive Infotainment Systems Market
Telematics and Infotainment
Infotainment System UX and Latency Test Platforms for Connected Vehicles Market
Telematics and Infotainment
In-Cabin Lighting-Climate-Audio Synchronized Experience Systems Market
Telematics and Infotainment
Edge Computing in Automotive Market
Telematics and Infotainment
India Connected Car Market