
 In-Taxi Digital Signage Market | 2026-2036
In-Taxi Digital Signage Market Size, Share, and Industry Trends Forecast 2026-2036
In-Taxi Digital Signage Market Foresight
Buyer concentration among fleet management services is hardening as large taxi operators consolidate purchasing decisions across thousands of vehicles. Vugo leverages its programmatic advertising stack to compete for national fleet contracts in North America. Samsung Electronics sustains technology leadership through ruggedized display portfolios purpose-built for high-vibration automotive environments.
In-taxi digital signage encompasses networked visual display systems mounted within passenger compartments, typically featuring 10- to 15-inch high-brightness LCD or LED panels with ambient light sensors and cellular connectivity for remote content management. These systems deliver targeted advertising, route information, and entertainment to captive audiences during transit. LCD Displays dominate installed volume due to cost efficiency and proven durability in fleet conditions, while Cloud-Based technology architectures capture expanding share as operators prioritize centralized content scheduling and real-time campaign analytics. LED Displays command premium positioning in luxury fleet segments where power efficiency and slim form factors justify higher hardware investment.
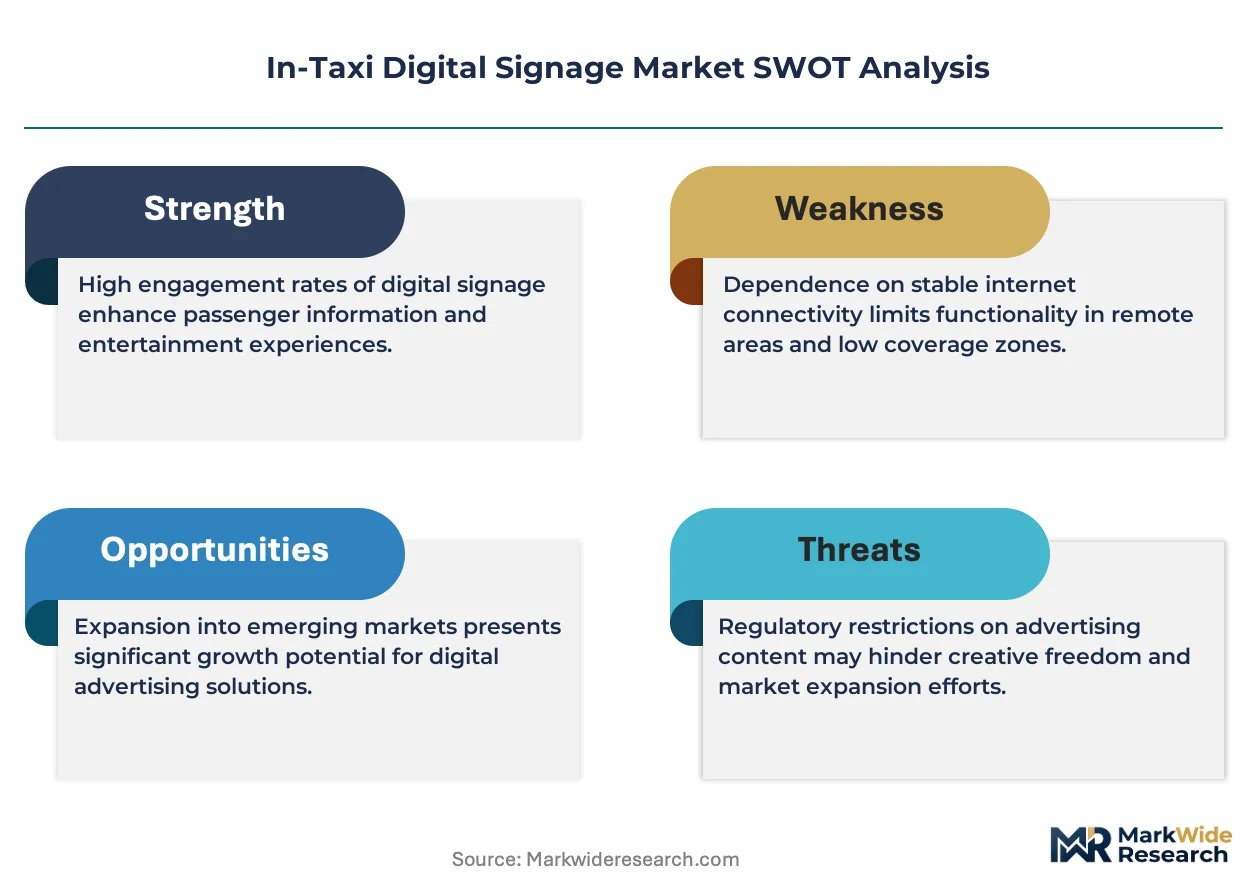
The FCC governs electromagnetic emissions and wireless communication protocols for connected taxi displays in the United States, while India's TRAI shapes data transmission frameworks affecting cloud-content delivery to mobile fleets. EASA guidelines across Europe influence mounting safety standards and driver distraction thresholds for in-vehicle screen placement. Stakeholders must weigh regulatory fragmentation against the operational benefits of unified hardware platforms that can adapt to jurisdiction-specific certification requirements without full redesign cycles.
Market Dynamics
Fleet management consolidation is compressing procurement cycles as operators seek unified passenger engagement platforms across multi-thousand vehicle deployments. The shift from siloed hardware purchases to integrated software-as-a-service contracts is restructuring vendor relationships and margin distribution across the value chain.
Growth Catalysts
- TRAI's connected vehicle framework:India's telecommunications regulator has established data transmission standards that enable cloud-based content delivery to mobile taxi fleets, accelerating infrastructure deployment in urban corridors.
- Programmatic advertising integration:Real-time bidding platforms are linking captive in-vehicle audiences with location-triggered campaigns, creating new revenue streams for fleet operators.
- High-vibration display durability:Ruggedized LCD panels with ambient light sensors now withstand automotive shock loads, extending replacement cycles and reducing total cost of ownership.
Market Restraints
- FCC electromagnetic certification costs:Hardware manufacturers face extended testing timelines for vehicular wireless displays, inflating pre-market compliance expenditures.
- Display panel supply concentration:Specialized automotive-grade screen production clusters in East Asian manufacturing hubs create vulnerability to regional logistics disruptions.
- Driver distraction thresholds:EASA mounting safety standards restrict screen placement angles and brightness levels, limiting design flexibility for premium cabin configurations.
Strategic Opportunities
- Underpenetrated secondary Indian cities:Tier-2 and Tier-3 urban taxi markets lack connected fleet infrastructure, presenting first-mover expansion potential for integrated signage platforms.
- 5G-Edge convergence:Low-latency cellular networks combined with vehicle-edge computing enable interactive passenger experiences and real-time personalization.
- EU Green Deal procurement incentives:Carbon-efficient digital retrofit programs subsidize fleet modernization, lowering adoption barriers for energy-optimized LED display systems.
Industry Challenges
- Embedded software talent scarcity:Fleet operators struggle to recruit automotive UX developers capable of integrating cellular modems with content management systems.
- Legacy dispatch system interoperability:New signage platforms must interface with heterogeneous taxi meter and routing software, complicating deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In-Taxi Digital Signage Market |
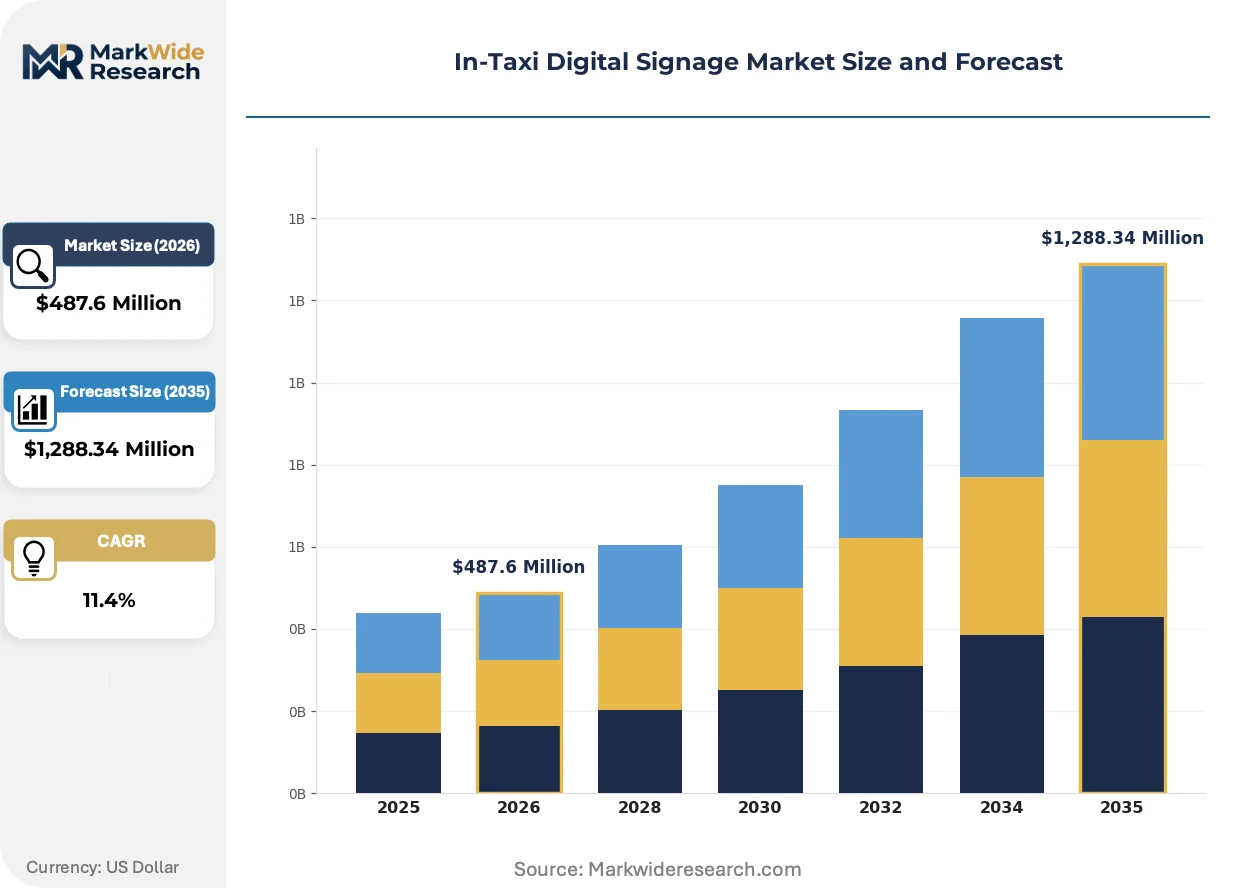
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,288.34 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LCD Displays, LED Displays, Projection Systems, Digital Billboards Technology: Cloud-Based, On-Premise, Internet of Things, Augmented Reality End User: Taxi Operators, Advertising Agencies, Media Companies, Fleet Management Services Content Type: Promotional Ads, Informational Content, Entertainment, Real-Time Updates |
| Companies Covered | Curb Mobility, LLC, Navori SA, Vugo, VeriFone Holdings Inc., Apple Inc., Firefly, 42 Gears Mobility Systems Private Limited, Adomni, Inc., Samsung Electronics Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In-Taxi Digital Signage Market Shifts & Advancements
Cloud-native content architectures are displacing on-premise server installations, enabling centralized campaign orchestration across dispersed vehicle fleets. This shift is compressing hardware margins while expanding recurring software revenue pools.
Edge-to-cloud synchronization is unifying real-time passenger analytics with centralized ad inventory management. Fleet operators in North America are adopting these architectures fastest, consolidating previously fragmented data streams into single-pane campaign dashboards. The technology is unifying what were separate hardware procurement and media sales functions into integrated platform subscriptions.
India's TRAI has issued specific guidelines on vehicular data localization, mandating domestic server storage for passenger-facing content delivery. This policy is fragmenting previously global cloud architectures, forcing operators to establish in-country infrastructure partnerships. Domestic fleet aggregators are responding by prioritizing vendors with certified local data centers.
Buyer committees now specify outcome-based performance metrics rather than hardware specifications alone. Large taxi fleet managers in Mumbai and Delhi evaluate vendors on passenger engagement duration and ad click-through rates, not display brightness or resolution. This behavioral shift is most visible in India, where regulatory momentum on connected infrastructure coincides with operator pressure for measurable media returns.
In-Taxi Digital Signage Market Segmentation
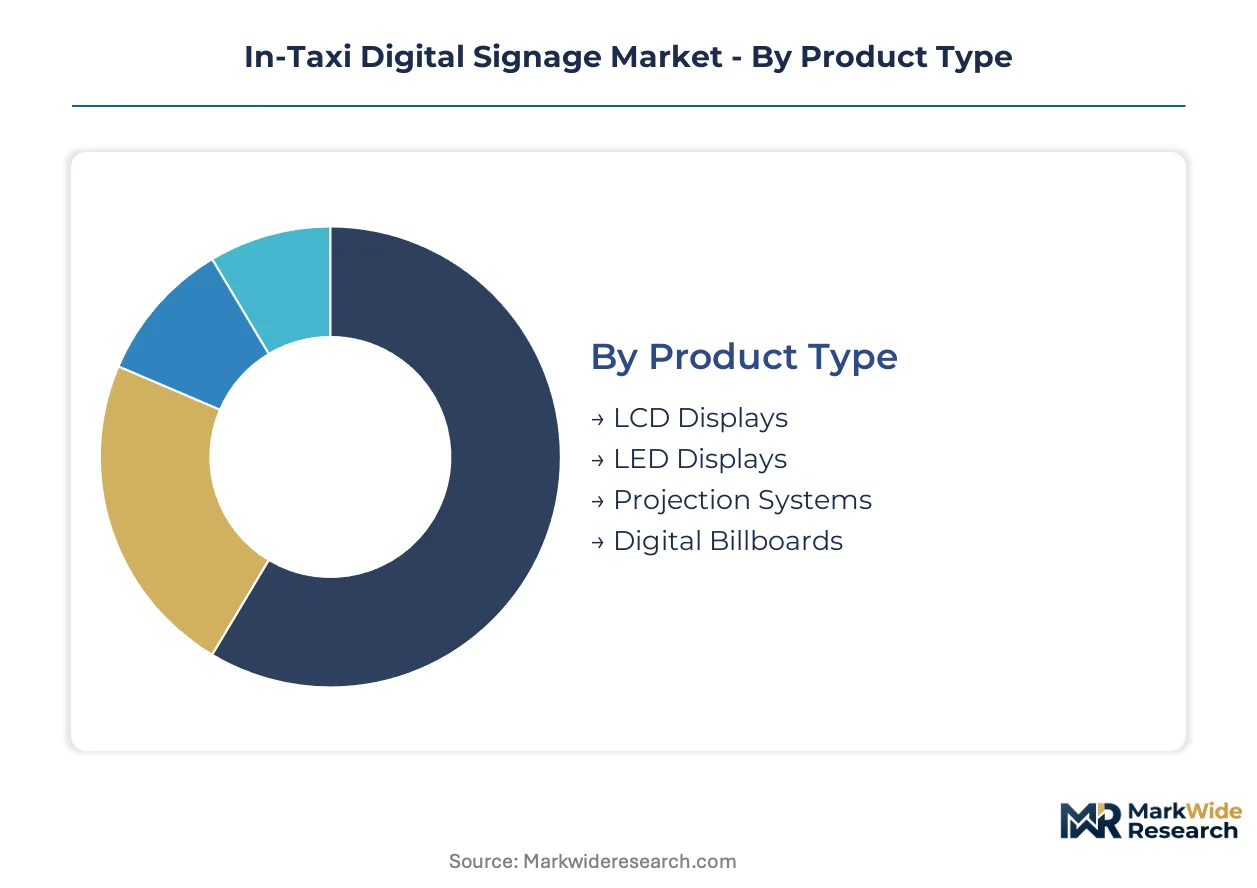
Segmentation reveals how procurement decisions fragment across hardware durability requirements, software deployment models, and buyer sophistication levels. Fleet operators prioritize replacement-cycle economics while advertising agencies emphasize real-time content flexibility.
Product Type:
Upgrade cycles vary sharply by display technology, with vibration tolerance and ambient light performance driving replacement timing across fleet conditions.
- LCD Displays:Ruggedized panels with ambient light sensors dominate fleet installations due to proven durability under automotive shock loads. Demand concentrates among large taxi operators in India seeking cost-efficient refresh cycles across high-mileage vehicle pools.
- LED Displays:Slim-form-factor panels with superior power efficiency command premium positioning in luxury fleet segments. Adoption clusters with operators in the United States pursuing EASA-aligned mounting standards for premium cabin configurations.
- Projection Systems:Compact laser-based units enable flexible mounting in compact vehicle architectures.
- Digital Billboards:Large-format exterior-facing displays serve rooftop advertising applications in select urban markets.
LCD Displays sits at the top of the volume ranking, with LED Displays climbing the fastest.
Technology:
Deployment architecture determines margin distribution between hardware vendors and software providers across the value chain.
- Cloud-Based:Centralized content scheduling with cellular connectivity enables real-time campaign analytics. Fleet management services in North America drive adoption, consolidating previously fragmented data streams into unified subscription platforms.
- On-Premise:Local server installations persist among operators with legacy infrastructure investments and data sovereignty requirements.
- Internet of Things:Sensor-integrated displays capture passenger engagement metrics and vehicle telemetry for dynamic content triggering.
- Augmented Reality:Overlay technologies enable interactive destination previews and gamified advertising experiences in pilot deployments.
Cloud-Based architecture holds the largest installed base, while Internet of Things integration is gaining share fastest.
End User:
Buyer sophistication shapes contract structures from hardware procurement to outcome-based performance agreements.
- Fleet Management Services:Consolidated purchasing across multi-thousand vehicle deployments compresses procurement cycles and demands integrated passenger engagement platforms. Large operators in Mumbai and Delhi now specify engagement duration metrics rather than display specifications alone.
- Taxi Operators:Individual and small-fleet owners prioritize upfront hardware cost over recurring software subscriptions.
- Advertising Agencies:Programmatic buying desks seek location-triggered inventory with verified impression data.
- Media Companies:Content owners require direct publisher relationships and brand safety controls for in-vehicle inventory.
Fleet Management Services dominates contract value, with Advertising Agencies expanding most quickly into programmatic integration.
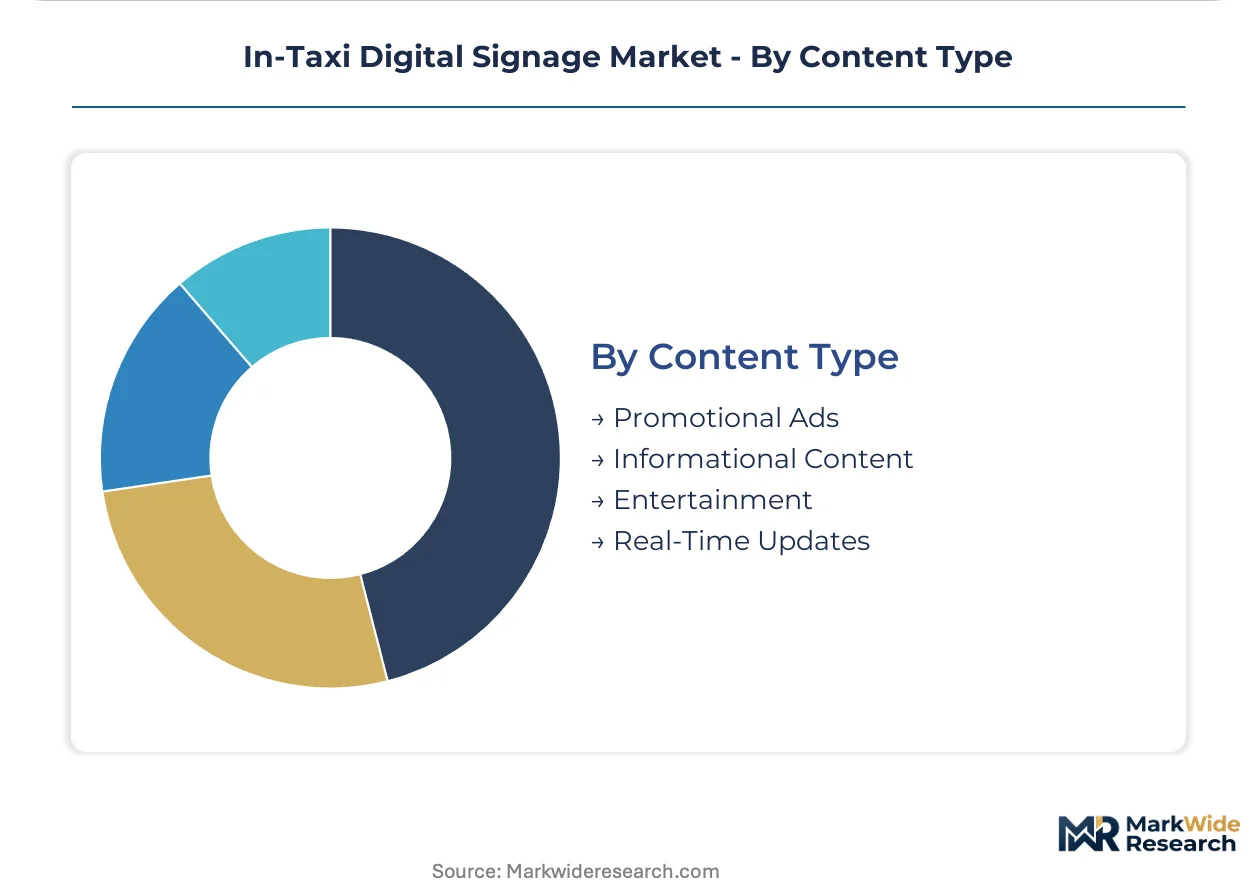
Content Type:
Content category determines hardware specification requirements for refresh rates, color accuracy, and interactivity support.
- Promotional Ads:Location-targeted campaigns with dynamic creative optimization generate direct revenue for fleet operators. India's TRAI-connected vehicle framework accelerates deployment in urban corridors where real-time bidding platforms link captive audiences with advertisers.
- Informational Content:Route updates and service notifications reduce perceived wait times and improve passenger satisfaction scores.
- Entertainment:Short-form video and gaming content demands higher processing capability and storage capacity in head-unit hardware.
- Real-Time Updates:Traffic, weather, and transit integration requires low-latency data pipelines and edge-computing capability.
Promotional Ads generates the highest revenue per impression, with Real-Time Updates showing the steepest expansion trajectory as 5G-Edge convergence matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's regulatory momentum on connected vehicle infrastructure contrasts with the United States' emphasis on electromagnetic certification standards, illustrating how divergent policy frameworks shape deployment velocity across major markets.
United States
Fleet management consolidation drives demand for integrated passenger engagement platforms across urban taxi corridors. The FCC governs electromagnetic emissions and wireless communication protocols for connected taxi displays, extending hardware certification timelines. New York City's dense ride-hail ecosystem anchors national adoption of programmatic advertising systems.
India
Urban taxi aggregators in Mumbai and Delhi specify outcome-based performance metrics rather than hardware specifications alone. TRAI's connected vehicle framework establishes data transmission standards enabling cloud-based content delivery to mobile fleets. Tier-2 cities including Pune and Hyderabad present first-mover expansion potential for integrated signage platforms.
Germany
Luxury fleet operators pursue premium cabin configurations with EASA-aligned mounting standards for in-vehicle screen placement. The EU Green Deal subsidizes carbon-efficient digital retrofit programs for fleet modernization. Berlin's ride-hail ecosystem drives demand for energy-optimized LED display systems.
Japan
High-vibration display durability requirements shape procurement decisions among precision-oriented fleet operators. METI guidelines influence automotive-grade screen certification for connected vehicle deployments. Tokyo's dense urban taxi network concentrates demand for ruggedized LCD panels with ambient light sensors.
United Kingdom
Advertising agencies seek location-triggered inventory with verified impression data across London's black cab fleet. GDPR compliance requirements shape data localization strategies for passenger-facing content delivery. The Greater Manchester area emerges as a testing ground for 5G-edge convergence in interactive passenger experiences.
In-Taxi Digital Signage Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across hardware manufacturing and software platform layers. The vendor base spans three tiers: multinational electronics manufacturers with automotive display portfolios, programmatic advertising technology providers, and fleet-specific mobility software vendors. Strategic moves concentrate on cloud-native content architecture partnerships and vertical integration into cellular connectivity modules.
Among North American mobility technology providers, Curb Mobility, Vugo, and Firefly exemplify the pure-play specialist archetype. Samsung Electronics Co., Ltd. anchors the diversified electronics manufacturer tier with ruggedized display portfolios. Navori SA occupies a position within the digital signage software specialist segment. These three company groupings represent the dominant competitive vectors shaping procurement relationships with consolidated fleet operators.
| Leading Market Players |
|---|
| Curb Mobility, LLC |
| Navori SA |
| Vugo |
| VeriFone Holdings Inc. |
| Apple Inc. |
| Firefly |
| 42 Gears Mobility Systems Private Limited |
| Adomni, Inc. |
| Samsung Electronics Co., Ltd. |
| Others |
Supply & Pricing Matrix
Cloud-native content architectures displacing on-premise server installations simultaneously compress hardware margins and concentrate purchasing leverage among consolidated fleet operators across North America and India. This technology transition redraws cost economics toward recurring software subscriptions while fragmenting display panel procurement across automotive-grade certification tiers.
Pricing Analysis
Capacity additions in South Korea and Taiwan are reshaping price floors for ruggedized LCD panels as automotive-grade display production scales. Three-tier pricing structure across premium LED, standard LCD, and economy projection systems differentiates by vibration tolerance and ambient light performance. Cost compression in standard LCD tiers is intensifying because fleet operators in India consolidate thousand-vehicle procurement decisions. Individual taxi operators show highest price sensitivity, while fleet management services prioritize total cost of ownership over upfront hardware expenditure.
Supply Chain Analysis
Refurbishment flows for field-failed displays create secondary supply channels extending replacement cycles among cost-conscious operators. Manufacturing concentrates in South Korea, Taiwan, and China for specialized automotive-grade screen production. Supply chains draw from indium tin oxide, polarizing films, and cellular modem chipsets as critical inputs. Single-source vulnerability in East Asian logistics corridors threatens just-in-time delivery schedules for North American fleet deployments. Distribution runs through direct OEM relationships with major fleet operators and tiered distributor networks serving fragmented taxi owner segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on software subscription attach rates climbing alongside hardware cost-down curves from automotive display commoditization.
For Market Incumbents: Deepen cellular connectivity module integration to capture recurring revenue streams as hardware margins compress. Samsung Electronics and diversified electronics manufacturers should consolidate cloud-native platform partnerships before pure-play software vendors lock fleet operator relationships. Certification investment in FCC electromagnetic compliance and EASA mounting standards creates defensive moats against emerging Asian display specialists. For New Entrants and Emerging Players: Launch via white-label partnerships with domestic fleet aggregators in India's Tier-2 cities including Pune and Hyderabad. Underpenetrated secondary Indian urban corridors lack connected infrastructure and present first-mover expansion potential. Target outcome-based performance contracts emphasizing passenger engagement metrics rather than hardware specifications. For Investors and Strategic Acquirers: Valuations sit cheapest among fleet-specific mobility software vendors lacking cellular hardware integration. Long-term viability favors platforms combining programmatic advertising stacks with certified vehicular data localization for TRAI compliance. Monitor 5G-edge convergence deployment velocity in Greater Manchester and Tokyo as inflection indicator for interactive passenger experience monetization.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Centralized campaign orchestration compresses hardware margins while expanding recurring software revenue pools across dispersed fleets. |
| Cellular Modem Integration | In-house production of connectivity modules captures value previously distributed to third-party telecommunications hardware suppliers. |
| TRAI Data Localization Certification | Domestic server infrastructure partnerships unlock procurement eligibility with India's regulatory-compliant fleet aggregators. |
| Programmatic Advertising Stack Development | Real-time bidding platforms link captive in-vehicle audiences with location-triggered campaigns generating new operator revenue streams. |
| EASA-Aligned Mounting Standard Investment | Premium cabin configuration eligibility opens luxury fleet segments in Germany and United Kingdom demanding slim-form-factor LED systems. |
Research Methodology
Direct dialogue with fleet operations directors, automotive display procurement managers, programmatic advertising platform engineers, and TRAI regulatory compliance officers grounded qualitative findings. Secondary validation drew from FCC equipment authorization databases, TRAI connected vehicle framework publications, EASA certification registries, and fleet operator RFP documentation. Bottom-up and top-down triangulation cross-checked vehicle installation forecasts against advertising inventory demand projections.
Bottom-up modeling built from individual fleet operator deployment schedules and hardware replacement cycles across the analysis window. Segmentation dimensions included display technology tier, deployment architecture, buyer sophistication level, and regional regulatory cluster. CAGRs derived from logistic adoption curves fitted to connected fleet penetration data. Edge-to-cloud synchronization adoption rates and 5G infrastructure rollout timelines served as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under TRAI data localization enforcement shifts and FCC certification timeline extensions. Practitioners should monitor electromagnetic testing backlog durations and Tier-2 Indian city aggregator consolidation for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Japan Commercial Telematics Market
Telematics and Infotainment
Trailer Telematics Market
Telematics and Infotainment
In-Cabin Lighting-Climate-Audio Synchronized Experience Systems Market
Telematics and Infotainment
Intelligent Transport Systems (ITS) Market
Telematics and Infotainment
Europe Automotive Navigation System Market
Telematics and Infotainment
Motorcycle Infotainment System Market
Telematics and Infotainment
In Vehicle Infotainment Market
Telematics and Infotainment
Automotive Infotainment Market
Telematics and Infotainment
Telematics Market
Telematics and Infotainment
Telematics-Linked Fleet Battery Health Management Systems Market
Telematics and Infotainment
Global Carpool-As-A-Service Market
Telematics and Infotainment
APAC Telematics Market
Telematics and Infotainment
Telematics and Connectivity Processors Market
Telematics and Infotainment
Vehicle Trip Computers Market
Telematics and Infotainment
Europe Telematics Market
Telematics and Infotainment
GPS Tracker Market