
 Global Car Sharing Telematics Market | 2026-2036
Global Car Sharing Telematics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Car Sharing Telematics Market Foresight
The EU Green Deal is repositioning fleet procurement criteria across European car sharing networks, forcing operators to prioritize telematics platforms that deliver real-time emissions monitoring and utilization optimization. INVERS GmbH leverages its embedded hardware-software integration to dominate European fleet deployments. Vulog anchors its competitive position through cloud-native fleet orchestration tools that reduce operator overhead. Geotab Inc. extends its North American data analytics footprint into shared mobility via open API architectures that simplify third-party integration.
Car sharing telematics encompasses the integrated hardware-software systems that capture, transmit, and analyze vehicle operational data—typically incorporating GPS receivers, CAN bus interfaces, cellular modems, and edge computing modules—to enable remote fleet monitoring, usage-based billing, and predictive maintenance for shared vehicle operators. GPS Tracking solutions within the telematics solution segment occupy the foundational layer, as geolocation accuracy directly determines fleet utilization rates and customer access convenience. Fleet Management platforms capture expanding margin pools as operators demand unified dashboards covering maintenance scheduling, fuel or charge level monitoring, and driver behavior scoring across heterogeneous vehicle classes. The Business-to-Consumer service model leads transaction volume, though Hybrid Model deployments are gaining traction as operators blend station-based and free-floating access to maximize asset turns.
The European Commission's F-Gas Regulation and the EPA's vehicle emissions testing protocols in the United States shape hardware certification requirements and data reporting standards for telematics devices installed in shared fleets. REACH compliance in Europe and FCC equipment authorization in the United States create divergent regulatory pathways that vendors must navigate for market access. Stakeholders should monitor how emerging data localization requirements and cybersecurity mandates from regulators in China and South Korea reshape cloud architecture decisions and cross-border data flows in telematics platform design.
Market Dynamics
The EU Green Deal's emissions accountability mandates are restructuring fleet procurement across shared mobility networks, forcing operators to embed real-time monitoring hardware that tracks carbon output per vehicle kilometer and optimizes asset utilization through predictive algorithms.
Growth Catalysts
- EU Green Deal compliance mandates:Shared fleet operators in Germany, France, and the Netherlands must deploy certified telematics stacks to meet binding emissions disclosure requirements for pooled vehicle assets.
- Edge computing module integration:CAN bus interfaces with onboard processing now enable millisecond-latency driver behavior scoring and predictive maintenance alerts without cloud dependency.
- Urban congestion pricing expansion:Municipal authorities in London, Singapore, and Stockholm are exempting car-sharing vehicles from congestion charges only when telematics-verified as shared-use.
Market Restraints
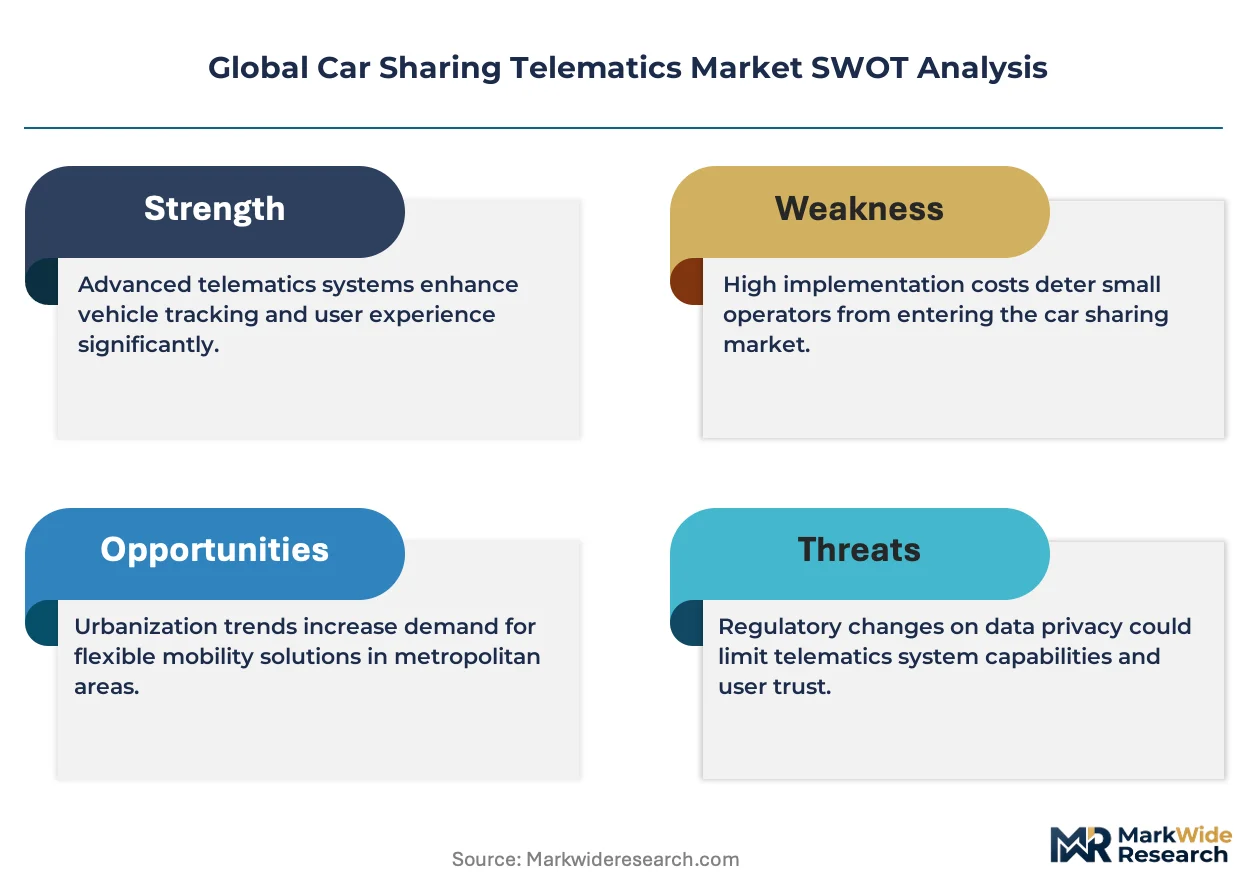
- Semiconductor supply concentration:Cellular modem chip fabrication concentrates in Taiwan and South Korea, creating input bottlenecks for telematics hardware manufacturers serving European fleet operators.
- FCC equipment authorization friction:North American vendors face 12-18 month certification timelines for cellular-enabled devices, delaying cross-Atlantic product launches.
- Smartphone-based substitution:Bring-your-own-device trip logging apps threaten low-cost GPS-only telematics deployments in price-sensitive free-floating car-sharing segments.
Strategic Opportunities
- India's urban mobility gaps:Metro rail integration with last-mile car-sharing remains underpenetrated in Bengaluru, Mumbai, and Delhi, creating white space for multimodal telematics platforms.
- Vehicle-to-grid bidirectional charging:Convergence of telematics with energy management systems enables shared EV fleets to sell stored power back to utilities during peak demand windows.
- CSRD reporting alignment:The EU Corporate Sustainability Reporting Directive creates procurement pull for telematics platforms that automate Scope 3 emissions calculations for fleet service providers.
Industry Challenges
- Embedded systems cybersecurity certification:UN ECE R155 vehicle cybersecurity regulations require telematics vendors to implement intrusion detection systems and secure over-the-air update pipelines.
- Legacy fleet management platform integration:Operators running 2015-era on-premise software face API incompatibility when adopting cloud-native telematics orchestration tools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Car Sharing Telematics Market |
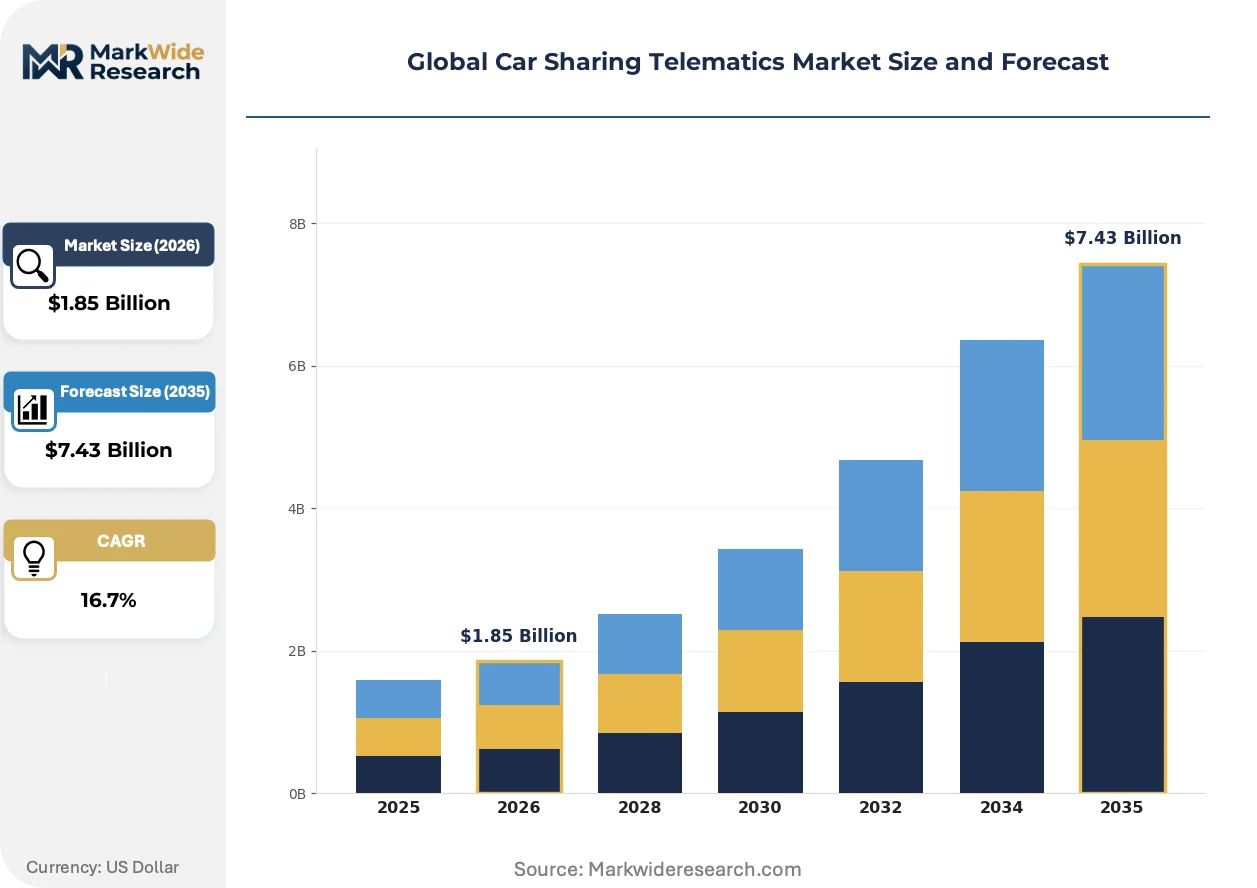
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $7.43 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, SUV, Hatchback, Van Telematics Solution: GPS Tracking, Data Analytics, Fleet Management, Security Systems Service Model: Peer-to-Peer, Business-to-Business, Business-to-Consumer, Hybrid Model Customer Type: Individuals, Corporates, Tourists, NGOs |
| Companies Covered | INVERS GmbH, Vulog, Ridecell, Inc, Convadis AG, Geotab Inc., Targa Telematics, Continental Aftermarket and Services, OCTO Group S.p.A, Share Now, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Car Sharing Telematics Market Shifts & Advancements
Telematics architectures are bifurcating between lightweight smartphone-dependent solutions and heavy embedded edge-computing stacks, with regulatory pressure determining which configuration dominates specific geographic markets.
Edge computing modules with integrated AI accelerators are consolidating the processing layer for real-time driver scoring and collision prediction. Tier 1 automotive suppliers in Germany and Japan are embedding these units directly into vehicle CAN bus architectures during manufacturing. This consolidation is compressing the aftermarket installation window and favoring OEM-integrated telematics over retrofitted hardware.
REACH chemical substance restrictions are forcing hardware redesigns for telematics enclosures and circuit boards sold in European markets. The European Chemicals Agency's expanded candidate list now covers flame retardants and plasticizers common in device housings. Vendors are responding by shifting supply chains to compliant material suppliers in Switzerland and Austria, adding 8-12 months to product development cycles.
Subscription-based fleet analytics are displacing perpetual-license software purchases among mid-size car-sharing operators. Platform vendors now price per-vehicle-per-month for predictive maintenance and utilization optimization dashboards. This shift is most visible in North American municipal fleet services, where budget constraints favor operational expenditure models over capital-intensive on-premise deployments.
Global Car Sharing Telematics Market Segmentation
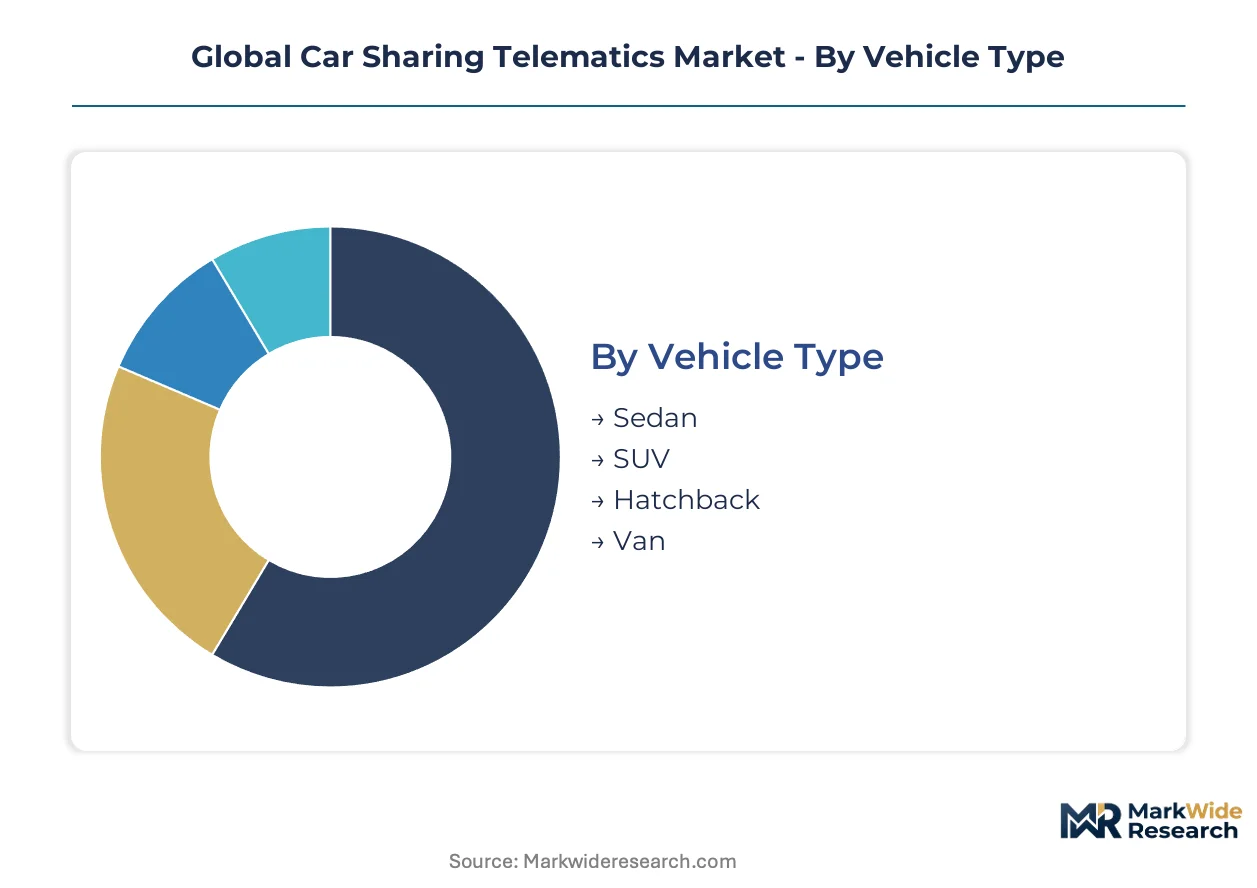
Telematics deployment patterns diverge sharply across vehicle classes and operational models. Fleet operators select hardware-software configurations based on utilization intensity, regulatory exposure, and customer access protocols.
Vehicle Type:
Powertrain electrification and cabin sensor density determine telematics hardware specifications across passenger vehicle categories.
- Sedan:Compact form factors accommodate integrated roof-mounted antennas and single CAN bus interfaces. German free-floating operators in Berlin and Hamburg prioritize sedan deployments for curb-side parking efficiency and battery thermal management in shared EV pools.
- SUV:Higher rooflines enable multi-band antenna arrays and redundant cellular modems for enhanced connectivity in suburban and exurban service zones. Demand concentrates in Nordic markets where all-weather capability and child safety seat compatibility drive family-oriented car-sharing subscriptions.
- Hatchback:Rear cargo sensors and compact OBD-II dongles suit last-mile delivery integrations in French and Dutch urban cores.
- Van:Commercial-grade telematics with load cell monitoring and geofenced cargo bay access serve B2B logistics contracts in Belgian and Spanish metropolitan freight networks.
Sedan leads on scale; SUV leads on momentum.
Telematics Solution:
Functional specialization in data processing layers creates distinct procurement priorities for fleet operators managing heterogeneous asset pools.
- GPS Tracking:Multi-constellation receivers combining GPS, Galileo, and GLONASS signals deliver sub-meter accuracy for free-floating vehicle recovery. Station-based operators in Vienna and Copenhagen deploy these modules to enforce mandatory return-to-hub protocols and optimize rebalancing logistics.
- Fleet Management:Unified dashboards consolidating maintenance scheduling, state-of-charge monitoring, and driver behavior scoring capture expanding procurement budgets. North American municipal fleet services favor per-vehicle-per-month subscription models over capital-intensive on-premise deployments.
- Data Analytics:Predictive algorithms processing utilization heatmaps and demand forecasting enable dynamic pricing in Italian and Portuguese tourist corridors.
- Security Systems:Immobilizer integration and remote door lock diagnostics address theft exposure in Eastern European markets with elevated vehicle loss rates.
Fleet Management commands the largest addressable base; Data Analytics shows the steepest expansion trajectory.
Service Model:
Revenue structure and asset ownership arrangements dictate telematics architecture requirements across operational paradigms.
- Business-to-Consumer:Direct customer-facing mobile applications require seamless API integration with reservation engines and digital key distribution. Transaction volume concentrates in dense metropolitan zones where Paris, London, and Amsterdam operators compete on access convenience and pricing transparency.
- Hybrid Model:Blended station-based and free-floating access protocols demand flexible geofencing and dynamic zone pricing capabilities. Expansion accelerates in Swiss and Austrian alpine cities seeking to optimize asset turns across seasonal demand fluctuations.
- Peer-to-Peer:Owner-installed hardware with minimal fleet management overhead targets cost-sensitive private vehicle sharing in Italian and Spanish secondary cities.
- Business-to-Business:Enterprise contract billing and pooled vehicle access for corporate campuses drive specialized procurement in Frankfurt and Munich commercial districts.
Business-to-Consumer maintains volume leadership; Hybrid Model is gaining share fastest.
Customer Type:
Usage intensity and payment reliability profiles shape telematics feature prioritization across user segments.
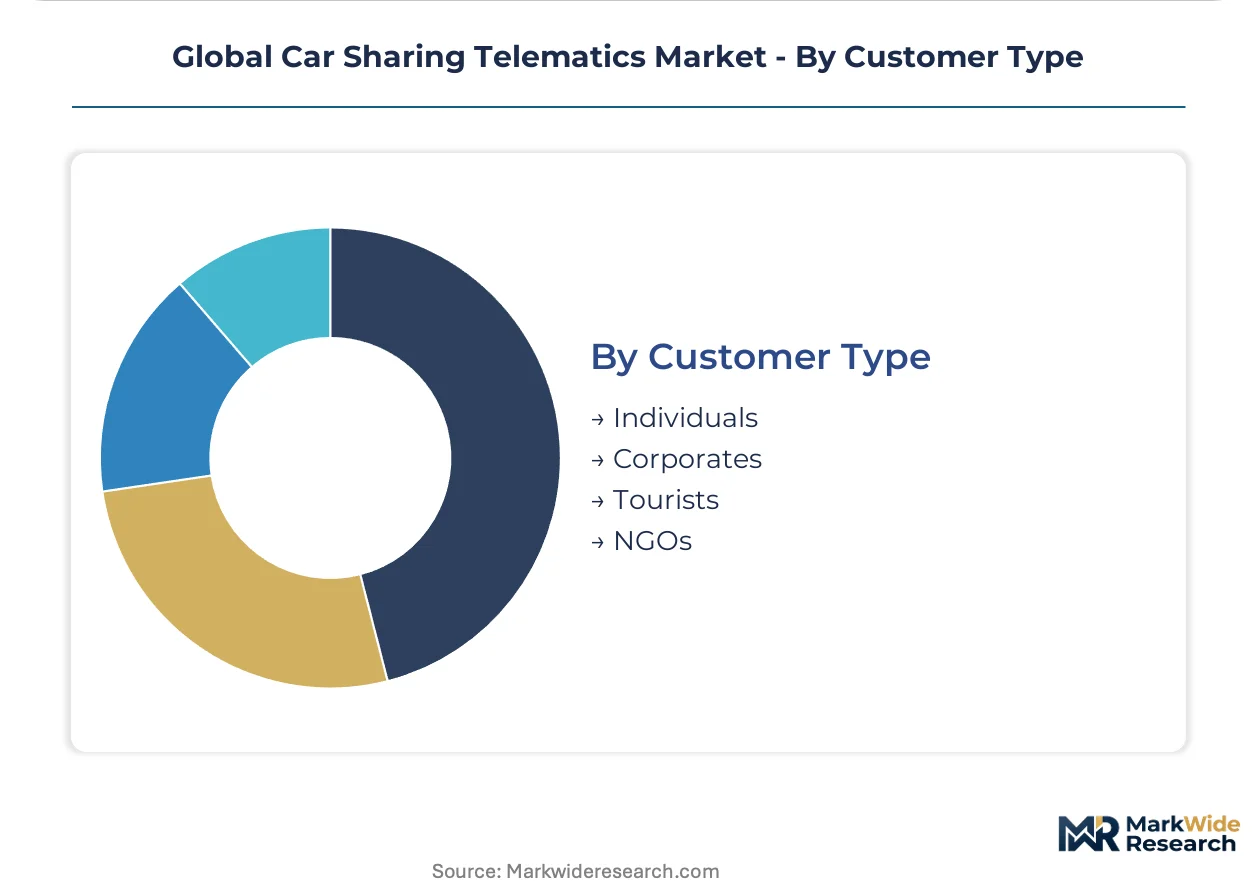
- Corporates:Centralized billing integration and CO2 reporting automation align with CSRD compliance requirements for Scope 3 emissions disclosure. Procurement concentrates among German and French multinational headquarters mandating sustainable mobility policies for employee travel.
- Individuals:Frictionless onboarding and single-trip pricing transparency dominate feature requirements in Dutch and Danish subscription services.
- Tourists:Multilingual interface support and airport zone geofencing serve seasonal demand in Greek and Croatian coastal destinations.
- NGOs:Subsidized access programs for underserved communities require specialized billing waivers and usage caps in Portuguese and Belgian social mobility initiatives.
Corporates anchor revenue stability; Individuals represent the broadest expansion opportunity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools in automotive electronics and embedded systems development concentrate procurement decisions across three continents. Fleet operators in Germany, the United States, China, and India select telematics architectures based on local regulatory pressure and infrastructure maturity.
Germany
KBA vehicle type approval requirements and EU Green Deal emissions disclosure mandates force shared fleet operators toward certified embedded telematics stacks. The EU F-Gas Regulation shapes hardware certification timelines for climate-controlled vehicle cabins. Berlin and Hamburg free-floating operators dominate procurement volumes for integrated roof-mounted antenna systems and CAN bus interfaces.
United States
FCC equipment authorization creates 12-18 month certification friction for cellular-enabled devices entering the market. EPA vehicle emissions testing protocols establish data reporting standards that telematics platforms must support for fleet compliance. Municipal fleet services in California and Texas favor subscription-based analytics dashboards over capital-intensive on-premise deployments.
China
MIIT telecommunication equipment certification and dual carbon goals accelerate domestic telematics platform development for shared mobility networks. GB standards for vehicle network security reshape cloud architecture decisions for cross-border data flows. Yangtze River Delta manufacturing clusters around Shanghai supply edge computing modules with integrated AI accelerators to regional fleet operators.
India
BIS electronics certification and urban metro rail expansion create white space for multimodal telematics platforms connecting last-mile car-sharing. Central government smart city missions fund pilot deployments in Bengaluru and Mumbai. Maharashtra and Karnataka state transport departments draft regulations for shared EV fleet data interoperability.
Japan
METI carbon neutrality roadmaps and JIS standards for automotive electronics guide telematics procurement in corporate mobility services. Tier 1 suppliers in Nagoya embed edge computing units directly into vehicle CAN bus architectures during manufacturing. Kanto region fleet operators prioritize predictive maintenance algorithms for high-utilization shared vehicle pools.
Global Car Sharing Telematics Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the telematics value chain. Hardware manufacturers with captive semiconductor sourcing face margin pressure from software specialists licensing white-label platforms. The market structure fragments across three strategic archetypes: embedded systems integrators with automotive OEM relationships, cloud-native fleet orchestration platforms, and data analytics specialists with open API architectures. Dominant competitive moves include strategic partnerships between hardware vendors and mobility operators, plus geographic expansion through regulatory certification stacking.
Within the embedded systems tier, INVERS GmbH and Continental Aftermarket and Services represent European engineering density in hardware-software integration. Cloud-native specialists include Vulog and Ridecell, Inc., exemplifying asset-light platform architectures that reduce operator overhead. Geotab Inc. anchors the data analytics archetype with North American footprint extension into shared mobility via API-centric designs.
| Leading Market Players |
|---|
| INVERS GmbH |
| Vulog |
| Ridecell, Inc |
| Convadis AG |
| Geotab Inc. |
| Targa Telematics |
| Continental Aftermarket and Services |
| OCTO Group S.p.A |
| Share Now |
| Others |
Supply & Pricing Matrix
Embedded systems engineering talent clusters in southern Germany and Stuttgart automotive corridors compress development cost differentials between premium certified stacks and economy-grade GPS-only modules. Labor-rate arbitrage between Munich-based Tier 1 integrators and Eastern European firmware houses widens pricing spreads across subscription tiers for fleet management platforms.
Pricing Analysis
Per-vehicle-per-month SaaS pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales service bundling. Premium tiers command spreads for UN ECE R155 cybersecurity compliance and KBA type approval, while economy tiers face cost compression from smartphone-based trip logging substitutes. Municipal fleet services in California exhibit highest price sensitivity; German corporate mobility programs show lowest.
Supply Chain Analysis
Cellular modem chip fabrication rests on Taiwan Semiconductor Manufacturing and South Korean foundry capacity for 4G LTE and 5G NR modules. CAN bus interface controllers and GPS receiver chipsets draw from Japanese and Dutch specialty semiconductor suppliers. Single-source vulnerability concentrates in advanced node cellular baseband processors. Distribution runs through Tier 1 automotive electronics distributors with direct OEM integration programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in car sharing telematics stems from software-subscription displacement of perpetual-license hardware sales, compressing customer acquisition costs while extending lifetime value per fleet endpoint.
For Market Incumbents: Extend embedded hardware-software integration capabilities toward OEM pre-installation programs, neutralizing smartphone-based substitution threats in free-floating segments. Deepen captive semiconductor sourcing relationships to buffer Taiwan and South Korean supply concentration risks. Prioritize UN ECE R155 certification pipelines to defend pricing power against uncertified cloud-native entrants. For New Entrants and Emerging Players: Edge computing modules with integrated AI accelerators offer a technology-first wedge into predictive maintenance and real-time driver scoring white spaces. Target India's Bengaluru and Mumbai metro rail integration corridors where multimodal telematics platforms remain underpenetrated. Pursue white-label licensing to European mid-size fleet operators seeking rapid EU Green Deal compliance without captive engineering. For Investors and Strategic Acquirers: Valuations sit cheapest among cloud-native fleet orchestration platforms lacking embedded hardware capabilities but possessing sticky operator relationships. Five-to-ten-year viability favors vendors with dual competence in edge computing hardware and recurring software revenue. Watch FCC equipment authorization backlog resolution as inflection signal for North American market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified dashboards consolidating CAN bus data and reservation APIs reduce operator overhead for heterogeneous EV fleets. |
| Strategic Partnership | Collaboration with Yangtze River Delta edge computing manufacturers secures AI accelerator supply for predictive maintenance modules. |
| Geographic Expansion | Regulatory certification stacking through BIS and MIIT approvals unlocks Indian and Chinese shared mobility procurement channels. |
| Acquisition of Specialist Firm | Targeted purchases of cybersecurity certification consultancies accelerate UN ECE R155 compliance timelines for embedded stacks. |
| Product Launch | Vehicle-to-grid bidirectional charging integration enables shared EV fleets to monetize stored power during utility peak demand. |
Research Methodology
Bottom-up fleet operator deployment modeling reconciled against top-down telematics hardware shipment tracking forms the analytical core. Primary interviews with shared mobility platform CTOs, OEM telematics procurement leads, Tier 1 automotive electronics distributors, and fleet management software product directors combined with secondary validation against SEC 10-K filings, EU vehicle registration databases, and MIIT equipment certification records. Triangulation across these sources anchors volume and value estimates.
Historical trendline analysis of embedded systems pricing and subscription SaaS adoption patterns informed projection frameworks across the analysis window. Segmentation dimensions modeled include vehicle powertrain architecture, telematics solution functional layer, service model revenue structure, and customer type utilization intensity. CAGRs derived from curve-fitting observed deployment trajectories against regulatory mandate timelines, incorporating EU Green Deal compliance deadlines and FCC authorization cycle impacts.
The model holds under stable semiconductor supply conditions and sustained EU emissions disclosure enforcement; deviation in Taiwan geopolitical stability or REACH chemical restriction expansion would shift hardware cost assumptions and certification timelines. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
In-Car Infotainment Market
Telematics and Infotainment
Europe Vehicle Remote Diagnostic Market
Telematics and Infotainment
Electronic Rotary Controller Systems for Infotainment Market
Telematics and Infotainment
In-Car Apps Market
Telematics and Infotainment
Automotive Rear Seat Infotainment Market
Telematics and Infotainment
APAC Telematics Market
Telematics and Infotainment
North America Electronic Toll Collection (ETC) Market
Telematics and Infotainment
Global Automotive Remote Diagnostics Market
Telematics and Infotainment
Automotive Embedded Telematics Market
Telematics and Infotainment
Vehicle to Vehicle (V2V) Communication Market
Telematics and Infotainment
Infotainment System UX and Latency Test Platforms for Connected Vehicles Market
Telematics and Infotainment
Asia-Pacific Automotive Telematics Market
Telematics and Infotainment
India Connected Car Market
Telematics and Infotainment
Mobility on Demand (Mod) Market
Telematics and Infotainment
North America Commercial Vehicle Telematics Market
Telematics and Infotainment
Trailer Telematics Market