
 Intelligent Transport Systems (ITS) Market | 2026-2036
Intelligent Transport Systems (ITS) Market Size, Share, and Industry Trends Forecast 2026-2036
Intelligent Transport Systems (ITS) Market Outlook
China is fragmenting its ITS deployment across provincial pilot zones rather than centralizing under a single framework. Siemens dominates European signaling and traffic control hardware through captive supply of rail-integrated control systems. Kapsch TrafficCom specializes in multi-protocol toll collection, leveraging decades of Austrian motorway technology transfer to Asian markets. Thales competes on cybersecurity-hardened V2X modules, sustaining defense-grade encryption standards across its transport portfolio.
Intelligent Transport Systems encompass networked hardware, software, and communication infrastructure that coordinates vehicle movement, traffic signal timing, and infrastructure status through real-time data exchange, typically operating via DSRC or C-V2X protocols with sub-100-millisecond latency requirements. These systems serve to reduce congestion, prevent collisions, and optimize energy consumption across road, rail, and multimodal networks. Traffic Management Systems anchor the largest revenue pool given their deployment scale across government agency budgets, while Vehicle-to-Everything (V2X) connectivity represents the fastest-expanding segment as automotive OEMs embed cellular-based communication modules in production vehicles. Toll Collection Systems occupy a mature margin position where incumbents defend long-term concession contracts, and Fleet Management Solutions are deepening their technology stack through IoT Sensors layered with Cloud Computing analytics for logistics companies.
The EU AI Act imposes risk-classification requirements on automated traffic decision systems, compelling vendors to document algorithmic transparency for urban mobility deployments. The US DOT and NHTSA jointly shape V2X mandate timelines through spectrum allocation rulings and vehicle safety standard updates, directly conditioning OEM product roadmaps. Japan's METI coordinates national V2X frequency harmonization with JIS standards bodies, creating a regulatory template that neighboring Asian economies reference for interoperability. Stakeholders must monitor which spectrum band authorities designate for safety-critical vehicle communication, as this technical choice will determine hardware refresh cycles and cross-border equipment compatibility for the next decade.
Market Dynamics
The EU AI Act's risk-classification requirements for automated traffic decision systems are forcing vendors to reengineer algorithmic transparency documentation, reshaping competitive positioning across urban mobility deployments.
Growth Catalysts
- EU Green Deal mobility targets:Emissions reporting obligations are tightening vehicle data collection mandates across member states, accelerating procurement of connected infrastructure by municipal transit authorities.
- DSRC-to-C-V2X protocol migration:Cellular-based vehicle communication modules are achieving sub-100-millisecond latency thresholds, enabling real-time collision prevention and traffic signal optimization.
- Japan's METI smart city pilots:V2X infrastructure integration with existing toll collection networks is creating reference architectures that neighboring Asian economies are adopting for interoperability.
Market Restraints
- Spectrum allocation uncertainty:US DOT and NHTSA deliberations over safety-critical vehicle communication bands are delaying OEM hardware refresh cycles and cross-border equipment compatibility planning.
- Concession contract lock-in:Toll collection incumbents defend mature-margin positions through long-term infrastructure agreements, restricting new entrant access to revenue-generating corridors.
- Legacy system integration costs:Rail-integrated control systems from established European suppliers create switching friction for transit agencies seeking modular, interoperable alternatives.
Strategic Opportunities
- German municipal transit acceleration:AI-powered traffic management platforms are penetrating procurement pipelines of city authorities seeking congestion reduction and energy optimization capabilities.
- Cloud-IoT convergence in fleet management:Logistics companies are layering sensor networks with analytics platforms, creating demand for integrated hardware-software subscriptions over capital-intensive equipment sales.
- Cybersecurity-hardened modules:Defense-grade encryption standards are transferring from aerospace portfolios into transport applications, opening premium positioning for vendors with certified security credentials.
Industry Challenges
- Algorithmic audit competency gaps:Vendors lack sufficient AI ethics and explainability engineering capacity to meet EU AI Act documentation requirements for high-risk automated decision systems.
- Multi-protocol hardware complexity:Equipment manufacturers must engineer compatibility across DSRC, C-V2X, and proprietary toll collection standards simultaneously, stretching R&D resources.
- Frequency harmonization timelines:Japan's METI-coordinated V2X standards are advancing faster than neighboring regulators can adapt, creating interoperability gaps in cross-border corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intelligent Transport Systems (ITS) Market |
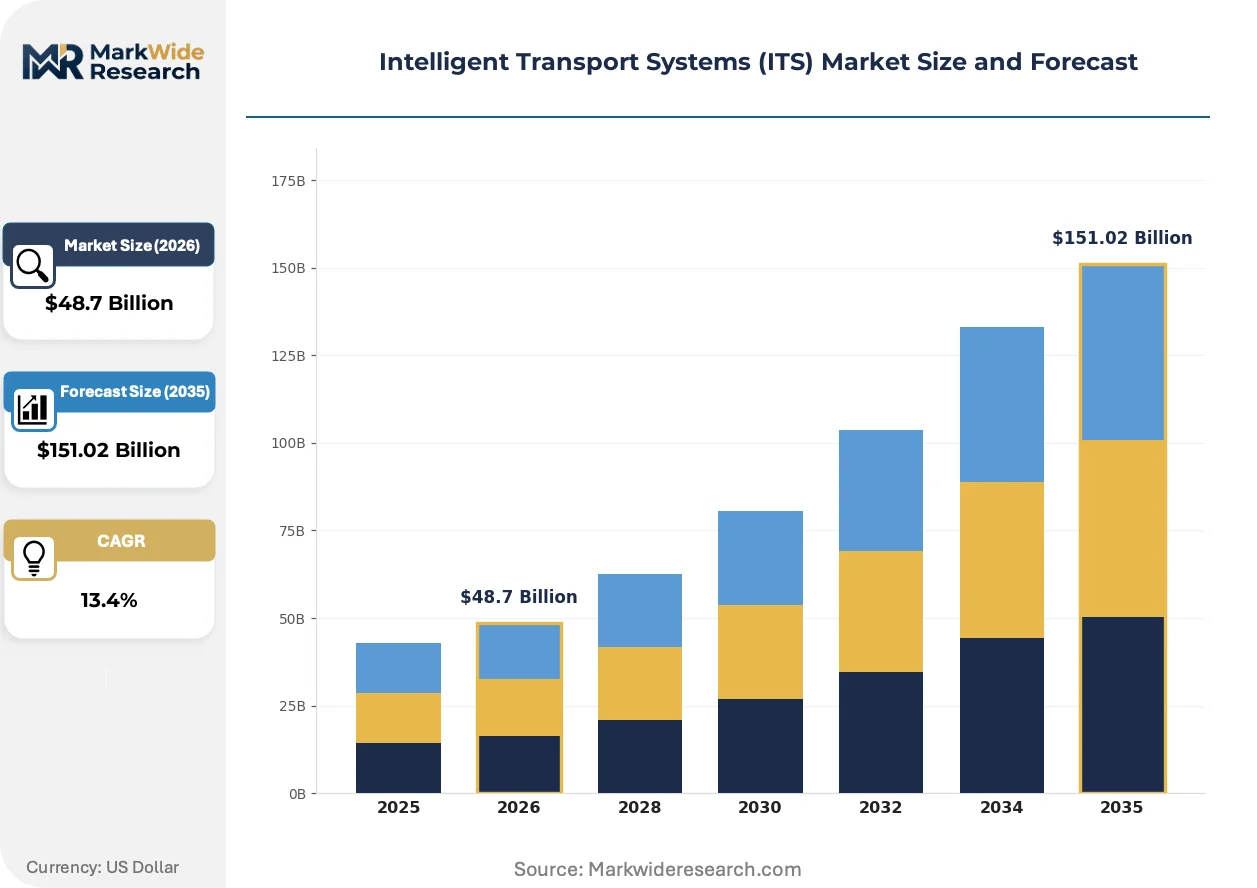
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $151.02 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traffic Management Systems, Vehicle-to-Everything (V2X), Toll Collection Systems, Fleet Management Solutions Technology: Artificial Intelligence, Cloud Computing, GPS, IoT Sensors End User: Government Agencies, Transportation Authorities, Automotive OEMs, Logistics Companies Application: Public Transport, Smart Parking, Traffic Safety, Urban Mobility |
| Companies Covered | Indra Sistemas, Cubic Corporation, Siemens, Thales, Kapsch TrafficCom, Hitachi Ltd., Verra Mobility, Teledyne Technologies, Mundys, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intelligent Transport Systems (ITS) Market Strategic Shifts
Cellular vehicle-to-everything communication is digitizing traffic infrastructure at the intersection of automotive electronics and municipal procurement, compressing development cycles and redefining supplier-customer relationships.
Edge computing architectures deployed at roadside units are digitizing real-time traffic signal optimization previously handled by centralized control centers. Municipal agencies in Germany and Japan are piloting these distributed systems for sub-50-millisecond response to congestion events. The shift is digitizing hardware procurement models from capital equipment sales toward managed service subscriptions with uptime guarantees.
The EU AI Act's risk-classification framework is mandating algorithmic transparency documentation for automated traffic management systems classified as high-risk. Vendors must now maintain technical files demonstrating human oversight capability and bias mitigation protocols. European municipal transit authorities are inserting these compliance requirements into procurement specifications, favoring suppliers with pre-certified AI governance structures.
Japanese logistics operators are consolidating fleet management procurement under integrated platform contracts that bundle IoT sensors, cloud analytics, and predictive maintenance. Tier-1 automotive suppliers are responding by acquiring telematics software capabilities rather than selling discrete hardware modules. This consolidation is most visible in Tokyo-Osaka corridor freight operations, where fuel optimization algorithms now determine supplier selection criteria.
Intelligent Transport Systems (ITS) Market Segmentation
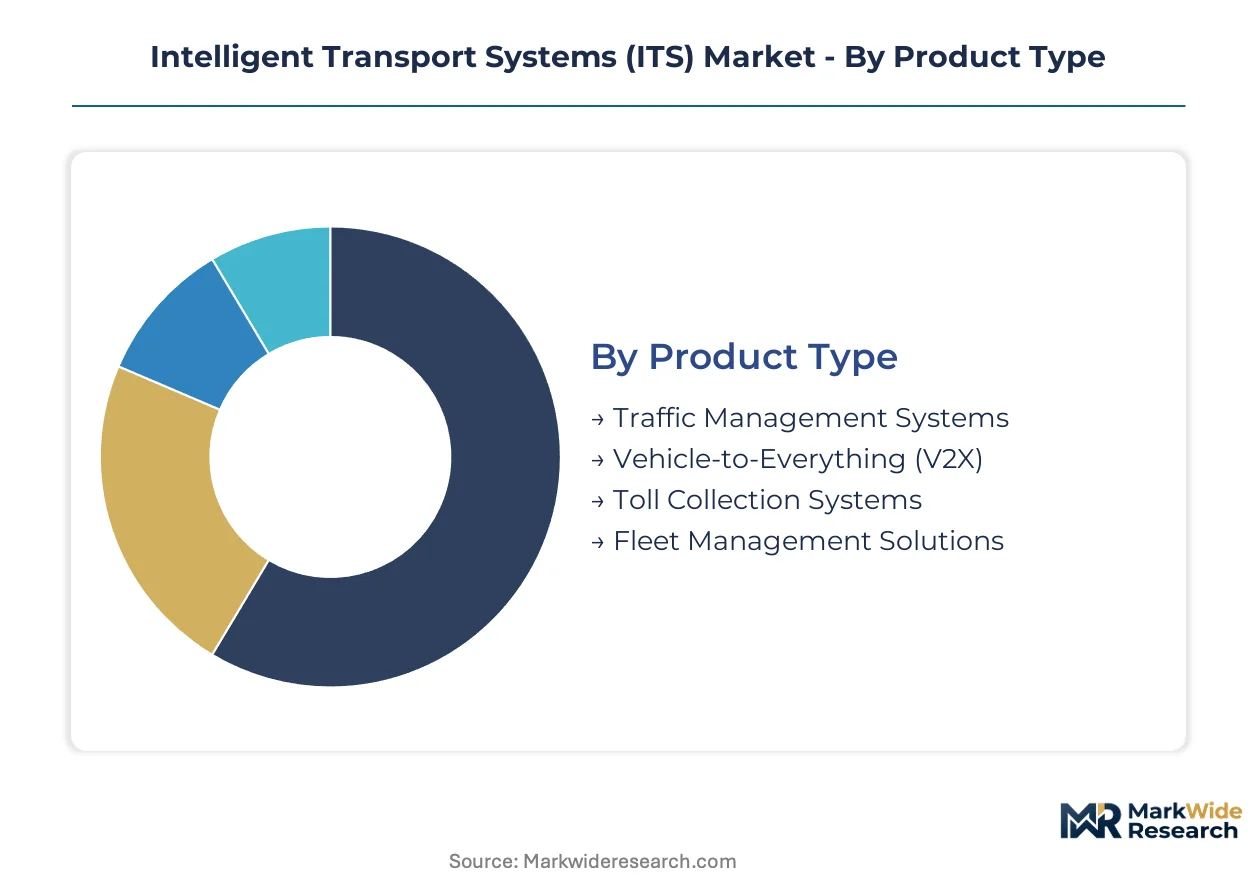
ITS market segmentation reveals how procurement authority, technical architecture, and operational use cases reshape competitive positioning across hardware, software, and service layers. Understanding these dimensions exposes where vendors capture margin and where standardization pressures compress pricing.
Product Type:
Cost tier differentiation separates capital-intensive infrastructure from recurring-revenue platforms and software subscriptions.
- Traffic Management Systems:Hardware-software platforms coordinating signal timing, incident detection, and congestion response through centralized or edge-deployed controllers. German municipal transit authorities anchor procurement volume as EU Green Deal emissions targets tighten data reporting mandates for urban corridors.
- Vehicle-to-Everything (V2X):Communication modules enabling sub-100-millisecond data exchange between vehicles, infrastructure, and pedestrians via DSRC or C-V2X protocols. Japanese METI-backed smart city pilots concentrate initial deployment, creating reference architectures that neighboring Asian economies adopt for interoperability.
- Toll Collection Systems:Multi-protocol roadside and onboard units processing electronic payment across concession-operated motorways.
- Fleet Management Solutions:Cloud-integrated platforms combining GPS tracking, fuel monitoring, and predictive maintenance for logistics operators.
Traffic Management Systems command the established base. The steepest expansion runs through Vehicle-to-Everything connectivity.
Technology:
Application maturity determines whether segments deliver proven ROI or require pilot-phase risk tolerance from adopters.
- Artificial Intelligence:Machine learning models optimizing traffic prediction, incident detection, and automated signal control. EU AI Act risk-classification requirements now compel algorithmic transparency documentation for high-risk urban mobility deployments.
- Cloud Computing:Distributed data processing and storage architectures enabling real-time analytics across distributed sensor networks. Logistics companies in Japan's Tokyo-Osaka freight corridor are consolidating procurement under integrated platform contracts that bundle cloud infrastructure with hardware subscriptions.
- GPS:Satellite-based positioning systems providing location tracking for fleet management and navigation services.
- IoT Sensors:Embedded devices collecting vehicle, infrastructure, and environmental data for edge or cloud processing.
Cloud Computing anchors the revenue base. Artificial Intelligence delivers the steepest growth trajectory as regulatory compliance creates vendor selection filters.
End User:
Customer type dictates procurement cycle length, budget source, and technical specification authority.
- Government Agencies:Federal, state, and municipal departments funding large-scale infrastructure through appropriated capital budgets. US DOT and NHTSA spectrum allocation deliberations directly condition their V2X deployment timelines and equipment refresh planning.
- Transportation Authorities:Regional transit operators managing multimodal networks with integrated fare and traffic systems.
- Automotive OEMs:Vehicle manufacturers embedding communication modules and telematics platforms in production models. C-V2X protocol migration is compressing their hardware development cycles as cellular-based modules achieve latency thresholds for safety-critical applications.
- Logistics Companies:Freight and delivery operators optimizing fleet utilization through sensor-network analytics.
Government Agencies control the foundational installed base. Automotive OEMs are expanding most quickly as production-line integration mandates proliferate.
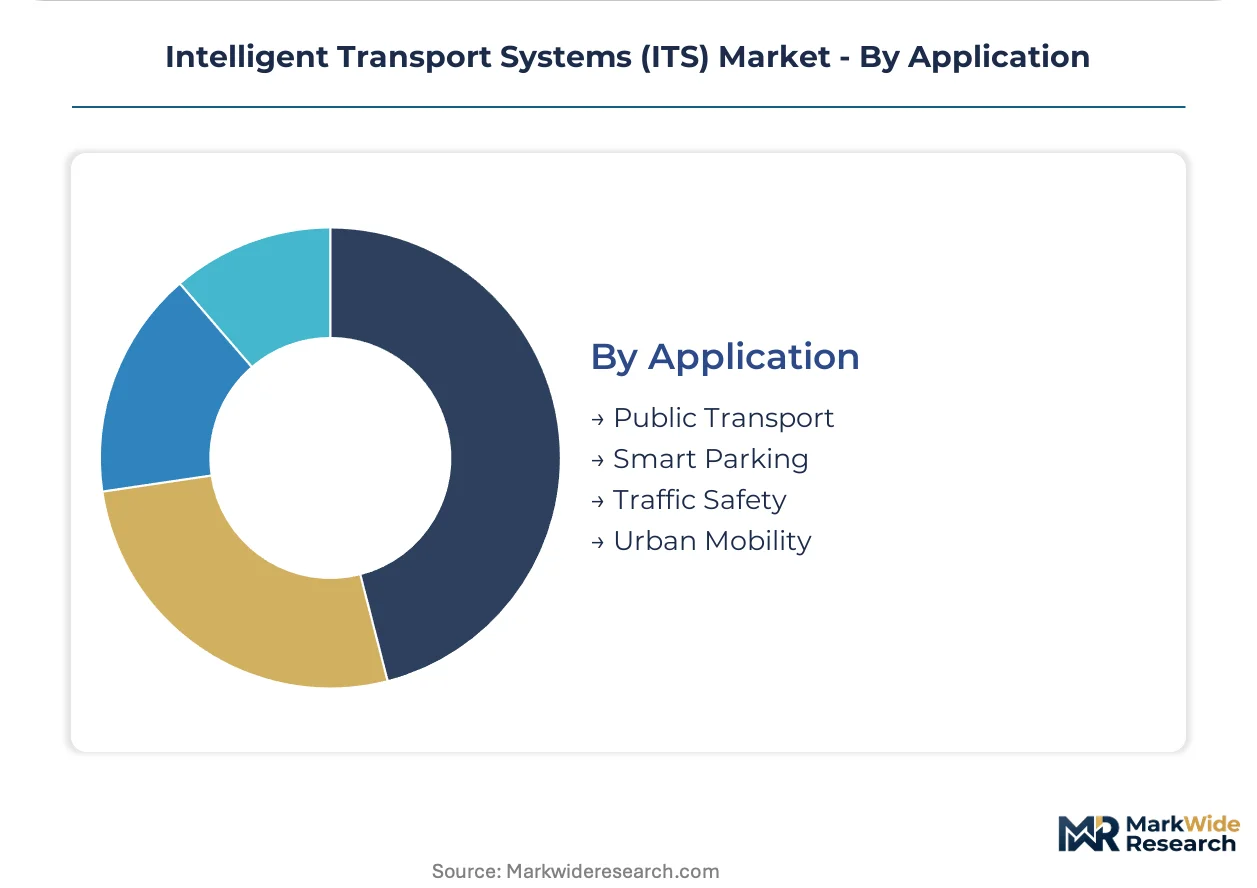
Application:
Volume concentration varies by urban density, regulatory priority, and existing infrastructure legacy.
- Public Transport:Bus, rail, and multimodal coordination systems prioritizing schedule adherence and passenger throughput. Rail-integrated control systems from established European suppliers create switching friction for transit agencies seeking modular alternatives.
- Smart Parking:Sensor-guided space detection and dynamic pricing platforms reducing urban search traffic.
- Traffic Safety:Collision avoidance, vulnerable road user protection, and incident response systems. Edge computing architectures at roadside units in Germany and Japan are achieving sub-50-millisecond response times for congestion events.
- Urban Mobility:Integrated platforms coordinating shared vehicles, micromobility, and curb management.
Public Transport holds the deepest installed base. Traffic Safety is climbing the fastest as latency thresholds enable real-time collision prevention.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI coordinates Japan's national V2X deployment, creating a regulatory template that neighboring Asian economies reference for interoperability standards and spectrum harmonization.
Germany
Municipal transit authorities in Berlin, Munich, and Hamburg are accelerating procurement of AI-powered traffic management platforms. The EU AI Act imposes risk-classification requirements on automated traffic decision systems, compelling vendors to document algorithmic transparency. Bavaria's automotive corridor anchors rail-integrated control system deployments from established European suppliers.
United States
The US DOT and NHTSA jointly shape V2X mandate timelines through spectrum allocation rulings and vehicle safety standard updates. FCC deliberations over safety-critical vehicle communication bands are delaying OEM hardware refresh cycles. California and Michigan anchor pilot deployments where edge computing architectures at roadside units achieve sub-50-millisecond congestion response.
Japan
METI-backed smart city pilots integrate V2X infrastructure with existing toll collection networks across the Tokyo-Osaka corridor. JIS standards bodies coordinate national V2X frequency harmonization, creating reference architectures for interoperability. Logistics operators in the Kanto region are consolidating fleet management procurement under integrated platform contracts bundling IoT sensors with cloud analytics.
China
Provincial pilot zones in Guangdong, Jiangsu, and Zhejiang are fragmenting ITS deployment rather than centralizing under a single framework. MIIT coordinates cellular-based vehicle communication standards as C-V2X modules achieve latency thresholds for safety-critical applications. The Yangtze River Delta anchors smart city infrastructure integration with multimodal transit networks.
United Kingdom
Transport for London and regional transit operators are deploying traffic signal optimization systems under tightened emissions reporting obligations. The EU Green Deal's mobility targets continue conditioning procurement specifications despite post-Brexit regulatory divergence. The Midlands and Southeast England concentrate V2X pilot programs testing cybersecurity-hardened communication modules.
Intelligent Transport Systems (ITS) Market Competitive Environment
Capability concentration sits with defense-aerospace tier suppliers; scale advantage sits with infrastructure incumbents with long-term concession relationships. The vendor base separates into three strategic archetypes: rail-integrated control system specialists, multi-protocol toll collection operators, and cybersecurity-hardened V2X module suppliers. Consolidation pressure runs through M&A activity targeting telematics software capabilities and strategic partnerships bridging automotive OEMs with municipal procurement channels.
Among European infrastructure incumbents, Siemens and Thales exemplify divergent positioning strategies. Siemens anchors rail-integrated control systems through captive supply relationships with transit agencies. Thales occupies a position transferring defense-grade encryption standards from aerospace portfolios into transport cybersecurity applications. Kapsch TrafficCom represents the toll collection archetype, leveraging Austrian motorway technology transfer to penetrate Asian concession markets. These three entities collectively illustrate how regulatory compliance requirements and long-term infrastructure agreements shape competitive mobility across the sector.
| Leading Market Players |
|---|
| Indra Sistemas |
| Cubic Corporation |
| Siemens |
| Thales |
| Kapsch TrafficCom |
| Hitachi Ltd. |
| Verra Mobility |
| Teledyne Technologies |
| Mundys |
| Others |
Value Chain & Pricing Dynamics
Semiconductor fabrication concentration in Taiwan and South Korea feeds directly into V2X module margin pools, where defense-grade encryption certification creates pricing separation between automotive-grade and aerospace-hardened tiers. Toll collection incumbents leverage decades-long concession relationships to defend premium positioning against modular hardware challengers.
Pricing Analysis
German municipal procurement premiums run 15-25 percent above Asian smart city pilots for equivalent AI-powered traffic management platforms. Three-tier pricing structure across premium, standard, and economy levels separates defense-certified V2X modules from commercial-grade alternatives, with customization for EU AI Act compliance driving the premium tier. Cost compression in standard-tier hardware is intensifying because C-V2X protocol standardization eliminates proprietary lock-in advantages. Government agencies exhibit lowest price sensitivity given appropriated capital budgets, while logistics operators in Japan's freight corridors demand outcome-based subscription models that shift capital expenditure to operating expense.
Supply Chain Analysis
Electronics manufacturing services concentration rests with Taiwanese and Chinese contract manufacturers holding capacity for DSRC and C-V2X module production. Raw material dependencies center on gallium nitride substrates for RF components, automotive-grade MCUs from Japanese foundries, and rare earth elements for magnetics in roadside unit enclosures. Single-source vulnerability in semiconductor lithography equipment creates chokepoint exposure for European traffic control hardware vendors. Distribution runs through systems integrators bridging municipal procurement channels with OEM direct supply agreements, with aftermarket service contracts capturing recurring revenue streams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ITS market is entering a cyclical recovery phase as DSRC-to-C-V2X protocol migration forces hardware refresh cycles across municipal and automotive installed bases. EU Green Deal emissions reporting mandates and US spectrum allocation resolutions provide synchronized regulatory tailwinds.
For Market Incumbents: Build switching-cost moats through captive supply relationships with German transit agencies seeking rail-integrated control system continuity. Deepen backward integration into edge computing silicon to secure sub-50-millisecond latency guarantees for safety-critical applications. Defend against modular challengers by embedding AI governance documentation services that preempt EU AI Act procurement filters. For New Entrants and Emerging Players: China's provincial pilot zones offer the most penetrable geographic entry point given fragmented deployment frameworks that bypass centralized vendor qualification. Target cybersecurity-hardened V2X modules for UK Midlands pilot programs testing defense-grade encryption standards. Pursue telematics software acquisitions to penetrate Japanese logistics operator procurement consolidating under integrated platform contracts. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed toll collection operators holding mature-margin concession contracts across Asian motorway networks. Five-to-ten year viability hinges on C-V2X module refresh demand replacing legacy DSRC infrastructure. Monitor FCC spectrum allocation rulings as the inflection signal conditioning OEM hardware roadmap commitments and cross-border equipment compatibility planning.| Strategic Initiative | Industry Significance |
|---|---|
| AI Governance Certification Investment | EU AI Act documentation capabilities preempt municipal procurement specifications in Germany and the UK. |
| C-V2X Module Platform Standardization | Cellular-based protocol migration compresses OEM development cycles and enables cross-border interoperability. |
| Edge Computing Architecture Deployment | Roadside unit digitization in California and Japan achieves sub-50-millisecond congestion response thresholds. |
| Telematics Software Capability Acquisition | Japanese logistics operators consolidate procurement under bundled sensor-cloud platform subscriptions. |
| Defense-Grade Encryption Technology Transfer | Aerospace-hardened standards penetrate transport applications through Thales-certified security credentials. |
Study Parameters
A spread of perspectives from municipal transit procurement officers, automotive OEM platform engineers, toll collection concession operators, and V2X systems integrators converged on the working assumptions driving segment-level demand forecasts. Primary interviews with traffic management system vendors and logistics fleet operators were cross-validated against secondary sources including US DOT spectrum allocation filings, EU AI Act implementation guidance, METI smart city pilot documentation, and MIIT C-V2X standard releases. Bottom-up equipment shipment tracking and top-down infrastructure budget appropriation analysis were triangulated to anchor volume estimates.
Demand-supply balance framing shaped the analytical framework across the analysis window, with segmentation modeled across product type, technology maturity tier, end-user procurement authority, and application latency requirements. CAGRs were derived from equipment refresh cycle timing, regulatory mandate phase-in schedules, and automotive production line integration rates. Industry-specific inputs included DSRC-to-C-V2X protocol migration velocity, EU AI Act risk-classification compliance timelines, and municipal smart city budget allocation patterns.
Practitioners should monitor FCC spectrum allocation rulings, EU AI Act enforcement precedent, and METI frequency harmonization announcements for early signals of forecast revision. Forecasts reflect assumptions about regulatory coordination continuity, semiconductor supply normalization, and concession contract renewal rates. Quarterly review of OEM hardware roadmap disclosures and municipal procurement pipeline data is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Telematics and Connectivity Processors Market
Telematics and Infotainment
In-Car Apps Market
Telematics and Infotainment
In Vehicle Infotainment Market
Telematics and Infotainment
In Car Infotainment System Market
Telematics and Infotainment
Global in Dash Navigation System Market
Telematics and Infotainment
Europe Automotive Navigation System Market
Telematics and Infotainment
Internet of Cars Market
Telematics and Infotainment
Advanced Traveller Information System Market
Telematics and Infotainment
Vehicle Digital Cockpit Market
Telematics and Infotainment
Europe Commercial Telematics Market
Telematics and Infotainment
C-V2X OBU Market
Telematics and Infotainment
Motorcycle Infotainment System Market
Telematics and Infotainment
Telematics-Linked Fleet Battery Health Management Systems Market
Telematics and Infotainment
Automotive Rear Seat Infotainment Market
Telematics and Infotainment
Automotive Dashboard Camera Market
Telematics and Infotainment
Internet of Things Vehicle-To-Vehicle Communication Market