
 In-Cabin Lighting-Climate-Audio Synchronized Experience Systems Market | 2026-2036
In-Cabin Lighting-Climate-Audio Synchronized Experience Systems Market Size, Share, and Industry Trends Forecast 2026-2036
In-Cabin Lighting-Climate-Audio Synchronized Experience Systems Market Insights
Unified cockpit wellness bundling is expanding as automakers merge ambient lighting, thermal management, and spatial audio into single-option packages rather than à la carte configurations. Continental leverages its cross-domain electronics portfolio to anchor integrated cabin-control architectures. HARMAN International differentiates through acoustic signal processing leadership that ties audio environments to lighting mood states. Valeo competes with advanced LED and OLED surface technologies that embed climate-feedback visual cues directly into interior panels.
In-cabin lighting-climate-audio synchronized experience systems orchestrate multiple sensory subsystems through centralized controllers that adjust LED or OLED spectral output, thermal actuator response, and acoustic field shaping based on occupant biometrics and preference profiles; these systems typically operate on 12V or 48V vehicle electrical architectures with sub-100ms latency requirements for real-time synchronization. Synchronization controllers and sensors capture expanding margin pools as the intelligence layer concentrates value away from commodity lighting and audio hardware. Application demand tilts toward personal vehicles and autonomous pods, where occupant experience replaces driver engagement as the primary cabin-design priority.
NHTSA guidelines on driver distraction and the EU's General Safety Regulation frame mandatory human-machine interface standards that push automakers toward integrated, eyes-free cabin controls. Germany's KBA enforces type-approval protocols for electronic subsystems that constrain how lighting-climate-audio sequences deploy during automated driving modes. Stakeholders must monitor how cybersecurity standards for connected cabin ecosystems reshape controller architecture requirements and supplier qualification barriers.
Market Dynamics
The market pivots on NHTSA and EU safety mandates that force hardware-software integration for eyes-free cabin controls, compressing supplier qualification timelines and elevating controller architecture above commodity lighting and audio components.
Growth Catalysts
- EU General Safety Regulation:Mandatory human-machine interface standards accelerate integrated cabin-control adoption across European premium electric vehicle OEMs, bundling ambient lighting with thermal and acoustic subsystems.
- Biometric sensor fusion:Real-time occupant monitoring enables dynamic synchronization of LED spectral output, climate actuators, and spatial audio fields with sub-100ms latency requirements.
- Germany's KBA type-approval protocols:Automated driving mode regulations in the country pioneer occupant-centric cockpit architectures that export design standards to adjacent European markets.
Market Restraints
- 48V electrical architecture transition costs:Legacy 12V vehicle platforms require expensive controller redesigns to support synchronized subsystem power demands and latency specifications.
- OLED surface supply concentration:Advanced interior panel technologies depend on concentrated Asian display manufacturing, exposing automakers to single-source disruption risks.
- Cybersecurity certification friction:Connected cabin ecosystem standards impose extended validation cycles that delay product launches and inflate development overhead.
Strategic Opportunities
- Autonomous pod applications:Robotaxi and shuttle segments prioritize occupant experience over driver engagement, creating demand for wellness-optimized lighting-climate-audio packages without steering wheel constraints.
- India's PLI scheme for automotive electronics:Component localization incentives attract controller and sensor manufacturing investments serving cost-sensitive personal vehicle segments.
- Acoustic-haptic convergence:Integration of spatial audio with seat and steering wheel vibration feedback opens new premium tier differentiation for wellness-focused OEMs.
Industry Challenges
- Cross-domain software engineering scarcity:Synchronization controller development demands rare expertise spanning LED driver firmware, thermal actuator protocols, and acoustic signal processing pipelines.
- Legacy HVAC integration complexity:Established climate control architectures resist real-time API exposure for centralized wellness orchestration, forcing expensive gateway layer implementations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In-Cabin Lighting-Climate-Audio Synchronized Experience Systems Market |
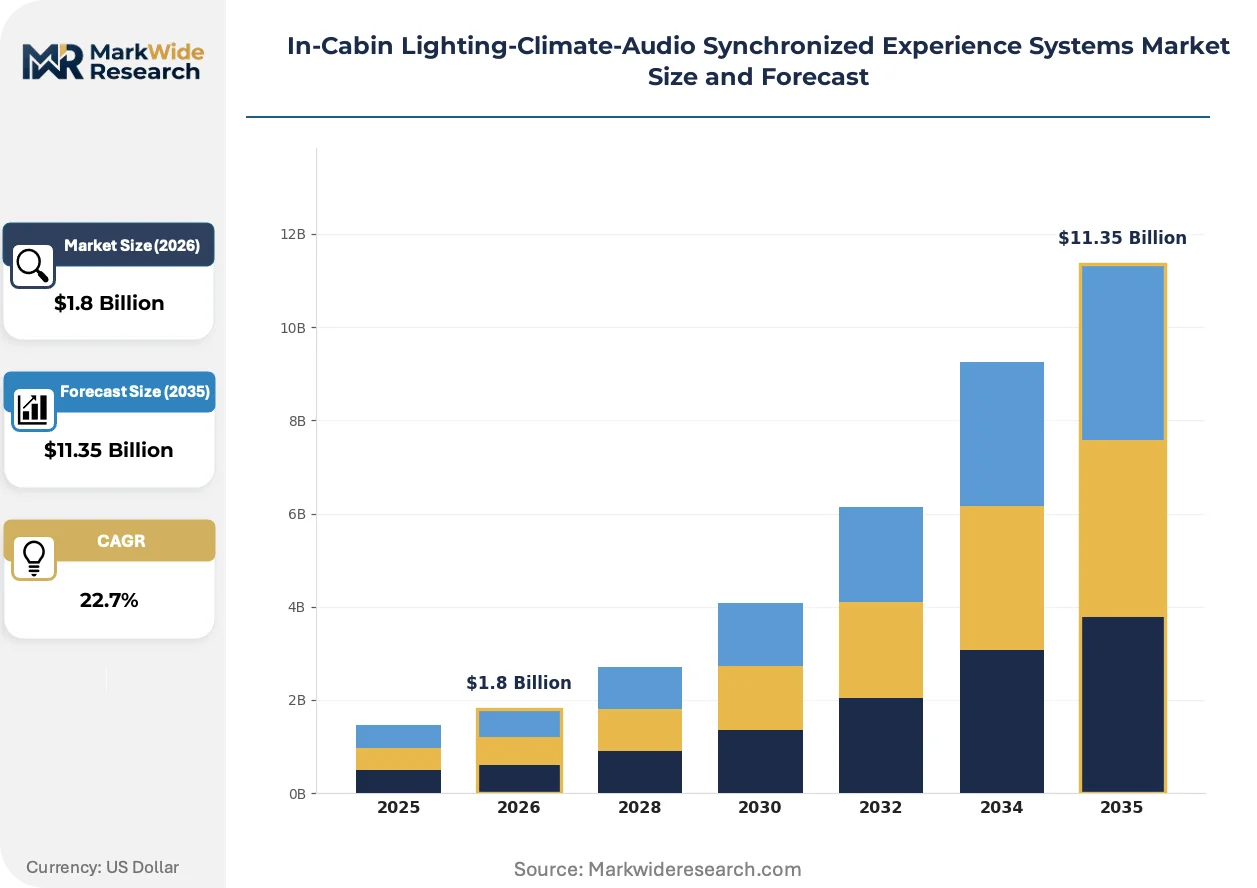
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $11.35 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lighting Systems, Climate Control Units, Audio Devices, Synchronization Controllers, Sensors Technology: LED, OLED, Thermal Sensors, Acoustic Signal Processing, Bluetooth Connectivity Application: Personal Vehicles, Commercial Transportation, Public Transit, Luxury Coaches, Autonomous Pods End User: Vehicle Manufacturers, Tier-1 Suppliers, Fleet Operators, Ride Sharing Services, Aftermarket Retailers |
| Companies Covered | Continental, HARMAN International, Valeo, Forvia, HELLA, Visteon, Magna International, Panasonic Automotive Systems, Gentherm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In-Cabin Lighting-Climate-Audio Synchronized Experience Systems Market Trends and Innovations
Centralized domain controllers are displacing distributed cabin electronics, compressing supplier tiers while enabling real-time biometric-responsive environments that unify previously siloed comfort systems.
OLED surface illumination is automating climate-feedback visual cues directly into interior panels, eliminating discrete indicator clusters. Premium electric vehicle OEMs in Germany and Scandinavia deploy these embedded technologies fastest, collapsing the distinction between decorative ambient lighting and functional thermal status communication into single hardware layers.
NHTSA distracted-driving guidelines and the EU's General Safety Regulation frame mandatory eyes-free interface standards that prohibit complex menu navigation during vehicle motion. These rules force automakers toward predictive, biometric-triggered cabin adjustments rather than occupant-initiated controls, privileging suppliers with integrated sensor-controller portfolios over point-solution vendors.
Fleet procurement of synchronized wellness systems is consolidating around long-term service contracts that bundle hardware, software updates, and predictive maintenance for robotaxi operators. This model displaces traditional component sourcing in North American and Chinese autonomous vehicle programs, where uptime guarantees and remote diagnostics outweigh upfront unit economics in supplier selection criteria.
In-Cabin Lighting-Climate-Audio Synchronized Experience Systems Market Segmentation
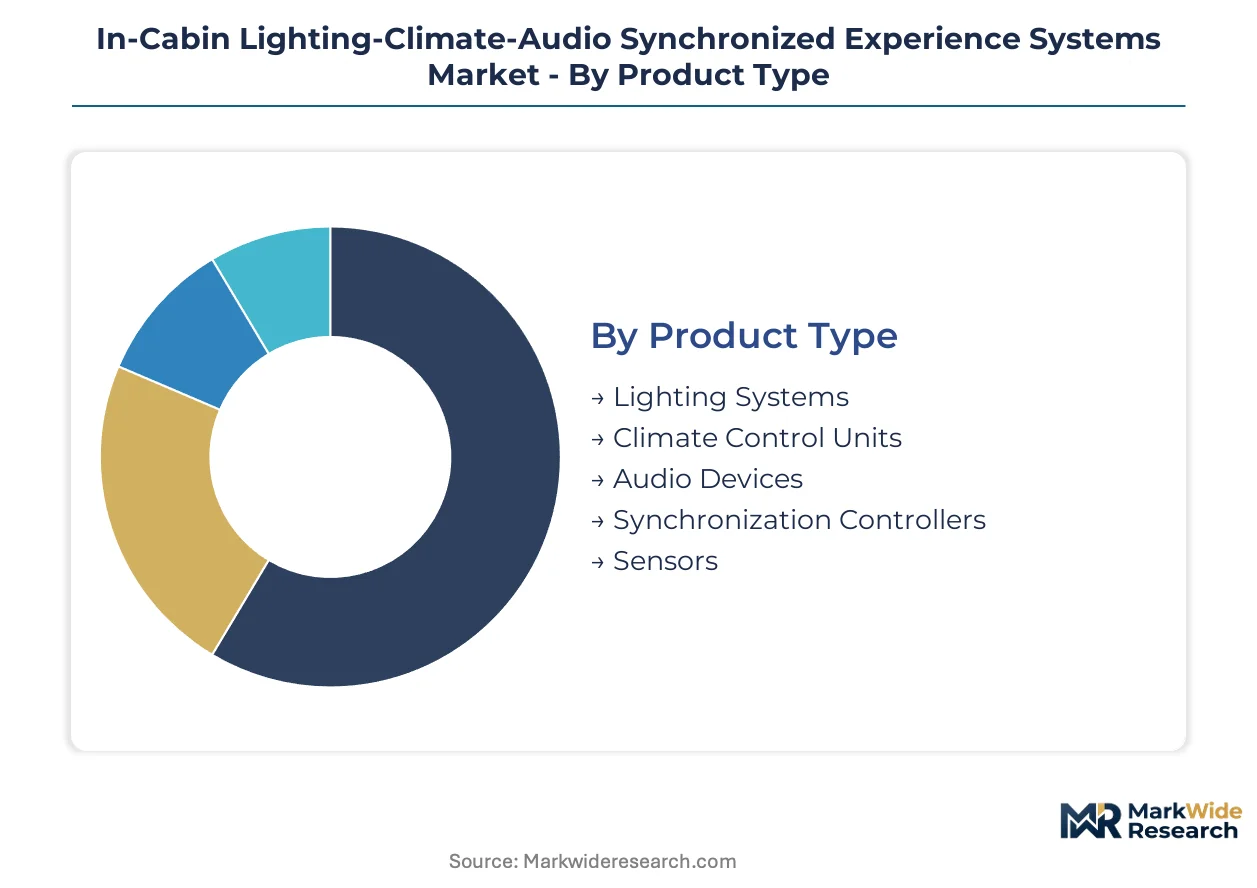
Segmentation in this market reveals how value migrates from commodity hardware toward intelligent orchestration layers. Upgrade cycles differ sharply across product categories, with synchronization controllers replacing at software-speed while lighting hardware follows slower vehicle-platform rhythms.
Product Type:
Replacement-cycle timing varies dramatically across product categories, forcing suppliers to maintain dual development velocities.
- Lighting Systems:LED and OLED surface technologies dominate new vehicle programs, with spectral-tunable architectures enabling climate-feedback visual integration directly into interior panels. German premium electric vehicle OEMs specify these for wellness-package bundling, though legacy 12V platform compatibility constraints delay retrofit penetration.
- Synchronization Controllers:Centralized domain controllers orchestrate sub-100ms latency coordination across lighting, thermal, and audio subsystems through unified firmware stacks. Demand concentrates in autonomous pod applications where predictive biometric-triggered cabin adjustments replace occupant-initiated controls.
- Climate Control Units:Thermal actuator modules with real-time API exposure for wellness orchestration.
- Audio Devices:Spatial audio field-shaping hardware tied to lighting mood-state algorithms.
- Sensors:Biometric fusion arrays capturing occupant state for dynamic environmental response.
Volume placements concentrate in Lighting Systems; the faster expansion belongs to Synchronization Controllers.
Technology:
Cost-tier stratification separates premium OLED and advanced acoustic processing from baseline LED and Bluetooth configurations.
- OLED:Surface-emitting panels embed climate-status communication into decorative interior elements, collapsing functional and ambient layers. Scandinavian premium electric vehicle programs deploy these fastest, though Asian display manufacturing concentration creates supply vulnerability.
- Acoustic Signal Processing:Digital signal pipelines enable real-time audio field shaping synchronized to lighting spectral output and thermal actuator response. Robotaxi fleet operators prioritize this technology for occupant-experience differentiation in driverless cabin environments.
- LED:Established solid-state illumination with limited spectral tunability.
- Thermal Sensors:Occupant skin-temperature and cabin-zone monitoring arrays.
- Bluetooth Connectivity:Legacy wireless protocol for smartphone-cabin interface bridging.
Cost tiers stratify around OLED at premium levels and LED at economy; acoustic signal processing climbs fastest on autonomous vehicle demand.
Application:
Customer-type divergence separates experience-optimized autonomous platforms from driver-centric legacy architectures.
- Autonomous Pods:Robotaxi and shuttle segments eliminate steering-wheel constraints entirely, enabling 360-degree wellness-optimized lighting-climate-audio environments. Fleet procurement here consolidates around long-term service contracts bundling hardware, software updates, and predictive maintenance.
- Personal Vehicles:Premium electric vehicle platforms bundle synchronized systems as single-option wellness packages rather than à la carte configurations. Germany's KBA type-approval protocols for automated driving modes constrain how sequences deploy, exporting design standards to adjacent European markets.
- Commercial Transportation:Fleet-duty durability requirements with standardized cabin configurations.
- Public Transit:High-occupancy vehicle specifications with simplified synchronization needs.
- Luxury Coaches:Long-haul passenger comfort applications with extended-duration wellness programming.
Application volume centers on Personal Vehicles; Autonomous Pods gain share fastest on fleet electrification timelines.
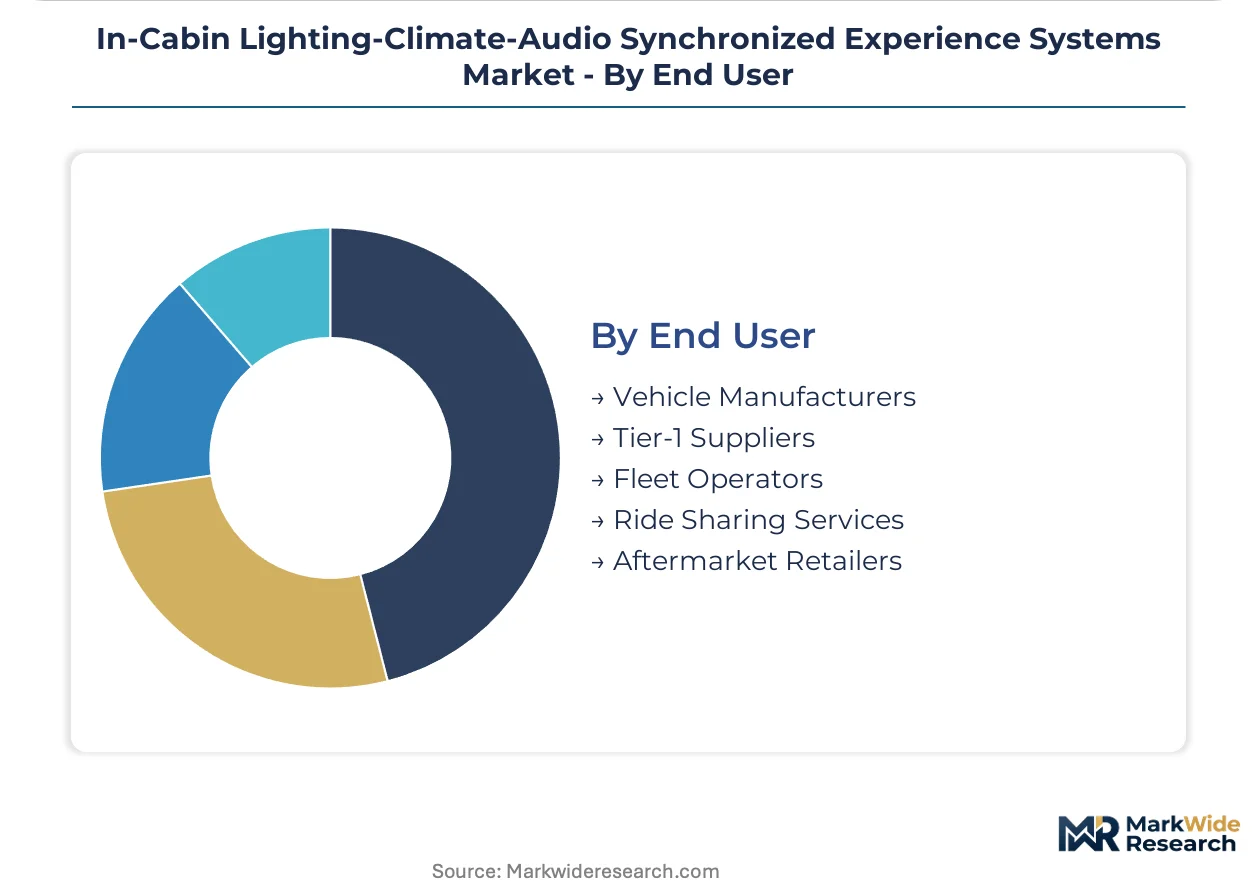
End User:
Supply-chain positioning determines margin capture, with vehicle manufacturers and tier-1 suppliers controlling architecture specification.
- Vehicle Manufacturers:Premium electric vehicle OEMs in Germany and Scandinavia pioneer occupant-centric cockpit architectures, bundling ambient lighting with thermal and acoustic subsystems as unified wellness packages. NHTSA distracted-driving guidelines and EU General Safety Regulation mandate integrated eyes-free controls, compressing supplier qualification timelines.
- Fleet Operators:Robotaxi and shuttle fleet managers prioritize uptime guarantees and remote diagnostics over upfront unit economics, displacing traditional component sourcing with long-term service contracts. This procurement model demands predictive maintenance capabilities and over-the-air update infrastructure.
- Tier-1 Suppliers:Cross-domain electronics integrators supplying controller and sensor modules.
- Ride Sharing Services:Vehicle-as-a-service platforms with standardized cabin experience requirements.
- Aftermarket Retailers:Retrofit synchronization kits for legacy vehicle compatibility.
End-user volume concentrates with Vehicle Manufacturers; Fleet Operators expand most quickly on autonomous service launches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates production of advanced cabin electronics while the United States and China absorb the largest deployment volumes for synchronized wellness systems.
Germany
Premium electric vehicle OEMs headquartered in Stuttgart and Munich specify integrated lighting-climate-audio packages as standard equipment. KBA type-approval protocols for automated driving modes constrain sequence deployment timing, accelerating hardware-software integration requirements. The Baden-Württemberg automotive cluster anchors Continental and Valeo development centers for cross-domain controller architectures.
United States
Robotaxi fleet operators in California and Arizona prioritize uptime-optimized wellness environments for autonomous passenger pods. NHTSA distracted-driving guidelines mandate eyes-free cabin controls, compressing supplier qualification timelines for integrated systems. The Detroit automotive corridor hosts Visteon and Magna International engineering facilities for North American platform integration.
China
Domestic EV manufacturers bundle synchronized cabin experiences as competitive differentiators in the premium sedan segment. MIIT cybersecurity standards for connected vehicle ecosystems impose extended validation cycles on controller architectures. The Yangtze River Delta manufacturing belt concentrates Panasonic Automotive Systems and local tier-1 suppliers serving domestic OEM demand.
Japan
Automotive electronics specialists supply precision acoustic processing and thermal sensor modules to global OEM programs. METI guidelines for autonomous vehicle safety systems influence cabin-interface design standards exported through Japanese automaker supply chains. The Nagoya-Chubu industrial region houses HELLA and Forvia technical centers for Asia-Pacific platform adaptation.
South Korea
Domestic battery-electric vehicle platforms integrate wellness-optimized cabin architectures as flagship model features. MFDS-aligned automotive safety certification frameworks shape human-machine interface requirements for export markets. The Seoul Capital Area cluster anchors HARMAN International acoustic engineering operations and Gentherm thermal system development for regional OEM programs.
In-Cabin Lighting-Climate-Audio Synchronized Experience Systems Market Competitive Landscape
The competitive structure tilts toward diversified automotive electronics conglomerates with cross-domain integration capabilities. Tier-1 suppliers with established lighting, thermal, and audio portfolios dominate architecture specification, while specialized sensor and controller vendors occupy niche orchestration layers. Two strategic archetypes prevail: integrated cockpit-systems integrators and point-solution specialists with forced partnering strategies. Dominant competitive moves include strategic partnerships for software stack access and geographic co-location with premium EV OEM engineering centers.
Within the integrated-systems tier, Continental, HARMAN International, and Valeo exemplify the cross-domain electronics archetype that automakers favor for unified wellness package sourcing. Continental leverages its broad automotive electronics portfolio to anchor centralized cabin-control architectures. HARMAN International occupies a position defined by acoustic signal processing leadership that enables audio-environment synchronization with lighting mood states. Valeo represents the advanced illumination specialist archetype, embedding climate-feedback visual cues through LED and OLED surface technologies that collapse decorative and functional layers into single hardware configurations.
| Leading Market Players |
|---|
| Continental |
| HARMAN International |
| Valeo |
| Forvia |
| HELLA |
| Visteon |
| Magna International |
| Panasonic Automotive Systems |
| Gentherm |
| Others |
Pricing and Supply Chain Analysis
Fleet procurement consolidation around long-term service contracts for autonomous pods forces suppliers to absorb hardware costs upfront while capturing value through software subscriptions, compressing margins on commodity lighting and audio components while elevating pricing power for synchronization controllers.
Pricing Analysis
Price erosion across LED and audio hardware traces to Asian manufacturing scale and automaker pressure for wellness-package cost containment. Three-tier pricing structure across premium OLED, standard LED, and economy Bluetooth configurations stratifies by certification grade and after-sales service bundling. Fleet operators exhibit highest price sensitivity due to volume procurement leverage, while premium electric vehicle OEMs prioritize integration capability over unit cost.
Supply Chain Analysis
India's PLI scheme for automotive electronics and China's MIIT cybersecurity mandates are reshaping controller and sensor sourcing toward localized manufacturing. OLED surface technologies draw from concentrated South Korean and Chinese display fabrication, while thermal actuators and acoustic processors source from German and Japanese precision electronics clusters. Single-source vulnerability in advanced panel supply exposes automakers to disruption, with distribution running through tier-1 integrators co-located with premium OEM engineering centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cross-domain software engineering scarcity for synchronization controller development props pricing for qualified suppliers, constraining capacity expansion and sustaining margin premiums for incumbents with proven firmware stacks.
For Market Incumbents: Cement controller architecture dominance by deepening in-house production of biometric sensor fusion arrays and thermal actuator modules. Acquire specialized acoustic signal processing firms to block new entrant access to audio-environment synchronization capabilities. Prioritize certification investment for EU General Safety Regulation compliance to compress competitor qualification timelines. For New Entrants and Emerging Players: Begin with aftermarket retrofit synchronization kits for legacy 12V vehicle platforms in cost-sensitive personal vehicle segments. Target India's PLI-subsidized manufacturing zones for controller production serving domestic EV manufacturers. Pursue white-label partnerships with ride-sharing platforms seeking standardized cabin experience specifications. For Investors and Strategic Acquirers: The window for entry favors tier-2 controller specialists with proven sub-100ms latency firmware and established OEM validation relationships. Long-term viability hinges on software-defined vehicle transition timelines and autonomous pod fleet deployment curves. Monitor KBA type-approval protocol expansions as the inflection signal for European market access barriers.| Strategic Initiative | Industry Significance |
|---|---|
| Cross-Domain Controller Acquisition | Consolidates LED driver, thermal, and audio firmware expertise under unified architecture specifications. |
| Biometric Sensor Fusion Partnership | Enables real-time occupant monitoring integration with predictive cabin adjustment algorithms. |
| OLED Surface Technology Licensing | Accelerates climate-feedback visual embedding into interior panel manufacturing. |
| PLI-Aligned India Manufacturing Footprint | Captures cost advantages for controller and sensor production serving Asian EV demand. |
| Fleet Service Contract Infrastructure | Positions suppliers for robotaxi procurement models prioritizing uptime guarantees over unit economics. |
Research Methodology
SEC filings, automotive production databases, and regulatory submission records formed the secondary backbone, supplemented by primary interviews with OEM platform engineers, tier-1 supplier procurement leads, and fleet operator technology directors. Bottom-up and top-down triangulation validated segmentation estimates across lighting systems, synchronization controllers, and sensor modules.
Bottom-up modeling built volume projections from vehicle platform content assumptions, while top-down analysis cross-checked against aggregate wellness-package penetration rates across the projection horizon. Segmentation dimensions spanned product type, technology tier, application archetype, and regional production cluster. CAGRs derived from fitted growth curves incorporating EU regulatory adoption timelines and autonomous pod fleet deployment schedules.
Underlying measurement precision varies by segment; synchronization controllers and biometric sensors carry tighter precision than commodity LED hardware due to supplier concentration. Forecasts reflect assumptions around NHTSA guideline enforcement timing and KBA protocol export adoption. Cybersecurity certification delays or OLED supply disruptions could materially revise trajectory assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Vehicle Trip Computers Market
Telematics and Infotainment
Vehicle Digital Cockpit Market
Telematics and Infotainment
Japan Commercial Telematics Market
Telematics and Infotainment
Electronic Rotary Controller Systems for Infotainment Market
Telematics and Infotainment
Car Generated Data Market
Telematics and Infotainment
Europe Vehicle Remote Diagnostic Market
Telematics and Infotainment
In-Car Apps Market
Telematics and Infotainment
Electric Vehicle Telematics Market
Telematics and Infotainment
Motor Racing Telematics Market
Telematics and Infotainment
Europe Dashboard Camera Market
Telematics and Infotainment
Asia-Pacific Automotive Telematics Market
Telematics and Infotainment
North America Dashboard Camera Market
Telematics and Infotainment
GCC Commercial Telematics Market
Telematics and Infotainment
North America Electronic Toll Collection (ETC) Market
Telematics and Infotainment
Motorcycle Infotainment System Market
Telematics and Infotainment
North America Automotive Navigation System Market