
 Internet of Things Vehicle-To-Vehicle Communication Market | 2026-2036
Internet of Things Vehicle-To-Vehicle Communication Market Size, Share, and Industry Trends Forecast 2026-2036
Internet of Things Vehicle-To-Vehicle Communication Market Foresight
NHTSA's proposed V2V mandate is pivoting the competitive landscape toward DSRC-CV2X dual-mode architectures. Qualcomm Technologies leverages its 5G modem portfolio to anchor premium tier chipset supply for North American OEMs. NXP Semiconductors dominates secure element integration for vehicle identity management, while AutoTalks Ltd specializes in dedicated V2X protocol stacks that sustain interoperability across regional spectrum allocations.
Internet of Things Vehicle-To-Vehicle Communication denotes a networked ecosystem where automobiles exchange kinematic data, traffic state information, and hazard warnings through standardized wireless protocols operating in the 5.9 GHz ITS band or cellular V2X spectra. The primary commercial purpose centers on cooperative awareness messaging that reduces collision incidence and enables predictive traffic flow optimization across mixed-autonomy road networks. C-V2X technology leads deployment momentum due to its 3GPP roadmap continuity and infrastructure reuse potential, while collision avoidance applications command the deepest OEM integration budgets and longest validation cycles. Edge computing deployment models are gaining share fastest among fleet operators seeking sub-10 millisecond decision latency for platooning coordination.
The FCC governs spectrum licensing and equipment authorization for US deployments, while the EU's ETSI-EN 302 636 framework shapes cross-border interoperability requirements that manufacturers must satisfy for CE marking. NHTSA crashworthiness standards and the EU AI Act's safety-critical system classifications are tightening the validation burden on V2X software stacks. Stakeholders must monitor whether spectrum harmonization negotiations between the FCC and European regulators produce unified certification pathways or sustain the current dual-test regime.
Market Dynamics
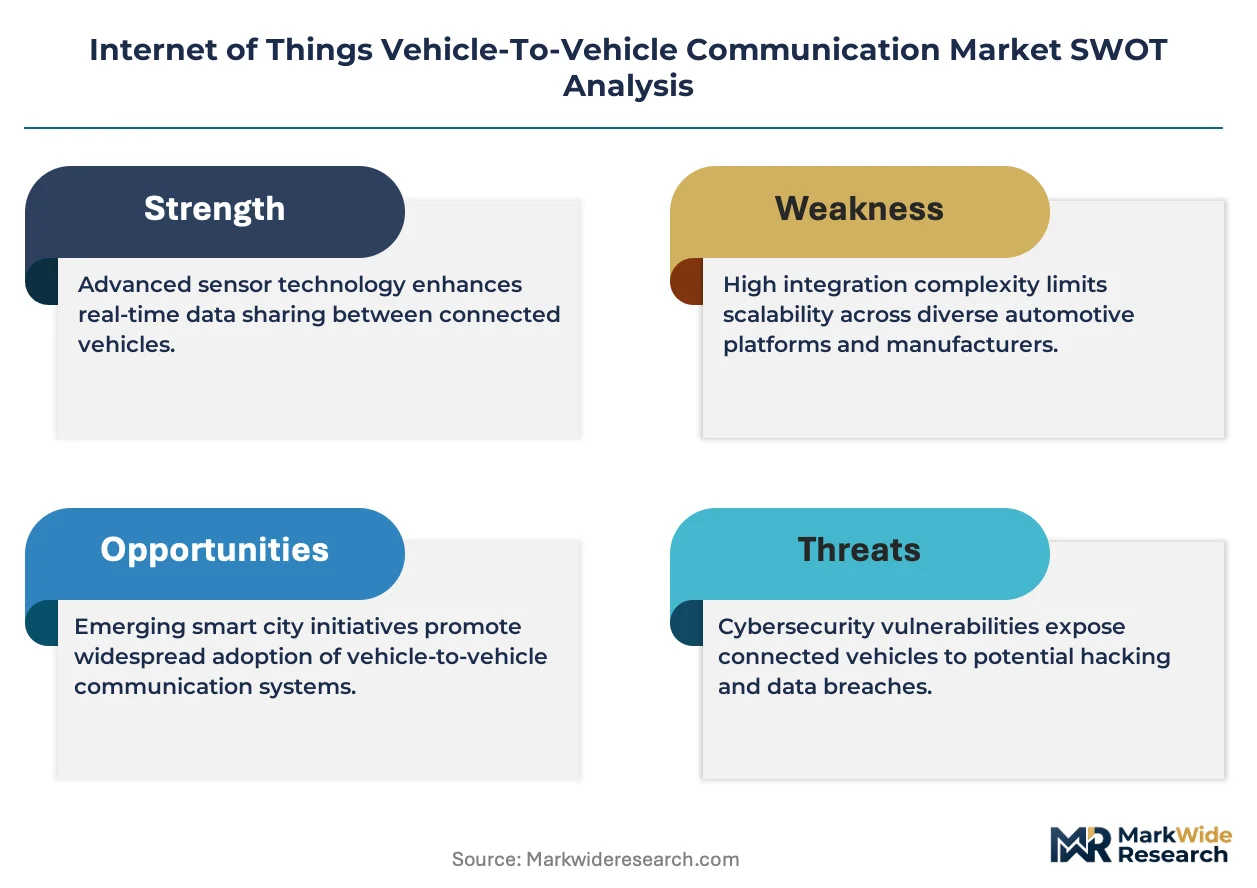
The FCC's spectrum reallocation for C-V2X deployment is compressing certification timelines while fragmenting hardware supply chains between DSRC legacy architectures and cellular-native chipsets.
Growth Catalysts
- Federal infrastructure spending:The Infrastructure Investment and Jobs Act channels dedicated funding toward smart corridor deployments across multiple states, creating concentrated procurement pipelines for roadside units and onboard equipment.
- NHTSA V2V mandate trajectory:Proposed rulemaking for cooperative intelligent transport systems is forcing OEMs to accelerate dual-mode chipset validation cycles and secure element integration.
- Fleet operator digitization:Commercial vehicle operators are deploying edge computing nodes for platooning coordination and predictive maintenance, driving recurring hardware refresh demand.
Market Restraints
- Silicon supply concentration:Secure element fabrication for vehicle identity management concentrates among a limited set of European and East Asian foundries, exposing procurement to geopolitical friction.
- Spectrum harmonization failure:Divergent FCC and ETSI-EN 302 636 channel access rules force manufacturers into dual-test certification regimes that extend time-to-market by 8-14 months.
- DSRC stranded asset risk:Prior investments in dedicated short-range communication infrastructure face accelerated obsolescence as C-V2X gains deployment momentum.
Strategic Opportunities
- Municipal smart corridor underpenetration:Mid-sized US metropolitan areas lack deployed roadside units, creating first-mover advantage for integrated C-V2X infrastructure providers.
- AI-driven hazard prediction convergence:Fusion of edge inference engines with V2X protocol stacks enables real-time kinematic forecasting that pure connectivity cannot achieve.
- State-level zero-emission vehicle mandates:California and New York regulations linking connected vehicle deployment to fleet electrification timelines create bundled procurement opportunities.
Industry Challenges
- Embedded systems cybersecurity certification:ISO/SAE 21434 compliance timelines for V2X software stacks extend 18-24 months, compressing firmware update windows against fixed vehicle launch cycles.
- Cross-functional talent scarcity:Integration of automotive functional safety with telecommunications protocol engineering requires hybrid skill sets that command 40-60% compensation premiums.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Internet of Things Vehicle-To-Vehicle Communication Market |
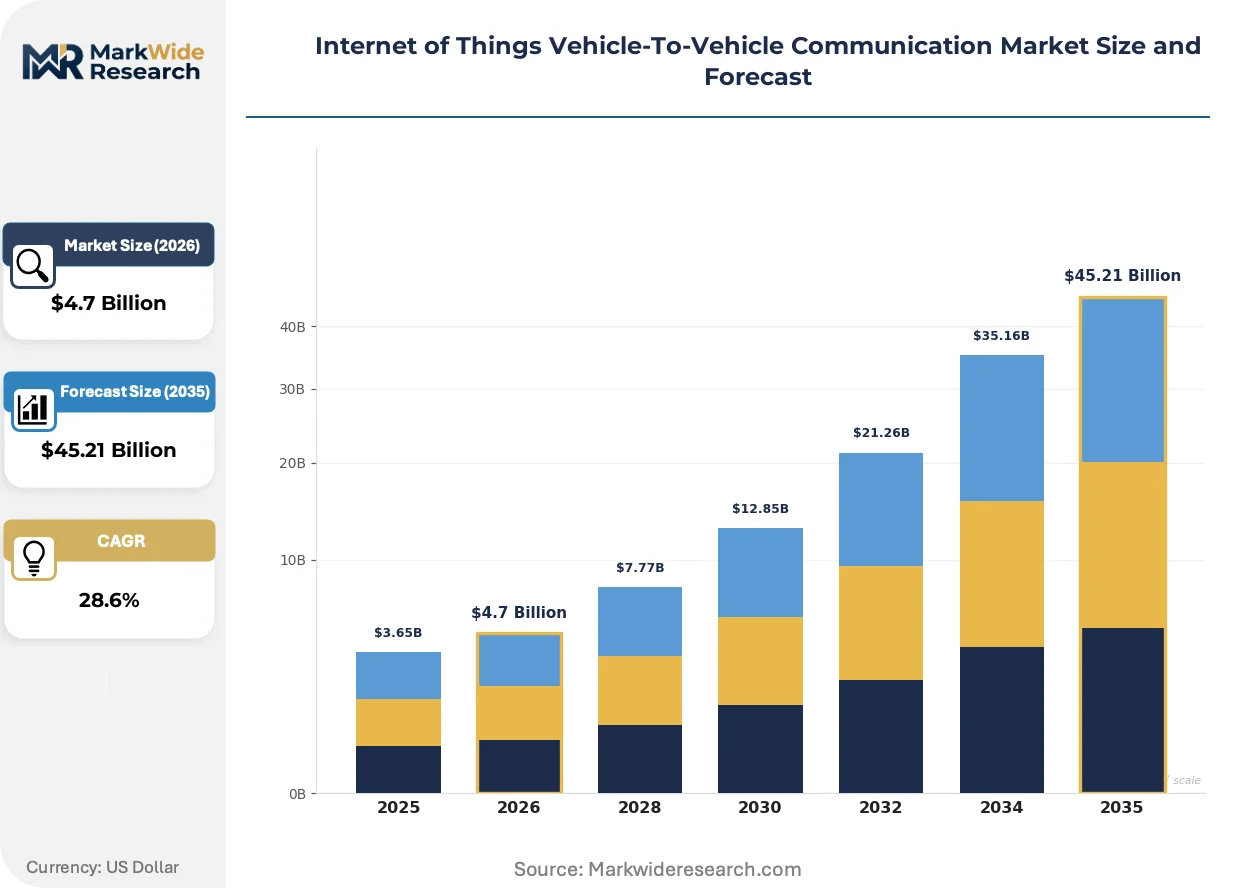
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $45.21 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: DSRC, C-V2X, 5G, Satellite Application: Traffic Management, Collision Avoidance, Fleet Management, Remote Diagnostics End User: OEMs, Fleet Operators, Vehicle Manufacturers, Automotive Service Providers Deployment Model: On-Premises, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | Qualcomm Technologies, NXP Semiconductors, Robert Bosch GmbH, Continental AG, Harman International Industries, AutoTalks Ltd, Denso Corporation, Infineon Technologies, BMW, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Internet of Things Vehicle-To-Vehicle Communication Market Shifts & Advancements
C-V2X technology is compressing the traditional automotive-electronics development cycle while redistributing value capture toward telecommunications infrastructure providers and away from tier-one automotive suppliers.
Edge-native V2X processing architectures are decentralizing hazard detection from centralized cloud pipelines to roadside units and vehicle-mounted compute nodes. Fleet operators are adopting these architectures fastest for platooning applications requiring sub-10 millisecond decision latency. The shift is decentralizing procurement authority from OEM central engineering to regional fleet maintenance divisions.
The EU AI Act's safety-critical system classifications are tightening validation documentation requirements for V2X software stacks deployed in European markets. Manufacturers must now demonstrate algorithmic transparency for collision avoidance decision trees alongside traditional functional safety metrics. European OEMs are responding by segregating AI-enabled V2X features into optional subscription tiers that limit regulatory exposure.
Commercial vehicle procurement is consolidating around integrated telematics-V2X platforms that bundle connectivity, compliance reporting, and predictive maintenance. Long-haul fleet operators are displacing point-solution vendors with full-stack providers offering unified hardware-software contracts. The consolidation is most visible across interstate freight corridors in Texas, Ohio, and Illinois where large fleet density supports vendor scale economics.
Internet of Things Vehicle-To-Vehicle Communication Market Segmentation
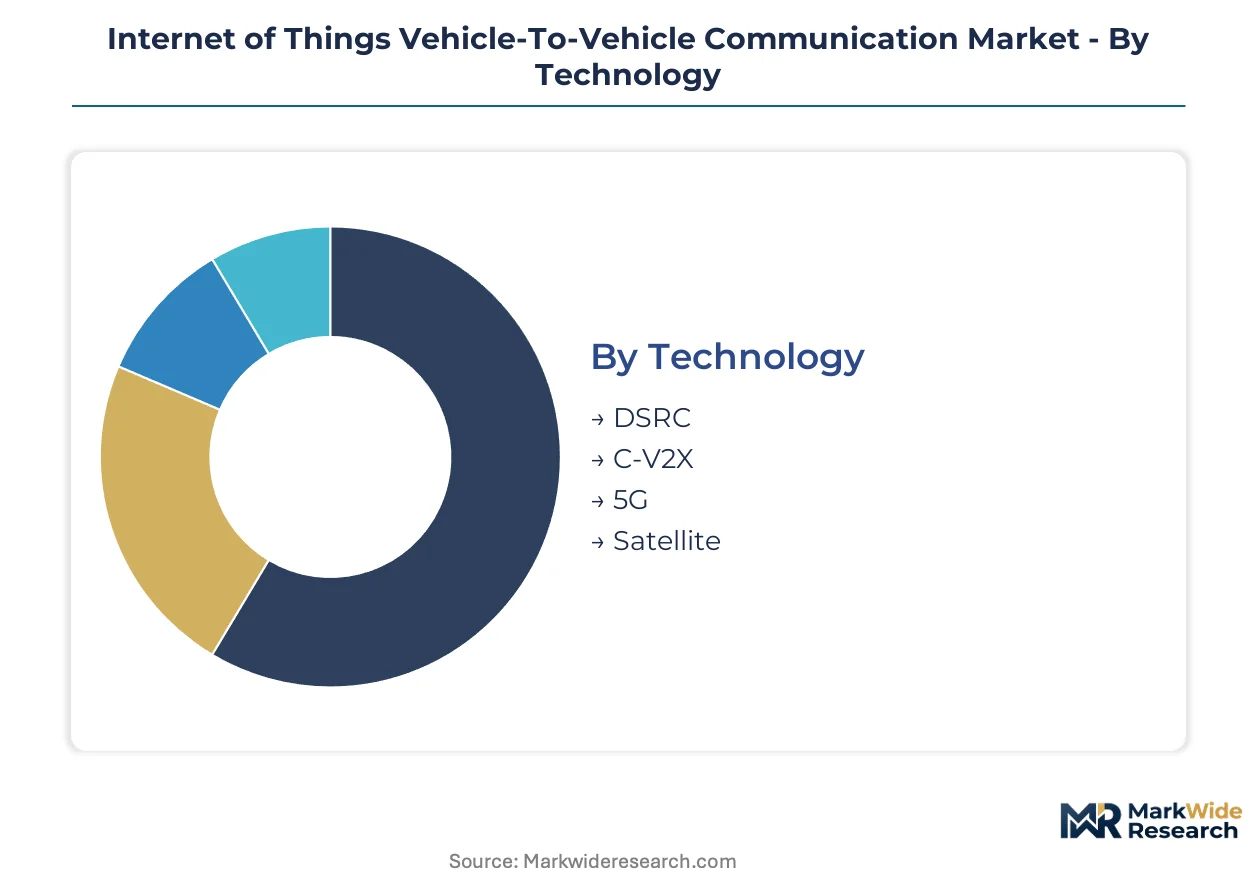
Technology selection dictates hardware certification pathways and spectrum access economics for V2X deployments. Application requirements determine latency thresholds and compute architecture choices. End-user procurement patterns shape whether sales cycles run through OEM central engineering or regional fleet operations.
Technology:
Protocol choice governs infrastructure reuse potential and regulatory compliance burden across deployment geographies.
- DSRC:Dedicated short-range communication operates in the 5.9 GHz ITS band with mature roadside unit deployments along US interstate corridors. Prior infrastructure investments face accelerated obsolescence risk as FCC spectrum reallocations favor cellular-native architectures.
- C-V2X:Cellular vehicle-to-everything leverages 3GPP roadmap continuity and existing tower infrastructure, compressing deployment timelines for municipal smart corridors. Demand concentrates in the United States where federal infrastructure spending channels procurement toward integrated C-V2X systems.
- 5G:Ultra-reliable low-latency communication enables sub-10 millisecond kinematic coordination for platooning applications.
- Satellite:Complementary coverage for rural corridors lacking terrestrial infrastructure density.
Mature deployment sits with DSRC. Newer deployment is concentrated in C-V2X.
Application:
Use case complexity determines validation cycle length and OEM integration budget allocation.
- Traffic Management:Cooperative awareness messaging optimizes signal timing and flow prediction across mixed-autonomy networks. State-level smart corridor initiatives in Texas, Ohio, and Illinois create concentrated procurement pipelines for traffic state information systems.
- Collision Avoidance:Real-time hazard warning protocols command the deepest validation cycles and longest safety certification timelines under NHTSA crashworthiness standards. OEMs allocate premium integration budgets to kinematic data exchange for autonomous emergency braking coordination.
- Fleet Management:Expanding most quickly as commercial operators pursue predictive maintenance and real-time coordination capabilities.
- Remote Diagnostics:Over-the-air software updates and health monitoring for distributed vehicle populations.
Regulatory pressure centers on collision avoidance. Commercial ROI clarity sits with fleet management.
End User:
Procurement authority distribution determines whether vendors sell through tier-one supplier channels or direct to operator maintenance divisions.
- OEMs:Central engineering organizations specify dual-mode chipset architectures and secure element integration for new vehicle platforms. NHTSA proposed mandate timelines are compressing validation cycles for cooperative intelligent transport systems.
- Fleet Operators:Regional maintenance divisions are displacing point-solution vendors with full-stack providers offering unified hardware-software contracts across interstate freight corridors. Edge computing procurement authority is decentralizing fastest among long-haul operators.
- Vehicle Manufacturers:Assembly-line integration of V2X modules during production.
- Automotive Service Providers:Aftermarket installation and maintenance for legacy fleet retrofits.
Volume concentration sits with OEMs. Procurement velocity sits with fleet operators.
Deployment Model:
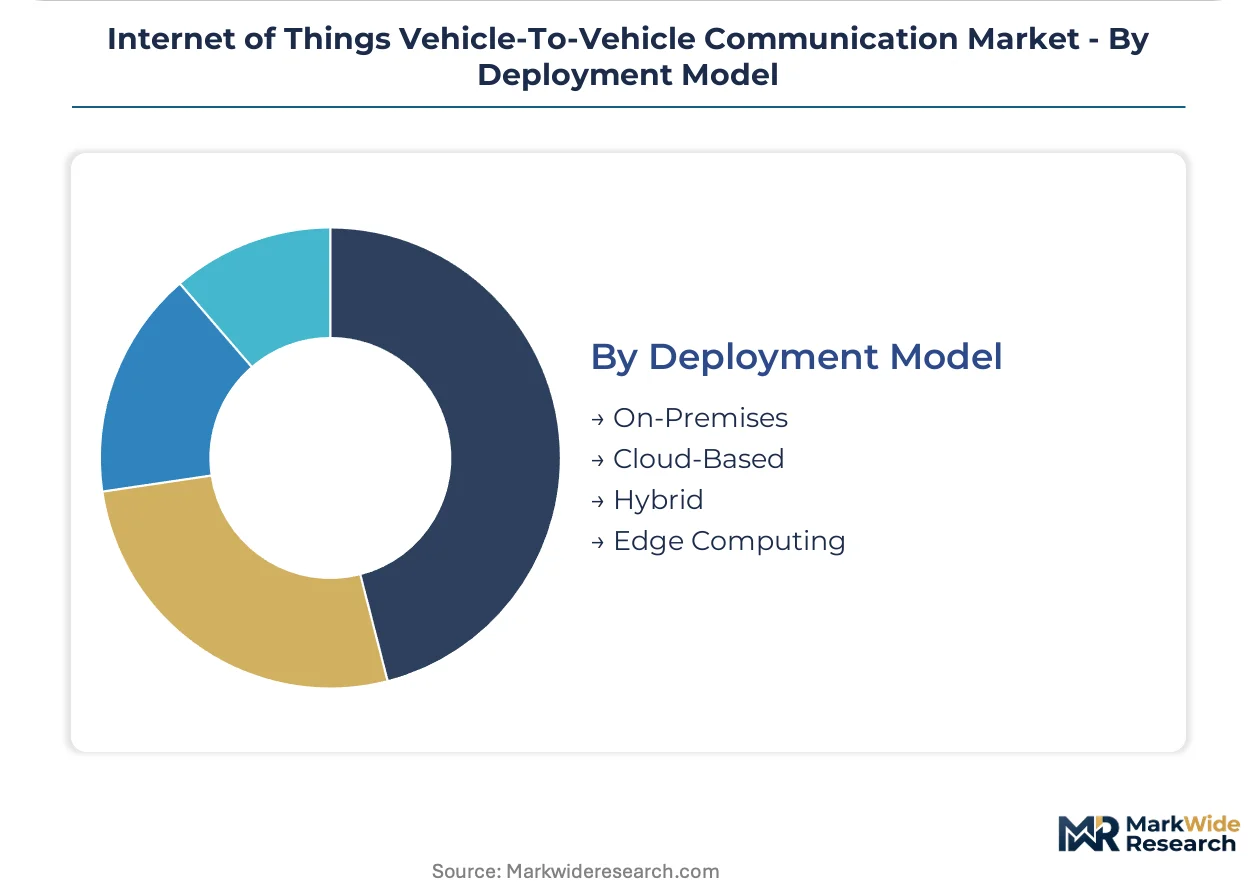
Compute architecture choice trades latency performance against capital expenditure and operational complexity.
- On-Premises:Dedicated roadside unit infrastructure with localized data processing and storage. Municipal deployments in California and New York bundle connected vehicle systems with zero-emission fleet electrification timelines.
- Cloud-Based:Centralized kinematic data aggregation and predictive analytics for traffic flow optimization. FCC spectrum allocations shape channel access economics for backhaul-dependent architectures.
- Hybrid:Split processing between edge nodes and cloud pipelines for cost-latency optimization.
- Edge Computing:Gaining share fastest among fleet operators seeking sub-10 millisecond decision latency for platooning coordination without backhaul dependency.
Capital efficiency sits with cloud-based. Latency-critical applications sit with edge computing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Guangdong and Jiangsu provinces are concentrating connected vehicle component manufacturing, while federal infrastructure corridors in the United States channel deployment capital toward interstate freight networks.
United States
The Infrastructure Investment and Jobs Act directs procurement toward smart corridor deployments across Texas, Ohio, and Illinois interstate freight routes. NHTSA proposed rulemaking for cooperative intelligent transport systems compresses OEM validation cycles for dual-mode chipsets. Michigan's automotive engineering cluster anchors secure element integration testing for North American vehicle identity management platforms.
Germany
Baden-Württemberg's OEM central engineering organizations specify ETSI-EN 302 636 compliant architectures for cross-border European deployments. The EU AI Act's safety-critical system classifications tighten validation documentation requirements for collision avoidance software stacks. Stuttgart's automotive supplier ecosystem concentrates secure element fabrication for vehicle identity management across EU member states.
China
Yangtze River Delta metropolitan authorities bundle C-V2X roadside unit deployment with municipal smart city infrastructure tenders. MIIT spectrum allocations for cellular vehicle-to-everything shape channel access economics for domestic chipset certification. Shanghai's telecommunications equipment cluster anchors 5G modem supply for regional OEM platform integration.
Japan
Kanto region fleet operators adopt edge computing architectures for platooning coordination along Tokyo-Osaka freight corridors. METI standards harmonization initiatives with 3GPP roadmaps compress cellular-native chipset deployment timelines. Nagoya's automotive electronics cluster validates sub-10 millisecond latency protocols for commercial vehicle kinematic coordination.
South Korea
Seoul Capital Area municipal authorities procure integrated C-V2X traffic management systems for mixed-autonomy network optimization. National spectrum harmonization with FCC channel access rules enables dual-test certification pathway efficiency for export-bound hardware. Busan-Ulsan's semiconductor fabrication complex supplies secure elements for Asia-Pacific vehicle identity management deployments.
Internet of Things Vehicle-To-Vehicle Communication Market Competitive Landscape
North American producers anchor the premium-tier chipset supply; European specialists hold secure element integration and automotive functional safety certification. The vendor base organizes around three strategic archetypes: telecommunications infrastructure providers leveraging 3GPP roadmap continuity, automotive semiconductor fabricators with ISO 26262 compliance capabilities, and dedicated V2X protocol stack developers sustaining interoperability across regional spectrum allocations. Competitive dynamics center on M&A activity consolidating point-solution vendors into full-stack platform providers, and strategic partnerships between chipset suppliers and municipal infrastructure operators securing first-mover corridor deployment rights.
Within the telecommunications-centric tier, Qualcomm Technologies and NXP Semiconductors exemplify divergent positioning strategies. Qualcomm Technologies occupies a position anchored to 5G modem portfolio leverage for premium-tier North American OEM supply. NXP Semiconductors represents the secure element integration specialist archetype, with automotive functional safety certification capabilities concentrated for vehicle identity management. AutoTalks Ltd sits within the dedicated protocol developer category, sustaining interoperability architectures across FCC and ETSI-EN 302 636 channel access regimes.
| Leading Market Players |
|---|
| Qualcomm Technologies |
| NXP Semiconductors |
| Robert Bosch GmbH |
| Continental AG |
| Harman International Industries |
| AutoTalks Ltd |
| Denso Corporation |
| Infineon Technologies |
| BMW |
| Others |
Supply & Pricing Matrix
Secure element fabrication costs for vehicle identity management flow through three distinct pricing tiers downstream, with FCC-certified C-V2X chipsets commanding premiums over legacy DSRC modules due to compressed certification timelines and dual-mode validation requirements.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent procurement from scheduled volume commitments, with municipal smart corridor deployments paying 15-25% premiums for sub-90-day chipset delivery against standard 6-month OEM production cycles. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—ISO/SAE 21434-compliant stacks with NHTSA pre-validation command tier-one positioning, while uncertified reference designs compete on spot pricing. Pricing pressure stems from silicon supply concentration among East Asian foundries, compressing margins for mid-tier automotive semiconductor fabricators. Fleet operators exhibit highest price sensitivity due to recurring hardware refresh cycles, whereas OEM central engineering tolerates premium positioning for platform-integrated secure elements.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for 5G modem silicon, while European foundries in Germany and France anchor secure element fabrication for vehicle identity management. Raw material dependencies span gallium nitride substrates for high-frequency RF components, automotive-grade silicon wafers, and rare earth elements for magnetics in roadside unit power supplies. Supply chain risk concentrates in tariff exposure for cross-border chipset shipments between Asia-Pacific fabrication hubs and North American OEM assembly plants. Distribution runs through tier-one automotive supplier channels for OEM-integrated modules, while fleet operator procurement bypasses traditional supplier hierarchies through direct contracts with full-stack platform providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Internet of Things Vehicle-To-Vehicle Communication Market sits in a technology-transition phase as C-V2X architectures displace stranded DSRC infrastructure investments, forcing stakeholders to recalibrate competitive positioning around 3GPP roadmap continuity and spectrum harmonization outcomes.
For Market Incumbents: To counter DSRC stranded asset risk and emerging telecommunications infrastructure provider encroachment, Qualcomm Technologies and NXP Semiconductors should accelerate backward integration into secure element foundry capacity in Germany and Taiwan. Certification investment in dual FCC-ETSI-EN 302 636 compliance pathways preserves channel access across Atlantic procurement pipelines, while channel control through exclusive municipal smart corridor partnerships locks out point-solution competitors in Texas and Ohio freight corridors. For New Entrants and Emerging Players: Direct-to-fleet digital sales channels bypass entrenched tier-one supplier relationships, enabling specialized edge computing vendors to capture procurement authority decentralizing toward regional fleet maintenance divisions. Mid-sized metropolitan areas in Illinois and California represent the most penetrable geography, lacking deployed roadside unit infrastructure and bundling connected vehicle deployment with zero-emission fleet electrification timelines. A hardware-as-a-service subscription model with predictive maintenance software bundling neutralizes upfront capital barriers for price-sensitive long-haul operators. For Investors and Strategic Acquirers: FCC spectrum reallocation finalization is the leading indicator that C-V2X deployment momentum will accelerate, signaling consolidation opportunity among dedicated V2X protocol stack developers sustaining interoperability across regional allocations. Acquisition targets should profile as vertically integrated specialists combining ISO 26262 functional safety certification with telecommunications protocol engineering capabilities, commanding scarcity premiums in talent-constrained labor markets. The signal to watch is NHTSA proposed rulemaking advancement for cooperative intelligent transport systems, which would mandate dual-mode chipset penetration and expand addressable hardware volumes across North American OEM platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Mode Chipset Platform Standardization | DSRC-CV2X architectures satisfy NHTSA mandate trajectories while preserving legacy infrastructure optionality for municipal buyers. |
| Secure Element Supply Agreement | Long-term foundry contracts with European and East Asian fabricators mitigate geopolitical friction in vehicle identity management silicon. |
| Edge Computing Software-Defined Vehicle Investment | Sub-10 millisecond platooning coordination capabilities differentiate fleet operator offerings from connectivity-only competitors. |
| Municipal Smart Corridor Partnership | First-mover deployment rights in underpenetrated metropolitan areas lock in recurring roadside unit maintenance revenue streams. |
| Spectrum Harmonization Regulatory Engagement | FCC-ETSI alignment advocacy reduces dual-test certification burdens and compresses time-to-market for export-bound hardware. |
Research Methodology
Independent corroboration across OEM platform engineering directors, fleet operator procurement leads, and municipal transportation authority planners underwrites the qualitative findings on procurement authority decentralization. Primary interviews with telecommunications infrastructure providers, automotive semiconductor fabricators, and dedicated V2X protocol stack developers were cross-referenced against FCC equipment authorization databases, NHTSA rulemaking dockets, and ETSI-EN 302 636 certification registries. Secondary validation drew from Infrastructure Investment and Jobs Act funding allocation disclosures, state-level smart corridor procurement records, and 3GPP roadmap documentation. Bottom-up triangulation across chipset shipment volumes and top-down reconciliation against federal infrastructure spending envelopes anchored market size estimation.
Rate-of-change decomposition across the analysis window separated technology substitution effects from greenfield deployment expansion, with C-V2X penetration curves modeled against DSRC infrastructure depreciation schedules. Segmentation dimensions span protocol architecture, application latency requirements, end-user procurement authority distribution, and deployment model compute architecture. Automotive functional safety certification timelines, spectrum harmonization negotiation status, and fleet electrification mandate synchronization served as industry-specific forecast inputs, with growth rates derived from infrastructure spending elasticity and OEM platform cycle alignment.
The model holds under continued FCC C-V2X spectrum allocation stability and sustained federal infrastructure appropriation levels; deviation in NHTSA mandate timing or ETSI-EN 302 636 channel access rule divergence would shift deployment velocity assumptions. Forecasts reflect documented regulatory trajectories and disclosed procurement pipelines rather than speculative technology adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Telematics Control Unit Market
Telematics and Infotainment
Vehicle to Vehicle (V2V) Communication Market
Telematics and Infotainment
In-Vehicle Infotainment Systems Market
Telematics and Infotainment
Europe Commercial Telematics Market
Telematics and Infotainment
Telematics and Connectivity Processors Market
Telematics and Infotainment
Automotive Dashboard Camera Market
Telematics and Infotainment
Global Automotive Infotainment System Market
Telematics and Infotainment
Park Assist Camera Market
Telematics and Infotainment
Car DVR Market
Telematics and Infotainment
Global Intelligent Transportation System (ITS) Market
Telematics and Infotainment
Video Telematics Market
Telematics and Infotainment
Connected Car Market
Telematics and Infotainment
Fleet Telematics System Market
Telematics and Infotainment
Global Automotive Navigation System Market
Telematics and Infotainment
Trailer Telematics Market
Telematics and Infotainment
APAC Telematics Market