
 Brazil Automotive Tire Market | 2026-2036
Brazil Automotive Tire Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Automotive Tire Market Insights
A shortage of certified tire technicians and compound engineers is unwinding production capacity expansion plans across southeastern Brazil. Bridgestone Corporation leverages its captive rubber processing facilities near Bahia to secure raw material continuity. Michelin Group anchors its premium positioning through sustained investment in fuel-efficient tread formulations for domestic OEM supply. Continental AG competes aggressively in the fleet services channel, where long-term service contracts lock in replacement volume.
Brazil automotive tires are reinforced rubber-composite structures engineered to withstand dynamic loads, thermal cycling, and abrasive road surfaces across tropical and subtropical climates; they incorporate steel belts, synthetic polymers, and silica-enhanced compounds to optimize grip and durability under varying payload conditions. Their primary purpose is to ensure vehicle safety, fuel efficiency, and operational uptime across passenger, commercial, and two-wheeler mobility platforms. Passenger car tires dominate volume throughput due to Brazil's expansive personal vehicle parc, while truck tires command disproportionate margin contribution from mining and agribusiness fleet operators. The replacement application channel generates the steadiest revenue flow, though OEM supply relationships determine brand positioning and technical credibility with downstream buyers.
ANVISA oversees chemical substance restrictions in tire manufacturing, while INMETRO mandates fuel-efficiency labeling that directly influences consumer purchasing decisions and importer market access. The national environmental regulator, IBAMA, enforces end-of-life tire disposal protocols that compel producers to fund collection and recycling infrastructure. Stakeholders must monitor pending updates to PROCONVE emission standards, as tighter vehicle-efficiency targets will cascade into tire rolling-resistance specifications and compound reformulation requirements.
Market Dynamics
INMETRO fuel-efficiency labeling mandates are compressing profit margins on entry-grade tires while forcing compound reformulation investments across domestic manufacturing lines.
Growth Catalysts
- Agribusiness fleet expansion:Large-scale soy and sugarcane operators in Mato Grosso and São Paulo are extending replacement cycles through premium radial adoption, creating sustained aftermarket pull.
- PROCONVE alignment pressure:Pending emission standard updates are cascading into rolling-resistance specifications that reward low-hysteresis compound development.
- Synthetic rubber localization:Petrobras petrochemical complexes in Bahia and Rio Grande do Sul are reducing import dependency for SBR and polybutadiene feedstocks.
Market Restraints
- Natural rubber price volatility:Southeast Asian supply disruptions and currency fluctuations in Thailand and Indonesia transmit directly to Brazilian compound costs.
- Carbon black import concentration:Over sixty percent of reinforcing filler arrives through Santos port, creating single-point vulnerability to customs delays and maritime rate spikes.
- Scrap tire processing lag:IBAMA end-of-life protocols outpace installed pyrolysis and crumb rubber capacity, forcing producers to fund underperforming collection cooperatives.
Strategic Opportunities
- Amazon logistics corridor:BR-163 highway paving and warehouse construction around Manaus free trade zone are unlocking commercial tire demand previously served by retread imports.
- Silica-silane integration:Domestic precipitated silica production expansion enables wet-grip compound localization for premium passenger segments.
- Digital fleet management bundling:Tire pressure monitoring and tread-wear telematics are creating attach-rate opportunities in long-haul operator contracts.
Industry Challenges
- Compound engineer scarcity:Federal University of São Paulo and University of Campinas graduate fewer than forty polymer specialists annually, forcing manufacturers to recruit from Argentine and Portuguese labor pools.
- ANVISA chemical notification timelines:New substance approvals for eco-friendly plasticizers and processing aids extend eighteen to twenty-four months, delaying product launches versus Asian competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Automotive Tire Market |
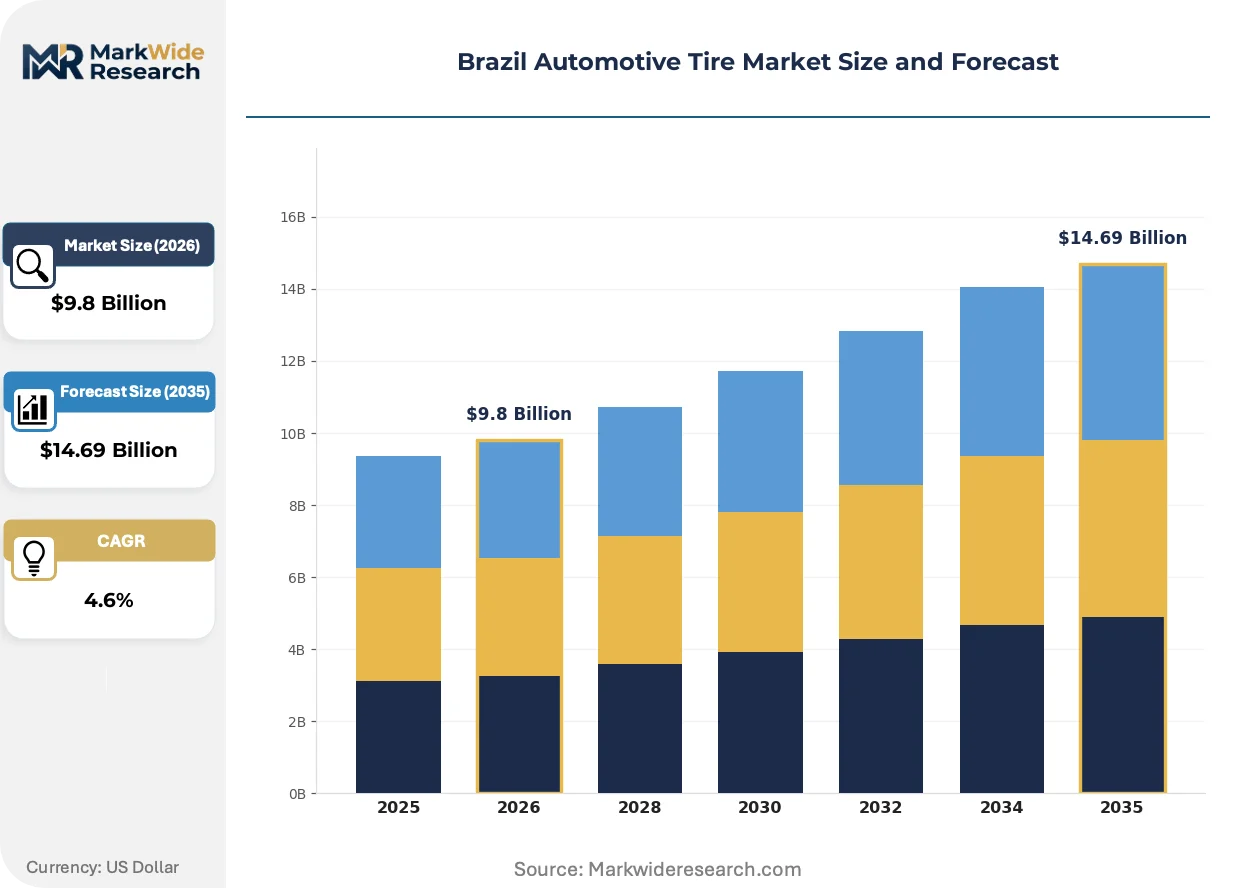
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $14.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passenger Car Tires, Truck Tires, SUV Tires, Motorcycle Tires Application: OEM, Replacement, Fleet Services, Racing Distribution Channel: Online Retail, Physical Store, Wholesalers, Distributors Customer Type: Individual Consumers, Commercial Fleets, Tire Dealers, Auto Shops |
| Companies Covered | Bridgestone Corporation, Michelin Group, Continental AG, Pirelli & C. S.p.A, The Goodyear Tire & Rubber Company, Yokohama Rubber Company, Sumitomo Rubber Industries, Hankook Tire, Toyo Tires, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Automotive Tire Market Trends and Innovations
Active tread sensors and sustainable filler systems are restructuring how tire value is captured and communicated to fleet buyers and individual consumers alike.
Silica-dominant tread compounds are fragmenting the traditional carbon-black paradigm in wet-climate performance tiers. Domestic OEM supply contracts now specify minimum silica loadings for B-segment vehicles, while aftermarket distributors struggle to explain wear-rate tradeoffs to price-sensitive replacement buyers. The technology is fragmenting brand loyalty patterns as performance claims become harder to verify without laboratory testing.
INMETRO labeling enforcement is hardening market access barriers for uncertified imports from Asian trading partners. The mandatory rolling-resistance grading system now covers light commercial vehicles, compelling distributors to reclassify inventory and absorb retesting costs. São Paulo state consumer protection courts are treating mislabeled fuel-efficiency claims as material defects, accelerating compliance investments among mid-tier brands.
Fleet operators are unbundling tire procurement from vehicle lease agreements and negotiating direct multi-year supply contracts with manufacturers. This disintermediation is compressing distributor margins in the heavy-duty segment while rewarding technical service capabilities at the point of mounting and balancing. The pattern is most visible in Minas Gerais mining corridors, where payload optimization contracts now include guaranteed cost-per-kilometer clauses.
Brazil Automotive Tire Market Segmentation
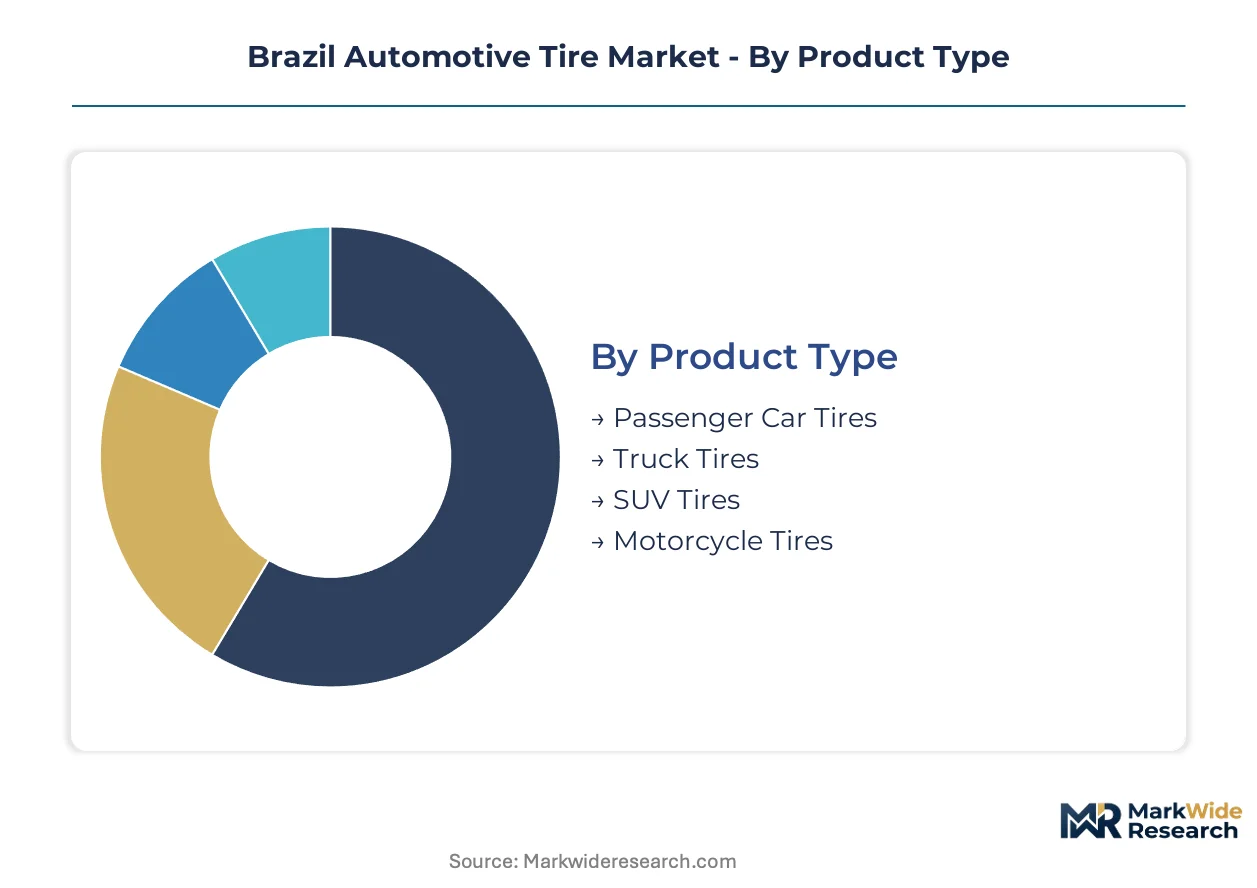
Segmentation in Brazil's automotive tire market reveals how procurement patterns diverge between domestic manufacturing clusters and import-dependent interior regions. Understanding these splits enables suppliers to align compound formulations, distribution investments, and service capabilities with distinct buyer economics across São Paulo's industrial corridor and the expanding Amazon logistics frontier.
Product Type:
Domestic production concentrates on radial passenger and truck tires for OEM supply and fleet replacement, while specialty motorcycle and performance SUV segments rely more heavily on imported finished goods through Santos port.
- Passenger Car Tires:Radial steel-belted constructions with silica-enhanced tread compounds dominate São Paulo state's assembly plant supply. Minas Gerais and Paraná aftermarket distributors move the highest replacement volumes, driven by INMETRO fuel-efficiency labeling compliance requirements that favor certified domestic production over uncertified imports.
- Truck Tires:Heavy-duty radial designs engineered for high-load mining and agribusiness applications incorporate reinforced sidewalls and cut-resistant compounds. Mato Grosso soy operators and São Paulo sugarcane fleets specify premium grades with guaranteed cost-per-kilometer contracts, creating sustained pull for domestic manufacturers with technical service networks.
- SUV Tires:All-terrain and highway-terrain specifications serve Brazil's expanding crossover parc, with demand clustering in southeastern urban centers.
- Motorcycle Tires:Bias-ply and radial options for two-wheeler mobility platforms, concentrated in northeastern urban delivery fleets and recreational segments.
Passenger car tires hold the largest share; momentum sits with truck tires as agribusiness fleet operators extend replacement cycles through premium radial adoption.
Application:
Cost tier separation distinguishes long-term contract-based fleet services from transaction-heavy replacement channels, with OEM supply determining technical credibility and margin structure.
- OEM:Direct supply contracts with domestic vehicle assemblers specify rolling-resistance targets and compound formulations that cascade into aftermarket product development. São Paulo state's automotive corridor anchors this segment, where ANVISA chemical compliance and INMETRO certification requirements create sustained technical barriers for uncertified competitors.
- Replacement:Steadiest revenue flow across Brazil's expansive vehicle parc, served through multi-tier distribution from manufacturer-owned depots to independent tire dealers. Price sensitivity intensifies in northeastern and northern states, where import dependency and logistics costs compress margins on entry-grade offerings.
- Fleet Services:Multi-year supply agreements with mining and agribusiness operators bundle tire procurement with mounting, balancing, and pressure monitoring services. This segment gains share fastest as operators disintermediate traditional distributors and negotiate direct manufacturer relationships with guaranteed uptime clauses.
- Racing:Specialty compounds and constructions for motorsport applications, limited to sanctioned competition circuits and performance enthusiast channels.
OEM supply holds the largest share; fleet services are climbing the fastest as procurement disintermediation reshapes heavy-duty segment economics.
Distribution Channel:
Volume concentration favors physical infrastructure in southeastern industrial zones, while customer type shifts push digital adoption in individual consumer segments.
- Physical Store:Manufacturer-branded retail networks and independent tire dealers dominate transaction volume, particularly for mounting and balancing services requiring technical labor. São Paulo, Rio de Janeiro, and Belo Horizonte metropolitan areas concentrate the highest outlet density, supported by just-in-time inventory replenishment from regional distribution centers.
- Wholesalers:Bulk procurement intermediaries serving interior states and secondary cities, absorbing inventory risk and extending manufacturer reach beyond direct service territories. Bahia and Pernambuco wholesalers bridge the gap between southeastern production and northeastern consumption.
- Online Retail:E-commerce platforms gaining traction in passenger tire replacement, constrained by consumer preference for professional installation and warranty validation.
- Distributors:Authorized regional distributors managing logistics, credit extension, and technical training for dealer networks across defined territories.
Physical stores hold the largest share; online retail is expanding most quickly as digital-native consumers enter the replacement cycle.
Customer Type:
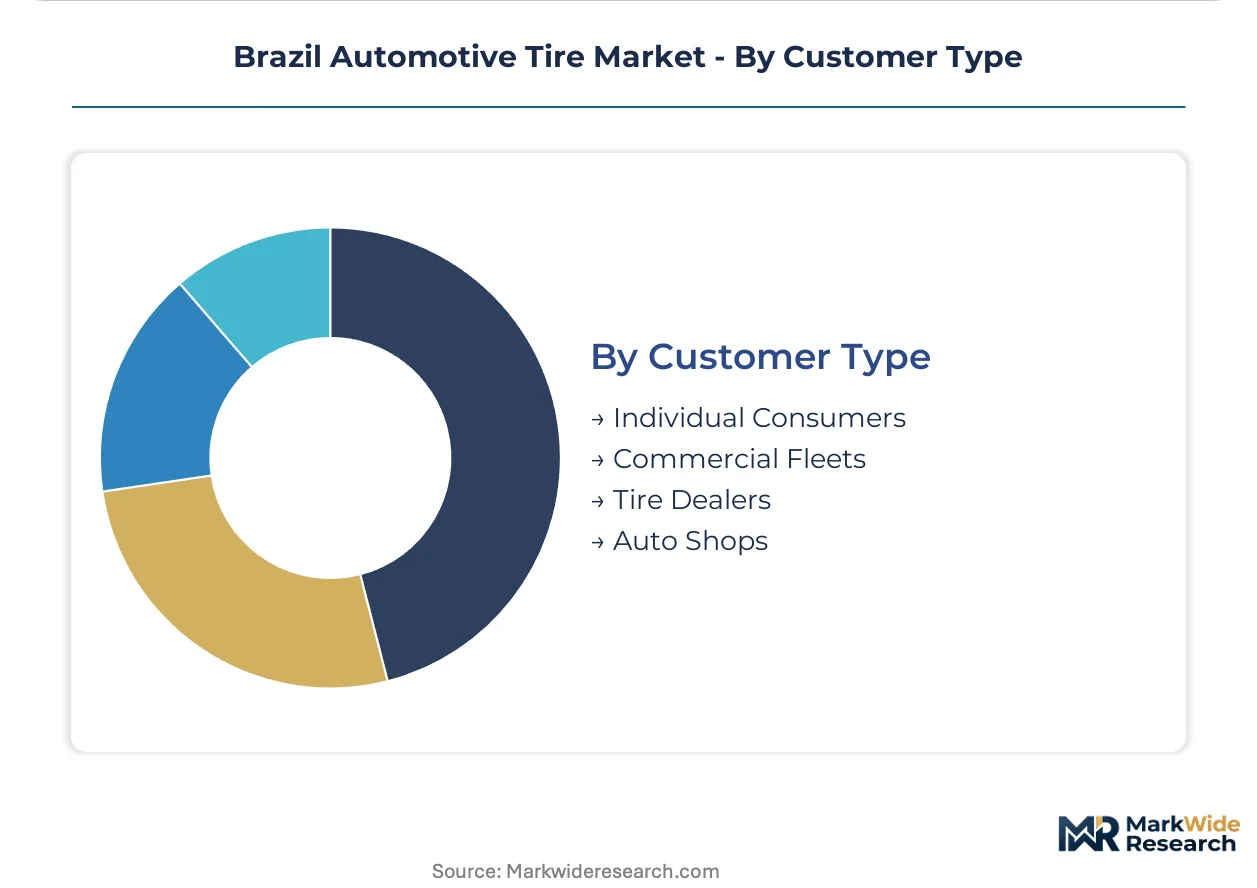
Margin structure varies sharply between price-sensitive individual consumers and contract-anchored commercial fleets, with tire dealers and auto shops capturing service attach-rate economics.
- Commercial Fleets:Mining, agribusiness, and long-haul operators negotiating direct manufacturer contracts with performance guarantees and total-cost-of-ownership optimization. These buyers prioritize technical service capabilities over unit price, concentrating procurement with suppliers offering pressure monitoring integration and predictive maintenance analytics.
- Individual Consumers:Price-driven replacement buyers served through retail and digital channels, with purchasing decisions heavily influenced by INMETRO fuel-efficiency labeling and seasonal promotional cycles.
- Tire Dealers:Independent and franchised outlets capturing margin through installation services, alignment, and extended warranty offerings alongside tire sales.
- Auto Shops:General repair facilities sourcing tires as part of broader maintenance and repair service bundles, with limited brand loyalty and high price sensitivity.
Commercial fleets hold the largest share; tire dealers are gaining share fastest as service bundling and warranty attach rates improve profitability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Southeastern states consume premium radial tires through OEM supply chains and fleet service contracts, while northern and northeastern regions depend on import-heavy replacement channels with compressed margins and extended logistics cycles.
São Paulo
Automotive assembly clusters along the ABC Paulista corridor anchor OEM tire demand, with INMETRO fuel-efficiency labeling mandates shaping procurement specifications for domestic assemblers. ANVISA chemical notification requirements filter compound formulations entering production lines. São Paulo state's industrial corridor concentrates the highest density of manufacturer-owned distribution depots and technical service centers serving both assembly plants and aftermarket channels.
Minas Gerais
Mining and agribusiness fleets in the Iron Quadrangle and Triângulo Mineiro generate heavy-duty tire replacement pull through cost-per-kilometer contracting models. IBAMA environmental enforcement pressures shape end-of-life tire collection obligations for operators in mineral extraction zones. Belo Horizonte metropolitan area anchors regional distribution infrastructure bridging southeastern production with interior consumption.
Mato Grosso
Large-scale soy and sugarcane operators extend replacement cycles through premium radial adoption, creating sustained aftermarket demand disconnected from urban retail channels. Federal agricultural credit programs influence fleet capitalization timing and tire procurement cycles. Cuiabá and Rondonópolis logistics hubs concentrate heavy-duty tire mounting and balancing services for agribusiness operators.
Bahia
Petrobras petrochemical complexes near Camaçari reduce import dependency for synthetic rubber feedstocks, anchoring backward integration strategies for tire manufacturers with captive processing facilities. Port of Salvador handles carbon black and specialty chemical imports for northeastern manufacturing. The state's rubber processing infrastructure supports compound localization for manufacturers serving the northern replacement market.
Amazonas
BR-163 highway paving and warehouse construction around the Manaus free trade zone unlock commercial tire demand previously served by retread imports from Colombian and Peruvian suppliers. IBAMA enforcement of end-of-life protocols lags behind southeastern standards, creating collection infrastructure gaps. Manaus industrial district attracts tire distributors positioning for logistics corridor expansion into Rondônia and Pará.
Brazil Automotive Tire Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with domestic manufacturing presence separating contract-eligible suppliers from import-dependent distributors. The upper tier commands fleet service relationships and OEM supply credibility, while mid-tier competitors concentrate on price-sensitive replacement channels. Three archetypes dominate: multinational manufacturers with captive rubber processing, regional distributors with logistics scale, and niche specialists in performance or motorcycle segments. Competitive moves center on backward integration into raw material processing and multi-year service contracting with agribusiness and mining operators.
Among Japan-based integrated manufacturers, Bridgestone Corporation and Yokohama Rubber Company occupy positions shaped by synthetic rubber localization strategies near Bahia petrochemical complexes. Continental AG represents the European archetype competing through fleet service channel penetration. These three exemplify how manufacturing presence and technical service infrastructure determine access to contract-based procurement in heavy-duty segments.
| Leading Market Players |
|---|
| Bridgestone Corporation |
| Michelin Group |
| Continental AG |
| Pirelli & C. S.p.A |
| The Goodyear Tire & Rubber Company |
| Yokohama Rubber Company |
| Sumitomo Rubber Industries |
| Hankook Tire |
| Toyo Tires |
| Others |
Pricing and Supply Chain Analysis
INMETRO fuel-efficiency labeling gates both manufacturing qualification and price tier separation in Brazil's tire market, compressing margins on uncertified imports while rewarding domestic producers with verified rolling-resistance grades. The certification regime simultaneously filters supply-side participants and segments buyer willingness-to-pay across fleet contract and retail replacement channels.
Pricing Analysis
Long-term offtake agreements with agribusiness and mining fleets anchor pricing stability for domestic manufacturers, while spot-market replacement transactions in northern states absorb volatile import costs and logistics premiums. Three-tier pricing structure across premium, standard, and economy levels reflects INMETRO grade differentiation, with certified A-grade compounds commanding service bundling premiums. Cost compression in entry-grade passenger segments is intensifying because Asian import competition and currency exposure transmit directly to distributor margins. Individual consumers in northeastern states exhibit highest price sensitivity, while Minas Gerais mining operators prioritize guaranteed uptime over unit cost.
Supply Chain Analysis
Santos port customs clearance serves as the primary chokepoint for carbon black and specialty chemical imports, with over sixty percent of reinforcing filler arriving through this single maritime gateway. Thailand, Indonesia, and Vietnam supply natural rubber feedstocks that Brazilian compounders process near Bahia petrochemical complexes. The supply chain rests on Southeast Asian latex pricing volatility and Petrobras synthetic rubber capacity utilization as dual raw material anchors. Single-source vulnerability concentrates in carbon black import pathways, where customs delays cascade to production scheduling. Distribution runs through manufacturer-owned depots in São Paulo's ABC corridor, extending via authorized wholesalers to interior states with extended replenishment cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's automotive tire market functions as a defensive-moat arena where INMETRO certification entrenchment and fleet service switching costs protect incumbent positioning against import arbitrage.
For Market Incumbents: Shield premium positioning by deepening captive rubber processing near Camaçari and securing multi-year fleet service contracts with cost-per-kilometer guarantees. Accelerate silica-silane compound localization to offset carbon black import concentration risk. Prioritize technical service network density in Mato Grosso and Minas Gerais corridors where agribusiness operators disintermediate traditional distributors. For New Entrants and Emerging Players: INMETRO certification fast-track through domestic manufacturing partnerships or joint ventures with established compounders offers the most viable market entry pathway. White-space opportunity concentrates in Amazon logistics corridor commercial tire demand, previously served by Colombian and Peruvian retread imports. Digital fleet management bundling with pressure monitoring telematics represents the strongest go-to-market angle for technical differentiation without legacy service infrastructure. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across silica-dominant tread compound manufacturing as wet-grip specifications harden in OEM supply contracts. Long-term viability favors suppliers with backward integration into synthetic rubber feedstocks and established INMETRO testing relationships. Acquisition target archetype: mid-tier domestic manufacturers with fleet service capabilities but underutilized certification assets. Monitor PROCONVE emission standard update timing as the critical signal for rolling-resistance specification tightening and compound reformulation capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Rubber | Petrobras partnership near Camaçari reduces import dependency and currency exposure for SBR feedstocks. |
| Silica-Silane Compound Localization | Domestic precipitated silica production enables wet-grip tier compliance without Asian chemical import concentration. |
| Fleet Service Contract Expansion | Direct manufacturer relationships with agribusiness operators disintermediate distributors and lock replacement volume. |
| INMETRO Certification Investment | Verified rolling-resistance grading gates OEM supply access and sustains premium pricing power. |
| Amazon Logistics Corridor Positioning | Manaus free trade zone warehouse construction unlocks commercial tire demand previously served by imports. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with fleet procurement managers, tire compound engineers, aftermarket distributors, and ANVISA regulatory affairs specialists. Secondary validation drew from INMETRO certification databases, IBAMA end-of-life tire collection reports, Petrobras petrochemical output disclosures, and Brazilian customs import records for natural rubber and carbon black. Bottom-up volume modeling across vehicle parc segments and top-down value triangulation against manufacturer revenue disclosures ensured analytical convergence.
Across the analysis window, the forecasting framework models passenger, truck, SUV, and motorcycle product type segments alongside OEM, replacement, and fleet services application channels. Vehicle class, propulsion architecture, and regional production cluster dimensions inform volume allocation. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic drivers including agricultural credit cycles and highway infrastructure investment pacing. Key inputs include federal agricultural credit disbursement timing and BR-163 paving progress milestones.
Underlying assumptions cover PROCONVE emission standard alignment with tire rolling-resistance specifications, with deviation risk concentrated in ANVISA chemical notification timeline delays and Southeast Asian natural rubber supply disruptions. Practitioners should keep alternative scenarios live as regulatory enforcement intensity and currency volatility evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Tire Changers Market
Tires and Wheels
Self-Sealing Tire Market
Tires and Wheels
Europe Two-Wheeler Tire Market
Tires and Wheels
North America 2-Wheeler Replacement Tire Market
Tires and Wheels
Tire & Wheel Cleaners Market
Tires and Wheels
Performance Tires Market
Tires and Wheels
Asia-Pacific Automotive Tire Pressure Management System Market
Tires and Wheels
Automotive Retread Tires Market
Tires and Wheels
Global Aircraft Tire Market
Tires and Wheels
Global Pneumatic Tires Market
Tires and Wheels
Global Off-Highway Tire Market
Tires and Wheels
Global Bead Wire (Tyre Bead Wire) Market
Tires and Wheels
Intelligent Tire Market
Tires and Wheels
Green Tires Market
Tires and Wheels
Global Tire Curing Press Market
Tires and Wheels
Global Tires Market