
 Infotainment System UX and Latency Test Platforms for Connected Vehicles Market | 2026-2036
Infotainment System UX and Latency Test Platforms for Connected Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Infotainment System UX and Latency Test Platforms for Connected Vehicles Market Insights
The performance validation landscape for in-vehicle infotainment is decoupling sharply between premium platforms capable of sub-20-millisecond latency benchmarking and commodity solutions serving baseline functional verification. dSPACE leverages its real-time simulation heritage to anchor high-fidelity cockpit prototyping for German luxury OEMs. Keysight Technologies competes through deep measurement science in 5G and Wi-Fi 6 air interface testing, while Rohde & Schwarz sustains dominance in EMC-qualified RF test environments for regulatory pre-certification.
Infotainment System UX and Latency Test Platforms for Connected Vehicles comprise integrated hardware-software systems that inject controlled network loads, render synthetic user inputs, and capture response times across multi-domain vehicle buses including Ethernet backbone and CAN FD segments. Their primary commercial purpose is to guarantee perceptual immediacy in touch, voice, and haptic feedback loops before production gate approvals. Cloud-Based platforms are capturing the fastest expansion as OEMs distribute validation workloads across geographically dispersed engineering teams, while Edge Computing configurations retain margin concentration where physical-in-the-loop timing fidelity cannot tolerate WAN variability. Hybrid deployments are emerging where latency-critical path testing runs locally and regression suites burst to cloud instances.
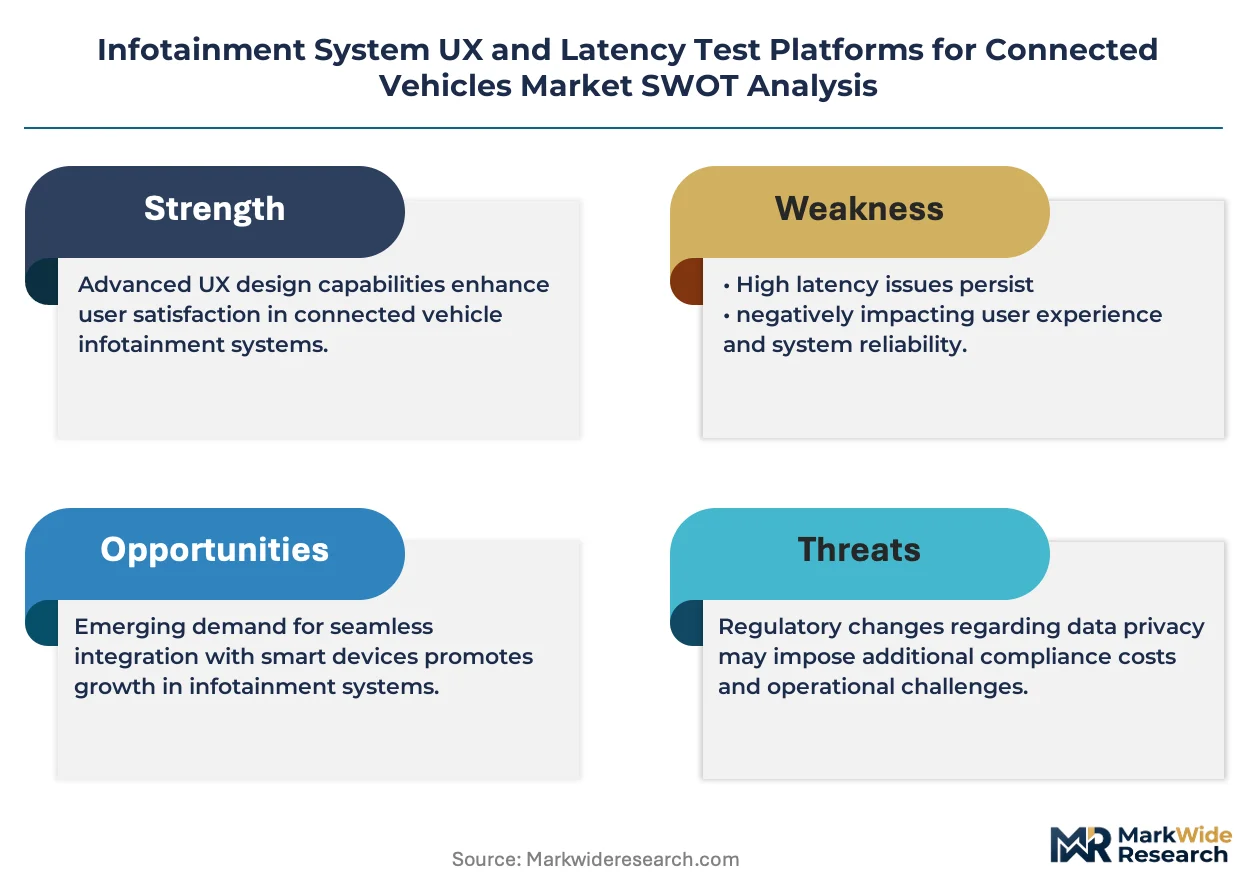
The EU AI Act and UNECE WP.29 cybersecurity regulations are tightening validation documentation requirements for human-machine interface decision chains, directly expanding mandatory test scope for software developers and vehicle manufacturers. The US NHTSA and FCC jointly influence platform specifications through distracted-driving guidelines and spectrum allocation rules that constrain wireless test parameters. Stakeholders must decide whether to build captive latency measurement IP or partner with specialized platform vendors as cockpit software complexity outpaces in-house test infrastructure refresh cycles.
Market Dynamics
The EU Cyber Resilience Act is forcing Tier-1 suppliers to rebuild validation protocols around continuous security monitoring, compressing test platform refresh cycles from five-year horizons to eighteen-month windows. This regulatory compression is restructuring procurement relationships between cockpit software developers and measurement equipment vendors.
Growth Catalysts
- UNECE WP.29 cybersecurity mandates:The regulation mandates documented validation chains for human-machine interface decision logic, expanding mandatory test scope for software developers and vehicle manufacturers across European markets.
- 5G-V2X deployment waves:Cellular vehicle-to-everything rollouts in Germany, China, and the United States are generating demand for air interface latency benchmarking under controlled network congestion.
- Stuttgart-Ingolstadt engineering cluster consolidation:German OEMs are centralizing validation centers in these Bavarian and Baden-Württemberg hubs, concentrating platform procurement decisions among fewer buyers with larger contract values.
Market Restraints
- High-performance FPGA cost volatility:Latency measurement engines depend on programmable logic devices whose supply concentrates among two foundry operators, creating input cost instability.
- EMC chamber infrastructure lock-in:RF-qualified test environments require specialized anechoic facilities that cannot be repurposed, stranding capital in physical assets as validation workloads migrate toward cloud architectures.
- CAN FD-Ethernet protocol translation overhead:Multi-domain bus testing incurs timing jitter from legacy segment bridging that synthetic load generators cannot fully eliminate, capping measurement fidelity.
Strategic Opportunities
- India PLI scheme for automotive electronics:Production-linked incentives for advanced driver assistance systems are attracting cockpit module assembly, creating downstream demand for localized validation infrastructure.
- Digital twin convergence:Virtual cockpit prototyping is converging with physical-in-the-loop testing, enabling hybrid validation workflows where software regression runs in cloud instances while hardware timing verification stays edge-local.
- Subscription-based platform access:Pay-per-test-hour models are emerging as an alternative to capital-heavy equipment purchases, lowering entry barriers for mid-tier suppliers and engineering service providers.
Industry Challenges
- Real-time systems engineering talent scarcity:The intersection of automotive bus protocols, RF measurement science, and UX perceptual psychology requires hybrid skill sets that universities and vocational programs have not scaled to produce.
- Cross-certification timeline fragmentation:Platform vendors must sequence EMC pre-certification, functional safety qualification, and cybersecurity validation across KBA, NHTSA, and MIIT jurisdictions with non-harmonized documentation requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infotainment System UX and Latency Test Platforms for Connected Vehicles Market |
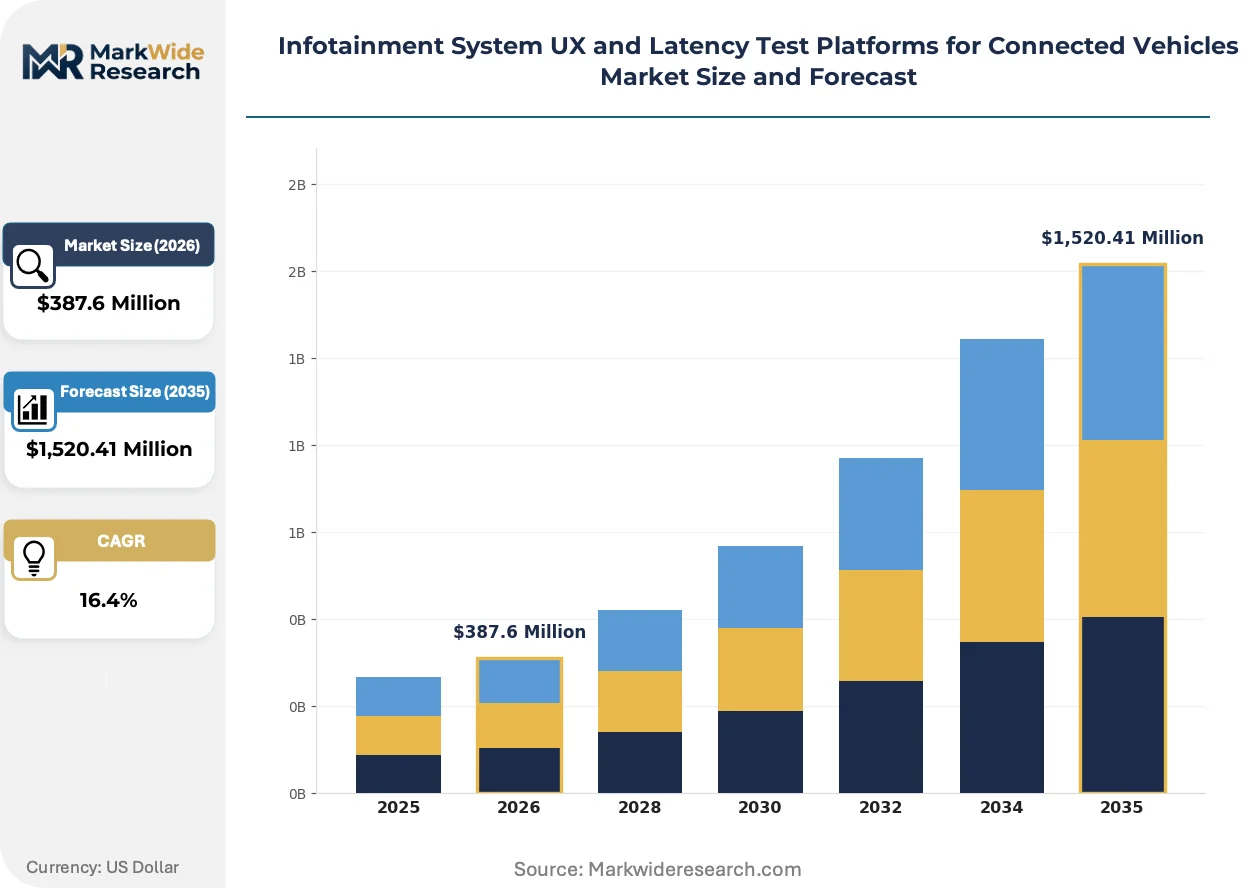
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,520.41 Million |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Cloud-Based, On-Premise, Hybrid, Edge Computing, Virtual Simulation Technology: 5G, Wi-Fi 6, Bluetooth, NFC, CAN Bus, Ethernet Use Case: User Experience Optimization, Latency Measurement, Functional Testing, Security Validation, Compatibility Testing, Network Performance Analysis End User: Vehicle Manufacturers, Tier-1 Suppliers, Software Developers, Research Institutes, Testing Laboratories |
| Companies Covered | dSPACE, Keysight Technologies, Rohde & Schwarz, Vector Informatik, Emerson, ETAS, IPG Automotive, Anritsu, Spirent, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infotainment System UX and Latency Test Platforms for Connected Vehicles Market Trends and Innovations
Synthetic user input generation is displacing manual touch-and-voice testing protocols, compressing validation cycles while expanding scenario coverage. Three technology and demand shifts are restructuring how cockpit responsiveness is measured and guaranteed.
Time-sensitive networking over automotive Ethernet is converging with precision timing protocol hardware, enabling sub-microsecond synchronization between infotainment head units and domain controllers. German luxury OEMs are deploying these synchronized test beds for haptic feedback loop validation. The structural consequence is collapsing the boundary between network performance testing and perceptual UX measurement into unified platform architectures.
The EU AI Act's risk classification framework for human-machine interface decision chains is mandating algorithmic transparency documentation that validation platforms must now generate automatically. Industrial consequence includes expanded logging requirements for voice recognition latency tests and touch response benchmarks. European engineering service providers are responding by embedding audit trail generation directly into synthetic input scripting tools.
Workload bursting patterns are reshaping how OEMs contract validation capacity, with regression test suites migrating to cloud instances while latency-critical path testing remains physically co-located with hardware prototypes. Tier-1 suppliers in the United States are unbundling test execution from platform ownership, preferring operational expenditure models that align costs with program phase gates. This shift is most visible among Detroit-based manufacturers consolidating multiple nameplate validation programs under shared infrastructure contracts.
Infotainment System UX and Latency Test Platforms for Connected Vehicles Market Segmentation
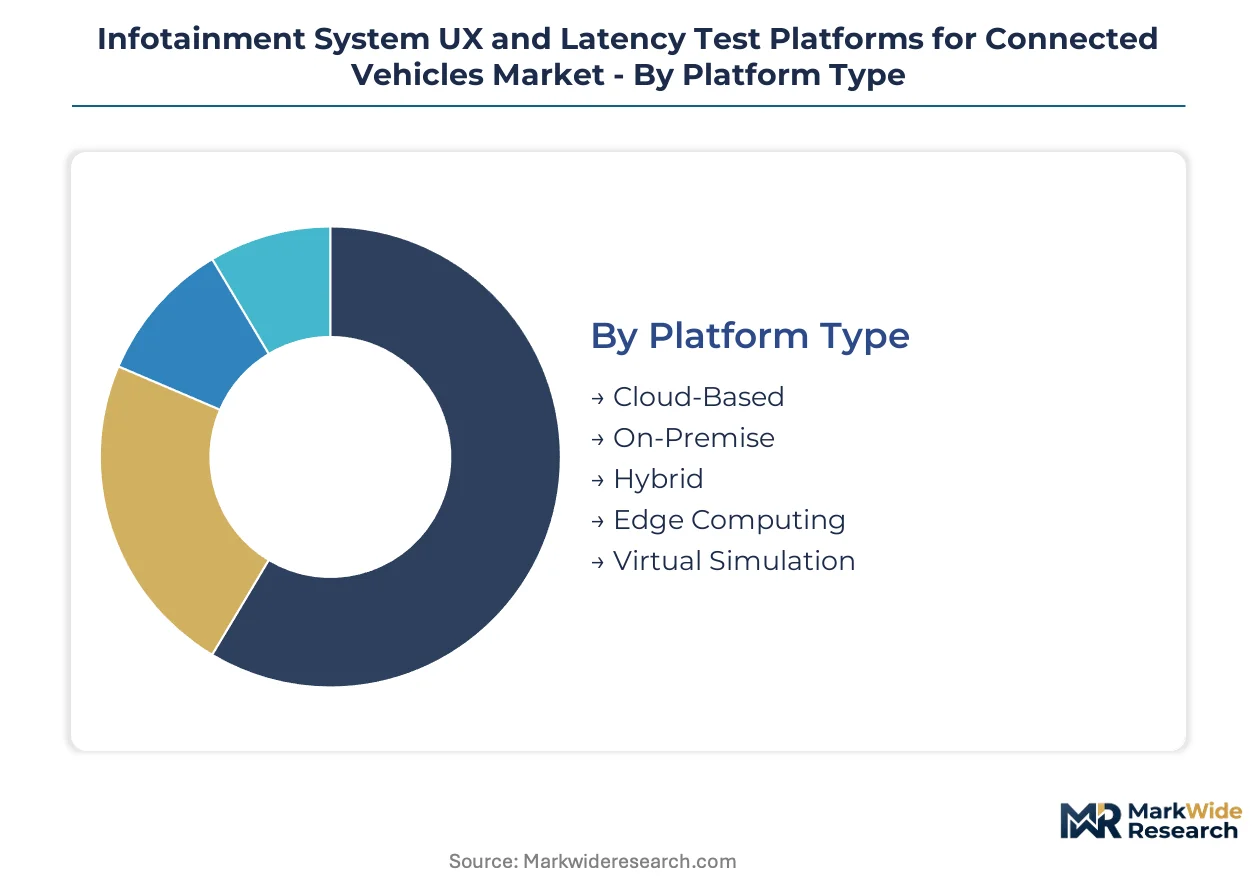
Test platform procurement patterns diverge sharply between latency-critical validation requiring physical timing fidelity and regression-scale workloads tolerating distributed execution. Segment-specific requirements around synchronization precision, regulatory documentation, and burst capacity reshape vendor selection criteria across the procurement base.
Platform Type:
Volume procurement concentrates in configurations enabling distributed team access, while premium deployments prioritize nanosecond-grade timing certainty for haptic loop verification.
- Cloud-Based:Platforms distribute synthetic load generation and regression suites across geographically dispersed engineering teams through containerized test orchestration. Demand is concentrating among Detroit-based manufacturers consolidating multi-nameplate programs under shared infrastructure contracts, driven by operational expenditure alignment with program phase gates.
- Hybrid:Architectures partition latency-critical path testing to edge-local hardware while bursting regression workloads to cloud instances. Deployment is accelerating around Stuttgart and Ingolstadt engineering clusters where German luxury OEMs require unified validation pipelines across distributed supplier networks.
- Edge Computing:Physical-in-the-loop configurations eliminate WAN variability for sub-20-millisecond benchmarking protocols.
- On-Premise:Captive infrastructure retains favor where EMC-qualified RF environments mandate specialized anechoic facilities.
- Virtual Simulation:Software-only execution enables early-stage cockpit prototyping without hardware prototype availability.
Mature deployment sits with On-Premise. Newer deployment is concentrated in Cloud-Based.
Technology:
Air interface selection tracks regional spectrum allocation and V2X rollout sequencing, with protocol translation overhead constraining multi-domain bus integration fidelity.
- 5G:Cellular vehicle-to-everything air interfaces enable controlled network congestion benchmarking under production-relevant load conditions. Demand is concentrating in Germany and China where spectrum auctions have accelerated C-V2X infrastructure deployment, constrained by FCC and MIIT equipment authorization timelines.
- Ethernet:Automotive backbone implementations with time-sensitive networking and precision timing protocol hardware achieve sub-microsecond synchronization between head units and domain controllers. Adoption is expanding among Tier-1 suppliers validating haptic feedback loops for premium cockpit programs, pressured by EU AI Act documentation requirements for decision-chain transparency.
- Wi-Fi 6:High-throughput local area testing supports in-vehicle entertainment streaming validation.
- Bluetooth:Low-energy protocols enable peripheral pairing responsiveness measurement.
- NFC:Short-range contactless interfaces require proximity timing verification.
- CAN Bus:Legacy segment bridging incurs timing jitter that synthetic generators cannot fully eliminate.
Established integration sits with CAN Bus. Steepest expansion trajectory belongs to 5G.
Use Case:
Regulatory scope expansion is restructuring mandatory test coverage from functional verification toward documented validation chains for human-machine interface decision logic.
- Latency Measurement:Sub-millisecond response time capture across touch, voice, and haptic feedback loops requires hardware-timestamped event logging with audit trail generation. Demand is concentrating in European markets where UNECE WP.29 and EU AI Act mandates tighten documentation requirements, compressed by KBA cybersecurity validation timelines.
- Security Validation:Continuous monitoring protocols under EU Cyber Resilience Act specifications force eighteen-month platform refresh cycles. Procurement is accelerating among Tier-1 suppliers rebuilding validation architectures, constrained by cross-certification fragmentation across NHTSA and MIIT jurisdictions.
- User Experience Optimization:Perceptual immediacy benchmarking combines psychometric thresholds with synthetic input generation.
- Functional Testing:Baseline operational verification retains volume deployment in mid-tier supplier segments.
- Compatibility Testing:Multi-vendor ecosystem interoperability validation expands with cockpit software complexity.
- Network Performance Analysis:End-to-end throughput and jitter characterization supports 5G-V2X deployment waves.
Conventional deployment sits with Functional Testing. Emerging priority is concentrated in Security Validation.
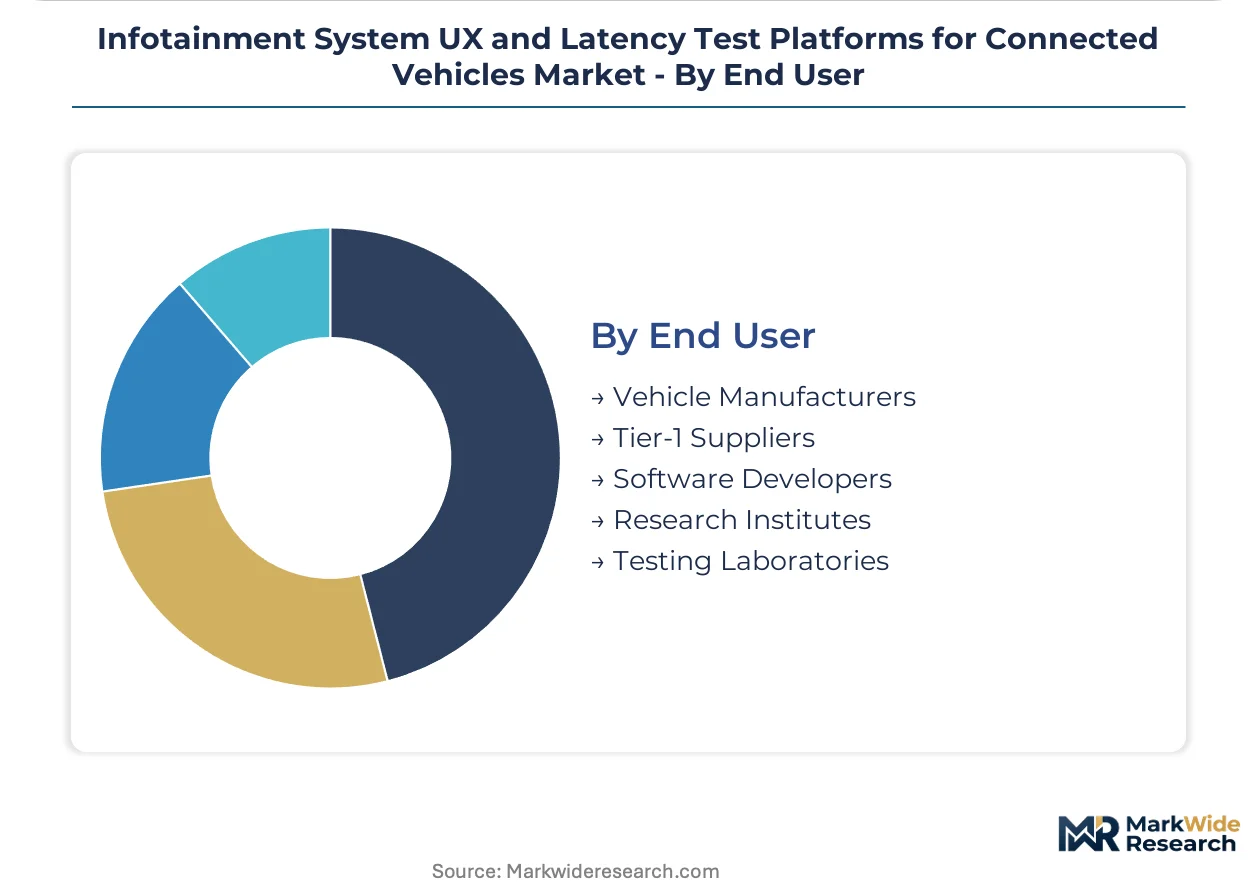
End User:
Procurement authority consolidation around engineering clusters is concentrating contract values among fewer buyers with larger validation program scopes.
- Tier-1 Suppliers:Cockpit module integrators face compressed refresh cycles from EU Cyber Resilience Act implementation, driving platform procurement for continuous security monitoring validation. Demand is concentrating in Germany around Stuttgart and Ingolstadt hubs where OEMs have centralized supplier qualification, pressured by real-time systems engineering talent scarcity.
- Vehicle Manufacturers:OEMs unbundle test execution from platform ownership through subscription-based access models. Adoption is expanding among United States manufacturers preferring operational expenditure alignment, constrained by FPGA cost volatility in latency measurement engine supply.
- Software Developers:Algorithmic transparency documentation requirements expand mandatory test scope for HMI decision chains.
- Testing Laboratories:Independent validation service providers capture mid-tier supplier demand through pay-per-test-hour models.
- Research Institutes:Academic and government research programs support pre-competitive standardization activities.
Traditional procurement sits with Vehicle Manufacturers. Fastest share gain belongs to Tier-1 Suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart and Ingolstadt anchor platform procurement concentration as German OEMs consolidate validation centers around these Bavarian and Baden-Württemberg engineering clusters, with regulatory mandates from Brussels and Washington reshaping geographic deployment patterns.
Germany
KBA cybersecurity validation timelines and UNECE WP.29 mandates compress test platform refresh cycles to eighteen-month windows. The EU Cyber Resilience Act forces Tier-1 suppliers to rebuild continuous security monitoring protocols. Stuttgart and Ingolstadt engineering clusters concentrate procurement authority among cockpit module integrators serving luxury OEM programs.
United States
NHTSA distracted-driving guidelines and FCC spectrum allocation rules constrain wireless test parameters for 5G-V2X benchmarking. Detroit-based manufacturers unbundle test execution from platform ownership through subscription-based access models. Cloud-based validation workloads concentrate among multi-nameplate consolidation programs under shared infrastructure contracts.
China
MIIT equipment authorization timelines and C-V2X infrastructure deployment accelerate demand for air interface latency benchmarking. Production-linked incentives for automotive electronics attract cockpit module assembly to regional manufacturing zones. Shanghai and Beijing engineering centers drive localized validation infrastructure procurement.
Japan
METI industrial standards and precision timing protocol adoption support sub-microsecond synchronization test bed deployment. Automotive Ethernet backbone validation expands among Tier-1 suppliers integrating infotainment head units with domain controllers. Nagoya and Tokyo metropolitan areas concentrate haptic feedback loop verification programs.
India
PLI scheme incentives for advanced driver assistance systems create downstream demand for localized validation infrastructure. BIS certification requirements and TRAI spectrum regulations shape platform specifications for domestic cockpit module production. Karnataka and Tamil Nadu automotive electronics corridors attract test platform deployment.
Infotainment System UX and Latency Test Platforms for Connected Vehicles Market Competitive Landscape
Premium-margin players sit above commodity-margin players across timing fidelity and regulatory documentation capabilities. The vendor base stratifies between real-time simulation specialists, RF measurement science providers, and EMC-qualified test environment operators. Three archetypes dominate: precision timing protocol hardware vendors, air interface testing specialists, and integrated cockpit prototyping platforms. Competitive moves center on subscription-based platform access models and hybrid cloud-edge architecture partnerships.
Within the precision timing tier, dSPACE and ETAS exemplify German-engineered real-time simulation heritage. Keysight Technologies occupies a position among measurement science providers with deep 5G and Wi-Fi 6 air interface capabilities. Rohde & Schwarz anchors the EMC-qualified RF test environment segment for regulatory pre-certification workflows.
| Leading Market Players |
|---|
| dSPACE |
| Keysight Technologies |
| Rohde & Schwarz |
| Vector Informatik |
| Emerson |
| ETAS |
| IPG Automotive |
| Anritsu |
| Spirent |
| Others |
Pricing and Supply Chain Analysis
FPGA silicon from TSMC and Samsung Foundry feeds through latency measurement engine production into three-tier pricing structures across premium, standard, and economy levels, with German luxury OEMs absorbing premium tiers while mid-tier suppliers face cost compression from eighteen-month platform refresh cycles mandated by the EU Cyber Resilience Act.
Pricing Analysis
Value-based pricing anchors on validated sub-20-millisecond latency guarantees for haptic feedback loop certification. Three-tier pricing structure across premium, standard, and economy levels separates EMC-qualified RF environments from cloud-based regression suites. Price differentiation centers on precision timing protocol hardware certification and KBA cybersecurity validation documentation completeness. Pricing pressure stems from FPGA cost volatility concentrated among two foundry operators. Tier-1 suppliers in Germany exhibit lowest price sensitivity due to consolidated procurement authority around Stuttgart and Ingolstadt engineering clusters.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from German luxury manufacturers, while engineering service providers access platforms through subscription-based distribution. Supply concentrates in Germany, the United States, and China for precision timing hardware and RF measurement equipment. Raw material dependencies include FPGA silicon, anechoic chamber materials, and automotive Ethernet PHY components. Supply chain risk centers on single-source vulnerability for programmable logic devices from TSMC. Distribution runs through Tier-1 supplier procurement offices co-located with OEM validation centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Cyber Resilience Act constructs a cost-of-compliance barrier that rewards incumbent platform vendors with pre-certified EMC and cybersecurity documentation while straining mid-tier suppliers unable to sustain eighteen-month refresh investments.
For Market Incumbents: Lock in multi-year shared infrastructure contracts with Detroit-based manufacturers consolidating multi-nameplate validation programs. Expand captive supply of precision timing protocol hardware to offset FPGA foundry concentration risk. Defend against cloud-native entrants by embedding audit trail generation directly into synthetic input scripting tools for EU AI Act compliance. For New Entrants and Emerging Players: Mid-tier engineering service providers in India represent the most penetrable buyer archetype, underserved by legacy platform vendors focused on German and US OEMs. Target PLI scheme beneficiaries in Karnataka and Tamil Nadu automotive electronics corridors with pay-per-test-hour subscription models. Establish go-to-market partnerships with local testing laboratories seeking to unbundle test execution from capital-heavy equipment ownership. For Investors and Strategic Acquirers: Tier-1 supplier announcements of Stuttgart-Ingolstadt validation center consolidation is the leading indicator that procurement authority concentration will accelerate platform vendor M&A activity. Long-term viability favors vendors with hybrid cloud-edge architectures capable of serving both latency-critical path testing and regression workload bursting. Monitor FPGA foundry capacity allocation announcements as the primary inflection signal for input cost stability.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Cloud-Edge Architecture Deployment | Enables German OEMs to partition latency-critical testing locally while bursting regression suites to cloud instances. |
| Subscription-Based Platform Access Launch | Aligns operational expenditure with program phase gates for Detroit-based multi-nameplate consolidation programs. |
| Precision Timing Protocol Hardware Certification | Supports KBA cybersecurity validation timelines for sub-microsecond haptic feedback loop verification. |
| Synthetic User Input Generation Integration | Compresses validation cycles while expanding scenario coverage for EU AI Act algorithmic transparency documentation. |
| India Localization Partnership | Captures PLI scheme downstream demand from Karnataka and Tamil Nadu automotive electronics corridors. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with Tier-1 supplier procurement directors, OEM platform engineers, validation laboratory operations managers, and RF measurement equipment specialists. KBA cybersecurity validation timelines, FCC equipment authorization databases, and MIIT C-V2X deployment records provided regulatory trajectory inputs. Bottom-up triangulation across platform deployment configurations reconciled with top-down OEM R&D expenditure patterns.
Data-stream reconciliation across platform type, technology protocol, use case intensity, and end-user procurement authority yielded volume and value estimates across the analysis window. Segmentation dimensions modeled include deployment architecture, air interface selection, latency measurement precision tier, and geographic engineering cluster concentration. CAGRs were derived from regression analysis of historical platform procurement cycles against regulatory mandate implementation schedules. FPGA supply constraints and EMC chamber infrastructure lock-in served as industry-specific forecast boundary conditions.
Revisions become necessary when EU Cyber Resilience Act implementation timelines accelerate, foundry capacity allocation shifts disrupt FPGA supply, or OEM validation center consolidation patterns deviate from Stuttgart-Ingolstadt concentration. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Automotive Wi-Fi Router Market
Telematics and Infotainment
Vehicle Trip Computers Market
Telematics and Infotainment
Automotive Human Machine Interface (HMI) Market
Telematics and Infotainment
Smart Telematics Gateway Market
Telematics and Infotainment
Europe Commercial Vehicle Telematics Market
Telematics and Infotainment
Electric Vehicle Infotainment Market
Telematics and Infotainment
North America Automotive Navigation System Market
Telematics and Infotainment
Automotive Rear Seat Infotainment Market
Telematics and Infotainment
Connected Car Market
Telematics and Infotainment
Global Vehicle Fleet Communication Market
Telematics and Infotainment
GPS Tracker Market
Telematics and Infotainment
5G V2X Communications Market
Telematics and Infotainment
Marine Telematics Market
Telematics and Infotainment
Global Intelligent Transportation System (ITS) Market
Telematics and Infotainment
Europe Vehicle Remote Diagnostic Market
Telematics and Infotainment
Global in Dash Navigation System Market