
 Automotive Ecall Market | 2026-2036
Automotive Ecall Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Ecall Market Intelligence
The bundling of eCall functionalities with comprehensive telematics packages is rebalancing procurement choices for automotive OEMs. Continental AG leverages its extensive portfolio in vehicle electronics to offer integrated solutions. Robert Bosch GmbH competes on the basis of its deep system integration expertise and global manufacturing scale. Meanwhile, Thales Group specializes in secure connectivity modules, a critical component for reliable eCall operation.
Automotive eCall is an in-vehicle system designed to automatically dial emergency services in the event of a severe collision. The system transmits critical data, including precise GPS coordinates and vehicle identification, over cellular networks to a Public Safety Answering Point. Embedded Systems represent the largest product segment, driven by factory installation mandates for new vehicles. Concurrently, the aftermarket provider segment is expanding through the sale of retrofit solutions for legacy vehicle fleets.
Mandatory regulations are the primary market accelerant, led by the European Union's eCall rule. Similar standards, such as India's AIS-140 which specifies emergency buttons and vehicle tracking, create parallel demand streams. In the United States, the NHTSA encourages advanced automatic collision notification systems, influencing voluntary adoption by automakers. Future system development will hinge on integration with 5G networks and V2X communication protocols.
Market Dynamics
The convergence of safety mandates with consumer demand for connectivity is the central force. This shifts eCall from a compliance device into an integrated feature within broader vehicle telematics platforms, reshaping OEM procurement choices.
Growth Catalysts
- Regulatory Mandates:The European Union's eCall rule and India's AIS-140 standard create compulsory demand, making factory installation a default for new vehicles in these key markets.
- Technology Integration:The planned incorporation with 5G and Vehicle-to-Everything (V2X) communication expands capabilities beyond emergency calls, adding value for automakers and consumers.
- OEM Consolidation:Demand is concentrating within major automotive manufacturing centers like Germany and Japan as global vehicle platforms standardize on embedded eCall systems.
Market Restraints
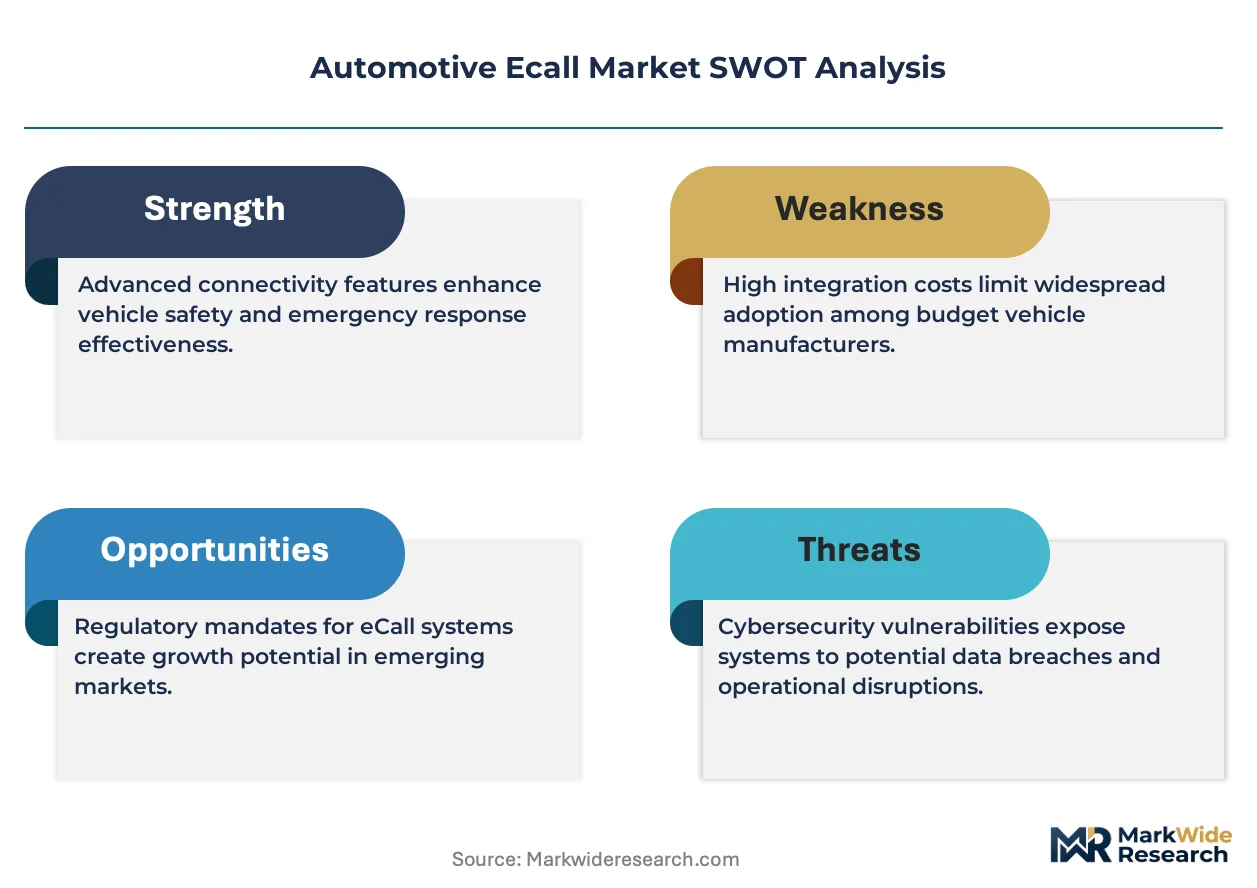
- Cost Barriers:The expense of integrating certified embedded systems and associated service contracts remains a significant hurdle, particularly for economy-segment vehicles.
- Network Dependency:System effectiveness is limited by the availability and reliability of cellular networks, creating coverage gaps in rural and remote regions.
- Fragmented Standards:Divergent regulatory approaches, such as the mandatory framework in the EU versus the voluntary one encouraged by the NHTSA in the US, complicate global vehicle platform design.
Strategic Opportunities
- Aftermarket Expansion:The large installed base of legacy vehicles without factory-fitted systems presents a significant opportunity for retrofit solutions, especially in North America.
- Value-Added Services:Bundling eCall with subscription-based services like stolen vehicle tracking, remote diagnostics, and concierge assistance creates new recurring revenue streams.
- ADAS Data Fusion:Integrating eCall with Advanced Driver-Assistance Systems allows for the transmission of pre-crash data, enhancing the information available to emergency responders.
Industry Challenges
- System Interoperability:Ensuring seamless communication between diverse eCall hardware, vehicle architectures, and the varied technical standards of Public Safety Answering Points (PSAPs) is a primary operational hurdle.
- Data Privacy Compliance:Managing vehicle and location data in adherence to strict regulations like Europe's GDPR requires secure connectivity and transparent data handling policies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Ecall Market |
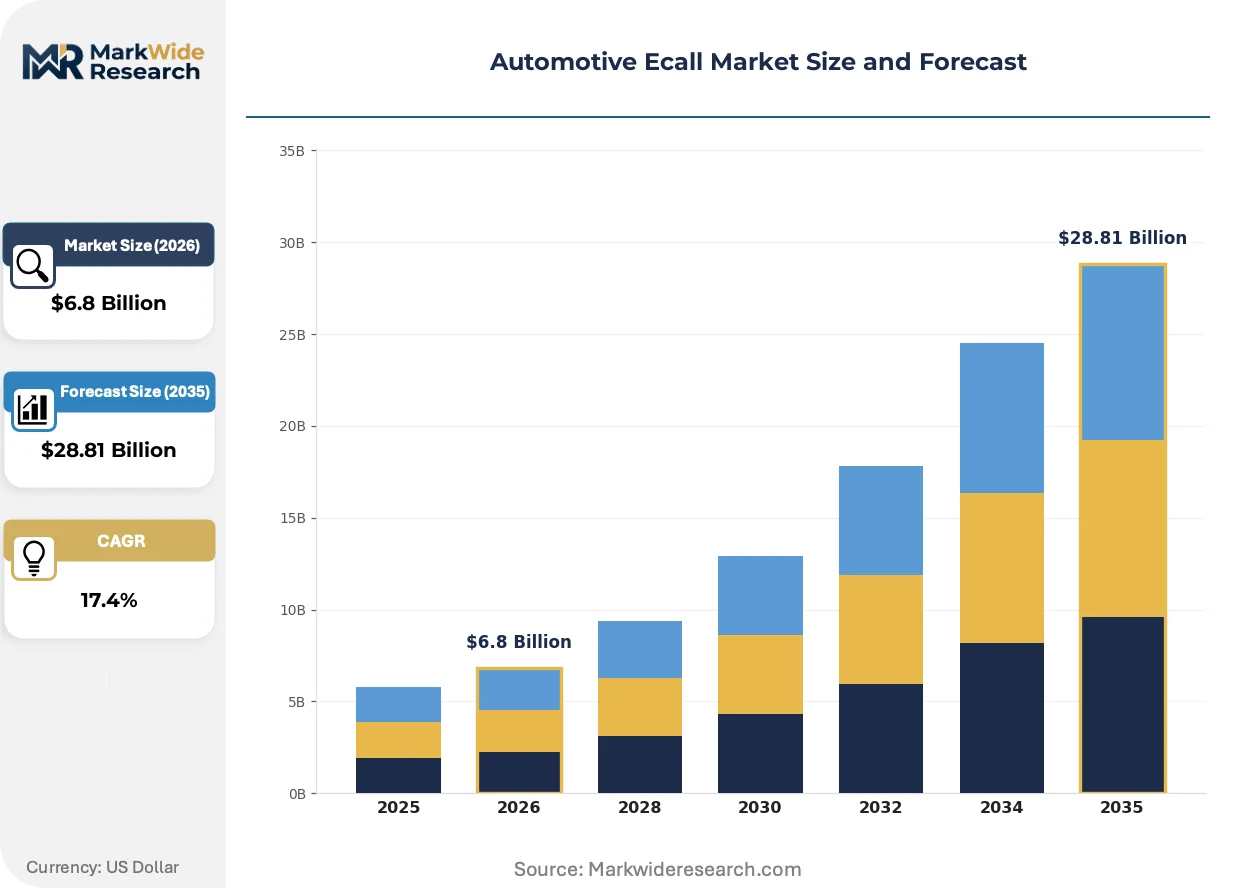
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $28.81 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Embedded Systems, Telematics Units, Software Applications, Mobile Solutions Technology: GPS, Cellular Networks, Satellite Communication, Bluetooth End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Fleet Operators Installation: Factory-Installed, Dealer-Installed, DIY Kits, Retrofit Solutions |
| Companies Covered | Continental AG, Robert Bosch GmbH, Telit Cinterion, Thales Group, STMicroelectronics, Infineon Technologies AG, DENSO CORPORATION, Valeo, u-blox, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Ecall Market Strategic Shifts & Innovations
System evolution is defined by the transition from a single-function emergency device to a data-rich node in the connected vehicle ecosystem. This shift prioritizes deeper integration with other vehicle systems and external networks for enhanced functionality.
Advanced Automatic Collision Notification (AACN) systems use sensor fusion from ADAS and vehicle dynamics to predict crash severity. Premium and mid-tier automakers are adopting this technology to differentiate their safety offerings beyond basic compliance. This level of data integration is automating the triage process for emergency services by providing richer context, such as the probability of severe injury.
European regulators are advancing initiatives to transition the eCall system from legacy 2G/3G networks to 4G/5G infrastructure. This legislative push necessitates a hardware refresh cycle for both in-vehicle units and public safety answering points. Telematics hardware suppliers are most affected, facing significant redesign and validation costs to meet new network requirements.
A clear shift in OEM sourcing strategy is moving away from single-function eCall components. Automakers now prefer integrated telematics control units that combine emergency calling with infotainment and remote diagnostic services. This consolidation trend is most visible in competitive European and Japanese markets where connected features are a key sales driver.
Automotive Ecall Market Segmentation
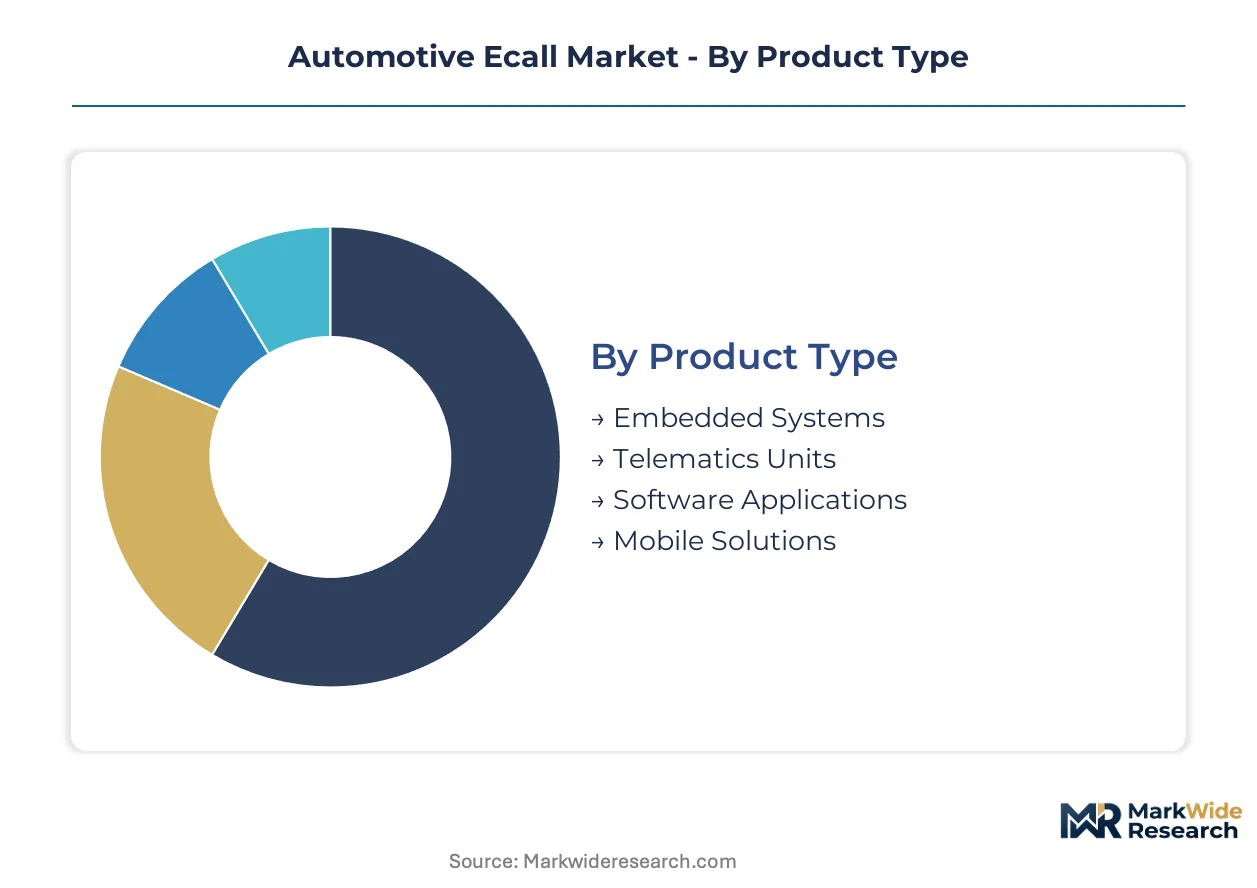
The Automotive Ecall market segmentation reveals distinct pathways for product development and market penetration. Understanding these segments helps automakers and suppliers tailor solutions for diverse regulatory environments and consumer needs. This granular view highlights areas of concentrated investment and emerging growth across the connected vehicle ecosystem.
Product Type:
The product type segmentation highlights varying upfront development costs and integration complexities for manufacturers.
- Embedded Systems:These dedicated hardware and software units are factory-installed within new vehicles to automatically initiate emergency calls. Mandatory regulations in the European Union and India drive significant demand for these highly integrated, safety-critical components.
- Telematics Units:These integrated control units combine eCall functionality with broader connectivity services like infotainment and remote diagnostics. Automakers increasingly prefer these consolidated platforms to enhance value propositions and streamline procurement processes, particularly in competitive markets.
- Software Applications:These primarily refer to software components enabling eCall functionality within existing vehicle systems or mobile devices. Their development focuses on interoperability and secure data transmission protocols.
- Mobile Solutions:These are smartphone-based applications or portable devices offering eCall services, often leveraging a vehicle's Bluetooth connection. They cater to aftermarket users seeking basic emergency notification capabilities.
Most installed capacity flows through Embedded Systems. Expansion is steepest in Telematics Units.
Technology:
Technology choices dictate the reliability and data transmission capabilities essential for effective emergency response.
- Cellular Networks:These networks form the backbone for eCall systems, transmitting critical data, including GPS coordinates and vehicle identification, to Public Safety Answering Points. Ongoing legislative pushes to transition from 2G/3G to 4G/5G networks necessitate hardware refreshes and significant infrastructure investment.
- GPS:Global Positioning System technology provides the precise location data transmitted during an eCall, allowing emergency services to accurately pinpoint the vehicle's position. Its integration is fundamental for the system's core function of rapid incident localization.
- Satellite Communication:This technology provides an alternative or supplementary communication channel for eCall systems, particularly valuable in remote areas with limited cellular coverage. Its use addresses network dependency restraints in geographically challenging regions.
- Bluetooth:Bluetooth connectivity facilitates communication between in-vehicle eCall modules and mobile devices, often used in aftermarket or mobile solutions. It enables data exchange for basic system functionality and user interaction.
The core functionality of eCall systems heavily relies on GPS for location accuracy. The transition to Cellular Networks based on 4G/5G infrastructure represents a significant technological evolution.
End User:
End-user segmentation reflects distinct procurement strategies and service requirements across the automotive value chain.
- OEMs:Original Equipment Manufacturers integrate eCall systems directly into new vehicle production lines, driven by mandatory safety regulations and consumer demand for connectivity. Their procurement choices increasingly favor comprehensive telematics packages over single-function components.
- Aftermarket Providers:These entities supply retrofit eCall solutions for legacy vehicles lacking factory-installed systems, addressing a substantial installed base. This segment offers significant opportunities for recurring revenue through subscription-based value-added services.
- Tier-1 Suppliers:These major automotive component manufacturers develop and supply eCall modules and integrated telematics control units to OEMs. They compete on system integration expertise and global manufacturing scale, such as Robert Bosch GmbH.
- Fleet Operators:Commercial fleet operators adopt eCall systems for enhanced driver safety and operational efficiency, often bundling it with vehicle tracking and remote diagnostics. Their focus includes compliance with specific regional safety standards like India's AIS-140.
The largest volume of eCall system procurement originates from OEMs. The Aftermarket Providers segment is gaining share fastest due to the large installed base of older vehicles.
Installation:
Installation methods differentiate between factory-integrated solutions and those catering to existing vehicle fleets.
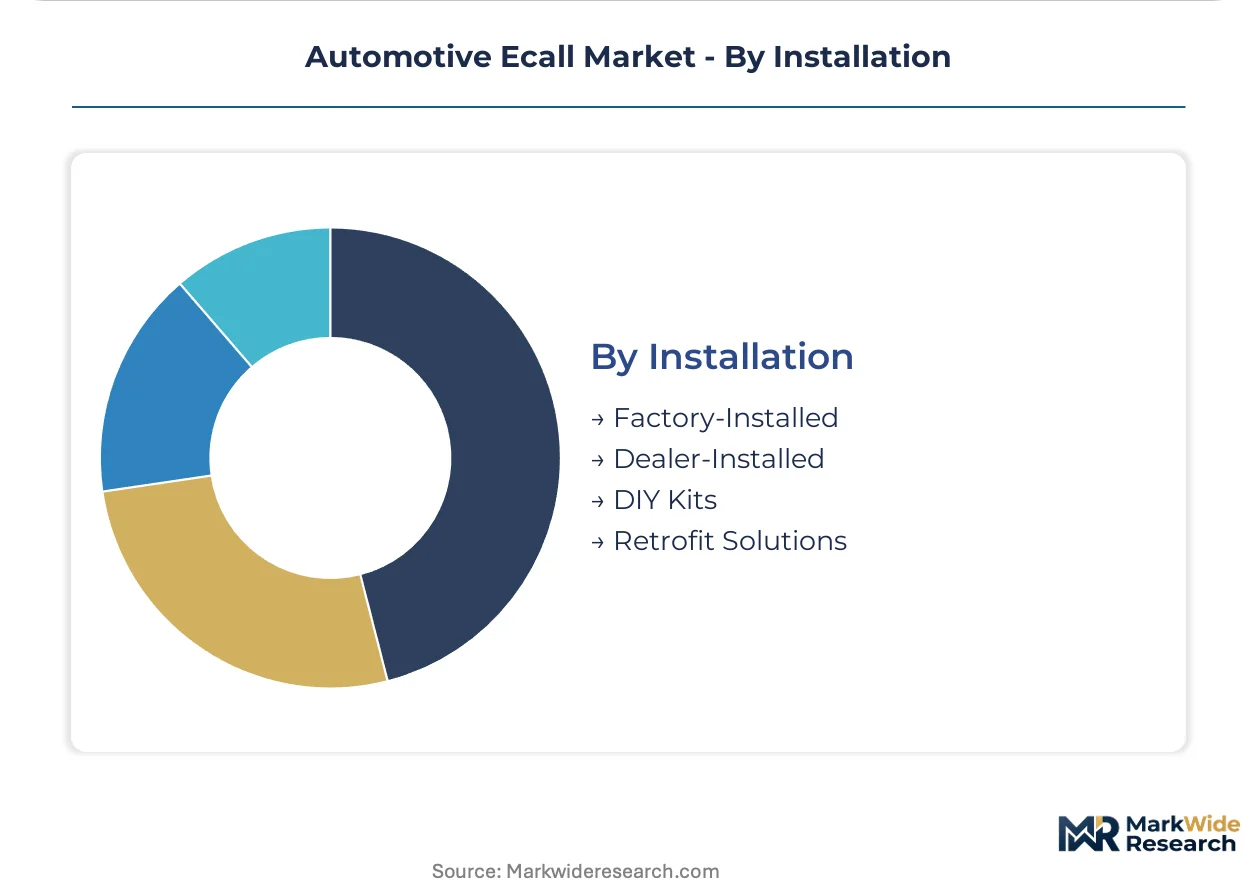
- Factory-Installed:These systems are integrated directly onto the vehicle assembly line, ensuring deep system integration and compliance with stringent automotive standards. Mandatory regulations in the European Union and India make this the default installation method for new vehicles.
- Retrofit Solutions:These involve installing eCall systems into vehicles that did not originally come equipped with the technology, primarily targeting the large installed base of legacy cars. This segment offers a strategic opportunity for aftermarket expansion, particularly in North America.
- Dealer-Installed:Systems installed by authorized dealerships, often as an optional extra or as part of a service package. This method provides a professional installation while offering more flexibility than factory integration.
- DIY Kits:Do-It-Yourself kits allow vehicle owners to install basic eCall functionality themselves, typically connecting via the OBD-II port or cigarette lighter. These solutions prioritize affordability and ease of access for individual consumers.
Factory-Installed systems dominate the new vehicle market. The expansion trajectory for Retrofit Solutions remains significant for addressing older vehicle populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The automotive eCall market found its initial and significant scaling in Europe, driven by comprehensive safety mandates. Mandatory regulations like the European Union's eCall rule established a foundational demand for embedded systems. This legislative push created a blueprint for other regions to follow in terms of emergency response infrastructure.
Germany
Germany's robust automotive manufacturing base drives significant demand for integrated eCall solutions. The EU's eCall rule ensures factory installation across all new vehicle types. Major automotive hubs like Munich and Stuttgart concentrate OEM procurement, focusing on advanced telematics packages that integrate eCall functionality.
Japan
Japan's advanced telematics market and strong OEM presence contribute substantially to eCall system adoption. Domestic safety standards and consumer demand for connected services influence manufacturers. The Nagoya and Tokyo regions are key centers for automotive R&D and production, fostering innovation in integrated vehicle systems.
India
India's AIS-140 standard for public transport and commercial vehicles creates compulsory demand for emergency buttons and tracking systems. This regulation extends beyond passenger vehicles, driving growth in the fleet operator segment. Automotive manufacturing centers such as Pune and Chennai are experiencing increased production of compliant vehicles.
United States
The United States market is characterized by voluntary adoption, with the NHTSA encouraging advanced automatic collision notification systems. This approach fosters innovation in value-added services bundled with eCall. Detroit remains a central hub for automotive engineering, while Silicon Valley contributes to telematics software development.
France
France's automotive sector adheres strictly to the European Union's eCall regulation, mandating factory-installed systems. Demand for secure connectivity modules, critical for reliable eCall operation, is strong among French OEMs. Paris and Toulouse serve as important centers for automotive technology and telematics system integration.
Automotive Ecall Market Key Industry Players
Premium-margin players sit above commodity-margin players across the automotive eCall value chain, distinguished by their system integration capabilities. The market features a blend of established automotive suppliers and specialized connectivity providers. Key strategic archetypes include integrated telematics solution providers and secure module specialists. Strategic partnerships and portfolio diversification are dominant competitive moves among these entities.
Within the integrated telematics solution tier, Germany-based Robert Bosch GmbH exemplifies deep system integration expertise and global manufacturing scale. Continental AG, also a German multinational, represents a comprehensive portfolio in vehicle electronics, offering integrated solutions. Meanwhile, Thales Group, a French company, occupies a position as a specialist in secure connectivity modules, critical for reliable eCall operation.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| Telit Cinterion |
| Thales Group |
| STMicroelectronics |
| Infineon Technologies AG |
| DENSO CORPORATION |
| Valeo |
| u-blox |
| Others |
Cost & Logistics Intelligence
Global semiconductor chip pricing significantly influences the cost structure of embedded eCall systems. This commodity benchmark cascades through Tier-1 suppliers, shaping the final pricing tiers for automotive OEMs.
Pricing Analysis
Contract-based long-term agreements characterize the dominant pricing model for eCall systems. Price differentiation stems from the certification level required for specific regions, such as EU eCall or India's AIS-140, and the complexity of system integration into broader telematics units. Pricing pressure stems from OEMs seeking cost efficiencies, particularly for economy-segment vehicles. Aftermarket providers exhibit the highest price sensitivity, while OEMs prioritize regulatory compliance and deep integration.
Supply Chain Analysis
Specialized microcontroller unit (MCU) production for eCall modules primarily centers in Germany and Japan. The supply chain draws from critical dependencies like semiconductor chips and secure communication modules. Single-source vulnerability for highly specialized components represents a structural risk. Distribution runs through direct supply channels to Tier-1 automotive suppliers and then to OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive eCall market functions as a stable compounder, driven by mandatory safety regulations that ensure continuous demand for embedded systems.
For Market Incumbents: Extend core telematics platforms into adjacent vehicle services, leveraging existing OEM relationships. Deepen integration with Advanced Driver-Assistance Systems (ADAS) to offer advanced automatic collision notification capabilities, mitigating threats from specialized connectivity providers. Invest in 5G/V2X compatibility and certification to meet evolving regulatory standards. This reinforces market position against emerging technology shifts.
For New Entrants and Emerging Players: Online retail platforms offer a viable digital-channel route for market entry. Target retrofit solutions for the large installed base of older vehicles, particularly in North America, which lacks mandatory factory installation. Focus on subscription-based value-added services bundled with basic eCall functionality. This go-to-market angle addresses price-sensitive aftermarket consumers.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized secure connectivity module providers. Strong regulatory tailwinds ensure sustained demand over the next decade, making this a long-term viable segment. Target firms with proprietary 5G/V2X communication protocols or advanced AACN algorithms for acquisition. Widespread adoption rates of 5G infrastructure for V2X communications serves as a critical inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces complexity for OEMs and suppliers across global vehicle architectures. |
| Advanced Sensor Integration | Enhances crash severity prediction for emergency services, improving response. |
| Strategic Partnership | Accelerates development of 5G/V2X compatible modules for future vehicle platforms. |
| Certification Investment | Ensures compliance with evolving regional safety standards like India's AIS-140. |
| Subscription Service Expansion | Creates recurring revenue streams from value-added telematics features for consumers. |
Research Approach
Direct dialogue with OEM procurement managers, Tier-1 automotive electronics engineers, telematics solution architects, and public safety answering point (PSAP) operators formed the primary qualitative grounding. This primary research was validated through extensive secondary data, including EU eCall implementation reports, NHTSA safety guidelines, and AIS-140 compliance documents. The analysis employed both bottom-up and top-down triangulation to ensure robust data integrity.
The quantitative model generated volume and value projections across the analysis window. This framework integrated segmentation dimensions including product type, technology, end-user, installation method, and vehicle class. Compound annual growth rates were derived from historical trends and future regulatory timelines. New vehicle production forecasts by region and retrofit market penetration rates served as key industry-specific inputs.
The model assumes a particular technology adoption path; alternative pathways for 5G network rollout would alter the outlook. Forecasts reflect assumptions concerning global semiconductor supply chain stability and consistent regulatory enforcement. Divergent regulatory timelines or significant supply chain disruptions represent specific risk factors. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Electric Vehicle Motor Communication Controller Market
Automotive Electrical & Electronics
Global Automotive Engine Coolant Temperature Sensor Market
Automotive Electrical & Electronics
EPS Motors Market
Automotive Electrical & Electronics
Automotive Digital Market
Automotive Electrical & Electronics
China Automotive Electric Power Steering (EPS) Market
Automotive Electrical & Electronics
Switchrack Assemblies Market
Automotive Electrical & Electronics
Asia Pacific Automotive Camera Market
Automotive Electrical & Electronics
Automotive Temperature Sensor Market
Automotive Electrical & Electronics
Automotive Alternator and Starter Motor Market
Automotive Electrical & Electronics
Europe Automotive LED Lighting Market
Automotive Electrical & Electronics
South Korea Automotive Camera Market
Automotive Electrical & Electronics
Automotive Clean Cold Technology Market
Automotive Electrical & Electronics
Mexico Automotive Electric Actuators Market
Automotive Electrical & Electronics
Global Automotive Starter and Alternator Market
Automotive Electrical & Electronics
Automotive Starting System Market
Automotive Electrical & Electronics
Japan Automotive EPS Market