
 Asia Pacific Automotive Infotainment Systems Market | 2026-2036
Asia Pacific Automotive Infotainment Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Automotive Infotainment Systems Market Outlook
Semiconductor-grade silicon is decoupling from legacy germanium substrates in head-unit processors, lowering unit costs for high-resolution displays. Panasonic Corporation leverages captive semiconductor fabrication to anchor its supply chain across Japanese OEM programs. Denso Corporation specializes in thermal management integration for infotainment hardware operating in tropical climates. Harman International competes through audio subsystem dominance in premium vehicle segments.
Asia Pacific automotive infotainment systems integrate multi-core processors, touch-capacitive interfaces, and vehicle network protocols to deliver navigation, entertainment, and telematics functions within dashboard assemblies. Manufacturing employs surface-mount technology on multilayer PCBs with operating temperatures rated from minus forty to eighty-five degrees Celsius for cabin durability. Connectivity Modules lead product type revenue as 5G-V2X rollout accelerates, while Software-Defined Platforms represent the fastest-expanding technology dimension due to over-the-air update architectures. Electric Vehicles within the application dimension command concentrated R&D investment from Tier-1 Suppliers seeking thermal-efficient designs.
China's MIIT enforces GB standards for vehicle data security and cross-border transmission, compelling foreign suppliers to localize cloud infrastructure. Japan's METI promotes connected vehicle roadmaps through JIS standards harmonization with ASEAN frameworks. South Korea's MFDS-aligned electromagnetic compatibility rules shape hardware certification pathways for display modules. Stakeholders must monitor evolving data-sovereignty requirements across multiple jurisdictions to determine localization versus platform-standardization strategies.
Market Dynamics
Software-defined vehicle architectures are decoupling infotainment hardware from application layers, enabling Tier-1 suppliers to monetize recurring software revenue streams independent of discrete unit sales cycles.
Growth Catalysts
- China's MIIT GB Standards:Mandates for connected vehicle data security and cross-border transmission protocols are accelerating localization investments by foreign suppliers. Domestic cloud infrastructure deployment creates captive demand for compliant platform architectures.
- 5G-V2X Module Deployment:Network infrastructure buildouts across Japan, South Korea, and China's Yangtze River Delta automotive cluster are pulling embedded connectivity hardware into mass-market vehicle segments previously served by smartphone mirroring.
- Thermal-Efficient Processor Designs:Electric vehicle cabin electronics operating in tropical climates require specialized thermal management integration, opening specification windows for suppliers with climate-hardened hardware portfolios.
Market Restraints
- Semiconductor Substrate Concentration:Premium head-unit processors depend on Taiwan-based foundry capacity for advanced node fabrication, exposing order fulfillment to geopolitical supply disruptions.
- Legacy Vehicle Parc Inertia:Southeast Asia's large installed base of combustion-engine vehicles with basic audio systems limits near-term replacement demand for integrated infotainment platforms.
- Harmonization Friction:Divergent electromagnetic compatibility certification pathways between Japan's METI-aligned JIS standards and South Korea's MFDS requirements inflate regional product adaptation costs.
Strategic Opportunities
- ASEAN Manufacturing Pivot:Thailand and Vietnam's expanding automotive assembly capacity offers localization platforms for suppliers seeking tariff-advantaged access to regional export markets.
- Over-the-Air Revenue Models:Subscription-enabled feature activation creates recurring revenue streams from hardware already deployed in vehicle fleets, decoupling supplier economics from production volume cyclicality.
- Audio Subsystem Premiumization:Differentiated acoustic engineering for electric vehicle cabins—where powertrain noise masking requirements differ from combustion platforms—opens specification windows above commodity display integration.
Industry Challenges
- Embedded Software Talent Scarcity:Shortage of automotive-grade cybersecurity engineers familiar with GB standards compliance is extending platform development timelines for foreign suppliers establishing China operations.
- Multi-Jurisdiction Data Sovereignty:Simultaneous compliance with China's data localization mandates, Japan's cross-border transmission frameworks, and emerging ASEAN privacy regimes fragments cloud architecture standardization efforts.
- Hardware-Software Version Synchronization:Discrepancies between semiconductor procurement lead times and software sprint cycles create inventory mismatches for suppliers managing both component streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Automotive Infotainment Systems Market |
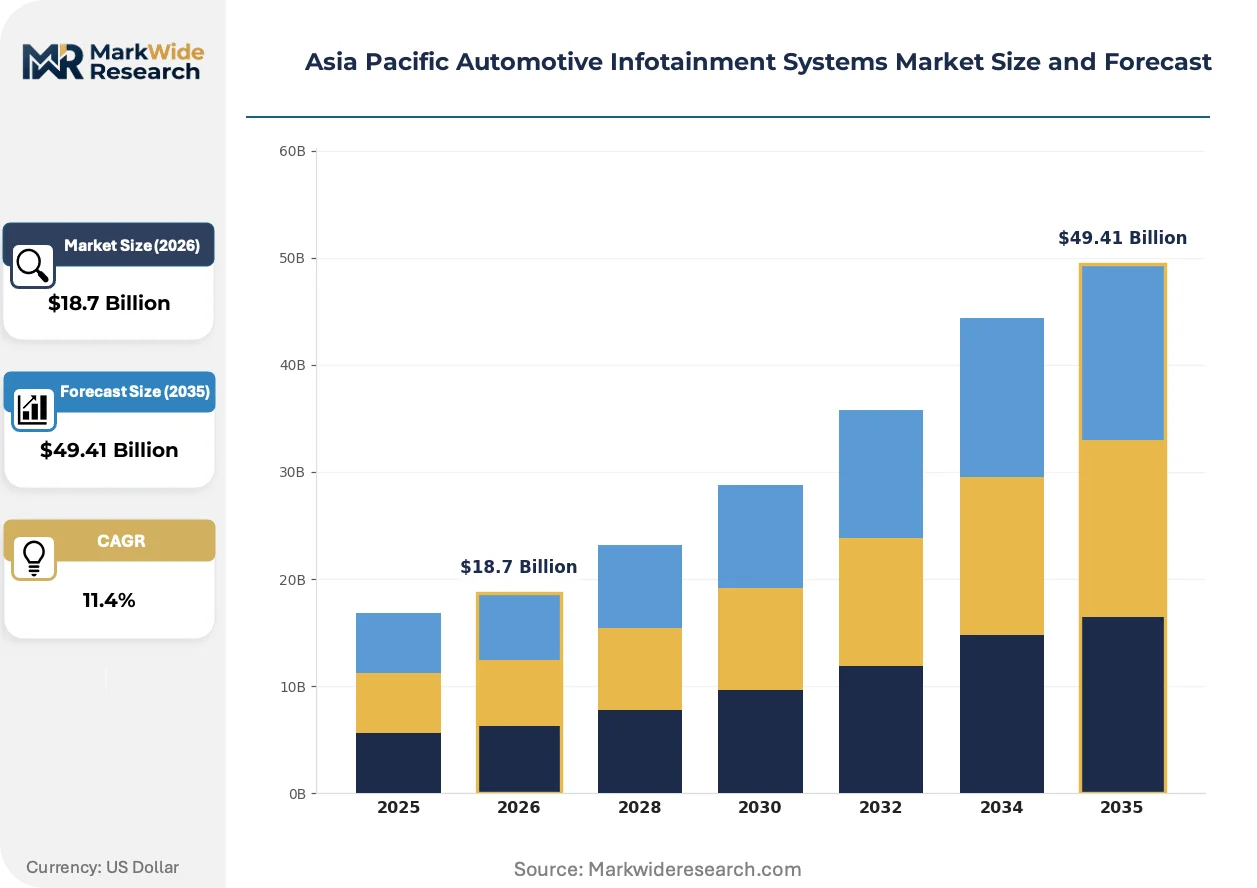
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Navigation Systems, Audio Systems, Video Systems, Connectivity Modules Technology: Embedded Systems, Cloud-Based Systems, Hybrid Systems, Software-Defined Platforms End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Application: Passenger Cars, Commercial Vehicles, Electric Vehicles, Luxury Vehicles |
| Companies Covered | Panasonic Corporation, Denso Corporation, Harman International, Robert Bosch GmbH, Continental AG, Alpine Electronics, Visteon Corporation, Pioneer Corporation, Mitsubishi Electric Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Automotive Infotainment Systems Market Strategic Shifts
Automotive infotainment platforms are transitioning from fixed-function appliances to updatable compute substrates, with supplier competitive advantage migrating toward software ecosystem depth and data service integration.
Automotive-grade silicon-on-insulator processes are absorbing display driver functions previously handled by discrete components, compressing bill-of-materials complexity for high-resolution touch interfaces. Japanese and South Korean OEM programs are adopting these consolidated processors at volume scale for 2026 model-year platforms. The technology is absorbing margin pressure from commoditized display panel sourcing by shifting value capture toward semiconductor design.
China's MIIT enforcement of GB/T vehicle data security standards is compelling foreign Tier-1 suppliers to establish domestic cloud infrastructure partnerships. The regulation fragments previously centralized global platform architectures into region-specific instances. Premium passenger car segments in China are responding with accelerated software-defined platform upgrades to maintain feature parity against domestic competitors.
Fleet procurement of infotainment systems is consolidating around specification templates that prioritize over-the-air update capability over initial hardware capability benchmarks. Rental and mobility-service vehicle operators in Australia's urban corridors are driving this preference shift, treating cabin electronics as depreciating software delivery vehicles rather than fixed entertainment assets. The behavioral change is most visible in commercial fleet RFPs that weight update latency guarantees above launch-day feature checklists.
Asia Pacific Automotive Infotainment Systems Market Segmentation
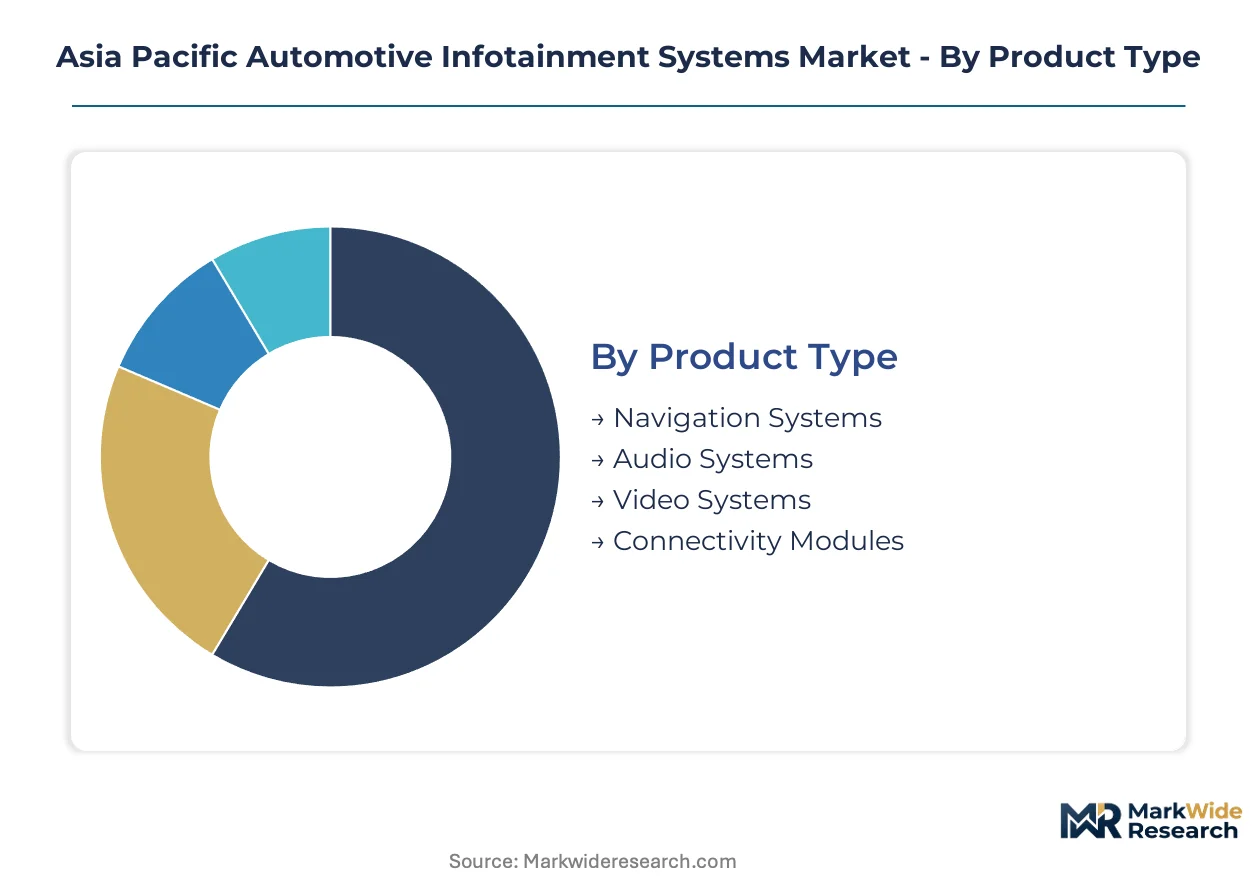
Infotainment system segmentation in Asia Pacific reflects divergent technology maturities across vehicle electrification stages and regulatory environments. Tier-1 suppliers configure hardware-software bundles differently for each category to capture value from both legacy combustion platforms and emerging software-defined architectures.
Product Type:
Volume leaders anchor procurement budgets while premium interfaces command specification margins in Japanese and South Korean OEM programs.
- Connectivity Modules:5G-V2X chipsets integrated with antenna subsystems enable vehicle-to-everything communication protocols. Demand concentrates in China's Yangtze River Delta cluster where MIIT-mandated connected vehicle standards are accelerating embedded hardware deployment ahead of smartphone mirroring obsolescence.
- Navigation Systems:Multi-constellation GNSS receivers fused with HD map databases provide lane-level positioning for advanced driver assistance. South Korean OEMs are expanding orders for augmented-reality head-up display integration, treating navigation as a premium feature differentiator against mass-market Chinese competitors.
- Audio Systems:Multi-channel amplifiers with active noise cancellation for electric vehicle cabins.
- Video Systems:Rear-seat entertainment arrays with streaming codec support for long-haul commercial vehicles.
Today's leader: Connectivity Modules. Tomorrow's challenger: Navigation Systems with AR integration.
Technology:
Architecture choices determine supplier margin durability as hardware commoditization pressures fixed-function platforms.
- Software-Defined Platforms:Decoupled application layers running on hypervisor-enabled compute substrates enable over-the-air feature activation. China's MIIT data localization mandates are fragmenting previously centralized global architectures into region-specific cloud instances, creating captive demand for compliant platform variants.
- Embedded Systems:Fixed-function processors with deterministic real-time operating systems dominate legacy vehicle parc replacement cycles. Panasonic Corporation leverages captive semiconductor fabrication to anchor supply chains across Japanese OEM programs seeking thermal-hardened designs for tropical climate operation.
- Cloud-Based Systems:Thin-client architectures dependent on continuous network connectivity.
- Hybrid Systems:Edge computing with intermittent cloud synchronization for bandwidth-constrained corridors.
Software-Defined Platforms are climbing the fastest as subscription revenue models decouple supplier economics from production cyclicality.
End User:
Procurement authority distribution shapes contract structures and technical specification control.
- OEMs:Direct platform specification authority with integrated cockpit domain controllers. Japanese and South Korean premium passenger car manufacturers are expanding embedded system orders, consolidating infotainment with instrument cluster functions under single semiconductor substrates to compress bill-of-materials complexity.
- Tier-1 Suppliers:Subsystem integrators managing thermal management and electromagnetic compatibility certification. Denso Corporation specializes in climate-hardened hardware portfolios for tropical operating environments, opening specification windows where cabin electronics face sustained high-temperature exposure.
- Aftermarket Providers:Retrofit solutions for legacy vehicle parc with basic audio system replacement demand.
- Vehicle Assemblers:Contract manufacturing arrangements in Thailand and Vietnam assembly corridors.
OEMs retain specification control today. Tier-1 Suppliers with software capabilities threaten that dominance tomorrow.
Application:
Electrification intensity determines thermal design requirements and processing power allocation priorities.
- Electric Vehicles:Cabin electronics operating without powertrain heat rejection require specialized thermal management integration. Tier-1 suppliers are concentrating R&D investment in thermal-efficient processor designs as electric vehicle production scales across China's Yangtze River Delta and South Korean battery manufacturing corridors.
- Luxury Vehicles:Multi-display arrays with haptic feedback and personalized audio zoning. Harman International competes through acoustic engineering dominance where powertrain noise masking requirements differ fundamentally from combustion platforms, opening specification windows above commodity integration.
- Passenger Cars:Mass-market touchscreen interfaces with smartphone mirroring as baseline configuration.
- Commercial Vehicles:Fleet telematics integration with driver behavior monitoring for logistics operators.
Electric Vehicles command concentrated investment today. Luxury Vehicles with differentiated audio engineering represent the steepest expansion trajectory for premium subsystem suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta automotive cluster anchors regional demand concentration, pulling embedded connectivity hardware into mass-market vehicle segments as domestic OEMs scale electric vehicle production. Japanese and South Korean premium passenger car manufacturers are expanding embedded system orders, while Southeast Asian assembly corridors in Thailand and Vietnam attract tariff-advantaged localization investments.
China
MIIT-mandated GB standards for connected vehicle data security are accelerating software-defined platform upgrades across domestic and foreign supplier operations. Foreign Tier-1 suppliers must establish domestic cloud infrastructure partnerships to maintain platform compliance. The Yangtze River Delta cluster concentrates R&D investment as electric vehicle production scales.
Japan
METI promotes connected vehicle roadmaps through JIS standards harmonization with ASEAN frameworks, creating specification windows for thermal-hardened hardware portfolios. Premium passenger car OEMs are consolidating infotainment with instrument cluster functions under single semiconductor substrates. Kanto and Kansai industrial corridors anchor captive semiconductor fabrication supply chains.
South Korea
MFDS-aligned electromagnetic compatibility rules shape hardware certification pathways for display modules targeting premium vehicle segments. Battery manufacturing corridors are driving concentrated R&D investment in thermal-efficient processor designs for electric vehicle cabin electronics. Seoul Capital Area and Busan-Ulsan clusters host subsystem integrators managing climate-hardened specifications.
Thailand
Expanding automotive assembly capacity offers localization platforms for suppliers seeking tariff-advantaged access to regional export markets. The country's national automotive regulator enforces harmonized electromagnetic compatibility standards aligned with ASEAN frameworks. Eastern Economic Corridor concentrations are pulling embedded connectivity hardware into contract manufacturing arrangements.
Vietnam
Growing vehicle assembly operations are attracting Tier-1 subsystem integrators establishing climate-hardened hardware production for tropical operating environments. Domestic industrial policy prioritizes technology transfer requirements for foreign suppliers entering production joint ventures. Northern industrial provinces around Hanoi and Hai Phong are concentrating logistics-linked manufacturing investments.
Asia Pacific Automotive Infotainment Systems Market Competitive Environment
Capacity expansion dominates the current landscape as suppliers establish localized cloud infrastructure to satisfy data sovereignty requirements across multiple jurisdictions. The vendor base concentrates around electronics conglomerates with captive semiconductor fabrication capabilities and Tier-1 subsystem integrators with thermal management specialization. Three strategic archetypes define competitive positioning: diversified electronics conglomerates, specialized automotive subsystem integrators, and audio-centric premium specialists. M&A activity and strategic partnerships represent the dominant competitive moves as suppliers seek software ecosystem depth.
Among Japanese electronics conglomerates, Panasonic Corporation and Denso Corporation exemplify divergent strategic archetypes within the competitive structure. Panasonic Corporation occupies a position representing diversified conglomerates with captive semiconductor fabrication capabilities anchoring supply chain security across OEM programs. Denso Corporation exemplifies the specialized Tier-1 integrator archetype, with its corporate structure indicating deep automotive sector focus. Harman International sits within the premium audio specialist tier, representing competitive positioning through acoustic engineering differentiation rather than commodity hardware scale.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Denso Corporation |
| Harman International |
| Robert Bosch GmbH |
| Continental AG |
| Alpine Electronics |
| Visteon Corporation |
| Pioneer Corporation |
| Mitsubishi Electric Corporation |
| Others |
Value Chain & Pricing Dynamics
Electronics conglomerates with captive semiconductor fabrication anchor pricing discipline through supply chain control, while foreign Tier-1 suppliers absorb localization premiums to satisfy China's MIIT data sovereignty mandates. This ownership pattern concentrates margin capture among Japanese and South Korean integrated producers while fragmenting pricing power for software-defined platform specialists forced into domestic cloud partnerships.
Pricing Analysis
Input-cost pass-through from Taiwan-based foundry capacity constraints is compressing margins for advanced node processors while silicon-on-insulator consolidation absorbs display driver cost pressure. Pricing stratifies across premium acoustic engineering, standard embedded connectivity modules, and economy-grade smartphone mirroring alternatives. Cost compression in standard-tier hardware is intensifying because Chinese OEMs are scaling electric vehicle production with aggressive procurement targets. Fleet operators exhibit lowest price sensitivity due to subscription-enabled feature activation models, while aftermarket retrofit providers face acute margin pressure from commoditized display sourcing.
Supply Chain Analysis
Advanced node semiconductor supply rests on Taiwan, South Korea, and Japan specialty producers, with automotive-grade silicon-on-insulator processes drawing from Japanese captive fabrication. Multilayer PCB substrates, 5G-V2X chipsets, and thermal management components feed from China, Thailand, and Vietnam assembly corridors. Single-source vulnerability concentrates in Taiwan foundry exposure for premium head-unit processors. Distribution runs through Tier-1 subsystem integrators managing electromagnetic compatibility certification before OEM platform integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific automotive infotainment functions as a regulatory compounder where China's MIIT GB standards for connected vehicle data security are accelerating software-defined platform upgrades across domestic and foreign supplier operations.
For Market Incumbents: Extend thermal-hardened hardware portfolios into Vietnam and Thailand assembly corridors to capture tariff-advantaged regional export access. Deepen software ecosystem partnerships to defend against domestic Chinese platform competitors leveraging captive cloud infrastructure. Prioritize ASEAN electromagnetic compatibility certification harmonization to reduce multi-jurisdiction adaptation costs.
For New Entrants and Emerging Players: Australia's urban mobility-service fleet operators represent an underserved buyer archetype prioritizing over-the-air update latency guarantees above launch-day hardware specifications. White-space concentration sits in commercial vehicle rear-seat entertainment with streaming codec support for long-haul logistics corridors. Enter through audio subsystem premiumization for electric vehicle cabins where powertrain noise masking requirements differ from combustion platforms.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized Tier-1 integrators lacking software-defined platform capabilities but holding climate-hardened hardware expertise. Long-term viability favors suppliers with demonstrated GB standards compliance and domestic China cloud partnerships. Monitor MIIT enforcement intensity for cross-border transmission restrictions as the primary inflection signal for localization investment returns.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Decouples supplier economics from production cyclicality through subscription revenue models. |
| Geographic Manufacturing Footprint | Thailand and Vietnam localization satisfies ASEAN tariff advantages and MIIT data sovereignty requirements. |
| Battery Supply Agreement | South Korean cell manufacturers anchor thermal-efficient processor R&D for electric vehicle cabin electronics. |
| Platform Standardization | Japanese OEMs consolidate infotainment with instrument cluster functions under single semiconductor substrates. |
| Charging Infrastructure Partnership | China's Yangtze River Delta cluster pulls embedded connectivity hardware into mass-market electric vehicle segments. |
Study Parameters
Coverage spans China, Japan, South Korea, Thailand, and Vietnam, with primary inputs from each market's automotive electronics ecosystem. The research combines structured interviews with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations heads with secondary validation from vehicle production databases, IHS Markit registration data, MIIT regulatory filings, and METI JIS standard documentation. Bottom-up segmentation modeling triangulates against top-down regional demand aggregation.
Rate-of-change decomposition separates volume expansion from value capture migration across software-defined platform adoption curves. The analytical framework models segmentation across vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster throughout the forecast period. CAGRs derive from regression analysis of historical penetration rates against regulatory milestone timing and electric vehicle production scaling trajectories. Semiconductor procurement lead times and software sprint cycle mismatches inform inventory mismatch risk adjustments.
Underlying measurement precision varies by segment; software-defined platforms and connectivity modules carry tighter precision than aftermarket retrofit categories due to disclosed OEM procurement volumes. Forecasts reflect assumptions regarding MIIT enforcement consistency, Taiwan foundry capacity allocation, and ASEAN electromagnetic compatibility harmonization progress. A small set of triggers warrants ongoing watch: MIIT cross-border transmission rule tightening, Taiwan semiconductor supply disruption events, and South Korean battery manufacturing corridor expansion rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Automotive Data Monetization Market
Telematics and Infotainment
Europe Commercial Vehicle Telematics Market
Telematics and Infotainment
Advanced Traveller Information System Market
Telematics and Infotainment
Marine Telematics Market
Telematics and Infotainment
Electric Vehicle Telematics Market
Telematics and Infotainment
Automotive Human Machine Interface (HMI) Market
Telematics and Infotainment
Europe Automotive Navigation System Market
Telematics and Infotainment
Europe Automotive Infotainment Systems Market
Telematics and Infotainment
Europe Vehicle Remote Diagnostic Market
Telematics and Infotainment
Automotive Infotainment Market
Telematics and Infotainment
Asia Pacific Automotive Navigation System Market
Telematics and Infotainment
Europe Telematics Market
Telematics and Infotainment
In Vehicle Infotainment Market
Telematics and Infotainment
Asia-Pacific Automotive Telematics Market
Telematics and Infotainment
Electric Vehicle Infotainment Market
Telematics and Infotainment
Vehicle Digital Cockpit Market