
 Commercial Air Brake Market | 2026-2036
Commercial Air Brake Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Air Brake Market Insights
FMVSS 121 certification is redrawing competitive boundaries for air brake suppliers serving commercial vehicle platforms. Knorr-Bremse AG leverages its integrated compressor and control module portfolio to anchor European OEM relationships. Wabtec Corporation dominates North American rail and transit braking, while Bendix CVS LLC specializes in aftermarket service channels and fleet support infrastructure across the United States.
Commercial air brakes are pneumatic friction braking systems operating at 100–120 psi supply pressure, using compressed air to actuate S-cam, wedge, or disc mechanisms that slow heavy-duty vehicles with gross combination weights exceeding 26,000 pounds. Disc brakes command premium positioning in front axle applications due to superior thermal fade resistance and shorter stopping distances under loaded conditions. Air drum brakes retain volume leadership in rear axle and trailer installations where cost sensitivity and service simplicity outweigh performance advantages. Anti-lock Braking Systems generate expanding retrofit demand as aging fleets face mandated compliance upgrades.
Federal Motor Carrier Safety Administration hours-of-service rules and NHTSA stopping-distance mandates directly shape brake specification requirements for interstate carriers. EPA Phase 2 greenhouse gas standards indirectly pressure brake system efficiency through reduced rolling resistance and regenerative compatibility demands. Stakeholders must monitor how pending updates to FMVSS 121 testing protocols and state-level fleet safety inspections reshape product qualification timelines and aftermarket parts eligibility.
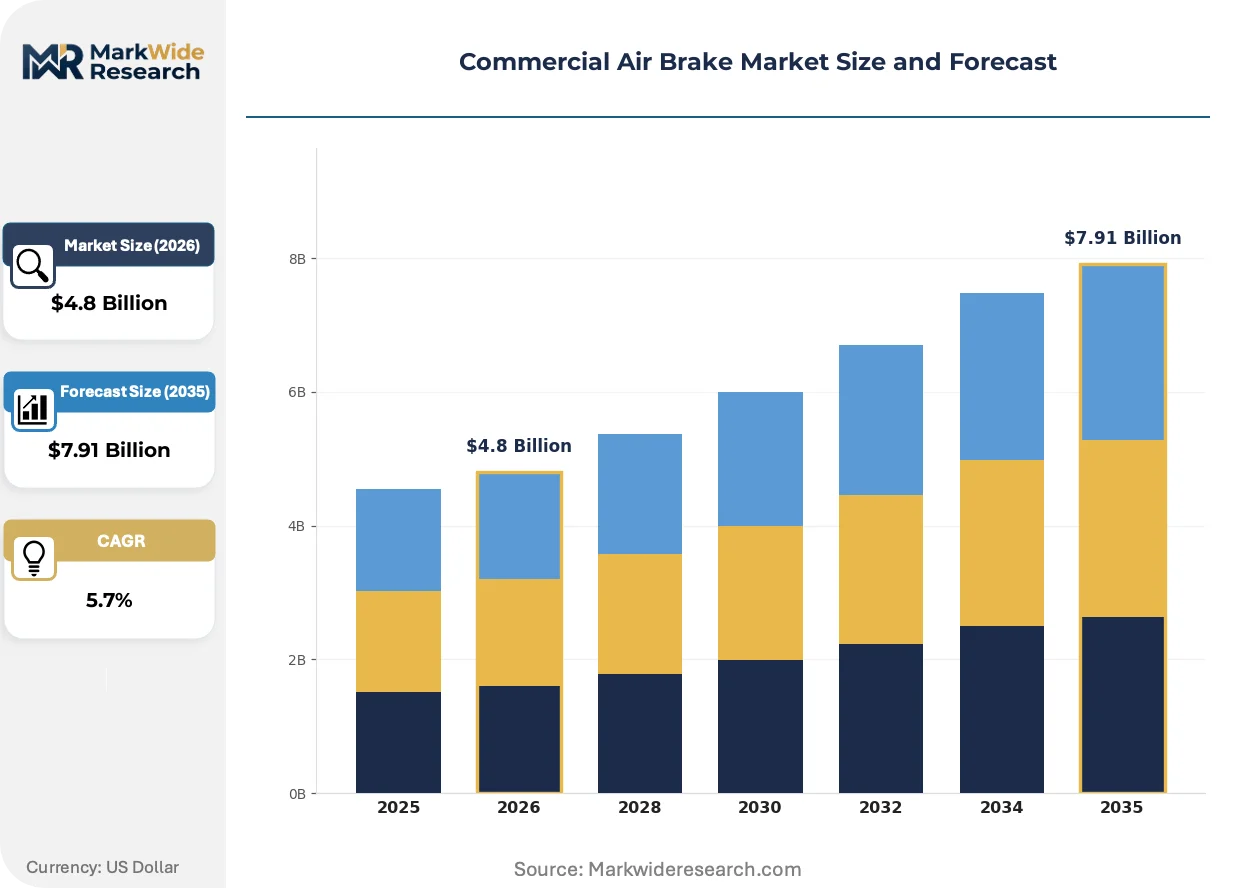
Market Dynamics
Fleet operators face compressed replacement cycles as NHTSA stopping-distance mandates force wholesale brake system upgrades across heavy-duty vehicle platforms.
Growth Catalysts
- NHTSA FMVSS 121 mandates:Federal stopping-distance requirements compel disc brake retrofits on front axles of Class 8 tractors, creating sustained aftermarket demand.
- ABS integration:Anti-lock modules are becoming standard specification on refrigerated trailers and tanker fleets where stability control reduces rollover incidents.
- Fleet consolidation:Large national carriers with centralized procurement are standardizing on premium brake configurations to simplify maintenance protocols.
Market Restraints
- Cast iron supply concentration:Drum brake manufacturing depends on foundry capacity concentrated in specific industrial regions, exposing suppliers to input volatility.
- Copper-free friction material transition:Washington and California environmental regulations are forcing reformulation of brake linings, raising R&D costs for smaller suppliers.
- Air compressor durability limits:Pneumatic system reliability in extreme cold climates constrains deployment in northern Canadian oilfield operations.
Strategic Opportunities
- Electric truck compatibility:Regenerative braking integration with pneumatic foundation brakes creates specification opportunities for blended friction systems.
- Telematics-enabled predictive maintenance:Brake wear sensors transmitting to fleet management platforms are opening subscription service revenue streams.
- Mexico manufacturing expansion:OEM assembly growth in Querétaro and Nuevo León is pulling localized brake component supply chains southward.
Industry Challenges
- FMVSS 121 certification timelines:Extended validation protocols for new friction compounds delay product launches by 18-24 months.
- Technician training gaps:Fleet maintenance departments lack sufficient certified air brake specialists to support advanced ABS diagnostics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Air Brake Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: S-cam Brakes, Disc Brakes, Air Drum Brakes, Anti-lock Braking Systems End User: Trucking Companies, Bus Operators, Fleet Managers, OEMs Installation Type: New Installations, Retrofits, Upgrades, Replacements Service Type: Maintenance, Repair, Overhaul, Inspection |
| Companies Covered | Knorr-Bremse AG, Meritor, Inc., Haldex AB, ZF Friedrichshafen AG, Wabtec Corporation, Nabtesco Corporation, TSE Brakes Inc., SORL Auto Parts Inc., Bendix CVS LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Air Brake Market Trends and Innovations
Electronics are penetrating pneumatic systems at an accelerating pace, compressing traditional mechanical component value chains while enabling predictive capabilities.
Electro-pneumatic brake controllers are miniaturizing valve bodies and integrating sensor arrays directly into actuator housings. Regional less-than-truckload fleets are piloting these configurations to reduce weight and wiring complexity. This convergence is compressing supplier margins on standalone valve products while expanding addressable market for integrated control modules.
NHTSA is revising test protocols for loaded stopping-distance performance under wet pavement conditions. The proposed amendments would tighten tolerance bands for disc brake thermal fade characteristics. Front axle disc configurations on combination vehicles would face the most stringent new qualification requirements.
Large fleet buyers are consolidating brake procurement through direct OEM channel agreements rather than aftermarket distributors. National carriers with over 5,000 power units are negotiating captive supply arrangements with brake system integrators. This concentration is most visible among dedicated contract carriers serving retail and grocery distribution networks.
Commercial Air Brake Market Segmentation
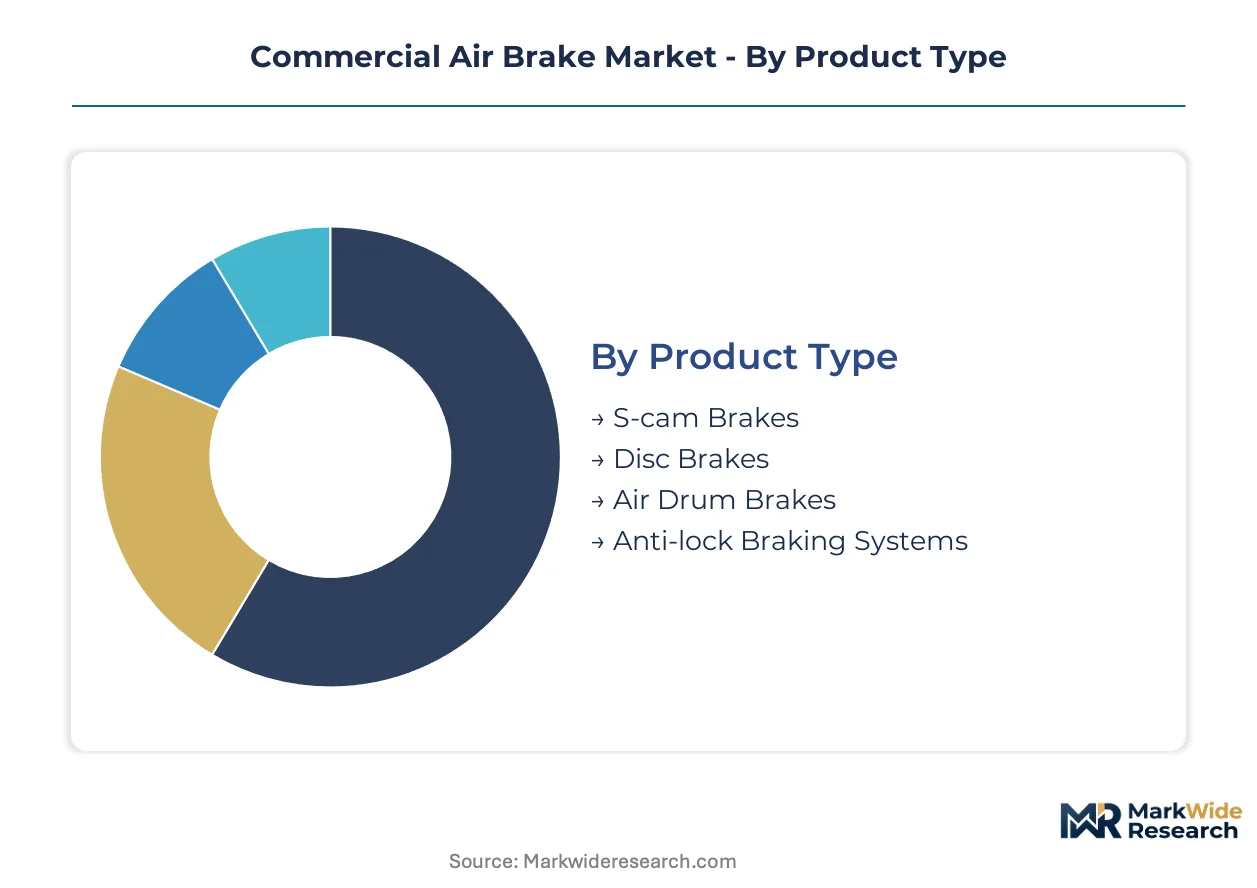
Brake specification patterns diverge sharply across duty cycles, regulatory exposure, and fleet ownership structures. Understanding these fault lines reveals where procurement power concentrates and which technologies command sustainable premiums.
Product Type:
NHTSA stopping-distance rules and state-level friction material bans create divergent compliance burdens across brake architectures.
- Disc Brakes:Pneumatically actuated caliper systems deliver superior thermal fade resistance under loaded stopping scenarios. Front axle installations on Class 8 tractors dominate procurement volume in the United States, driven by FMVSS 121 mandates requiring shorter stopping distances for combination vehicles.
- Air Drum Brakes:S-cam and wedge-actuated drum configurations retain cost advantages in rear axle and trailer positions. Fleet managers prioritize these systems for high-mileage linehaul trailers where service intervals and parts availability outweigh absolute performance metrics.
- S-cam Brakes:The dominant drum brake mechanism in North American heavy-duty applications, using a rotating camshaft to spread brake shoes against the drum surface.
- Anti-lock Braking Systems:Electronic control modules modulating air pressure to prevent wheel lockup during emergency stops, now standard on refrigerated trailers and tanker fleets.
Established volume favors Air Drum Brakes; emerging adoption favors Disc Brakes.
End User:
Procurement scale and technical sophistication determine specification authority across buyer categories.
- Fleet Managers:Centralized buyers at national carriers with 5,000-plus power units negotiate direct OEM supply agreements, standardizing configurations to compress maintenance protocols and training costs. Their specification power is reshaping supplier relationships across dedicated contract carriage serving retail distribution networks.
- OEMs:Vehicle manufacturers integrate brake systems at assembly, capturing warranty lifecycle value and influencing aftermarket parts eligibility through proprietary diagnostic interfaces. Their platform decisions lock in foundation brake architectures for decade-long production runs.
- Trucking Companies:Owner-operators and small fleet owners purchasing through distributor channels, prioritizing upfront cost and parts availability over integrated system performance.
- Bus Operators:Transit authorities and motorcoach fleets subject to distinct Federal Transit Administration brake testing protocols and passenger safety mandates.
Volume concentrates with Fleet Managers; margin expansion concentrates with OEMs.
Installation Type:
Replacement cycle timing and regulatory compliance deadlines segment demand between new build and aftermarket channels.
- Retrofits:Mandated upgrades to meet NHTSA stopping-distance rules drive front axle disc brake conversions on existing Class 8 tractors. Compressed compliance timelines have created sustained aftermarket demand independent of normal wear-based replacement cycles.
- New Installations:Factory-integrated systems specified at vehicle assembly, capturing warranty coverage and OEM diagnostic compatibility. These installations set the technical baseline for subsequent aftermarket parts eligibility.
- Upgrades:Elective enhancements adding ABS modules or stability control to trailers not originally so equipped, common in tanker and hazardous materials fleets.
- Replacements:Scheduled maintenance-driven component swaps following wear-based service intervals, dominating revenue in drum brake segments.
Regulatory pressure elevates Retrofits; fleet standardization elevates New Installations.
Service Type:
Revenue recurrence and technical barrier height separate commoditized maintenance from specialized overhaul operations.
- Maintenance:Routine inspection, adjustment, and lining replacement services performed at fleet facilities or dealer networks. This segment captures the highest transaction frequency but faces pricing pressure from standardized labor guides and competitive bidding.
- Overhaul:Complete actuator and control module rebuilds requiring specialized equipment and certified technicians. ABS diagnostics and electronic control unit programming create technical barriers that protect margins for authorized service providers.
- Repair:Unscheduled component replacement following failure or accident damage, generating premium pricing for expedited parts availability.
- Inspection:Mandatory periodic examinations under FMCSA and state fleet safety programs, creating recurring revenue for certified inspection stations.
Transaction density favors Maintenance; margin protection favors Overhaul.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal stopping-distance mandates and fleet replacement cycles concentrate procurement volume in the United States, while Canadian oilfield operations and Mexican manufacturing expansion create distinct demand patterns across North America.
United States
Class 8 tractor fleet operators in the United States face compressed compliance timelines under NHTSA FMVSS 121 rules, forcing front axle disc brake retrofits independent of normal wear cycles. The Federal Motor Carrier Safety Administration hours-of-service regulations indirectly shape brake specification priorities for interstate carriers. Detroit-Warren-Livonia and Chicago-Naperville-Elgin anchor the densest concentrations of heavy-duty vehicle assembly and aftermarket brake distribution infrastructure.
Canada
Canadian heavy-duty fleets serving Alberta oil sands and northern mining corridors encounter pneumatic system reliability constraints in extreme cold climates, limiting air compressor deployment in sub-zero operations. Transport Canada's Motor Vehicle Safety Standards align with NHTSA protocols while adding distinct winter performance testing requirements. Calgary and Edmonton host specialized service networks for oilfield truck brake overhaul operations.
Mexico
OEM assembly growth in Querétaro and Nuevo León is pulling localized brake component supply chains southward from traditional United States manufacturing bases. Mexican federal vehicle safety regulations under NOM standards create parallel certification requirements for brake systems serving domestic and export markets. The Bajío automotive corridor around León and Silao concentrates stamping and friction material processing capacity for North American supply integration.
Germany
German commercial vehicle OEMs anchor European air brake technology development, with integrated compressor and control module portfolios serving export markets globally. KBA type-approval requirements for braking systems establish technical baselines adopted across EU member states. Stuttgart and Munich metropolitan areas host the headquarters and primary R&D facilities of leading pneumatic brake system integrators.
China
Chinese heavy-duty truck production volume drives foundation brake demand, with domestic suppliers capturing share in drum brake segments while foreign joint ventures dominate disc and ABS modules. MIIT vehicle approval protocols and GB standards for commercial vehicle braking performance shape product qualification requirements. The Yangtze River Delta around Shanghai and the Beijing-Tianjin-Hebei corridor concentrate OEM assembly and tier-one brake component manufacturing.
Commercial Air Brake Market Competitive Landscape
Listed leaders compete with private specialists across technology integration and aftermarket service channels, creating a tiered structure where scale-driven system integrators coexist with regional component fabricators. Consolidation pressures concentrate around OEM direct supply agreements and captive fleet procurement arrangements. Three archetypes dominate: integrated brake system suppliers with compressor-to-actuator portfolios, aftermarket service specialists with diagnostic and rebuild capabilities, and regional friction material manufacturers serving price-sensitive trailer segments. Competitive moves center on strategic partnerships for electric truck compatibility development and geographic expansion into Mexican manufacturing corridors.
Within the integrated system tier, Knorr-Bremse AG and Wabtec Corporation exemplify divergent geographic anchoring strategies, with the former representing European OEM relationship depth and the latter occupying a position in North American rail and transit braking extension. Bendix CVS LLC sits within the aftermarket service specialist archetype, with its name signaling United States-based fleet support infrastructure concentration. These three entities illustrate how competitive positioning separates technology-integrated suppliers from channel-anchored service providers across the value chain.
| Leading Market Players |
|---|
| Knorr-Bremse AG |
| Meritor, Inc. |
| Haldex AB |
| ZF Friedrichshafen AG |
| Wabtec Corporation |
| Nabtesco Corporation |
| TSE Brakes Inc. |
| SORL Auto Parts Inc. |
| Bendix CVS LLC |
| Others |
Pricing and Supply Chain Analysis
Foundry capacity utilization above 85% in the United States and Mexico establishes asymmetric pricing power for drum brake castings, compressing margins for smaller fabricators while anchoring price floors for integrated system suppliers serving OEM direct channels. This concentration dynamic feeds back into procurement decisions, as fleet buyers with volume scale negotiate captive supply arrangements that lock out distributor-dependent competitors.
Pricing Analysis
FMVSS 121 certification grade creates the primary spread between premium disc brake systems and commodity drum configurations. Three-tier pricing structure separates OEM-validated integrated modules from aftermarket service-grade components and economy trailer replacement parts. Cost compression in the economy tier is intensifying because Chinese friction material imports face escalating state-level copper-free formulation mandates. Small fleet owner-operators purchasing through distributor channels exhibit highest price sensitivity, while national carriers with centralized procurement prioritize total cost of ownership over upfront component cost.
Supply Chain Analysis
Strait of Hormuz transit exposure for specialty alloy feedstocks underwrites supply vulnerability for high-performance friction material producers serving disc brake applications. Manufacturing concentration centers on the United States, Mexico, and China, with the Bajío corridor and Detroit-Warren-Livonia anchoring North American stamping and assembly capacity. Raw material dependencies include gray iron castings, copper-free friction compounds, and pneumatic valve forgings. Single-source vulnerability concentrates in foundry capacity for S-cam and wedge brake housings. Distribution runs through OEM captive supply agreements for new vehicle build, with independent aftermarket channels serving wear-based replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where NHTSA certification timelines and FMVSS 121 validation protocols create switching costs that protect incumbent positions across decade-long OEM platform cycles.
For Market Incumbents: Shield market position by deepening backward integration into copper-free friction material production to preempt California and Washington environmental compliance costs. Prioritize captive supply agreements with national carriers operating above 5,000 power units, as fleet consolidation compresses procurement channels and locks out distributor-dependent competitors. The emerging threat of Chinese disc brake module imports with accelerated FMVSS certification timelines demands proactive OEM relationship anchoring. For New Entrants and Emerging Players: FMVSS 121 fast-track certification for blended regenerative-pneumatic systems opens white-space penetration into electric truck retrofit channels where incumbents lack validated product portfolios. Target the refrigerated trailer ABS upgrade segment, where stability control mandates create compressed compliance timelines and fleet managers prioritize expedited availability over brand loyalty. A telematics-integrated brake wear monitoring service bundled with hardware supply offers the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors aftermarket service specialists with diagnostic capabilities and authorized rebuild networks, as fleet electrification extends replacement intervals and concentrates revenue in overhaul rather than replacement transactions. Long-term viability hinges on electric truck compatibility development and Mexican manufacturing footprint expansion. The signal to watch is NHTSA loaded stopping-distance test protocol revisions under wet pavement conditions, which would accelerate disc brake retrofit demand and reshape parts eligibility requirements.| Strategic Initiative | Industry Significance |
|---|---|
| FMVSS 121 Certification Investment | Validates front axle disc brake configurations for Class 8 tractor compliance mandates. |
| Copper-Free Friction Material Transition | Aligns brake lining formulations with California and Washington environmental regulations. |
| Mexican Manufacturing Footprint Expansion | Captures OEM assembly growth in Querétaro and Nuevo León automotive corridors. |
| Telematics-Enabled Predictive Maintenance | Creates subscription revenue streams through brake wear sensor data integration. |
| Electric Truck Compatibility Development | Positions pneumatic foundation brakes for regenerative braking system integration. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with fleet maintenance directors, OEM platform engineers, aftermarket distributor principals, and brake system technical specialists; and secondary validation against NHTSA FMVSS 121 certification databases, EPA Phase 2 greenhouse gas filings, vehicle production registration data, and customs trade records for friction material imports. Bottom-up triangulation across component-level bill-of-materials analysis and top-down fleet replacement cycle modeling ensured convergence on volume and value estimates.
Across the analysis window, forecasts reflect analytical frameworks segmenting by brake architecture, installation type, end-user procurement authority, and regional regulatory cluster. CAGRs derive from regression against historical fleet replacement patterns, NHTSA compliance deadline impacts, and OEM platform life cycles. Industry-specific inputs include foundry capacity utilization rates, copper-free friction material adoption curves, and electric truck production ramp assumptions.
Decision-makers should treat outputs as directional under base assumptions of sustained NHTSA enforcement and stable foundry input costs; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as EPA Phase 3 greenhouse gas standards and state-level fleet safety inspection protocols evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Automated Truck Market
Commercial Vehicles
Russia Commercial Vehicle Market
Commercial Vehicles
Commercial Vehicle Foundation Brakes Market
Commercial Vehicles
Global Fuel Cell Commercial Vehicle Market
Commercial Vehicles
Electric Truck Chassis Market
Commercial Vehicles
Small Commercial Vehicle Market
Commercial Vehicles
Refrigerated Vans Market
Commercial Vehicles
Industrial Truck Market
Commercial Vehicles
Heavy-Duty Trucks Market
Commercial Vehicles
Canada Commercial Vehicles Market
Commercial Vehicles
Truck-As-A-Service Market
Commercial Vehicles
Asia Pacific Non Passenger Vehicle Market
Commercial Vehicles
Modular Trailer Market
Commercial Vehicles
Commercial Vehicle Steering Column Market
Commercial Vehicles
Commercial Truck Use APU Market
Commercial Vehicles
Europe Light Commercial Vehicle Trailer Market