
 Global Car Digital Cockpit Market | 2026-2036
Global Car Digital Cockpit Market Size, Share, and Industry Trends Forecast 2026-2036
Global Car Digital Cockpit Market Analysis
Glass substrate is consolidating around larger-format curved displays as automakers phase out mechanical instrument clusters. Continental AG leverages captive production of bonded display modules to sustain cost leadership across European premium programs. Robert Bosch GmbH anchors its position through R&D intensity in human-machine interface software stacks. Visteon Corporation specializes in integrated domain controller architectures that merge infotainment with instrument cluster functions.
A car digital cockpit encompasses the unified electronic interface replacing traditional analog gauges and discrete control panels, typically integrating multiple high-resolution displays with touch, voice, and haptic feedback operating over automotive Ethernet and LVDS backbones at temperatures from minus forty to eighty-five degrees Celsius. Its primary purpose is to centralize vehicle information, entertainment, and control functions while minimizing driver cognitive load. Central Display and Head-Up Display categories command the dominant share of current installations as OEMs prioritize screen real estate for navigation and ADAS visualization. OLED technology is displacing LCD in luxury vehicle programs where contrast ratio and form factor flexibility justify unit cost premiums, while MicroLED remains pre-commercial for automotive volume applications.
FCC certification governs wireless connectivity modules embedded within cockpit systems in the United States, while ECE R121 regulates speedometer and tell-tale display legibility across European type approvals. NHTSA distraction guidelines and Euro NCAP assessment protocols directly shape touchscreen response latency requirements and voice recognition minimum performance thresholds. Stakeholders must monitor divergence between regional software content regulations and over-the-air update compliance frameworks as cockpit systems become persistent network endpoints.
Market Dynamics
Automotive OEMs face mounting pressure to consolidate discrete electronic control units into unified domain architectures as NHTSA and Euro NCAP tighten driver distraction protocols and mandate larger, more legible display surfaces.
Growth Catalysts
- OLED Display Penetration:Premium vehicle programs in Germany and South Korea adopt curved OLED panels for instrument clusters, exploiting superior contrast ratios and form factor flexibility to differentiate luxury interiors.
- Euro NCAP Safety Mandates:The assessment protocol's 2026 update prioritizes direct driver monitoring and augmented reality head-up displays, compelling European OEMs to upgrade cockpit electronics ahead of model refresh cycles.
- Automotive Ethernet Backbone:100BASE-T1 and 1000BASE-T1 standards enable real-time data fusion between ADAS sensors and cockpit displays, supporting higher-resolution rendering with reduced wiring harness complexity.
Market Restraints
- Semiconductor Supply Concentration:Advanced driver ICs and timing controllers for large-format displays concentrate among Taiwanese and South Korean foundries, exposing OEMs to geopolitical disruption and allocation rationing.
- Thermal Management Complexity:MicroLED and high-brightness OLED modules generate localized heat loads exceeding 85°C operational thresholds in direct sunlight, requiring active cooling subsystems that add cost and packaging volume.
- Software Fragmentation:Proprietary hypervisor implementations from competing tier-one suppliers create integration friction, forcing OEMs to maintain multiple middleware stacks across vehicle platforms.
Strategic Opportunities
- India Passenger Vehicle Segment:Maruti Suzuki and Hyundai Motor India are piloting simplified digital cockpit configurations for compact SUVs, targeting first-time buyers with smartphone-mirror-centric architectures at sub-premium price points.
- Over-the-Air Update Revenue:Persistent connectivity transforms cockpit systems into subscription endpoints, enabling feature unlocks for navigation, voice assistants, and themed display skins throughout vehicle ownership.
- MicroLED Pre-Commercial Positioning:Early partnerships between display manufacturers and German luxury OEMs are securing volume allocation for 2028-2030 model generations, ahead of mass-market cost curves.
Industry Challenges
- Functional Safety Certification:ISO 26262 ASIL-B and ASIL-C ratings for instrument cluster graphics pipelines demand rigorous verification cycles, extending development timelines by 12-18 months for new platform introductions.
- Legacy Architecture Migration:OEMs maintaining parallel analog and digital cockpit variants across model years face duplicated validation costs and supplier management complexity.
- Human Factors Engineering Gap:Shortage of automotive UX specialists with expertise in glance time modeling and cognitive load assessment limits OEMs' ability to optimize HMI designs for safety compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Car Digital Cockpit Market |
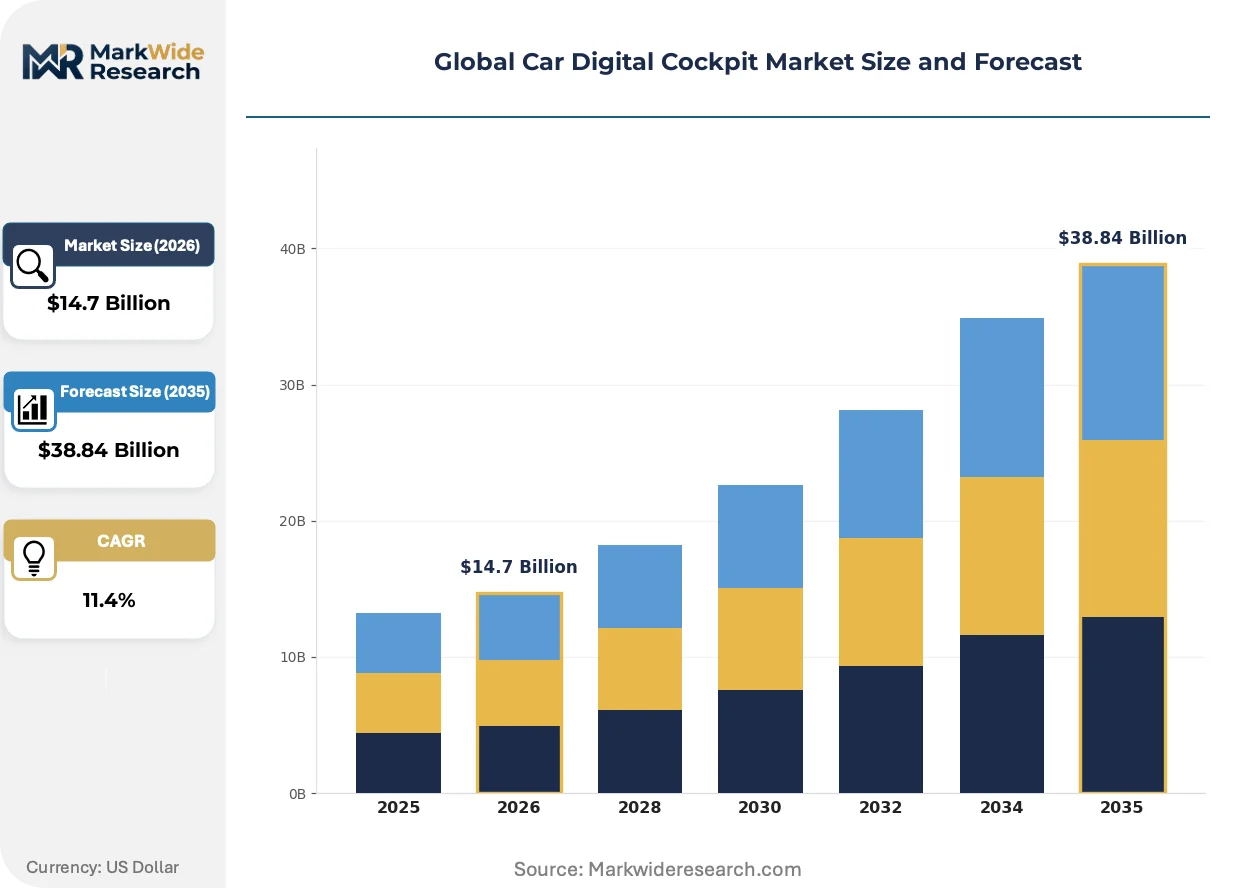
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $38.84 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Head-Up Display, Instrument Cluster, Central Display, Rear-Seat Entertainment Technology: LCD, OLED, QLED, MicroLED End User: Passenger Vehicles, Commercial Vehicles, Luxury Vehicles, Electric Vehicles Feature: Voice Recognition, Touchscreen Interface, Gesture Control, Navigation System |
| Companies Covered | Continental AG, Robert Bosch GmbH, DENSO Corporation, Visteon Corporation, HARMAN International, Panasonic Holdings Corporation, Aptiv PLC, Hyundai Mobis, Marelli Holdings Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Car Digital Cockpit Market Emerging Trajectories
Glass substrate processing and bonded display module assembly are converging with software-defined vehicle architectures, compressing hardware refresh cycles and enabling post-sale feature activation.
Freeform curved display glass is automating the elimination of mechanical bezel structures and discrete gauge housings. Premium OEMs in Germany and Japan are adopting single-piece bonded modules spanning A-pillar to A-pillar. This technology is automating the consolidation of previously separate instrument cluster, infotainment, and passenger entertainment surfaces into unified, shape-conformable assemblies.
CSRD disclosure requirements and EU AI Act risk classification for driver monitoring systems are mandating documented algorithmic transparency and bias testing for cockpit-integrated cameras. Tier-one suppliers must now maintain technical documentation repositories subject to third-party audit. European premium programs face the steepest compliance burden, with some OEMs segregating AI-enabled features by market to manage regulatory divergence.
Fleet operators and ride-hail platforms are unbundling cockpit hardware specifications from vehicle procurement decisions, treating display and HMI packages as interchangeable modules across multi-OEM fleets. This procurement fragmentation pressures tier-one suppliers to standardize mechanical and electrical interfaces. The shift is most visible in North American commercial fleet channels, where leasing companies negotiate cockpit downgrade options to optimize total cost of ownership.
Global Car Digital Cockpit Market Segmentation
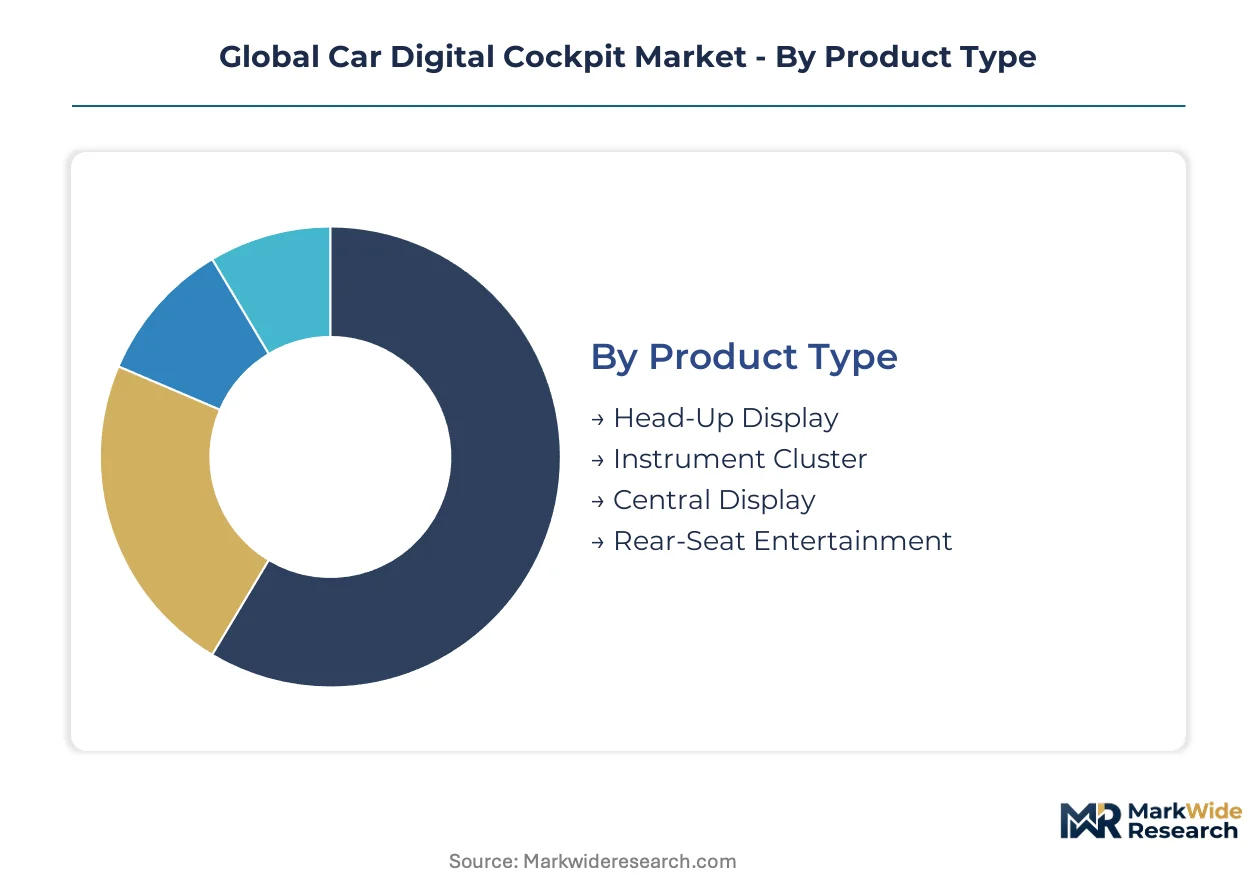
Digital cockpit segmentation tracks how automakers allocate spending across display technologies and user interfaces during platform refresh cycles. Upgrade decisions hinge on regulatory mandates for visibility, thermal performance thresholds, and the shift from distributed ECUs to domain controllers.
Product Type:
Replacement cycles for cockpit hardware accelerate as Euro NCAP and NHTSA mandates force larger, more legible display surfaces across vehicle classes.
- Head-Up Display:Projects navigation and ADAS alerts onto windshields using combiner optics or direct projection. Demand clusters in German premium programs where augmented reality overlays justify unit cost premiums against safety scoring requirements.
- Instrument Cluster:Replaces analog gauges with fully reconfigurable digital surfaces, typically 10-12 inches diagonal. Chinese EV OEMs dominate volume placements as they standardize unified clusters across compact and mid-size platforms.
- Central Display:Curved bonded modules spanning 12-15 inches integrate infotainment and climate controls. South Korean suppliers anchor production for this segment.
- Rear-Seat Entertainment:Deployed primarily in luxury MPVs and long-wheelbase sedans for the Chinese and Middle Eastern markets. Adoption remains concentrated in chauffeur-driven configurations.
Volume placements concentrate in Central Display; the faster expansion belongs to Head-Up Display.
Technology:
Cost tiers separate display technologies by contrast performance, form factor flexibility, and thermal management requirements.
- LCD:Dominates mass-market installations with mature supply chains and proven automotive qualification. Japanese and Taiwanese panel makers sustain cost leadership through scale.
- OLED:Organic emitters enable curved form factors and superior black levels without backlight assemblies. German and South Korean luxury programs drive adoption despite higher unit costs and burn-in mitigation complexity.
- QLED:Quantum dot enhancement layers extend LCD color gamut for mid-premium positioning. Samsung Display anchors supply for this transitional technology.
- MicroLED:Inorganic emitters promise brightness and longevity advantages but remain pre-commercial for automotive volume. Early partnerships target German luxury 2028-2030 model generations.
LCD retains the dominant placement volume; OLED climbs the fastest as curved instrument clusters proliferate.
End User:
Application requirements diverge sharply between passenger convenience and commercial fleet durability specifications.
- Passenger Vehicles:Compact and mid-size segments standardize simplified digital cockpits with smartphone-centric architectures. Maruti Suzuki and Hyundai Motor India pilot configurations for first-time buyers.
- Commercial Vehicles:Fleet operators prioritize ruggedized displays with glove-compatible touch and anti-glare coatings. North American leasing companies negotiate downgrade options to optimize total cost of ownership.
- Luxury Vehicles:A-pillar to A-pillar bonded glass modules eliminate mechanical bezels entirely. German and Japanese OEMs lead adoption of freeform curved substrates.
- Electric Vehicles:Integrated domain architectures merge instrument cluster and infotainment functions over Automotive Ethernet backbones. Chinese OEMs accelerate adoption ahead of ICE platform refresh cycles.
Passenger Vehicles account for the dominant placement base; Electric Vehicles gain share fastest as dedicated EV platforms multiply.
Feature:
Customer type separates interface modalities by safety compliance burden and development timeline risk.
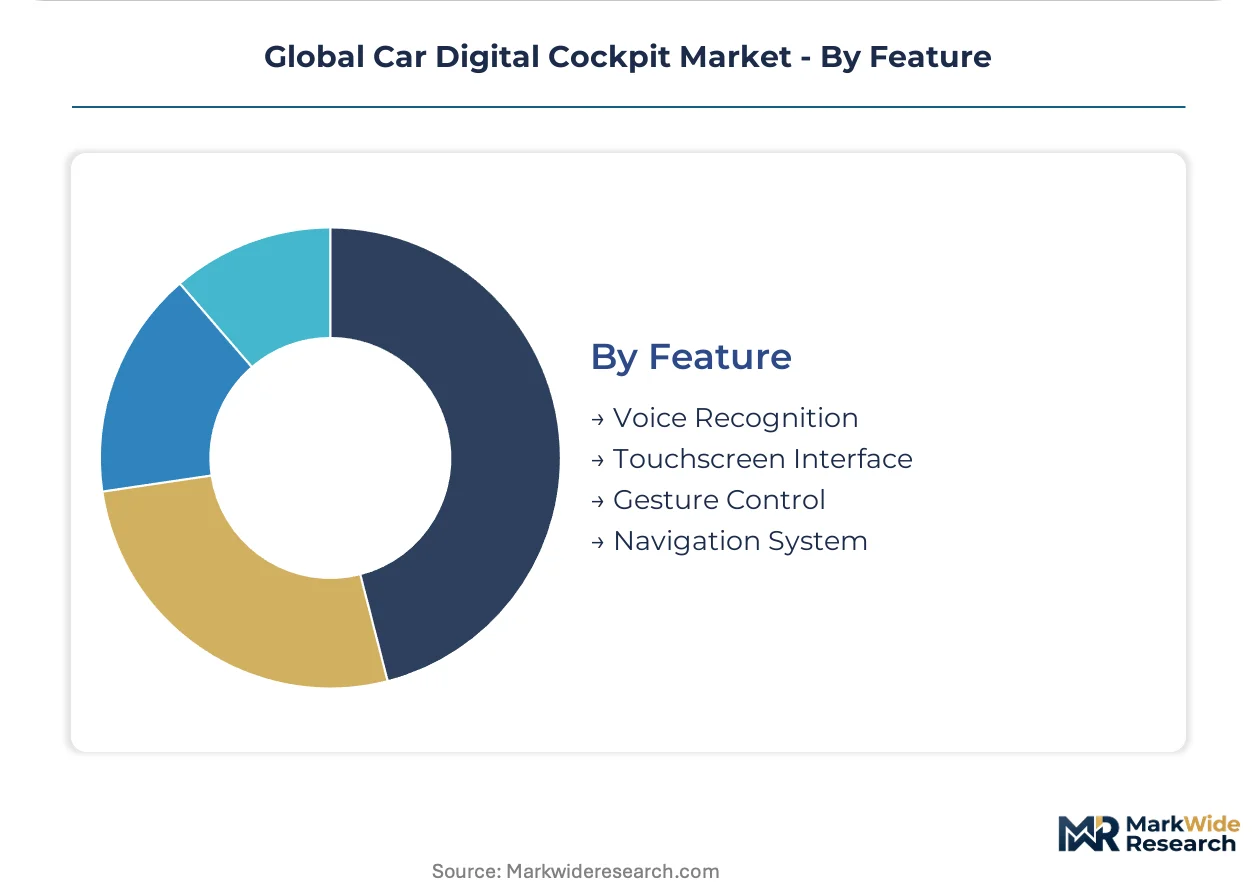
- Voice Recognition:Natural language processing reduces glance time for navigation and media selection. Euro NCAP assessment protocols mandate minimum performance thresholds.
- Touchscreen Interface:Capacitive multi-touch dominates but faces regulatory pressure on response latency and haptic feedback. NHTSA guidelines directly shape design constraints.
- Gesture Control:Time-of-flight cameras enable non-contact interaction for basic functions. BMW and Volkswagen Group have deployed this in premium programs with mixed user acceptance.
- Navigation System:Real-time traffic and EV routing integration requires persistent connectivity. Subscription revenue models transform this from hardware sale to recurring service.
Touchscreen Interface holds the volume concentration; Voice Recognition expands most quickly as hands-free mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates the dominant share of digital cockpit demand as domestic EV OEMs accelerate integrated domain architectures ahead of legacy platform refresh cycles. Tier-one suppliers operate dedicated engineering centers in Shanghai, Beijing, and Shenzhen to support localized development timelines.
China
Domestic EV OEMs BYD and NIO standardize unified cockpit systems across compact and mid-size platforms, driving volume placements. MIIT mandates govern display legibility and driver monitoring system performance for type approval. Engineering clusters in Shanghai and Beijing host R&D facilities for both local suppliers and European tier-ones seeking proximity to OEM decision centers.
Germany
Premium OEMs BMW, Mercedes-Benz, and Audi adopt A-pillar to A-pillar bonded glass modules to eliminate mechanical bezels entirely. KBA enforces ECE R121 speedometer visibility standards and Euro NCAP assessment protocols that shape touchscreen latency requirements. Stuttgart and Ingolstadt anchor development activity where Continental AG and Robert Bosch GmbH maintain captive display module production.
United States
Detroit Three OEMs consolidate infotainment and instrument cluster functions under pressure from NHTSA distraction guidelines. FCC certification governs wireless connectivity modules embedded within cockpit systems. Michigan's automotive corridor hosts validation facilities where tier-one suppliers test human-machine interface designs against federal safety thresholds.
South Korea
Hyundai Motor Group and Kia accelerate curved OLED adoption for instrument clusters across Genesis luxury programs. MFDS-equivalent automotive regulations align with Euro NCAP protocols for driver monitoring compliance. Gyeonggi Province concentration includes Samsung Display production of quantum dot enhancement layers for mid-premium vehicle programs.
India
Maruti Suzuki and Hyundai Motor India pilot simplified digital cockpit configurations for compact SUVs targeting first-time buyers. BIS standards govern electromagnetic compatibility for embedded display modules. Tamil Nadu and Haryana manufacturing corridors host assembly operations where tier-one suppliers adapt smartphone-mirror-centric architectures for cost-sensitive segments.
Global Car Digital Cockpit Market Vendor Landscape
Strategic partnerships dominate the current landscape as tier-one suppliers align with display manufacturers to secure allocation of advanced panel technologies. The vendor base organizes into three tiers: integrated system architects owning full software-hardware stacks, display specialists providing bonded module assemblies, and software vendors supplying hypervisor and HMI middleware. Two archetypes define competitive positioning: European and Japanese conglomerates leveraging captive automotive electronics divisions, and Korean and Taiwanese component specialists controlling critical display and semiconductor supply. Capacity expansion for curved glass substrate processing and cross-licensing agreements for automotive Ethernet connectivity represent the dominant competitive moves.
Among European-based integrated suppliers, Continental AG exemplifies the captive production archetype through bonded display module assembly, while Robert Bosch GmbH anchors the software-intensive tier with human-machine interface development. Visteon Corporation represents the North American specialist model focused on domain controller architectures. These three entities illustrate how competitive positioning fragments across hardware integration, software stack ownership, and system-level consolidation capabilities.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| DENSO Corporation |
| Visteon Corporation |
| HARMAN International |
| Panasonic Holdings Corporation |
| Aptiv PLC |
| Hyundai Mobis |
| Marelli Holdings Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Curved OLED instrument clusters versus commodity LCD central displays bifurcate the market into margin-rich premium programs and high-volume standard installations, with supply chain configurations tracking this split through dedicated bonding lines in Germany and South Korea versus scale-focused panel operations in China and Taiwan.
Pricing Analysis
Volume placements in LCD central displays run at thinner margins than curved OLED instrument clusters, where German and South Korean luxury programs absorb unit cost premiums for form factor differentiation. Price differentiation hinges on thermal management certification grades and software stack complexity, with ASIL-B rated graphics pipelines commanding substantial premiums. Cost compression in standard LCD tiers intensifies as Chinese EV OEMs consolidate procurement around unified domain architectures. Fleet operators in North America exhibit highest price sensitivity, negotiating cockpit downgrade options to optimize total cost of ownership.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Shanghai, and Detroit orchestrate hub-and-spoke delivery patterns for bonded display modules and domain controller assemblies. Manufacturing concentrates in China, South Korea, and Germany, with Taiwanese foundries anchoring supply of advanced driver ICs and timing controllers. The ecosystem draws from glass substrate processing, automotive-grade semiconductor fabrication, and bonded module assembly as critical inputs. Single-source vulnerability in Taiwanese and South Korean foundry capacity exposes OEMs to geopolitical disruption. Distribution runs through tier-one supplier direct-ship programs to OEM assembly plants, with aftermarket channels serving legacy platform retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The car digital cockpit market has become a vertical-integration race, with tier-one suppliers pursuing captive production of bonded display modules to defend margin structures against display manufacturer forward-integration.
For Market Incumbents: Hedge against semiconductor supply concentration by diversifying foundry relationships across Taiwanese and South Korean sources while securing long-term allocation agreements for advanced driver ICs. Deepen captive bonding line capacity in European engineering clusters to maintain cost leadership against Korean display specialists expanding into system integration. Software stack ownership represents the critical defensive moat as proprietary hypervisor implementations create switching costs for OEM customers. For New Entrants and Emerging Players: MicroLED pre-commercial partnerships offer technology-first wedge positioning ahead of 2028-2030 luxury program ramps, bypassing incumbent OLED supply relationships. Target India's compact SUV segment with smartphone-mirror-centric architectures at sub-premium price points, where Maruti Suzuki and Hyundai Motor India pilot simplified configurations for first-time buyers. Pursue direct OEM relationships rather than tier-one supplier channels to capture domain controller integration opportunities. For Investors and Strategic Acquirers: Re-rating potential sits with integrated domain controller specialists given the shift from distributed ECUs to unified architectures merging instrument cluster and infotainment functions. Long-term viability favors vendors owning both hardware integration capabilities and software stack assets across the ownership cycle. Monitor over-the-air update revenue attachment rates as the inflection indicator for persistent connectivity monetization.| Strategic Initiative | Industry Significance |
|---|---|
| Curved Glass Bonding Capacity Expansion | Captive production lines in Stuttgart and Ingolstadt secure allocation for German premium programs eliminating mechanical bezels. |
| Automotive Ethernet Backbone Integration | 1000BASE-T1 standard adoption enables real-time ADAS data fusion with reduced wiring harness complexity across vehicle platforms. |
| Domain Controller Architecture Consolidation | Unified systems merging instrument cluster and infotainment functions reduce ECU count and software fragmentation for OEMs. |
| Over-the-Air Update Platform Development | Persistent connectivity transforms cockpit systems into subscription endpoints for navigation and voice assistant feature unlocks. |
| MicroLED Pre-Commercial Partnerships | Early volume allocation agreements with German luxury OEMs position suppliers ahead of mass-market cost curve convergence. |
Methodological Framework
Multi-period observation of display technology adoption curves, regulatory mandate implementation timelines, and tier-one supplier capacity announcements anchored the trend analysis, supplemented by interviews with OEM platform engineers, tier-one supplier procurement leads, automotive UX specialists, and semiconductor distribution channel managers. Secondary validation drew from vehicle production databases, IHS Markit registration data, NHTSA and Euro NCAP protocol documentation, and SEC filings of publicly traded automotive electronics suppliers. Bottom-up volume modeling triangulated against top-down OEM spending forecasts to reconcile segment-level projections.
Segment-weighting approaches applied differential growth assumptions across display technologies, vehicle classes, and regional regulatory clusters throughout the projection horizon. The analytical framework modeled propulsion architecture splits, content per vehicle trajectories, and OEM tier positioning as core segmentation dimensions. CAGRs derived from fitted growth curves calibrated to historical adoption patterns for comparable automotive electronics transitions. Industry-specific inputs included Euro NCAP assessment protocol update schedules and MIIT type approval timelines for driver monitoring systems.
Forecast precision tightens around the base case; tail outcomes carry wider variance under scenarios of accelerated semiconductor supply disruption or divergent regional software content regulations. Outputs reflect documented assumptions regarding EV platform refresh cycles and regulatory mandate enforcement timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Global 5G in Automotives Market
Telematics and Infotainment
Boat and Ship Telematics Market
Telematics and Infotainment
Europe Vehicle Remote Diagnostic Market
Telematics and Infotainment
Automotive Wi-Fi Router Market
Telematics and Infotainment
Japan Commercial Telematics Market
Telematics and Infotainment
Internet of Cars Market
Telematics and Infotainment
Telematics and Connectivity Control Unit Systems Market
Telematics and Infotainment
Europe Automotive Telematics Market
Telematics and Infotainment
5G V2X Communications Market
Telematics and Infotainment
Video Telematics Market
Telematics and Infotainment
Vehicle Trip Computers Market
Telematics and Infotainment
North America Automotive Navigation System Market
Telematics and Infotainment
Consumer Telematics Market
Telematics and Infotainment
Commercial Vehicle Telematics Market
Telematics and Infotainment
Automotive OEM Telematics Market
Telematics and Infotainment
India Fleet Management Software Market