
 Automotive Inverter Busbar Laminates Market | 2026-2036
Automotive Inverter Busbar Laminates Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Inverter Busbar Laminates Market Insights
The capital-intensity divergence between thin-film sputtering specialists and conventional press-lamination houses is unwinding competitive hierarchies in inverter busbar supply. Rogers Corporation leverages its ceramic-filled polymer expertise to sustain premium positioning in high-frequency switching applications. Amphenol anchors North American EV platform supply through vertically integrated stamping and plating operations. Mersen competes on graphite-composite thermal management layers that extend operating temperatures beyond standard epoxy systems.
Automotive inverter busbar laminates are multi-layer conductive assemblies comprising copper or aluminum foils interleaved with polyimide, epoxy-glass, or ceramic-filled dielectric substrates, manufactured through sequential hot-press bonding with controlled cure cycles to achieve partial discharge resistance above 3 kV/mm and thermal conductivity targets exceeding 2 W/mK; their primary purpose is to distribute DC-link current between battery packs and traction inverters while minimizing parasitic inductance and electromagnetic interference. Insulated laminates dominate current volume as legacy platform designs persist, though ceramic laminates are capturing margin pools in 800V silicon carbide architectures where thermal cycling resistance proves decisive. Electric vehicles anchor application demand, yet commercial transport segments are accelerating fastest as depot-charged bus and truck fleets standardize on laminated busbar topologies for serviceability.
NHTSA crashworthiness standards for high-voltage isolation and EPA lifecycle emissions rules shape laminate material selection and recyclability design in the US market, while EU REACH restrictions on halogenated flame retardants and the EU Green Deal carbon-border adjustments force substrate chemistry transitions across European supply chains. Stakeholders must monitor how battery-electric platform voltage architectures above 800V redefine dielectric thickness-to-conductivity ratios in next-generation laminate stacks.

Market Dynamics
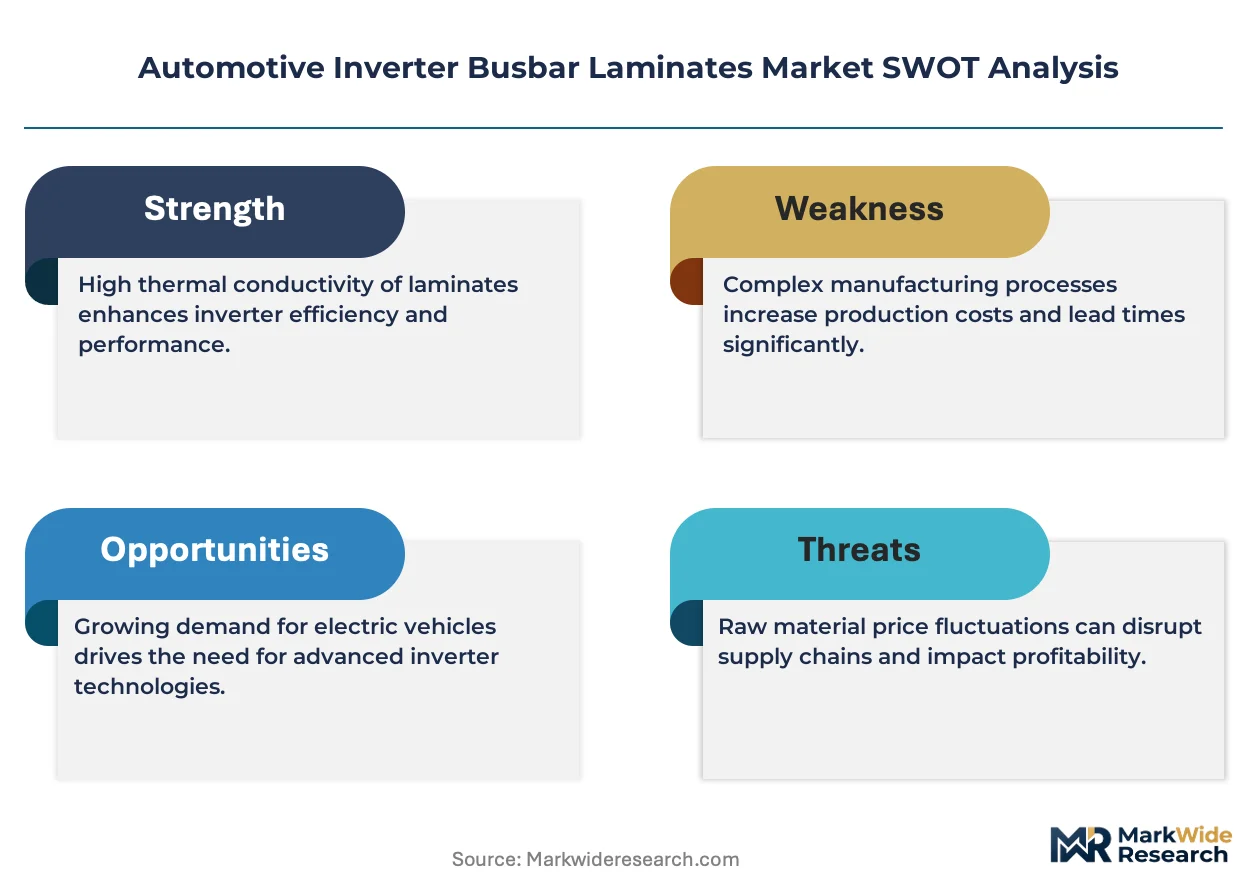
The transition to 800V silicon carbide inverter architectures is compressing dielectric thickness requirements while multiplying thermal cycling loads, forcing laminate suppliers to recalibrate material stacks around ceramic-filled substrates rather than legacy epoxy-glass systems.
Growth Catalysts
- Silicon carbide inverter deployment:Traction inverter OEMs are specifying ceramic-filled laminates capable of withstanding 150°C continuous operation and 10,000+ thermal cycles. This specification pull is accelerating qualification timelines across European EV platforms.
- EU REACH halogen-free mandates:ECHA restrictions on brominated flame retardants in electrical insulation substrates are redirecting R&D spending toward polyimide and mineral-filled alternatives that maintain partial discharge resistance above 3 kV/mm.
- Depot-charged commercial fleet electrification:Battery-electric bus and truck manufacturers in Germany's Stuttgart-Munich corridor are standardizing laminated busbar topologies for modular serviceability, creating pull-through demand for high-volume laminate suppliers.
Market Restraints
- Copper foil supply concentration:Rolled copper thin-gauge supply for 0.1-0.2mm laminate layers concentrates among Japanese and Korean metal processors, exposing laminate houses to tolling queue volatility and forex-driven input cost swings.
- Halogen-free substrate qualification timelines:New dielectric formulations require 18-24 month OEM validation cycles for partial discharge and tracking resistance under IEC 60664, freezing material transitions mid-development.
- Thermal interface material substitution:Direct-bonded copper on ceramic substrates is capturing niche 800V applications above 200kW where laminate bulk becomes a packaging constraint, compressing addressable laminate volume at the power extreme.
Strategic Opportunities
- India PLI scheme for EV components:The government's production-linked incentive scheme for advanced automotive technology is attracting laminate suppliers to establish localized stamping and bonding operations for domestic OEMs and export to Southeast Asian markets.
- Battery-electric off-highway equipment:Mining truck and agricultural machinery electrification is creating demand for laminate assemblies with IP6K9K sealing and vibration resistance beyond passenger vehicle specifications.
- Closed-loop copper recovery:EU Green Deal carbon-border adjustment mechanisms and battery passport requirements are incentivizing laminate designs with separable conductor-dielectric bonds to enable end-of-life material recovery and Scope 3 emissions reduction.
Industry Challenges
- Thin-film sputtering technician scarcity:Ceramic metallization processes for next-generation thermal management layers require vacuum deposition specialists whose training pipelines lag demand expansion by 3-5 years.
- Multi-site ISO 26262 functional safety audits:Automotive laminate suppliers must maintain ASIL-D capable quality systems across stamping, bonding, and plating operations, creating compliance overhead that favors consolidated manufacturing footprints over distributed supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Inverter Busbar Laminates Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $1,461.39 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulated Laminates, Metal Core Laminates, Ceramic Laminates, Organic Laminates Technology: Multilayer Laminate, Single Layer Laminate, Heat Resistant Laminate, High Dielectric Laminate Application: Electric Vehicles, Hybrid Electric Vehicles, Commercial Transport, Light-Duty Vehicles End User: Electric Powertrain Manufacturers, Battery Module Makers, Busbar Assemblers, Tier-1 Electrical Suppliers |
| Companies Covered | Amphenol, Rogers Corporation, Mersen, Methode Electronics, Schneider Electric, ABB, Sun.King Power Electronics Group, Raychem RPG, Storm Power Components, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Inverter Busbar Laminates Market Trends and Innovations
Material science advances and regulatory chemistry mandates are converging to redefine laminate stack architectures, with thermal performance and recyclability now co-equal design constraints alongside electrical isolation.
Ceramic-filled polyimide substrates with alumina or boron nitride loading are supplanting conventional epoxy-glass prepregs in 800V traction inverter applications. Tier-1 suppliers to German and Korean EV platforms have accelerated qualification of these materials since 2023, compressing the market window for legacy laminate houses that lack ceramic compounding expertise or high-temperature press capacity.
EU REACH Annex XVII restrictions on halogenated flame retardants are forcing substrate reformulation across European supply chains. Laminate manufacturers serving Stuttgart-based automotive suppliers are transitioning to phosphorus-nitrogen synergist systems and magnesium hydroxide fillers, accepting modest dielectric constant penalties to maintain regulatory compliance and market access.
Buyer consolidation around platform-specific laminate specifications is compressing supplier qualification cycles and fragmenting procurement across dedicated versus multi-source strategies. Large European EV OEMs are bifurcating their supply bases between captive laminate specialists for high-voltage platforms and merchant suppliers for legacy 400V architectures, with this split most visible in Germany's Baden-Württemberg supplier cluster.
Automotive Inverter Busbar Laminates Market Segmentation
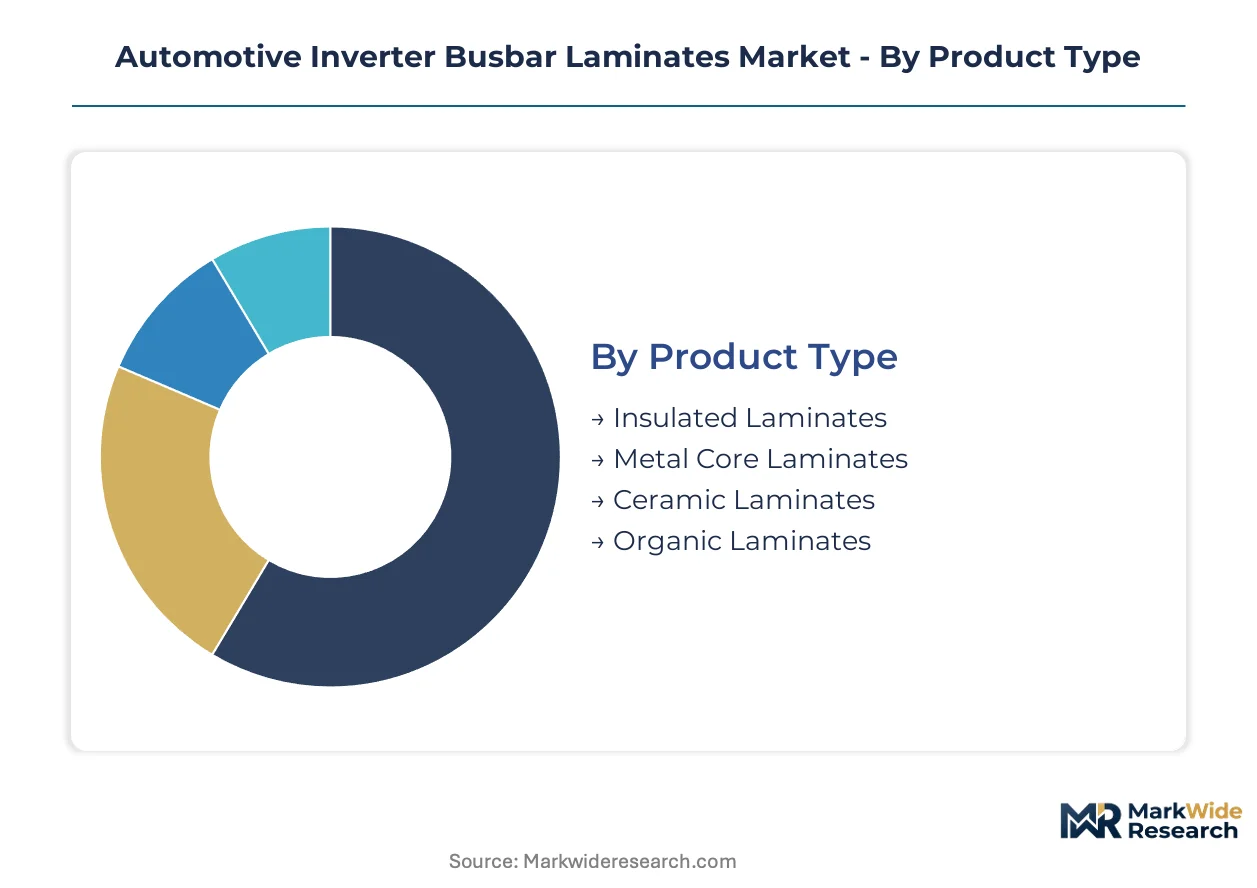
Segmentation in automotive inverter busbar laminates reveals how material chemistry and voltage architecture decisions cascade through procurement tiers. Each dimension exposes different vulnerability to substitution, regulatory pressure, or supply chain restructuring.
Product Type:
Substitution pressure from direct-bonded copper and ceramic substrates intensifies unevenly across laminate categories, with legacy epoxy systems facing the steepest displacement risk.
- Insulated Laminates:Multi-layer copper or aluminum foils bonded with polyimide, epoxy-glass, or ceramic-filled dielectric substrates. Demand concentrates in legacy 400V EV platforms across Germany's Stuttgart-Munich corridor, where OEMs prioritize proven partial discharge resistance over thermal cycling upgrades. ECHA REACH halogen-free mandates are forcing substrate reformulation timelines that freeze procurement commitments.
- Ceramic Laminates:Alumina or boron nitride-filled polyimide substrates engineered for 150°C continuous operation and 10,000+ thermal cycles. Korean and German EV platforms above 800V specify these for silicon carbide inverter integration, with qualification cycles compressing as traction inverter OEMs accelerate SiC deployment.
- Metal Core Laminates:Aluminum or copper base layers with dielectric coating for improved thermal spreading. Battery module makers in depot-charged commercial fleets specify these for serviceability in modular busbar topologies.
- Organic Laminates:Epoxy or phenolic resin systems with glass fiber reinforcement. Tier-1 electrical suppliers retain these for cost-sensitive hybrid electric vehicle applications where voltage isolation requirements remain moderate.
Insulated laminates retain volume leadership; ceramic laminates hold the steepest expansion curve.
Technology:
Cost tier stratification separates qualification-intensive multilayer stacks from single-layer alternatives in aftermarket and repair segments.
- Multilayer Laminate:Sequential hot-press bonding of 3-7 conductive and dielectric layers with controlled cure cycles. Electric powertrain manufacturers in Germany specify these for ASIL-D functional safety compliance, absorbing ISO 26262 audit overhead across stamping, bonding, and plating operations.
- Heat Resistant Laminate:Ceramic-filled substrates rated for continuous operation above 150°C. Battery-electric off-highway equipment OEMs demand these for IP6K9K sealing and vibration resistance beyond passenger vehicle specifications.
- Single Layer Laminate:One conductive layer with surface dielectric coating. Busbar assemblers serving aftermarket repair channels stock these for legacy platform maintenance where full multilayer replacement proves uneconomical.
- High Dielectric Laminate:Engineered for partial discharge resistance above 3 kV/mm in reduced thickness configurations. 800V architectures specify these where packaging constraints demand thinner dielectric layers without isolation degradation.
Multilayer technology commands the premium tier; heat resistant formulations are expanding most quickly into commercial transport electrification.
Application:
Customer type fragmentation splits procurement between captive laminate specialists for high-voltage platforms and merchant suppliers serving legacy architectures.
- Electric Vehicles:Battery-electric passenger cars and light trucks with laminated busbar distribution between battery packs and traction inverters. OEMs in Germany's Baden-Württemberg cluster bifurcate supply bases between dedicated and multi-source strategies for 400V versus 800V platforms.
- Commercial Transport:Depot-charged battery-electric buses and trucks. Manufacturers in Germany standardize on laminated busbar topologies for modular serviceability, creating pull-through demand for high-volume laminate suppliers with localized stamping capacity.
- Hybrid Electric Vehicles:Internal combustion-electric powertrains with lower voltage inverter requirements. Tier-1 electrical suppliers specify organic laminates here where thermal cycling loads remain modest.
- Light-Duty Vehicles:Compact cars and urban delivery vehicles with space-constrained power electronics. Battery module makers prioritize thin-profile insulated laminates for packaging efficiency.
Electric vehicles anchor current procurement volume; commercial transport applications are gaining share fastest as fleet electrification accelerates.
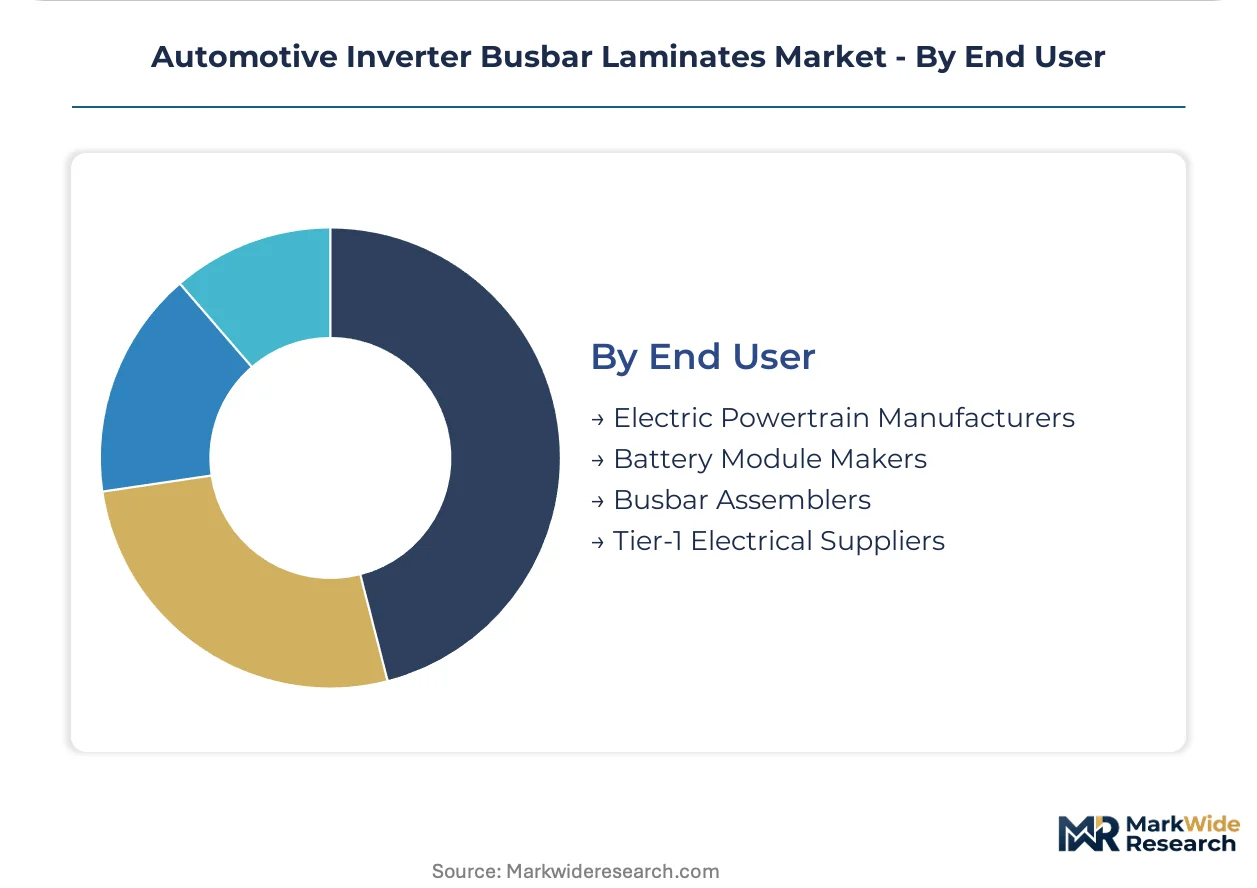
End User:
Supply concentration among Japanese and Korean copper foil processors exposes laminate houses to input cost volatility that reshapes end-user procurement strategies.
- Electric Powertrain Manufacturers:Integrated traction inverter and motor suppliers specifying laminate assemblies for 800V silicon carbide architectures. These stakeholders drive ceramic-filled substrate qualification and compress supplier validation timelines.
- Busbar Assemblers:Specialist integrators combining stamped conductors with dielectric layers for OEM delivery. India's PLI scheme for EV components is attracting these operators to establish localized bonding operations for domestic OEMs and Southeast Asian export.
- Battery Module Makers:Cell-to-pack integrators requiring DC-link current distribution within enclosure constraints. EU Green Deal carbon-border adjustments and battery passport requirements incentivize these stakeholders to specify separable conductor-dielectric bonds for end-of-life recovery.
- Tier-1 Electrical Suppliers:Diversified automotive component houses with in-house laminate production or merchant procurement. These entities maintain ASIL-D capable quality systems across multi-site operations, creating compliance overhead that favors consolidated manufacturing footprints.
Electric powertrain manufacturers dominate specification authority; busbar assemblers are climbing the fastest as regional localization mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in automotive inverter busbar laminates tilt toward net-import positions in European EV manufacturing hubs while Asian copper processors dominate thin-gauge foil supply. Currency volatility and logistics costs are reshaping regional procurement strategies as OEMs localize laminate bonding operations.
United States
NHTSA crashworthiness standards for high-voltage isolation drive laminate specification toward ASIL-D compliant multilayer stacks. EPA lifecycle emissions rules incentivize separable conductor-dielectric designs for end-of-life recovery. Michigan and Ohio-based powertrain manufacturers are absorbing ISO 26262 audit overhead across stamping and bonding operations.
Germany
ECHA REACH restrictions on halogenated flame retardants force substrate chemistry transitions toward phosphorus-nitrogen synergist systems. EU Green Deal carbon-border adjustments elevate Scope 3 emissions tracking in procurement decisions. Stuttgart-Munich corridor suppliers concentrate ceramic-filled laminate qualification for 800V silicon carbide platforms.
China
MIIT dual carbon goals accelerate domestic laminate capacity for battery-electric commercial fleets. GB standards for electrical insulation substrates tighten partial discharge resistance requirements. Yangtze River Delta fabricators scale ceramic metallization processes for traction inverter OEMs.
India
PLI scheme production-linked incentives attract laminate suppliers to establish localized stamping and bonding operations. BIS certification requirements for automotive electrical components extend qualification timelines. Tamil Nadu and Maharashtra-based busbar assemblers target Southeast Asian export markets.
South Korea
METI-aligned technology roadmaps for next-generation EV platforms specify ceramic-filled substrates rated for 10,000+ thermal cycles. Domestic rolled copper supply concentrates among specialized metal processors. Seoul Capital Area powertrain manufacturers compress supplier validation timelines for 800V architectures.
Automotive Inverter Busbar Laminates Market Competitive Landscape
Concentration sits with vertically integrated electrical component houses and specialized laminate fabricators rather than diversified materials conglomerates. The vendor base stratifies across three tiers: captive laminate specialists serving single OEM platforms, merchant suppliers with multi-customer qualification, and regional stamp-and-bond operators. Two strategic archetypes dominate—ceramic-filled substrate compounders leveraging thermal performance premiums, and high-volume copper processors optimizing tolling economics. Competitive moves center on backward integration into thin-gauge foil supply and geographic expansion toward PLI-subsidized manufacturing zones.
Among North American electrical component houses, Amphenol anchors integrated stamping and plating capabilities, while Rogers Corporation exemplifies ceramic-filled polymer expertise for high-frequency switching applications. Mersen occupies a position bridging thermal management specialization with laminate fabrication. These three represent distinct competitive vectors: vertical process control, materials science premiumization, and thermal-mechanical integration.
| Leading Market Players |
|---|
| Amphenol |
| Rogers Corporation |
| Mersen |
| Methode Electronics |
| Schneider Electric |
| ABB |
| Sun.King Power Electronics Group |
| Raychem RPG |
| Storm Power Components |
| Others |
Pricing and Supply Chain Analysis
Thin-gauge copper foil capacity utilization above 85% across Japanese and Korean metal processors is compressing laminate house margins while elevating price floors for ceramic-filled substrate stacks. This scale concentration simultaneously restricts supply alternatives and hardens input cost pass-through to German and Korean EV platform procurement teams.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing across 400V legacy platforms, while 800V silicon carbide architectures command premium-mid-economy pricing differentiation based on thermal cycling certification grade and ceramic filler loading. Price differentiation hinges on ISO 26262 ASIL-D compliance tier and volume scale commitments above 50,000 units annually. Cost compression in standard epoxy-glass laminates is intensifying because tolling queue volatility at Japanese copper processors extends lead times and inflates spot premiums. Fleet procurement teams at depot-charged commercial operators exhibit highest price sensitivity, whereas captive powertrain divisions of Stuttgart-based OEMs absorb premium ceramic laminate costs without volume negotiation.
Supply Chain Analysis
Inventory buffers at 6-8 weeks across European laminate bonding houses mask vulnerability to rolled copper supply concentration in Japan, South Korea, and Taiwan. Raw material dependencies center on 0.1-0.2mm electrolytic copper foil, ceramic-filled polyimide prepreg, and phosphorus-nitrogen flame retardant chemistry. Single-source vulnerability at specialized Japanese foil processors exposes laminate houses to forex-driven input cost swings and tolling allocation disputes. Distribution runs through Tier-1 electrical suppliers with captive bonding capacity and merchant stamp-and-bond operators serving aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vacuum deposition technician pipelines lag ceramic metallization demand expansion by 3-5 years, creating durable scarcity premiums for laminate houses with in-house sputtering capabilities. This skill gap stratifies competitive position between integrated thermal management specialists and conventional press-lamination operators.
For Market Incumbents: Consolidate backward integration into thin-gauge copper foil supply through tolling partnerships with Korean metal processors or captive rolling mill investments in PLI-subsidized Indian manufacturing zones. Add ceramic compounding capacity in Germany's Baden-Württemberg corridor to defend margin position against direct-bonded copper substitution in 200kW+ traction inverters. Prioritize ISO 26262 multi-site audit consolidation to reduce compliance overhead across distributed stamping and bonding footprints. For New Entrants and Emerging Players: Aftermarket repair channel serviceability gaps in legacy 400V platform maintenance present the most penetrable entry vector, as incumbent laminate houses abandon single-layer laminate production for multilayer stack premiumization. Target India's Tamil Nadu and Maharashtra busbar assembler clusters with localized bonding operations under PLI scheme incentives, exporting to Southeast Asian markets with weaker domestic laminate capacity. Pursue qualification partnerships with battery module makers seeking separable conductor-dielectric designs for EU Green Deal carbon-border compliance. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among ceramic-filled substrate compounders with captive OEM platform qualification and 10,000+ thermal cycle validation libraries. Long-term viability favors vertically integrated operators with simultaneous control over foil supply, high-temperature press capacity, and thermal interface material co-development pipelines. Monitor silicon carbide inverter deployment acceleration at Korean and German traction inverter OEMs as the primary inflection signal for ceramic laminate demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Foil Supply | Tolling partnerships with Japanese and Korean metal processors reduce forex exposure and input cost volatility for laminate houses serving Stuttgart-based OEMs. |
| Ceramic Compounding Capacity Expansion | Alumina and boron nitride loading expertise captures premium positioning in 800V silicon carbide inverter qualification cycles at German EV platforms. |
| PLI-Subsidized Manufacturing Localization | Stamping and bonding operations in Tamil Nadu and Maharashtra unlock domestic Indian OEM supply and Southeast Asian export channels. |
| Closed-Loop Copper Recovery Design | Separable conductor-dielectric bonds satisfy EU Green Deal battery passport requirements and Scope 3 emissions reduction mandates for European battery module makers. |
| Multi-Site ISO 26262 Consolidation | ASIL-D capable quality systems across unified stamping, bonding, and plating footprints reduce audit overhead versus distributed supply chain configurations. |
Research Methodology
Cross-validation between primary interviews with laminate procurement directors at German EV OEMs and secondary validation through customs trade data, SEC filings of listed electrical component houses, and IHS Markit vehicle production databases anchors the qualitative findings. The research program combined structured discussions with Tier-1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and ceramic substrate R&D directors with bottom-up and top-down triangulation across regional production cluster analysis.
Sensitivity analysis around silicon carbide inverter deployment pace, copper foil tolling capacity expansion, and ECHA REACH regulatory enforcement timelines shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product type (insulated, ceramic, metal core, organic), technology tier (multilayer, heat resistant, single layer, high dielectric), application (electric vehicles, commercial transport, hybrid electric, light-duty), and end-user category (electric powertrain manufacturers, busbar assemblers, battery module makers, Tier-1 electrical suppliers). CAGRs derive from installed base growth, content-per-vehicle trajectories, and platform voltage architecture transition curves without year-specific anchoring.
Underlying assumptions cover sustained 800V platform rollout at Korean and German OEMs, stable copper foil supply from Japanese and Korean processors, and ECHA REACH enforcement continuity, with deviation risk concentrated in silicon carbide inverter adoption delays or ceramic substrate qualification timeline extensions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Automotive E-Axle Market
Automotive Electrical & Electronics
Automotive Speed Sensor Market
Automotive Electrical & Electronics
Global Automotive Charge Air Cooler Market
Automotive Electrical & Electronics
Car Satellite Antenna Market
Automotive Electrical & Electronics
Mexico Automotive Electric Actuators Market
Automotive Electrical & Electronics
Argentina Automotive EPS Market
Automotive Electrical & Electronics
Automotive Thermal Management System Market
Automotive Electrical & Electronics
South Korea Automotive Electric Actuators Market
Automotive Electrical & Electronics
Global Automotive Engine Coolant Temperature Sensor Market
Automotive Electrical & Electronics
Automotive Temperature Sensor Market
Automotive Electrical & Electronics
Automotive Emission Sensors Market
Automotive Electrical & Electronics
Brazil Automotive EPS Market
Automotive Electrical & Electronics
Global Automotive Starter and Alternator Market
Automotive Electrical & Electronics
Global Automotive Electrical Distribution System Market
Automotive Electrical & Electronics
Europe Automotive Display Market
Automotive Electrical & Electronics
Automotive EMC Test Equipment Market