
 Europe Automotive Tpms Market | 2026-2036
Europe Automotive Tpms Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Automotive Tpms Market Foresight
UNECE R141 certification is reorganizing supplier eligibility across the Europe Automotive TPMS landscape. Continental AG leverages captive sensor manufacturing to dominate OEM supply contracts for direct systems. Huf Hülsbeck & Fürst GmbH & Co. KG anchors its position through valve-integrated sensor design specialization. ZF Friedrichshafen AG competes by extending its chassis electronics portfolio into wireless TPMS modules for commercial vehicle fleets.
Automotive TPMS comprises pressure monitoring sensors, receiver units, and display interfaces that transmit real-time tire inflation data to vehicle control systems, typically operating at 433 MHz in Europe with battery-powered sensors lasting 7-10 years. The primary purpose is preventing blowouts, optimizing fuel consumption, and reducing tire wear across passenger and commercial vehicle platforms. Direct TPMS holds the established revenue base due to regulatory mandates requiring actual pressure measurement, while smart TPMS represents the fastest-expanding margin pool as Bluetooth-enabled sensors integrate with telematics platforms. OEMs concentrate procurement for passenger vehicles, though aftermarket providers are gaining traction as sensor replacement cycles accelerate across aging European fleets.
The EU General Safety Regulation mandates TPMS fitment on all new vehicle types, with ECE R141 establishing performance thresholds that filter non-compliant suppliers from the market. ECHA scrutiny of battery materials in disposable sensors is reshaping design requirements, while CE marking enforcement through national type-approval authorities governs market access. Stakeholders must monitor how the EU Battery Regulation's extended producer responsibility rules will alter sensor replacement economics and aftermarket service models.
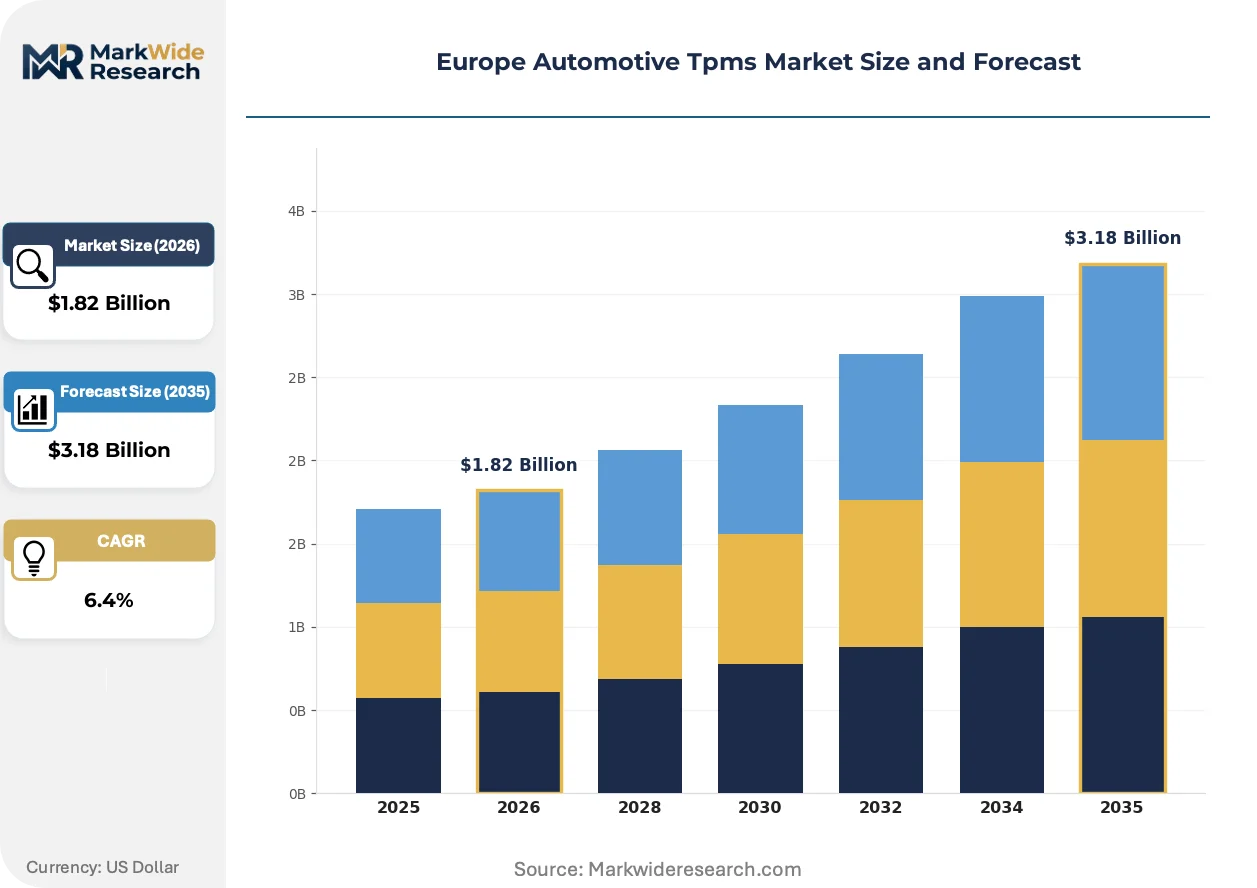
Market Dynamics
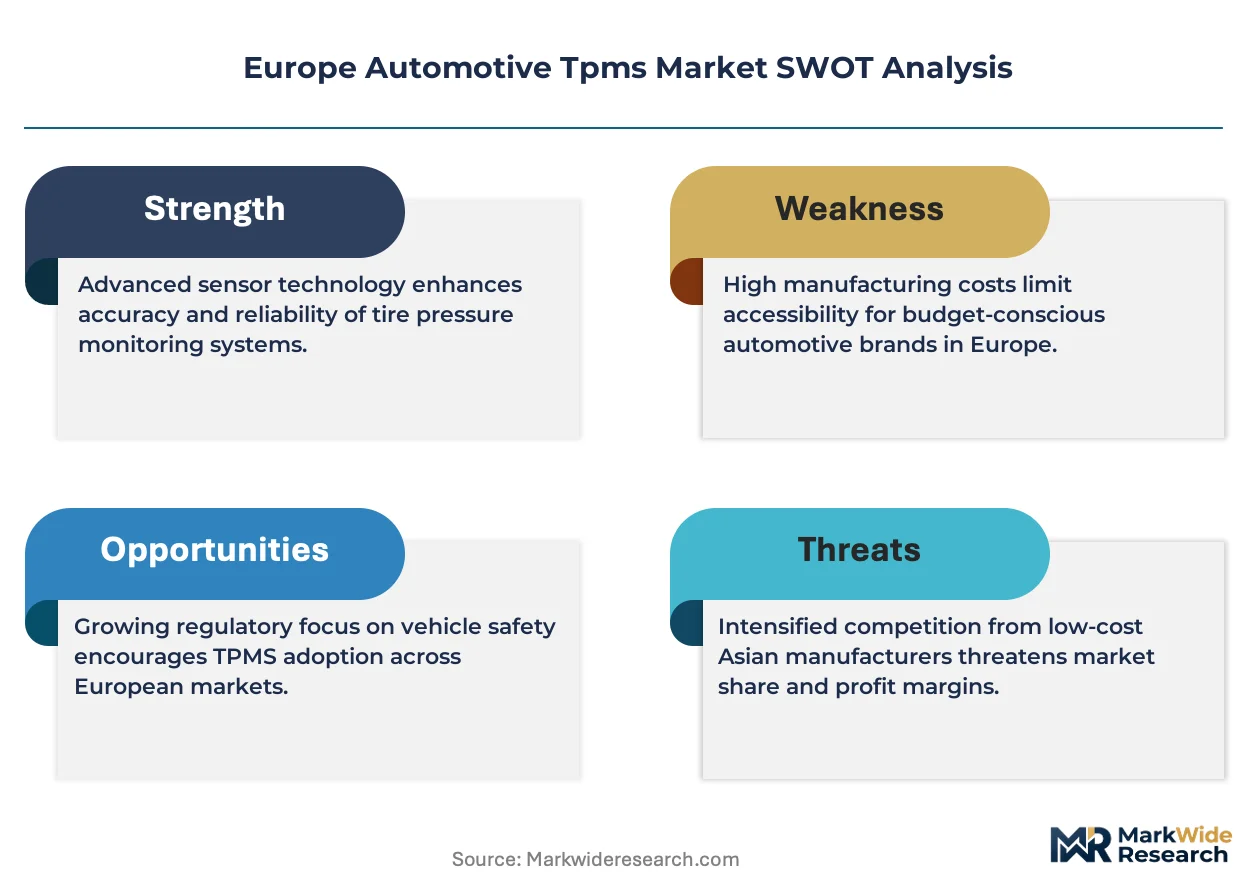
The EU General Safety Regulation and ECE R141 certification are compressing supplier margins while accelerating replacement cycles across Europe's aging vehicle fleet, forcing sensor manufacturers to absorb compliance costs or exit the market entirely.
Growth Catalysts
- ECE R141 Mandate:The regulation requires actual pressure measurement rather than indirect estimation, locking in demand for direct TPMS sensors across all new passenger and commercial vehicle registrations in EU member states.
- Electric Vehicle Platforms:Germany's premium OEM cluster is specifying high-accuracy TPMS for battery-electric architectures where tire load sensitivity affects range optimization and regenerative braking calibration.
- Aftermarket Replacement Acceleration:Sensor battery depletion in vehicles registered during the 2012-2018 TPMS rollout wave is driving replacement demand through independent service channels in France, Italy, and Spain.
Market Restraints
- Lithium Battery Cost Volatility:ECHA scrutiny of cell materials in disposable sensors is forcing redesigns that raise unit economics while supply chain concentration in East Asian cell manufacturers creates input price instability.
- Supplier Consolidation Risk:Continental AG's captive sensor manufacturing and valve-integrated design patents concentrate OEM supply contracts, limiting viable alternative sourcing for mid-tier manufacturers.
- Indirect TPMS Substitution:Wheel speed sensor-based estimation systems, though non-compliant for new type approvals, persist in budget vehicle segments and create pricing pressure on direct system margins.
Strategic Opportunities
- Bluetooth-Enabled Smart TPMS:Wireless protocol convergence with telematics platforms opens fleet management integration for commercial vehicle operators seeking real-time tire analytics.
- Poland and Czech Republic Manufacturing:Central European automotive clusters offer labor cost arbitrage for sensor assembly operations serving German OEM supply chains.
- EU Battery Regulation Tailwind:Extended producer responsibility rules will advantage service providers capable of closed-loop sensor collection and material recovery, reshaping aftermarket economics.
Industry Challenges
- RF Engineering Talent Scarcity:433 MHz antenna design and low-power wireless protocol optimization require specialized skills concentrated in Germany's automotive electronics corridor, constraining R&D scaling.
- UNECE Type-Approval Timelines:Certification bottlenecks at national approval authorities in Italy and Spain delay product launches and compress commercialization windows for new sensor variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Automotive Tpms Market |
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $3.18 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Direct TPMS, Indirect TPMS, Hybrid TPMS, Smart TPMS Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Heavy Trucks End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Fleet Managers Technology: Wireless Sensor, Bluetooth, RFID, GPS |
| Companies Covered | Continental AG, Huf Hülsbeck & Fürst GmbH & Co. KG, ZF Friedrichshafen AG, Schrader Electronics, Dunlop Tech GmbH, Delphi Automotive LLP, ALLIGATOR Ventilfabrik GmbH, HELLA GmbH & Co. KGaA, NIRA Dynamics AB, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Automotive Tpms Market Shifts & Advancements
Sensor architecture is converging with vehicle telematics infrastructure, while regulatory pressure on battery materials and wireless interoperability standards is rewriting design priorities across the supplier base.
MEMS pressure sensing elements are miniaturizing to sub-5mm die sizes while maintaining the 0.1 bar accuracy threshold demanded by electric vehicle thermal management systems. German premium OEMs are specifying these compact sensors for integrated wheel module designs that combine pressure, temperature, and acceleration measurement. The form factor reduction is miniaturizing valve-integrated assemblies and enabling retrofit applications previously inaccessible to direct TPMS technology.
REACH compliance enforcement through ECHA is restricting heavy metal content in sensor batteries and printed circuit board substrates, forcing suppliers to qualify alternative chemistries and surface finishes. The regulatory burden falls disproportionately on aftermarket providers lacking the testing infrastructure of tier-one OEM suppliers. Component manufacturers are responding by consolidating certification programs and sharing toxicology data through industry consortia to defray compliance costs.
Fleet operators are unbundling tire service contracts from vehicle lease agreements and specifying outcome-based performance metrics tied to pressure maintenance compliance. This procurement evolution favors TPMS providers capable of integrating cloud analytics platforms with existing fleet management software. The shift is most visible in Germany's long-haul logistics corridor, where commercial vehicle lessors are mandating real-time pressure monitoring as a condition of extended warranty coverage.
Europe Automotive Tpms Market Segmentation
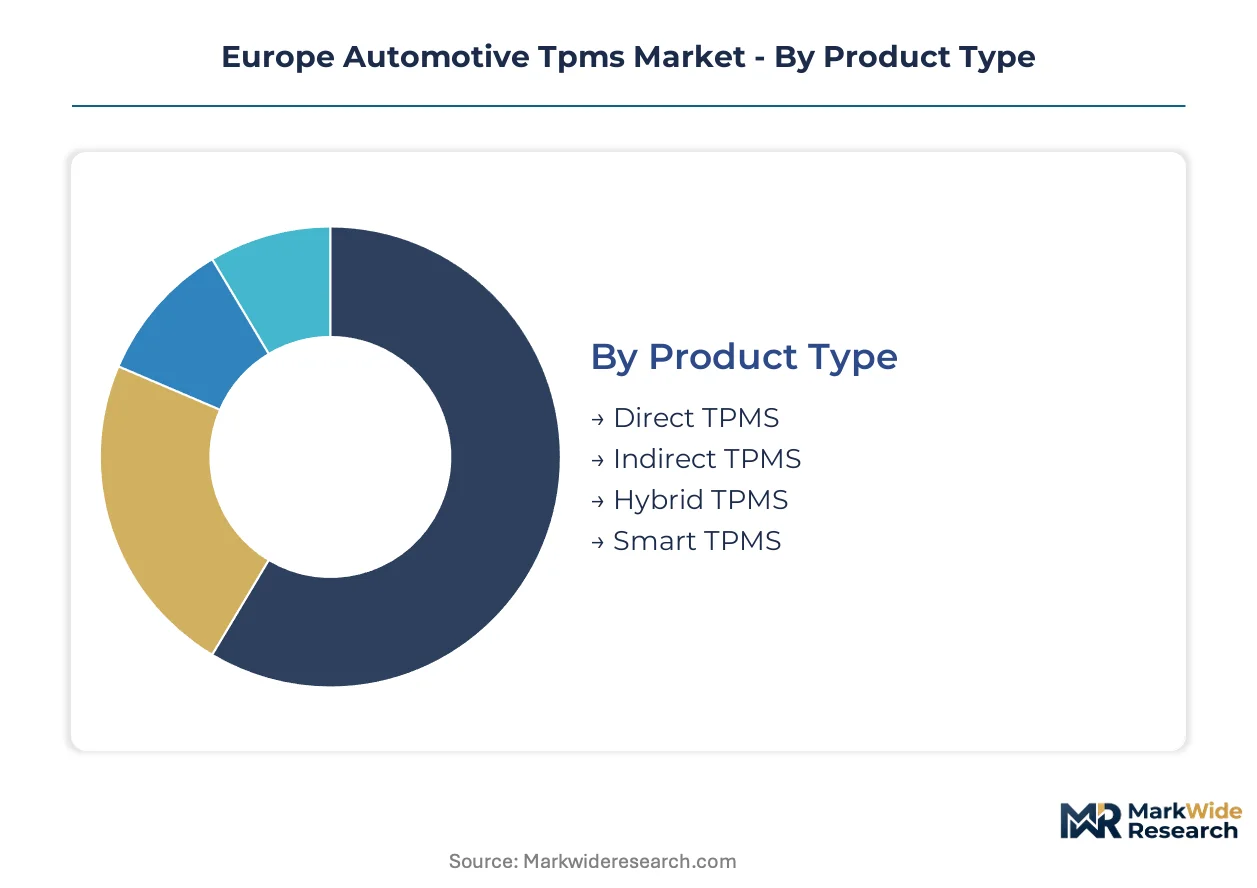
TPMS segmentation in Europe reflects the tension between ECE R141 compliance mandates and emerging connectivity protocols. Suppliers must navigate distinct certification requirements, battery chemistry constraints, and integration complexity across vehicle platforms.
Product Type:
ECE R141 mandates actual pressure measurement, creating regulatory differentiation between compliant and non-compliant architectures across EU member states.
- Direct TPMS:Pressure sensors mounted inside each wheel transmit real-time inflation data via 433 MHz radio signals to a central receiver. German premium OEMs specify these systems for electric vehicle platforms where thermal management demands 0.1 bar accuracy thresholds.
- Smart TPMS:Bluetooth-enabled sensors integrate with vehicle telematics and fleet management platforms, enabling cloud-based analytics and over-the-air diagnostics. Logistics operators in Germany's long-haul corridor are mandating these systems for extended warranty coverage.
- Indirect TPMS:Wheel speed sensor-based estimation algorithms calculate pressure differentials through ABS infrastructure. Budget vehicle segments in Southern Europe retain these systems despite non-compliance with new type approvals.
- Hybrid TPMS:Combines direct wheel sensors with indirect estimation algorithms for redundancy. Commercial vehicle fleets specify these architectures for dual-mode operation across varied load conditions.
Direct TPMS handles the majority of throughput; Smart TPMS is expanding most quickly on share as fleet telematics integration accelerates.
Application:
Vehicle platform specifications diverge sharply between passenger car integration complexity and commercial vehicle duty cycle demands.
- Passenger Vehicles:OEMs concentrate procurement for high-volume platforms with integrated receiver units and dashboard displays. France and Italy show replacement cycle acceleration as 2012-2018 registered vehicles approach sensor battery depletion.
- Commercial Vehicles:Fleet operators unbundle tire service contracts and specify outcome-based pressure maintenance metrics. Long-haul corridors across Germany and Poland drive demand for real-time monitoring with cloud analytics integration.
- Heavy Trucks:Multi-axle configurations require extended sensor networks with reinforced battery housings for high-vibration environments. Central European manufacturing clusters supply these specialized assemblies.
- Two-Wheelers:Motorcycle TPMS adoption lags due to packaging constraints and cost sensitivity, though premium Italian manufacturers are integrating valve-mounted sensors for touring models.
Passenger vehicles anchor volume concentration; commercial vehicles are climbing the fastest as fleet digitization reshapes procurement.
End User:
Supply channel structure varies between captive OEM supply chains and fragmented aftermarket service networks.
- OEMs:Direct procurement contracts with tier-one suppliers dominate premium vehicle platforms. Continental AG's captive manufacturing secures long-term supply agreements with German manufacturers.
- Aftermarket Providers:Independent service channels capture replacement demand as sensor battery lifecycles expire. France, Italy, and Spain show accelerated activity through regional garage networks.
- Fleet Managers:Commercial vehicle lessors specify TPMS as condition of extended warranty coverage. Real-time pressure analytics integrate with existing fleet management software platforms.
- Vehicle Assemblers:Contract manufacturers for niche and specialty vehicles source modular TPMS kits for low-volume production runs.
OEMs control the dominant share of new fitment; aftermarket providers are gaining share fastest as replacement cycles intensify.
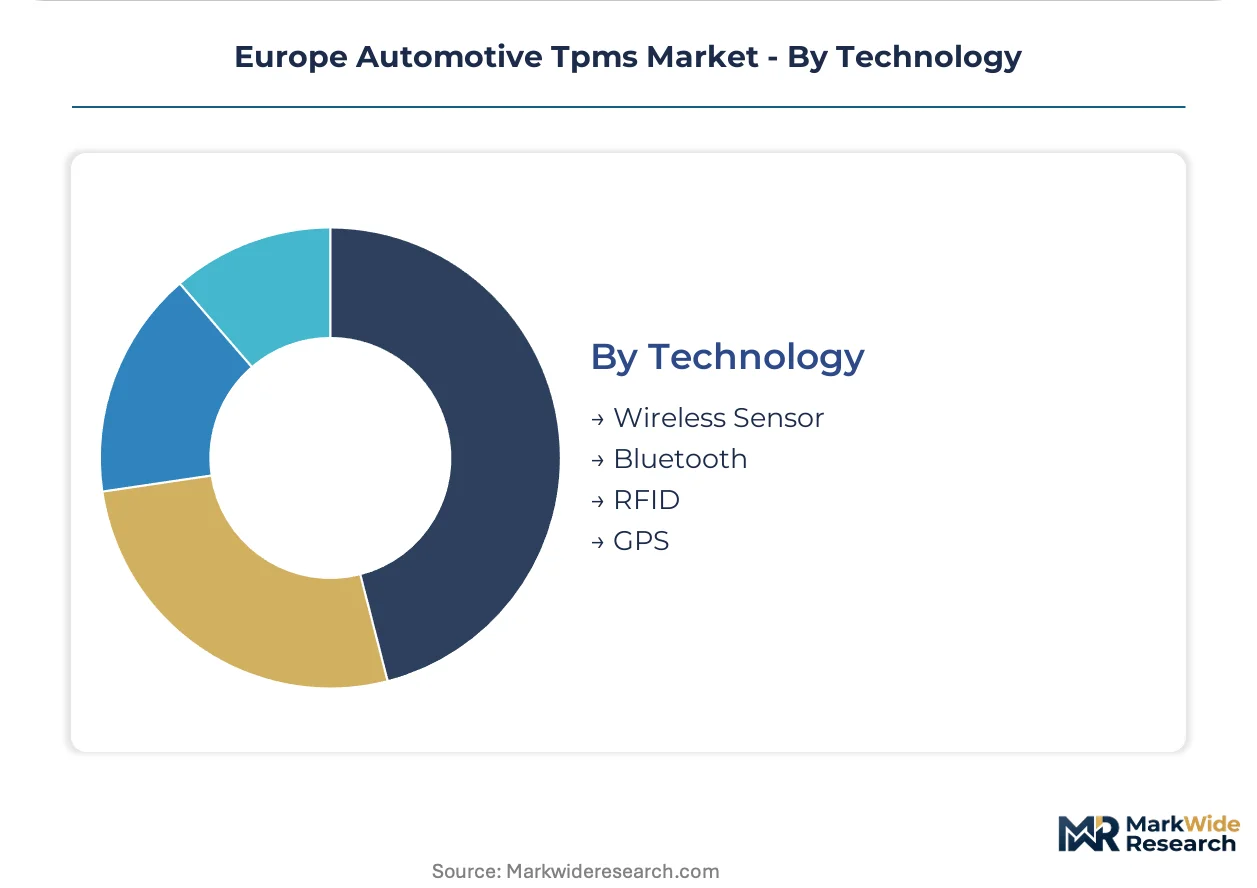
Technology:
Wireless protocol selection determines integration architecture and regulatory compliance pathways.
- Wireless Sensor:433 MHz radio frequency transmission remains the European standard for direct TPMS, with sub-5mm MEMS die miniaturization enabling integrated wheel module designs.
- Bluetooth:Low-energy protocol convergence with smartphone and telematics platforms enables fleet analytics without dedicated receiver hardware.
- RFID:Passive identification tags support logistics tracking and tire lifecycle management through manufacturing and service intervals.
- GPS:Location-aware pressure monitoring supports commercial vehicle routing optimization and geofenced maintenance alerts.
Wireless sensor technology carries the established installed base; Bluetooth is gaining share fastest as protocol standardization advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German fleet operators and premium OEMs anchor procurement concentration across Europe's TPMS demand base. French and Italian aftermarket channels accelerate replacement cycles as 2012-2018 registered vehicles approach sensor battery depletion. Spanish and Polish manufacturing clusters supply component assemblies into German supply chains.
Germany
Premium OEMs specify high-accuracy TPMS for battery-electric architectures where tire load sensitivity affects range optimization. ECE R141 certification filters non-compliant suppliers from OEM supply contracts. The Stuttgart-Munich automotive corridor concentrates direct TPMS integration for electric vehicle platforms.
France
Independent garage networks capture accelerating replacement demand as first-generation TPMS batteries reach end-of-life. REACH compliance enforcement through ECHA restricts heavy metal content in sensor batteries and circuit substrates. The Île-de-France region hosts aftermarket distribution hubs serving national service chains.
Italy
Premium motorcycle manufacturers integrate valve-mounted sensors for touring models despite broader two-wheeler cost sensitivity. CE marking enforcement through national type-approval authorities governs market access for aftermarket providers. Emilia-Romagna's industrial districts supply specialized sensor housings for high-vibration commercial vehicle applications.
Poland
Central European manufacturing clusters offer labor cost arbitrage for sensor assembly operations serving German OEM supply chains. The EU Battery Regulation's extended producer responsibility rules will reshape aftermarket service economics. Silesian automotive electronics facilities expand capacity for MEMS pressure sensing element packaging.
Spain
UNECE type-approval bottlenecks at national approval authorities delay product launches for new sensor variants. ECHA scrutiny of lithium battery materials forces redesigns that raise unit economics for disposable sensors. Catalonia's logistics infrastructure supports distribution to Southern European aftermarket channels.
Europe Automotive Tpms Market Competitive Landscape
Player mix skews toward vertically integrated component manufacturers with captive sensor production. Continental AG's manufacturing depth and Huf Hülsbeck & Fürst's valve-integrated specialization concentrate OEM supply contracts. Three archetypes dominate: integrated automotive electronics conglomerates, valve-system specialists with sensor design capabilities, and chassis technology providers extending into wireless modules. Competitive moves center on backward integration into MEMS fabrication and strategic partnerships with telematics platform providers.
Among German-based conglomerates, Continental AG and ZF Friedrichshafen AG occupy positions defined by manufacturing scale and chassis electronics portfolio breadth. Huf Hülsbeck & Fürst GmbH & Co. KG represents the valve-integrated specialization archetype, anchoring design-led differentiation in direct TPMS architectures. These three entities exemplify how European supplier concentration around ECE R141 compliance has compressed viable sourcing alternatives for mid-tier vehicle manufacturers.
| Leading Market Players |
|---|
| Continental AG |
| Huf Hülsbeck & Fürst GmbH & Co. KG |
| ZF Friedrichshafen AG |
| Schrader Electronics |
| Dunlop Tech GmbH |
| Delphi Automotive LLP |
| ALLIGATOR Ventilfabrik GmbH |
| HELLA GmbH & Co. KGaA |
| NIRA Dynamics AB |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between German OEMs and tier-one sensor manufacturers lock in multi-year supply access while anchoring price visibility against lithium cell cost volatility. These contracts bundle MEMS die supply with valve-integrated assembly services, compressing margin flexibility for mid-tier suppliers competing on spot procurement.
Pricing Analysis
Cost-plus contracts with lithium carbonate indexation dominate direct TPMS procurement between Continental AG and Stuttgart-Munich OEM clusters. Three-tier pricing structure across premium, standard, and economy levels separates ECE R141-certified sensors from aftermarket alternatives and indirect estimation systems. Pricing pressure stems from REACH compliance redesigns forcing alternative battery chemistry qualification. Budget vehicle segments in Southern Europe exhibit highest price sensitivity, while German premium OEMs prioritize accuracy specifications over unit cost.
Supply Chain Analysis
Inventory buffers for 433 MHz RF modules stretch lead times when MEMS foundry capacity tightens in German and Czech automotive electronics corridors. East Asian cell manufacturers anchor lithium battery supply, while Silesian packaging facilities and Stuttgart-Munich sensor design centers complete final assembly. Single-source vulnerability concentrates in East Asian cathode material supply. Distribution runs through captive OEM supply chains for new fitment, with independent garage networks capturing aftermarket replacement cycles across France, Italy, and Spain.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sensor replacement services and cloud-based tire analytics represent service-attach layers expanding faster than hardware unit growth, as fleet operators unbundle maintenance contracts and mandate outcome-based pressure compliance.
For Market Incumbents: Shield OEM supply relationships through backward integration into MEMS fabrication capacity in Czech and Polish manufacturing clusters. Accelerate certification investment for EU Battery Regulation extended producer responsibility compliance before national type-approval bottlenecks tighten. Valve-integrated design patents and captive sensor production remain critical defensive moats against emerging Bluetooth-enabled telematics entrants. For New Entrants and Emerging Players: Cloud analytics integration gaps in commercial fleet management software present white-space targets where incumbent hardware suppliers under-serve data-layer demands. Aftermarket replacement cycles across 2012-2018 registered vehicles in France, Italy, and Spain offer the most penetrable entry geography. Partner with regional garage networks for sensor collection and reverse logistics rather than competing for OEM supply contracts. For Investors and Strategic Acquirers: Capital is best deployed toward valve-system specialists with sensor design capabilities and established ECE R141 certification pathways. Long-term viability hinges on regulatory compliance infrastructure rather than commodity hardware scale. Watch for EU Battery Regulation enforcement timelines as the inflection signal reshaping aftermarket service economics and acquisition premiums for closed-loop collection capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Fabrication Backward Integration | Captive die production secures supply continuity for German OEM long-term offtake contracts. |
| Bluetooth Telematics Platform Partnership | Wireless protocol convergence enables fleet analytics integration beyond hardware sales. |
| Central European Manufacturing Expansion | Czech and Polish assembly operations capture labor cost arbitrage for sensor packaging. |
| EU Battery Regulation Compliance Investment | Extended producer responsibility certification filters non-compliant aftermarket competitors. |
| Cloud Analytics Service Layer Development | Recurring revenue from tire maintenance software outpaces hardware margin compression. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of vehicle production databases, IHS Markit registration data, ECE R141 certification records, and REACH compliance filings. Interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and fleet management operators informed demand-side assumptions. Bottom-up sensor unit estimates triangulated against top-down vehicle production forecasts across passenger and commercial segments.
Segmentation dimensions modeled include product type architecture, vehicle platform application, end-user channel structure, and wireless protocol technology across the analysis window. CAGRs derived from regression analysis of historical fitment rates projected against regulatory mandate timelines and electric vehicle platform penetration. Forecast inputs incorporated ECE R141 compliance thresholds and EU Battery Regulation implementation schedules.
Underlying assumptions cover regulatory enforcement consistency, lithium cell supply continuity, and OEM platform launch timelines, with deviation risk concentrated in national type-approval bottlenecks and REACH alternative chemistry qualification delays. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
New Energy Automotive Antenna Market
Automotive Electrical & Electronics
Automotive Electronics Control Unit Management (ECU/ECM) Market
Automotive Electrical & Electronics
Automotive EMI Shielding Market
Automotive Electrical & Electronics
Global Automotive ECU Market
Automotive Electrical & Electronics
Argentina Automotive EPS Market
Automotive Electrical & Electronics
X-By-Wire Systems Market
Automotive Electrical & Electronics
Automotive Clean Cold Technology Market
Automotive Electrical & Electronics
Mexico Automotive Electric Actuators Market
Automotive Electrical & Electronics
Europe Automotive Steering Sensor Market
Automotive Electrical & Electronics
Germany X by Wire Systems Market
Automotive Electrical & Electronics
Automotive Traction Inverters Market
Automotive Electrical & Electronics
Automotive Alternator and Starter Motor Market
Automotive Electrical & Electronics
Global Automotive Electrical Distribution System Market
Automotive Electrical & Electronics
Automotive Immersion Cooling Dielectric Fluid Market
Automotive Electrical & Electronics
Stepper Motors Market
Automotive Electrical & Electronics
Brazil Automotive EPS Market