
 Automotive Digital Market | 2026-2036
Automotive Digital Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Digital Market Analysis
Germany's electronics manufacturing corridor is narrowing the supply bottleneck for high-resolution display modules and sensor fusion hardware. Robert Bosch GmbH leverages its semiconductor foundry partnerships to secure captive supply of system-on-chip components for digital cockpit architectures. Continental AG anchors European production of AI-driven advanced driver assistance systems through dedicated R&D centers in Saxony. DENSO Corporation extends its sensor calibration expertise into North American assembly plants serving Detroit-based OEM programs.
Automotive digital encompasses embedded electronic systems, software platforms, and connectivity infrastructure that process vehicle data, enable human-machine interfaces, and coordinate distributed computing across powertrain, chassis, and cabin domains. These systems integrate multi-core processors operating at 100+ tera-operations per second, over-the-air update protocols, and real-time operating systems to deliver predictive maintenance, autonomous navigation, and personalized occupant experiences. Telematics and digital cockpit segments lead current revenue contribution due to fleet electrification mandates and consumer expectations for smartphone-integrated cabin environments. Artificial intelligence and machine learning technologies within the technology segment represent the fastest-expanding capability layer, as neural network inference engines migrate from cloud dependency to edge deployment within vehicle electronic control units.
The U.S. NHTSA cybersecurity guidelines and EU GDPR data governance frameworks shape product development timelines by mandating encrypted data pipelines and consent-based telematics collection before market entry. China's MIIT software-defined vehicle standards and GB/T connectivity protocols create parallel compliance tracks for suppliers serving domestic OEMs versus export programs. ISO 26262 functional safety requirements and SAE automation level definitions further segment engineering investment across safety-critical and convenience-oriented digital modules. Stakeholders must evaluate which regulatory convergence pathways between European type-approval and Chinese certification will dominate their platform architecture decisions.
Market Dynamics
The automotive digital market is being fundamentally restructured by the migration of neural network inference from cloud servers to edge-deployed vehicle electronic control units, compressing latency requirements and reshaping silicon procurement patterns across tier-one suppliers.
Growth Catalysts
- Fleet electrification mandates:Corporate fleet operators in Germany and California are mandating zero-emission vehicle transitions that require integrated telematics and battery management digital platforms for range optimization and charging infrastructure coordination.
- EU AI Act compliance frameworks:The European Union's risk-based AI classification system is accelerating investment in certified algorithm development for advanced driver assistance systems, creating captive demand for safety-validated software stacks.
- Sensor fusion hardware advances:Solid-state lidar and 4D imaging radar technologies are enabling higher automation levels by reducing computational overhead for object recognition in adverse weather conditions.
Market Restraints
- Semiconductor foundry concentration:Advanced node production for automotive system-on-chip components remains concentrated in Taiwan, exposing supply continuity risks from geopolitical friction or seismic disruption.
- ISO 26262 functional safety certification:The rigorous ASIL-D validation process for safety-critical digital modules extends development cycles by 18-24 months and requires specialized engineering talent pools that remain geographically constrained.
- Legacy vehicle architecture incompatibility:Existing controller area network bus systems in vehicles produced before 2020 lack the bandwidth to support over-the-air update protocols, limiting retrofit market penetration.
Strategic Opportunities
- India's automotive software corridor:The country's PLI scheme for advanced automotive technology is attracting embedded systems engineering centers serving both domestic OEMs and export programs to Southeast Asian markets.
- Software-defined vehicle subscription revenue:Feature-on-demand business models for autonomous parking and highway assist functions are creating recurring revenue streams independent of initial hardware sales.
- Edge AI and digital twin convergence:The integration of real-time vehicle simulation with predictive maintenance algorithms is opening new service contracts for fleet operators managing electrified commercial vehicles.
Industry Challenges
- Embedded systems cybersecurity expertise scarcity:The shortage of engineers qualified in both automotive functional safety and encrypted data pipeline architecture is constraining product development timelines for connected vehicle platforms.
- Multi-jurisdiction certification complexity:Suppliers must simultaneously satisfy NHTSA cybersecurity guidelines, EU GDPR consent frameworks, and China's MIIT software-defined vehicle standards, fragmenting engineering resources across parallel compliance tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Digital Market |
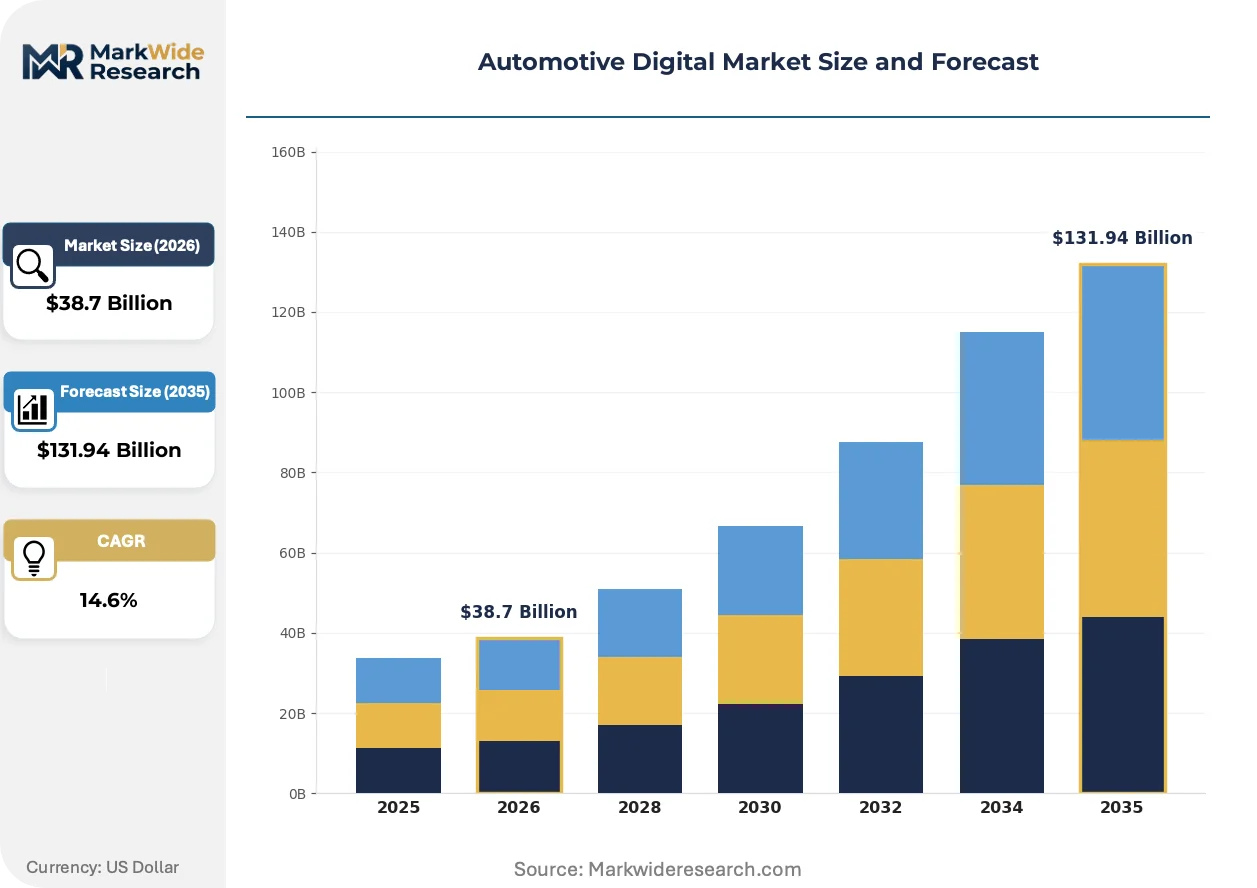
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $131.94 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Telematics, Infotainment Systems, Advanced Driver Assistance Systems, Digital Cockpit Technology: Cloud Computing, Artificial Intelligence, Machine Learning, Blockchain End User: OEMs, Aftermarket Providers, Fleet Operators, Dealerships Application: Navigation, Vehicle Tracking, Remote Diagnostics, Smart Maintenance |
| Companies Covered | Robert Bosch GmbH, Continental AG, DENSO Corporation, Visteon Corporation, Harman International, Aptiv PLC, Valeo SA, Panasonic Holdings Corp., Hyundai Mobis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Digital Market Emerging Trajectories
Automotive digital systems are undergoing architectural transformation as centralized computing domains replace distributed electronic control unit networks, enabling software-defined vehicle capabilities that decouple hardware lifecycles from feature evolution.
Domain-centralized zonal architectures are collapsing the traditional 70-100 ECU topology into 3-5 high-performance computing clusters. German and Japanese OEMs are accelerating this transition for 2026-2028 vehicle platforms, compressing tier-one supplier margins on discrete component sales while expanding software licensing revenue pools. The structural consequence is a wholesale shift in supplier power toward semiconductor and operating system vendors capable of delivering safety-certified integrated stacks.
The EU AI Act's risk-based classification system is mandating conformity assessments for autonomous driving algorithms before European type-approval. This regulatory framework is forcing OEMs to document training data provenance and algorithmic decision boundaries, extending development timelines for SAE Level 3+ systems. The premium passenger vehicle segment is responding by establishing dedicated AI ethics boards and third-party audit partnerships to preempt market access delays.
Fleet procurement patterns are consolidating around integrated mobility service contracts rather than discrete vehicle and telematics purchases. North American logistics operators are bundling vehicle lease, predictive maintenance, and energy management under single-vendor agreements, displacing traditional equipment finance arrangements. This concentration is most visible in California and Texas, where electrified last-mile delivery operators demand guaranteed uptime commitments backed by real-time diagnostic platforms.
Automotive Digital Market Segmentation
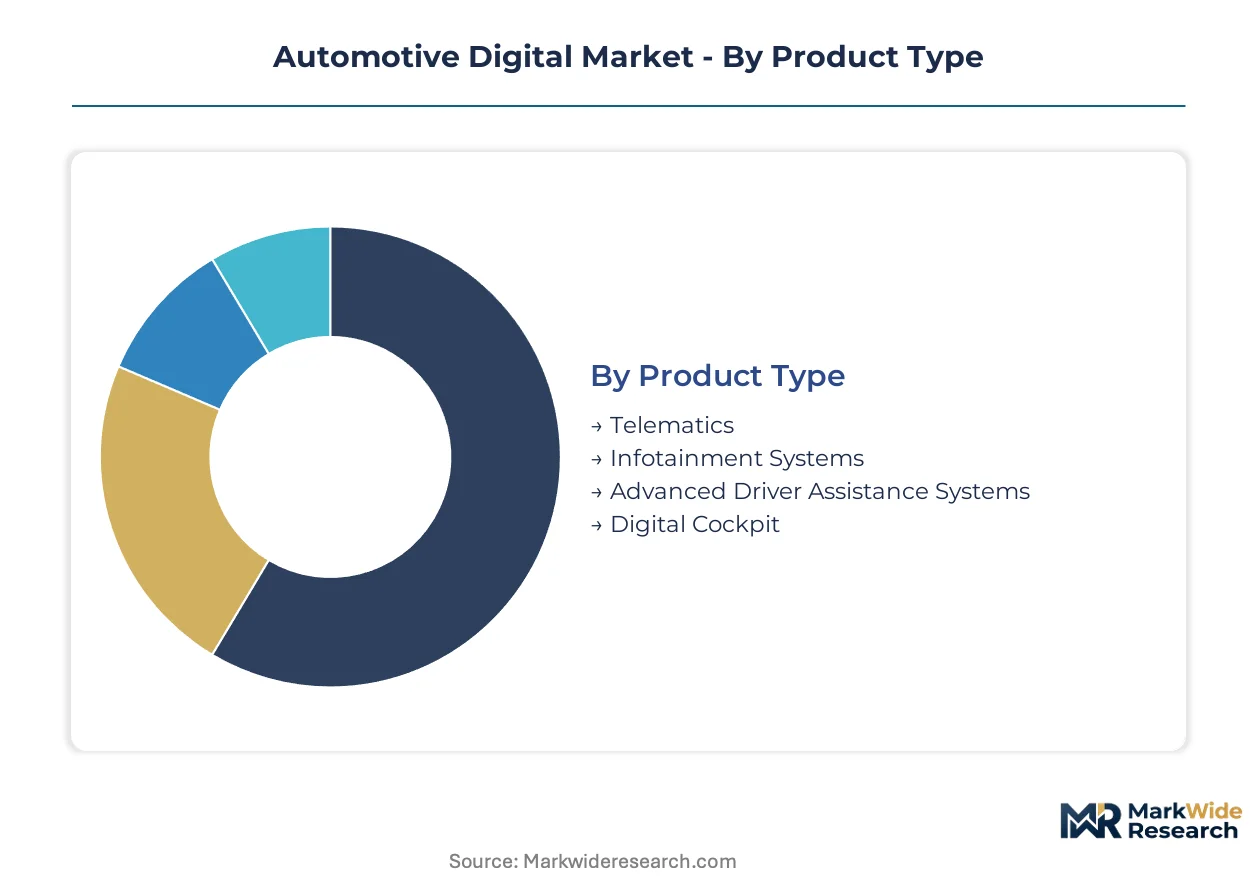
Automotive digital systems fragment across hardware, software, and service layers that demand distinct engineering competencies and recurring revenue models. Suppliers must align portfolio investments with the specific certification requirements and update cadences each segment imposes.
Product Type:
After-sales-service intensity varies dramatically across product categories, with software-heavy systems requiring continuous cloud connectivity and firmware patches while hardware-centric modules demand physical replacement protocols.
- Telematics:Embedded cellular modules transmit vehicle telemetry to fleet management platforms through encrypted 4G/5G protocols. Commercial vehicle operators in Germany and California mandate these systems for regulatory compliance and fuel optimization, creating sticky subscription revenue streams.
- Digital Cockpit:Integrated display clusters combine instrument panels, head-up projection, and passenger entertainment through centralized compute domains. German OEMs consolidate sourcing with tier-one electronics manufacturers to secure high-resolution OLED supply amid semiconductor constraints.
- Infotainment Systems:Human-machine interface platforms running Android Automotive or proprietary operating systems with over-the-air update capability.
- Advanced Driver Assistance Systems:Sensor fusion hardware and neural inference engines enabling adaptive cruise control and lane-keeping functions.
Digital Cockpit holds the largest share; momentum sits with Telematics as fleet electrification accelerates.
Technology:
Cost tier stratification separates capital-intensive infrastructure investments from algorithmic capabilities that scale with data volume.
- Artificial Intelligence:Neural network inference engines process sensor data for object detection and path planning within vehicle electronic control units. EU AI Act conformity assessments now mandate documented training data provenance, extending development timelines for European type-approval.
- Machine Learning:Predictive algorithms optimize battery thermal management and charging schedules based on driving pattern analysis. Edge deployment of these models reduces cloud dependency latency for real-time decision-making.
- Cloud Computing:Distributed data centers handle fleet-scale analytics and over-the-air software distribution.
- Blockchain:Distributed ledger protocols securing vehicle identity verification and supply chain provenance tracking.
Cloud Computing anchors current infrastructure spending; Artificial Intelligence is gaining share fastest as automakers chase SAE Level 3+ automation.
End User:
Volume concentration patterns diverge between production-integrated procurement and post-warranty service channels with divergent margin structures.
- Fleet Operators:Connected logistics and ride-hail companies procure integrated mobility packages bundling vehicles, telematics, and predictive maintenance under long-term contracts. North American last-mile delivery electrification mandates are compressing these procurement cycles.
- OEMs:Vehicle manufacturers specify embedded digital systems during platform development, locking suppliers into multi-year program commitments with stringent ISO 26262 functional safety requirements.
- Aftermarket Providers:Independent installers retrofit connectivity modules and infotainment upgrades to existing vehicle parc.
- Dealerships:Franchised retail networks distribute factory-authorized digital accessories and software subscriptions.
OEMs command the largest share; Fleet Operators are expanding most quickly as mobility-as-a-service models displace discrete vehicle ownership.
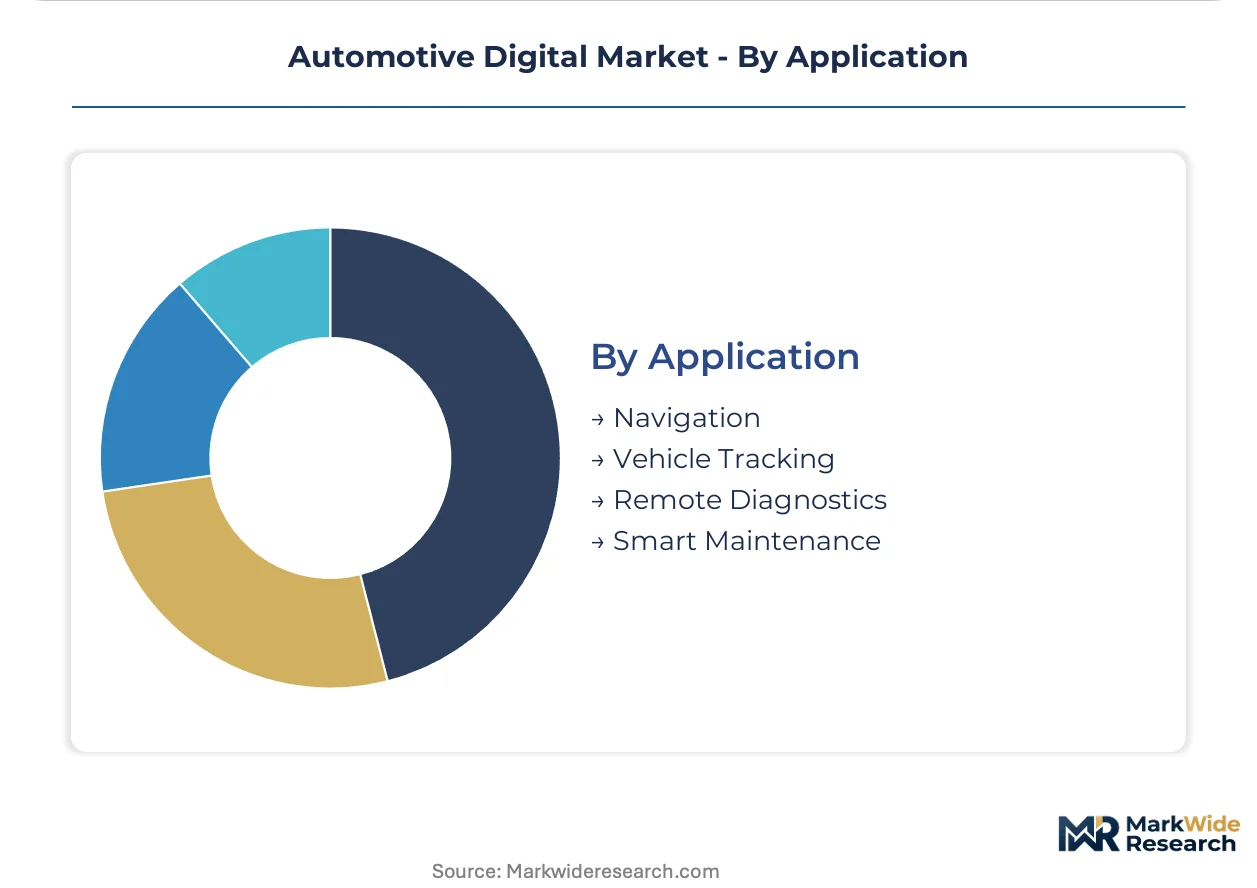
Application:
Maturity gradients separate established navigation services from emerging predictive capabilities that require vehicle-health data accumulation.
- Remote Diagnostics:Real-time fault code analysis and prognostic algorithms anticipate component failures before drivability impact. Commercial fleet uptime guarantees in California and Texas depend on these platforms meeting contractual availability thresholds.
- Smart Maintenance:Condition-based service scheduling integrates vehicle sensor data with parts inventory and technician dispatch systems. Electrified powertrains eliminate oil-change intervals while expanding battery thermal management monitoring requirements.
- Navigation:GPS and high-definition map fusion with traffic prediction and electric vehicle charging station availability.
- Vehicle Tracking:Geofencing and asset recovery systems for fleet security and insurance verification.
Navigation holds the largest share; Smart Maintenance follows the steepest expansion trajectory as electrified commercial vehicle parc accumulates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes automotive digital systems through consolidated OEM procurement of integrated cockpit and ADAS platforms, while the United States absorbs them via fragmented fleet operator subscriptions and California electrification mandates. China deploys the technology through domestic software-defined vehicle standards distinct from export certification tracks. India captures engineering services rather than hardware production.
Germany
Automotive OEMs consolidate digital cockpit sourcing with tier-one electronics manufacturers, creating captive demand for high-resolution display modules. The EU AI Act mandates conformity assessments for autonomous driving algorithms before KBA type-approval. Saxony hosts dedicated R&D centers where Continental AG anchors European production of AI-driven advanced driver assistance systems.
United States
Connected fleet operators across California and Texas expand procurement of telematics and remote diagnostic platforms for electrified last-mile delivery. NHTSA cybersecurity guidelines mandate encrypted data pipelines before market entry. Detroit-based OEM programs draw sensor calibration expertise from DENSO Corporation's North American assembly plants.
China
Domestic OEMs operate under MIIT software-defined vehicle standards and GB/T connectivity protocols that create parallel compliance tracks versus export programs. The country's dual carbon goals accelerate battery management digital platform deployment. Yangtze River Delta clusters concentrate semiconductor foundry partnerships for automotive system-on-chip components.
Japan
Automotive electronics manufacturers leverage METI industrial policy support for edge AI deployment in vehicle electronic control units. JIS standards govern functional safety requirements for neural network inference engines. Kansai and Nagoya industrial corridors maintain legacy tier-one supplier relationships with Detroit and German OEMs.
India
The PLI scheme for advanced automotive technology attracts embedded systems engineering centers serving domestic OEMs and Southeast Asian export programs. TRAI regulations shape telematics data governance frameworks for commercial vehicle operators. Karnataka and Tamil Nadu host software development corridors for predictive maintenance algorithm design.
Automotive Digital Market Vendor Landscape
Capability concentration sits with semiconductor and operating system vendors delivering safety-certified integrated stacks; scale advantage sits with tier-one electronics manufacturers with multi-year OEM program commitments. The market structure favors suppliers with captive foundry partnerships and ISO 26262 ASIL-D certification expertise. Three archetypes dominate: diversified industrial conglomerates with semiconductor divisions, pure-play automotive electronics specialists, and technology licensing platforms. Competitive moves center on strategic partnerships for zonal architecture software stacks and backward integration into system-on-chip design.
Among German-based diversified industrial groups, Robert Bosch GmbH and Continental AG exemplify the conglomerate archetype with foundry partnerships securing captive component supply. Visteon Corporation represents the pure-play automotive electronics specialist tier, occupying a position focused on digital cockpit integration. These three entities anchor the competitive structure by demonstrating how geographic clustering in Germany's electronics manufacturing corridor narrows supply bottlenecks for high-resolution modules and sensor fusion hardware.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| DENSO Corporation |
| Visteon Corporation |
| Harman International |
| Aptiv PLC |
| Valeo SA |
| Panasonic Holdings Corp. |
| Hyundai Mobis |
| Others |
Supply Flow & Price Mechanics
Undercapacity at Taiwan's advanced semiconductor foundries is compressing tier-one supplier margins while amplifying pricing power for captive supply holders. German OEMs now index digital cockpit module contracts to silicon wafer availability, forcing electronics manufacturers to absorb volatility or renegotiate multi-year program terms.
Pricing Analysis
Long-term offtake agreements dominate procurement for automotive system-on-chip components, with OEMs locking capacity 24-36 months ahead of platform launch. Pricing stratifies across ASIL-D safety-certified, ASIL-B intermediate, and non-safety-critical economy tiers based on ISO 26262 validation depth. Cost compression in standard-grade telematics modules is intensifying because Chinese suppliers are flooding the aftermarket with unbundled connectivity hardware. Fleet operators exhibit the highest price sensitivity due to volume procurement mandates, while premium passenger OEMs prioritize supply security over unit cost.
Supply Chain Analysis
Contract manufacturing concentration rests with Taiwan Semiconductor Manufacturing Company, Samsung Foundry, and GlobalFoundries for automotive-grade silicon production. Raw material dependencies span silicon wafers, rare earth elements for sensor magnetics, and high-purity substrates for OLED display modules. Single-source vulnerability in EUV lithography equipment exposes supply continuity to export control restrictions. Distribution runs through tier-one electronics aggregators who consolidate modules from semiconductor vendors before JIT delivery to OEM assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized engineering talent pools for embedded systems cybersecurity remain geographically constrained, creating a persistent bottleneck that rewards early capability acquisition. Suppliers who secure ASIL-D certification expertise and foundry partnerships ahead of program ramps will capture disproportionate share in software-defined vehicle architectures.
For Market Incumbents: Pre-empt margin erosion in discrete component sales by consolidating software licensing revenue through zonal architecture partnerships. Threaten emerging pure-play cockpit integrators by backward integration into system-on-chip design via foundry joint ventures. Prioritize certification investment in EU AI Act conformity assessment capabilities to secure European type-approval gatekeeper status. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-subsidized embedded systems engineering corridor serving Southeast Asian export programs. White-space targets include predictive maintenance algorithm design for electrified commercial fleets and edge AI deployment for tier-two OEMs lacking in-house silicon expertise. Go-to-market angle: position as a compliance-native alternative for suppliers struggling with multi-jurisdiction certification complexity. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across AI-driven advanced driver assistance systems as training data provenance documentation extends development timelines. Long-term viability favors diversified industrial conglomerates with captive semiconductor supply over pure-play hardware specialists. Acquisition target archetype: tier-one electronics manufacturers with ASIL-D certification pipelines and established OEM program relationships. Signal to watch: KBA type-approval delays for SAE Level 3+ systems as an indicator of regulatory capacity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Decouples hardware lifecycles from feature evolution, enabling recurring subscription revenue streams for autonomous functions. |
| Battery Supply Agreement | Secures captive capacity for battery management digital platforms under fleet electrification mandates in California and Germany. |
| Platform Standardization | Reduces ECU proliferation costs while concentrating procurement power with semiconductor vendors delivering integrated stacks. |
| Geographic Manufacturing Footprint | Positions suppliers to satisfy parallel EU AI Act and China MIIT compliance tracks without engineering resource fragmentation. |
| Charging Infrastructure Partnership | Integrates telematics platforms with energy management systems for commercial fleet uptime guarantees in Texas and California. |
Methodological Framework
A standing panel of OEM platform engineers, tier-one supplier procurement directors, aftermarket distribution managers, and dealership operations heads provided ongoing calibration against secondary validation from vehicle production databases, IHS Markit registration data, SEC 10-K filings, and EU type-approval records. Bottom-up segmentation modeling triangulated against top-down market sizing from automotive electronics trade associations.
Scenario-bracketing framed projections across the analysis window, with CAGRs derived from segment-level content-per-vehicle trajectories, OEM platform launch cadences, and fleet electrification mandate compliance schedules. Modeled dimensions spanned hardware-software-service layering, propulsion architecture electrification rates, ASIL safety tier penetration, and regional regulatory cluster convergence patterns.
Stress conditions across semiconductor foundry utilization, EU AI Act enforcement timelines, and China export program certification bifurcation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about zonal architecture adoption curves and neural network edge deployment rates. Quarterly review of KBA type-approval queues and MIIT software-defined vehicle standard updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Steering Wheel Switches Market
Automotive Electrical & Electronics
South Korea Automotive Electric Actuators Market
Automotive Electrical & Electronics
Electric Vehicle Shielded HV Cables Market
Automotive Electrical & Electronics
Stepper Motors Market
Automotive Electrical & Electronics
Automotive Esim Market
Automotive Electrical & Electronics
Nox Automotive Sensors Market
Automotive Electrical & Electronics
Automotive Electronic Expansion Valve Market
Automotive Electrical & Electronics
Global Automotive on Board AC-DC Power Inverters Market
Automotive Electrical & Electronics
Automotive Ecall Market
Automotive Electrical & Electronics
Japan X by Wire Systems Market
Automotive Electrical & Electronics
Wire Harness Market
Automotive Electrical & Electronics
Global Automotive Projector Headlamps Market
Automotive Electrical & Electronics
Automotive EMI Shielding Market
Automotive Electrical & Electronics
Automotive E-Axle Disconnect Actuator Market
Automotive Electrical & Electronics
US Automotive EPS Market
Automotive Electrical & Electronics
Automotive Inverter Busbar Laminates Market