
 Electric Vehicle High-Voltage Cables Market | 2026-2036
Electric Vehicle High-Voltage Cables Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle High-Voltage Cables Market Insights
Multi-source procurement from dedicated cable manufacturers is expanding as EV platforms scale beyond internal harness production capacity. Prysmian Group leverages its submarine cable expertise to anchor high-voltage shielding technology for automotive applications. Sumitomo Electric Industries Ltd. sustains vertical integration from copper smelting to finished harness assemblies, controlling cost structures across the value chain. Leoni AG specializes in flexible routing solutions that navigate the packaging constraints of skateboard battery architectures.
Electric vehicle high-voltage cables are insulated conductive assemblies rated typically between 600V and 1,500V DC, employing cross-linked polyethylene or silicone-based compounds to withstand thermal cycling, abrasion, and electromagnetic interference in powertrain electrification. Their primary purpose is to transmit energy between battery packs, inverters, motors, and charging interfaces while maintaining safety integrity under fault conditions. Battery cables dominate material tonnage as cell-to-pack architectures extend conductor lengths per vehicle. Charging cables command premium positioning due to liquid-cooled conductor designs enabling faster energy transfer rates. Copper conductors maintain share against aluminum alternatives where flexural fatigue resistance and contact reliability outweigh mass reduction priorities.
The EU's CE marking and ECHA REACH frameworks restrict halogenated flame retardants in cable insulation, compelling reformulation toward phosphorus-nitrogen synergists. China's NMPA and GB standards mandate electromagnetic compatibility testing for high-voltage assemblies integrated into passenger vehicles. The US NHTSA and EPA coordinate on wire harness durability requirements under crash and thermal runaway scenarios. Stakeholders must monitor how 800-volt platform proliferation reshapes conductor sizing standards and whether solid-state battery packaging eliminates junction box complexity that currently drives cable count per vehicle.
Market Dynamics
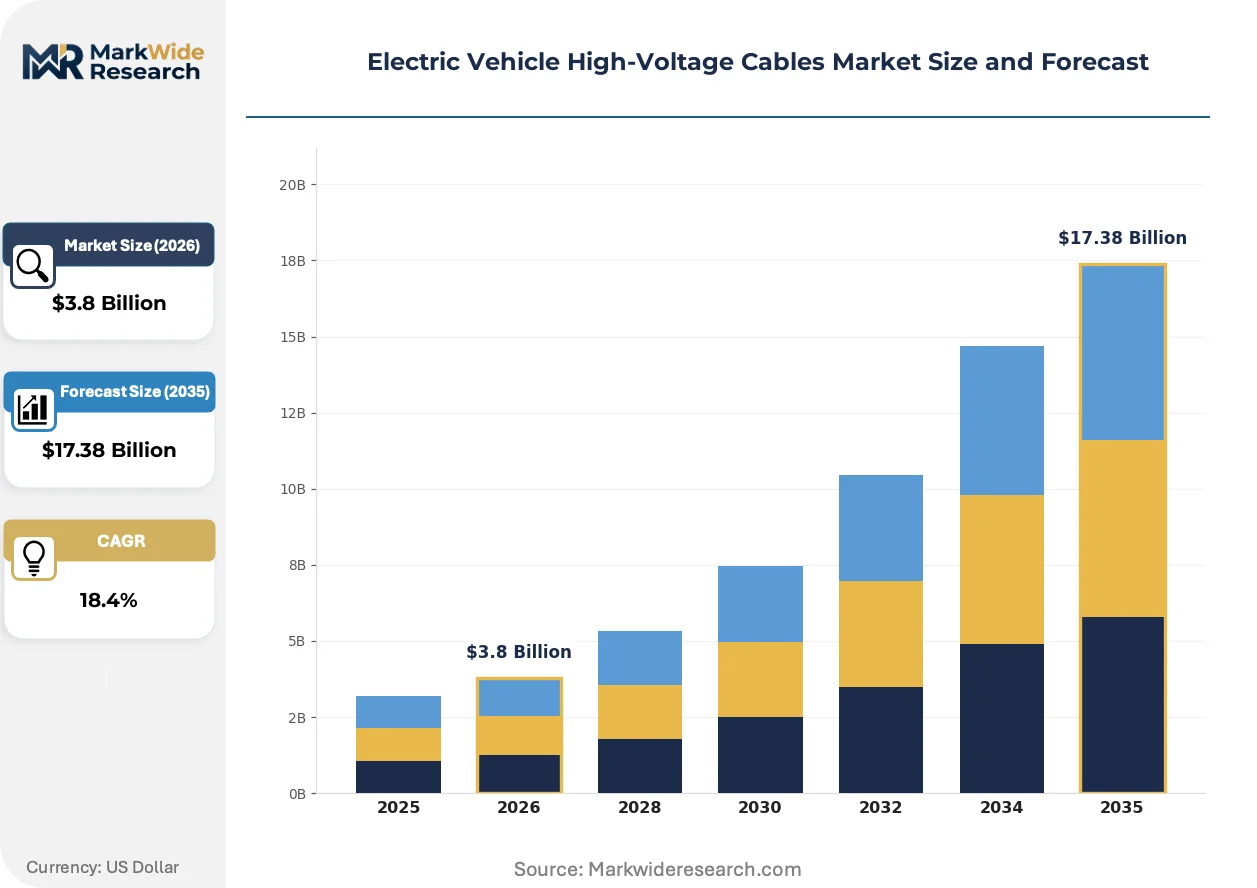
Platform voltage escalation from 400V to 800V architectures is compressing conductor sizing tolerances and amplifying procurement complexity for shielded harness assemblies across battery electric vehicle programs.
Growth Catalysts
- EU F-Gas Regulation:Phase-down mandates for fluorinated greenhouse gases in thermal management systems are accelerating adoption of liquid-cooled cable designs that eliminate refrigerant-dependent cooling loops.
- Cell-to-pack battery architectures:Extended conductor lengths per vehicle are expanding material tonnage requirements for battery-to-inverter connections in skateboard platform designs.
- Germany's automotive supplier corridor:Concentrated demand around Stuttgart and Wolfsburg is anchoring specialized high-voltage cable capacity investments from dedicated harness manufacturers.
Market Restraints
- Copper price volatility:Conductor material cost fluctuations are compressing margin structures for cable assemblers locked into fixed-price OEM supply agreements.
- Electromagnetic compatibility testing:China's GB/T standards mandate extended certification timelines that delay platform launch schedules for 800-volt programs.
- Aluminum conductor substitution:Mass-reduction priorities in commercial vehicle segments are displacing copper in non-flexing powertrain applications where contact reliability constraints relax.
Strategic Opportunities
- India's PLI scheme for automotive:Localized cell manufacturing incentives are creating captive demand for domestic high-voltage cable production serving battery pack assembly operations.
- Solid-state battery packaging:Simplified junction box architectures may reduce cable count per vehicle, but higher operating voltages expand premium shielding requirements per conductor.
- Direct OEM procurement channels:Platform scale is enabling bypass of traditional tier-1 harness suppliers for dedicated cable manufacturer relationships.
Industry Challenges
- High-voltage safety certification:Technician training gaps for 800-volt system handling are constraining field service network expansion for aftermarket cable replacement.
- Cross-platform standardization:Proprietary connector specifications between Hyundai, BYD, and Volkswagen architectures are fragmenting production economies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle High-Voltage Cables Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.38 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Charging Cables, Battery Cables, Connectivity Cables, Control Cables Material: Copper, Aluminum, Thermoplastic, Composite Installation Type: Onboard, Offboard, Indoor, Outdoor End User: OEMs, Fleet Operators, Charging Stations, Aftermarket Providers |
| Companies Covered | Sumitomo Electric Industries Ltd., Prysmian Group, Huber + Suhner, Aptiv, Nexans, Leoni AG, Yazaki Corporation, TE Connectivity, ACOME, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle High-Voltage Cables Market Trends and Innovations
Silicone-based insulation compounds are displacing cross-linked polyethylene in thermally stressed routing zones, while liquid-cooled conductor designs proliferate across fast-charging interface applications. Procurement patterns are compressing supplier qualification cycles as platform launches accelerate.
Silicone elastomer insulation is decentralizing thermal management architecture by enabling continuous operating temperatures above 180°C without auxiliary cooling channels. Battery electric vehicle platforms from South Korean and German OEMs are adopting these compounds for inverter-adjacent routing where heat soak peaks. This material shift is decentralizing thermal design responsibility from vehicle-level cooling systems to component-level material selection.
China's GB/T electromagnetic compatibility standards are mandating shielding effectiveness testing above 100 MHz for all high-voltage assemblies integrated into passenger vehicles. Cable manufacturers must redesign braid geometries and conductive tape wraps to meet radiated emission limits. Battery-to-inverter harnesses face the most stringent compliance timelines, compressing product development cycles for new platform introductions.
Automotive OEMs are consolidating high-voltage cable procurement under direct material contracts rather than tier-1 harness supplier intermediation. Volkswagen and Hyundai Motor Group are establishing dedicated supplier development programs with specialized cable manufacturers for 800-volt platform scale. South Korea's battery manufacturing cluster near Ulsan exhibits the most visible procurement restructuring, with cell producers specifying conductor specifications directly to cable specialists.
Electric Vehicle High-Voltage Cables Market Segmentation
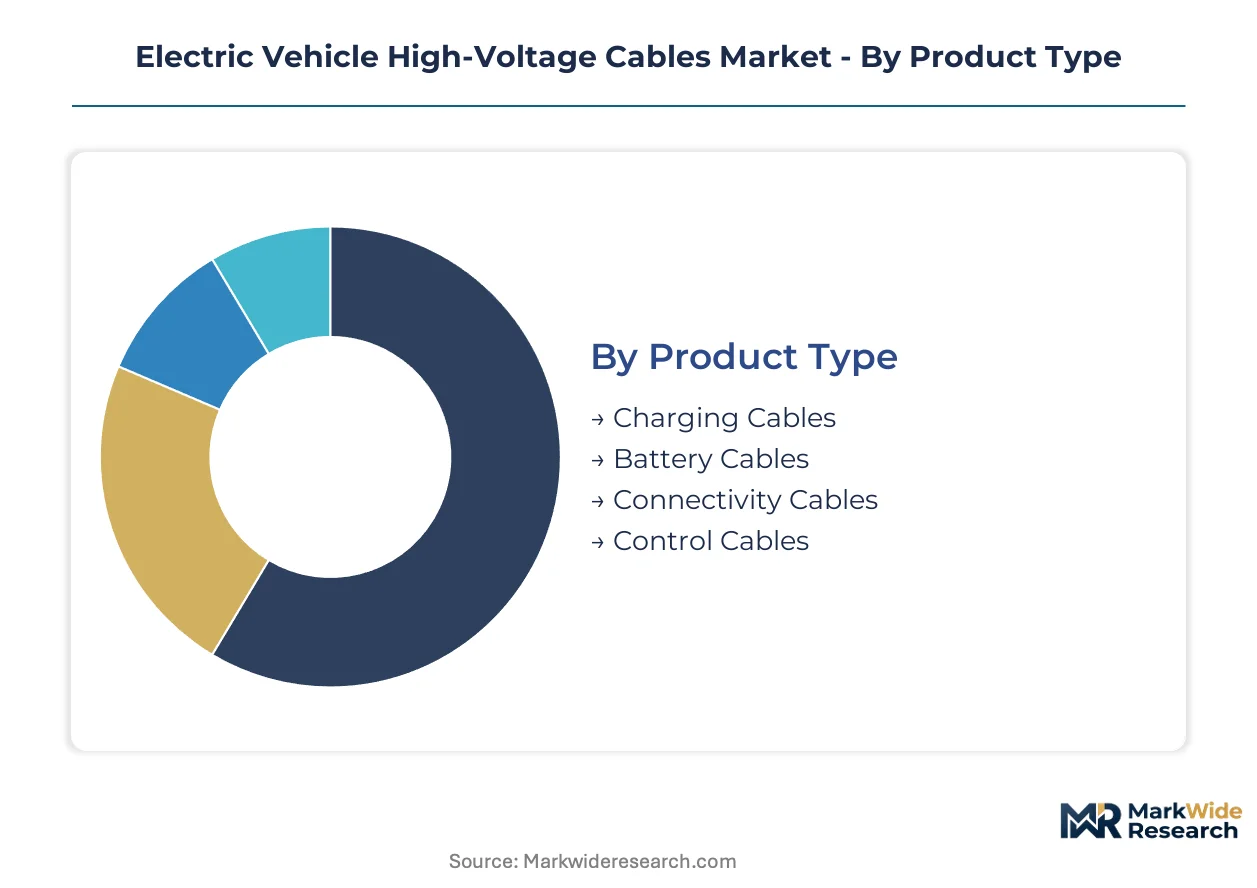
Platform voltage escalation and thermal management complexity are fragmenting procurement specifications across conductor geometries, insulation compounds, and shielding architectures. Segmentation discipline separates volume-driven battery interconnects from premium-positioned charging interfaces with divergent margin structures and certification requirements.
Product Type:
Battery cables dominate tonnage as cell-to-pack architectures extend conductor lengths per vehicle, while charging cables extract premium positioning through liquid-cooled designs enabling faster energy transfer rates.
- Charging Cables:Liquid-cooled conductor assemblies rated for continuous high-current duty cycles at 800-volt charging interfaces. Demand concentrates in Germany's automotive supplier corridor around Stuttgart, where fast-charging infrastructure buildout is compressing supplier qualification timelines for thermal management integration.
- Battery Cables:High-flexibility harnesses connecting cell modules to junction boxes and inverters within skateboard platform architectures. Procurement volumes from South Korea's battery manufacturing cluster near Ulsan are anchoring dedicated capacity investments as Hyundai and cell suppliers specify conductor geometries directly.
- Connectivity Cables:Shielded assemblies for data and power integration between battery management systems and vehicle control modules.
- Control Cables:Low-current signal pathways for safety interlocks and isolation monitoring circuits.
Today's leader: Battery Cables. Tomorrow's challenger: Charging Cables.
Material:
Copper maintains conductor share where flexural fatigue resistance and contact reliability outweigh mass reduction priorities, while aluminum substitution advances in commercial vehicle segments with relaxed cycling requirements.
- Copper:Oxygen-free high-conductivity conductors with tin or silver plating for oxidation resistance in high-temperature routing zones. Germany's KBA type-approval requirements for 800-volt crash safety are reinforcing copper's dominance in passenger vehicle powertrain applications where joint reliability cannot degrade under mechanical stress.
- Aluminum:Lightweight conductors with specialized termination geometries addressing galvanic corrosion and creep relaxation. Fleet operator procurement for electric commercial vehicles in China is accelerating aluminum adoption where reduced cycle life tradeoffs are acceptable against payload optimization.
- Thermoplastic:Halogen-free flame-retardant insulation compounds replacing cross-linked polyethylene in cost-sensitive volume applications.
- Composite:Hybrid conductor-insulation systems combining aluminum cores with copper cladding for intermediate mass-performance positioning.
Copper commands current volume leadership. Aluminum is climbing the fastest as commercial electrification scales.
Installation Type:
Onboard integration faces severe packaging constraints beneath vehicle floors and within thermal enclosures, while offboard installations must withstand environmental exposure without vehicle-level protection systems.
- Onboard:Harnesses routed within battery enclosures, motor compartments, and passenger cabin firewalls. China's GB/T electromagnetic compatibility standards are mandating shielding effectiveness testing above 100 MHz for all onboard assemblies, compressing development cycles for new platform introductions.
- Offboard:Cables connecting charging infrastructure to vehicle inlets with enhanced abrasion and UV resistance. The EU's F-Gas Regulation phase-down for fluorinated greenhouse gases is accelerating liquid-cooled offboard designs that eliminate refrigerant-dependent thermal management loops.
- Indoor:Controlled-environment installations in manufacturing facilities and service centers with reduced IP rating requirements.
- Outdoor:Weather-exposed routing for charging stations and fleet depots requiring enhanced sealing and rodent protection.
Onboard maintains installed base dominance. Offboard offers the steepest expansion trajectory as charging infrastructure deploys.
End User:
OEM procurement is consolidating under direct material contracts bypassing traditional tier-1 harness suppliers, while aftermarket providers face technician training gaps for 800-volt system handling.
- OEMs:Direct platform-scale procurement from specialized cable manufacturers for 800-volt battery electric vehicle programs. Volkswagen and Hyundai Motor Group supplier development programs are restructuring supply relationships in South Korea's Ulsan cluster, with cell producers specifying conductor requirements directly to cable specialists.
- Charging Stations:Infrastructure operators procuring liquid-cooled assemblies for high-power charging hubs. Germany's charging corridor buildout along autobahn networks is concentrating demand for certified assemblies with extended continuous duty ratings.
- Fleet Operators:Commercial vehicle purchasers optimizing total cost of ownership through aluminum conductor adoption and standardized maintenance protocols.
- Aftermarket Providers:Service networks requiring high-voltage safety certification for cable replacement and repair operations.
OEMs anchor current procurement volume. Charging Stations are gaining share fastest as infrastructure investment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive supplier corridor around Stuttgart and Wolfsburg anchors procurement concentration for shielded high-voltage harnesses as 800-volt platforms scale across European battery electric vehicle programs.
China
Cell-to-pack architectures from BYD and CATL are extending conductor lengths per vehicle, amplifying material tonnage demand. The country's GB/T electromagnetic compatibility standards mandate shielding effectiveness testing above 100 MHz for all high-voltage assemblies. Yangtze River Delta manufacturing clusters near Shanghai are consolidating dedicated cable capacity investments to serve domestic OEM procurement.
Germany
Volkswagen's platform-scale procurement is restructuring supply relationships toward direct cable manufacturer contracts. The EU's F-Gas Regulation phase-down is accelerating liquid-cooled designs that eliminate refrigerant-dependent thermal loops. Stuttgart's supplier corridor is anchoring specialized high-voltage capacity from dedicated harness manufacturers serving premium 800-volt programs.
South Korea
Hyundai Motor Group's battery electric vehicle platforms are expanding procurement of shielded harnesses for 800-volt architectures. The country's MFDS coordinates with automotive regulators on wire harness durability requirements under crash scenarios. Ulsan's battery manufacturing cluster is exhibiting visible procurement restructuring as cell producers specify conductor requirements directly to cable specialists.
United States
Domestic OEMs are compressing supplier qualification cycles as platform launches accelerate for next-generation electric powertrains. The US NHTSA coordinates with EPA on wire harness durability requirements under thermal runaway scenarios. Michigan's automotive engineering corridor is concentrating development activity for 800-volt system integration and high-voltage safety certification protocols.
India
The country's PLI scheme for automotive manufacturing is creating captive demand for domestic high-voltage cable production serving battery pack assembly operations. BIS standards are evolving to address electromagnetic compatibility for high-voltage assemblies integrated into passenger vehicles. Tamil Nadu's manufacturing belt is attracting capacity investments as localized cell manufacturing incentives reshape procurement geography.
Electric Vehicle High-Voltage Cables Market Competitive Landscape
Global majors compete with regional champions across shielding technology and thermal management integration, producing a tiered structure where scale-driven cable specialists, diversified industrial conglomerates, and automotive-focused harness manufacturers each occupy distinct competitive positions. Strategic archetypes include submarine cable technology adapters, vertically integrated copper processors, and flexible routing specialists navigating skateboard battery packaging constraints. Dominant competitive moves encompass direct OEM procurement channel development and liquid-cooled conductor design proliferation.
Among Japan-based industrial conglomerates, Sumitomo Electric Industries Ltd. exemplifies backward integration from copper smelting through finished harness assemblies. Prysmian Group, the Italian cable specialist, anchors high-voltage shielding technology adaptation from submarine power transmission expertise. Leoni AG, the German harness manufacturer, occupies a position within flexible routing solutions for constrained battery architectures. These three represent divergent strategic postures on vertical scope, thermal management specialization, and geographic procurement proximity.
| Leading Market Players |
|---|
| Sumitomo Electric Industries Ltd. |
| Prysmian Group |
| Huber + Suhner |
| Aptiv |
| Nexans |
| Leoni AG |
| Yazaki Corporation |
| TE Connectivity |
| ACOME |
| Others |
Pricing and Supply Chain Analysis
London Metal Exchange copper futures pricing cascades through conductor procurement tiers, compressing margin structures for cable assemblers locked into fixed-price OEM supply agreements while amplifying cost pass-through volatility across shielding and insulation compound layers.
Pricing Analysis
Input-cost pass-through from copper smelter premiums to finished harness assemblies operates on contract-based long-term offtake structures with quarterly adjustment clauses. Price differentiation separates liquid-cooled charging cable tiers from standard battery interconnects based on thermal management certification grade and continuous duty ratings. Cost compression in economy-tier aluminum conductor segments is intensifying because fleet operator procurement teams are standardizing specifications across commercial vehicle programs. Aftermarket service providers exhibit the highest price sensitivity due to technician training overhead, while premium 800-volt platform OEMs prioritize shielding performance over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from Volkswagen and Hyundai Motor Group procurement teams mandate multi-supplier qualification for shielded harness assemblies across 800-volt platform programs. Geographic supply concentration centers on Germany's Stuttgart supplier corridor, South Korea's Ulsan battery manufacturing cluster, and China's Yangtze River Delta cable production zones. Raw material dependencies draw from Chilean copper cathode, Japanese silicone elastomer compounds, and German conductive tape metallization. Single-source vulnerability in liquid-cooled conductor termination technology creates chokepoint exposure for fast-charging cable tiers. Distribution runs through direct OEM material contracts that bypass traditional tier-1 harness supplier intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric vehicle high-voltage cables constitute a late-cycle quality story as 800-volt platform proliferation shifts procurement specifications toward premium shielding and thermal management tiers that command sustainable margin structures.
For Market Incumbents: To counter aluminum substitution in commercial vehicle segments, Prysmian Group and Sumitomo Electric Industries Ltd. should anchor backward integration into copper smelting and conductive compound formulation to defend cost structures against commodity volatility. Certification investment in China's GB/T electromagnetic compatibility testing protocols creates channel control leverage for battery-to-inverter harness programs. For New Entrants and Emerging Players: Aftermarket service networks for 800-volt cable replacement represent the most penetrable buyer archetype given technician training gaps that constrain incumbent field service expansion. India's PLI scheme for automotive manufacturing offers white-space geographic entry through localized cell manufacturing incentives. Direct supplier development partnerships with battery producers in Tamil Nadu's manufacturing belt provide the strongest go-to-market angle bypassing established tier-1 relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized cable manufacturers possessing liquid-cooled conductor design capabilities and direct OEM procurement channel access. Long-term viability over a five-to-ten year window favors targets with proven 800-volt platform qualification rather than undifferentiated commodity harness producers. Solid-state battery packaging announcements serve as the critical signal to watch for inflection in junction box complexity and per-vehicle cable count assumptions.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid-Cooled Conductor Scale-Up | Enables 800-volt fast-charging compatibility for Hyundai and Volkswagen platform programs. |
| Direct OEM Procurement Channel Development | Bypasses tier-1 harness suppliers to capture margin from Volkswagen and Hyundai Motor Group. |
| GB/T Electromagnetic Compatibility Certification | Secures market access under China's mandatory shielding effectiveness testing protocols. |
| Backward Integration into Copper Processing | Controls cost volatility from London Metal Exchange pricing fluctuations for conductor materials. |
| Silicone Elastomer Compound Formulation | Addresses thermal management requirements above 180°C in inverter-adjacent routing zones. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with OEM platform engineers, tier-1 supplier procurement leads, aftermarket service network managers, and high-voltage safety certification trainers with secondary validation from vehicle production databases, IHS Markit registration data, SEC filings of listed cable manufacturers, and customs records of copper conductor trade flows. Bottom-up segment sizing and top-down market reconciliation anchored volume and value estimates.
Comparable-period anchoring linked projection assumptions to historical platform launch cycles and voltage architecture transitions across the modeling period. Segmentation dimensions modeled included propulsion architecture, conductor material, installation type, and regional production cluster. CAGRs were derived from fitted growth curves applied to unit shipment trajectories, with 800-volt platform penetration rates and cell-to-pack adoption serving as primary forecast inputs.
Underlying measurement precision varies by segment; charging cable volumes carry tighter precision than aftermarket replacement estimates given infrastructure deployment visibility. Forecasts reflect documented assumptions regarding platform voltage escalation timelines and solid-state battery commercialization pathways. Deviation in China's GB/T certification enforcement intensity or copper price volatility spikes would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Mexico Automotive Electric Actuators Market
Automotive Electrical & Electronics
Global Automotive ECU Market
Automotive Electrical & Electronics
Global Automotive on Board AC-DC Power Inverters Market
Automotive Electrical & Electronics
South Korea Automotive Electric Actuators Market
Automotive Electrical & Electronics
Electric Vehicle Motor Communication Controller Market
Automotive Electrical & Electronics
Bicycle Electronic Drivetrain Market
Automotive Electrical & Electronics
Global Automotive Multifunctional Lamp Market
Automotive Electrical & Electronics
Automotive Rain Sensor Market
Automotive Electrical & Electronics
Personal Mobility Devices Market
Automotive Electrical & Electronics
Nox Automotive Sensors Market
Automotive Electrical & Electronics
Europe Automotive Tpms Market
Automotive Electrical & Electronics
Automotive Electronic Control Unit Market
Automotive Electrical & Electronics
Global Automotive Electronically Controlled Air Suspension System Market
Automotive Electrical & Electronics
Europe Automotive Steering Sensor Market
Automotive Electrical & Electronics
Automotive LED Market
Automotive Electrical & Electronics
Automotive E-Axle Disconnect Actuator Market