
 Electric Motor Horn Market | 2026-2036
Electric Motor Horn Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Motor Horn Market Analysis
Aftermarket service revenue is rewriting margin economics across the electric motor horn value chain. Robert Bosch GmbH leverages its global service network to capture recurring calibration and replacement demand. DENSO Corporation anchors production scale through integrated manufacturing of horn assemblies alongside sensor platforms. MAHLE GmbH competes on acoustic engineering specialization for electric vehicle pedestrian warning systems.
An electric motor horn is an electromechanical acoustic device that converts electrical energy into sound waves through diaphragm vibration, typically operating at 105-118 decibels to meet statutory warning requirements. The device serves critical safety functions in transportation and industrial settings where audible alerts prevent collisions and signal operational status. Disc horns dominate OEM vehicle applications due to compact packaging and reliable performance across temperature extremes. Electromagnetic horns retain strong aftermarket demand from fleet operators seeking cost-effective replacement units. Marine and railway applications command premium pricing through corrosion-resistant specifications and extended duty-cycle engineering.
The US NHTSA mandates minimum sound levels for hybrid and electric vehicles under the Pedestrian Safety Enhancement Act, directly shaping product design requirements for OEM suppliers. Europe's UN ECE R28 and CE marking frameworks enforce acoustic output consistency and electromagnetic compatibility across member states. India's BIS certification and Automotive Industry Standards Committee protocols govern local manufacturing and import qualification. Stakeholders must monitor regulatory divergence between decibel thresholds and frequency specifications as electric vehicle adoption accelerates acoustic system redesign cycles.
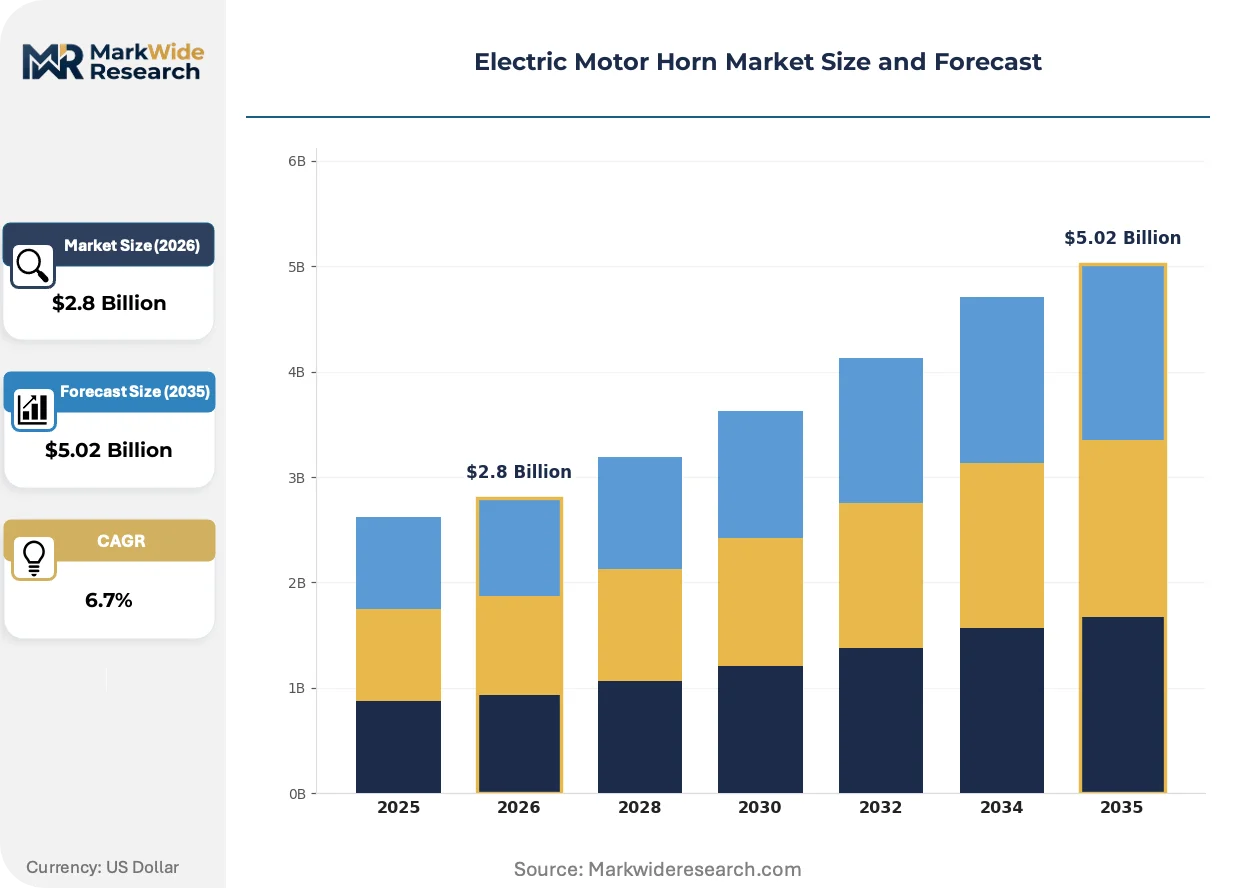
Market Dynamics
Acoustic regulation divergence between decibel thresholds and frequency specifications is forcing simultaneous redesign cycles across OEM programs, compressing development timelines while expanding engineering scope for pedestrian warning systems.
Growth Catalysts
- UN ECE R28 acoustic consistency mandates:European homologation requirements now enforce electromagnetic compatibility alongside sound output, compelling suppliers to integrate shielding and frequency modulation into base designs.
- Electric vehicle platform proliferation:Automakers redesigning quieter powertrains require purpose-built warning systems, creating fresh procurement volumes for disc horn assemblies with extended temperature tolerance.
- Stuttgart-Munich supplier corridor concentration:Tier-one acoustics engineering clusters co-located with premium OEM headquarters accelerate prototype-to-production cycles through embedded technical collaboration.
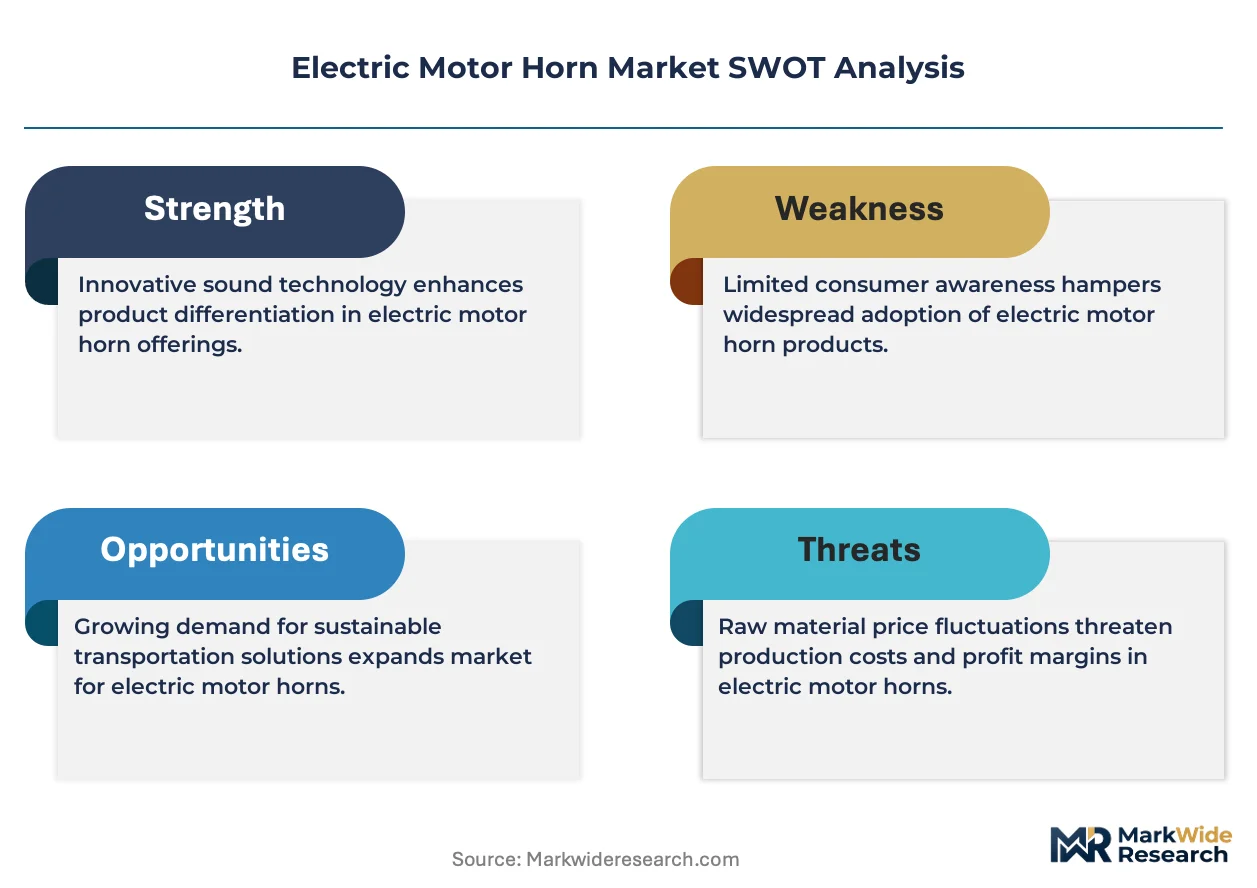
Market Restraints
- Neodymium magnet cost volatility:Rare-earth price swings in Chinese processing facilities compress margin predictability for electromagnetic horn manufacturers locked into annual supply agreements.
- Corrosion-resistant alloy sourcing concentration:Marine and railway specifications requiring extended duty-cycle engineering depend on limited Nordic stainless steel suppliers, creating bottleneck risk.
- Acoustic output standardization lag:Divergent frequency specifications between NHTSA pedestrian safety mandates and UN ECE R28 frameworks force parallel certification tracks, duplicating testing expenditure.
Strategic Opportunities
- India BIS certification expansion:Local manufacturing incentives under Automotive Industry Standards Committee protocols attract greenfield investment for domestic EV platform supply.
- Sensor-horn convergence:Integration of acoustic warning modules with ADAS proximity detection systems creates bundled value propositions for next-generation vehicle architectures.
- Direct fleet procurement channels:Logistics operators bypass traditional distribution tiers through volume service contracts, capturing calibration and replacement demand at source.
Industry Challenges
- Acoustic engineer talent scarcity:Specialized expertise in electromechanical transducer design and NVH simulation concentrates in German automotive supplier networks, constraining global program staffing.
- Homologation timeline compression:Simultaneous NMPA, NHTSA, and UN ECE R28 certification requirements for shared EV platforms extend validation cycles beyond traditional model-year windows.
- Legacy 12V electrical architecture integration:New 48V vehicle systems require voltage step-down engineering for backward-compatible horn assemblies, adding component complexity without performance gain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Motor Horn Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disc Horns, Air Horns, Electromagnetic Horns, Musical Horns Application: Vehicles, Industrial Equipment, Marine, Railways End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Musicians Installation Type: Direct Mount, Surface Mount, Flush Mount, Customized Mount |
| Companies Covered | Mitsuba Corporation, Fiamm Energy Technology S.p.A., Robert Bosch GmbH, Clarton Horn, Wolo Manufacturing Corporation, DENSO Corporation, UNO Minda, MAHLE GmbH, HELLA GmbH & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Motor Horn Market Emerging Trajectories
Piezoelectric transducer architectures are displacing traditional electromagnetic diaphragm mechanisms across premium electric vehicle programs, while regulatory agencies accelerate frequency-specific mandates that favor programmable acoustic signatures over fixed-tone designs.
Solid-state piezoelectric actuators eliminate mechanical wear points through ceramic element vibration, delivering precise frequency modulation for pedestrian warning systems. Premium OEMs in Germany and California are specifying these units for 2027 platform launches. The technology is rendering obsolete conventional disc horn assemblies in applications requiring customizable sound profiles for brand differentiation.
China's NMPA safety standards now mandate minimum sound pressure levels for electric vehicles at low speeds, mirroring NHTSA's Pedestrian Safety Enhancement Act implementation timeline. The regulation compels acoustic system redesign across shared vehicle platforms destined for multiple markets. Suppliers serving both Chinese and North American programs face convergent engineering requirements that favor modular, reprogrammable horn architectures over region-locked hardware variants.
Fleet operators now unbundle after-sales service contracts from initial equipment procurement, negotiating direct calibration and replacement agreements with tier-one acoustics suppliers. This disintermediation compresses distributor margins while shifting inventory risk to manufacturer balance sheets. The pattern is most visible in German commercial vehicle corridors, where logistics conglomerates leverage concentrated procurement volumes to secure multi-year technical service partnerships.
Electric Motor Horn Market Segmentation
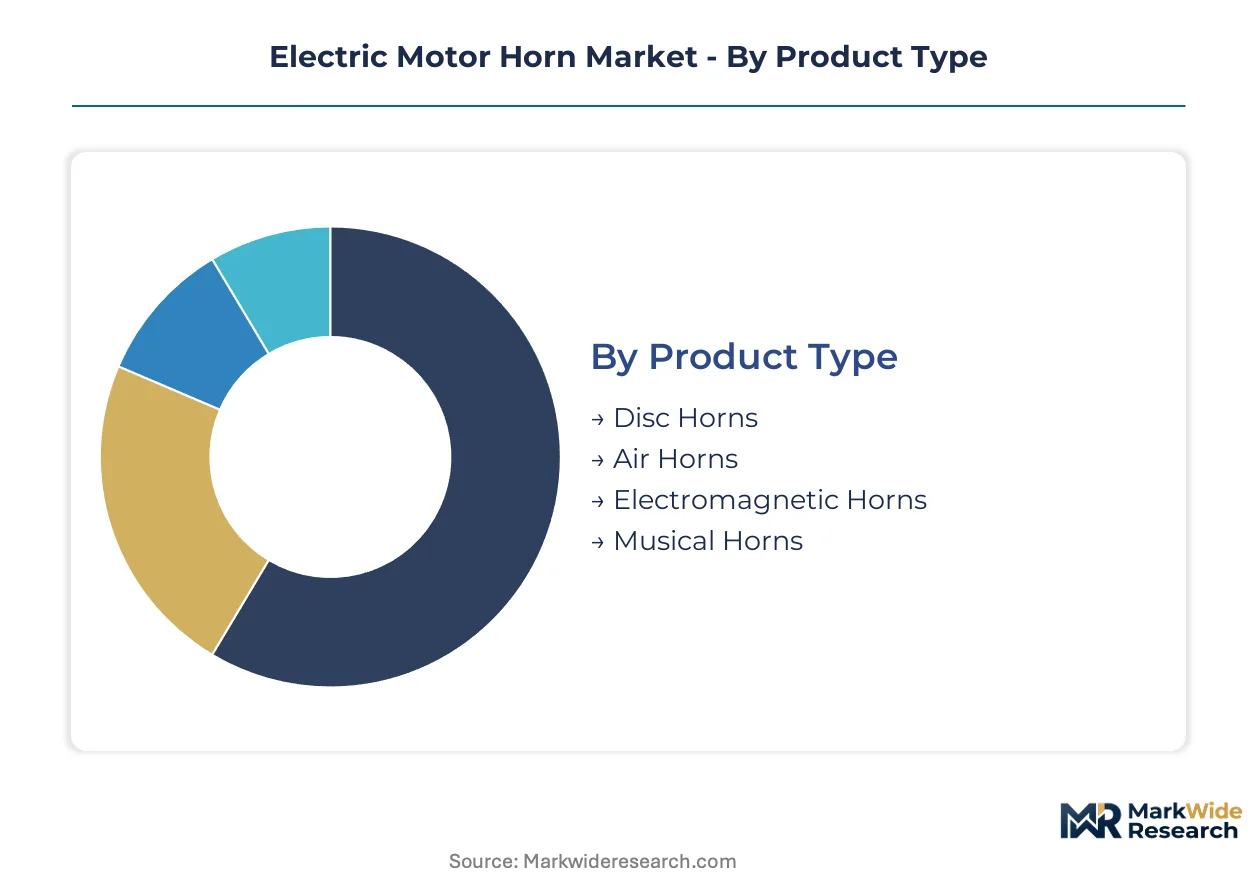
Aftermarket calibration and replacement cycles vary dramatically across electric motor horn configurations, with disc horns and electromagnetic units generating recurring revenue streams that reshape supplier margin structures. Fleet operators unbundle service contracts from initial procurement, forcing segmentation strategies to account for lifetime value rather than unit economics alone.
Product Type:
After-sales service intensity concentrates in disc and electromagnetic variants where diaphragm wear and electromagnetic coil degradation drive predictable replacement intervals.
- Disc Horns:Electromechanical diaphragm assemblies operating through electromagnetic coil excitation deliver 105-118 decibel output with compact packaging suited for engine-bay constraints. OEM procurement from Stuttgart-Munich supplier corridors dominates volume, with premium electric vehicle programs specifying extended temperature tolerance for quieter powertrain integration.
- Electromagnetic Horns:Traditional solenoid-actuated diaphragm mechanisms retain strong aftermarket demand from logistics fleets seeking cost-effective replacement units. Fleet operators in German commercial vehicle corridors negotiate direct calibration agreements, bypassing distribution tiers to capture volume pricing on electromagnetic coil assemblies.
- Air Horns:Compressed-air diaphragm systems command premium positioning in heavy-duty commercial and railway applications requiring sustained high-decibel output.
- Musical Horns:Programmable tone-generation units serve niche customization demand with limited aftermarket service attachment.
By volume, disc horns lead. By growth pace, electromagnetic variants for fleet replacement are ahead.
Application:
Cost tier stratification separates premium corrosion-resistant specifications from standard-duty units across transportation modes.
- Vehicles:Passenger and commercial automotive applications dominate procurement volumes with NHTSA pedestrian safety mandates and UN ECE R28 homologation requirements driving acoustic system redesign. Electric vehicle platform proliferation creates fresh demand for purpose-built warning systems with programmable frequency modulation.
- Industrial Equipment:Factory automation and material handling systems require intermittent-duty horns with IP-rated enclosures for dust and moisture protection. Warehouse operators in China's manufacturing zones specify electromagnetic units for forklift collision avoidance, with replacement cycles tied to equipment leasing arrangements.
- Marine:Saltwater-resistant stainless steel specifications from Nordic suppliers command premium pricing through extended duty-cycle engineering.
- Railways:Heavy-haul locomotive applications require MIL-spec vibration tolerance with corrosion-resistant alloy sourcing creating supply bottlenecks.
By revenue concentration, vehicle applications dominate. By margin expansion, marine and railway specifications are climbing the fastest.
End User:
Customer type determines procurement channel structure, with direct fleet agreements displacing traditional distribution for high-volume accounts.
- OEMs:Original equipment manufacturers specify disc horn assemblies through embedded technical collaboration with tier-one acoustics engineering clusters. German premium automakers co-locate supplier engineering teams for prototype-to-production acceleration on electric vehicle platforms.
- Aftermarket Providers:Independent distributors and service networks capture replacement demand through inventory risk absorption and technical calibration services. Bosch leverages global service infrastructure for recurring revenue on electromagnetic unit replacement.
- Vehicle Assemblers:Contract manufacturers and kit builders procure standard-duty electromagnetic horns through volume supply agreements with limited service attachment.
- Musicians:Niche customization demand for programmable tone systems generates sporadic procurement with minimal aftermarket engagement.
By procurement volume, OEMs lead. By margin sustainability, aftermarket providers with embedded service contracts are gaining share fastest.
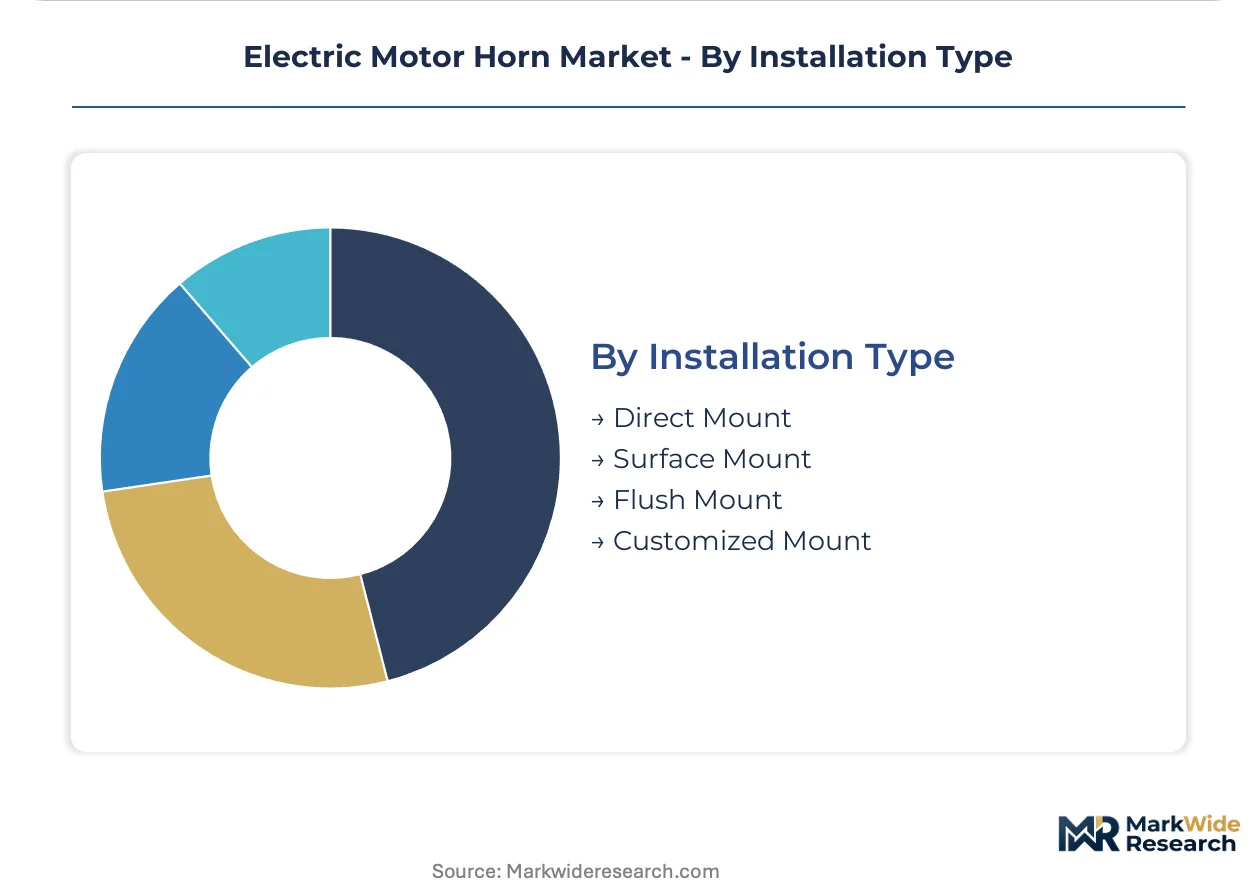
Installation Type:
Supply concentration in German automotive supplier corridors favors direct mount configurations engineered for platform-specific integration.
- Direct Mount:Vehicle-specific bracketry and electrical connectors designed for engine-bay or fascia integration dominate OEM specifications. Stuttgart-based engineering clusters optimize direct mount designs for premium electric vehicle programs requiring electromagnetic compatibility shielding.
- Surface Mount:Universal bracket systems serve aftermarket replacement demand with simplified installation protocols for fleet maintenance operations.
- Flush Mount:Concealed integration for aesthetic-sensitive applications in premium passenger vehicles commands engineering premium with limited volume.
- Customized Mount:Bespoke fabrication for marine, railway, and specialty vehicle applications requires extended lead times with project-based procurement.
By unit volume, direct mount leads. By engineering premium capture, customized mount for marine and railway applications shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electric motor horn consumption patterns diverge sharply by geography. Germany and China prioritize OEM-integrated pedestrian warning systems for electric vehicle platforms, while India and the United States concentrate aftermarket replacement demand through fleet service networks.
Germany
Premium automakers in Stuttgart and Munich drive procurement of disc horn assemblies with electromagnetic compatibility shielding. UN ECE R28 acoustic consistency mandates enforce frequency modulation requirements across OEM programs. The Stuttgart-Munich supplier corridor concentrates tier-one acoustics engineering clusters serving embedded technical collaboration contracts.
China
Domestic electric vehicle manufacturers accelerate platform-specific warning system redesigns for quieter powertrains. NMPA safety standards mandate minimum sound pressure levels at low speeds, compelling acoustic system homologation. Yangtze River Delta manufacturing zones attract greenfield investment for localized EV platform supply under Automotive Industry Standards Committee protocols.
United States
Commercial fleet operators negotiate direct calibration agreements bypassing traditional distribution tiers. NHTSA Pedestrian Safety Enhancement Act requirements shape product design specifications for hybrid and electric vehicle suppliers. Midwest automotive manufacturing corridors absorb replacement demand through volume service contracts with tier-one suppliers.
India
Two-wheeler and commercial vehicle assemblers drive electromagnetic horn procurement through cost-optimized supply agreements. BIS certification expansion under Automotive Industry Standards Committee protocols incentivizes local manufacturing investment. Maharashtra and Gujarat industrial zones concentrate domestic production capacity for regional EV platform qualification.
Japan
Automotive suppliers integrate piezoelectric transducer architectures for premium electric vehicle programs requiring programmable acoustic signatures. METI industrial standards guide electromechanical component specifications for export-oriented production. Kanto and Kansai manufacturing belts anchor precision ceramic actuator development for 2027 platform launches.
Electric Motor Horn Market Vendor Landscape
Capability concentration sits with specialized acoustics engineering firms; scale advantage sits with diversified automotive component conglomerates. The market structures around three tiers: integrated tier-one suppliers with embedded OEM relationships, independent horn specialists with marine and railway expertise, and regional fabricators serving aftermarket replacement cycles. Strategic moves center on sensor-horn convergence for ADAS integration and direct fleet procurement channel development.
Among diversified automotive suppliers, Robert Bosch GmbH and DENSO Corporation exemplify scale-driven positions through global service network leverage and integrated manufacturing platforms. MAHLE GmbH occupies a specialization tier focused on acoustic engineering for electric vehicle pedestrian warning systems. Fiamm Energy Technology S.p.A. represents the independent specialist archetype with European heritage in electromechanical acoustic devices.
| Leading Market Players |
|---|
| Mitsuba Corporation |
| Fiamm Energy Technology S.p.A. |
| Robert Bosch GmbH |
| Clarton Horn |
| Wolo Manufacturing Corporation |
| DENSO Corporation |
| UNO Minda |
| MAHLE GmbH |
| HELLA GmbH & Co. KGaA |
| Others |
Supply Flow & Price Mechanics
The Rhine-Alpine freight corridor's container rate volatility feeds directly into Stuttgart-Munich supplier cluster economics, amplifying price spreads between electromagnetic coil assemblies and piezoelectric ceramic actuators while compressing distributor margins on aftermarket replacement cycles.
Pricing Analysis
Long-term offtake agreements dominate OEM procurement from German premium automakers, locking in volume pricing for disc horn assemblies with electromagnetic compatibility shielding. Price differentiation stems from certification tier—UN ECE R28 homologated units command premium positioning over BIS-compliant variants—and after-sales service bundling. Cost compression in electromagnetic horn tiers is intensifying because neodymium magnet price swings erode margin predictability for suppliers locked into annual supply contracts. Fleet operators exhibit highest price sensitivity through direct procurement channels, while marine specifications show lowest sensitivity due to corrosion-resistant alloy scarcity.
Supply Chain Analysis
Contract manufacturing capacity concentrates with tier-one acoustics engineering clusters in Germany, China, and Japan, where integrated horn-sensor platforms are assembled alongside ADAS modules. Raw material dependencies rest on neodymium rare-earth processing from Chinese facilities, Nordic stainless steel for marine specifications, and precision ceramic substrates for piezoelectric actuators. Single-source vulnerability in neodymium magnet supply creates structural risk for electromagnetic horn manufacturers. Distribution runs through embedded OEM technical collaboration contracts for direct mount configurations, while surface mount variants flow through aftermarket service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment defensive moat: UN ECE R28, NHTSA, and NMPA homologation requirements create switching costs that lock OEMs into established tier-one supplier relationships across redesign cycles.
For Market Incumbents: Insulate embedded OEM relationships by deepening acoustic engineering co-location in Stuttgart-Munich corridors and accelerating piezoelectric platform certification ahead of 2027 launch windows. Solid-state transducer substitution threatens electromagnetic assembly volumes; backward integration into precision ceramic actuator supply secures component availability for programmable horn architectures. For New Entrants and Emerging Players: Pursue white-space positioning in India's BIS-certified domestic manufacturing for two-wheeler and commercial vehicle electromagnetic horn supply, where local content incentives attract greenfield investment. The most penetrable segment lies in direct fleet procurement channels for calibration and replacement services, bypassing traditional distribution tiers through volume technical service partnerships with logistics operators. For Investors and Strategic Acquirers: Independent acoustics specialists with marine and railway corrosion-resistant engineering capabilities represent priority acquisition targets, given Nordic alloy sourcing bottlenecks and extended duty-cycle premium capture. Long-term viability across the analysis window hinges on sensor-horn convergence for ADAS integration; monitor piezoelectric platform adoption rates at premium German and Japanese OEMs as inflection signal for electromagnetic displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Horn Platform Integration | ADAS proximity detection bundling with acoustic warning modules captures next-generation vehicle architecture value. |
| Piezoelectric Actuator Certification | UN ECE R28 frequency modulation compliance for solid-state ceramic designs displaces electromagnetic diaphragm mechanisms. |
| Direct Fleet Service Contracts | Calibration and replacement agreements with German logistics conglomerates compress distributor margins while shifting inventory risk. |
| Nordic Alloy Supply Anchoring | Corrosion-resistant stainless steel sourcing partnerships secure marine and railway premium positioning against bottleneck risk. |
| India Greenfield Manufacturing | BIS certification expansion under Automotive Industry Standards Committee protocols qualifies domestic supply for regional EV platforms. |
Methodological Framework
Desk research of regulatory filing databases, customs trade records, and vehicle production statistics preceded structured interviews with tier-one supplier procurement directors, OEM platform engineers, aftermarket service network managers, and acoustics engineering specialists. Secondary validation drew from UN ECE R28 homologation registries, NHTSA pedestrian safety compliance filings, and BIS certification directories. Bottom-up segment sizing triangulated against top-down automotive production forecasts.
Assumptions held fixed across the modeling period include UN ECE R28 acoustic consistency mandate enforcement timelines, neodymium magnet price volatility within historical bands, and OEM platform redesign cycle frequencies. Segmentation dimensions modeled encompass product type, application, end user, and installation configuration alongside regional regulatory cluster alignment. CAGRs were derived from production volume elasticities and content-per-vehicle trajectories, with electric vehicle platform proliferation and piezoelectric adoption velocity as primary forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in automotive production volumes, rare-earth commodity prices, or regulatory harmonization timelines would shift the trajectory. Forecasts reflect documented assumptions with acknowledged sensitivity to homologation timeline compression and acoustic engineer talent scarcity constraints. Quarterly review of OEM platform launch schedules, NMPA rulemaking updates, and fleet operator procurement pattern shifts is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
US Automotive EPS Market
Automotive Electrical & Electronics
Global Automotive Electronically Controlled Air Suspension System Market
Automotive Electrical & Electronics
Commercial Vehicle Switches and Relays Market
Automotive Electrical & Electronics
Japan X by Wire Systems Market
Automotive Electrical & Electronics
Global Automotive Multifunctional Lamp Market
Automotive Electrical & Electronics
China Electric Power Steering Market
Automotive Electrical & Electronics
China Automotive Electric Power Steering (EPS) Market
Automotive Electrical & Electronics
Global Automotive DC-DC Converters Market
Automotive Electrical & Electronics
E-Bike Lights Market
Automotive Electrical & Electronics
Automotive Electronic Suspension System (ESS) Market
Automotive Electrical & Electronics
South Korea Automotive Camera Market
Automotive Electrical & Electronics
Automotive Temperature Sensor Market
Automotive Electrical & Electronics
Global Automotive Electrical Distribution System Market
Automotive Electrical & Electronics
Automotive Charge Port Actuator Market
Automotive Electrical & Electronics
Automotive Temperature and Humidity Sensors Market
Automotive Electrical & Electronics
South Korea Automotive Electric Actuators Market