
 Automotive Power Window Regulator Market | 2026-2036
Automotive Power Window Regulator Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Power Window Regulator Market Insights
Electromechanical engineering talent scarcity is reorganizing supplier footprints across the automotive power window regulator supply chain. Brose Fahrzeugteile SE & Co. KG leverages its vertical integration into motor and cable drive production to sustain cost advantages in European OEM programs. Magna International anchors North American supply through dedicated module assembly plants serving Detroit-based vehicle manufacturers. Denso Corporation competes on electronic control integration, positioning its regulator systems within broader door module architectures.
An automotive power window regulator is an electromechanical or mechanical device that converts rotational motor output into linear window glass displacement through cable drum, scissor, or sector gear mechanisms, typically operating at 12V or 48V in modern architectures and rated for 10,000+ cycles to withstand environmental loading. Its primary commercial purpose is enabling occupant-controlled window positioning while satisfying federal and manufacturer safety requirements for pinch detection and emergency reversal. Electric regulators dominate OEM fitment due to consumer expectation of one-touch automation and integration with centralized body control modules. Electronic technology segments capture expanding value pools as pulse-width modulation and Hall-effect sensing replace basic relay-driven designs. Aftermarket providers occupy a mature channel concentrated in collision repair and aging vehicle maintenance rather than upgrade demand.
NHTSA Federal Motor Vehicle Safety Standard 118 governs power window automatic reversal systems in the United States, compelling sensor integration that elevates electronic regulator content per door. ECE R21 and EU General Safety Regulation extend similar anti-trap mandates across European type approvals, while China's GB standards administered by MIIT impose homologation testing on window system durability. Japan's METI oversees industrial standards coordination that influences JIS compliance pathways for export-bound regulators. Stakeholders must monitor 48V electrical architecture migration and corresponding motor redesign requirements as mild-hybrid platforms proliferate without full battery electric transition.
Market Dynamics
The automotive power window regulator market is experiencing structural compression as 48V electrical architecture migration forces simultaneous motor redesign and control electronics consolidation across supplier portfolios.
Growth Catalysts
- NHTSA Federal Motor Vehicle Safety Standard 118:Anti-pinch mandates in the United States are compelling sensor integration that elevates electronic content per door module and expands addressable component value.
- Electric vehicle platform proliferation:EV architectures prioritize weight reduction and energy efficiency, driving demand for compact cable-drum regulators with integrated motor-control units.
- China MIIT homologation pathways:GB standards durability testing creates certification barriers that favor established module suppliers with in-house validation capabilities.
Market Restraints
- Copper and rare-earth magnet cost volatility:Motor winding materials face commodity price swings that compress supplier margins on fixed-price OEM contracts.
- Manufacturing concentration in East Asia:Module assembly capacity clusters in China, Japan, and South Korea expose supply chains to single-point geopolitical disruption.
- Mechanical regulator substitution ceiling:Low-cost scissor mechanisms in emerging-market vehicle segments limit premium electronic system penetration.
Strategic Opportunities
- India automotive production expansion:PLI scheme incentives for advanced automotive components create localized manufacturing opportunities for electronic regulator modules.
- Software-defined vehicle convergence:Integration of window control with centralized body domain controllers enables over-the-air calibration and predictive maintenance revenue streams.
- Collision repair channel digitization:E-commerce platforms and VIN-matched catalog systems are streamlining aftermarket parts distribution for aging vehicle parc maintenance.
Industry Challenges
- Electromechanical engineering talent scarcity:Motor design and cable-drive simulation expertise concentrates at a handful of Tier 1 suppliers, constraining new entrant capability building.
- Dual-voltage certification complexity:Simultaneous 12V and 48V validation requirements extend development timelines and multiply testing costs for platform-spanning products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Power Window Regulator Market |
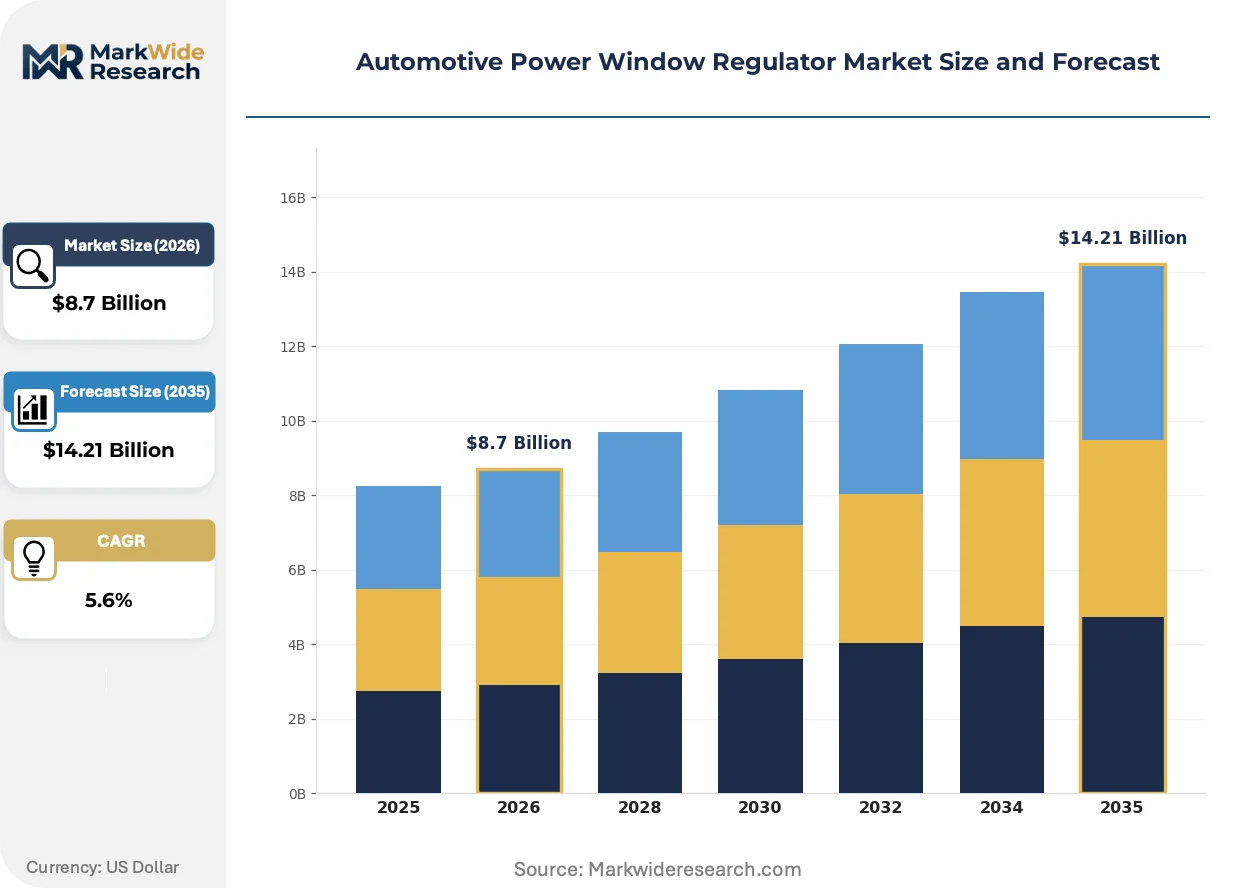
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Regulators, Manual Regulators, Complete Assembly, Components End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Auto Repair Shops Vehicle Type: Passenger Cars, Commercial Vehicles, SUVs, Electric Vehicles Technology: Hydraulic, Mechanical, Electronic, Multi-Point |
| Companies Covered | Brose Fahrzeugteile SE & Co. KG, Grupo Antolin, Hi-Lex Corporation, Valeo, Magna International, Shiroki Corporation, Robert Bosch GmbH, Kongsberg Automotive, Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Power Window Regulator Market Trends and Innovations
Power window regulator architecture is converging with broader door module electronics as pulse-width modulation and position sensing displace basic relay-driven designs. This technological transition is reshaping supplier value capture and OEM sourcing strategies.
Hall-effect position sensing with pulse-width modulation motor control is displacing binary limit-switch designs in premium and mid-range vehicle segments. OEMs in Germany and Japan are specifying these systems for one-touch express-up functionality with precise anti-pinch torque measurement. The technology is displacing standalone relay modules and consolidating motor driver electronics into centralized body control architectures.
EU General Safety Regulation anti-trap mandates are extending ECE R21 requirements across all European type approvals without grandfathering exemptions. Regulator suppliers must now validate reversal systems across temperature, voltage, and wear-state matrices before market entry. Aftermarket providers serving European collision repair face compliance documentation burdens that favor OEM-certified channel partners.
Fleet operators and mobility service providers are compressing supplier payment cycles and demanding modular replacement strategies that minimize vehicle downtime. Traditional full-regulator assembly sales are giving way to motor-cartridge and cable-drive separate component availability in North American commercial vehicle channels. This unbundling is most visible in rental fleet maintenance programs where rapid turnaround overrides total cost optimization.
Automotive Power Window Regulator Market Segmentation
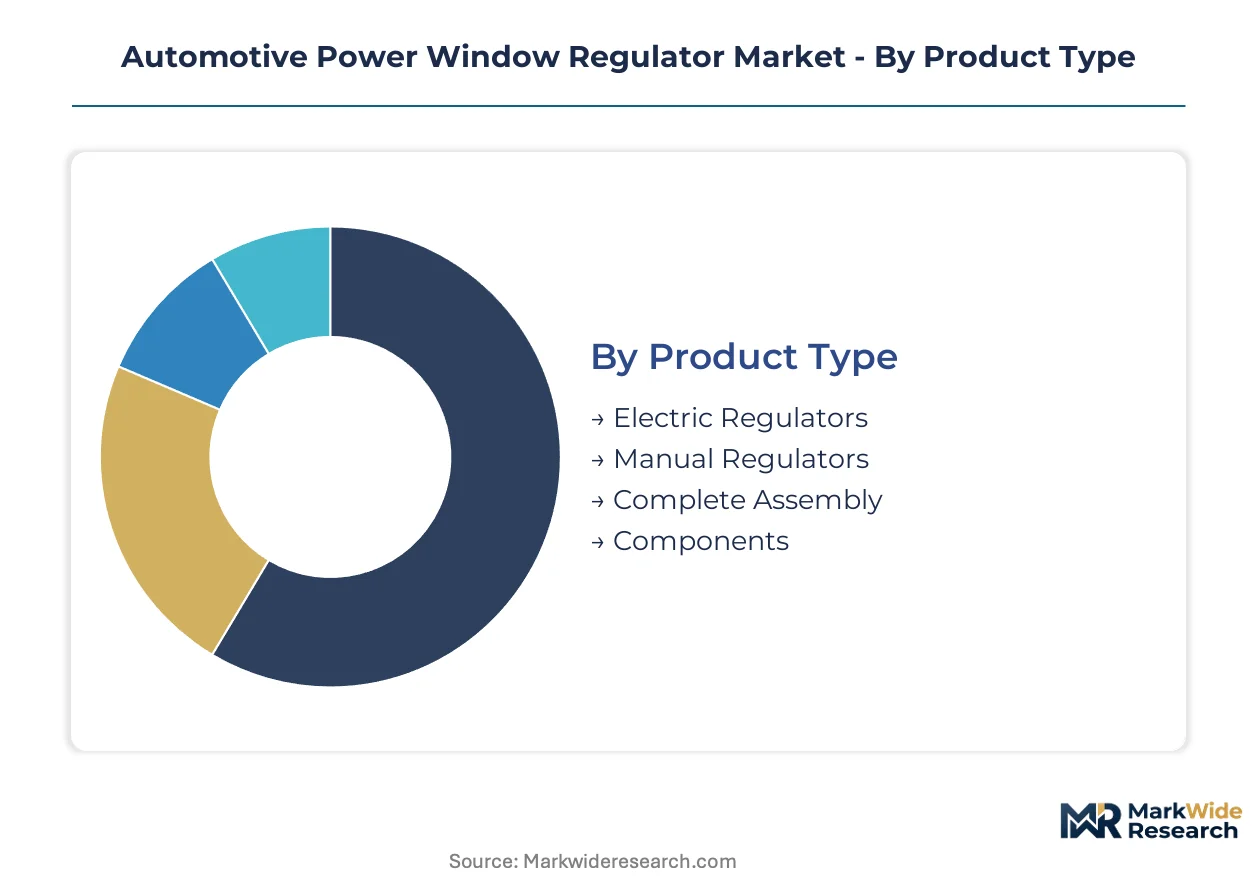
Power window regulator segmentation reveals distinct channel economics across product architectures. OEMs source integrated electronic modules through long-term platform contracts, while aftermarket channels fragment across collision repair and aging vehicle maintenance with divergent technical requirements.
Product Type:
Channel mix varies sharply by product form—complete assemblies flow through OEM vehicle assembly plants, while component-level sales concentrate in aftermarket collision repair and service channels.
- Electric Regulators:Pulse-width modulation motor control with Hall-effect position sensing enables one-touch express-up functionality and precise anti-pinch torque measurement. OEM demand from Germany and Japan concentrates here as NHTSA Federal Motor Vehicle Safety Standard 118 mandates elevate electronic content per door module.
- Manual Regulators:Mechanical scissor or sector gear mechanisms without motor integration serve cost-sensitive emerging-market vehicle segments where consumer expectations for automation remain lower. Low-cost manufacturing in China sustains this segment through high-volume supply to budget vehicle platforms.
- Complete Assembly:Pre-integrated door modules combining regulator, motor, and control electronics ship directly to vehicle assembly plants for just-in-sequence installation.
- Components:Motor cartridges, cable drums, and drive mechanisms sell separately through distributor networks serving collision repair and fleet maintenance channels.
Electric regulators dominate installed base. Components is where expansion concentrates as fleet operators unbundle replacement strategies to minimize vehicle downtime.
End User:
Cost tier stratification separates specification-heavy OEM programs from price-sensitive aftermarket procurement with minimal technical documentation requirements.
- OEMs:Vehicle manufacturers specify platform-integrated regulator systems with 10,000+ cycle durability ratings and centralized body control module compatibility. These contracts carry multi-year supply agreements with stringent validation protocols.
- Aftermarket Providers:Distributors and catalog houses serve collision repair and aging vehicle parc maintenance through VIN-matched part identification systems. E-commerce platform digitization is streamlining channel logistics.
- Vehicle Assemblers:Contract manufacturers and regional assembly operations procure regulator modules for localized production of global vehicle platforms.
- Auto Repair Shops:Independent service facilities source replacement regulators through wholesale distributors, prioritizing part availability and turnaround speed over technical sophistication.
OEMs command specification authority. Aftermarket providers is where margin compression from channel digitization concentrates.
Vehicle Type:
Application-specific durability and weight requirements drive divergent regulator architectures across passenger and commercial duty cycles.
- Passenger Cars:Compact cable-drum regulators with integrated motor-control units satisfy weight reduction priorities in high-volume sedan and hatchback production. Electronic pulse-width modulation designs dominate this segment.
- Commercial Vehicles:Heavy-duty scissor mechanisms withstand frequent cycling and environmental loading in fleet taxi and delivery applications. Fleet operators here demand modular replacement strategies.
- SUVs:Larger glass areas require higher-torque motor specifications and reinforced cable drive systems to manage increased mechanical load.
- Electric Vehicles:48V electrical architecture migration is forcing simultaneous motor redesign and control electronics consolidation for mild-hybrid and battery electric platforms.
Passenger cars anchor volume scale. Electric vehicles is where technology transition and steepest expansion trajectory intersect.
Technology:
Supply concentration in electromechanical engineering talent favors established Tier 1 suppliers with in-house motor design and cable-drive simulation capabilities.
- Electronic:Microcontroller-based motor drivers with position feedback enable software-defined vehicle integration and over-the-air calibration. Brose and Denso compete here on control integration within broader door module architectures.
- Mechanical:Scissor lift and sector gear linkages without electronic control serve manual window systems and cost-optimized emerging-market vehicle programs. China's MIIT GB standards durability testing applies to these systems.
- Hydraulic:Fluid-powered actuation persists in specialty commercial and off-highway applications requiring extreme force multiplication.
- Multi-Point:Distributed sensor arrays and redundant control pathways serve premium vehicle segments with advanced anti-pinch and obstacle detection requirements.
Electronic systems capture expanding value pools. Multi-point is where safety regulation stringency drives premium tier differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Japanese supplier clusters while Chinese manufacturing bases compete on unit cost. OEMs in Stuttgart and Toyota City command specification premiums. Contract manufacturers in Shanghai and Tianjin absorb margin compression from fixed-price agreements.
United States
NHTSA Federal Motor Vehicle Safety Standard 118 mandates anti-pinch sensor integration across all light vehicle platforms. Detroit-based OEMs source pulse-width modulation regulators through dedicated module assembly plants. Michigan and Ohio host the densest concentration of Tier 1 supplier engineering centers.
Germany
EU General Safety Regulation anti-trap requirements extend ECE R21 compliance across all European type approvals. Brose Fahrzeugteile SE & Co. KG anchors cable-drum production in Coburg with backward integration into motor manufacturing. Stuttgart and Wolfsburg OEMs specify Hall-effect sensing for express-up functionality.
China
MIIT GB standards impose homologation durability testing that favors established module suppliers with captive validation laboratories. Yangtze River Delta clusters in Shanghai and Suzhou concentrate cable-drive assembly capacity. Local OEMs procure electronic regulators for domestic EV platforms at compressed price points.
Japan
METI coordinates industrial standards through JIS compliance pathways for export-bound regulators. Denso Corporation integrates window control within broader door module architectures from Aichi Prefecture. Toyota City and Hiroshima OEMs specify 10,000-cycle durability ratings for high-volume hatchback production.
India
PLI scheme incentives for advanced automotive components attract localized electronic module manufacturing. Tamil Nadu and Maharashtra host emerging regulator assembly operations serving Maruti Suzuki and Hyundai Motor India. Domestic OEMs balance cost targets against emerging consumer expectations for one-touch automation.
Automotive Power Window Regulator Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Integrated electronics specialists capture premium value through control module consolidation. Scale-driven cable-drive manufacturers defend position through motor winding efficiency and material sourcing discipline. Two dominant competitive moves define current rivalry: geographic expansion into India under PLI incentives and portfolio diversification toward 48V architecture compatibility.
Within the integrated control tier, Brose Fahrzeugteile SE & Co. KG and Denso Corporation exemplify archetypes combining motor production with electronic module design. Among diversified automotive suppliers, Magna International occupies a position representing North American module assembly scale. Robert Bosch GmbH anchors a technology-forward archetype spanning sensor integration and body control software.
| Leading Market Players |
|---|
| Brose Fahrzeugteile SE & Co. KG |
| Grupo Antolin |
| Hi-Lex Corporation |
| Valeo |
| Magna International |
| Shiroki Corporation |
| Robert Bosch GmbH |
| Kongsberg Automotive |
| Denso Corporation |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization above 85 percent at Yangtze River Delta cable-drive assembly plants compresses unit economics for mid-tier suppliers while elevating price floors for electronic regulator modules. This scale concentration simultaneously anchors global supply chains and hardens negotiated contract terms for Detroit and Stuttgart OEMs seeking just-in-sequence delivery.
Pricing Analysis
Configured-to-order pricing for Hall-effect sensing modules with integrated pulse-width modulation control commands 15-25 percent premiums over standard relay-driven scissor mechanisms. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade divergence—NHTSA Federal Motor Vehicle Safety Standard 118 compliance elevates electronic tiers while mechanical scissor units serve cost-optimized emerging-market platforms. Pricing pressure stems from fixed-price OEM contracts confronting copper winding and rare-earth magnet cost volatility. Fleet operators and mobility service providers exhibit highest price sensitivity through unbundled component procurement, while premium OEMs in Germany and Japan absorb customization premiums for express-up functionality.
Supply Chain Analysis
Inbound logistics costs through Shanghai-Ningbo port corridors and Yokohama container terminals feed into landed cost calculations for North American and European assembly plants. Manufacturing concentrates in China, Japan, and Germany, with cable-drum production anchored in Coburg and Aichi Prefecture motor winding operations. Supply chains draw from copper wire, neodymium magnets, and engineered polymer cable sheathing. Single-source vulnerability concentrates in Hall-effect sensor semiconductor fabrication. Distribution runs through Tier 1 module assembly plants serving just-in-sequence OEM vehicle production, with aftermarket channels fragmenting across VIN-matched e-commerce platforms and wholesale distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive power window regulator demand tracks vehicle production cycles with 12-18 month lag structures, positioning the market for recovery alignment as OEM platform refreshes accelerate EV architecture transitions.
For Market Incumbents: Compound backward integration into motor winding and cable-drive simulation capabilities to defend margin position against emerging Chinese module suppliers. Prioritize captive validation laboratory investment for MIIT GB standards compliance, creating certification barriers for non-integrated competitors. Channel control through OEM-certified collision repair partnerships protects aftermarket revenue streams from e-commerce platform disintermediation.
For New Entrants and Emerging Players: Lead with 48V architecture-compatible motor redesign capabilities targeting mild-hybrid platform procurement windows at domestic Chinese OEMs. White-space concentrates in India PLI scheme localized manufacturing for Maruti Suzuki and Hyundai Motor India supply chains. Go-to-market execution should anchor in Tamil Nadu or Maharashtra assembly partnerships with technical documentation support for BIS compliance pathways.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors electromechanical engineering specialists with Hall-effect sensing integration and software-defined vehicle body domain controller compatibility. Five-to-ten year viability rests on 48V migration completion and predictive maintenance revenue capture through over-the-air calibration infrastructure. Acquisition screening should prioritize suppliers with captive motor production and in-house cable-drive simulation. The inflection signal to watch is NHTSA rulemaking on enhanced anti-pinch sensitivity thresholds requiring multi-point sensor array adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| 48V Motor Architecture Redesign | Enables supply to mild-hybrid platforms at Toyota City and Wolfsburg OEMs. |
| MIIT GB Standards Validation Investment | Creates homologation barriers favoring established module suppliers with captive laboratories. |
| Hall-Effect Sensing Integration | Captures NHTSA Federal Motor Vehicle Safety Standard 118 compliance premiums. |
| India PLI Manufacturing Footprint | Localizes production for Maruti Suzuki and Hyundai Motor India procurement programs. |
| Software-Defined Vehicle Control Integration | Positions regulator systems within centralized body domain architectures at Denso and Brose. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of vehicle production databases, IHS Markit registration data, SEC filings, and customs trade records. Primary interviews engaged Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and dealership operations heads across Germany, China, Japan, and the United States. Secondary validation drew from NHTSA regulatory filings, MIIT GB standards documentation, and ECE R21 type approval records. Bottom-up segment sizing triangulated against top-down macroeconomic vehicle production forecasts.
Segmentation dimensions modeled span vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster across the analysis window. CAGRs derived from regression analysis of historical production volumes, technology substitution curves for electronic versus mechanical systems, and regulatory mandate implementation timelines. Industry-specific forecast inputs incorporated 48V electrical architecture migration pace and PLI scheme incentive utilization rates for Indian manufacturing expansion.
Forecasts assume regulatory continuity in NHTSA, ECE, and MIIT regimes; material policy shifts on anti-pinch sensitivity thresholds or GB standards durability testing would require re-modeling. Commodity price volatility in copper and rare-earth magnets, geopolitical disruption to East Asian manufacturing clusters, and faster-than-anticipated mechanical regulator substitution in emerging markets constitute specific risk factors. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Bulgaria Automotive Engine Oils Market
Automotive Parts
North America Automotive Actuators Market
Automotive Parts
Automotive Trailing Arm Market
Automotive Parts
Malaysia Passenger Vehicles Lubricants Market
Automotive Parts
North America Automotive AHSS Market
Automotive Parts
Power Steering Oil Market
Automotive Parts
Argentina Automotive Parts Aluminium Die Casting Market
Automotive Parts
Europe Commercial Vehicles Lubricants Market
Automotive Parts
Global Aerodynamic Automotive Market
Automotive Parts
Italy Automotive Hydraulic Actuators Market
Automotive Parts
Engine Oil Pan Market
Automotive Parts
X-Arm Type Window Regulator Market
Automotive Parts
UK Automotive Parts Zinc Die Casting Market
Automotive Parts
Global Automotive Gear Shift System Market
Automotive Parts
Automotive Variable Valve Timing Market
Automotive Parts
Automotive Air Lift Jack Market