
 Railway Connectors Market | 2026-2036
Railway Connectors Market Size, Share, and Industry Trends Forecast 2026-2036
Railway Connectors Market Analysis
Modular connector architectures with integrated fiber-optic and power transmission capabilities is reconfiguring how railway electrical systems are assembled and maintained. TE Connectivity leverages its broad portfolio across signaling and rolling stock applications to sustain engineering partnerships with major rail OEMs. Amphenol Corporation anchors its position through specialized harsh-environment designs that withstand vibration, temperature cycling, and electromagnetic interference in locomotive installations.
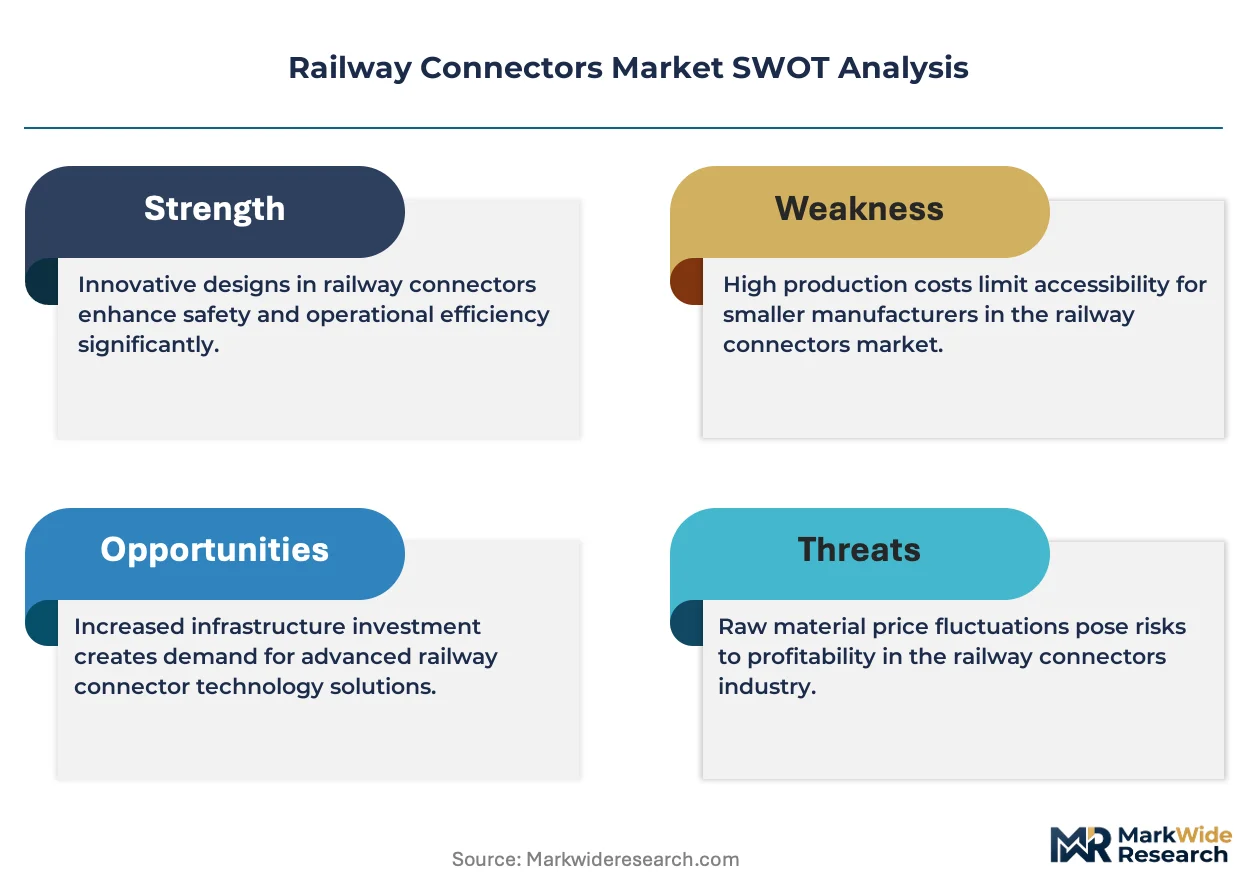
Railway connectors are electromechanical joining devices engineered to establish reliable electrical continuity between rail vehicle subsystems, typically rated for voltage ranges spanning 24V control circuits to 25kV traction power and manufactured with precision-machined copper alloy contacts in thermoplastic housings. Their primary purpose is to ensure safe, maintainable interconnection of power, data, and control pathways across rolling stock and trackside infrastructure under severe mechanical and environmental stress. Wire connectors and terminal blocks command the largest volume share as legacy rolling stock fleets require extensive replacement of degraded termination points during mid-life refurbishment cycles. Junction boxes represent a concentrated margin pool where manufacturers differentiate through IP67 sealing ratings and integrated cable management features that reduce installation labor for infrastructure contractors.
The Federal Railroad Administration enforces crashworthiness and fire safety standards that dictate connector housing materials and flame propagation limits for US passenger equipment, while the European Union's CE marking and EN 50155 railway standard mandate electromagnetic compatibility and environmental testing protocols that filter non-compliant suppliers from procurement lists. China's National Railway Administration implements GB standards for high-speed train electrical interfaces that align with domestic manufacturing capabilities and create localized specification ecosystems. Stakeholders must monitor how regional certification divergence affects component interchangeability as cross-border rail projects multiply and operators seek to unify spare parts inventories across multinational fleets.
Market Dynamics
High-speed rail electrification programs across Asia are compressing procurement cycles for signaling-grade connector assemblies while simultaneously tightening material specifications through evolving EN 50155 compliance requirements in Europe. This dual pressure from infrastructure expansion and regulatory harmonization is restructuring supplier qualification protocols and engineering partnership priorities across the value chain.
Growth Catalysts
- EN 50155 Compliance Mandates:European rolling stock electrification standards are filtering non-compliant suppliers from procurement lists and elevating certified component manufacturers into preferred vendor tiers for cross-border fleet projects.
- China's Intercity Network Expansion:State-backed infrastructure investment in high-speed rail corridors is generating concentrated demand for 25kV traction power connectors and fiber-optic signaling assemblies.
- Hybrid Fiber-Power Architectures:Modular connector designs integrating optical data transmission with copper power pathways are reducing installation complexity and maintenance downtime for infrastructure contractors.
Market Restraints
- Copper Alloy Price Volatility:Precision-machined contact materials constitute substantial input cost exposure, with rolling stock OEMs resisting pass-through pricing during multi-year tender cycles.
- Regional Certification Fragmentation:Divergent GB standards in China, EN frameworks in Europe, and FRA crashworthiness rules in the US create non-interchangeable specification ecosystems that fragment production scale economies.
- Silicon Carbide Traction Systems:Emerging wide-bandgap semiconductor architectures in next-generation locomotives are altering voltage isolation requirements and potentially obsoleting legacy connector form factors.
Strategic Opportunities
- India's Dedicated Freight Corridors:The country's freight rail electrification program under the Dedicated Freight Corridor Corporation is opening procurement windows for vibration-resistant junction box assemblies in harsh-environment installations.
- Digital Twin Integration:Connector manufacturers embedding sensor-enabled condition monitoring capabilities are capturing predictive maintenance budgets from operators unifying spare parts inventories across multinational fleets.
- EU Green Deal Procurement Incentives:Lifecycle carbon accounting requirements in European public rail tenders are favoring suppliers with recyclable thermoplastic housings and regionalized production footprints.
Industry Challenges
- Electromagnetic Compatibility Certification Timelines:Extended testing protocols for EN 50155 electromagnetic interference compliance are delaying product launches and compressing margin recovery windows.
- Legacy Fleet Interoperability:Mid-life refurbishment programs for aging rolling stock require backward-compatible connector interfaces that constrain design freedom for next-generation architectures.
- Precision Machining Talent Scarcity:Specialized copper alloy contact manufacturing expertise is concentrating among a narrowing base of European and Japanese tooling suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Railway Connectors Market |
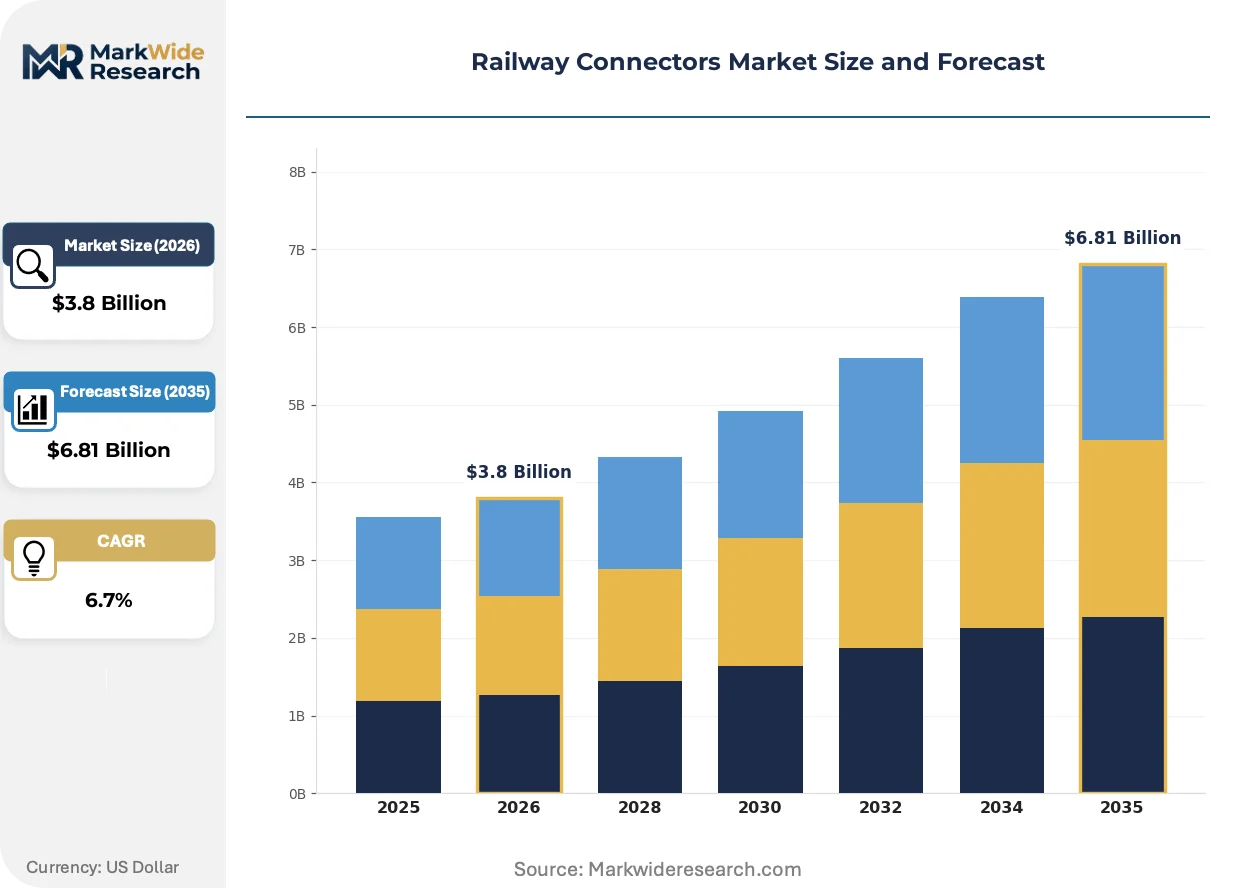
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wire Connectors, Terminal Blocks, Relays, Junction Boxes Material: Copper, Aluminum, Plastic, Steel Application: Rolling Stock, Signaling, Power Distribution, Communication End User: OEMs, Maintenance Providers, Infrastructure Companies, Railway Operators |
| Companies Covered | ITT, Fischer Connectors, TE Connectivity, Nexans, Harting Technology, Amphenol Corporation, Smiths Interconnect, Staubli Electrical Connectors, Molex Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Railway Connectors Market Emerging Trajectories
Active developments in connector architecture are compressing the boundary between power distribution and data transmission functions while regulatory bodies accelerate environmental and safety standard convergence. These forces are reconfiguring how rail OEMs evaluate supplier partnerships and technology roadmaps.
Hybrid fiber-optic and copper power connector assemblies are hybridizing traditional electrical interconnection paradigms by enabling simultaneous high-voltage traction and high-bandwidth signaling through single modular housings. Chinese high-speed rail operators are specifying these integrated designs for new intercity corridors to reduce cable routing complexity. The technology is hybridizing procurement categories that previously separated power and data subsystem vendors, forcing connector manufacturers to develop dual-competency engineering teams or risk disqualification from integrated tender packages.
REACH substance restrictions and RoHS material declarations in the European Union are compelling housing material transitions from halogenated flame retardants to phosphorus-based alternatives that maintain IP67 sealing ratings under thermal cycling. Connector manufacturers serving the European rolling stock market are reformulating thermoplastic compounds and resubmitting for EN 50155 fire propagation testing. Rolling stock OEMs in Germany and France are now requiring full material disclosure documentation upstream of component qualification, extending supplier onboarding timelines.
After-sales service unbundling is separating connector replacement from integrated maintenance contracts as rail operators seek to consolidate spare parts purchasing across heterogeneous fleets. Infrastructure contractors in China's state railway administration are negotiating direct component procurement agreements that bypass traditional rolling stock OEM distribution channels. This pattern is most visible in high-volume wire connector and terminal block categories where standardization enables inventory pooling across multiple operator fleets.
Railway Connectors Market Segmentation
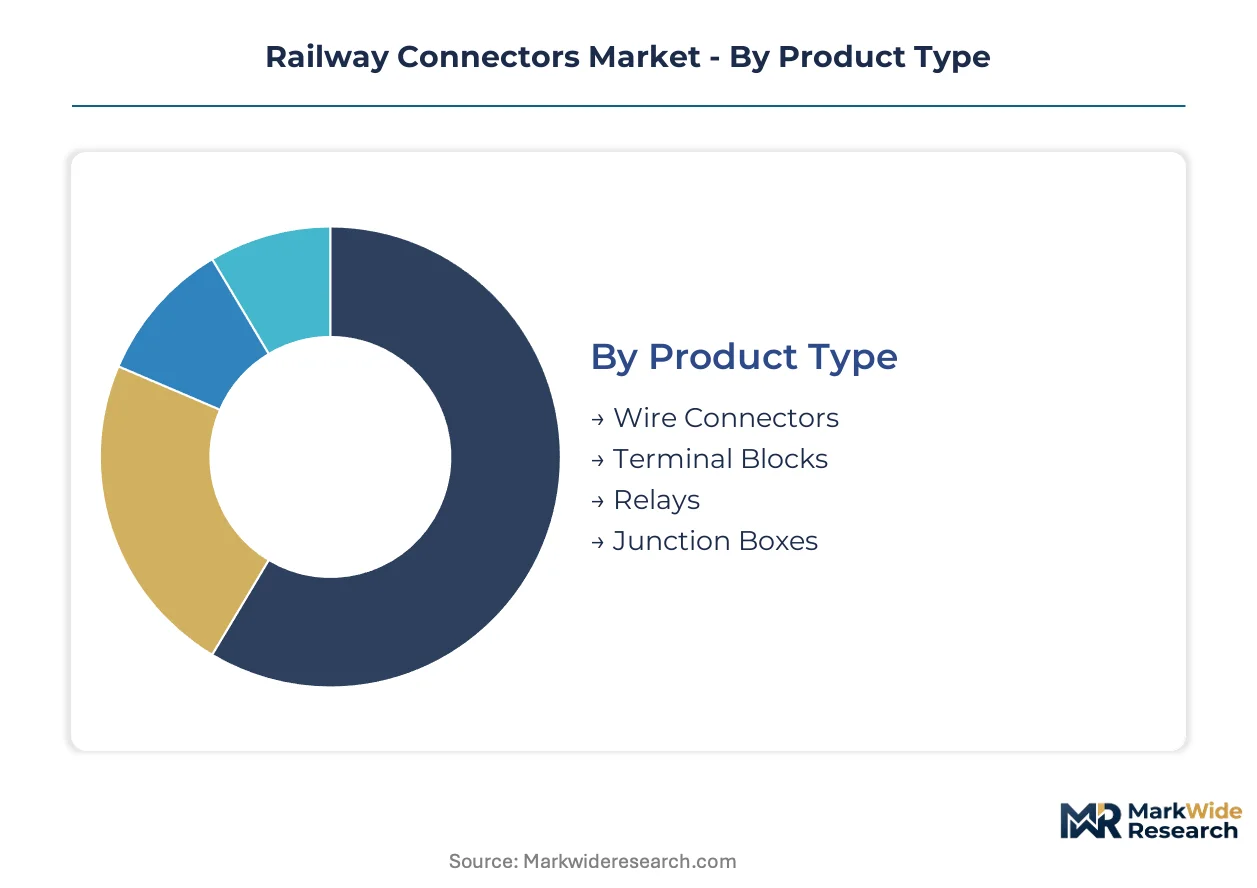
Railway connector procurement splits across multiple technical and commercial dimensions, with product architecture and material composition determining qualification pathways for distinct electrification and signaling applications. Understanding these segment boundaries clarifies where engineering requirements diverge and where standardization creates procurement scale.
Product Type:
Use-case spectrum spans legacy fleet refurbishment through next-generation high-speed rail electrification, with each connector family serving distinct voltage, current, and environmental specifications.
- Wire Connectors:Precision-crimped termination devices rated for 24V control circuits through 25kV traction power, utilizing machined copper alloy contacts in thermoplastic housings. Mid-life refurbishment cycles for aging rolling stock fleets in Germany and Japan concentrate replacement demand for degraded termination points, though rolling stock OEMs resist pass-through pricing on copper alloy inputs during multi-year tender cycles.
- Junction Boxes:IP67-sealed enclosures integrating cable management features and electromagnetic shielding for harsh-environment installations. Infrastructure contractors across China's state-backed intercity network specify these assemblies for reduced installation labor, with integrated fiber-optic and power transmission capabilities capturing procurement preference in new high-speed corridors.
- Terminal Blocks:Modular screw-clamp or spring-clamp connection systems for control panel and distribution board assemblies.
- Relays:Electromechanical switching devices isolating control circuits from power pathways in signaling and traction systems.
Established volume favors wire connectors; emerging adoption favors junction boxes.
Material:
Cost tier differentiation separates precision-machined conductive alloys from commodity structural materials, with regulatory compliance increasingly dictating housing compound selection.
- Copper:Oxygen-free high-conductivity alloy contacts delivering low electrical resistance and thermal stability across temperature cycling extremes. REACH substance restrictions and RoHS declarations in the European Union are compelling transitions from halogenated flame retardants to phosphorus-based thermoplastic alternatives, extending supplier onboarding timelines for EN 50155 fire propagation recertification.
- Plastic:Glass-filled polyamide and thermoplastic polyester housings providing dielectric isolation and mechanical protection. Chinese high-speed rail operators specify these compounds for weight reduction in new intercity corridors, while EU Green Deal procurement incentives favor recyclable formulations with regionalized production footprints.
- Aluminum:Lightweight conductive alloy for secondary power distribution and structural connector components.
- Steel:Galvanized or stainless enclosures for mechanical armor and electromagnetic shielding in severe vibration environments.
Copper commands premium positioning for traction power applications; plastic compounds gain share fastest in weight-sensitive rolling stock designs.
Application:
Customer type stratification distinguishes rolling stock OEM specifications from infrastructure contractor procurement, with signaling and power distribution representing divergent certification pathways.
- Rolling Stock:Onboard connector assemblies for locomotive, multiple-unit, and passenger car electrical systems. The Federal Railroad Administration enforces crashworthiness and fire safety standards dictating housing materials and flame propagation limits for US passenger equipment, filtering non-compliant suppliers from procurement lists.
- Signaling:Trackside and train-borne data transmission connectors for interlocking, automatic train protection, and traffic management systems. Hybrid fiber-optic and copper power assemblies are climbing the fastest as Chinese operators specify integrated designs to reduce cable routing complexity in new high-speed corridors.
- Power Distribution:Substations, catenary, and third-rail connection systems for traction energy delivery.
- Communication:Passenger information, Wi-Fi, and operational radio connector interfaces.
Rolling stock anchors current procurement volume; signaling applications show steepest expansion trajectory from digital rail modernization programs.
End User:
Supply concentration varies across OEM-integrated channels versus independent aftermarket procurement, with service unbundling reshaping traditional distribution relationships.
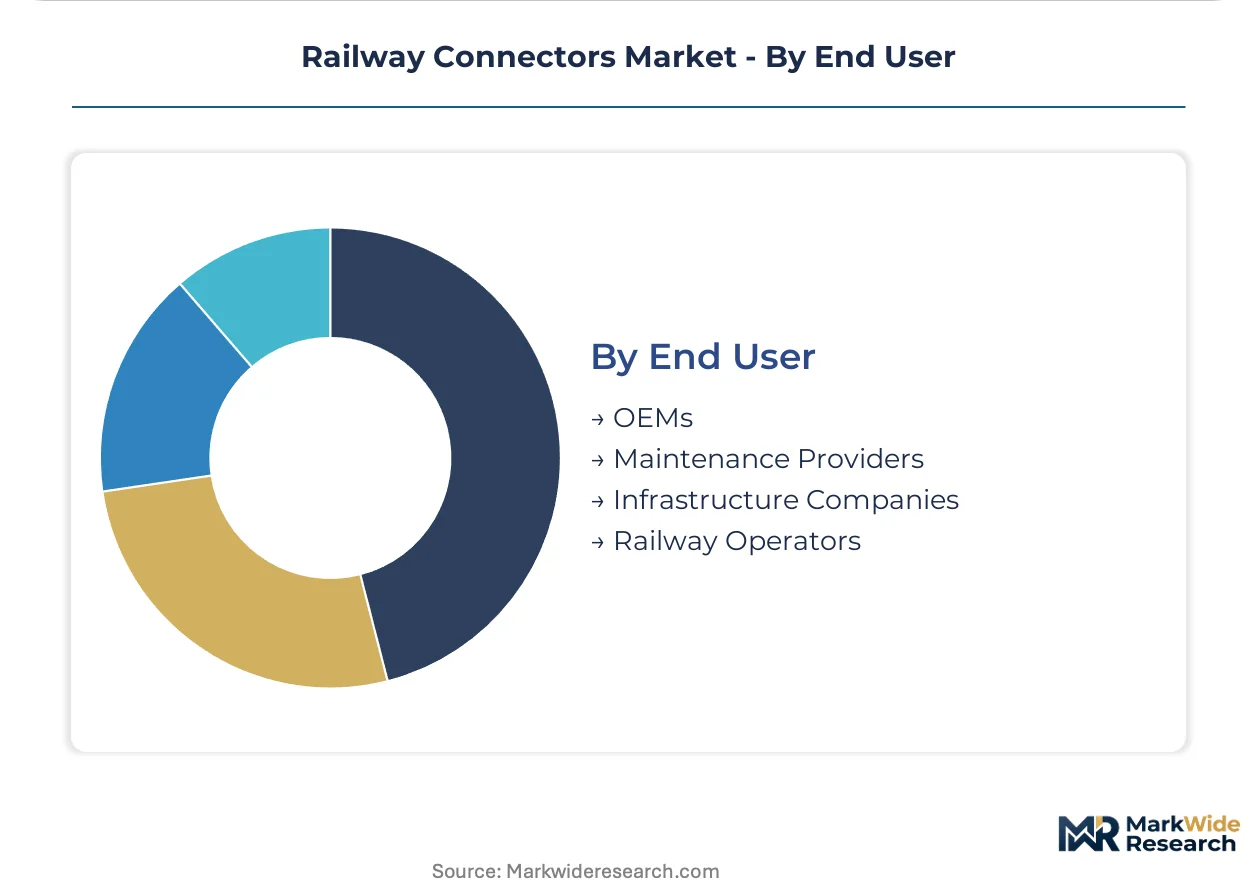
- OEMs:Rolling stock manufacturers integrating connector specifications into original equipment designs. TE Connectivity and Amphenol Corporation sustain engineering partnerships through specialized harsh-environment designs that withstand vibration, temperature cycling, and electromagnetic interference in locomotive installations.
- Infrastructure Companies:Trackside electrification and signaling contractors procuring directly for installation projects. China's state railway administration contractors negotiate direct component agreements bypassing traditional OEM distribution channels, most visible in high-volume wire connector categories enabling inventory pooling.
- Maintenance Providers:Independent service organizations executing mid-life refurbishment and component replacement.
- Railway Operators:Fleet owners consolidating spare parts purchasing across heterogeneous multinational inventories.
OEM channels dominate specification influence; infrastructure direct procurement expands fastest from state-backed electrification programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German connector manufacturers export precision-machined assemblies to China's expanding high-speed rail network, establishing the dominant trade corridor in this sector. This flow reflects Europe's engineering heritage meeting Asia's infrastructure investment intensity.
China
State-backed electrification of intercity corridors generates concentrated procurement for 25kV traction power connectors and fiber-optic signaling assemblies. The National Railway Administration enforces GB standards for high-speed train electrical interfaces that align with domestic manufacturing capabilities. CRRC Corporation clusters in Qingdao and Changchun specify integrated hybrid fiber-power designs for reduced cable routing complexity.
Germany
Rolling stock OEMs in Berlin and Munich drive demand for EN 50155-certified junction boxes with IP67 sealing ratings. The EU Green Deal procurement framework mandates lifecycle carbon accounting that favors recyclable thermoplastic housings. Siemens Mobility and Alstom Deutschland anchor engineering partnerships in Bavaria and Baden-Württemberg for next-generation locomotive installations.
United States
Freight rail electrification programs and passenger equipment refurbishment sustain demand for crashworthy connector housings. The Federal Railroad Administration enforces flame propagation limits that filter non-compliant suppliers from procurement lists. Wabtec Corporation and Progress Rail concentrate specification influence in Pennsylvania and Illinois manufacturing corridors.
India
The Dedicated Freight Corridor Corporation electrification program opens procurement windows for vibration-resistant assemblies in harsh-environment installations. Central Electricity Authority standards govern traction power distribution equipment qualification. Manufacturing activity clusters in Pune and Chennai where infrastructure contractors negotiate direct component agreements bypassing traditional OEM channels.
Japan
Shinkansen network modernization and export-oriented rolling stock production sustain precision connector demand. METI coordinates JIS standards alignment with international certification frameworks to preserve component interchangeability. Hitachi and Kawasaki Heavy Industries concentrate procurement specification in the Kanto and Kansai industrial belts.
Railway Connectors Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered supply relationships. Consolidated engineering partnerships with major rail OEMs define the upper tier, while mid-scale fabricators capture infrastructure direct procurement. Three archetypes dominate: broad-portfolio electrical component houses, harsh-environment specialists, and precision-machining contract manufacturers. Competitive moves center on EN 50155 certification acquisition and regional production footprint expansion to satisfy EU Green Deal carbon accounting requirements.
Within the broad-portfolio tier, TE Connectivity and Amphenol Corporation occupy positions sustaining engineering partnerships across signaling and rolling stock applications. TE Connectivity exemplifies the diversified electrical component house archetype with coverage spanning voltage ranges from control circuits through traction power. Amphenol Corporation anchors the harsh-environment specialist position through designs addressing vibration, temperature cycling, and electromagnetic interference. Harting Technology represents the precision-machining and modular architecture archetype with German engineering heritage concentrated in industrial connectivity systems.
| Leading Market Players |
|---|
| ITT |
| Fischer Connectors |
| TE Connectivity |
| Nexans |
| Harting Technology |
| Amphenol Corporation |
| Smiths Interconnect |
| Staubli Electrical Connectors |
| Molex Incorporated |
| Others |
Supply Flow & Price Mechanics
Copper alloy price volatility determines both pricing tier spreads and supply chain shape in railway connector procurement, with precision-machined contact materials constituting substantial input cost exposure that rolling stock OEMs resist passing through during multi-year tender cycles. This commodity risk compresses margin recovery windows while simultaneously filtering smaller fabricators from qualified supplier lists.
Pricing Analysis
Technology-generation pricing gaps separate legacy fleet refurbishment contracts from next-generation high-speed rail specifications, with EN 50155-certified junction boxes commanding substantial premiums over standard industrial-grade alternatives. Three-tier pricing structure across premium EN 50155-certified, mid-tier FRA-compliant, and economy non-certified levels reflects certification investment amortization and electromagnetic compatibility testing overhead. Cost compression in the economy tier is intensifying because infrastructure contractors in China negotiate direct component agreements bypassing traditional OEM distribution channels. Maintenance providers executing mid-life refurbishment programs exhibit highest price sensitivity due to budget constraints on aging rolling stock fleets, while rolling stock OEMs sourcing for new high-speed corridors prioritize qualification reliability over unit cost.
Supply Chain Analysis
Contract manufacturing concentration rests with German precision-machining specialists and Japanese tooling suppliers holding specialized copper alloy contact manufacturing expertise. Geographic supply concentration centers on Germany, China, and Japan, with Qingdao and Changchun clusters serving domestic Chinese high-speed rail demand while Bavarian and Baden-Württemberg facilities export EN 50155-certified assemblies. Raw material dependencies draw from Chilean copper concentrate, German engineering-grade thermoplastic compounds, and Japanese precision-machining equipment. Single-source vulnerability concentrates in European and Japanese tooling suppliers capable of EN 50155-compliant contact fabrication. Distribution runs through rolling stock OEM-integrated channels for original equipment, with infrastructure contractors increasingly negotiating direct procurement for high-volume wire connector categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Railway connector procurement constitutes a defensive-moat market where regulatory entrenchment through EN 50155, FRA, and GB certification requirements creates substantial barriers to supplier qualification and sustains incumbent positioning across multi-year tender cycles.
For Market Incumbents: Build certification moats by accelerating EN 50155 electromagnetic compatibility recertification for phosphorus-based thermoplastic housings ahead of REACH substance restriction deadlines. Deepen backward integration into precision-machined copper alloy contact manufacturing to offset single-source vulnerability from narrowing European and Japanese tooling supplier bases. Capture India's Dedicated Freight Corridor procurement windows through vibration-resistant junction box qualification under Central Electricity Authority standards before domestic fabricators achieve certification scale. For New Entrants and Emerging Players: India's freight electrification program under the Dedicated Freight Corridor Corporation offers the most penetrable geographic entry point, with infrastructure contractors negotiating direct component agreements that bypass entrenched OEM channel relationships. Target aftermarket maintenance provider segments for wire connector and terminal block categories where standardization enables inventory pooling across heterogeneous fleets. Pursue white-label manufacturing partnerships with established European precision-machining contract manufacturers to accelerate EN 50155 qualification timelines without captive tooling investment. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized harsh-environment design capabilities over broad-portfolio electrical component houses. Long-term viability over the next decade hinges on positioning for silicon carbide traction system voltage isolation requirements that may obsolete legacy connector form factors. Acquisition targets should demonstrate dual-competency engineering teams spanning fiber-optic and copper power pathways. Monitor CRRC Corporation procurement specification shifts toward integrated hybrid designs as the primary inflection indicator for technology-generation transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| EN 50155 Recertification Acceleration | Phosphorus-based thermoplastic qualification ahead of REACH deadlines preserves European market access for housing manufacturers. |
| Hybrid Fiber-Power Engineering Investment | Dual-competency teams capture integrated tender packages from Chinese high-speed rail operators specifying combined assemblies. |
| India Direct Procurement Channel Development | Infrastructure contractor relationships bypass OEM distribution concentration and access Dedicated Freight Corridor electrification budgets. |
| Precision Machining Capability Acquisition | Captive contact manufacturing reduces dependency on narrowing German and Japanese tooling supplier bases. |
| Digital Twin Sensor Integration | Condition monitoring capabilities capture predictive maintenance budgets from operators consolidating multinational spare parts inventories. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and rolling stock OEM procurement disclosures. Primary interviews engaged rolling stock platform engineers, infrastructure contractor procurement leads, EN 50155 certification laboratory directors, and maintenance provider fleet managers. Secondary validation drew from National Railway Administration GB standard publications, Federal Railroad Administration safety advisories, EU Green Deal procurement framework documentation, and Siemens Mobility and Alstom Deutschland engineering partnership announcements. Bottom-up segment sizing triangulated against top-down market aggregation across product type, material, application, and end-user dimensions.
Forecast inputs considered high-speed rail electrification program announcements, mid-life refurbishment cycle timing for aging European and Japanese fleets, and silicon carbide traction system adoption curves in next-generation locomotive architectures. Segmentation modeling spanned product architecture, material composition, customer type, and regional regulatory cluster variations. CAGRs derived from installation base expansion rates, replacement cycle frequencies, and average content per vehicle trajectories across voltage class specifications from 24V control circuits through 25kV traction power.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed domestic suppliers or silicon carbide semiconductor specialists would shift outcomes beyond projected ranges. Quarterly review of CRRC Corporation procurement specifications, EN 50155 certification timeline extensions, and copper alloy futures pricing is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway Transportation
Rail Fasteners Market
Railway Transportation
Global Train Communication Gateways Systems Market
Railway Transportation
High Speed Rail Coating Market
Railway Transportation
Global Rail Freight Transport Market
Railway Transportation
Railway Sleepers Market
Railway Transportation
Rail Gangways Market
Railway Transportation
Railway Li-Ion Battery Market
Railway Transportation
Digital Railway Market
Railway Transportation
United States Rail Freight Transport Market
Railway Transportation
Rail Testing Vehicle Market
Railway Transportation
Railway Station Lighting Market
Railway Transportation
Railroad Tank Car Market
Railway Transportation
Automatic Train Protection Signaling Market
Railway Transportation
Global Railway Wiring Harness Market
Railway Transportation
Rail Pads Market
Railway Transportation
Urban Rail Transit Market