
 Alternate Transportation Market | 2026-2036
Alternate Transportation Market Size, Share, and Industry Trends Forecast 2026-2036
Alternate Transportation Market Outlook
Subscription-based fleet management software is decoupling vehicle ownership from transportation access in metropolitan networks. Waymo leverages autonomous routing algorithms to sustain its technology leadership in driverless ride-hailing. Keolis anchors European public transit modernization through integrated mobility-as-a-service platforms. East Japan Railway Company dominates high-capacity rail corridors with precision-timed operations across dense urban corridors.
Alternate transportation encompasses vehicles, infrastructure, and services that operate outside conventional internal-combustion road networks, including battery electric drivetrains with lithium-ion cell packs rated above 400 watt-hours per kilogram and hydrogen fuel cell stacks producing 60-80 kilowatts for medium-duty deployment. The primary commercial purpose is reducing carbon intensity per passenger-mile while alleviating roadway congestion in dense population centers. Urban commuting and shared mobility applications command the largest volume pools, while last mile delivery segments register the fastest expansion as e-commerce fulfillment tightens delivery windows. Battery electric technology leads installed base, though hydrogen fuel cell systems capture premium margin pools in heavy-duty fleet conversions where range requirements exceed 500 kilometers.
The US EPA tailpipe standards and the EU Green Deal mobility benchmarks are tightening emission thresholds for urban fleet operators, forcing technology transitions before permit renewal cycles. China's MIIT new energy vehicle mandate and Japan's METI hydrogen roadmap are accelerating domestic manufacturing scale while restricting import market access for uncertified platforms. India's FAME subsidy framework and BIS charging standards are reshaping procurement specifications for government fleet tenders. Stakeholders must monitor regulatory divergence across certification regimes to avoid stranded asset risk in multi-country fleet deployments.
Market Dynamics
Battery chemistry advances above 400 watt-hours per kilogram are compressing range anxiety for electric fleets while hydrogen fuel cell stack costs decline toward parity for heavy-duty corridors over 500 kilometers.
Growth Catalysts
- EU Green Deal mobility benchmarks:Urban fleet operators across Germany, France, and the Netherlands face emission threshold tightening before permit renewal cycles, accelerating zero-emission procurement timelines.
- Last-mile delivery density:E-commerce fulfillment networks in Chinese metropolitan corridors are deploying electric cargo bikes and micro-fulfillment nodes to tighten delivery windows below two hours.
- Lithium-ion cell manufacturing:China's MIIT new energy vehicle mandate is scaling domestic gigafactory output while restricting import market access for uncertified battery platforms.
Market Restraints
- Charging infrastructure gap:Grid interconnection queues in India and Southeast Asian markets delay depot electrification for commercial fleets by 18-24 months.
- Hydrogen supply concentration:Steam methane reforming and electrolyzer manufacturing capacity clusters in Saudi Arabia and Qatar create import dependency for European fuel cell adopters.
- Certification fragmentation:Divergent UN ECE, EPA, and MIIT vehicle approval protocols force redundant testing cycles for multi-country fleet operators.
Strategic Opportunities
- India's FAME subsidy framework:Government fleet tenders in Maharashtra, Karnataka, and Tamil Nadu are reshaping procurement specifications toward domestic battery assembly requirements.
- Autonomous ride-hailing convergence:Integration of LiDAR perception stacks with electric drivetrains in Arizona and California test corridors enables driverless service scaling without union labor constraints.
- Rail-based mobility-as-a-service:Japan's METI hydrogen roadmap is funding fuel cell multiple-unit trains for non-electrified rural lines, opening captive demand for domestic stack manufacturers.
Industry Challenges
- High-voltage technician scarcity:Fleet maintenance networks lack certified personnel for 800-volt battery pack diagnostics and thermal runaway containment protocols.
- Legacy dispatch system integration:Proprietary APIs from incumbent taxi and logistics software vendors block real-time data flows into modern fleet optimization platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alternate Transportation Market |
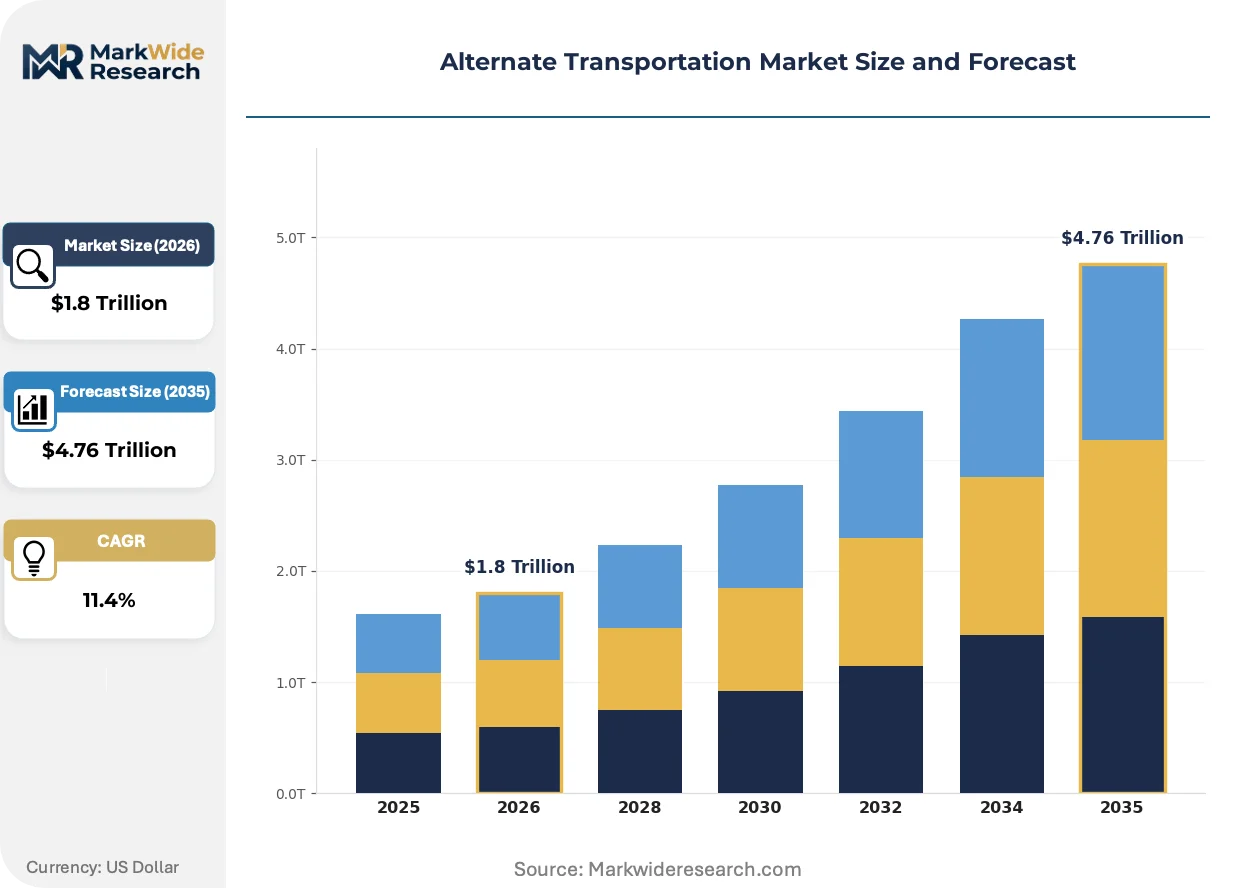
| Market Size in 2026 | $1.8 Trillion |
| Market Size in 2035 | $4.76 Trillion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Electric Bikes, E-Scooters, Hoverboards, Personal Rapid Transit Technology: Battery Electric, Hydrogen Fuel Cell, Ultracapacitor, Hybrid Systems Application: Urban Commuting, Last Mile Delivery, Leisure Activities, Shared Mobility End User: Individual Consumers, Ride-Sharing Services, Government Fleets, Corporate Clients |
| Companies Covered | Keolis, Transport for London, Waymo, Mass Transit Railway, East Japan Railway Company, Werner Enterprises, Transdev, Lineage Logistics, ArcBest, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alternate Transportation Market Strategic Shifts
Vehicle-grid integration protocols and solid-state battery prototyping are compressing total cost of ownership calculations for commercial operators while reshaping utility demand response programs.
Solid-state electrolyte architectures with lithium-metal anodes are decentralizing energy storage risk profiles for electric aviation and maritime applications. Regional carriers in Scandinavia and harbor ferry operators in British Columbia are piloting 300-kilowatt-hour packs for 50-nautical-mile routes. This chemistry transition is decentralizing supplier power away from incumbent cylindrical cell manufacturers toward solid-state specialists with ceramic processing expertise.
The US EPA tailpipe standards and California Air Resources Board fleet rules are mandating zero-emission sales quotas for commercial vehicle manufacturers. OEMs must secure battery supply agreements or face exclusion from state procurement pools. Medium-duty delivery van segments in the Northeast and Pacific Coast corridors are responding with dedicated BEV platform launches ahead of federal compliance deadlines.
Corporate fleet managers are unbundling vehicle ownership from mobility service contracts through subscription-based total cost per mile arrangements. Third-party fleet operators in Germany and the United Kingdom are displacing captive vehicle pools with guaranteed availability service levels. This consumption-pattern shift is most visible in pharmaceutical and technology sector headquarters relocations to transit-adjacent campuses.
Alternate Transportation Market Segmentation
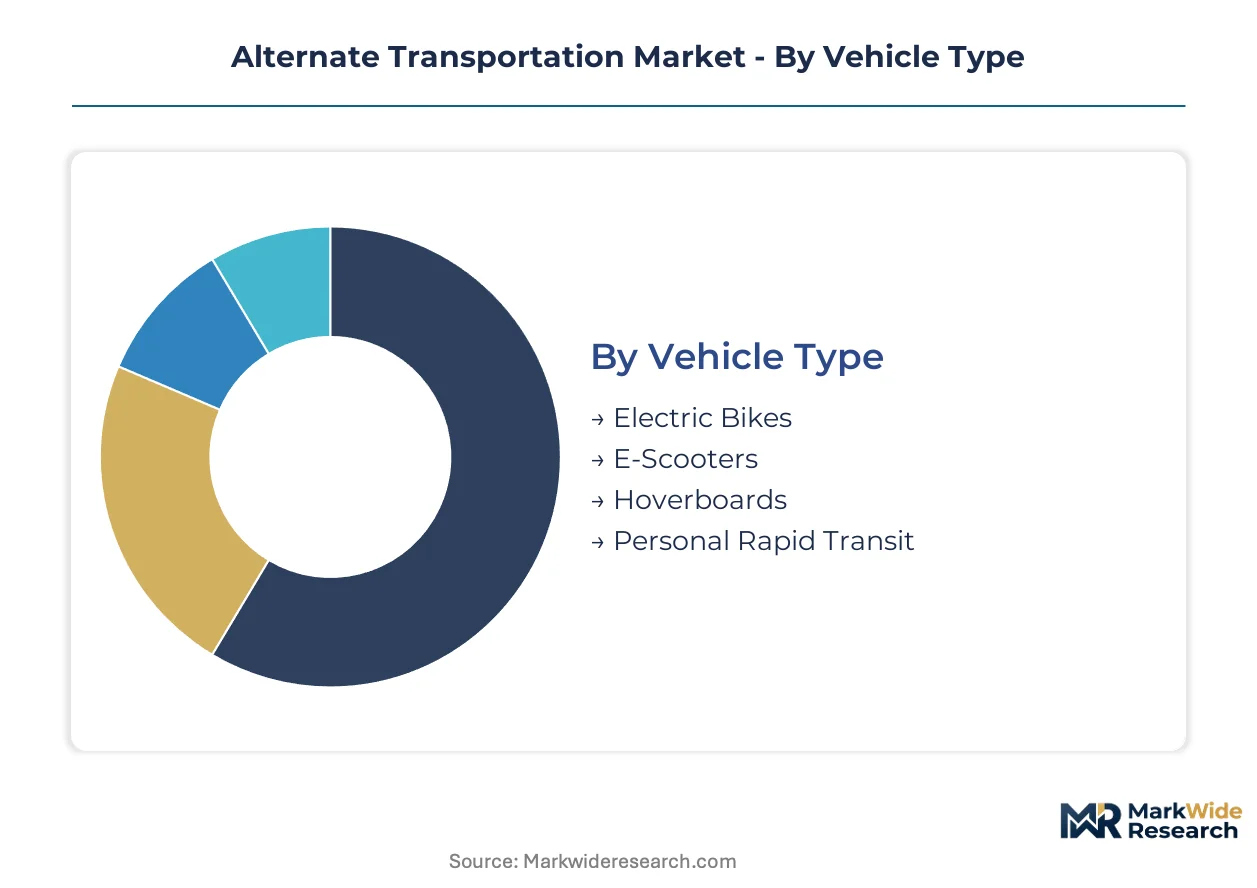
Segmentation reveals how technology transitions and user economics reshape procurement patterns across alternate transportation platforms. Fleet operators and individual adopters face divergent upgrade cycles depending on battery chemistry maturity and regulatory compliance windows.
Vehicle Type:
Replacement cycles compress as lithium-ion energy density improves and urban infrastructure adapts to micro-mobility formats.
- Electric Bikes:Lithium-ion cell packs integrated into frame-integrated or rack-mounted configurations dominate urban commuting corridors. Demand concentrates in Chinese metropolitan networks where MIIT certification requirements favor domestic manufacturers with established service networks.
- E-Scooters:Folding aluminum chassis with swappable battery architectures enable shared fleet operators to minimize downtime. European cities including Paris and Berlin impose weight and speed limits that favor lighter platforms with 25-kilometer-per-hour governors.
- Hoverboards:Self-balancing gyroscopic platforms with dual-hub motors serve recreational and short-distance applications. UL 2272 certification requirements in the US and equivalent BIS standards in India filter out uncertified imports.
- Personal Rapid Transit:Automated guideway vehicles operating on dedicated elevated or at-grade tracks connect airport terminals and campus networks. Installation concentrates in Saudi Arabia's NEOM development and Singapore's Jurong Lake District where greenfield construction permits dedicated right-of-way.
Volume placements concentrate in Electric Bikes; the faster expansion belongs to Personal Rapid Transit.
Technology:
Cost tier differentiation separates established chemistries from emerging architectures still scaling manufacturing yield.
- Battery Electric:Lithium-ion cell configurations with nickel-manganese-cobalt or lithium-iron-phosphate cathodes deliver 400-plus watt-hours per kilogram in premium automotive formats. China's gigafactory clusters supply global demand while MIIT domestic content rules restrict import market access.
- Hydrogen Fuel Cell:Proton-exchange-membrane stacks producing 60-80 kilowatts power medium-duty fleet conversions where range requirements exceed 500 kilometers. Japan's METI hydrogen roadmap funds domestic stack manufacturing for captive rail and bus deployments.
- Ultracapacitor:Graphene-enhanced electric double-layer capacitors enable rapid charge-discharge cycles for kinetic energy recovery in stop-start urban routes. Deployment concentrates in Chinese bus fleets with overhead opportunity charging infrastructure.
- Hybrid Systems:Combined battery-ultracapacitor architectures optimize power density and energy density for variable-duty cycles. European manufacturers leverage EU Green Deal procurement preferences for transitional zero-emission platforms.
Volume placements concentrate in Battery Electric; Hybrid Systems are climbing the fastest as fleet operators manage transition risk.
Application:
Customer type determines performance specifications and total-cost-per-mile calculations across deployment scenarios.
- Urban Commuting:First-last mile connectivity solutions integrating with fixed-route transit reduce single-occupancy vehicle dependency. Subscription-based fleet services in Germany and the Netherlands displace captive vehicle ownership among pharmaceutical and technology sector employees.
- Last Mile Delivery:Electric cargo bikes and micro-fulfillment nodes tighten delivery windows below two hours in Chinese e-commerce corridors. Grid interconnection queues in India delay depot electrification for commercial fleets by 18-24 months.
- Leisure Activities:Recreational electric bikes and personal watercraft serve tourism and outdoor recreation markets. Seasonal demand patterns in Scandinavian markets and Alpine regions create utilization challenges for rental operators.
- Shared Mobility:Dockless and station-based systems with GPS-locked parking enforcement reduce sidewalk clutter. Waymo's autonomous routing algorithms in Arizona and California test corridors enable driverless service scaling without union labor constraints.
Volume placements concentrate in Urban Commuting; Last Mile Delivery is gaining share fastest as fulfillment networks densify.
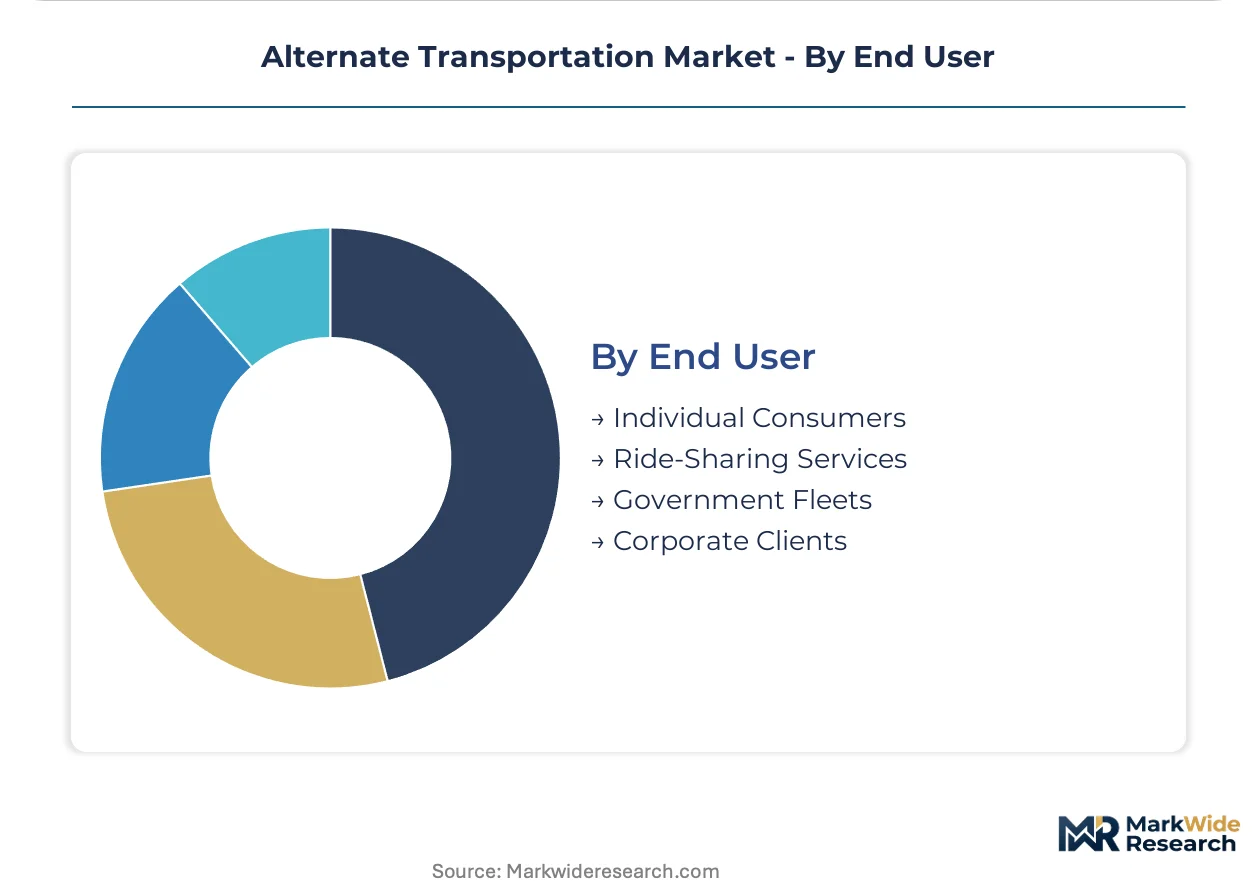
End User:
Procurement authority and compliance obligations segment demand across consumer, commercial, and institutional buyers.
- Individual Consumers:Direct-to-channel purchases driven by fuel cost avoidance and parking convenience in dense metropolitan cores. India's FAME subsidy framework reduces upfront acquisition cost for certified domestic assembly.
- Ride-Sharing Services:Fleet-scale procurement with guaranteed availability service levels and predictive maintenance contracts. Keolis anchors European public transit modernization through integrated mobility-as-a-service platforms.
- Government Fleets:Tender-based procurement with domestic content requirements and emission threshold compliance. US EPA tailpipe standards and California Air Resources Board fleet rules mandate zero-emission sales quotas for commercial vehicle manufacturers.
- Corporate Clients:Total-cost-per-mile arrangements unbundling vehicle ownership from mobility service delivery. Third-party fleet operators in the United Kingdom displace captive vehicle pools with subscription-based availability guarantees.
Volume placements concentrate in Individual Consumers; Government Fleets show the steepest expansion trajectory as procurement mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the dominant share of battery cell capacity while the United States and Germany absorb premium fleet deployments. Japan and India concentrate hydrogen infrastructure pilots and subsidy-driven procurement respectively.
China
MIIT certification requirements and domestic gigafactory clusters concentrate lithium-ion output in the Yangtze River Delta. The MIIT new energy vehicle mandate restricts import market access for uncertified battery platforms. Shenzhen and Shanghai metropolitan corridors deploy electric cargo bikes and micro-fulfillment nodes for sub-two-hour delivery windows.
United States
EPA tailpipe standards and California Air Resources Board fleet rules mandate zero-emission sales quotas for commercial vehicle manufacturers. The IRA production tax credits accelerate domestic battery assembly investments. Arizona and California test corridors host autonomous ride-hailing pilots integrating LiDAR perception with electric drivetrains.
Germany
EU Green Deal mobility benchmarks tighten emission thresholds before urban fleet permit renewals. The KBA administers vehicle approval protocols that diverge from UN ECE standards. Rhine-Ruhr and Bavarian logistics hubs displace captive vehicle pools with subscription-based total cost per mile arrangements.
Japan
METI hydrogen roadmap funding accelerates domestic stack manufacturing for captive rail deployments. The country's national railway regulator oversees fuel cell multiple-unit trains for non-electrified rural lines. Nagoya and Osaka manufacturing clusters produce proton-exchange-membrane stacks rated 60-80 kilowatts for medium-duty conversions.
India
FAME subsidy frameworks reshape government fleet tender specifications toward domestic battery assembly. BIS charging standards delay depot electrification through grid interconnection queues. Maharashtra, Karnataka, and Tamil Nadu state tenders concentrate procurement authority for certified electric two-wheeler and three-wheeler platforms.
Alternate Transportation Market Competitive Environment
Capital-heavy rail operators compete with asset-light mobility-as-a-service platforms for corridor control. The market structures around three tiers: integrated public transit authorities with dedicated infrastructure, autonomous technology developers with algorithmic routing advantages, and third-party fleet operators unbundling ownership from service delivery. Dominant competitive moves include strategic partnerships between battery manufacturers and transit agencies, plus geographic expansion of subscription-based availability guarantees into pharmaceutical and technology sector campuses.
Within the integrated public transit tier, Keolis and East Japan Railway Company exemplify asset-heavy operators with precision-timed corridor dominance. Waymo occupies a position among autonomous technology developers leveraging driverless routing without union labor constraints. These three entities represent divergent archetypes: European mobility-as-a-service integration, Asian high-capacity rail operations, and North American algorithmic ride-hailing scale.
| Leading Market Players |
|---|
| Keolis |
| Transport for London |
| Waymo |
| Mass Transit Railway |
| East Japan Railway Company |
| Werner Enterprises |
| Transdev |
| Lineage Logistics |
| ArcBest |
| Others |
Value Chain & Pricing Dynamics
Certified high-voltage technician scarcity in Germany's Rhine-Ruhr corridor widens pricing-tier spreads between premium service-bundled fleets and bare-metal procurement contracts. Labor-cost differentials between European maintenance networks and Chinese assembly hubs force tiered contract structures that reflect technician certification premiums rather than hardware margins alone.
Pricing Analysis
Margin tightening in subscription-based fleet contracts reflects lithium-ion cell price volatility and domestic content mandates from China's MIIT. Three-tier pricing structure across premium, standard, and economy levels separates guaranteed-availability service tiers from depreciated asset pools. Price differentiation hinges on battery chemistry certification and after-sales thermal-runaway containment protocols. Government fleet tenders in India and Germany show highest price sensitivity; corporate campus mobility services absorb premium tiers for uptime guarantees.
Supply Chain Analysis
Dual-sourcing requirements from European fleet operators mandate qualified cell suppliers across China, South Korea, and emerging domestic assembly in Germany. Raw material dependencies center on lithium carbonate from Chile, nickel matte from Indonesia, and cobalt hydroxide from the DRC. Single-source vulnerability concentrates in ceramic-coated separator membranes where Japanese suppliers dominate. Distribution runs through regional gigafactory clusters with direct OEM offtake agreements displacing spot-market procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The alternate transportation sector occupies a technology-transition phase where battery electric drivetrains displace hydrogen fuel cell systems in medium-duty segments below 500-kilometer range thresholds.
For Market Incumbents: Acquire solid-state battery specialists with ceramic processing expertise before chemistry transitions strand cylindrical cell manufacturing assets. Secure captive lithium supply through offtake agreements with Chilean and Australian producers to defend against price volatility from China's MIIT export restrictions. Reinforce technician certification pipelines with 800-volt diagnostic training partnerships in Germany and the United States. For New Entrants and Emerging Players: The mid-tier price-point gap between Waymo's autonomous premium service and unbranded electric bike subscriptions opens white-space in corporate campus mobility. Target pharmaceutical and technology sector headquarters relocations in the Netherlands and Bavaria with guaranteed-availability contracts. Deploy subscription-based total-cost-per-mile arrangements that displace captive vehicle pools without upfront capital requirements. For Investors and Strategic Acquirers: Re-rating potential sits with hydrogen fuel cell stack manufacturers serving Japan's METI-funded rural rail deployments given captive demand insulation from battery-electric competition. Long-term viability favors specialists with proton-exchange-membrane manufacturing in Nagoya and Osaka clusters. Watch for MIIT relaxation of domestic content rules as the inflection signal for cross-border consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures lithium-ion cell allocation from Yangtze River Delta gigafactories for fleet-scale deployment. |
| Charging Infrastructure Partnership | Resolves grid interconnection delays in India and Southeast Asian depot electrification programs. |
| Autonomous Platform Integration | Combines LiDAR perception stacks with electric drivetrains in Arizona and California test corridors. |
| Technician Certification Program | Addresses 800-volt diagnostic scarcity through KBA-aligned training in German maintenance networks. |
| Hydrogen Stack Manufacturing Scale-Up | Captures METI roadmap funding for fuel cell multiple-unit trains on non-electrified rural lines. |
Study Parameters
Document review covered SEC filings from fleet operators and battery manufacturers, EU Green Deal regulatory texts, and MIIT certification databases, complemented by interviews with fleet procurement managers, high-voltage maintenance technicians, and mobility-as-a-service platform engineers. Secondary validation drew from EPA tailpipe standard dockets, Japan's METI hydrogen roadmap publications, and India's FAME subsidy tender records. Bottom-up unit economics triangulated against top-down market sizing from vehicle registration data.
Segment-level outputs across vehicle type, technology architecture, and end-user procurement authority were modeled over the projection horizon. CAGRs derived from logistic diffusion curves fitted to battery energy density improvement trajectories and regulatory compliance deadline clustering. Industry-specific inputs included lithium-ion cell manufacturing yield curves and hydrogen electrolyzer capacity buildout schedules.
Underlying measurement precision varies by segment; battery electric vehicle deployments carry tighter precision than hydrogen fuel cell pilot programs with limited commercial traction. Forecasts reflect assumptions on MIIT certification continuity and EU Green Deal enforcement intensity across German and French permit cycles. Deviation in solid-state battery prototyping timelines or IRA production tax credit renewal would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Car Sharing Market
Smart Transportation Solutions
Shared Mobility Market
Smart Transportation Solutions
Intelligent Traffic Management Market
Smart Transportation Solutions
Fleet Management Software Market
Smart Transportation Solutions
Monorail System Market
Smart Transportation Solutions
Smart Car Digital Key System Market
Smart Transportation Solutions
Transportation for Smart Cities Market
Smart Transportation Solutions
5G in Automotive and Smart Transportation Market
Smart Transportation Solutions
Smart Fleet Management Market
Smart Transportation Solutions
Europe Car Parking Market
Smart Transportation Solutions
Traffic Signal Controller Market
Smart Transportation Solutions
Automated Robotic Parking System Market
Smart Transportation Solutions
Fleet Management Solution Market
Smart Transportation Solutions
US Smart Highway Market
Smart Transportation Solutions
Smart Car Tracking Systems Market
Smart Transportation Solutions
Asia-Pacific Smart Transportation Market