
 Argentina Automotive EPS Market | 2026-2036
Argentina Automotive EPS Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Automotive EPS Market Outlook
Modular steering rack packaging is expanding buyer choice across Argentina's automotive supply base. JTEKT Corporation leverages its regional manufacturing footprint to serve OEM assembly lines in Córdoba province. Robert Bosch GmbH anchors its position through integrated sensor-steering modules that reduce installation complexity for local tier-one suppliers. Denso Corporation competes on thermal management integration, bundling EPS controllers with power electronics to capture share among electric vehicle programs.
Argentina Automotive EPS refers to electrically powered steering assistance systems that replace hydraulic pumps with brushless DC motors, typically operating at 12V or 48V and delivering torque outputs from 30 Nm to 80 Nm depending on vehicle class. These systems reduce parasitic engine load and enable advanced driver assistance functions such as lane-keeping and automated parking. Rack-assist configurations command the largest installed base among passenger vehicles due to packaging efficiency in front-wheel-drive platforms, while column-assist systems retain cost advantages in entry-level commercial vehicle segments. Electric technology within the technology dimension outpaces hydraulic alternatives as OEMs phase out belt-driven pumps to meet corporate average fuel economy targets.
Argentina's national automotive regulator enforces safety and emissions standards that directly mandate EPS compatibility with electronic stability control systems. The country's central bank and industry ministry coordinate import-substitution incentives that condition market access on local content thresholds for steering system assemblies. Stakeholders must monitor regulatory alignment between Mercosur technical standards and evolving UN ECE braking-steering harmonization protocols to sustain product certification validity.
Market Dynamics
Argentina's transport ministry is tightening fuel-efficiency mandates that compel OEMs to eliminate hydraulic steering pumps from new vehicle platforms. This regulatory pressure is compressing the transition timeline for electrically powered steering architectures across Buenos Aires and Córdoba assembly corridors.
Growth Catalysts
- Mercosur Technical Standards Alignment:Harmonization protocols between Argentine and Brazilian automotive regulators are streamlining cross-border component certification. EPS suppliers gain scale economies serving integrated regional supply chains.
- 48V Mild-Hybrid Architectures:Rising penetration of belt-integrated starter-generator systems in Córdoba-produced vehicles creates electrical infrastructure that supports higher-voltage EPS motors without dedicated power electronics redesign.
- Pampas Industrial Corridor Concentration:Geographic clustering of electric vehicle assemblers around Rosario generates localized demand density. Tier-one suppliers reduce logistics costs serving multiple OEMs within 150-kilometer radii.
Market Restraints
- Brushless DC Motor Magnet Supply:Rare-earth element price volatility constrains cost predictability for torque motors. Argentine manufacturers lack upstream control over neodymium supply chains concentrated in Asian processing facilities.
- Import-Substitution Localization Thresholds:Central bank conditioning of market access on local content minimums creates compliance friction. Steering system assemblers must reconfigure supplier bases to meet evolving domestic value-added requirements.
- Hydraulic Remnant Fleet Inertia:Commercial vehicle operators in peripheral provinces maintain belt-driven pump inventories. Service network density for EPS diagnostics remains insufficient outside Buenos Aires metropolitan zones.
Strategic Opportunities
- Mendoza and Tucumán Peripheral Markets:Underpenetrated provincial fleets present conversion potential as national fuel-economy enforcement extends beyond industrial corridors. Regional distributors can capture first-mover advantage establishing EPS service capabilities.
- ADAS Integration Bundling:Lane-keeping and automated parking functionality convergence with base steering hardware creates premium tier differentiation. OEMs monetize software-enabled features through subscription architectures layered on physical EPS platforms.
- Remanufacturing Channel Development:Independent aftermarket operators currently lack authorized access to controller recalibration tools. Partnership frameworks with original equipment suppliers unlock circular economy revenue streams for electronic steering modules.
Industry Challenges
- Embedded Software Validation Timelines:Functional safety certification under ISO 26262 extends development cycles. Argentine engineering teams face capability gaps in automotive cybersecurity assessment protocols.
- Legacy Hydraulic Technician Retraining:Provincial service networks require reskilling investments to diagnose CAN-bus integrated steering faults. Workforce transition costs concentrate on smaller independent repair operations.
- Tier-One Supplier Integration Complexity:Multi-source controller procurement from international module manufacturers creates firmware version fragmentation. Vehicle assemblers manage compatibility matrices across simultaneous production programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Automotive EPS Market |
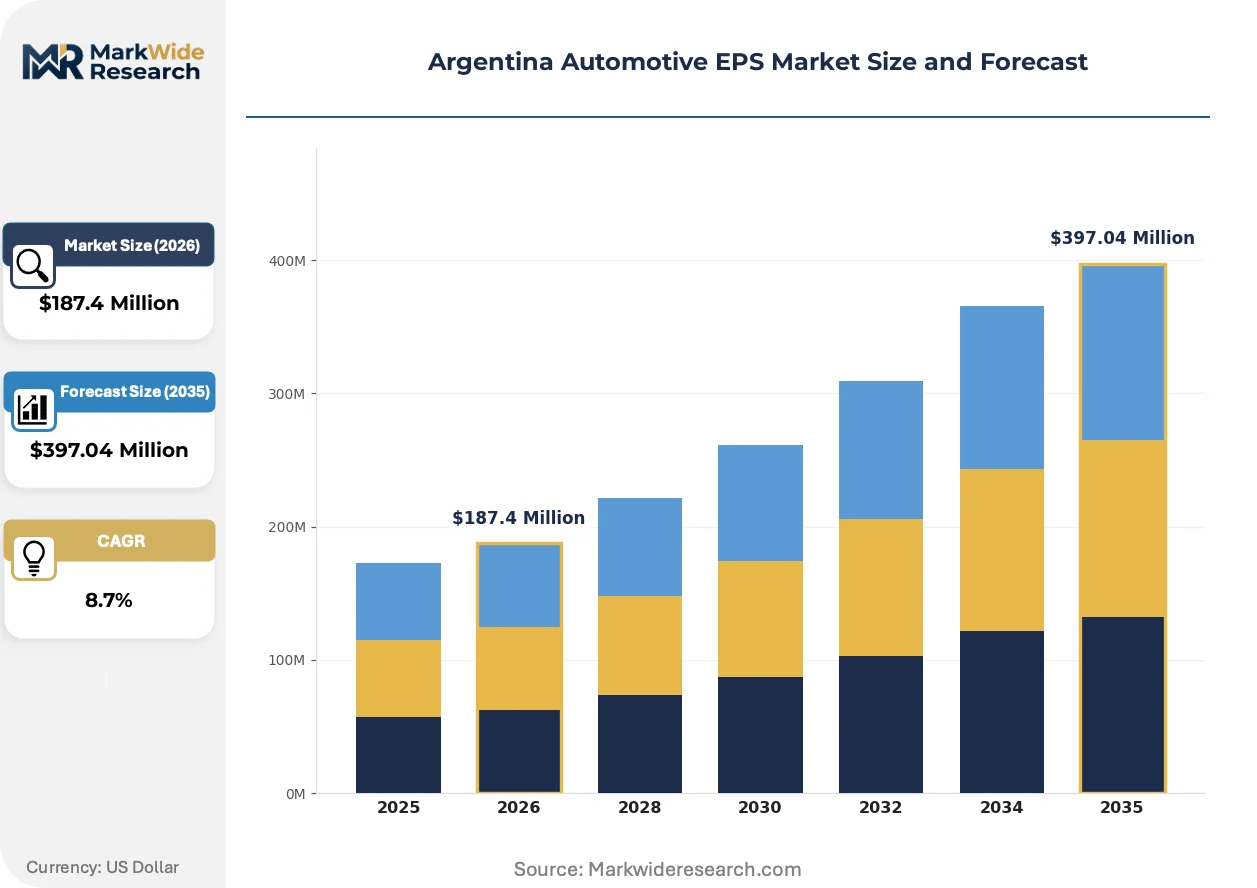
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Column Assist, Rack Assist, Direct Drive, Others End User: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, SUVs Technology: Hybrid, Electric, Hydraulic, Mechanical Application: Steering Systems, Safety Systems, Driver Assistance, Comfort Features |
| Companies Covered | JTEKT Corporation, Denso Corporation, ZF Friedrichshafen AG, NSK Ltd, Nexteer Automotive, Robert Bosch GmbH, Mitsubishi Electric Corporation, GKN PLC, Hubei Henglong Auto System Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Automotive EPS Market Strategic Shifts
Modular rack-assist packaging architectures are compressing installation complexity while enabling platform-scale standardization across front-wheel-drive vehicle families. Three developments are actively restructuring competitive positioning and procurement patterns.
Dual-pinion rack-assist configurations are consolidating technical preference among Buenos Aires-based passenger vehicle manufacturers. These systems split torque application across two pinion gears, reducing individual component stress while maintaining packaging efficiency in compact engine bays. Tier-one suppliers standardize on this topology to serve multiple OEM programs with minimal tooling variation.
Argentina's national automotive regulator is mandating electronic stability control interoperability as a precondition for type approval. This policy compresses hydraulic steering system viability since mechanical pump architectures cannot deliver the millisecond-latency torque adjustments required for integrated chassis control. Electric vehicle programs in the Pampas corridor respond by specifying sensor-integrated steering modules from inception.
Fleet procurement officers are unbundling steering hardware from traditional powertrain sourcing agreements. Large rental and corporate fleet operators in Córdoba province now negotiate direct controller calibration service contracts with electronics specialists, bypassing legacy tier-one distribution channels. This disintermediation concentrates price transparency pressure on established supply chain intermediaries.
Argentina Automotive EPS Market Segmentation
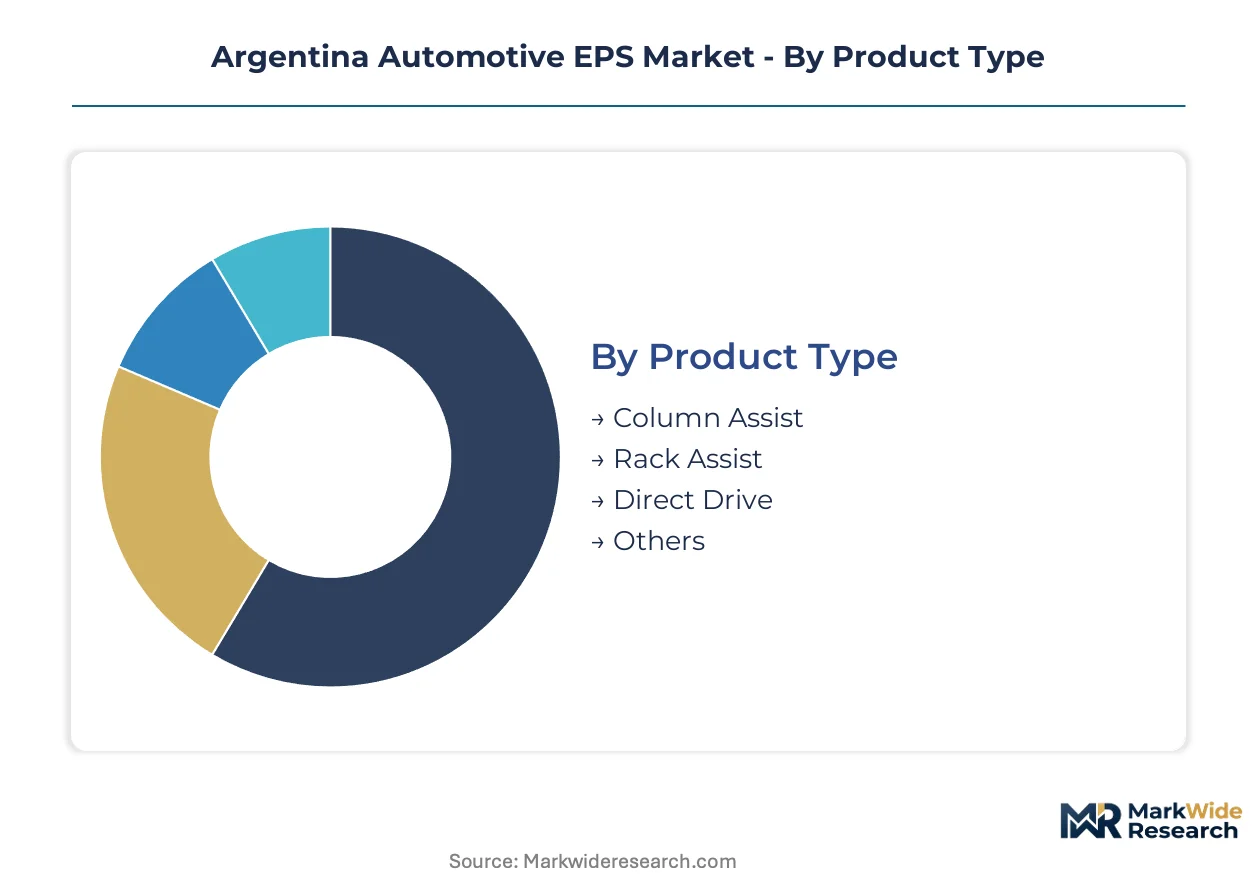
Argentina's automotive EPS market fragments across four structural dimensions that determine procurement patterns and supplier economics. Each segmentation layer reveals distinct capital requirements, regulatory exposure, and customer concentration profiles that shape competitive strategy in Buenos Aires and Córdoba assembly corridors.
Product Type:
Rack-assist configurations demand the heaviest upfront tooling investment due to precision rack-and-pinion machining requirements and integrated housing castings.
- Rack Assist:Torque delivery occurs through a motor-driven pinion engaging the steering rack directly, enabling precise torque vectoring for electronic stability control integration. Passenger vehicle assemblers in Córdoba province specify this topology for front-wheel-drive platforms where packaging density matters. The configuration commands premium pricing but reduces per-vehicle installation labor.
- Column Assist:Brushless DC motors mount atop the steering column, delivering assistance through intermediate shafts. Entry-level commercial vehicle manufacturers in peripheral provinces favor this architecture for its lower bill-of-materials cost and simpler service access. Column-assist systems retain viability where hydraulic pump inventories still dominate aftermarket channels.
- Direct Drive:Eliminates mechanical linkage entirely through hub-mounted actuators.
- Others:Includes pinion-assist variants and emerging steer-by-wire prototypes.
Rack-assist absorbs the bulk of installed capacity; direct drive is expanding most quickly among electric vehicle programs.
End User:
Customer segmentation reflects divergent procurement sophistication, with fleet operators negotiating service-level agreements that individual retail buyers cannot match.
- Passenger Vehicles:Volume concentration in Buenos Aires metropolitan assembly plants drives platform standardization. OEMs specify EPS modules with integrated torque sensors and CAN-bus interfaces to support lane-keeping assist as standard equipment. Argentina's transport ministry fuel-efficiency mandates accelerate hydraulic phase-out in this segment.
- Electric Vehicles:48V electrical architectures in Pampas corridor production enable higher-torque EPS motors without dedicated voltage conversion. Battery-electric platforms demand steering systems with minimal parasitic draw to preserve range. Start-up assemblers around Rosario source controller-integrated modules from tier-one electronics specialists.
- Commercial Vehicles:Fleet operators in Mendoza and Tucumán maintain hydraulic pump inventories.
- SUVs:Higher curb weights demand elevated torque outputs from 80 Nm-class motors.
Passenger vehicles anchor production volume; electric vehicles are climbing the fastest as OEMs retool for battery platforms.
Technology:
Powertrain electrification intensity separates segments by margin structure and regulatory compliance burden.
- Electric:Brushless DC motors operating at 12V or 48V replace belt-driven pumps entirely, eliminating parasitic engine load. Buenos Aires-based passenger vehicle manufacturers specify electric EPS exclusively for new platforms to meet corporate average fuel economy targets. The technology enables millisecond-latency torque adjustments required for electronic stability control interoperability.
- Hybrid:Combines electric assistance with residual hydraulic backup for fail-safe redundancy.
- Hydraulic:Belt-driven power steering pumps persist in commercial vehicle segments.
- Mechanical:Unassisted steering retains niche presence in ultra-light vehicles.
Electric technology captures the dominant share of new platform engineering; hybrid systems serve transitional architectures.
Application:
Functional integration depth determines software validation complexity and supplier qualification timelines.
- Steering Systems:Core torque assistance functionality with base position sensing. All EPS modules deliver this capability, with differentiation emerging from motor efficiency and packaging density. Córdoba assembly lines standardize on rack-assist configurations for this primary application.
- Driver Assistance:Lane-keeping and automated parking require torque overlay capabilities and high-resolution steering angle sensing. OEMs monetize these features through subscription architectures layered on base hardware. Firmware development cycles extend qualification timelines for suppliers targeting this tier.
- Safety Systems:Electronic stability control integration mandates specific torque response latency.
- Comfort Features:Variable effort programming and active return-to-center functionality.
Steering systems represent the foundational application; driver assistance features are gaining share fastest through software-enabled monetization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Argentina's automotive EPS production concentrates in Buenos Aires and Córdoba provinces while provincial fleet operators in Mendoza and Tucumán lag in adoption. This geographic split shapes supplier logistics and service network deployment.
Buenos Aires Province
Passenger vehicle assembly plants in this province drive rack-assist EPS specification for front-wheel-drive platforms. Argentina's transport ministry enforces fuel-efficiency mandates that accelerate hydraulic steering phase-out. Industrial corridors around La Matanza and Tigre concentrate tier-one supplier warehousing to serve multiple OEM lines.
Córdoba Province
48V mild-hybrid vehicle production here creates electrical infrastructure supporting higher-voltage EPS motors without dedicated power conversion. The central bank conditions import-substitution incentives on local content thresholds for steering assemblies. Assembly clusters around Córdoba city and Villa María attract controller-integrated module sourcing from electronics specialists.
Mendoza Province
Commercial vehicle fleets in this western province maintain hydraulic pump inventories due to limited EPS service network density. National fuel-economy enforcement has not yet penetrated peripheral markets with equivalent pressure. Regional distributors face first-mover opportunity costs establishing diagnostic capabilities for CAN-bus integrated steering faults.
Tucumán Province
Entry-level commercial vehicle segments here retain column-assist architectures for lower bill-of-materials cost. The national automotive regulator's electronic stability control interoperability mandates have slower implementation timelines outside industrial corridors. Independent repair operations require workforce reskilling investments to transition from belt-driven pump maintenance.
Santa Fe Province
The Pampas industrial corridor around Rosario generates localized demand density from electric vehicle assemblers. Tier-one suppliers reduce logistics costs serving multiple OEMs within 150-kilometer radii. Battery-electric platforms here specify steering systems with minimal parasitic draw to preserve range.
Argentina Automotive EPS Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across Argentina's automotive EPS supply base. The market structure shows moderate consolidation around integrated module manufacturers with established Mercosur certification pathways. Three strategic archetypes dominate: full-system integrators with controller-motor-sensor bundling, component specialists supplying rack-and-pinion hardware, and electronics houses providing firmware-calibration services. Capacity expansion and strategic partnerships represent the dominant competitive moves as suppliers position for 48V architecture transitions.
Among Japanese-origin conglomerates, JTEKT Corporation, Denso Corporation, and NSK Ltd occupy positions exemplifying integrated module supply archetypes. These entities anchor the premium tier through manufacturing footprints that serve regional OEM assembly lines. Their presence reflects the broader pattern of Asia-Pacific industrial groups leveraging established Mercosur trade relationships to capture share in electrified steering procurement.
| Leading Market Players |
|---|
| JTEKT Corporation |
| Denso Corporation |
| ZF Friedrichshafen AG |
| NSK Ltd |
| Nexteer Automotive |
| Robert Bosch GmbH |
| Mitsubishi Electric Corporation |
| GKN PLC |
| Hubei Henglong Auto System Group |
| Others |
Value Chain & Pricing Dynamics
Argentina's transport ministry fuel-efficiency mandates gate qualified supply access for EPS module manufacturers, with compliance-certified suppliers commanding premium-tier pricing from Buenos Aires and Córdoba OEMs while non-compliant hardware faces systematic procurement exclusion.
Pricing Analysis
Cost-down pressure on rack-assist configurations accelerates because tier-one suppliers compete for platform-standardization contracts across multiple OEM programs. Three-tier pricing structure across premium, standard, and economy levels differentiates by ISO 26262 functional safety certification grade and after-sales calibration service bundling. Price erosion runs through column-assist segments as peripheral commercial vehicle fleet operators resist specification upgrades. Entry-level buyers in Tucumán and Mendoza provinces exhibit highest price sensitivity; electric vehicle assemblers in the Pampas corridor prioritize performance over unit cost.
Supply Chain Analysis
Remanufacturing flows for controller modules and torque motors remain underdeveloped, constraining circular economy revenue capture for independent aftermarket operators. Manufacturing concentration rests on Japan, Germany, and China for brushless DC motors, neodymium-based permanent magnets, and integrated sensor-controller assemblies. Raw material dependencies center on rare-earth element processing, copper winding stock, and automotive-grade semiconductor substrates. Single-source vulnerability in Asian neodymium supply chains exposes Argentine assemblers to price volatility. Distribution runs through tier-one supplier direct-ship arrangements to OEM assembly lines, with limited authorized channel penetration into provincial aftermarket service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Argentina's automotive EPS market sits in a technology-transition phase as 48V electric architectures systematically displace hydraulic pump legacy systems across new vehicle platforms.
For Market Incumbents: Anchor manufacturing capacity in Córdoba province to satisfy central bank local-content thresholds and defend against emerging electronics specialists capturing controller-calibration service contracts. Deepen backward integration into permanent magnet sourcing through partnerships with Asian processors to mitigate rare-earth price volatility. Prioritize firmware development capabilities for ADAS torque-overlay functionality to maintain premium-tier positioning. For New Entrants and Emerging Players: Peripheral fleet operators in Mendoza and Tucumán provinces represent underserved buyer archetypes with conversion potential as national fuel-economy enforcement extends beyond industrial corridors. Target authorized aftermarket diagnostic tool partnerships to capture remanufacturing revenue streams currently monopolized by OEM suppliers. Pursue direct service-level agreements with commercial vehicle fleet managers as a go-to-market angle bypassing legacy tier-one distribution channels. For Investors and Strategic Acquirers: Central bank announcements tightening local-content minimums for steering assemblies are the leading indicator that acquisition premiums for domestically certified suppliers will expand. Long-term viability favors integrated module manufacturers with established Mercosur certification pathways and controller-motor-sensor bundling capabilities over component specialists lacking firmware expertise. Monitor transport ministry enforcement actions in peripheral provinces for early signals of market expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Rack-assist topology convergence across front-wheel-drive families reduces tooling variation for Córdoba assembly lines. |
| 48V Electrical Architecture Investment | Higher-voltage EPS motor compatibility without dedicated power conversion attracts Pampas corridor electric vehicle programs. |
| ADAS Firmware Development | Lane-keeping and automated parking torque-overlay capabilities enable subscription monetization layered on base hardware. |
| Local Content Compliance Expansion | Central bank import-substitution incentives condition market access on domestic value-added thresholds for steering assemblies. |
| Aftermarket Service Network Buildout | Authorized diagnostic capabilities in Mendoza and Tucumán unlock conversion potential from hydraulic remnant fleets. |
Study Parameters
Independent corroboration across OEM platform engineering directors, tier-one supplier procurement leads, aftermarket distributor operations managers, and national automotive regulator technical staff underwrites the qualitative findings. Primary interview intelligence combined with secondary validation from vehicle production databases, Mercosur trade flow records, and central bank import-substitution policy filings establishes baseline market sizing. Bottom-up unit demand estimates triangulate against top-down fuel-efficiency mandate compliance requirements.
Comparable-period anchoring to historical platform transition timelines in adjacent Latin American markets calibrates the forecast framework. Segmentation modeling spans product type, end-use vehicle class, propulsion architecture, and regional production cluster dimensions across the analysis window. CAGRs derive from installed base turnover rates, regulatory phase-out schedules, and electric vehicle program ramp assumptions. Forecast inputs incorporate 48V mild-hybrid penetration curves and electronic stability control interoperability mandates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to rare-earth supply disruptions, central bank localization threshold revisions, and Mercosur regulatory harmonization delays. Forecasts reflect documented assumptions regarding OEM platform refresh cycles and provincial enforcement penetration timelines. Practitioners should monitor transport ministry peripheral province inspection frequency and central bank local-content rule amendments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Global Automotive Charge Air Cooler Market
Automotive Electrical & Electronics
Japan X by Wire Systems Market
Automotive Electrical & Electronics
On-Board Fuse Box Market
Automotive Electrical & Electronics
Personal Mobility Devices Market
Automotive Electrical & Electronics
Automotive Digital Key Market
Automotive Electrical & Electronics
Automotive Emission Sensors Market
Automotive Electrical & Electronics
India Automotive LED Lighting Market
Automotive Electrical & Electronics
Automotive Electronic Manufacturing Services Market
Automotive Electrical & Electronics
Automotive Electronics Control Unit Management (ECU/ECM) Market
Automotive Electrical & Electronics
Automotive Lighting Actuators Market
Automotive Electrical & Electronics
Europe Electric Power Steering Market
Automotive Electrical & Electronics
UK Automotive Eps Market
Automotive Electrical & Electronics
Global Automotive Engine Coolant Temperature Sensor Market
Automotive Electrical & Electronics
Automotive Airbag Electronic Control Unit Market
Automotive Electrical & Electronics
Automotive Speed Sensor Market
Automotive Electrical & Electronics
India Automotive Camera Market