
 Global Automotive ECU Market | 2026-2036
Global Automotive ECU Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive ECU Market Analysis
Tier-1 supplier channel relationships is rewriting how ECU contracts flow from vehicle assemblers to semiconductor packagers. Bosch anchors European powertrain controller supply through captive foundry partnerships. Continental competes on safety system integration across multiple OEM programs. Denso dominates Japanese domestic sourcing while extending into North American EV platforms.
An automotive electronic control unit (ECU) is an embedded computing module that processes sensor inputs through microcontrollers or ASICs to execute real-time commands for engine, chassis, or cabin functions. The device typically integrates flash memory, analog-to-digital converters, and CAN/LIN transceivers within a sealed housing rated for under-hood thermal stress. Powertrain ECU demand remains the largest revenue pool as internal-combustion efficiency regulations persist alongside hybrid transitions. Safety ECU architectures are expanding fastest due to mandatory advanced driver-assistance system fitment across multiple regulatory jurisdictions. FPGA-based designs command premium positioning in prototyping and low-volume autonomous platforms where reprogrammability offsets unit cost.
FDA vehicle software guidance, UNECE WP.29 cybersecurity regulations, and ISO 26262 functional-safety standards collectively mandate traceable development processes and over-the-air update capabilities. These frameworks force ECU suppliers to restructure validation cycles and liability coverage. Stakeholders must monitor how chip shortage resolution timelines interact with regional content requirements for subsidy eligibility.
Market Dynamics
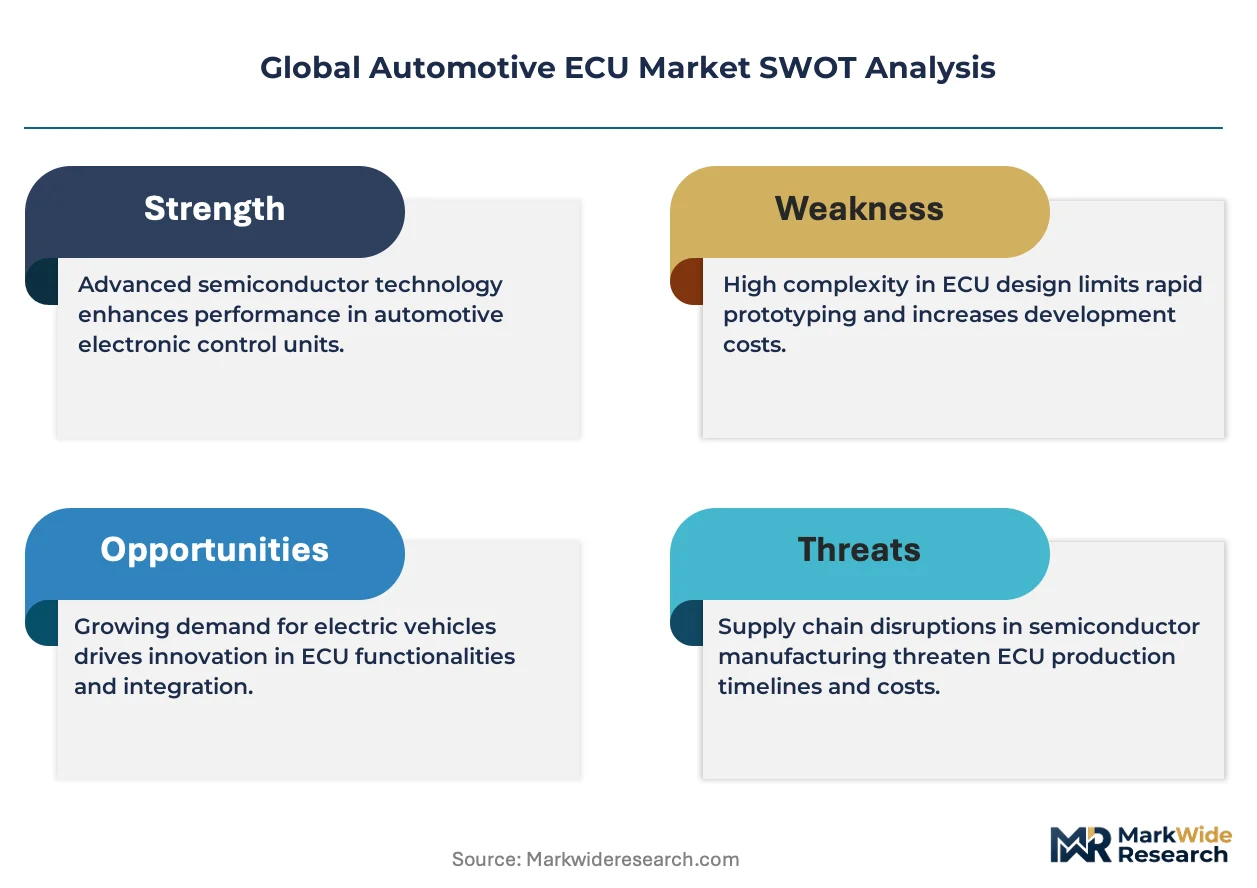
Functional safety mandates and cybersecurity regulations are compressing ECU development cycles while forcing semiconductor architecture redesigns across powertrain and safety domains. Tier-1 suppliers now carry liability exposure that previously rested with OEMs alone.
Growth Catalysts
- ISO 26262 ASIL-D certification:Mandatory functional safety ratings for autonomous braking and steering systems expand addressable controller volumes in Germany and Japan.
- Electric vehicle platform proliferation:Battery management systems and motor inverters require dedicated ECU architectures distinct from combustion powertrains.
- UNECE WP.29 cybersecurity frameworks:Over-the-air update mandates create recurring software validation revenue streams for suppliers.
Market Restraints
- Silicon wafer cost volatility:300mm foundry capacity concentration in Taiwan creates input price instability for microcontroller die procurement.
- Legacy vehicle fleet inertia:Internal-combustion platforms with 15-year service lives delay full electrification transitions and hybrid ECU demand plateaus.
- Functional safety audit timelines:ISO 26262 third-party certification cycles extend 18-24 months, gating product launches.
Strategic Opportunities
- Domain controller consolidation:Zonal architectures merging powertrain, chassis, and body functions reduce per-vehicle ECU count while raising unit value.
- India PLI scheme for automotive electronics:Localized assembly incentives attract Tier-1 investments for export-oriented EV component sourcing.
- FPGA-to-ASIC conversion pathways:Autonomous prototyping platforms mature into volume silicon, capturing margin from reprogrammable premium pricing.
Industry Challenges
- Embedded cybersecurity engineering scarcity:UNECE WP.29 threat analysis and penetration testing expertise resides in limited talent pools across automotive and aerospace sectors.
- Multi-generation software stack integration:Classic AUTOSAR legacy code must coexist with adaptive platforms in mixed-criticality controllers without compromising determinism.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive ECU Market |
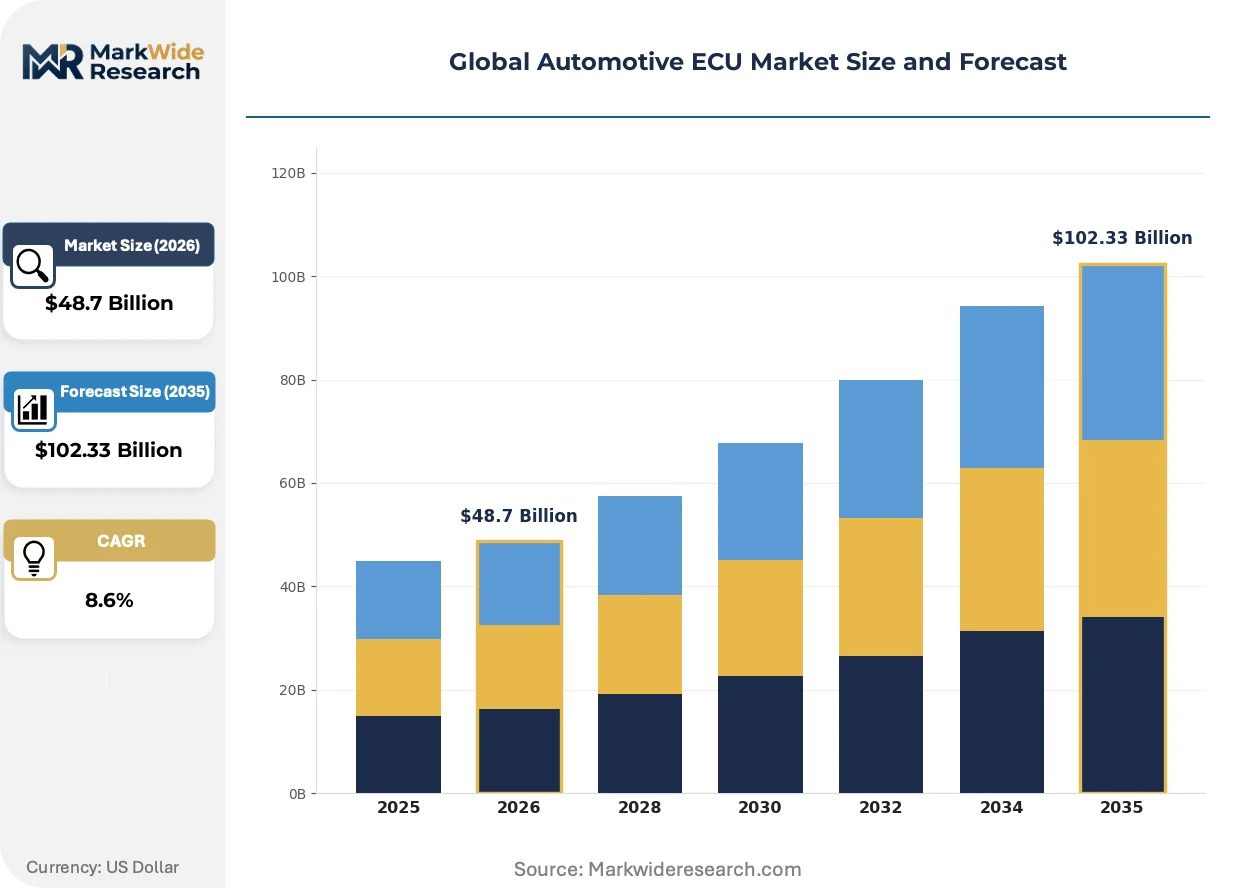
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $102.33 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powertrain ECU, Body Control ECU, Safety ECU, Infotainment ECU Technology: FPGA, Microcontroller, DSP, ASIC End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Functionality: Vehicle Dynamics, Engine Management, Driver Assistance, Infotainment |
| Companies Covered | Delphi, Marelli, Bosch, Hyundai Autron, Mitsubishi Electric, Continental, Hitachi Automotive Systems, Panasonic Corporation, Denso, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive ECU Market Emerging Trajectories
Automotive computing architectures are converging toward centralized domain controllers that displace distributed ECU networks. This shift redefines supplier competitive boundaries and semiconductor packaging requirements.
Silicon carbide power semiconductors are replacing silicon IGBTs in inverter applications. EV drivetrain engineers at OEMs in Germany and China have accelerated SiC adoption timelines from 2028 to 2025 model years. The technology is rendering obsolete traditional ECU thermal management designs built for lower switching frequencies and higher losses.
EU AI Act risk classification rules now capture automated driving systems above SAE Level 2. Conformity assessment obligations for high-risk AI systems impose documentation burdens on ECU software development workflows. Safety-critical controller suppliers in Stuttgart and Munich are restructuring quality management systems to satisfy both ISO 26262 and AI Act traceability mandates simultaneously.
Fleet operators now specify lifetime software update commitments as contract prerequisites. Direct procurement relationships between rental and logistics companies and Tier-1 electronics suppliers are displacing OEM-mediated component sourcing in commercial vehicle segments. This pattern concentrates in North American long-haul trucking and European last-mile delivery electrification programs.
Global Automotive ECU Market Segmentation
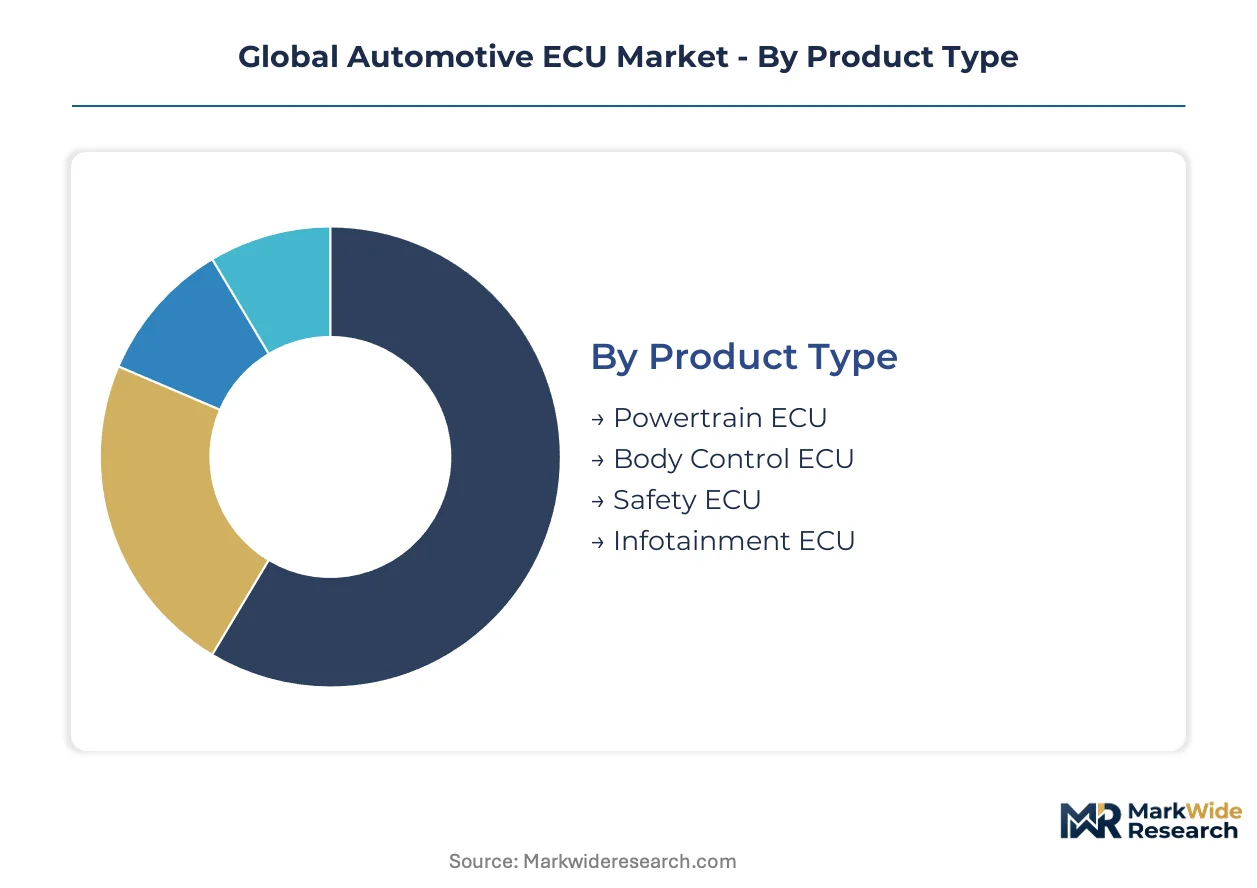
ECU segmentation reveals how computing workloads distribute across vehicle domains and how semiconductor choices map to cost-performance tradeoffs. Suppliers calibrate portfolio depth against domain controller consolidation timelines.
Product Type:
Use-case spectrum spans combustion efficiency, occupant protection, cabin experience, and vehicle-wide body electronics.
- Powertrain ECU:Manages fuel injection, ignition timing, and transmission shift logic through 32-bit microcontrollers with automotive-grade temperature ratings. Demand concentrates in Germany and Japan where Euro 7 and upcoming emissions standards force precision engine control; hybrid transitions sustain volumes even as BEV share rises.
- Safety ECU:Executes airbag deployment, anti-lock braking, and electronic stability control with ASIL-D certified architectures and redundant processing channels. Adoption concentrates in North American and European OEM programs where NHTSA and UNECE mandates require fitment across all vehicle classes; sensor fusion complexity drives unit value expansion.
- Body Control ECU:Coordinates door locks, lighting, and climate systems through LIN bus networked modules with sleep-mode power management.
- Infotainment ECU:Powers head-unit displays and connectivity stacks using application processors with graphics acceleration and over-the-air update capabilities.
Established volume favors Powertrain ECU; emerging adoption favors Safety ECU.
Technology:
Silicon choices trace cost tier against reprogrammability needs and volume scale.
- Microcontroller:Dominates through ARM Cortex-R and TriCore architectures with embedded flash and deterministic real-time operating systems. Procurement concentrates at Renesas, NXP, and Infineon fabs where automotive-qualified 40nm and 28nm processes balance cost against performance headroom; legacy codebases lock in multi-year design cycles.
- ASIC:Delivers lowest unit cost at million-plus annual volumes through full-custom logic synthesis and hardwired peripheral integration. Design wins concentrate in high-volume powertrain and body applications at German and Japanese OEMs where amortized NRE costs justify dedicated silicon; domain controller consolidation accelerates ASIC transitions.
- FPGA:Enables late-stage algorithm changes through reconfigurable logic gates in prototyping and low-volume autonomous platforms.
- DSP:Accelerates sensor signal processing and motor control loops with dedicated multiply-accumulate hardware.
Microcontroller shipments anchor revenue; ASIC conversion captures margin expansion.
End User:
Channel structure reflects liability allocation and technical integration depth.
- Tier-1 Suppliers:Bosch, Continental, and Denso engineer complete ECU subsystems including hardware, software stacks, and validation documentation. Sourcing relationships concentrate with German and Japanese OEMs where long-term platform contracts span multiple vehicle generations; cybersecurity liability under UNECE WP.29 reshapes contract terms.
- OEMs:Internal electronics divisions at Volkswagen, Toyota, and General Motors design strategic controllers in-house. Investment concentrates in autonomous and battery management domains where intellectual property control determines competitive differentiation; vertical integration deepens for software-defined vehicle architectures.
- Vehicle Assemblers:Contract manufacturers perform final ECU integration and calibration.
- Aftermarket Providers:Supply replacement units and performance tuning modules through independent distribution channels.
Tier-1 relationships dominate safety-critical sourcing; OEM captive design expands in strategic domains.
Functionality:
Application maturity spans from decades-old engine algorithms to emerging AI inference workloads.
- Engine Management:Optimizes combustion efficiency through oxygen sensor feedback and variable valve timing control with lookup-table calibration. Deployment concentrates in markets with stringent tailpipe regulations where real-world driving emissions testing forces continuous refinement; hybrid architectures extend relevance.
- Driver Assistance:Processes camera and radar inputs for adaptive cruise control and lane-keeping through sensor fusion algorithms. Fitment concentrates in European and North American premium segments where EU AI Act documentation requirements and NHTSA crash-rating incentives accelerate standardization; L2+ functionality demands escalating compute.
- Vehicle Dynamics:Coordinates suspension, steering, and braking for ride comfort and handling response.
- Infotainment:Integrates navigation, media streaming, and voice interfaces through consumer-electronics-derived software ecosystems.
Engine Management sustains volume base; Driver Assistance captures steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German Euro 7 emissions standards and Japanese automotive electrification subsidies are accelerating ECU procurement cycles. Tier-1 suppliers in Stuttgart and Toyota City are expanding microcontroller sourcing to meet hybrid platform deadlines. The regulatory push across multiple jurisdictions is compressing development timelines for powertrain and safety controllers.
United States
NHTSA mandates for automatic emergency braking are expanding safety ECU volumes across all vehicle classes. The Inflation Reduction Act's domestic content requirements for EV tax credits are reshaping Tier-1 supplier localization strategies. Detroit-area engineering centers at General Motors and Ford are integrating battery management systems with domain controller architectures for next-generation electric platforms.
Germany
KBA enforcement of UNECE WP.29 cybersecurity frameworks is forcing ECU suppliers to restructure software validation workflows. ISO 26262 ASIL-D certification requirements for autonomous braking systems are gating product launches at Bosch and Continental. Stuttgart and Munich host concentrated development activity where functional safety engineering talent commands premium compensation.
Japan
METI subsidies for xEV component production are accelerating dedicated ECU architectures for battery management and motor control. Toyota and Honda procurement patterns favor Denso for domestic sourcing while extending supply agreements into North American EV programs. Nagoya and Tokyo metropolitan areas concentrate semiconductor packaging partnerships with Renesas and NXP.
China
MIIT new energy vehicle mandates and dual carbon goals are driving domestic ECU production capacity expansion. GB standards for functional safety are converging with ISO 26262, enabling local suppliers to compete for international OEM programs. Shanghai and Shenzhen engineering clusters are developing zonal domain controllers for BYD and NIO platforms.
India
PLI scheme incentives for automotive electronics are attracting Tier-1 investments for export-oriented EV component sourcing. BIS certification requirements for electronic control modules are accelerating local assembly partnerships. Tamil Nadu and Maharashtra manufacturing corridors are emerging as contract manufacturing hubs for European and Japanese OEM supply chains.
Global Automotive ECU Market Vendor Landscape
On the supply side, the industry is consolidating around integrated subsystem providers that combine hardware, software stacks, and validation documentation. Tier-1 suppliers now carry direct cybersecurity liability under UNECE WP.29 that previously rested with OEMs alone. Three strategic archetypes dominate: German powertrain specialists, Japanese safety system integrators, and Korean battery management developers. Competitive positioning depends on captive foundry partnerships and ISO 26262 certification velocity.
Among German-based suppliers, Bosch and Continental occupy positions as full-stack subsystem architects, while Denso anchors Japanese sourcing relationships. These three exemplify the integrated archetype where semiconductor procurement, software development, and functional safety validation reside under single organizational control. Their market presence reflects decades-long platform contracts that span multiple vehicle generations and resist displacement by newer entrants.
| Leading Market Players |
|---|
| Delphi |
| Marelli |
| Bosch |
| Hyundai Autron |
| Mitsubishi Electric |
| Continental |
| Hitachi Automotive Systems |
| Panasonic Corporation |
| Denso |
| Others |
Supply Flow & Price Mechanics
Taiwanese foundry concentration risk determines both pricing tier spreads and supply chain shape across automotive ECU procurement. Single-source dependency for 300mm automotive-grade microcontroller wafers compresses margins at volume tiers while amplifying premium positioning for suppliers with captive silicon access.
Pricing Analysis
Certification level under ISO 26262 ASIL-D creates the primary spread between premium safety-critical controllers and standard body electronics modules. Three-tier pricing structure across ASIL-D certified, ASIL-B compliant, and non-safety-grade ECUs reflects validation cost recovery and liability coverage differentiation. Cost compression in standard-grade powertrain controllers is intensifying because microcontroller die procurement faces foundry allocation constraints. Fleet procurement teams at commercial vehicle operators exhibit highest price sensitivity, while luxury OEM platform engineers prioritize certification velocity over unit cost.
Supply Chain Analysis
300mm silicon wafer feedstock draws from Taiwan, South Korea, and Japan for automotive microcontroller fabrication. Raw material dependencies span automotive-grade epoxy molding compounds from Japan, copper lead frames from China, and rare-earth magnet materials for motor control modules. Single-source vulnerability concentrates at TSMC automotive-qualified nodes for 28nm and 40nm processes. Distribution runs through Tier-1 subsystem integrators who bundle semiconductor procurement with software validation and functional safety documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Domain controller consolidation fragments incumbent supplier relationships, creating white-space opportunities for specialized cybersecurity engineering firms and zonal architecture specialists.
For Market Incumbents: Entrench platform engineering relationships through captive foundry partnerships at Renesas and Infineon that guarantee microcontroller allocation during supply constraints. Deepen backward integration into software-defined vehicle middleware stacks to resist displacement by OEM in-house controller development. For New Entrants and Emerging Players: Build out UNECE WP.29 cybersecurity validation capabilities as a differentiated service layer for Tier-1 suppliers lacking embedded threat analysis expertise. Target Indian PLI scheme automotive electronics corridors for export-oriented contract manufacturing of battery management ECUs, leveraging BIS certification pathways as market entry mechanism. For Investors and Strategic Acquirers: Functional safety engineering boutiques with ISO 26262 certification velocity and existing OEM relationships represent priority acquisition targets for semiconductor firms seeking automotive verticalization. Long-term viability hinges on domain controller consolidation timelines; monitor zonal architecture adoption rates at German and Chinese OEMs as inflection indicator for distributed ECU displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| Domain Controller Consolidation | Bosch and Continental are merging powertrain, chassis, and body functions to reduce per-vehicle ECU count while raising unit value. |
| Silicon Carbide Powertrain Transition | German and Chinese OEMs accelerated SiC inverter adoption from 2028 to 2025 model years, obsoleting traditional thermal management designs. |
| Cybersecurity Engineering Acquisition | Tier-1 suppliers carry direct UNECE WP.29 liability, creating demand for threat analysis and penetration testing expertise. |
| India PLI Manufacturing Footprint | Tamil Nadu and Maharashtra corridors attract export-oriented EV component sourcing for European and Japanese OEM supply chains. |
| FPGA-to-ASIC Conversion Pathway | Autonomous prototyping platforms mature into volume silicon, capturing margin from reprogrammable premium pricing at low volumes. |
Methodological Framework
Initial hypotheses were tested against primary input from Tier-1 supplier procurement directors, OEM platform engineers, semiconductor packaging specialists, and aftermarket distribution managers and refined through secondary validation. Automotive production databases, IHS Markit registration data, SEC filings from exposed suppliers, and UNECE regulatory implementation timelines anchored quantitative sizing. Bottom-up microcontroller shipment analysis and top-down OEM electronics spend estimates provided cross-verification.
Demand-supply balance framing anchored the forecast framework across the analysis window, with segmentation by vehicle class, propulsion architecture, content per vehicle, and regional production cluster. CAGRs derived from vehicle production trajectory modeling and electronics content expansion curves. ISO 26262 certification pipeline visibility and silicon carbide adoption timelines served as automotive-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by Chinese battery OEMs or accelerated domain controller consolidation at German luxury manufacturers would shift outcomes. Cross-checking against IHS Markit vehicle production forecasts and semiconductor foundry capex disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
Automotive UPS (in Vehicle UPS) Market
Automotive Electrical & Electronics
Electric Vehicle Shielded HV Cables Market
Automotive Electrical & Electronics
South Korea Automotive Camera Market
Automotive Electrical & Electronics
Europe Automotive EPS Market
Automotive Electrical & Electronics
Canada Automotive Electric Actuators Market
Automotive Electrical & Electronics
India Automotive Camera Market
Automotive Electrical & Electronics
Automotive Digital Key Market
Automotive Electrical & Electronics
Africa and Middle East Automotive Tpms Market
Automotive Electrical & Electronics
Asia Pacific Automotive Camera Market
Automotive Electrical & Electronics
Personal Mobility Devices Market
Automotive Electrical & Electronics
Automotive Inverter Busbar Laminates Market
Automotive Electrical & Electronics
Electric Vehicle Motor Communication Controller Market
Automotive Electrical & Electronics
Automotive Starting System Market
Automotive Electrical & Electronics
On-Board Fuse Box Market
Automotive Electrical & Electronics
Argentina Automotive EPS Market
Automotive Electrical & Electronics
Automotive Electric Power Steering ECU Market