
 Nox Automotive Sensors Market | 2026-2036
Nox Automotive Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Nox Automotive Sensors Market Insights
Electrochemical engineering talent is rotating from legacy automotive roles into solid-state sensor development, tightening labor pools for conventional NOx sensor production. Robert Bosch GmbH leverages captive semiconductor fabrication to secure die supply for its ceramic NOx sensing elements. Continental AG anchors European OEM relationships through integrated exhaust after-treatment architectures. DENSO Corporation dominates Asian volume contracts with thermal management expertise that extends into sensor packaging.
NOx automotive sensors are gas detection devices that measure nitrogen oxide concentrations in vehicle exhaust streams, typically employing yttria-stabilized zirconia electrolytes operating at temperatures exceeding 600°C to enable selective catalytic reduction system feedback. Their primary purpose is ensuring regulatory compliance while optimizing urea injection rates for emission control. OEM channel partnerships concentrate margin pools at the top of the value chain, while aftermarket providers compete on diagnostic compatibility and replacement velocity. Solid-state sensor technology is displacing electrochemical alternatives in heavy-duty segments due to faster response times and extended service intervals.
EPA Tier 3 standards in the United States and EURO 7 regulations in Europe are mandating tighter NOx monitoring precision, forcing sensor manufacturers to certify under harmonized OBD-II and WVTA frameworks. NHTSA crashworthiness requirements additionally shape sensor housing and placement specifications for under-vehicle mounting. Stakeholders must monitor how California Air Resources Board waivers and EU F-Gas Regulation amendments reshape refrigerant and exhaust sensor bundling strategies.
Market Dynamics
Solid-state ceramic sensing architectures are compressing development cycles for NOx detection modules while simultaneously draining engineering talent from legacy electrochemical production lines. This technology migration is restructuring supplier hierarchies and certification pathways across automotive exhaust after-treatment ecosystems.
Growth Catalysts
- EURO 7 emission mandates:Stringent nitrogen oxide monitoring requirements in Europe are mandating dual-sensor architectures per vehicle, expanding unit volumes for OEM and tier-one suppliers.
- Heavy-duty fleet electrification delays:Extended diesel dominance in long-haul trucking is sustaining demand for precise SCR feedback systems in commercial vehicle segments.
- Yttria-stabilized zirconia advances:Improved high-temperature electrolyte stability is extending sensor service intervals beyond 150,000 miles in severe-duty applications.
Market Restraints
- Palladium and platinum price volatility:Precious metal electrodes in solid-state designs expose manufacturers to commodity swings that compress margin predictability.
- Semiconductor die concentration:Captive silicon carbide substrate supply chains in Germany and Japan create bottlenecks for ceramic sensor element fabrication.
- Electrochemical sensor obsolescence drag:Existing fleet replacement demand for legacy designs is fragmenting R&D investment across incompatible technology platforms.
Strategic Opportunities
- India BS-VI Phase II compliance:Stricter real-driving emission testing is opening sensor procurement contracts for domestic commercial vehicle manufacturers.
- Sensor-fusion integration:Combined NOx-particulate matter modules are capturing exhaust architecture consolidation mandates from European OEMs.
- Wireless diagnostic retrofit channels:Bluetooth-enabled aftermarket sensors are penetrating independent repair networks in North American states with inspection mandates.
Industry Challenges
- High-temperature packaging engineering:Sustained 600°C+ operation demands specialized ceramic-to-metal sealing expertise that remains scarce in conventional sensor manufacturing.
- Harmonized OBD-II and WVTA certification timelines:Divergent validation protocols between EPA and KBA are extending product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nox Automotive Sensors Market |
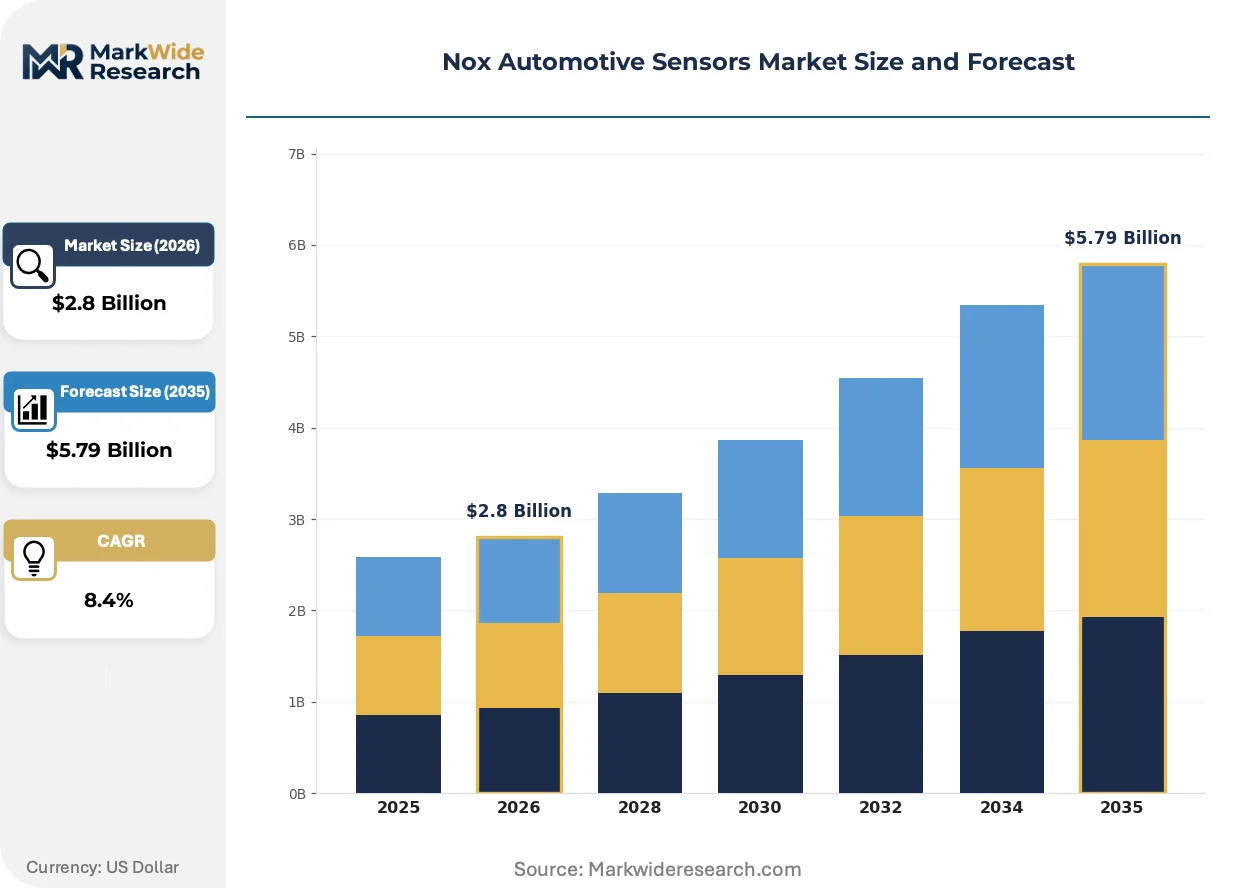
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: O2 Sensors, NOx Sensors, Temperature Sensors, Pressure Sensors End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Technology: Chemical Sensor, Optical Sensor, Solid-State Sensor, Electrochemical Sensor Application: Exhaust Monitoring, Emission Control, Engine Management, Fuel Efficiency |
| Companies Covered | Robert Bosch GmbH, Continental AG, DENSO Corporation, Sensata Technologies, Infineon Technologies AG, Faurecia, Delphi Technologies, Honeywell International Inc, Fujikura Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nox Automotive Sensors Market Trends and Innovations
Automotive exhaust sensing is undergoing platform consolidation as multi-gas detection modules displace single-function NOx units. This convergence is compressing supplier margins while elevating system-level engineering requirements.
Silicon carbide-based heater substrates are fragmenting the thermal management layer of NOx sensors into specialized semiconductor foundry supply chains. Tier-one suppliers with captive wafer processing in Germany and Japan are securing cost advantages. This substrate fragmentation is excluding pure-play sensor assemblers from premium OEM contracts.
EPA Tier 3 and CARB waiver harmonization is tightening diagnostic threshold requirements for SCR system feedback loops. Manufacturers must now certify under combined federal and state protocols that mandate redundant sensing paths. Heavy-duty diesel applications in California face the most stringent validation burdens.
Fleet procurement offices are consolidating sensor contracts into multi-year exhaust system bundles that include after-treatment hardware. This bundling is marginalizing standalone sensor distributors in North American commercial vehicle channels. Independent repair operators in Texas and Florida are responding with diagnostic service unbundling to retain customer relationships.
Nox Automotive Sensors Market Segmentation
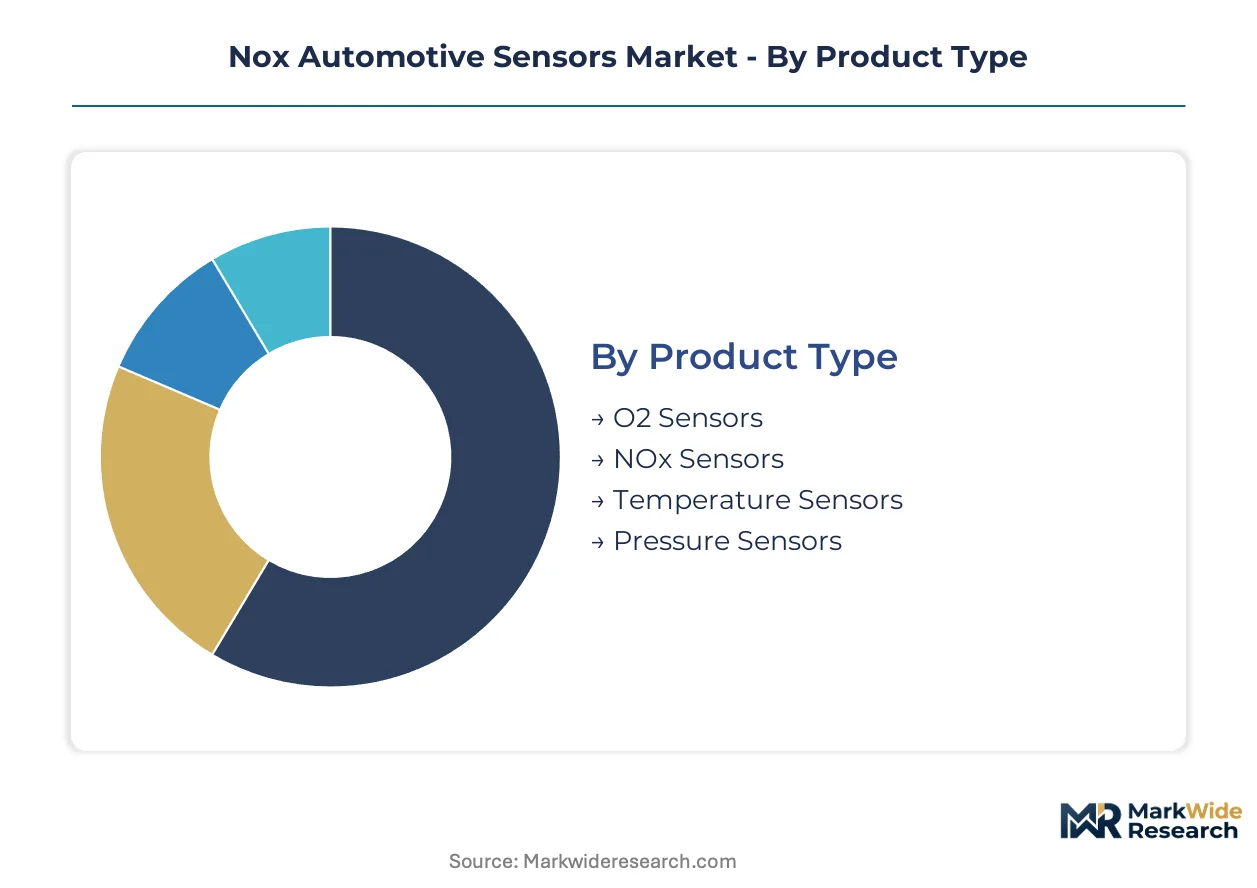
Segmentation in the NOx automotive sensors market reveals how regulatory stringency fragments procurement patterns across OEM and aftermarket channels. Technology transitions and certification requirements reshape margin distribution differently across each dimension.
Product Type:
EPA Tier 3 and EURO 7 impose distinct calibration requirements on each sensor category, forcing manufacturers to maintain parallel certification tracks.
- NOx Sensors:Yttria-stabilized zirconia electrolytes operating above 600°C enable selective catalytic reduction feedback. German OEM procurement concentrates here due to EURO 7 dual-sensor mandates and KBA-type approval density.
- O2 Sensors:Lambda probes measuring residual oxygen content in exhaust streams provide air-fuel ratio data to engine control modules. Japanese tier-one suppliers dominate volume contracts through thermal management integration expertise.
- Temperature Sensors:Thermocouple and RTD elements track exhaust gas thermal profiles for catalyst protection strategies.
- Pressure Sensors:Differential pressure elements monitor diesel particulate filter loading states and regeneration timing.
NOx sensors handle the majority of throughput; O2 sensors are expanding most quickly on share as engine management integration deepens.
End User:
Channel concentration varies sharply by geography, with captive OEM supply relationships dominating European value capture while aftermarket fragmentation persists in North American inspection-mandate states.
- OEMs:Vehicle manufacturers specify sensor architectures during exhaust system co-development, locking in multi-year supply agreements. German OEMs bundle sensors into integrated after-treatment platforms that marginalize standalone component distributors.
- Tier-1 Suppliers:Delphi Technologies and similar integrators assemble sensor modules into complete exhaust subsystems for OEM direct delivery. These suppliers capture margin through ceramic-to-metal sealing expertise and harmonized OBD-II certification capabilities.
- Aftermarket Providers:Independent distributors serve replacement demand in states with biennial emission inspection requirements.
- Vehicle Assemblers:Contract manufacturers in emerging markets procure sensors through tier-one intermediaries rather than direct sourcing.
OEMs command the steepest margin pools; tier-1 suppliers are climbing the fastest as exhaust architecture consolidation accelerates.
Technology:
Cost tier differentiation separates premium solid-state designs from legacy electrochemical platforms, with semiconductor substrate access determining competitive position.
- Solid-State Sensor:Ceramic zirconia architectures with silicon carbide heater substrates deliver sub-second response times and 150,000-mile service intervals. German and Japanese manufacturers with captive wafer fabrication secure OEM premium contracts.
- Electrochemical Sensor:Amperometric cells with liquid electrolytes face obsolescence pressure despite persistent fleet replacement demand in legacy diesel applications.
- Optical Sensor:UV absorption spectroscopy enables multi-gas detection but remains cost-prohibitive for mass-market deployment.
- Chemical Sensor:Metal oxide semiconductor variants respond to multiple exhaust constituents without selectivity precision required for regulatory compliance.
Solid-state sensors absorb the majority of new platform development; optical sensors are gaining share fastest in R&D-intensive European validation programs.
Application:
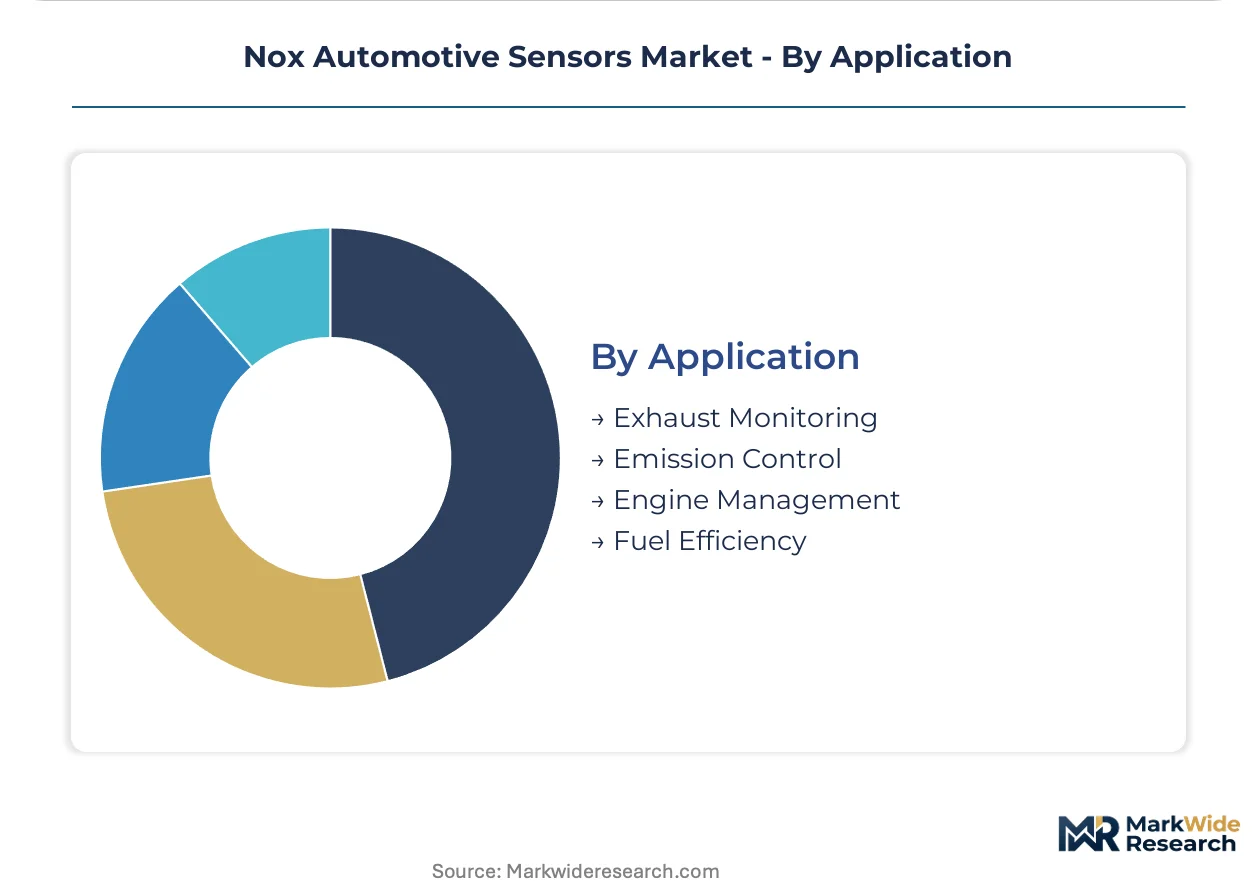
Application segmentation tracks how sensor deployment maps onto emission control system architecture, with exhaust monitoring and emission control functions increasingly converging in integrated modules.
- Exhaust Monitoring:Real-time NOx concentration measurement upstream and downstream of SCR catalysts enables closed-loop urea dosing optimization. California CARB waiver requirements mandate redundant sensing paths in heavy-duty diesel configurations.
- Emission Control:Sensor feedback directly modulates after-treatment hardware operation including SCR, DPF, and LNT regeneration cycles. EPA Tier 3 diagnostic thresholds tighten allowable deviation margins.
- Engine Management:Combustion feedback sensors optimize air-fuel ratios for particulate and NOx trade-off minimization.
- Fuel Efficiency:Lambda sensor data enables lean-burn operation strategies that reduce consumption while maintaining emission compliance boundaries.
Exhaust monitoring carries the heaviest certification burden; emission control applications are expanding fastest as real-driving emission testing protocols proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys dual-sensor architectures per vehicle under EURO 7 mandates, while the United States concentrates single-sensor dominance in heavy-duty diesel fleets. Japan and China pursue divergent certification pathways that fragment procurement patterns across Pacific Rim supply chains.
Germany
KBA-type approval density drives sensor bundling into integrated exhaust platforms. EURO 7 nitrogen oxide monitoring requirements mandate redundant upstream and downstream sensing paths. Stuttgart's OEM supplier ecosystem anchors ceramic-to-metal sealing expertise for premium solid-state designs.
United States
Commercial vehicle fleets expand sensor deployments to meet EPA Tier 3 emission mandates. California CARB waivers impose the heaviest diagnostic threshold requirements for SCR feedback systems. Texas and Florida aftermarket operators respond with diagnostic service unbundling to retain independent repair relationships.
Japan
METI industrial standards shape silicon carbide substrate development for heater-integrated sensor elements. Domestic tier-one suppliers capture volume contracts through thermal management integration expertise. Nagoya's automotive cluster concentrates captive wafer fabrication capabilities for ceramic sensing architectures.
China
Domestic commercial vehicle manufacturers procure sensors through tier-one intermediaries rather than direct sourcing. MIIT emission standards tighten real-driving testing protocols for heavy-duty diesel applications. Yangtze River Delta manufacturing bases scale electrochemical sensor production for legacy fleet replacement demand.
India
BS-VI Phase II compliance opens sensor procurement contracts for domestic truck and bus manufacturers. BIS certification requirements diverge from harmonized OBD-II frameworks, extending validation timelines. Tamil Nadu and Maharashtra vehicle assembly corridors concentrate tier-one supplier distribution networks.
Nox Automotive Sensors Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the NOx automotive sensors market. Captive semiconductor fabrication capabilities separate premium OEM suppliers from pure-play sensor assemblers. Two strategic archetypes dominate: diversified automotive electronics conglomerates with in-house ceramic processing, and exhaust system integrators with after-treatment bundling expertise. Competitive moves center on backward integration into silicon carbide substrates and multi-year exhaust architecture contracts that marginalize standalone component distributors.
Within the diversified electronics tier, Robert Bosch GmbH and Continental AG exemplify integrated manufacturing positions. DENSO Corporation anchors the Asia-Pacific volume vector through thermal management heritage. These three entities occupy positions that reflect divergent geographic certification advantages rather than convergent technology strategies.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| DENSO Corporation |
| Sensata Technologies |
| Infineon Technologies AG |
| Faurecia |
| Delphi Technologies |
| Honeywell International Inc |
| Fujikura Ltd. |
| Others |
Pricing and Supply Chain Analysis
EURO 7 and EPA Tier 3 certification frameworks gate both supplier qualification and price tiering simultaneously, as dual-sensor mandates and harmonized OBD-II validation create steep entry barriers that stratify procurement economics across OEM and aftermarket channels.
Pricing Analysis
Long-term offtake contracts dominate OEM procurement, locking in multi-year exhaust system bundles that marginalize spot-market transactions. Pricing stratifies across premium solid-state designs with captive silicon carbide substrates, standard ceramic architectures from tier-one integrators, and economy electrochemical units serving legacy fleet replacement. Cost compression in the aftermarket tier intensifies as Bluetooth-enabled diagnostic retrofits erode traditional distributor margins. Fleet procurement offices exhibit lowest price sensitivity due to bundled after-treatment contracts, while independent repair operators in inspection-mandate states face acute margin pressure.
Supply Chain Analysis
Silicon carbide substrate fabrication concentrates in Germany and Japan, creating a chokepoint that filters competitive access to premium OEM contracts. Yttria-stabilized zirconia electrolytes, palladium-platinum electrode materials, and specialized ceramic-to-metal sealing expertise anchor tier-one supplier cost structures. Single-source vulnerability in semiconductor die supply chains exposes assemblers to allocation risk during automotive chip cycles. Distribution runs through captive OEM channels in Stuttgart and Nagoya clusters, with aftermarket penetration concentrated in North American inspection-corridor states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
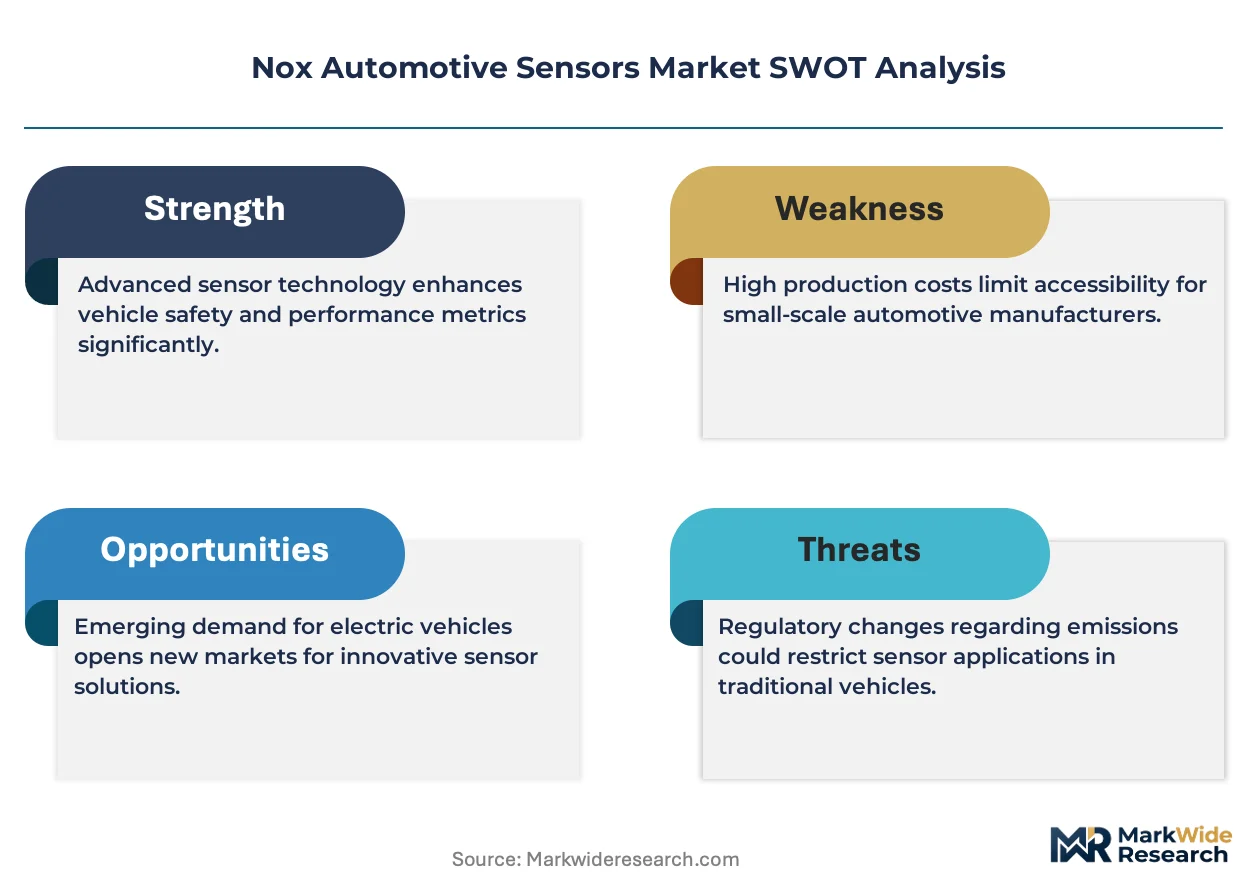
This market functions as a regulatory-moat arena where switching costs between sensor architectures and certification entrenchment defend incumbent positions against pure-play challengers.
For Market Incumbents: Shield premium OEM relationships through backward integration into silicon carbide heater substrates, denying tier-two assemblers access to critical thermal management layers. Deepen ceramic-to-metal sealing expertise scarcity by recruiting electrochemical engineering talent before solid-state migration completes, foreclosing competitor R&D bandwidth. For New Entrants and Emerging Players: Anchor in India's BS-VI Phase II compliance window, where domestic commercial vehicle manufacturers lack established tier-one relationships and BIS certification divergence extends validation timelines that favor agile specialists. Target wireless diagnostic retrofit channels in Texas and Florida inspection-mandate states, unbundling diagnostic services from hardware sales to capture independent repair loyalty. For Investors and Strategic Acquirers: EURO 7 implementation reshapes the acquisition landscape by mandating dual-sensor architectures that consolidate procurement toward integrated exhaust platform suppliers. Long-term viability centers on tier-one suppliers with captive wafer fabrication and harmonized OBD-II certification capabilities. Watch California CARB waiver harmonization progress as the signal for North American margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicon Carbide Substrates | Captive heater element supply secures OEM premium contracts against pure-play assemblers. |
| Multi-Year Exhaust Architecture Bundling | Integrated after-treatment platforms lock in sensor procurement and marginalize standalone distributors. |
| Sensor-Fusion Module Development | Combined NOx-particulate matter designs capture European OEM consolidation mandates. |
| Wireless Diagnostic Retrofit Certification | Bluetooth-enabled aftermarket sensors penetrate inspection-mandate states with unbundled service models. |
| Electrochemical Talent Acquisition | Preemptive hiring tightens labor pools for legacy production while accelerating solid-state migration. |
Research Methodology
A standing panel of OEM platform engineers, tier-one supplier procurement leads, aftermarket distributor operations heads, and exhaust after-treatment R&D directors provided ongoing calibration across primary fieldwork phases. Secondary validation drew from EPA certification filings, KBA type-approval databases, vehicle production registries, and customs trade records for yttria-stabilized zirconia and precious metal electrode materials. Bottom-up unit shipment estimates triangulated against top-down OEM exhaust system procurement values.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including sensor technology type, vehicle propulsion architecture, content per vehicle by emission control system complexity, OEM tier positioning, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to certified unit deployment schedules, with inputs including EURO 7 implementation phasing, heavy-duty fleet electrification delay assumptions, and real-driving emission test protocol expansion rates.
Material uncertainties — palladium and platinum commodity swings, semiconductor die allocation disruptions, and California CARB waiver timeline shifts — sit outside the modeled envelope. Forecasts reflect documented assumptions about certification harmonization progress and technology migration rates. Practitioners should keep alternative scenarios live as solid-state yield improvements and electrochemical obsolescence drag evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electrical & Electronics
US Automotive E-Axle Market
Automotive Electrical & Electronics
Automotive Inverter Busbar Laminates Market
Automotive Electrical & Electronics
In-Chassis Cooling Market
Automotive Electrical & Electronics
Car Bulb Market
Automotive Electrical & Electronics
Automotive Thermoelectric Generator Market
Automotive Electrical & Electronics
Global Automotive Engine Coolant Temperature Sensor Market
Automotive Electrical & Electronics
Europe Automotive Display Market
Automotive Electrical & Electronics
US Automotive EPS Market
Automotive Electrical & Electronics
Automotive Electric Power Steering ECU Market
Automotive Electrical & Electronics
Automotive Rain Sensor Market
Automotive Electrical & Electronics
Electric Vehicle HV Cables Market
Automotive Electrical & Electronics
Automotive Ecall Market
Automotive Electrical & Electronics
Global Automotive Electronic Lock Differential Market
Automotive Electrical & Electronics
On-Board Charger Market
Automotive Electrical & Electronics
On-Board Fuse Box Market
Automotive Electrical & Electronics
Automotive Chassis Electronics Market