
 United States Automotive Heat Exchanger Market | 2026-2036
United States Automotive Heat Exchanger Market Size, Share, and Industry Trends Forecast 2026-2036
United States Automotive Heat Exchanger Market Analytics
Mexico's expanding auto assembly capacity is reconfiguring North American supply chain flows for thermal components. Denso Corporation leverages its Tennessee manufacturing base to serve Detroit Three thermal module programs. MAHLE GmbH anchors its aftermarket radiator distribution through regional warehouses in Ohio and California. Robert Bosch GmbH competes on integrated sensor-heat exchanger modules for electrified powertrains.
An automotive heat exchanger transfers thermal energy between fluids at different temperatures to maintain optimal operating conditions for engines, batteries, and cabin climate systems. Most units employ aluminum fin-and-tube construction with brazed joints to achieve heat transfer coefficients exceeding 50 W per square meter Kelvin while minimizing weight. Radiators and condensers remain the largest product categories by installed base, though intercoolers for turbocharged engines command premium pricing due to higher pressure ratings. Electric vehicle battery cooling modules represent the fastest-expanding application segment as thermal management directly impacts cell cycle life and fast-charging capability.
NHTSA crashworthiness standards and EPA emissions regulations jointly determine heat exchanger durability and efficiency specifications for vehicles sold in the United States. OSHA workplace safety rules and ISO 9001 quality management standards govern manufacturing processes at domestic production facilities. Stakeholders must monitor how California Air Resources Board zero-emission vehicle mandates reshape thermal system architectures as battery electric platforms displace conventional engine cooling loops.
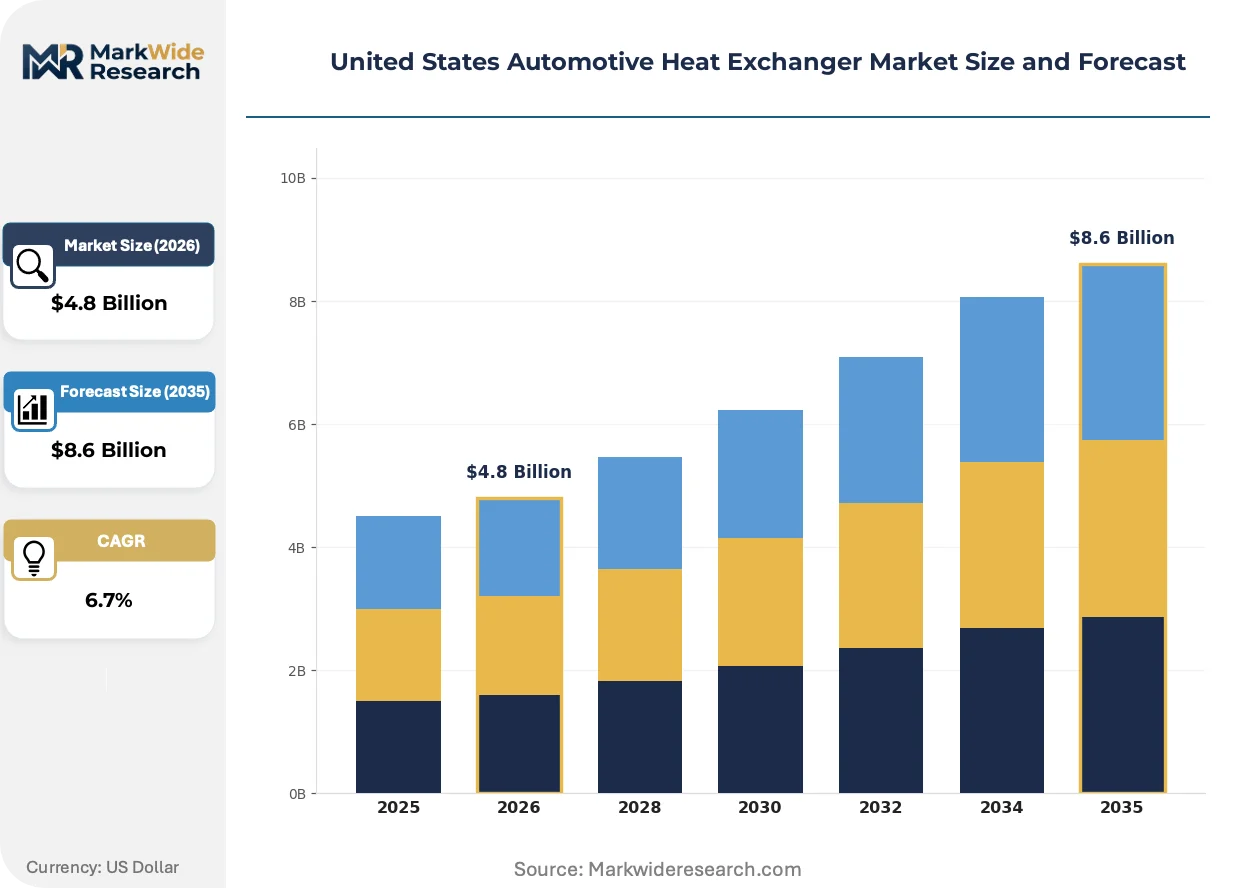
Market Dynamics
Electrification of vehicle platforms is dismantling the radiator-centric thermal architecture that dominated internal combustion engines for a century, forcing suppliers to engineer battery-specific cooling circuits and integrated power electronics modules.
Growth Catalysts
- EPA Corporate Average Fuel Economy standards:Manufacturers must deploy advanced intercoolers and transmission oil coolers to squeeze thermal efficiency gains from downsized turbocharged engines. Fleet compliance deadlines compress development cycles.
- Electric vehicle battery thermal management:Lithium-ion cell chemistry demands precise temperature control within narrow bands to preserve cycle life and enable DC fast-charging protocols. OEMs specify multi-zone cooling plates.
- Michigan-Texas manufacturing corridor:Proximity to Detroit Three headquarters and Mexico border assembly plants concentrates procurement volumes, reducing logistics costs for just-in-sequence delivery.
Market Restraints
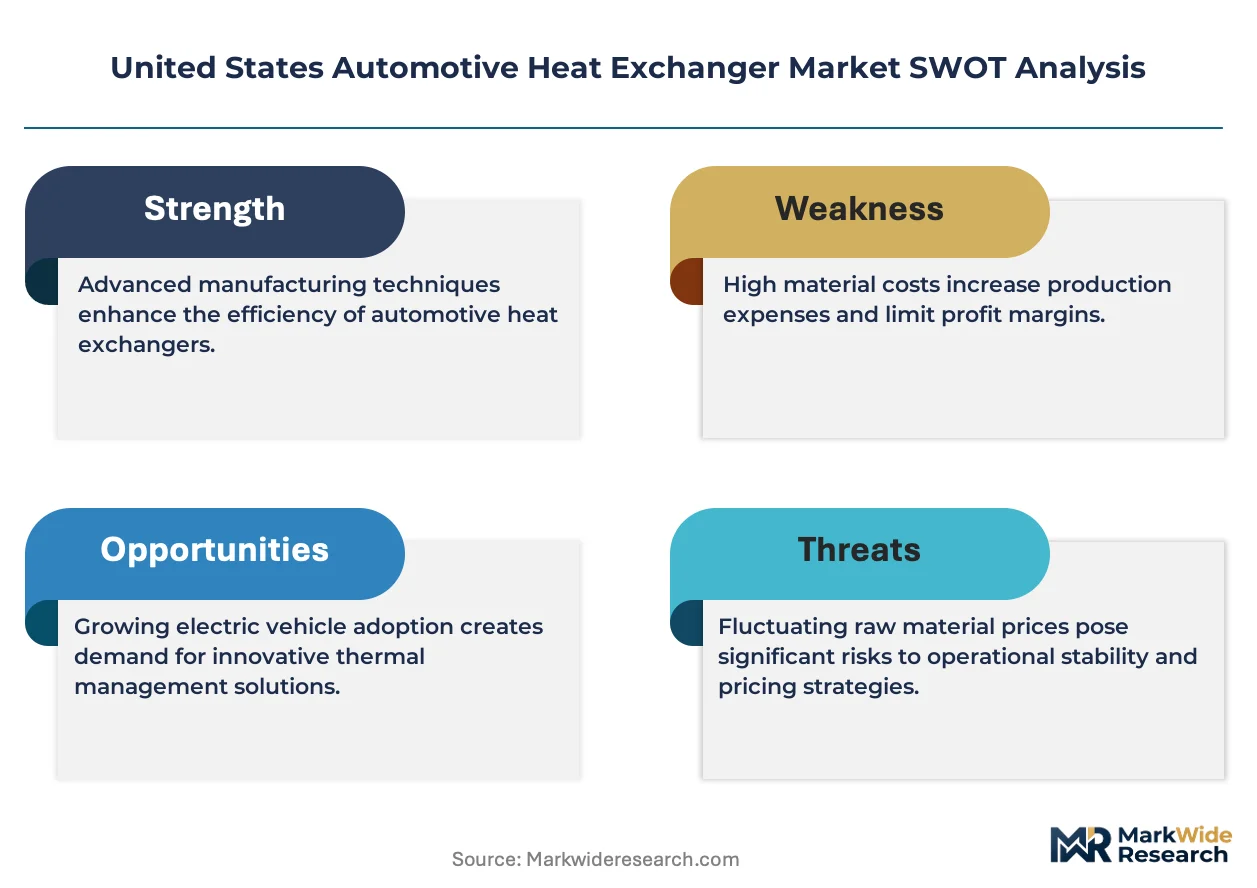
- Aluminum price volatility:Fin-and-tube construction depends on rolled aluminum alloy sheet, exposing margins to London Metal Exchange fluctuations and tariff uncertainty.
- Single-source brazing furnace concentration:Vacuum brazing equipment for complex aluminum assemblies concentrates among a handful of German and Japanese equipment builders, creating capacity bottlenecks.
- Copper-aluminum galvanic corrosion:Dissimilar metal interfaces in hybrid cooling loops limit service life in harsh road salt environments, constraining warranty terms.
Strategic Opportunities
- California Air Resources Board zero-emission vehicle mandates:ZEV credit banking systems accelerate battery electric platform rollouts, expanding demand for integrated battery cooling and cabin heat pump modules.
- Data-driven predictive thermal management:Convergence of vehicle telematics with machine learning algorithms enables real-time cooling load optimization, opening software-anchored service revenue streams.
- Aftermarket remanufacturing networks:Independent distributors in Ohio and California regional warehouses capture replacement demand as first-generation electrified vehicles exit warranty coverage.
Industry Challenges
- Multi-physics simulation talent scarcity:Battery thermal runaway modeling requires coupled computational fluid dynamics and electrochemistry expertise that traditional radiator engineers rarely possess.
- ISO 9001-IATF 16949 dual certification timelines:New entrants face eighteen-month qualification periods before supplying OEM assembly lines, locking out agile competitors.
- Legacy cooling loop integration:Plug-in hybrid architectures must synchronize conventional engine radiators with battery chillers, multiplying interface complexity and failure modes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Automotive Heat Exchanger Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radiators, Oil Coolers, Intercoolers, Condensers Material: Aluminum, Copper-Nickel, Stainless Steel, Brass Application: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Trucks, Electric Vehicles Technology: Plate Type, Shell & Tube, Fin Tube, Hybrid |
| Companies Covered | Denso Corporation, Hanon Systems, Valeo, MAHLE GmbH, T.RAD Co., Ltd, Modine, Dana Limited, Continental AG, Robert Bosch GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Automotive Heat Exchanger Market Evolving Landscape
Smart thermal systems are supplanting passive hardware, embedding sensors and actuators that enable closed-loop control and predictive maintenance across powertrain and battery applications.
Additive manufacturing of topology-optimized aluminum heat sinks is digitizing thermal component design workflows. Tier-1 suppliers prototype conformal cooling channels that wrap around battery cell geometries in weeks rather than months. This compresses tooling investment and accelerates platform-specific customization for electric vehicle programs.
NHTSA crashworthiness standards now incorporate thermal system integrity under impact loading, forcing structural reinforcement of battery cooling plates and refrigerant line routing. Manufacturers respond with extruded aluminum crash cans that protect heat exchanger cores while maintaining heat transfer coefficients. The Detroit Three have accelerated validation testing to meet 2025 model year structural requirements.
Fleet operators and leasing companies now specify total cost of ownership metrics rather than unit price in thermal system procurement. Multi-year service contracts bundle hardware with predictive monitoring, displacing spot aftermarket purchases. This shift concentrates buying power among national fleet managers and rewards suppliers with diagnostic software capabilities, particularly visible in Texas-Mexico cross-border logistics corridors.
United States Automotive Heat Exchanger Market Segmentation
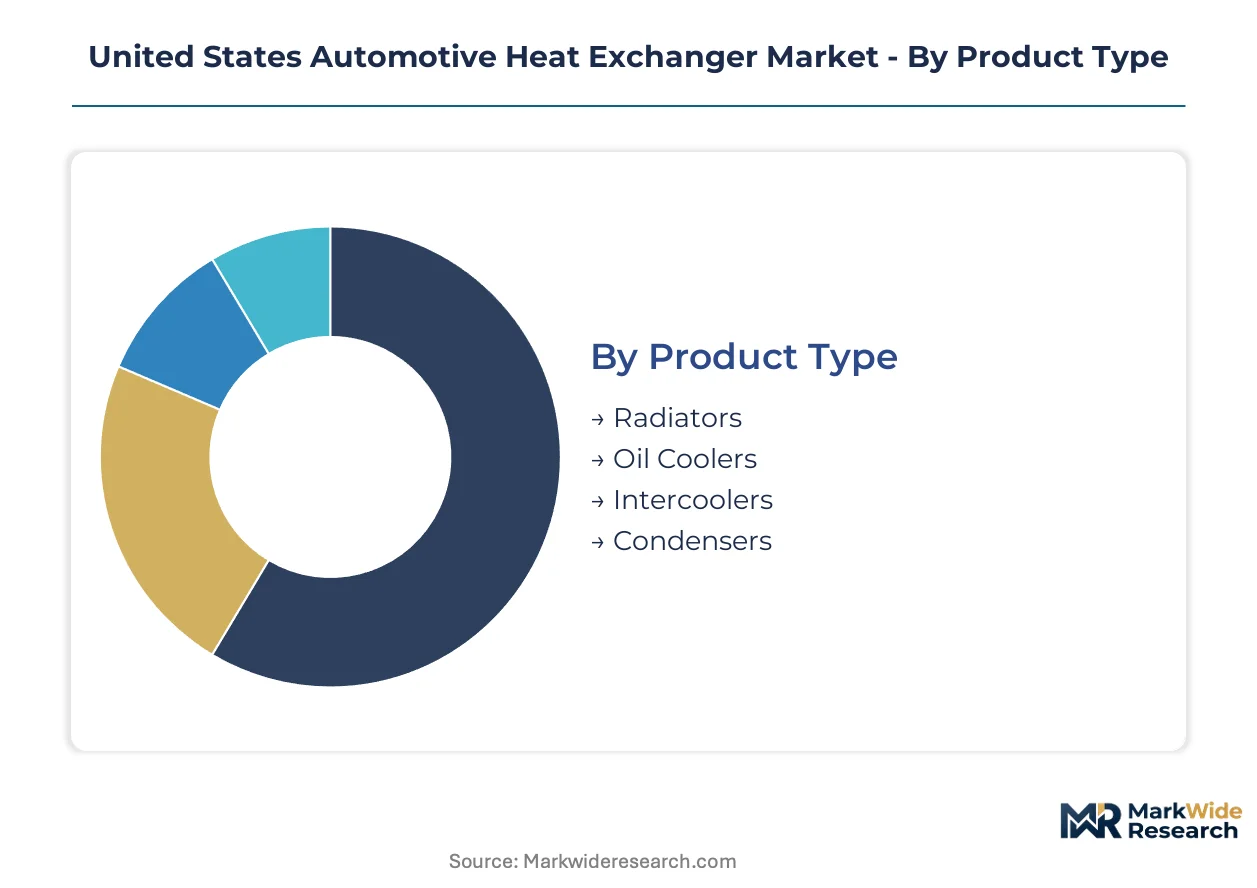
Heat exchanger procurement patterns diverge sharply across thermal load specifications, material cost structures, and electrification readiness. Understanding segment boundaries clarifies where engineering investment concentrates and where margin compression threatens supplier viability.
Product Type:
Application intensity varies by thermal duty cycle and pressure rating across vehicle platforms.
- Radiators:Aluminum fin-and-tube cores dissipate engine coolant heat through forced air convection. Michigan assembly plants and Texas-Mexico border facilities anchor procurement volumes for Detroit Three thermal module programs. EPA fuel economy deadlines compress development cycles for lightweight variants.
- Intercoolers:Charge air cooling for turbocharged engines demands higher burst pressure ratings and denser fin packing. Downsize-boost engine strategies across Ford, GM, and Stellantis lineages concentrate demand in premium light-truck segments.
- Oil Coolers:Transmission and differential thermal management extends component life under towing loads. Fleet specifications in commercial segments drive specification tightening.
- Condensers:Refrigerant phase-change heat rejection for cabin climate systems. Heat pump integration in electric vehicle platforms is altering refrigerant circuit architectures.
Radiators hold installed capacity. Intercoolers is rotating up the share rankings.
Material:
Cost tier and corrosion resistance tradeoffs shape alloy selection for specific duty environments.
- Aluminum:Rolled 3003 and 6061 alloys dominate fin-and-tube construction through brazed assembly. London Metal Exchange price volatility and tariff exposure compress margins at rolling mills serving Tennessee and Ohio manufacturing corridors.
- Copper-Nickel:Seawater-grade alloys resist galvanic corrosion in heavy-duty marine-adjacent applications. Limited automotive penetration concentrates in specialty commercial retrofits.
- Stainless Steel:300-series austenitic grades withstand exhaust gas recirculation condensate in selective catalytic reduction circuits. Emissions aftertreatment thermal loads drive specification in heavy-duty diesel.
- Brass:Traditional radiator construction persists in aftermarket remanufacturing networks. Ohio and California regional warehouses stock brass-copper cores for legacy vehicle parc.
Aluminum holds installed capacity. Stainless Steel is rotating up the share rankings.
Application:
Customer type determines thermal system complexity and service interval expectations.
- Passenger Vehicles:Integrated front-end modules package radiators, condensers, and fan shrouds for high-volume assembly. OEM just-in-sequence delivery from Michigan-based suppliers dominates procurement.
- Electric Vehicles:Battery cooling plates and power electronics chillers displace traditional engine-centric architectures. California Air Resources Board zero-emission mandates accelerate platform rollout timelines.
- Commercial Vehicles:Class 4-7 truck thermal loads demand redundant cooling circuits for engine, transmission, and hydraulic systems. Fleet total-cost-of-ownership metrics displace unit-price procurement.
- Heavy-Duty Trucks:Class 8 long-haul specifications prioritize thermal durability under continuous high-load operation. Interstate corridor logistics operators concentrate specification authority.
Passenger Vehicles holds installed capacity. Electric Vehicles is rotating up the share rankings.
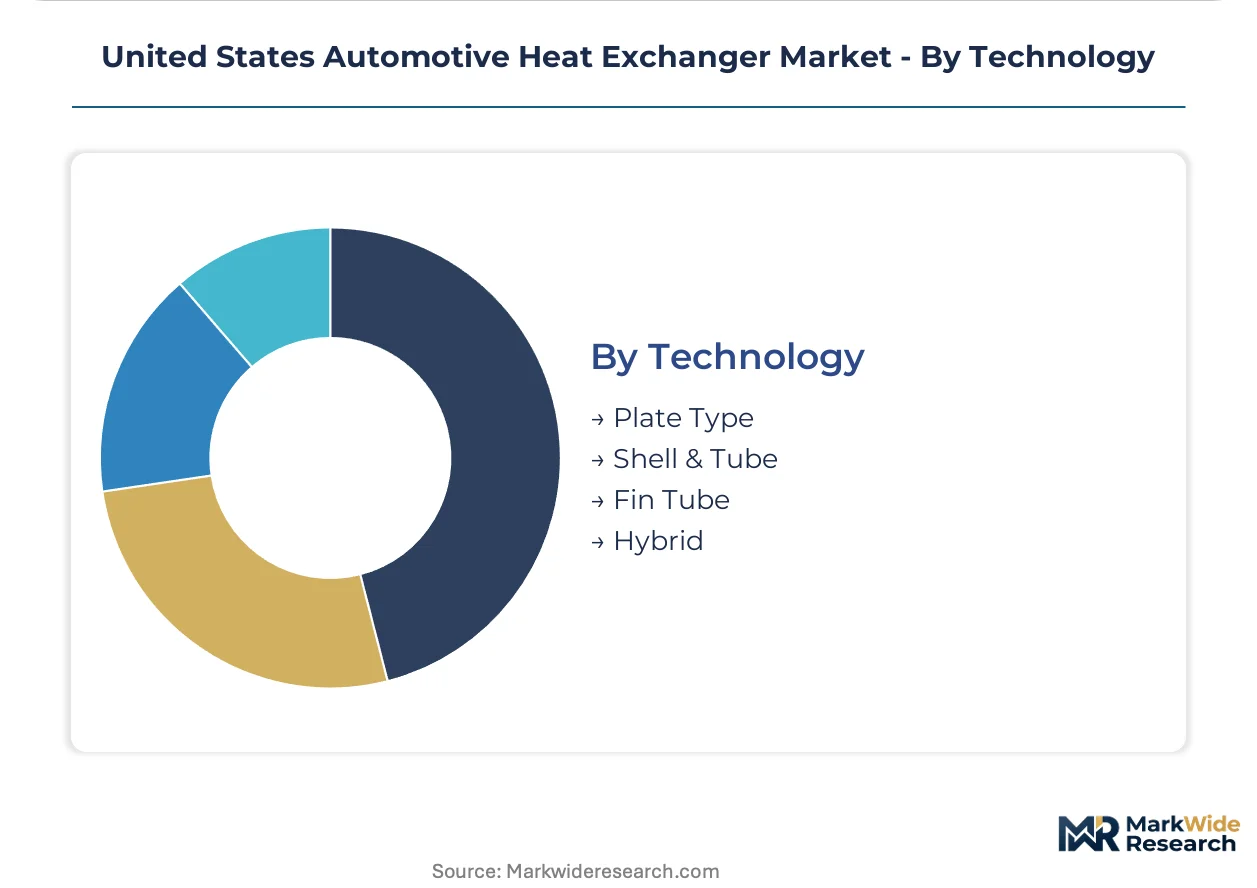
Technology:
Manufacturing process maturity and design flexibility separate established from emerging form factors.
- Fin Tube:Conventional round-tube-and-fin construction dominates high-volume radiator and condenser production. Vacuum brazing furnace capacity constraints limit expansion at new entrants.
- Plate Type:Stacked aluminum plates with turbulent flow promoters enable compact battery cooling modules. Additive manufacturing prototyping accelerates electric vehicle platform customization.
- Shell & Tube:Pressure vessel construction suits oil cooler and transmission fluid applications. Heavy-duty specifications favor this robust architecture.
- Hybrid:Combined fin-tube and plate architectures synchronize engine and battery thermal loops in plug-in hybrid platforms. Interface complexity multiplies failure mode analysis requirements.
Fin Tube holds installed capacity. Plate Type is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Michigan assembly plants consume heat exchangers differently from California battery factories, with the former prioritizing engine cooling density and the latter demanding compact battery plate architectures. This geographic split in thermal system specifications fragments procurement patterns across domestic manufacturing corridors.
Michigan
Detroit Three headquarters and Warren Tech Center R&D facilities drive specification authority for conventional powertrain cooling modules. NHTSA crashworthiness standards for 2025 model years accelerate structural validation timelines for radiator assemblies. Flint and Lansing stamping plants anchor just-in-sequence delivery networks for front-end thermal modules.
Texas
Border assembly zones in Laredo and El Paso concentrate procurement for Mexico-sourced vehicle platforms requiring dual-circuit thermal architectures. EPA regional enforcement offices in Dallas monitor Corporate Average Fuel Economy compliance for southwestern fleet operators. Houston petrochemical corridors supply brazing alloy precursors to Tennessee-based rolling mills serving the region.
California
California Air Resources Board zero-emission vehicle mandates reshape thermal system demand toward battery cooling plates and heat pump condensers. Fremont and Los Angeles metro battery assembly facilities specify multi-zone cooling circuits for lithium-ion platforms. Silicon Valley telematics providers enable predictive thermal management software integration.
Ohio
Aftermarket remanufacturing networks in Cleveland and Columbus stock brass-copper radiator cores for legacy vehicle parc maintenance. OSHA regional offices in Cincinnati enforce workplace safety standards at aluminum brazing facilities. Toledo glass manufacturing corridors supply adjacent thermal module assembly operations with logistics proximity advantages.
Tennessee
Denso Corporation's Maryville manufacturing base serves Detroit Three thermal module programs with vacuum-brazed aluminum assemblies. Department of Energy clean vehicle manufacturing grants support battery cooling plate production line expansions. Knoxville aluminum rolling mills supply fin-stock material to southeastern automotive corridors.
United States Automotive Heat Exchanger Market Competitive Landscape
Capability concentration sits with integrated sensor-thermal module specialists; scale advantage sits with high-volume aluminum fin-and-tube fabricators. The supplier base organizes into three tiers: multinational Tier-1 systems integrators, regional aluminum rolling and brazing specialists, and aftermarket remanufacturing distributors. Dominant competitive moves include backward integration into brazing furnace capacity and geographic co-location with Detroit Three assembly plants.
Among Japanese-origin Tier-1 suppliers, Denso Corporation and T.RAD Co., Ltd exemplify the integrated systems archetype, while German engineering conglomerates Robert Bosch GmbH and MAHLE GmbH occupy positions emphasizing precision thermal control for electrified powertrains. These four entities represent contrasting geographic anchoring strategies—Asia-Pacific headquarters with Tennessee manufacturing presence versus European R&D centers with Ohio distribution networks.
| Leading Market Players |
|---|
| Denso Corporation |
| Hanon Systems |
| Valeo |
| MAHLE GmbH |
| T.RAD Co., Ltd |
| Modine |
| Dana Limited |
| Continental AG |
| Robert Bosch GmbH |
| Others |
Value Network & Pricing Analysis
London Metal Exchange aluminum price volatility compresses margin spreads across fin-and-tube fabricators while simultaneously forcing procurement consolidation toward Tennessee and Ohio rolling mills with captive brazing capacity. This commodity exposure bifurcates the supplier base into price-takers at spot-market mercy and integrated players commanding OEM contract premiums.
Pricing Analysis
Michigan assembly corridors command premium pricing against Texas-Mexico border zones due to just-in-sequence delivery requirements and NHTSA structural validation costs. Three-tier pricing structure across premium, standard, and economy levels separates OEM-certified modules from aftermarket remanufactured cores and unbranded imports. Cost compression in standard-tier battery cooling plates intensifies as Chinese rolling mills expand export capacity. Fleet procurement managers exhibit lowest price sensitivity due to total-cost-of-ownership contracting, while independent aftermarket distributors face acute margin pressure.
Supply Chain Analysis
Vacuum brazing furnace concentration among German and Japanese equipment builders limits domestic expansion capacity for new entrants. Raw material flows draw from Tennessee aluminum rolling mills, Mexican assembly subcomponents, and Canadian alloy precursors. Single-source dependency on brazing equipment creates qualification bottlenecks extending eighteen months. Distribution runs through regional warehouses in Ohio and California serving aftermarket channels alongside direct OEM sequencing from Michigan and Tennessee manufacturing bases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent radiator-centric suppliers face substitution pressure from battery cooling plate specialists as electric vehicle architectures dismantle conventional thermal loops. Defense requires preemptive capability acquisition before platform standardization locks out late entrants.
For Market Incumbents: Pre-empt battery thermal module consolidation by acquiring plate-type manufacturing expertise and additive manufacturing prototyping capabilities. Secure IATF 16949 certification ahead of OEM qualification windows to lock out agile competitors. Deepen backward integration into vacuum brazing furnace capacity before equipment lead times extend further.
For New Entrants and Emerging Players: California battery assembly corridors offer underpenetrated demand for multi-zone cooling plate customization serving CARB zero-emission mandates. Target aftermarket remanufacturing networks in Ohio and California where first-generation electrified vehicles exit warranty coverage. Enter through software-anchored predictive thermal management services rather than capital-intensive hardware fabrication.
For Investors and Strategic Acquirers: EPA Corporate Average Fuel Economy compliance deadlines reshape the acquisition landscape toward intercooler and transmission oil cooler specialists serving downsized turbocharged engine strategies. Prioritize targets with dual aluminum-stainless steel alloy capabilities spanning conventional and electrified platforms. Monitor California Air Resources Board ZEV credit banking system adjustments as inflection signals for battery cooling demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures lithium-ion cell thermal interface capacity for Detroit Three electric platforms. |
| Backward Integration | Captive vacuum brazing furnace control eliminates German and Japanese equipment bottlenecks. |
| Geographic Manufacturing Footprint | Tennessee-Michigan corridor positioning reduces logistics costs for just-in-sequence delivery. |
| Software-Defined Vehicle Investment | Predictive thermal algorithms enable recurring service revenue from fleet operators. |
| Platform Standardization | Modular battery cooling plate architectures accelerate electric vehicle program customization. |
Research Methodology
The analysis maps radiator, intercooler, oil cooler, condenser, and battery cooling plate sub-sectors, each validated through Tier 1 supplier procurement directors, OEM platform thermal engineers, aftermarket distribution managers, and aluminum rolling mill operations leads. Primary fieldwork combined structured interviews with secondary triangulation against EPA regulatory filings, NHTSA safety standard updates, vehicle production databases, and SEC supplier disclosures. Bottom-up segment sizing and top-down market reconciliation anchored volume estimates.
Fixed assumptions across the modeling period include EPA fuel economy enforcement intensity, aluminum LME price bands within historical volatility ranges, and IATF 16949 certification timeline stability. Segmentation dimensions modeled encompass product type, material alloy, vehicle application, propulsion architecture, and regional production cluster. CAGRs derived from segment-level build-up analysis incorporating content-per-vehicle trajectories and platform rollout schedules. Forecast inputs included OEM electrification commitment disclosures and CARB ZEV mandate trajectory.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese battery cooling specialists or additive manufacturing disruptors would shift outcomes. Quarterly review of aluminum LME futures curves, vacuum brazing equipment order backlogs, and CARB regulatory amendments is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Assemblies
China Automotive Heat Exchanger Market
Automotive Assemblies
Automotive Heat Exchanger Market
Automotive Assemblies
Automotive Steering Rack Market
Automotive Assemblies
Robotic Welding for Automotive Manufacturing Market
Automotive Assemblies
Global Automotive Transfer Case Market
Automotive Assemblies
Africa Automotive Market
Automotive Assemblies
Automotive Tube Bending and Assembly Parts Market
Automotive Assemblies
Automotive Cell Vent Spacer Market
Automotive Assemblies
Automotive Rocker Arm Market
Automotive Assemblies
Automotive Track Bars Market
Automotive Assemblies
Global Automotive Air Spring Market
Automotive Assemblies
Automotive Casting Market
Automotive Assemblies
Automotive Strut Bar Market
Automotive Assemblies
Global Automotive Oem Market
Automotive Assemblies
Automotive Frame Machine Market
Automotive Assemblies
Automotive Clock Spring Market