
 Electric Moped Market | 2026-2036
Electric Moped Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Moped Market Insights
The EU Green Deal is decoupling urban mobility demand from fossil fuel dependence across European city centers, forcing fleet operators and commuters toward electrified two-wheeler alternatives. Yadea leverages its integrated battery manufacturing footprint to dominate cost curves in Asian export markets. NIU Technologies sustains software-defined product differentiation through connected vehicle platforms and over-the-air firmware updates. Honda anchors premium positioning with hybrid heritage engineering and established dealer density across Japanese and Southeast Asian urban corridors.
An electric moped is a two-wheeled motorized vehicle with step-through frame architecture, typically rated between 25 km/h and 45 km/h maximum speed, powered by an electric motor drawing from a rechargeable battery pack rather than an internal combustion engine, designed primarily for short-distance urban commuting and commercial last-mile logistics. Standard Mopeds occupy the volume base across emerging markets where purchase price sensitivity governs household decisions, while High-Power Mopeds command margin pools in European and East Asian cities where speed-rated models qualify for lane access privileges. Lithium-ion battery configurations are displacing Lead-acid across all price tiers as energy density improvements compress pack weight and extend cycle life, though Lead-acid persists in rural Indian and African markets where upfront cost constraints override total ownership economics.
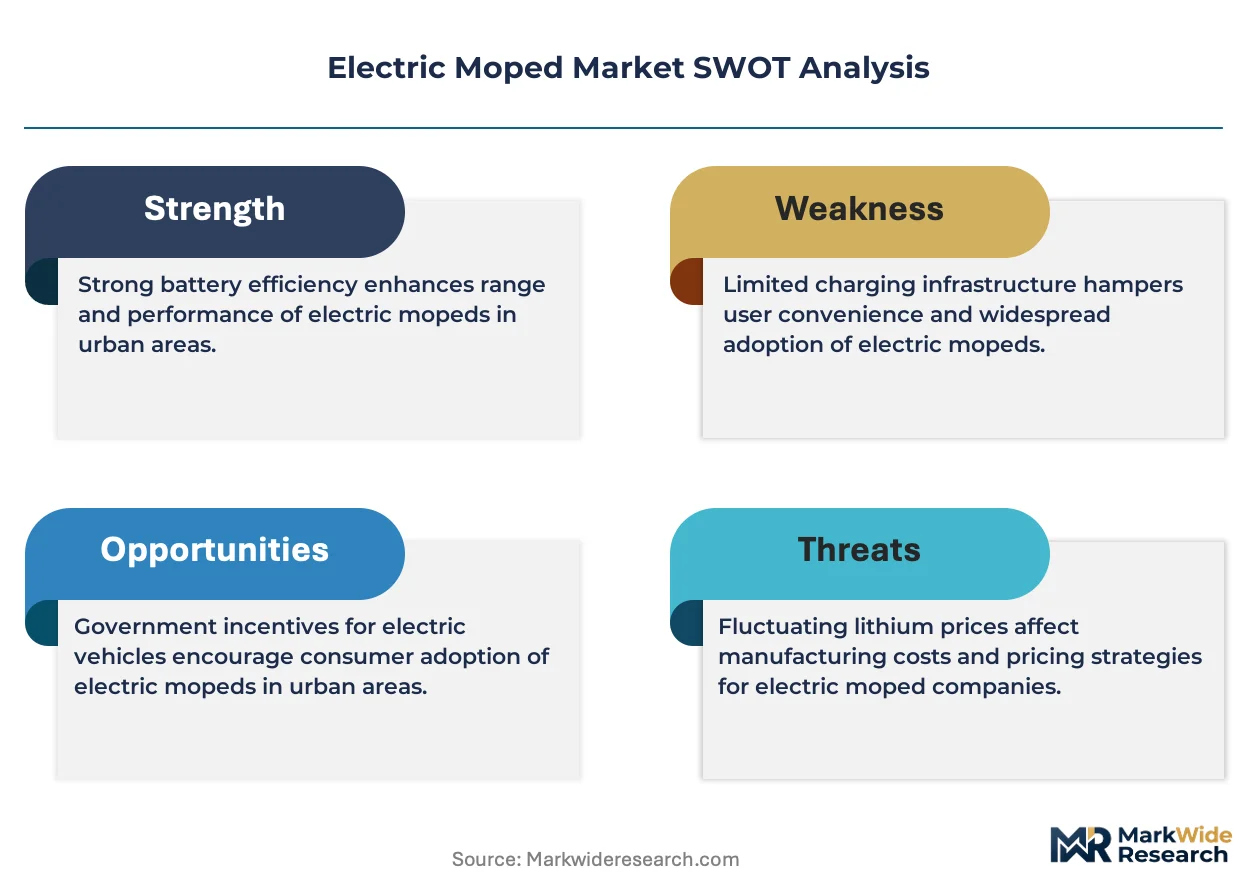
The EPA tailpipe standards and EU F-Gas Regulation jointly constrain internal combustion moped availability in North American and European distribution channels, redirecting importer portfolios toward electric-only lineups. India's FAME subsidy scheme and PLI scheme for advanced chemistry cell manufacturing are restructuring domestic supply chains, compelling brands to localize assembly or forfeit public procurement eligibility. Stakeholders must monitor how battery passport traceability requirements under EU CSRD and emerging Indian BIS safety standards reshape component sourcing rules and warranty liability allocation across multinational manufacturing networks.
Market Dynamics
City-level combustion bans are forcing fleet operators to electrify two-wheeler portfolios faster than battery cost curves can compress, creating a supply-demand gap that favors manufacturers with captive cell production and swappable architectures.
Growth Catalysts
- EU F-Gas Regulation:Phase-down schedules for fluorinated greenhouse gases are eliminating refrigerant-dependent thermal management systems in European markets, accelerating native electric powertrain adoption.
- Last-mile logistics:Food delivery platforms across Indonesia, Vietnam, and India are mandating electric vehicle adoption in rider contracts as urban congestion charges render petrol mopeds uneconomical.
- Lithium-ion density improvements:Advanced cathode chemistries are extending single-charge range sufficiently to eliminate range anxiety for typical 30-50 kilometer daily urban duty cycles.
Market Restraints
- Raw material concentration:Cobalt and lithium refining capacity clusters in China, exposing non-Chinese assemblers to supply disruption and price volatility during trade friction episodes.
- Charging infrastructure gaps:Residential parking scarcity in dense Asian and European cities prevents overnight charging for a significant share of target households.
- Lead-acid lock-in:Rural Indian and African markets remain tethered to heavy, short-cycle lead-acid batteries due to upfront cost constraints that override total ownership calculations.
Strategic Opportunities
- Battery-as-a-service models:Swappable pack networks in Indonesian and Vietnamese cities are decoupling vehicle purchase from energy storage capital expenditure, expanding addressable household income brackets.
- India PLI scheme:Production-linked incentives for advanced chemistry cell manufacturing are attracting component localization investments that qualify brands for public fleet procurement tenders.
- Connected vehicle convergence:Integration of telematics with fleet management software is enabling subscription revenue streams that offset hardware margin compression.
Industry Challenges
- Electronics hardware integration:Sourcing and validating motor controllers, battery management systems, and vehicle control units from disparate suppliers strains quality assurance timelines.
- EU CSRD traceability:Battery passport requirements mandating full supply chain disclosure are forcing renegotiation of long-term component contracts with insufficient documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Moped Market |
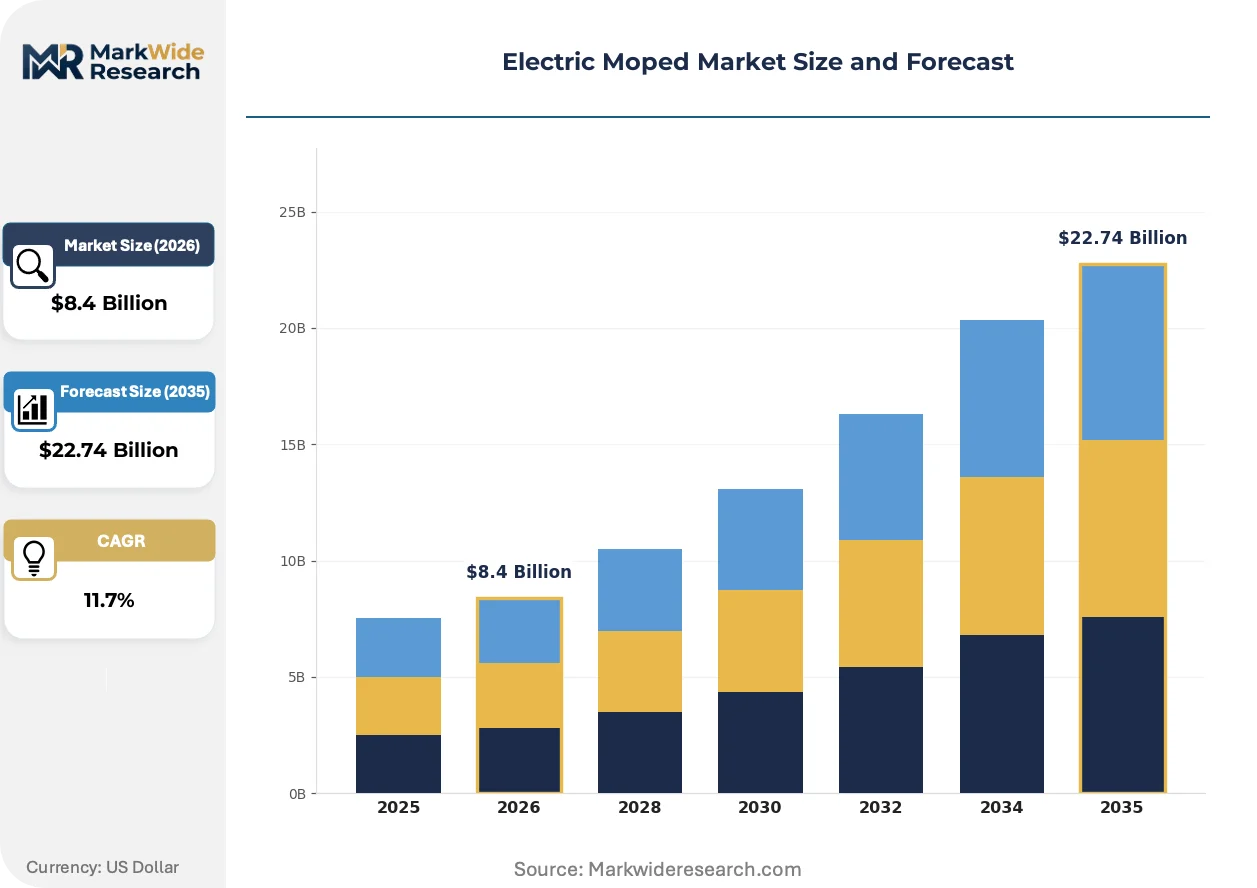
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $22.74 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Mopeds, High-Power Mopeds, Foldable Models, Off-road Mopeds End User: Personal Use, Delivery Services, Ride-sharing, Educational Institutions Battery Type: Lithium-ion, Lead-acid, Nickel-metal Hydride, Solid-State Charging Method: Home Charging, Public Charging Stations, Fast Charging, Solar Charging |
| Companies Covered | Yadea, VinFast, Piaggio, Vmoto, Honda, Ola Electric, Horwin, Yamaha Motor, NIU Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Moped Market Trends and Innovations
Swappable battery ecosystems are rewiring competitive advantage away from vehicle engineering toward energy network density and software integration, compressing traditional moats around manufacturing scale.
Silicon-carbide power electronics are modularizing inverter architectures across premium moped segments. Tier-1 suppliers are shipping standardized motor controller platforms that reduce OEM development cycles from 24 months to 12. This modularity is enabling smaller brands to compete on vehicle styling and connected features rather than powertrain investment.
India's FAME subsidy scheme is restructuring domestic procurement eligibility around localized assembly thresholds. Brands without captive Indian manufacturing forfeit access to state-level fleet tenders and consumer purchase incentives. Domestic assemblers are responding by establishing knock-down kit operations in Gujarat and Tamil Nadu industrial corridors.
Fleet operators are consolidating vendor relationships around integrated service contracts that bundle vehicles, maintenance, and energy access. Food delivery platforms in Jakarta, Ho Chi Minh City, and Bangalore are shifting from rider-owned asset models to corporate leasing arrangements. This concentration is compressing supplier margins while extending contract durations and technical support obligations.
Electric Moped Market Segmentation
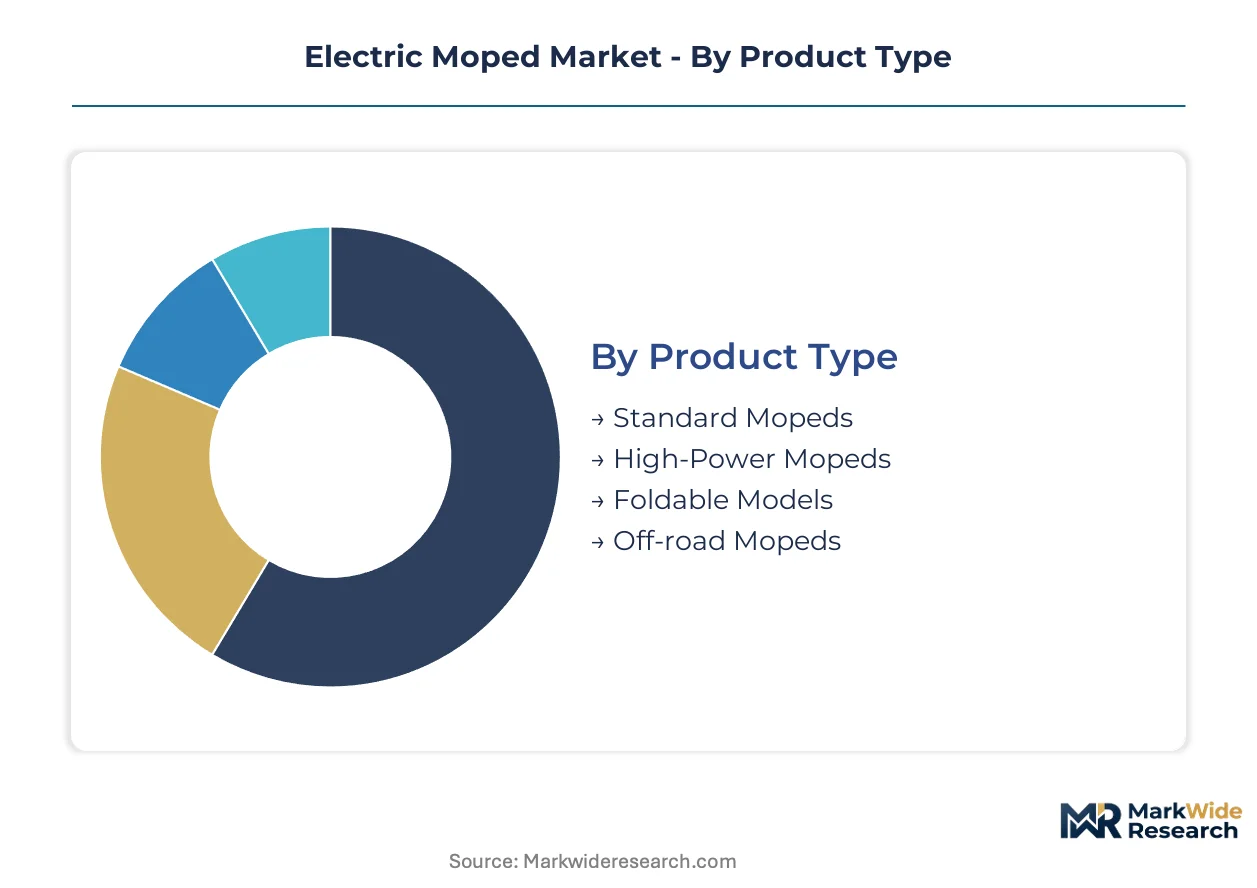
Segmentation in the electric moped market exposes divergent buyer priorities across price sensitivity, duty cycle intensity, and energy access constraints. Manufacturers configure battery chemistry, motor ratings, and frame architectures to match distinct procurement contexts rather than pursuing universal platform strategies.
Product Type:
Speed ratings and frame geometry separate buyers optimizing for purchase price against those prioritizing lane access privileges and load capacity.
- Standard Mopeds:Step-through designs with 25-45 km/h speed ratings and 1.5-3 kWh battery packs dominate household procurement in India, Indonesia, and Vietnam. Demand concentrates where urban congestion charges render petrol alternatives uneconomical and domestic assembly incentives compress sticker prices below internal combustion equivalents.
- High-Power Mopeds:45-90 km/h rated models with enhanced suspension and dual battery configurations command premium positioning in European cities where speed-rated lane access reduces commute times. German and French fleet operators prioritize these specifications for suburban courier routes exceeding 30 kilometers per shift.
- Foldable Models:Collapsible frame architectures with sub-25 kg curb weights address multimodal commuters in Japanese and South Korean dense urban cores.
- Off-road Mopeds:Reinforced suspension and knobby tire configurations serve agricultural and rural terrain applications across Brazil and Thailand.
Volume sits with Standard Mopeds; growth tilts toward High-Power Mopeds.
End User:
Ownership models and utilization intensity create divergent requirements for battery durability, telematics integration, and service response times.
- Personal Use:Individual commuters prioritize purchase price, charging convenience, and styling over connected features. Indian and Vietnamese households dominate this segment where two-wheelers serve as primary family transport.
- Delivery Services:Food and parcel platforms in Jakarta, Ho Chi Minh City, and Bangalore mandate swappable battery architectures and integrated fleet management software. Daily duty cycles exceeding 100 kilometers drive demand for rapid battery exchange networks over overnight charging infrastructure.
- Ride-sharing:Short-term rental operators in Barcelona, Lisbon, and Taipei specify ruggedized frames and vandal-resistant components for high-turnover urban deployment.
- Educational Institutions:Campus security and facilities management fleets across US and Australian universities favor low-speed configurations with simplified maintenance protocols.
Personal Use retains the largest installed base; Delivery Services are expanding most quickly.
Battery Type:
Energy density trade-offs against capital cost and recycling infrastructure shape procurement decisions across price tiers and geographic markets.
- Lithium-ion:NMC and LFP cathode chemistries deliver 150-250 Wh/kg energy density, enabling 60-120 kilometer ranges within 8-15 kg pack weights. Indonesian and Vietnamese manufacturers leverage Chinese cell supply to dominate cost curves in export markets.
- Lead-acid:Heavy 30-50 kg packs with 300-500 cycle life persist in rural Indian and African markets where upfront cost constraints override total ownership economics and recycling infrastructure for lithium chemistries remains undeveloped.
- Nickel-metal Hydride:Intermediate energy density and thermal stability position this chemistry for niche cold-climate applications in Nordic countries.
- Solid-State:Pre-commercial prototypes from Japanese and South Korean suppliers promise enhanced safety and energy density for premium segments.
Lithium-ion holds current volume dominance; Solid-State represents the steepest expansion trajectory once manufacturing scales.
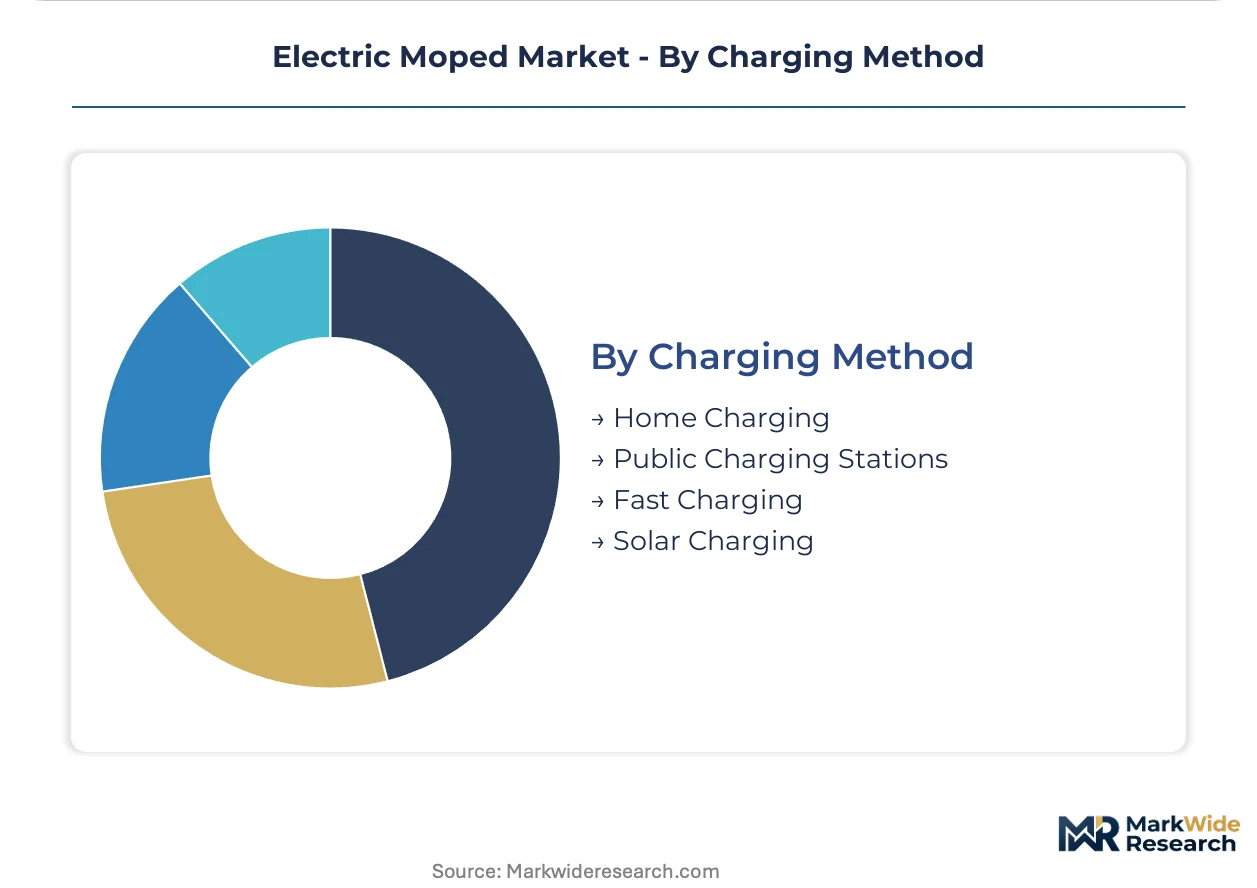
Charging Method:
Residential parking availability and grid reliability determine infrastructure investment patterns across urban density gradients.
- Home Charging:Standard 220V outlet compatibility serves detached and semi-detached housing in suburban European and North American markets where overnight charging aligns with typical 30-50 kilometer daily duty cycles.
- Public Charging Stations:Curbside and parking structure installations in London, Amsterdam, and Singapore address apartment dwellers lacking dedicated parking. Municipal procurement programs accelerate deployment density in central business districts.
- Fast Charging:30-60 minute DC charging protocols target commercial fleets and intercity corridor applications in Germany and France.
- Solar Charging:Off-grid photovoltaic integration serves rural African and Southeast Asian markets with unreliable grid connectivity.
Home Charging captures the largest transaction volume; Public Charging Stations are gaining share fastest as urbanization concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates electric moped manufacturing capacity while consumption fragments across Southeast Asian last-mile delivery corridors and European urban mobility zones. Assembly plants in Zhejiang and Jiangsu provinces feed export demand as domestic Chinese cities restrict petrol two-wheeler registrations. Indonesia, Vietnam, and India now absorb the majority of volume growth as localized production incentives reshape procurement patterns.
China
Domestic manufacturers in Zhejiang and Jiangsu provinces leverage integrated battery cell production to dominate export cost curves. MIIT production quotas and dual carbon goals accelerate petrol moped phase-out in tier-one cities. Yadea and NIU Technologies anchor manufacturing clusters in Wuxi and Changzhou, shipping knock-down kits for final assembly in target export markets.
Indonesia
Jakarta's combustion ban in central business districts forces food delivery platforms to electrify rider fleets ahead of battery cost compression. The national B30 biodiesel mandate and impending EV incentives redirect state procurement toward domestic assembly partners. Surabaya and Bandung industrial corridors host emerging knock-down kit operations serving archipelago distribution.
Vietnam
Hanoi and Ho Chi Minh City congestion charges render petrol mopeds uneconomical for delivery riders covering 100-kilometer daily duty cycles. VinFast's domestic battery manufacturing and swappable network investments reshape total cost of ownership calculations. Domestic assemblers in Hai Phong and Da Nang industrial zones qualify for reduced import tariff schedules on Chinese cell components.
India
Maharashtra and Karnataka state governments mandate electric vehicle quotas in commercial fleet registrations. The FAME subsidy scheme and PLI scheme for advanced chemistry cell manufacturing compel brands to localize assembly in Gujarat and Tamil Nadu corridors. Ola Electric's Tamil Nadu manufacturing hub targets domestic procurement eligibility for state-level delivery fleet tenders.
Germany
Berlin and Munich fleet operators prioritize speed-rated models qualifying for bus lane access privileges on suburban courier routes. The EU F-Gas Regulation and national combustion vehicle restrictions redirect importer portfolios toward electric-only lineups. KBA type-approval requirements and battery passport traceability obligations under EU CSRD reshape component sourcing documentation standards.
Electric Moped Market Competitive Landscape
The competitive structure tilts toward integrated battery manufacturers with captive cell production and swappable network operators. Tier-1 assembly concentration in Chinese industrial provinces contrasts with fragmented brand distribution across Southeast Asian and European markets. Three archetypes dominate: integrated battery-vehicle manufacturers, software-defined platform specialists, and legacy two-wheeler incumbents with dealer density advantages. Capacity expansion in Indian and Indonesian industrial corridors and strategic partnerships for swappable battery interoperability represent the dominant competitive vectors.
Within the integrated manufacturing tier, Yadea and NIU Technologies occupy positions exemplifying cost-curve dominance through captive battery production. Among legacy two-wheeler incumbents, Honda and Yamaha Motor sit within archetypes leveraging established dealer networks across Japanese and Southeast Asian urban corridors. VinFast represents the domestic battery-network integration model emerging in Vietnamese and broader Southeast Asian markets.
| Leading Market Players |
|---|
| Yadea |
| VinFast |
| Piaggio |
| Vmoto |
| Honda |
| Ola Electric |
| Horwin |
| Yamaha Motor |
| NIU Technologies |
| Others |
Pricing and Supply Chain Analysis
Swappable battery architecture adoption simultaneously compresses manufacturing cost curves and concentrates procurement leverage among Chinese and Vietnamese cell producers. This dual shift rewards assemblers with captive battery production while squeezing margin pools for brands dependent on spot-market cell sourcing.
Pricing Analysis
Margin tightening in standard moped tiers reflects lithium-ion cell commoditization and Indonesian domestic assembly incentives compressing sticker prices. Three-tier pricing structure across premium, standard, and economy levels separates connected-vehicle platforms from basic commuter models and lead-acid rural configurations. Cost-down pressure on entry-level segments accelerates because delivery fleet operators negotiate consolidated service contracts bundling vehicles, maintenance, and energy access. Household commuters in Indian and Vietnamese markets exhibit highest price sensitivity; European fleet operators purchasing speed-rated models for lane access privileges show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Chinese cobalt and lithium refining capacity clustering around Jiangxi and Sichuan provinces. Cell production concentrates in China, South Korea, and Japan; final assembly gravitates toward Indonesia, Vietnam, and India as localization incentives reshape procurement eligibility. Motor controllers, battery management systems, and vehicle control units draw from disparate Tier-1 suppliers across Taiwan, Germany, and Japan. Tariff exposure on Chinese cell components threatens non-integrated assemblers during trade friction episodes. Distribution runs through OEM-direct fleet contracts in delivery services and established dealer networks in household commuter segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electric moped market is consolidating around integrated battery-vehicle manufacturers as swappable network economics and localization mandates force capital-light brands toward exit or acquisition.
For Market Incumbents: Extend swappable battery network density ahead of competitor interoperability standards in Indonesian and Vietnamese corridors. Deepen upstream control over LFP cell production to defend margin position against spot-market volatility. Secure qualification under India's PLI scheme and state-level fleet tender requirements before tender windows close to emerging domestic challengers. For New Entrants and Emerging Players: Begin with foldable model segments in Japanese and South Korean dense urban cores where incumbent dealer density remains underdeveloped. Target agricultural off-road applications across Brazil and Thailand where suspension and terrain-specific engineering create defensible niches. Pursue direct-to-fleet sales contracts bypassing traditional retail infrastructure. For Investors and Strategic Acquirers: Exit pathways concentrate in domestic battery-network integration models with qualified manufacturing presence in India, Indonesia, or Vietnam. Long-term viability hinges on captive cell supply or exclusive swappable network access rather than pure vehicle engineering capability. Watch battery passport traceability compliance costs under EU CSRD as the inflection indicator separating acquirable assets from stranded manufacturing footprints.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures LFP cell offtake from Chinese or South Korean producers for cost-curve positioning. |
| Swappable Network Partnership | Expands addressable rider income brackets through battery-as-a-service models in Jakarta and Ho Chi Minh City. |
| Geographic Manufacturing Footprint | Qualifies brands for India's FAME subsidies and state-level delivery fleet procurement mandates. |
| Software-Defined Vehicle Investment | Enables subscription revenue streams through telematics integration with fleet management platforms. |
| Charging Infrastructure Partnership | Addresses residential parking scarcity in dense European and Asian urban cores through public station deployment. |
Research Methodology
Trade databases, vehicle registration records, and customs filings formed the secondary backbone for volume and trade flow calibration. Primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, delivery fleet operations managers, and municipal transport planners validated demand assumptions and regulatory interpretation. Bottom-up unit economics modeling triangulated against top-down market sizing across product type, battery chemistry, end-use segment, and regional production cluster dimensions.
Historical trendline analysis established baseline penetration rates and substitution elasticities against internal combustion equivalents across the projection horizon. Segmentation modeling incorporated speed rating tiers, battery chemistry evolution, charging method adoption patterns, and fleet versus household ownership splits. CAGRs derived from fitted growth curves adjusted for policy inflection points including combustion ban implementation schedules and subsidy phase-out trajectories. Forecast inputs included cell cost compression curves, urban congestion charge expansion, and domestic assembly incentive qualification thresholds.
Underlying measurement precision varies by segment; lithium-ion configurations and established delivery fleet markets carry tighter precision than solid-state prototypes and rural lead-acid demand pockets. Forecasts reflect documented assumptions regarding policy continuity, trade regime stability, and cell chemistry transition timelines. Battery raw material price volatility, trade restriction episodes, and charging infrastructure deployment gaps constitute primary revision risks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
New Energy Vehicle (NEV) Taxi Market
Electric Vehicles
Canada E-Bike Market
Electric Vehicles
China Electric Truck Market
Electric Vehicles
EV Condenser Market
Electric Vehicles
Lithium Battery Electric Scooters Market
Electric Vehicles
Neighbourhood Electric Vehicle Market
Electric Vehicles
NGO Steel in Electric Vehicle Market
Electric Vehicles
Global Electric Scooters Market
Electric Vehicles
Electric Vehicle Battery Trays Market
Electric Vehicles
Asia-Pacific Electric Vehicle Market
Electric Vehicles
Electric Vehicle (EV) Fluids Market
Electric Vehicles
Nordic E-Bike Market
Electric Vehicles
Europe Electric Truck Market
Electric Vehicles
Self Balancing Electric Scooter Market
Electric Vehicles
Three Wheel E-Scooter Market
Electric Vehicles
Recreational Vehicle (RV) Batteries Market