
 Automotive Die Casting Lubricants Market | 2026-2036
Automotive Die Casting Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Die Casting Lubricants Market Intelligence
Tier-1 aluminum die casters serving EV motor housings and battery tray programs is rotating purchasing criteria toward synthetic lubricants with lower thermal residue and extended die life metrics. Fuchs Petrolub SE anchors European supply through backward integration into base oil refining and additive chemistry. Henkel AG & Co. KGaA differentiates via water-based formulations that reduce VOC emissions during casting cycles. Quaker Houghton Inc. dominates North American foundry channels through direct technical service teams embedded at major OEM casting operations.
Automotive die casting lubricants are chemically engineered boundary films applied to mold surfaces to control metal adhesion, regulate thermal shock, and enable clean part ejection in high-pressure aluminum, magnesium, and zinc casting processes; these formulations typically contain graphite, synthetic esters, or water-dilutable polymers at operating temperatures exceeding 300°C to protect H13 tool steel dies across millions of casting cycles. Water-based lubricants lead volume share due to environmental compliance advantages and compatibility with closed-loop coolant systems, while synthetic formulations represent the fastest-expanding category as OEMs specify lower ash content for vacuum-assisted casting of structural EV components. Oil-based products retain margin pools in legacy engine block and transmission housing applications where established foundries prioritize proven release performance over formulation transitions.
EPA air quality standards and OSHA workplace exposure limits constrain solvent-based lubricant use in US foundries, while REACH registration requirements and EU F-Gas Regulation drive substitution toward biodegradable base stocks in European operations. China's MEE environmental enforcement and GB standards on industrial emissions are accelerating water-based adoption among domestic die casting clusters serving BYD, NIO, and Tesla supplier networks. Stakeholders must monitor evolving OEM material specifications for large structural castings and assess captive blending investments versus third-party supply as formulation complexity rises.
Market Dynamics
EV powertrain casting programs are forcing lubricant suppliers to reformulate for vacuum-assisted structural aluminum processes that demand near-zero thermal residue and extended die protection cycles.
Growth Catalysts
- REACH chemical restrictions:European ECHA registration requirements are accelerating biodegradable base stock substitution across German and Italian die casting clusters serving premium OEM transmission programs.
- Closed-loop coolant compatibility:Water-dilutable polymer formulations enable foundries to recover and reuse process water, cutting disposal costs and MEE compliance burdens at Chinese BYD and Tesla supplier networks.
- Motor housing thermal management:EV battery tray and e-axle housing programs specify synthetic ester lubricants capable of protecting H13 dies across 500,000+ high-pressure aluminum casting cycles.
Market Restraints
- Synthetic base oil supply concentration:Backward integration into Group V ester chemistry limits viable suppliers to petrochemical majors with captive refining, squeezing mid-tier blenders.
- EPA OSHA workplace exposure limits:Solvent-based graphite suspensions face phased elimination in US foundries, forcing capital-intensive aqueous system conversions without performance guarantees.
- Technical limitation in magnesium reactivity:Existing water-based formulations trigger hydrogen evolution during AZ91D casting, constraining adoption in lightweighting programs targeting seat frames and steering columns.
Strategic Opportunities
- India PLI scheme for auto component manufacturing:Domestic die casting capacity expansion around Pune and Chennai creates first-mover positioning for water-based lubricant technical service partnerships.
- EU F-Gas Regulation phase-down:Fluorinated gas restrictions in die temperature control systems indirectly favor lubricants enabling lower-temperature casting windows.
- AI-assisted die wear monitoring:Convergence of IoT thermal sensors and predictive maintenance platforms creates subscription-based lubricant optimization services at embedded OEM foundries.
Industry Challenges
- Formulation chemist scarcity:Expertise in high-temperature polymer stability and tribology at aluminum-magnesium interfaces remains concentrated among retiring specialists at European additive houses.
- MEE GB standards compliance timeline:Chinese domestic foundries face compressed certification windows for volatile organic compound testing, delaying qualified supplier status.
- Legacy oil-based system integration:Established engine block foundries resist aqueous conversion due to incompatible sludge handling infrastructure and retrained operator requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Die Casting Lubricants Market |
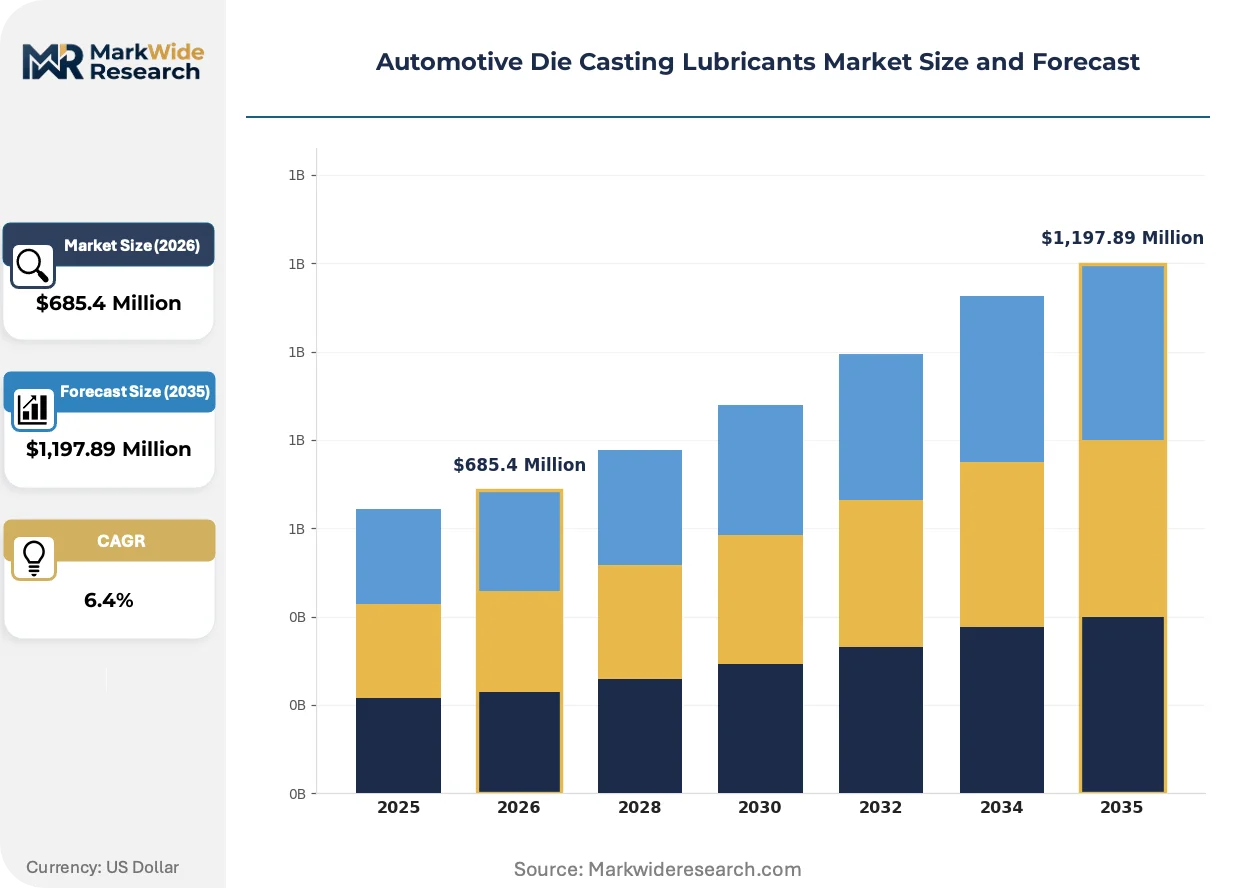
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,197.89 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Graphite, Water-Based, Oil-Based, Synthetic Application: Engine Components, Transmission Parts, Brake Systems, Chassis Frames End User: Vehicle Manufacturers, Tier-1 Suppliers, Aftermarket Providers, OEMs Packaging Type: Drums, Pails, Totes, Bulk |
| Companies Covered | Fuchs Petrolub SE, Henkel AG & Co. KGaA, Quaker Houghton Inc., Shell, Chem-Trend LP, ExxonMobil Corporation, TotalEnergies SE, Castrol, MORESCO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Die Casting Lubricants Market Strategic Shifts & Innovations
Formulation chemistry is pivoting toward synthetic water-dilutable systems as OEM material specifications harden around structural castings with cosmetic surface requirements.
Synthetic ester lubricants with ash content below 0.05% are displacing graphite-based formulations in vacuum-assisted die casting cells producing one-piece EV rear underbodies. BMW and Mercedes-Benz structural casting programs specify these chemistries to eliminate thermal residue that interferes with weldability and anodizing. The displacement is compressing legacy oil-based product margins in European premium OEM supply chains.
EU Green Deal chemical restrictions and REACH authorization timelines are forcing base stock substitutions ahead of 2030 sunset dates for certain mineral oil distillates. German foundries serving Volkswagen and Porsche programs now require biodegradable ester content exceeding 60% by mass. Suppliers without backward integration into sustainable base oil refining face exclusion from qualified vendor lists.
Buyer concentration among EV-dedicated mega-casting plants is compressing lubricant procurement to direct OEM technical partnerships rather than distributor channels. Tesla's Berlin and Austin gigacasting facilities negotiate multi-year formulation development contracts with embedded service engineers. This channel shift is marginalizing traditional foundry supply houses in North American and European EV supply chains.
Automotive Die Casting Lubricants Market Segmentation
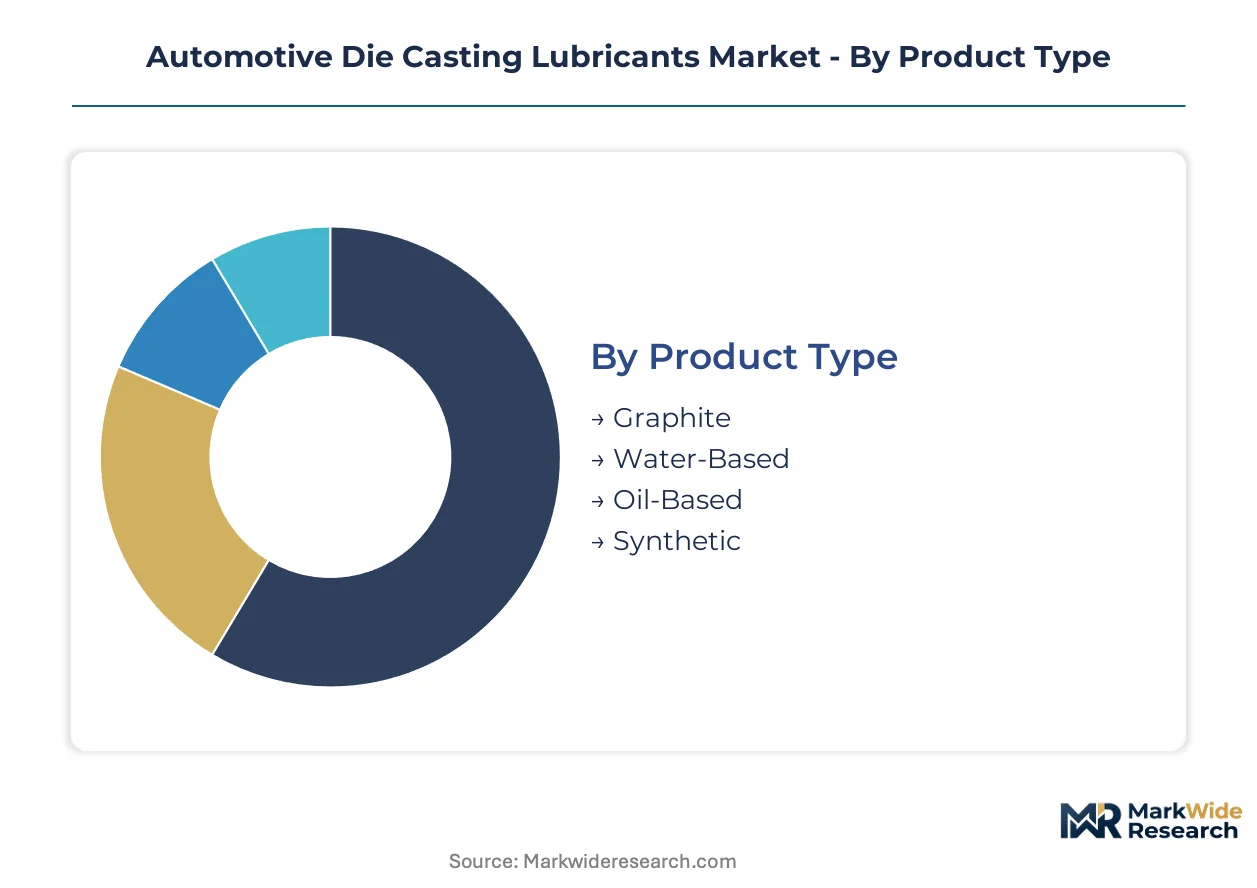
Automotive die casting lubricant procurement patterns diverge sharply between high-volume OEM foundries demanding synthetic formulations and legacy transmission suppliers maintaining oil-based systems. Segmentation reveals how formulation chemistry, application thermal requirements, and packaging logistics interact to determine supplier positioning across EV and ICE supply chains.
Product Type:
Domestic consumption concentrates in water-based and synthetic formulations serving EV mega-casting plants in Germany, China, and Mexico, while oil-based and graphite products retain export-led demand from established Indian and Eastern European foundries serving legacy engine programs.
- Water-Based:Polymer-dilutable formulations enable closed-loop coolant recovery at Chinese MEE-compliant facilities serving BYD and Tesla networks. Foundries in Stuttgart and Shanghai specify these systems to cut disposal costs while maintaining H13 die protection across 300,000+ casting cycles. Water-based products command the established base. The steepest expansion runs through synthetic formulations.
- Synthetic:Ester-based chemistries with sub-0.05% ash content protect vacuum-assisted structural casting dies at BMW and Mercedes-Benz EV underbody programs. German additive houses backward-integrated into Group V base oil refining control qualified supplier lists for these specifications. Synthetic lubricants are climbing the fastest as OEMs specify near-zero thermal residue for weldable aluminum castings.
- Graphite:Suspension-based release agents serve magnesium AZ91D seat frame casting where hydrogen evolution risks constrain water-based alternatives at Japanese tier-1 suppliers.
- Oil-Based:Legacy mineral oil formulations retain procurement at Detroit-area transmission housing foundries resisting aqueous system capital conversion.
Synthetic formulations gain share fastest in EV-dedicated casting cells, while water-based products anchor volume in regulatory-constrained jurisdictions.
Application:
Cost tier stratification separates premium synthetic lubricants specified for structural EV components from standard-grade products serving brake and chassis applications with less stringent surface finish requirements.
- Engine Components:Oil-based and graphite formulations protect aluminum cylinder block and head casting dies at legacy Volkswagen and Ford foundries in Puebla and Cologne, though procurement volumes face compression as ICE program allocations decline.
- Transmission Parts:Dual-clutch housing casting at Getrag and ZF facilities in Saarbrücken specifies synthetic ester lubricants enabling 500,000-cycle die life metrics demanded by premium OEM technical service agreements.
- Brake Systems:Standard water-based polymers serve caliper and master cylinder casting at high-volume Mexican export foundries supplying Detroit Three brake module integrators.
- Chassis Frames:Magnesium-intensive seat frames and steering columns at Korean tier-1 suppliers require specialized graphite formulations managing AZ91D reactivity without aqueous hydrogen generation.
Transmission and engine applications retain the revenue base. Structural EV component casting drives the steepest formulation premiumization.
End User:
Customer type determines technical service intensity, with vehicle manufacturers and tier-1 suppliers embedding lubricant engineers directly at casting cells while aftermarket providers and secondary OEMs transact through distributor channels.
- Vehicle Manufacturers:Tesla's Berlin and Austin gigacasting facilities negotiate multi-year formulation development contracts with captive service engineers, marginalizing traditional supply houses.
- Tier-1 Suppliers:Magna and Continental aluminum die casting operations in Graz and Regensburg rotate procurement criteria toward die life guarantees and thermal residue specifications enforced through direct supplier audits.
- Aftermarket Providers:Independent foundry service companies in India's Pune cluster source water-based lubricants through regional distributors lacking technical integration.
- OEMs:Secondary equipment manufacturers serving commercial vehicle transmission rebuild programs maintain oil-based product loyalty due to incompatible sludge handling infrastructure.
Tier-1 suppliers concentrate the highest-margin technical partnerships. Vehicle manufacturers are consolidating procurement to direct OEM relationships fastest.
Packaging Type:
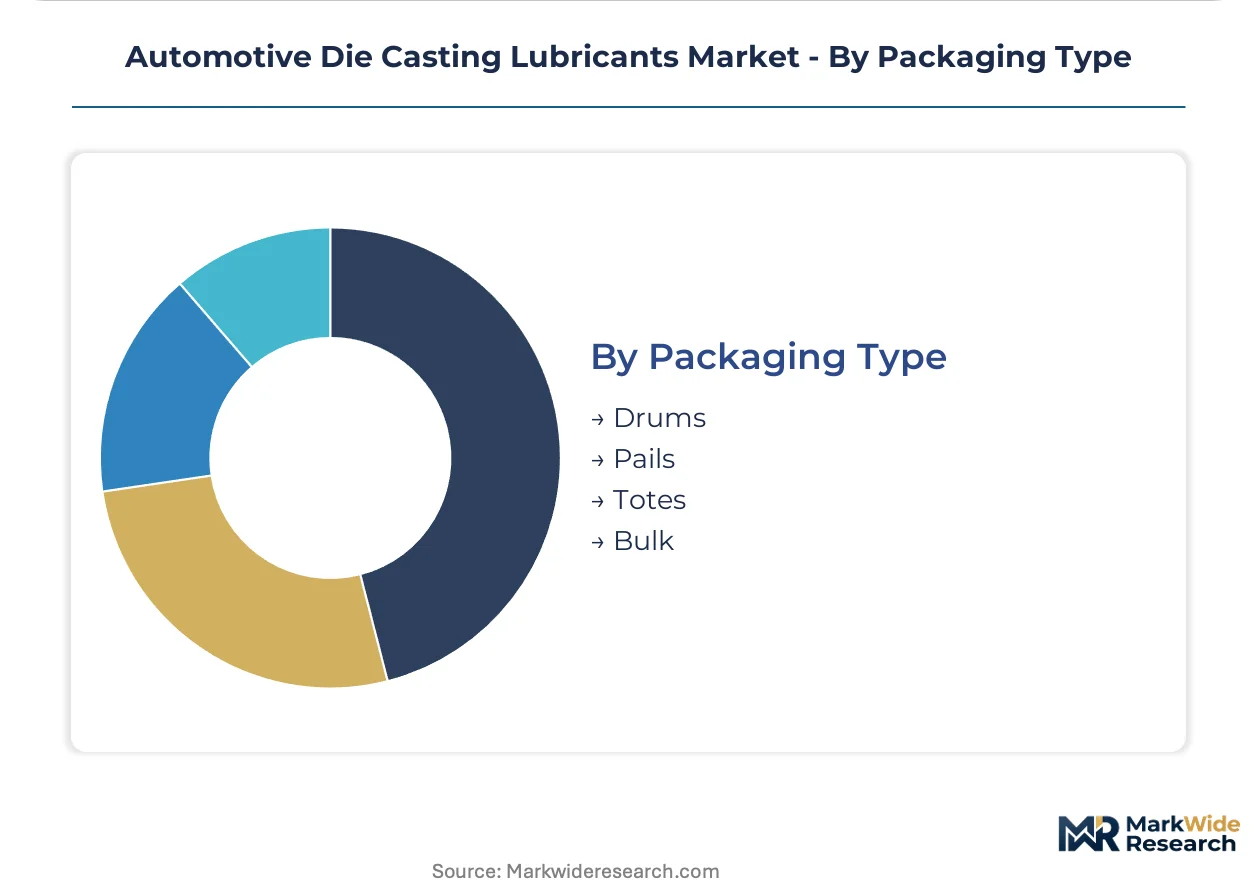
Volume scale and supply chain proximity dictate packaging selection, with bulk and tote systems serving integrated mega-casting plants while drums and pails retain relevance at smaller batch operations and import-dependent markets.
- Bulk:Direct pipeline delivery of synthetic ester concentrates eliminates packaging waste at Tesla Berlin and BMW's Debrecen EV component campus, requiring supplier investment in on-site dilution and metering systems.
- Totes:Intermediate bulk containers enable just-in-time polymer concentrate delivery at Chinese BYD supplier networks managing MEE environmental compliance documentation.
- Drums:Standard 55-gallon steel containers serve mid-volume transmission housing foundries in Guanajuato, Mexico, balancing inventory flexibility against handling labor costs.
- Pails:Five-gallon packaging retains procurement at Indian aftermarket rebuild shops and small magnesium die casting operations in Japan with limited storage infrastructure.
Bulk and tote systems anchor high-volume OEM supply. Drum and pail formats retain footholds in fragmented aftermarket and import channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput underwrites Germany's dominance in European die casting lubricant distribution, while the Yangtze River Delta's manufacturing density anchors Asia-Pacific demand concentration.
Germany
Stuttgart and Munich automotive clusters drive synthetic ester procurement for BMW and Mercedes-Benz EV structural casting programs. REACH authorization timelines and EU Green Deal chemical restrictions force biodegradable base stock adoption ahead of 2030 deadlines. Bavarian foundries serving Porsche transmission housing operations now mandate 60% minimum ester content in qualified supplier agreements.
China
BYD and Tesla supplier networks in Shenzhen and Shanghai accelerate water-based polymer adoption for closed-loop coolant compliance. MEE environmental enforcement and GB standards on industrial emissions compress VOC testing certification windows for domestic foundries. Ningbo die casting clusters serving NIO motor housing programs face accelerated reformulation requirements under dual carbon goals implementation.
United States
Detroit Three transmission housing foundries in Michigan and Ohio maintain oil-based system loyalty despite EPA air quality standards pressuring solvent-based graphite elimination. OSHA workplace exposure limits constrain legacy foundry operations without capital conversion guarantees. Tesla's Austin gigacasting facility negotiates direct synthetic lubricant partnerships bypassing traditional supply channels.
Mexico
Guanajuato and Nuevo León export foundries supply brake caliper and transmission housing castings to Detroit Three integrators through high-volume water-based polymer systems. NAFTA-origin content requirements and proximity logistics favor bulk tote delivery from US additive houses. Querétaro aerospace-adjacent die casters experiment with synthetic formulations for emerging EV supplier qualification.
India
Pune and Chennai auto component clusters expand die casting capacity under PLI scheme incentives, creating technical service partnership opportunities for water-based lubricant suppliers. BIS certification requirements and compressed domestic content timelines challenge mid-tier blenders without captive base oil refining. Mahindra and Tata supplier networks prioritize drum-format flexibility over bulk infrastructure investment.
Automotive Die Casting Lubricants Market Key Industry Players
Concentration sits with petrochemical majors possessing backward integration into Group V ester chemistry and additive synthesis. The supplier base stratifies between European additive houses controlling REACH-compliant formulation IP and North American technical service organizations embedded at OEM foundries. Three archetypes dominate: integrated petrochemical refiners, specialty chemical formulators, and regional distributors lacking technical depth. Competitive dynamics center on captive base oil supply security and direct OEM technical partnership capture versus distributor channel maintenance.
Among European-integrated formulators, Fuchs Petrolub SE and Henkel AG & Co. KGaA exemplify the backward-integrated archetype controlling qualified supplier lists through sustainable base oil refining investments. Quaker Houghton Inc. occupies a position representing North American technical service intensity at embedded OEM operations. These three entities anchor the competitive structure without exhaustive market coverage.
| Leading Market Players |
|---|
| Fuchs Petrolub SE |
| Henkel AG & Co. KGaA |
| Quaker Houghton Inc. |
| Shell |
| Chem-Trend LP |
| ExxonMobil Corporation |
| TotalEnergies SE |
| Castrol |
| MORESCO Corporation |
| Others |
Cost & Logistics Intelligence
REACH authorization timelines gate both supplier qualification and price differentiation simultaneously, forcing biodegradable ester investments that separate REACH-compliant formulators from commodity blenders while compressing margins on legacy mineral oil products.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations, with synthetic ester concentrates commanding premium-mid-economy pricing differentiation based on ash content certification and die life guarantee terms. Price differentiation hinges on backward integration into Group V base oil refining and embedded technical service intensity. Cost compression in oil-based tiers is intensifying because legacy foundries resist aqueous system conversions. Tier-1 suppliers embedded at BMW and Tesla facilities demonstrate lowest price sensitivity; Indian aftermarket rebuild shops exhibit highest.
Supply Chain Analysis
Germany and China anchor global supply of synthetic ester base stocks and water-dilutable polymer concentrates, while Mexico serves as regional blending hub for North American OEM networks. Formulation chemistry draws from Group V ester feedstocks, graphite suspensions, and water-treatment additives. Single-source vulnerability concentrates around European additive houses controlling REACH-compliant IP. Distribution runs through direct OEM technical partnerships at mega-casting plants, marginalizing traditional foundry supply houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where die wear monitoring IoT convergence creates subscription-based lubricant optimization ecosystems, displacing transactional procurement.
For Market Incumbents: Compound technical service intensity through captive additive synthesis investments that lock out mid-tier blenders from qualified supplier lists. Defend against aqueous system conversion risks at legacy foundries by offering capital-equipment financing bundled with formulation supply. Prioritize backward integration into sustainable base oil refining ahead of EU Green Deal deadlines. For New Entrants and Emerging Players: Differentiate on MEE-compliant water-based formulations for India's PLI-scheme auto component clusters around Pune and Chennai. Target technical service partnerships at domestic foundries lacking REACH-compliant supply access. Pursue white-label toll manufacturing for European additive houses seeking geographic diversification. For Investors and Strategic Acquirers: EU F-Gas Regulation phase-down reshapes the acquisition landscape toward lubricants enabling lower-temperature casting windows. Five-to-ten-year viability favors formulators with captive ester chemistry and embedded OEM service contracts. Watch for consolidation signals when mid-tier blenders face REACH registration cost thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Group V Ester Refining | Captive base oil supply secures qualified supplier status at BMW and Mercedes-Benz EV programs. |
| Embedded Technical Service Partnerships | On-site formulation engineers at Tesla gigacasting facilities displace distributor channels. |
| Closed-Loop Coolant System Compatibility | Water-dilutable polymers enable MEE compliance at BYD supplier networks in Shenzhen. |
| AI-Assisted Die Wear Monitoring Integration | IoT sensor convergence creates subscription revenue streams at predictive maintenance platforms. |
| Biodegradable Base Stock Substitution | 60% minimum ester content mandates from Bavarian foundries force formulation chemistry pivots. |
Research Approach
Cross-validation between foundry operations data and additive house formulation disclosures anchors the qualitative findings. Primary interviews with die casting plant managers, OEM procurement leads, technical R&D directors at lubricant suppliers, and channel distribution partners combined with secondary validation from customs trade records, SEC 10-K filings, and automotive production databases. Bottom-up volume modeling and top-down value triangulation reconcile segment outputs.
Sensitivity analysis across formulation chemistry tiers, end-use application thermal requirements, packaging logistics formats, and regional regulatory clusters shapes the analytical framework. CAGRs derive from die life cycle projections and OEM program allocation shifts across the modeling period. Vacuum-assisted structural casting adoption rates and MEE enforcement intensity serve as key forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained EV powertrain casting program allocations or accelerated REACH authorization timelines would require recalibration. Forecasts reflect assumptions on base oil supply continuity and foundry capital conversion willingness. Recalibration cycles align with material shifts in EU Green Deal implementation and Chinese dual carbon goal enforcement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Singapore Automotive Lubricants Market
Lubricants
Specialty Lubricants Market
Lubricants
Thailand Automotive Engine Oils Market
Lubricants
Poland Industrial Lubricants Market
Lubricants
China Commercial Vehicles Lubricants Market
Lubricants
Africa Lubricants Market
Lubricants
Global Friction Modifiers Market
Lubricants
US Industrial Lubricants Market
Lubricants
Automotive Suspension System Lubricants Market
Lubricants
Polyurea-Based Greases Market
Lubricants
Kenya Lubricants Market
Lubricants
Global Grease Cartridges Market
Lubricants
India Industrial Lubricants Market
Lubricants
Italy Automotive Lubricants Market
Lubricants
Japan Automotive Lubricants Market
Lubricants
Malaysia Commercial Vehicles Lubricants Market