
 Italy Automotive Lubricants Market | 2026-2036
Italy Automotive Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Automotive Lubricants Market Foresight
Low-viscosity synthetic formulations and Group III base oil upgrading are reshaping how Italian blenders engineer products for fuel economy mandates. Eni S.p.A. leverages its Ravenna refinery complex to sustain captive base oil supply for premium passenger car motor oils. Shell Italia S.p.A. anchors its position through extensive quick-lube service partnerships across northern Italy's dense vehicle population. TotalEnergies Marketing Italia S.r.l. differentiates via OEM co-development programs with domestic transmission and engine manufacturers.
Automotive lubricants are formulated mixtures of base oils and performance additives engineered to reduce friction, dissipate heat, and prevent wear in powertrain and drivetrain components, with SAE viscosity grades and ACEA performance categories defining compatibility with specific engine architectures. Engine oil occupies the dominant value share given high replacement frequency and stringent OEM fill specifications, while transmission fluid generates premium margins as dual-clutch and continuously variable transmissions proliferate in Italian-assembled vehicles. The aftermarket channel structures volume flows through independent workshops and fast-fit chains, though OEMs and Tier-1 suppliers capture strategic influence via factory-fill contracts and warranty-linked service protocols.
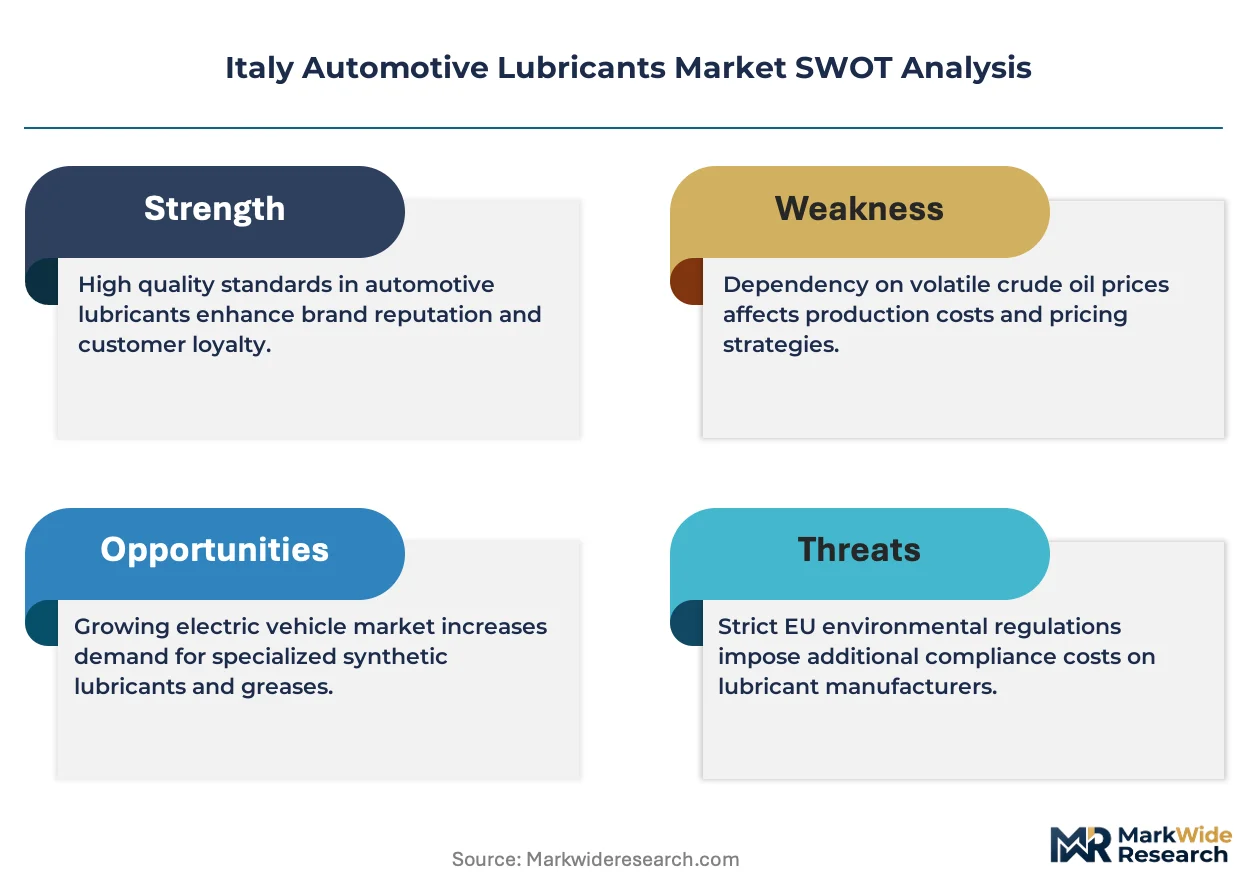
Italy's Ministry of Ecological Transition implements EU Green Deal-aligned decarbonization pathways that pressure lubricant producers toward bio-based and re-refined content quotas, while ECHA's REACH framework governs additive chemistry registration and substitution obligations. The National Recovery and Resilience Plan channels investment into sustainable mobility infrastructure, indirectly conditioning fleet renewal rates and lubricant demand profiles. Stakeholders must weigh backward integration into base oil refining against specialty additive sourcing partnerships as regulatory thresholds tighten and OEM specification cycles compress.
Market Dynamics
Euro 7 emission standards are compressing specification cycles and forcing lubricant formulators to engineer lower-viscosity, higher-durability products that protect aftertreatment systems under tighter thermal and soot-loading regimes.
Growth Catalysts
- Fleet electrification transition:Hybrid powertrains retain internal combustion engines requiring specialized thermal management fluids, extending addressable demand for advanced lubricant categories in commercial logistics.
- REACH framework evolution:ECHA's substance restriction roadmaps accelerate additive chemistry innovation, rewarding early movers with regulatory-compliant product portfolios ahead of compliance deadlines.
- Lombardy-Piedmont manufacturing density:Automotive OEM and Tier-1 concentration in northern Italy sustains high-frequency factory-fill and service-fill procurement volumes through captive distribution networks.
Market Restraints
- Group II/III base oil import dependence:Italian refining capacity constraints force blenders to source premium base stocks from northwest European suppliers, exposing margins to Rotterdam-ARA price volatility and freight differentials.
- Extended drain interval engineering:OEM fill specifications now routinely exceed 30,000 kilometers for synthetic formulations, structurally reducing lubricant consumption per vehicle-kilometer across the installed base.
- Bio-based feedstock cost premiums:Re-refined and vegetable-derived base oils command 15-40% price premiums over virgin mineral equivalents, limiting mass-market penetration despite sustainability mandates.
Strategic Opportunities
- Southern Italy aftermarket penetration:Sicily and Calabria exhibit lower quick-lube network density and deferred maintenance patterns, creating whitespace for service-format expansion and consumer education investments.
- Industrial gearbox fluid diversification:Precision manufacturing and packaging machinery sectors in Emilia-Romagna generate demand for specialized synthetic gear oils outside traditional automotive channels.
- PNRR sustainable mobility funding:Italy's National Recovery and Resilience Plan channels infrastructure investment toward fleet renewal, indirectly conditioning lubricant demand profiles toward premium synthetic categories.
Industry Challenges
- Additive chemist talent scarcity:Formulation expertise in friction modifier and antioxidant chemistry concentrates among aging specialist cohorts, constraining R&D throughput for specification-responsive product development.
- OEM approval timeline compression:Accelerated engine architecture cycles reduce available testing windows for ACEA and manufacturer-specific certifications, forcing parallel-track investment in multiple unproven specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Automotive Lubricants Market |
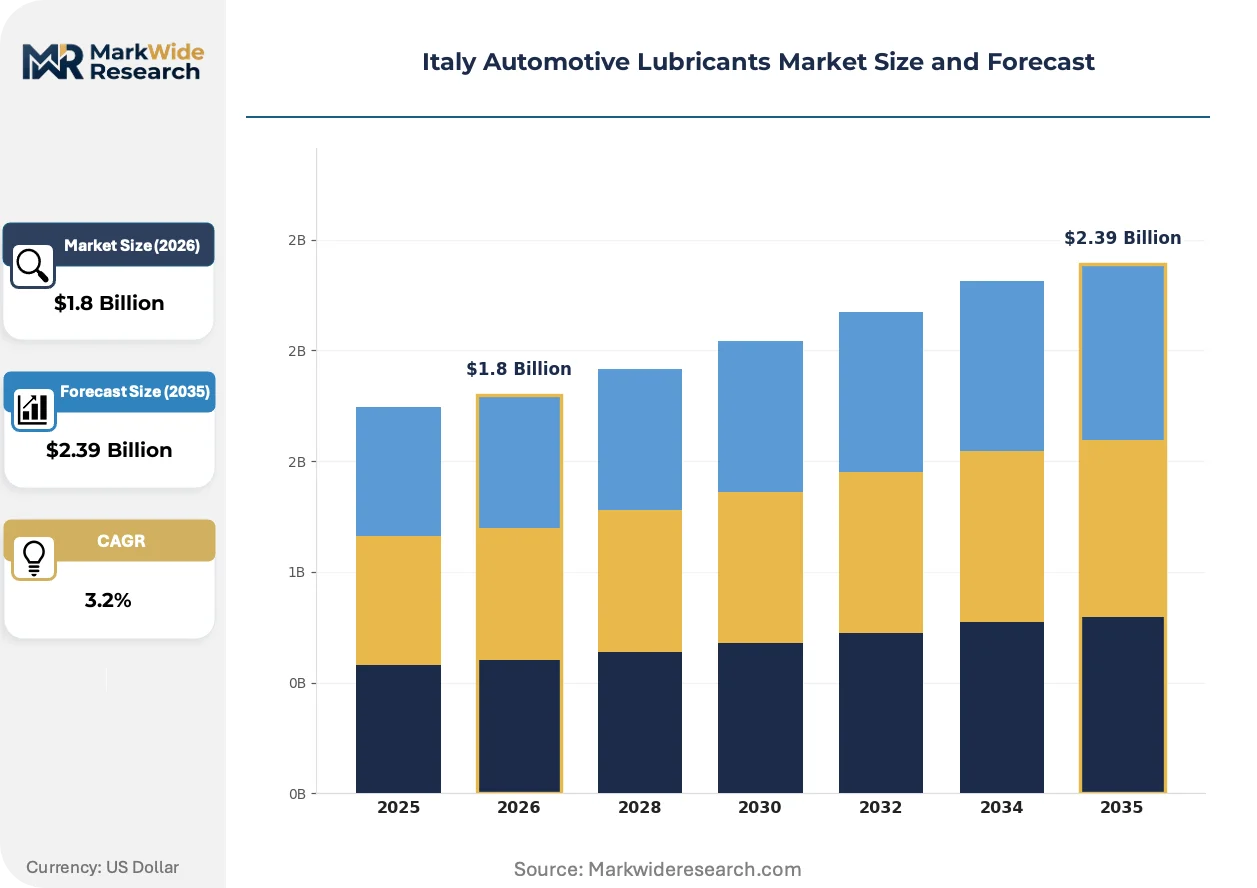
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.39 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Grease, Hydraulic Oil End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Dealerships Application: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Trucks, Motorcycles Distribution Channel: Retail, Online, Wholesale, Direct Sales |
| Companies Covered | Eni S.p.A., Shell Italia S.p.A., BP Italia S.p.A. (Castrol), ExxonMobil Italia S.r.l., TotalEnergies Marketing Italia S.r.l., Fuchs Petrolub SE, PETRONAS Lubricants International, Q8 Italia S.p.A., Liqui Moly GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Automotive Lubricants Market Shifts & Advancements
Formulation chemistry and service delivery models are diverging sharply as electrification, regulatory chemistry constraints, and fleet professionalization reshape how lubricants are engineered, specified, and consumed.
Ultra-low-viscosity 0W-8 and 0W-12 passenger car motor oils are rendering obsolete conventional 5W-30 formulations in hybrid thermal management applications. Stellantis and domestic OEM assembly lines in Turin and Melfi are specifying these grades for new-generation downsized engines. The shift is compressing blender R&D cycles and rendering obsolete legacy testing protocols designed for higher-viscosity matrices.
Italy's Ministry of Ecological Transition is implementing EU Green Deal-aligned decarbonization pathways that mandate bio-based and re-refined content quotas in public procurement. ECHA's REACH framework simultaneously governs additive registration and substitution obligations for zinc dialkyldithiophosphate and other chemistries. Domestic blenders are responding by accelerating partnerships with Spanish and German re-refining facilities to secure compliant base oil supply.
Fleet operators in commercial logistics are consolidating lubricant procurement through direct supplier contracts rather than workshop-mediated purchases. Large transport operators in the Milan-Bologna corridor now negotiate annual volume agreements with blenders for bulk delivery to captive maintenance facilities. This disintermediation is most visible in refrigerated freight and parcel delivery segments where vehicle utilization rates exceed 250,000 kilometers annually.
Italy Automotive Lubricants Market Segmentation
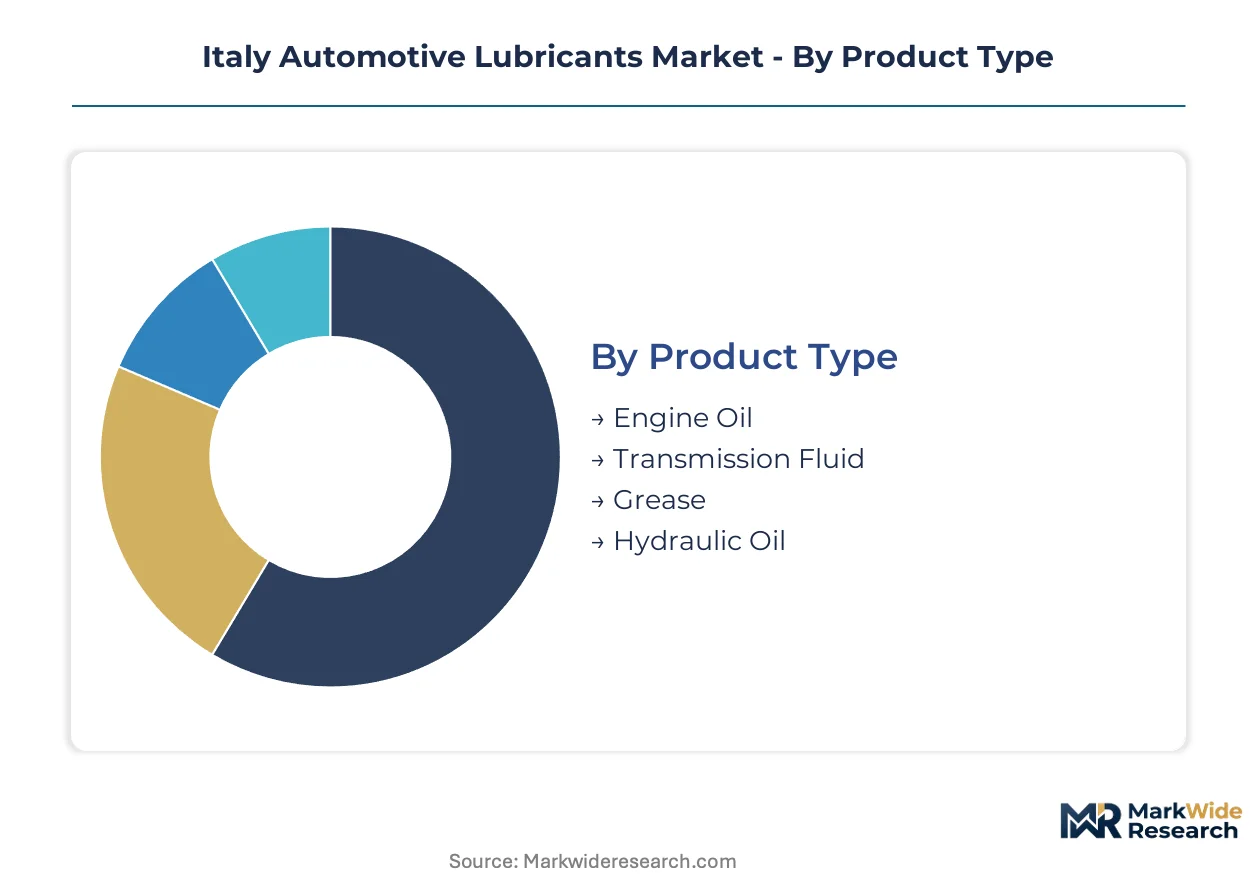
Segmentation in Italy's automotive lubricants market reveals how specification complexity, procurement authority, and service infrastructure shape volume flows. Each dimension exposes distinct margin structures and competitive access points for blenders and distributors.
Product Type:
Application intensity and replacement frequency vary sharply across lubricant categories, with thermal stress regimes and OEM specification cycles determining value capture potential.
- Engine Oil:Formulations blend Group II/III base stocks with detergent-dispersant and anti-wear additive packages to meet ACEA sequences and manufacturer-specific approvals. Demand concentrates in the Milan-Turin corridor where Stellantis assembly plants and dense aftermarket service networks drive factory-fill and service-fill procurement. Euro 7 thermal management requirements are forcing rapid reformulation toward lower-viscosity grades.
- Transmission Fluid:Specialized synthetic formulations manage friction coefficients in dual-clutch and continuously variable transmissions proliferating across Italian vehicle production. Procurement runs through OEM technical centers and Tier-1 transmission suppliers in Emilia-Romagna, where precision engineering clusters sustain premium pricing for factory-fill contracts.
- Grease:Thickener-stabilized lubricants serve chassis and bearing applications with extended service intervals. Commercial fleet operators in logistics corridors represent the core demand pool.
- Hydraulic Oil:Anti-wear additive systems protect high-pressure circuits in commercial vehicle braking and suspension systems. Agricultural and construction equipment dealers in Veneto and Lombardy anchor distribution.
Engine oil commands the established base. The steepest expansion runs through transmission fluid as automated gearbox penetration climbs.
End User:
Procurement authority and specification control determine how lubricant volumes flow through the value chain, with warranty conditions and captive maintenance infrastructure shaping supplier relationships.
- OEMs:Vehicle manufacturers dictate factory-fill specifications through technical service agreements that lock in blenders for entire model generations. Stellantis technical centers in Turin and Melfi source directly through tender processes that prioritize supply security and co-development capabilities.
- Aftermarket Providers:Independent workshops and fast-fit chains purchase through distributor networks or direct blender agreements based on volume tiers and technical support packages. The Lombardy-Piedmont region's dense vehicle population sustains the highest service bay density.
- Tier-1 Suppliers:Component manufacturers procure lubricants for in-house testing, assembly line operations, and warranty service protocols. Transmission and axle suppliers in Bologna and Modena represent concentrated demand.
- Dealerships:Authorized service networks execute warranty-linked oil changes using OEM-specified formulations, capturing premium-margin service-fill volumes.
Aftermarket providers absorb the volume base. OEMs concentrate the highest-margin factory-fill procurement.
Application:
Vehicle duty cycles and engine architecture diversity create distinct lubricant performance requirements, with thermal loading patterns and drain interval engineering determining formulation value.
- Passenger Vehicles:Downsized turbocharged engines and hybrid thermal management systems demand ultra-low-viscosity 0W-8 and 0W-12 formulations with enhanced oxidative stability. Northern Italy's high hybrid penetration drives specification advancement.
- Commercial Vehicles:Long-haul freight operations prioritize extended drain intervals and aftertreatment system compatibility under Euro 7 soot-loading regimes. Fleet operators in the Milan-Bologna logistics corridor negotiate direct supply agreements.
- Heavy-Duty Trucks:High-torque diesel architectures require robust detergent packages and shear-stable viscosity modifiers. Alpine transit routes stress cold-flow and high-temperature performance simultaneously.
- Motorcycles:Wet-clutch compatibility and high-RPM thermal management distinguish scooter and motorcycle oils from passenger car formulations. Southern Italy's two-wheeler density sustains regional demand concentration.
Passenger vehicles anchor volume consumption. Commercial vehicles generate the most rapid specification advancement.
Distribution Channel:
Channel economics reflect inventory velocity, technical service requirements, and customer scale, with digital platforms disrupting traditional wholesale relationships.
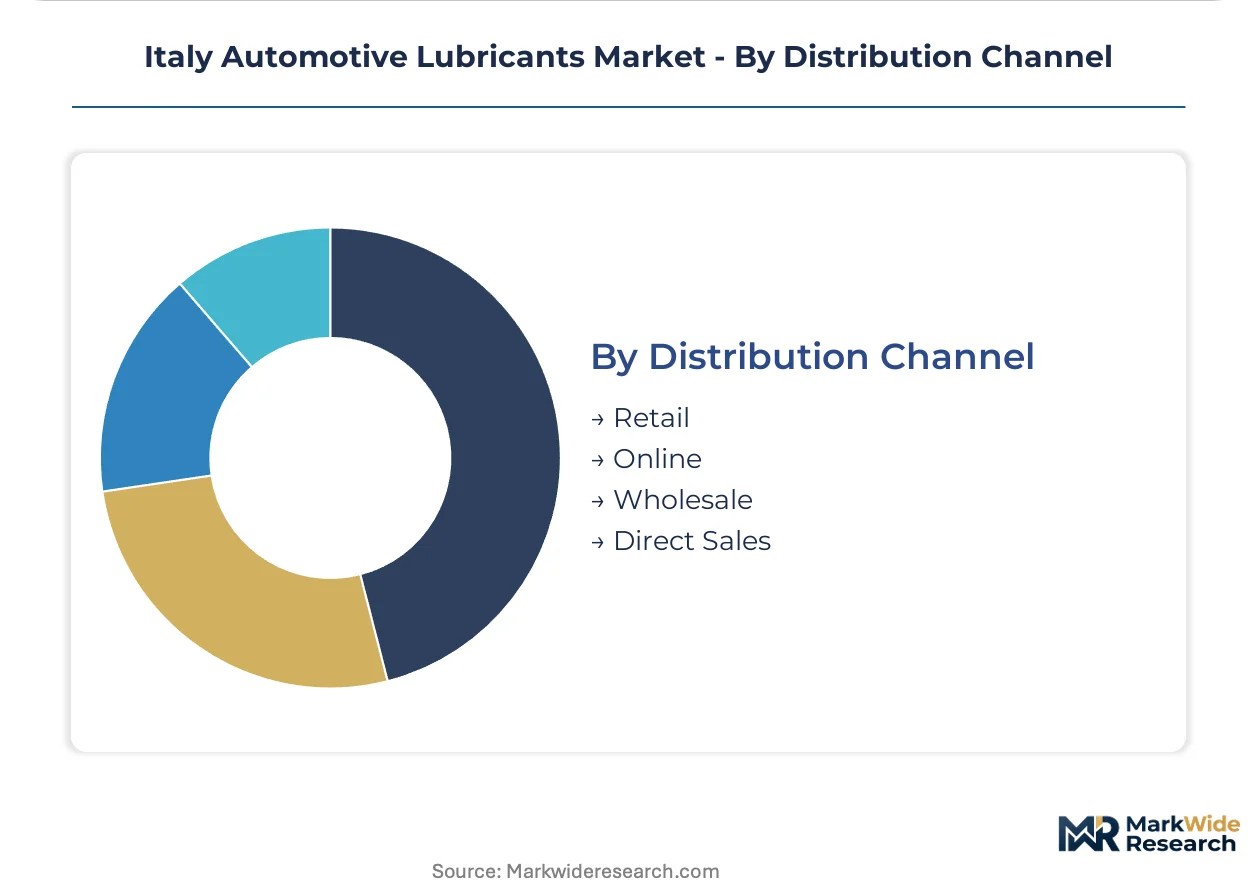
- Retail:Automotive parts chains and service stations serve DIY consumers and small independent workshops with packaged lubricants. Shelf space competition intensifies around premium synthetic tiers.
- Online:E-commerce platforms aggregate fragmented demand from enthusiast segments and small fleet operators, with logistics networks overcoming traditional distribution density requirements.
- Wholesale:Regional distributors hold inventory for independent workshops, extending credit terms and technical training as competitive differentiators. Campania and Sicily exhibit lower wholesale network penetration.
- Direct Sales:Blenders negotiate annual volume contracts with large fleet operators and industrial users, disintermediating traditional channel margins. Refrigerated freight and parcel delivery segments lead this shift.
Wholesale channels retain the volume foundation. Direct sales capture the fastest structural gain.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rotterdam-ARA base oil flows supply Italian blenders through the Rhine-Alpine corridor, with northwest European refineries anchoring feedstock security for the peninsula's formulation capacity.
Lombardy
Milan's dense commercial fleet concentration drives premium synthetic demand through direct procurement contracts. The region aligns with Italy's Ministry of Ecological Transition mandates for bio-based content in public procurement. Stellantis technical centers in Turin anchor factory-fill specification development for Euro 7-compliant formulations.
Piedmont
Automotive OEM assembly plants sustain high-frequency lubricant consumption through captive supply agreements. ECHA's REACH framework governs additive chemistry substitution timelines affecting local formulators. The Turin-Mirafiori manufacturing cluster concentrates transmission fluid development for dual-clutch architectures.
Veneto
Agricultural and construction equipment dealers generate specialized hydraulic oil demand across the Po Valley. Italy's National Recovery and Resilience Plan channels infrastructure investment toward fleet renewal in the region. Verona and Padua distribution hubs extend coverage into Alpine transit corridors stressing cold-flow performance requirements.
Emilia-Romagna
Precision manufacturing clusters in Bologna and Modena drive industrial gearbox fluid diversification beyond traditional automotive channels. The EU Green Deal's decarbonization pathways pressure processors toward re-refined base oil adoption. Tier-1 transmission suppliers concentrate factory-fill procurement through technical service agreements.
Sicily
Deferred maintenance patterns and low quick-lube network density create aftermarket whitespace for service-format expansion. Southern Italy's two-wheeler density sustains regional scooter oil demand concentration. Palermo and Catania logistics constraints elevate landed costs for bulk lubricant deliveries from northern blending facilities.
Italy Automotive Lubricants Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a structure where refinery-integrated majors anchor supply security while independent blenders pursue specification niches. The vendor base stratifies into three tiers: captive-refinery operators with backward integration into base oil production, formulation specialists with additive technology partnerships, and regional distributors with workshop network penetration. Dominant competitive moves include direct fleet contract negotiation disintermediating traditional wholesale channels and co-development programs with domestic OEM technical centers locking in factory-fill specifications.
Among Italy-based integrated operators, Eni S.p.A. and Q8 Italia S.p.A. occupy positions reflecting refinery-captive supply advantages. Shell Italia S.p.A. represents the multinational major archetype with extensive service network partnerships. These three exemplify how geographic anchoring and channel control differentiate positioning against formulation-focused competitors lacking upstream base oil security.
| Leading Market Players |
|---|
| Eni S.p.A. |
| Shell Italia S.p.A. |
| BP Italia S.p.A. (Castrol) |
| ExxonMobil Italia S.r.l. |
| TotalEnergies Marketing Italia S.r.l. |
| Fuchs Petrolub SE |
| PETRONAS Lubricants International |
| Q8 Italia S.p.A. |
| Liqui Moly GmbH |
| Others |
Supply & Pricing Matrix
Rhine-Alpine corridor freight differentials compress blender margins while amplifying price spreads between Rotterdam-sourced Group III base oils and Ravenna-refined captive supply. This logistics cost wedge forces northern Italian formulators toward premium synthetic positioning, whereas southern distributors absorb elevated landed costs that widen regional pricing dispersion.
Pricing Analysis
The technology-generation pricing gap separating legacy 5W-30 formulations from emerging 0W-8/0W-12 grades and next-generation hybrid thermal management fluids defines current market structure. Three-tier pricing structure across premium synthetic, mid-tier synthetic blend, and mineral economy levels tracks ACEA certification tiers and OEM approval density. Cost compression in standard-grade engine oils is intensifying because extended drain intervals structurally reduce per-vehicle consumption. Fleet operators in the Milan-Bologna corridor exhibit lowest price sensitivity due to warranty-linked service protocols, while independent workshops in southern Italy remain most responsive to volume discounts.
Supply Chain Analysis
Upstream feedstock security hinges on northwest European Group II/III base oil availability from Rotterdam-ARA and German refining complexes, with Italian domestic production concentrated at Eni's Ravenna facility. Formulation chemistry draws from Belgian and German additive packages, Spanish re-refined base oil streams, and domestic detergent-dispersant blending. Single-source vulnerability concentrates in premium Group III base stock procurement from Rotterdam, where ARA price volatility transmits directly to Italian blender cost structures. Distribution runs through regional distributors holding inventory for independent workshops, with direct sales channels disintermediating traditional wholesale relationships for large fleet accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's automotive lubricants market functions as a service-attach opportunity where fluid management programs and predictive maintenance contracts expand faster than standalone product sales. Recurring-revenue lubricant subscription models for commercial fleets now outpace hardware-only growth by capturing utilization-based consumption patterns.
For Market Incumbents: Harden factory-fill specification control through accelerated co-development timelines with Stellantis technical centers, compressing competitor testing windows. Deepen captive base oil security via Ravenna refinery utilization or Spanish re-refining partnerships to offset Rotterdam price volatility. Channel control through quick-lube network equity stakes defends against direct fleet procurement disintermediation threatening wholesale distributor economics.
For New Entrants and Emerging Players: Sicily and Calabria's deferred maintenance patterns and sparse quick-lube infrastructure present whitespace for service-format expansion with consumer education investments. Emilia-Romagna precision manufacturing clusters offer industrial gearbox fluid entry points outside saturated automotive channels. A mobile lubricant analysis and just-in-time delivery value proposition targets small fleet operators currently underserved by bulk supply agreements.
For Investors and Strategic Acquirers: Carve-out targets emerge from integrated oil majors divesting non-core lubricant blending assets amid energy transition portfolio rebalancing. Five-to-ten-year viability favors specialists with additive chemistry partnerships and OEM approval density over commodity mineral oil processors. The inflection signal to monitor is Euro 7 implementation pace affecting specification cycle compression and R&D throughput requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Re-Refining | Spanish and German re-refining partnerships secure ECHA REACH-compliant base oil supply ahead of bio-content mandates. |
| Direct Fleet Procurement Contracts | Annual volume agreements with Milan-Bologna logistics operators disintermediate wholesale channel margins. |
| OEM Co-Development Programs | Technical service agreements with Turin and Melfi assembly plants lock in factory-fill specifications across model generations. |
| Southern Service Network Expansion | Palermo and Catania quick-lube investments capture deferred maintenance demand with higher per-liter economics. |
| Additive Chemistry Partnerships | Collaboration with Belgian and German specialty chemical suppliers accelerates zinc-free formulation development. |
Research Methodology
Initial hypotheses were tested against primary input from lubricant blender technical directors, fleet procurement managers at commercial logistics operators, aftermarket distributor principals, and OEM platform engineers, then refined through secondary validation. Primary intelligence combined structured interviews with channel stakeholders and field observation of service bay specification practices. Secondary sources encompassed ACEA technical sequences, ECHA substance registration databases, vehicle production statistics from IHS Markit, and customs trade data tracking base oil import flows. Bottom-up volume modeling triangulated against top-down market sizing from refinery capacity and blending plant utilization estimates.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeling spanning product viscosity grade, OEM approval tier, end-user procurement authority, and regional service infrastructure density. CAGRs were derived from elasticity-adjusted consumption forecasts tied to vehicle fleet composition and drain interval engineering trends. Industry-specific inputs incorporated Euro 7 thermal management requirements, REACH substance restriction timelines, and PNRR fleet renewal funding disbursement patterns.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by multinational majors or rapid specification cycle compression by Stellantis would shift outcomes substantially. Cross-checking against ARA base oil price benchmarks and ACEA sequence adoption rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Norway Automotive Lubricants Market
Lubricants
China Commercial Vehicles Lubricants Market
Lubricants
Middle East Lubricants Market
Lubricants
Lubrication Equipment Market
Lubricants
Global Hydraulic Fluid Market
Lubricants
North America Automotive Lubricants Market
Lubricants
US Industrial Lubricants Market
Lubricants
Brazil Commercial Vehicles Lubricants Market
Lubricants
Turkey Commercial Vehicles Lubricants Market
Lubricants
Colombia Lubricants Market
Lubricants
North America and Europe Forestry Lubricants Market
Lubricants
Turkey Automotive Lubricants Market
Lubricants
Morocco Lubricants Market
Lubricants
Mexico Automotive Lubricants Market
Lubricants
Lubricated Tracks Market
Lubricants
United States Automotive Lubricants Market