
 Japan Automotive Lubricants Market | 2026-2036
Japan Automotive Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Automotive Lubricants Market Foresight
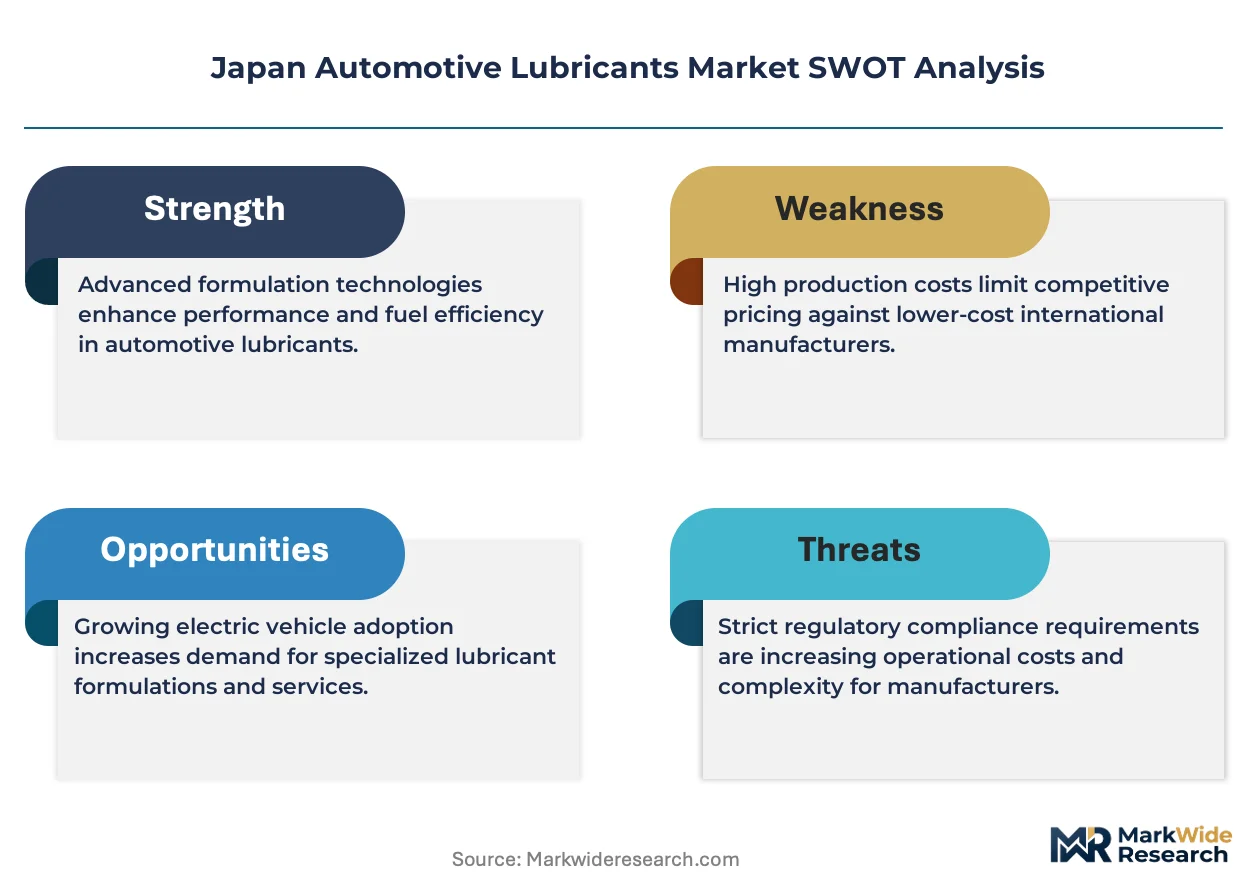
The Japan automotive lubricants market is decoupling along viscosity-grade lines, with premium synthetic formulations commanding sustained price premiums while mineral-based products face margin compression in commoditized fleet contracts. ENEOS Corporation leverages its integrated refinery-to-retail network to dominate domestic base oil supply. Idemitsu Kosan anchors its position through deep relationships with Japanese OEMs and captive distribution through company-owned service stations. Shell plc competes by importing high-performance additive packages that meet Japan's stringent fuel-economy benchmarks.
Automotive lubricants are formulated mixtures of base oils and performance additives engineered to reduce friction, dissipate heat, and prevent wear in powertrain components, with typical engine oils classified by SAE viscosity grades ranging from 0W-16 to 10W-40 depending on operating temperature requirements. Engine oil retains the largest value share due to high drain-frequency requirements in hybrid powertrains, though transmission fluid is expanding fastest as continuously variable transmissions proliferate across passenger car lineups. The aftermarket channel captures the dominant margin pool because repair shops and fleet operators prioritize immediate availability over wholesale volume discounts.
METI enforces fuel efficiency standards that directly shape lubricant viscosity specifications, while JIS standards govern minimum performance benchmarks for products sold in Japan. The country's national environmental regulator pushes waste oil recycling mandates that increase collection infrastructure costs for distributors. Stakeholders must monitor how electrification alters lubricant demand per vehicle and whether hybrid-specific formulations warrant dedicated R&D investment ahead of powertrain mix shifts.
Market Dynamics
Japan's automotive lubricants sector is compressing around fuel-economy mandates that force rapid viscosity-grade migration, with METI's efficiency standards pushing formulators toward 0W-16 and 0W-8 formulations that demand specialized base oil streams and additive chemistry investments.
Growth Catalysts
- Hybrid powertrain proliferation:Dual-motor architectures require dedicated thermal management fluids with higher oxidation stability, expanding addressable fluid volume per vehicle as electrified platforms capture mainstream passenger car segments.
- METI fuel efficiency standards:Regulatory pressure on OEM corporate average fuel economy accelerates lubricant specification tightening, mandating lower viscosity grades that command premium pricing and technical differentiation.
- Fleet operator consolidation:Large-scale logistics and ride-hail operators in the Kanto region are centralizing procurement under long-term supply agreements, stabilizing demand visibility for formulators with national distribution networks.
Market Restraints
- Base oil supply concentration:Domestic production clusters around integrated refiners in the Chiba and Yokkaichi industrial zones, creating geographic single-source vulnerability for independent blenders lacking captive supply.
- Group III+ base oil import dependency:High-performance synthetic formulations require API Group III+ and PAO feedstocks predominantly sourced from South Korean and Southeast Asian refiners, exposing margins to freight and currency volatility.
- Waste oil collection infrastructure costs:Japan's national environmental regulator mandates extended producer responsibility for used lubricant recovery, imposing fixed-cost burdens on distributors serving fragmented rural service networks.
Strategic Opportunities
- Chubu region fleet density:Nagoya's automotive manufacturing corridor hosts concentrated OEM service operations and tier-one supplier fleets currently underserved by premium synthetic distribution.
- EV thermal fluid specialization:Battery electric platforms require dielectric coolants and e-axle lubricants with novel electrical conductivity and material compatibility specifications, creating formulation white space distinct from legacy engine oils.
- JIS certification premium tier:Upcoming revisions to JIS K 2234 and K 2240 standards will introduce performance tiers that reward additive investments with official designation, enabling price stratification against uncertified imports.
Industry Challenges
- Formulation chemist scarcity:Japan's chemical engineering pipeline produces insufficient talent with tribology and additive-package optimization expertise, forcing incumbents to recruit from overseas or retrain process engineers.
- Hybrid-specific testing protocol gaps:No standardized bench test exists for stop-start wear and electrical compatibility in electrified powertrains, delaying product validation cycles and OEM approval timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Automotive Lubricants Market |
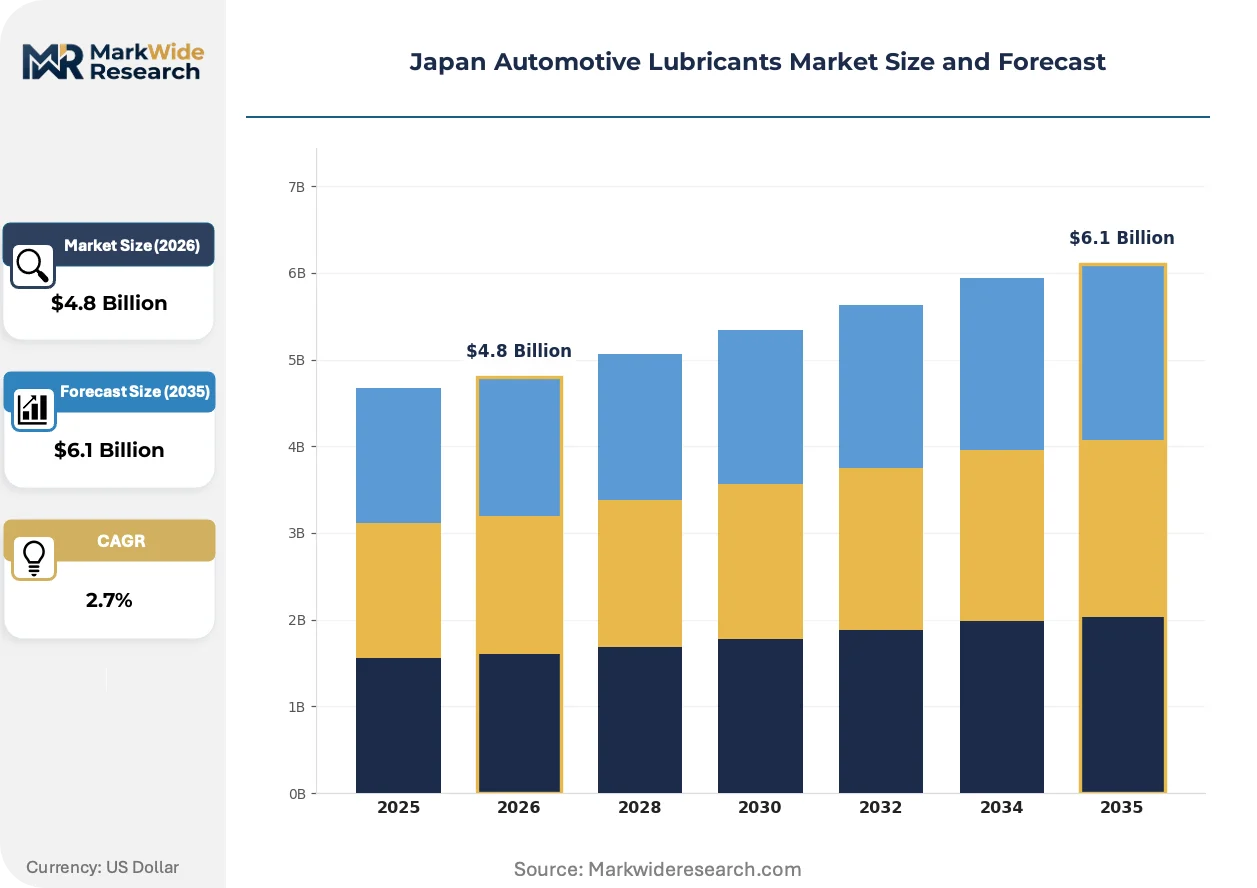
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.1 Billion |
| CAGR (2026 – 2036) | 2.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Gear Oil, Greases Vehicle Type: Passenger Cars, Commercial Vehicles, Motorcycles, Heavy Trucks Distribution Channel: Retail, Wholesale, Online, Service Stations End User: OEMs, Aftermarket, Fleet Operators, Repair Shops |
| Companies Covered | ENEOS Corporation, Idemitsu Kosan Co. Ltd, Exxon Mobil Corporation, Shell plc, BP p.l.c., Cosmo Energy Holdings Co. Ltd, BP Castrol KK, Fuchs SE, Repsol SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Automotive Lubricants Market Shifts & Advancements
Formulation automation and specification digitization are compressing product development cycles while regulatory pressure accelerates chemistry investments. Three forces are restructuring competitive advantage in Japan's lubricant value chain.
Artificial intelligence-driven formulation design is automating additive-package optimization that previously required months of bench testing. ENEOS and Idemitsu have deployed machine-learning models trained on decades of JIS compliance data to predict viscosity-temperature performance and oxidation stability. This compression of R&D iteration is automating the traditional competitive moat of experienced tribologists, forcing mid-tier blenders to license predictive platforms or accept slower time-to-market.
METI's 2030 fuel efficiency roadmap is tightening corporate average targets that cascade into lubricant specifications. The regulation mandates progressive viscosity reduction across OEM lineups, compelling formulators to invest in Group III+ and PAO base oil capacity. Passenger car engine oil faces the steepest reformulation pressure, with 0W-8 grades moving from niche hybrid applications to mainstream compact vehicle fills by mid-decade.
Fleet procurement teams are consolidating supplier relationships around integrated service providers rather than transactional product purchases. Large logistics operators in the Kanto corridor now negotiate total fluid management contracts covering monitoring, analysis, and replenishment. This bundling displaces traditional distributor relationships and concentrates margin capture with formulators possessing direct fleet service infrastructure and used-oil logistics capabilities.
Japan Automotive Lubricants Market Segmentation
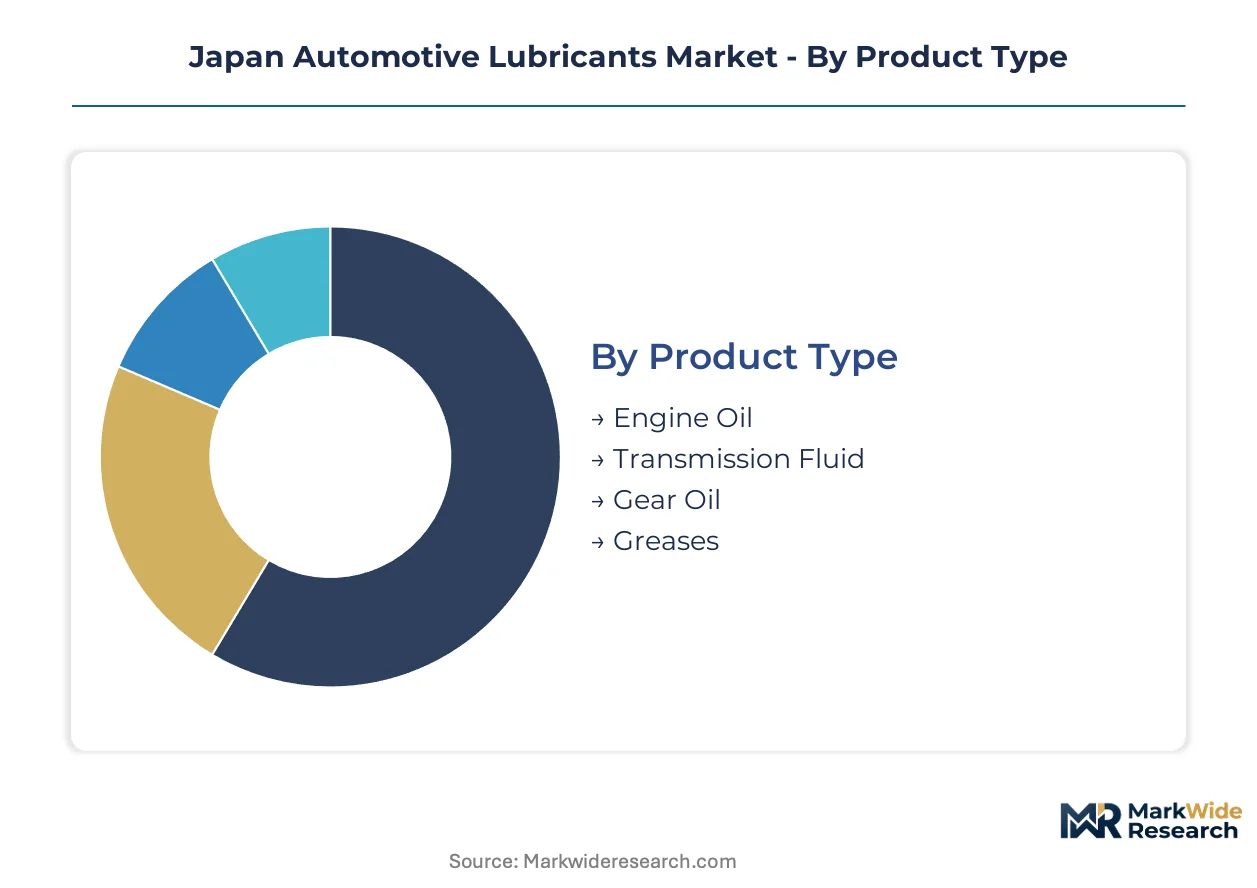
Segmentation in Japan's automotive lubricants market reveals how viscosity-grade specialization and channel fragmentation create distinct margin pools. Understanding these divides exposes where formulation investments translate to pricing power versus commodity exposure.
Product Type:
Upgrade cycles vary dramatically across lubricant categories, with hybrid powertrains accelerating drain intervals for some fluids while extending them for others.
- Engine Oil:Formulations span SAE 0W-8 through 10W-40 grades with base oil blends determining thermal stability and fuel-economy contribution. Demand concentrates in Kanto region service networks serving Tokyo's dense hybrid fleet, where METI efficiency standards mandate ultra-low viscosity fills.
- Transmission Fluid:Continuously variable transmission formulations require specialized friction modifiers and oxidation resistance distinct from stepped-gear applications. Adoption climbs fastest in Nagoya's automotive manufacturing corridor as CVT penetration expands across compact passenger lineups.
- Gear Oil:Hypoid gear lubricants for differentials and transfer cases balance extreme pressure protection with fuel economy.
- Greases:Lithium complex and polyurea thickeners serve chassis and bearing applications with extended service intervals.
Engine Oil sits at the top of the volume ranking, with Transmission Fluid climbing the fastest.
Vehicle Type:
Cost tier segmentation separates premium synthetic formulations for passenger vehicles from mineral-based bulk supply serving commercial fleets.
- Passenger Cars:Hybrid architectures dominate Japan's passenger fleet, requiring dedicated 0W-16 and 0W-8 engine oils with enhanced electrical compatibility and stop-start wear protection. Volume concentrates in metropolitan Kanto and Kansai regions where vehicle density supports premium synthetic adoption.
- Commercial Vehicles:Fleet operators in logistics and distribution prioritize total cost of ownership over per-liter pricing, negotiating long-term supply agreements with integrated service providers.
- Motorcycles:Wet clutch compatibility and shear stability specifications differentiate motorcycle oils from passenger car formulations.
- Heavy Trucks:Long-haul applications demand extended drain interval oils with soot handling and TBN retention capabilities.
Passenger Cars command the largest value share, while Commercial Vehicles are gaining share fastest through fleet consolidation.
Distribution Channel:
Application-focused channel strategies separate immediate-availability service networks from price-sensitive bulk procurement.
- Retail:Automotive parts stores and mass merchandisers serve DIY enthusiasts and small independent garages with packaged lubricants. Margin pressure intensifies as online price transparency erodes traditional markup structures in urban centers.
- Wholesale:Distributors supply fragmented rural service networks and secondary cities, carrying inventory costs for lower-turn SKUs.
- Online:Direct-to-consumer platforms and B2B procurement portals expand share among tech-enabled fleet operators and price-sensitive independents.
- Service Stations:Company-owned and affiliated networks captive-distribute house-brand formulations with guaranteed specification compliance.
Service Stations retain the dominant volume position, with Online channels expanding most quickly.
End User:
Customer type segmentation determines whether procurement prioritizes specification compliance, total fluid management, or transactional price minimization.
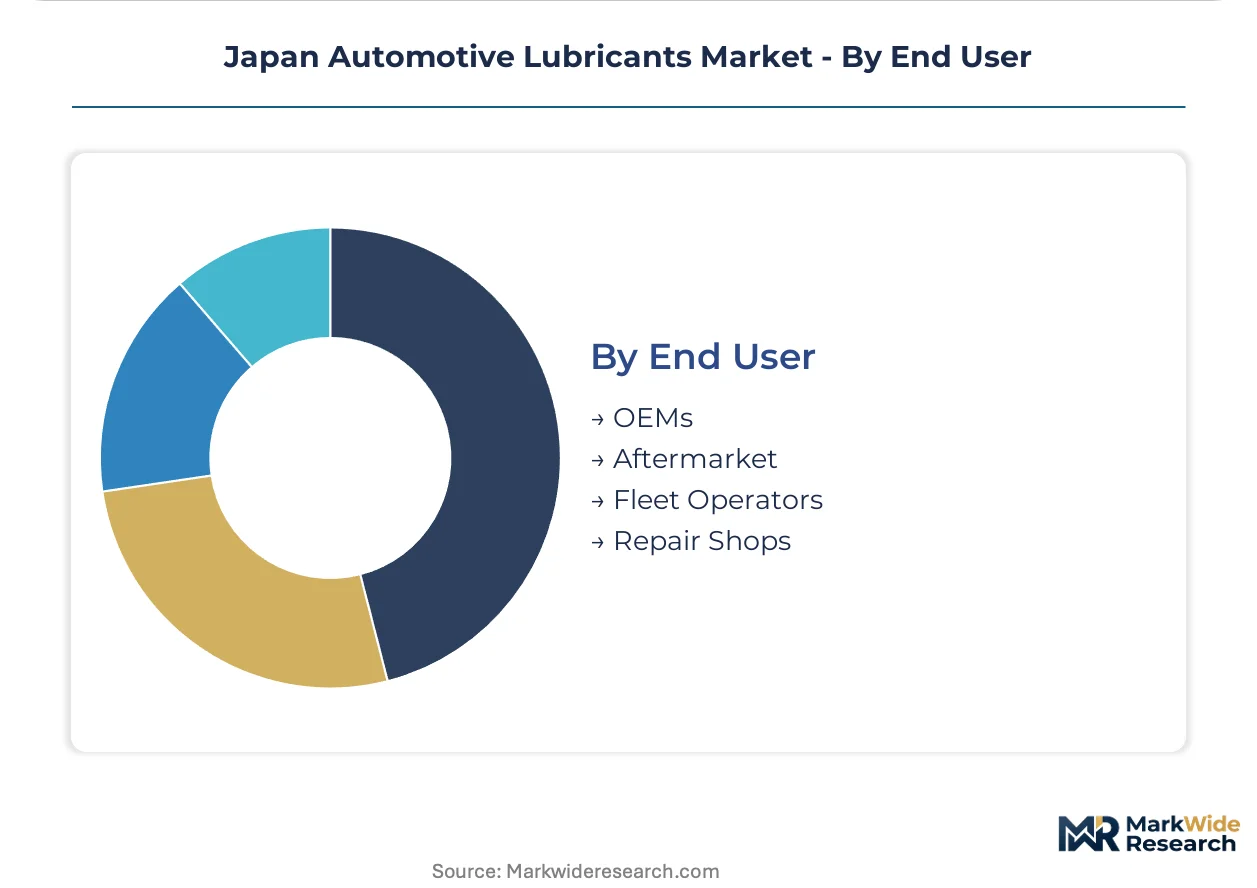
- OEMs:Factory fill specifications require JIS-certified formulations with documented approval timelines and quality audit trails. Toyota, Honda, and Nissan maintain captive technical requirements that filter available suppliers.
- Aftermarket:Independent repair shops and parts retailers prioritize immediate availability and brand recognition over technical differentiation, creating price competition among distributors.
- Fleet Operators:Large logistics and ride-hail platforms in the Kanto corridor centralize procurement under total fluid management contracts covering monitoring, analysis, and replenishment.
- Repair Shops:Franchise and independent service centers balance customer-facing brand preferences with wholesale cost minimization.
Fleet Operators anchor the steepest expansion trajectory, while OEMs retain specification control over factory fills.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's automotive lubricants market diverges from South Korea's export-driven model through its captive domestic supply chains and METI-mandated efficiency standards that reshape formulation requirements across prefectural manufacturing corridors.
Kanto/Tokyo
Metropolitan Tokyo anchors Japan's highest lubricant consumption density through its hybrid-dominant passenger fleet and concentrated service infrastructure. METI's fuel efficiency standards cascade through OEM technical centers in Yokohama and Toyota City, mandating 0W-16 and 0W-8 viscosity migrations. Fleet operators in the Keihin industrial zone negotiate total fluid management contracts with integrated distributors.
Kansai/Osaka
Osaka's automotive component suppliers drive specialized transmission fluid demand for CVT manufacturing lines serving domestic and export markets. The region's port infrastructure facilitates Group III+ base oil imports from South Korean refiners. SME repair networks in Kyoto and Kobe prioritize JIS-certified formulations with documented quality audit trails.
Chubu/Nagoya
Toyota's headquarters region concentrates OEM factory fill specifications and captive technical requirements that filter supplier eligibility. Nagoya's tier-one supplier corridor hosts concentrated fleet operations currently expanding synthetic lubricant procurement. The prefecture's industrial zone connects to Yokkaichi refinery complexes through dedicated supply pipelines.
Kyushu
Fukuoka's automotive assembly plants generate steady factory fill demand while rural service networks impose higher waste oil collection infrastructure costs. The island's distance from Chiba and Yokkaichi refining centers creates distribution challenges for independent blenders lacking captive supply. Local regulators enforce extended producer responsibility mandates with particular stringency in coastal prefectures.
Hokkaido
Sapporo's cold-climate operating conditions sustain demand for higher viscosity winter grades distinct from national efficiency trends. The region's fragmented rural service infrastructure concentrates procurement through wholesale distributors carrying inventory costs for lower-turn SKUs. Seasonal tourism fleets generate episodic demand spikes requiring flexible supply arrangements.
Japan Automotive Lubricants Market Competitive Landscape
Top-tier vendors anchor integrated refinery-to-retail networks, while mid-tier blenders compete through specialized additive packages and regional distribution partnerships. The market structure concentrates around domestic refiners with captive base oil supply, international majors importing high-performance formulations, and independent distributors serving fragmented rural networks. Strategic archetypes include integrated energy conglomerates, global lubricant specialists, and regional blending operations. Competitive moves center on backward integration into additive chemistry and geographic expansion through fleet service infrastructure.
Within the integrated domestic tier, ENEOS Corporation exemplifies refinery-captive supply chain control, while Idemitsu Kosan occupies a position anchoring OEM technical relationships. Among international majors, Shell plc represents the imported high-performance formulation archetype competing through additive package differentiation. These three companies illustrate how competitive positioning in Japan's lubricant sector depends on base oil access, OEM certification depth, and fleet service infrastructure rather than price minimization alone.
| Leading Market Players |
|---|
| ENEOS Corporation |
| Idemitsu Kosan Co. Ltd |
| Exxon Mobil Corporation |
| Shell plc |
| BP p.l.c. |
| Cosmo Energy Holdings Co. Ltd |
| BP Castrol KK |
| Fuchs SE |
| Repsol SA |
| Others |
Supply & Pricing Matrix
API Group II base oil spot prices in Singapore set the floor for Japan's lubricant pricing tiers, cascading through Chiba and Yokkaichi refinery complexes into three distinct product bands serving OEM factory fills, fleet service contracts, and rural wholesale channels. METI's viscosity-grade mandates amplify cost differentials as formulators absorb premium feedstock expenses for 0W-16 and 0W-8 synthetic formulations.
Pricing Analysis
Capacity additions in South Korea's Ulsan refining corridor are reshaping price floors for high-performance synthetic grades, compressing margins on Group III+ imports while domestic integrated producers maintain cost advantages through captive base oil supply. Three-tier pricing structure across premium synthetic, mid-grade synthetic blend, and mineral-based economy levels separates OEM-certified formulations from fleet bulk contracts and rural distributor SKUs. Price differentiation hinges on JIS certification tier and volume commitment scale, with independent repair shops in Kansai exhibiting highest sensitivity to per-liter differentials while Nagoya OEM service operations prioritize specification compliance over cost.
Supply Chain Analysis
Regional distribution centers in Chiba, Yokkaichi, and Osaka form a hub-and-spoke network feeding company-owned service stations and independent distributors across Japan's four main islands. Base oil supply concentrates in Japan, South Korea, and Singapore, with Group III+ and PAO feedstocks drawing from South Korean and Southeast Asian refiners. Additive packages rest on imports from US and European specialty chemical producers. Single-source vulnerability in base oil supply exposes independent blenders to freight and currency volatility. Distribution runs through integrated refiner networks for premium tiers and fragmented wholesale channels for rural economy segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's automotive lubricants market offers margin-expansion pathways through synthetic-grade premiumization and fleet service bundling, as METI efficiency mandates force viscosity downgrades that concentrate value in formulation expertise rather than commodity base oil supply.
For Market Incumbents: Deploy captive refinery capacity to defend against import-driven price erosion in high-viscosity segments. ENEOS and Idemitsu should deepen additive-package partnerships with Japanese OEMs to lock in factory fill specifications ahead of JIS K 2234 revisions, while expanding used-oil logistics infrastructure to capture fleet operator consolidation in the Kanto corridor.
For New Entrants and Emerging Players: METI's 2030 fuel efficiency roadmap in Japan opens a window for specialized EV thermal fluid formulations distinct from legacy engine oil chemistry. White-space targets include Nagoya's tier-one supplier fleet operations currently underserved by premium synthetic distribution, and dielectric coolant development for battery electric platforms. Go-to-market should emphasize JIS certification pre-investment to qualify for OEM technical approval timelines.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier blenders possessing regional distribution infrastructure but lacking captive base oil supply, as acquisition by integrated refiners accelerates through 2025-2035. Target archetypes include Chubu-region distributors with fleet service contracts and additive blending capabilities. Watch hybrid powertrain production volumes at Toyota and Honda as the inflection signal for thermal fluid demand per vehicle.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Chemistry | Captures margin pool currently exported to US and European specialty chemical suppliers serving JIS-certified formulations. |
| EV Thermal Fluid R&D Investment | Positions formulators for dielectric coolant specifications required by Toyota and Nissan battery electric platforms. |
| Fleet Service Infrastructure Expansion | Consolidates procurement relationships with Kanto logistics operators negotiating total fluid management contracts. |
| JIS Certification Pre-Investment | Secures official designation ahead of K 2234 and K 2240 standard revisions enabling price stratification. |
| Used-Oil Logistics Network Buildout | Complies with national environmental regulator mandates while creating competitive moat against import-dependent competitors. |
Research Methodology
Coverage spans Japan's Kanto, Kansai, Chubu, Kyushu, and Hokkaido regions, with primary inputs from each prefectural manufacturing corridor. The research combines structured interviews with lubricant formulators, OEM procurement specialists, fleet operations managers, and aftermarket distributors with secondary validation from METI regulatory filings, JIS standard documentation, Japan Petroleum Energy Center industry statistics, and customs trade data for base oil imports. Bottom-up triangulation across product-type volume estimates and top-down reconciliation against refinery production data ensures consistency.
Rate-of-change decomposition separates volume effects from value-mix shifts across the projection horizon, modeling segmentation dimensions including viscosity grade tier, vehicle propulsion architecture, distribution channel type, and end-user procurement pattern. CAGRs derive from trend-line extrapolation of historical formulation adoption rates, adjusted for METI regulatory phase-in schedules and OEM platform rollout timelines. Forecast inputs incorporate hybrid powertrain production forecasts and fleet operator consolidation trajectories in the Keihin industrial zone.
Revisions become necessary when electrification penetration exceeds modeled pathways, base oil supply disruptions alter import dependency ratios, or JIS standard implementation timelines shift. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and OEM specification adoption rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Marine Grease Market
Lubricants
India Lubricants Market
Lubricants
Anti-Static Oil Market
Lubricants
Fire Resistant Fluids Market
Lubricants
Japan Lubricants Market
Lubricants
Non-Flammable Hydraulic Fluids Market
Lubricants
Forestry Lubricants Market
Lubricants
Global Automotive Engine Oils Market
Lubricants
Norway Automotive Lubricants Market
Lubricants
India Industrial Lubricants Market
Lubricants
China Commercial Vehicles Lubricants Market
Lubricants
US Industrial Lubricants Market
Lubricants
Qatar Lubricants Market
Lubricants
Spain Automotive Lubricants Market
Lubricants
Chile Lubricants Market
Lubricants
Russia Automotive Engine Oils Market