
 US Industrial Lubricants Market | 2026-2036
US Industrial Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
US Industrial Lubricants Market Insights
Synthetic ester formulations is broadening the addressable premium tier as mineral oil-based alternatives face performance limitations in high-temperature industrial environments. ExxonMobil Corporation leverages its integrated base oil production network across the US Gulf Coast to secure feedstock cost advantages. Chevron Corporation competes through specialized hydraulic fluid portfolios tailored to shale extraction equipment. Fuchs Lubricants anchors its position in metalworking fluids through technical service partnerships with Midwest automotive stamping plants.
US industrial lubricants encompass formulated fluids and greases engineered with viscosity grades, additive packages, and base oil chemistries designed to reduce friction, dissipate heat, and prevent wear in machinery operating under extreme loads and temperatures. Manufacturing processes involve blending Group I through Group IV base stocks with antioxidants, anti-wear agents, and viscosity index improvers to meet OEM equipment specifications and maintenance intervals. Hydraulic fluids dominate volume consumption across energy and heavy equipment applications, while synthetic formulations capture expanding margin pools as OEMs extend drain intervals and equipment warranties. Metalworking fluids represent a mature but structurally critical segment where biodegradable formulations gain traction amid wastewater discharge regulations.
The EPA governs lubricant disposal and spill containment under the Clean Water Act and Resource Conservation and Recovery Act, while OSHA mandates material safety data sheet compliance and workplace exposure limits for metalworking fluid mist. State-level regulations in California through CARB and Texas through TCEQ impose additional formulation constraints on volatile organic compound content. Stakeholders must monitor evolving federal bio-preferred procurement standards and state renewable content mandates that will reshape supplier qualification requirements and reformulation timelines.
Market Dynamics
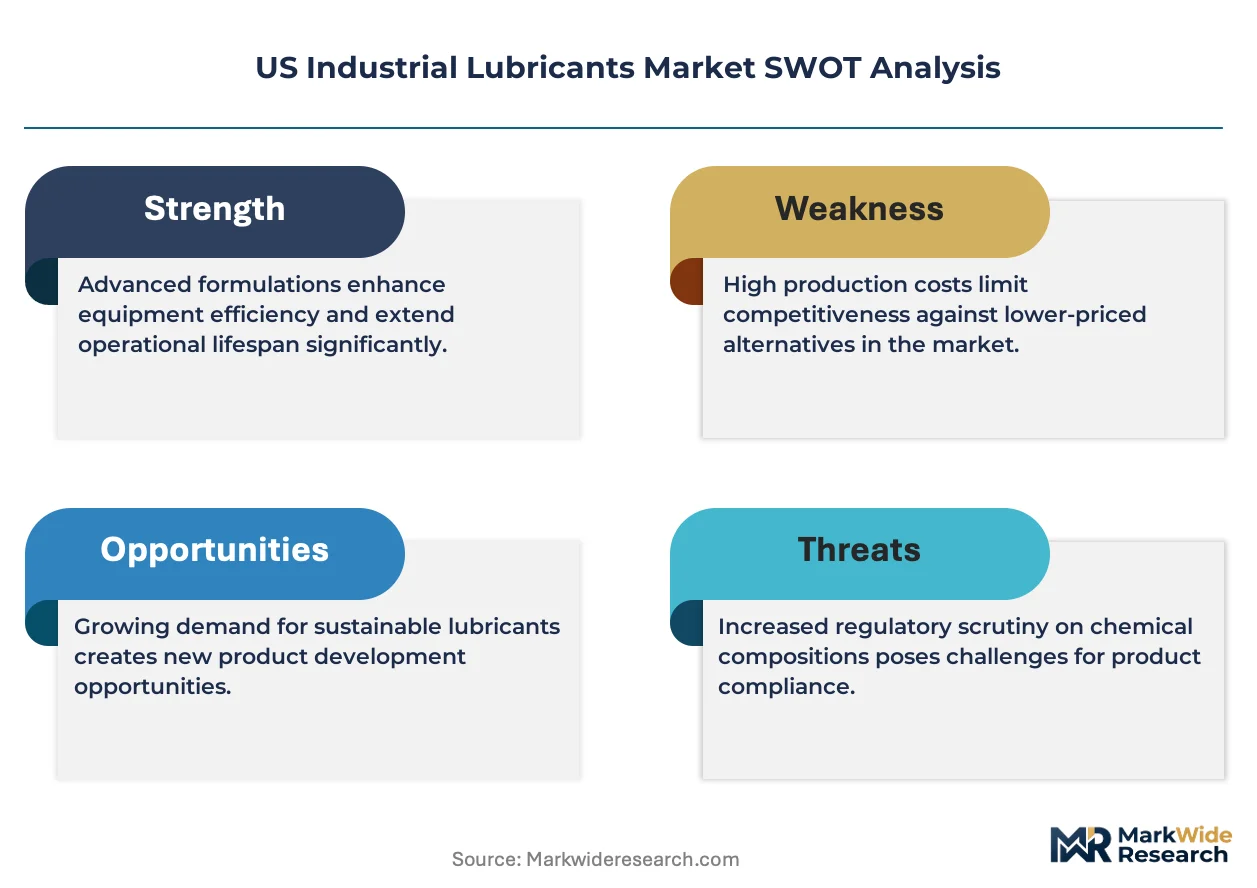
EPA emissions standards and OSHA workplace exposure mandates are compressing formulation timelines and forcing blenders to accelerate additive package upgrades across hydraulic and metalworking fluid portfolios.
Growth Catalysts
- Automotive Manufacturing Reshoring:Domestic stamping and powertrain facilities in Michigan and Ohio are extending maintenance intervals, pulling synthetic hydraulic fluids into high-volume contracts.
- REACH-Style State Mandates:California CARB volatile organic compound limits and Texas TCEQ discharge rules are disqualifying legacy mineral oil formulations from public procurement bids.
- Synthetic Ester Chemistry:Group V base stocks now withstand temperatures above 150°C in Gulf Coast petrochemical compressors where mineral oils thermally degrade.
Market Restraints
- Base Oil Supply Concentration:Group II/III capacity clusters along the US Gulf Coast expose blenders to hurricane-related production disruptions and force majeure allocations.
- Additive Cost Volatility:ZDDP anti-wear compounds and molybdenum friction modifiers track sulfur and metal commodity indices, compressing blender margins unpredictably.
- Biodegradable Performance Gap:Vegetable-derived esters hydrolyze in humid Southeast Asian-equivalent conditions inside US food processing plants, limiting substitution depth.
Strategic Opportunities
- Wind Turbine Gearbox Fluids:Texas and Great Plains wind farms require 7-10 year fill-for-life synthetics that command 3-4x pricing over standard industrial grades.
- Federal Bio-Preferred Procurement:USDA certification standards create a qualified supplier list for military and federal maintenance contracts with reformulation deadlines.
- Predictive Maintenance Integration:Sensor-enabled condition monitoring in Midwest heavy equipment fleets enables fluid-as-a-service contracts tied to uptime guarantees.
Industry Challenges
- Tribology Talent Scarcity:Formulation chemists with Group IV/V base stock expertise command premium compensation and exit to specialty chemical sectors.
- OEM Certification Timelines:Caterpillar and Komatsu specification approvals require 18-24 month test cycles that lock out reformulated products mid-development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Industrial Lubricants Market |
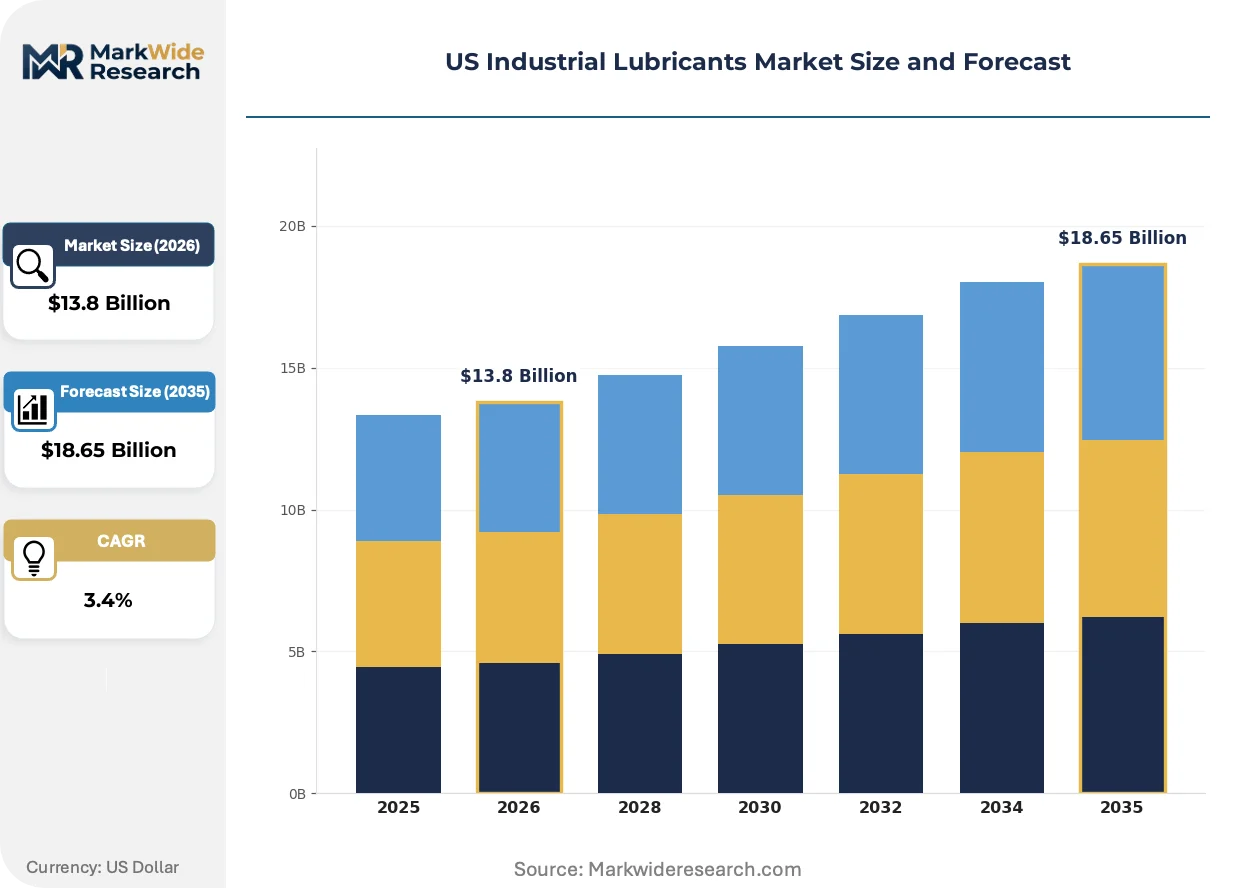
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $18.65 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Greases, Oils, Hydraulic Fluids, Metalworking Fluids Application: Automotive Manufacturing, Heavy Equipment, Aerospace, Energy End User: OEMs, Maintenance Service Providers, Industrial Plants, Transportation Formulation: Synthetic, Biodegradable, Mineral Oil-based, Semi-synthetic |
| Companies Covered | ExxonMobil Corporation, Shell plc, Chevron Corporation, Phillips 66, The Lubrizol Corporation, Fuchs Lubricants, Valvoline International, Clariant, Castrol, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Industrial Lubricants Market Trends and Innovations
Formulation chemistry and regulatory compliance timelines are compressing product development cycles while digital integration restructures how lubricants are specified, purchased, and consumed across industrial accounts.
Polyalkylene glycol (PAG) synthetic formulations is overtaking mineral oil-based compressor fluids in petrochemical and natural gas processing facilities. Operators in the Gulf Coast corridor now specify PAG for high-pressure reciprocating compressors handling sour gas. The technology is overtaking legacy naphthenic grades by eliminating varnish deposition and extending drain intervals beyond 8,000 operating hours, compressing the addressable market for conventional hydraulic fluids in process industries.
OSHA's pending metalworking fluid mist exposure limits are forcing stamping plants and machining centers to retrofit ventilation systems or switch to semi-synthetic and synthetic alternatives with lower mist generation profiles. The proposed permissible exposure level reduction to 0.5 mg/m³ threatens legacy soluble oil formulations that rely on high mineral oil content. Midwest automotive tier suppliers are responding with centralized coolant management systems and mist collection retrofits that favor longer-life synthetics despite 40-60% fluid cost premiums.
Integrated fluid management contracts are displacing spot purchasing across multi-site manufacturing networks. Fleet operators and heavy equipment dealers now bundle lubricant supply with used oil analysis, filtration services, and waste fluid removal under single-source agreements. This consolidation concentrates specification authority at regional procurement hubs and marginalizes independent distributors lacking technical service capabilities, with the shift most visible in Pennsylvania and Ohio manufacturing belts where dealer networks have invested in on-site fluid analysis laboratories.
US Industrial Lubricants Market Segmentation
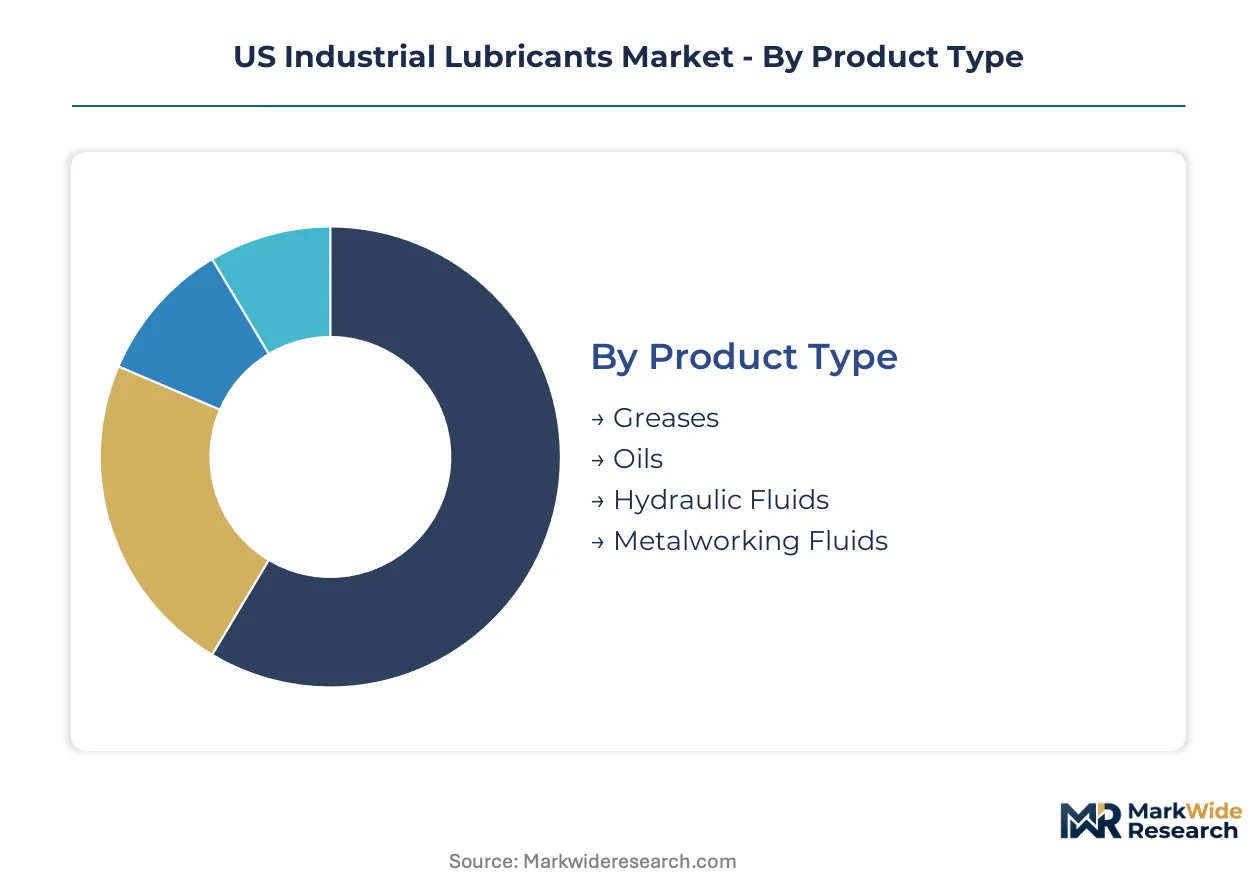
Equipment upgrade cycles and extended drain interval specifications are fragmenting demand across formulation tiers, with synthetic grades commanding premium positioning in high-temperature applications while mineral oil formulations defend volume in cost-sensitive maintenance contracts.
Product Type:
Replacement cycles differ sharply across fluid categories, with hydraulic systems driving predictable bulk consumption while metalworking and grease applications follow tool life and bearing maintenance schedules.
- Hydraulic Fluids:Formulated with anti-wear additive packages and viscosity index improvers to transmit power in closed-loop systems operating at pressures exceeding 3,000 psi. Demand concentrates in Gulf Coast petrochemical compressors and Midwest heavy equipment fleets where thermal stability specifications now default to Group II+ base stocks. EPA spill containment rules and OSHA fire-resistant fluid mandates in steel mills accelerate reformulation timelines.
- Metalworking Fluids:Emulsifiable oils, synthetics, and semi-synthetics designed for cutting, grinding, and forming operations with mist generation profiles under regulatory scrutiny. Automotive stamping plants in Michigan and Ohio are retrofitting centralized coolant systems to meet proposed OSHA permissible exposure limits, favoring longer-life synthetics despite higher per-gallon costs.
- Greases:Thickened lubricants combining base oils with metallic soap or complex thickener systems for sealed bearing and chassis applications. Food processing plants in the Upper Midwest specify H1-registered formulations for incidental contact zones.
- Oils:General-purpose lubricants for gearboxes, compressors, and circulating systems outside dedicated hydraulic circuits. Texas wind farm operators specify synthetic turbine oils with 7-10 year fill-for-life warranties.
Hydraulic fluids sit at the top of the volume ranking, with metalworking fluids climbing the fastest amid OSHA mist exposure rulemaking.
Application:
Cost tier stratification separates specification authority, with aerospace and energy procurement teams optimizing for equipment life while automotive manufacturing pursues total fluid management cost reduction.
- Automotive Manufacturing:Powertrain machining, stamping press hydraulics, and assembly line conveyor systems consume formulated fluids in high-volume, predictable patterns. Tier suppliers in Ohio and Indiana extend drain intervals through condition monitoring programs that favor synthetic hydraulic and metalworking chemistries.
- Energy:Upstream drilling equipment, midstream pipeline pumps, and downstream refinery process units demand fire-resistant and high-temperature formulations. Gulf Coast petrochemical facilities specify polyalkylene glycol compressor fluids to eliminate varnish deposition in sour gas service.
- Heavy Equipment:Construction, mining, and agricultural machinery operating in abrasive environments with extended service intervals. Dealer networks in Pennsylvania bundle lubricant supply with used oil analysis and filtration services under integrated fluid management contracts.
- Aerospace:Precision machining of turbine components and airframe assemblies with stringent cleanliness specifications. California and Washington state manufacturing facilities prioritize low-mist synthetic metalworking fluids for titanium and nickel alloy processing.
Automotive manufacturing anchors volume consumption, with energy applications gaining share fastest on synthetic formulation adoption.
End User:
Procurement authority is consolidating at regional hubs, with multi-site operators displacing spot purchasing through technical service partnerships while independent distributors lose specification influence.
- Industrial Plants:Self-directed maintenance organizations with in-house tribology expertise and centralized lubricant storage. Texas and Louisiana chemical processors maintain on-site laboratories for used oil analysis and additive package monitoring.
- Maintenance Service Providers:Independent and OEM-affiliated service contractors performing outsourced equipment upkeep. Fleet operators in the Great Plains specify fluid-as-a-service contracts tied to uptime guarantees and predictive maintenance integration.
- OEMs:Original equipment manufacturers specifying factory-fill and service-fill lubricants for warranty compliance. Caterpillar and Komatsu certification timelines lock in approved supplier lists through 18-24 month test cycles.
- Transportation:Rail, marine, and fleet operators with centralized procurement and waste fluid handling requirements. California CARB volatile organic compound limits disqualify legacy formulations from public transit authority bids.
Industrial plants dominate volume procurement, with maintenance service providers expanding most quickly through integrated fluid management contracts.
Formulation:
Margin structure separates base stock chemistry tiers, with Group IV and V synthetics capturing value pools from extended drain intervals while mineral oil formulations compete on price in undifferentiated applications.
- Synthetic:Polyalphaolefin, polyalkylene glycol, and ester base stocks engineered for thermal stability above 150°C and oxidative resistance extending drain intervals beyond 8,000 hours. Gulf Coast petrochemical compressors and Texas wind turbine gearboxes specify synthetic esters for fill-for-life performance.
- Semi-synthetic:Blends combining Group II/III mineral stocks with synthetic components to balance cost and performance. Midwest automotive stamping plants adopt semi-synthetic metalworking fluids to reduce mist generation while controlling per-gallon expenditure.
- Mineral Oil-based:Group I through Group III refined petroleum stocks serving cost-sensitive applications with standard temperature and load profiles. Legacy hydraulic systems in mature manufacturing belts continue specification of mineral oil formulations where equipment replacement timelines delay upgrade.
- Biodegradable:Vegetable-derived esters and synthetic esters meeting federal bio-preferred procurement standards and state renewable content mandates. USDA certification creates qualified supplier lists for military and federal maintenance contracts, though hydrolysis stability limits penetration in humid food processing environments.
Mineral oil-based formulations retain volume leadership, with synthetic grades ascending fastest on OEM warranty extension and thermal performance specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gulf Coast petrochemical corridor anchors national demand concentration, with Midwest manufacturing belts and Texas wind installations forming secondary volume poles. EPA regional offices in Dallas and Chicago coordinate enforcement timelines that compress formulation upgrade schedules across these clusters.
Gulf Coast
Texas and Louisiana host the densest concentration of petrochemical compressors and refinery process units demanding high-temperature synthetic formulations. TCEQ discharge rules and EPA Region 6 spill containment protocols force rapid additive package upgrades. Houston-area blending facilities now default to Group II+ base stocks for hydraulic systems operating above 150°C.
Midwest Manufacturing Belt
Michigan and Ohio automotive stamping plants consume metalworking fluids in high-volume, predictable patterns tied to powertrain production schedules. OSHA Region 5 workplace exposure enforcement accelerates mist collection retrofits and centralized coolant system investments. Detroit and Cleveland tier suppliers extend drain intervals through condition monitoring programs favoring synthetic chemistries.
Texas Wind Corridor
Great Plains wind farms spanning West Texas and the Panhandle specify 7-10 year fill-for-life synthetic turbine oils. USDA bio-preferred procurement standards create qualified supplier lists for federal maintenance contracts serving these installations. Amarillo and Lubbock service hubs bundle fluid supply with predictive maintenance integration under uptime-guarantee contracts.
California Industrial Zones
CARB volatile organic compound limits disqualify legacy mineral oil formulations from public procurement bids across Los Angeles and Bay Area manufacturing facilities. EPA Region 9 coordinates with state regulators on lubricant disposal enforcement under Clean Water Act authority. Precision machining operations in San Diego and San Jose prioritize low-mist synthetic metalworking fluids for titanium and nickel alloy processing.
Pennsylvania Heavy Equipment Hub
Pittsburgh and Philadelphia dealer networks bundle lubricant supply with used oil analysis and filtration services under integrated fluid management contracts. OSHA material safety data sheet compliance mandates drive specification consolidation at regional procurement hubs. Caterpillar and Komatsu certification timelines lock approved supplier lists through extended test cycles across this mature equipment market.
US Industrial Lubricants Market Competitive Landscape
Integrated fluid management contract expansion dominates the current landscape as procurement authority consolidates at regional hubs. The vendor base separates into three tiers: integrated majors with captive base oil production, specialized blenders with technical service partnerships, and regional distributors competing on logistics coverage. Strategic archetypes include upstream-integrated formulators, application-focused specialists, and service-integrated distributors. M&A activity and backward integration into additive package development represent the dominant competitive vectors reshaping supplier positioning.
Among upstream-integrated majors, ExxonMobil Corporation and Chevron Corporation exemplify the Gulf Coast production advantage archetype, leveraging captive base oil networks to secure feedstock cost positions. Fuchs Lubricants occupies a position within the technical service specialist tier, anchoring metalworking fluid partnerships with Midwest automotive stamping operations. Shell plc and Castrol represent the global portfolio diversification archetype, spanning multiple formulation chemistries and end-use segments without geographic concentration dependency.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Shell plc |
| Chevron Corporation |
| Phillips 66 |
| The Lubrizol Corporation |
| Fuchs Lubricants |
| Valvoline International |
| Clariant |
| Castrol |
| Others |
Pricing and Supply Chain Analysis
Base oil feedstock costs originating from Gulf Coast refinery operations cascade through three distinct pricing tiers as blenders balance Group II/III spot market volatility against long-term automotive OEM contract structures. This cost transmission mechanism concentrates margin pressure on independent distributors lacking captive upstream supply while rewarding integrated majors with inventory hedging flexibility.
Pricing Analysis
Input-cost pass-through from ZDDP additive packages and molybdenum friction modifiers drives contract renegotiation cycles every 12-18 months across hydraulic fluid portfolios. Three-tier pricing structure across premium synthetic, mid-grade semi-synthetic, and economy mineral oil levels separates specification authority by application temperature and OEM warranty requirements. Cost compression in the mineral oil tier intensifies because of Group I capacity rationalization and import substitution from Asian blenders. Tier suppliers in the Midwest automotive belt exhibit highest price sensitivity due to consolidated procurement hubs, while Texas petrochemical operators prioritize thermal stability specifications over per-gallon expenditure.
Supply Chain Analysis
Regional distribution centers in Houston, Chicago, and Philadelphia operate hub-and-spoke patterns that position bulk inventory within 4-hour drive time of major consumption clusters. Geographic supply concentration centers on United States Gulf Coast refinery complexes, Canadian oil sands upgrading facilities, and South Korean Group II/III export terminals. Raw material dependencies rest on sulfur-derived additive packages, viscosity index improvers, and metallic soap thickeners. Single-source vulnerability from hurricane-exposed Louisiana base oil production creates force majeure allocation risk during Atlantic storm seasons. Distribution runs through lubricant marketing companies with technical service capabilities rather than pure logistics providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US Industrial Lubricants Market functions as a geographic-arbitrage play where California CARB compliance costs exceed Texas TCEQ requirements by sufficient margin to justify dedicated formulation lines and regional blending assets.
For Market Incumbents: Deploy backward integration into additive package development to secure formulation differentiation against commodity import threats. ExxonMobil and Chevron already leverage captive base oil networks; extending this upstream into ZDDP and PAG chemistry protects margin pools in synthetic grades. Capacity addition in Pennsylvania and Ohio manufacturing belts tightens service radius around Midwest automotive stamping operations. Certification investment in USDA Bio-Preferred standards locks in military and federal maintenance contract eligibility before reformulation deadlines compress. For New Entrants and Emerging Players: Sensor-enabled condition monitoring platforms offer technology-first wedge positioning against established distributors lacking predictive maintenance integration. White-space targets concentrate on Texas wind corridor fluid-as-a-service contracts and biodegradable formulations for food processing H1 registrations. The most penetrable segment sits in maintenance service provider outsourcing agreements where regional procurement hubs seek single-source technical partnerships. Go-to-market execution requires on-site laboratory capabilities and used oil analysis bundling rather than spot price competition. For Investors and Strategic Acquirers: Consolidation pressure builds where additive cost volatility and OEM certification timelines exceed independent blender capitalization capacity. Long-term viability over the 5-10 year window favors suppliers with demonstrated EPA and OSHA compliance track records plus existing Caterpillar or Komatsu approvals. Acquisition target archetype: regional distributors with technical service infrastructure in the Midwest manufacturing belt or Gulf Coast petrochemical corridor. Signal to watch: USDA Bio-Preferred procurement standard finalization triggering supplier list qualification windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Chemistry | Captive ZDDP and PAG production insulates blender margins from sulfur commodity volatility. |
| USDA Bio-Preferred Certification Investment | Federal procurement qualification creates qualified supplier moats before military contract deadlines. |
| Regional Blending Capacity Expansion | Pennsylvania and Ohio assets compress service radius around Midwest automotive tier suppliers. |
| Predictive Maintenance Platform Integration | Sensor-enabled condition monitoring enables fluid-as-a-service contracts tied to uptime guarantees. |
| OEM Specification Fast-Track Partnership | Caterpillar and Komatsu certification timelines lock approved supplier status for 18-24 month cycles. |
Research Methodology
Coverage spans the Gulf Coast petrochemical corridor, Midwest manufacturing belt, Texas wind corridor, California industrial zones, and Pennsylvania heavy equipment hub, with primary inputs from each region triangulated against secondary validation. Primary interviews engaged lubricant blending plant managers, automotive OEM procurement leads, petrochemical facility maintenance directors, and aftermarket service heads at dealer networks. Secondary sources included EPA enforcement databases, OSHA compliance filings, USDA Bio-Preferred procurement records, customs trade data, and SEC 10-K disclosures from integrated oil majors. Bottom-up volume modeling across formulation tiers and top-down value reconciliation from disclosed segment revenues ensured cross-validation.
Granularity-level framing applied product type, application, end user, and formulation chemistry dimensions at the state-cluster level, with base stock tier and additive package composition modeled as sub-segment variables. CAGRs were derived from regression analysis against industrial production indices and equipment stock forecasts across the projection horizon. Industry-specific forecast inputs incorporated EPA regulatory timeline assumptions and OEM drain interval extension specifications.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to hurricane-related supply disruptions, additive raw material commodity swings, and OSHA metalworking fluid mist exposure rule finalization. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and OEM specification stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Friction Reducers Market
Lubricants
Global Independent Lubricant Manufacturers Market
Lubricants
Russia Automotive Engine Oils Market
Lubricants
Poland Automotive Lubricants Market
Lubricants
Solid/Dry Lubricants Market
Lubricants
Nigeria Lubricants Market
Lubricants
Fire Resistant Fluids Market
Lubricants
South Korea Commercial Vehicles Lubricants Market
Lubricants
Aviation Lubricants Market
Lubricants
Global Automotive Engine Oils Market
Lubricants
Europe Metalworking Fluids Market
Lubricants
Perfluoropolyether Fluorinated Fluids Market
Lubricants
Lube Skid Market
Lubricants
Europe Grease Market
Lubricants
Japan Lubricants Market
Lubricants
Kenya Lubricants Market