
 Global Aluminum Anodizing Dyes Market | 2026-2036
Global Aluminum Anodizing Dyes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aluminum Anodizing Dyes Market Foresight
A capital-intensity divergence between integrated pigment manufacturers and regional dye blenders is redrawing competitive boundaries in aluminum anodizing dyes. Heubach Group leverages captive azo and metal-complex pigment production to control raw material pass-through costs across European architectural coating accounts. Clariant AG anchors its position through specialty organic dye formulations engineered for high-lightfastness specifications in automotive trim applications. Kingscote Chemicals Inc. competes on formulation flexibility and shorter lead times for North American job-shop anodizers serving machinery component orders.
Aluminum anodizing dyes are colorant formulations designed to bond with porous anodic oxide layers formed through sulfuric acid electrolysis, typically achieving coating thicknesses of 5–25 microns depending on alloy substrate and end-use durability requirements. These dyes impart decorative and functional coloration to aluminum surfaces while maintaining electrical insulation and corrosion resistance properties critical for architectural, electronics, and industrial applications. Organic dye formulations command premium positioning in consumer electronics and decorative items where color consistency and UV stability determine supplier qualification, while inorganic dye systems retain cost advantages in heavy equipment and building applications where earth-tone palettes dominate specification sheets. Metal complex dyes represent the fastest-expanding technology segment as manufacturers seek chromate-free alternatives that satisfy dual requirements for vivid color gamut and environmental compliance.
EPA effluent guidelines and OSHA hexavalent chromium exposure limits constrain process chemistry choices for U.S.-based anodizing operations, directly shaping dye selection toward trivalent and organic systems. REACH authorization requirements under ECHA oversight continue restricting certain azo dye precursors in European coating supply chains, creating compliance-driven replacement cycles. EU Green Deal carbon border adjustments and China's MEE environmental enforcement together elevate lifecycle assessment transparency as a procurement criterion for multinational aluminum finishers. Stakeholders must monitor regulatory divergence between jurisdictions while evaluating backward integration into dye synthesis versus reliance on qualified specialty chemical distributors.
Market Dynamics
REACH authorization requirements under ECHA oversight are compressing the azo dye precursor supply base across European coating operations, forcing formulators toward metal-complex and organic alternatives while reshaping raw material procurement strategies.
Growth Catalysts
- Automotive Lightweighting Mandates:German and Japanese OEM specification programs are expanding anodized aluminum in chassis and trim applications, creating specification-grade demand for high-lightfastness dye systems.
- REACH Hexavalent Chromium Phase-Out:ECHA restrictions on chromate conversion coatings are accelerating migration toward organic dyeing systems across European architectural and industrial finishing operations.
- Consumer Electronics Cluster Concentration:Chinese manufacturing hubs serving domestic and export OEM accounts are driving volume demand for color-consistent organic dyes in smartphone and laptop housings.
Market Restraints
- Raw Material Concentration Risk:Captive azo and metal-complex pigment production concentrates among integrated European manufacturers, limiting supply flexibility for regional dye blenders.
- Process Chemistry Lock-In:Sulfuric acid electrolysis infrastructure investments create technical path dependency, slowing adoption of alternative anodizing chemistries that require dye reformulation.
- Substitution Pressure from Powder Coatings:Architectural and heavy equipment segments increasingly specify thermoset powder alternatives where color durability requirements permit lower-cost finishing.
Strategic Opportunities
- Carbon Border Adjustment Alignment:EU Green Deal lifecycle assessment transparency requirements create qualification advantages for dye suppliers with verified low-carbon synthesis routes.
- Chromate-Free Metal Complex Expansion:Formulators developing vivid-gamut, environmentally compliant dye systems capture specification share in automotive and electronics verticals.
- North American Job-Shop Service Models:Regional dye distributors offering formulation flexibility and compressed lead times capture machinery component finishing demand from integrated pigment suppliers.
Industry Challenges
- Colorimetric Calibration Expertise Gap:Anodizing operations lack sufficient spectrophotometric quality control specialists to maintain Delta-E tolerances required by consumer electronics OEMs.
- Multijurisdictional Compliance Complexity:Dye manufacturers face divergent EPA effluent guidelines, OSHA hexavalent chromium exposure limits, and REACH authorization timelines across U.S. and European production footprints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aluminum Anodizing Dyes Market |
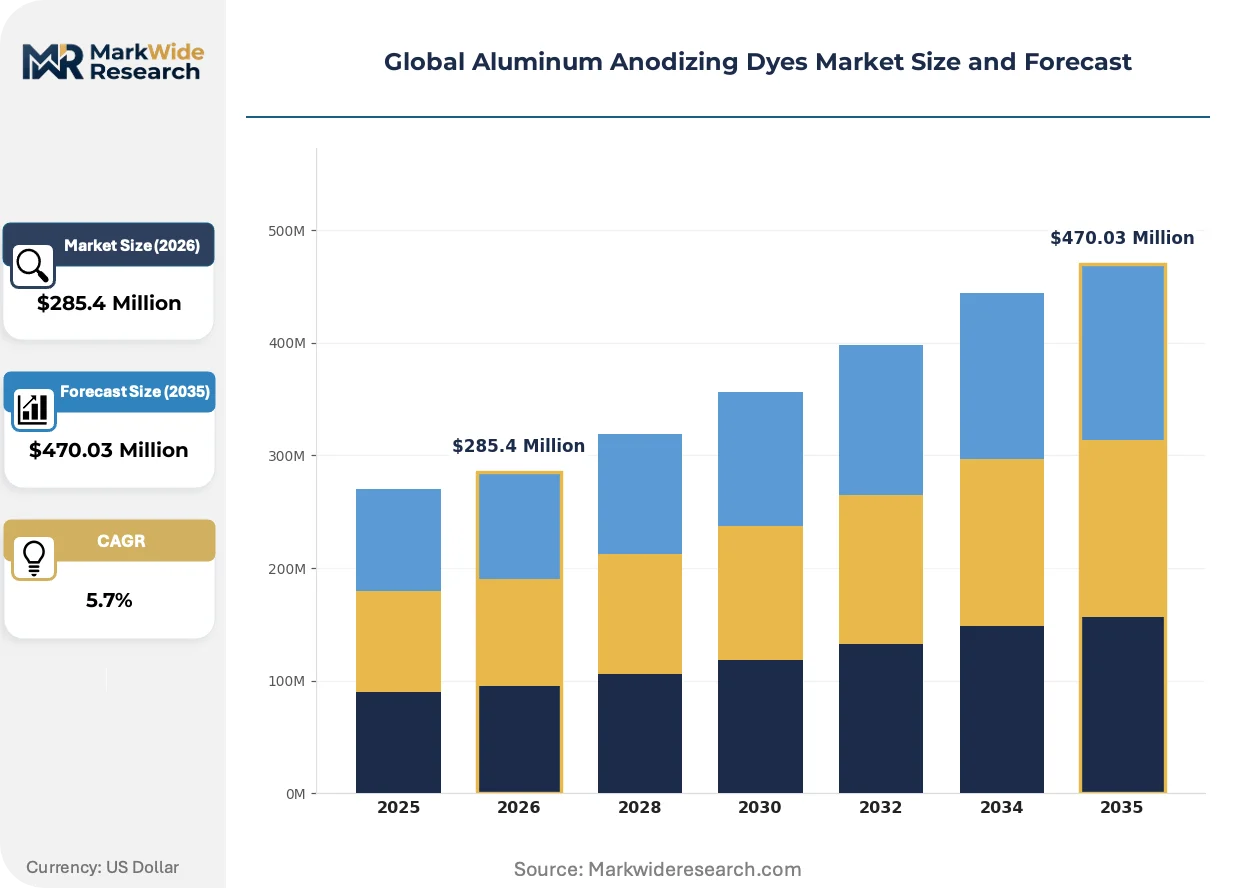
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $470.03 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Dyes, Inorganic Dyes, Metal Complex Dyes, Pre-Anodized Pigments Application: Architectural Panels, Consumer Electronics, Machinery Components, Lighting Fixtures, Decorative Items Technology: Sealing Methods, Electrolytic Coloring, Organic Dyeing, Anodic Oxide Layer Coloring End User Industry: Building & Construction, Consumer Durables, Heavy Equipment, Electrical Components |
| Companies Covered | Heubach Group, Kingscote Chemicals Inc., SIC Technologies, Stratosphere Enterprise Co. Ltd., Okuno Chemical Industries Co., Ltd., Clariant AG, CHEMEON Surface Technology, Colorants Chem Private Limited, DayGlo Color Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aluminum Anodizing Dyes Market Shifts & Advancements
Digital color matching systems and closed-loop dye bath management are compressing batch-to-batch variation while regulatory chemistry restrictions are fragmenting process technology adoption across geographic markets.
Metal-complex dye technology is fragmenting the traditional organic-inorganic product hierarchy in aluminum anodizing. These formulations bond with porous anodic oxide layers to deliver chromate-free vivid coloration with enhanced UV stability. Automotive trim suppliers in Germany and Japan are adopting metal-complex systems at accelerated qualification cycles. The technology is fragmenting supplier tiers by enabling mid-scale formulators to meet OEM lightfastness specifications without captive pigment synthesis infrastructure.
REACH authorization requirements under ECHA oversight continue restricting specific azo dye precursors in European coating supply chains. This regulatory pressure is forcing reformulation cycles among architectural anodizing operations dependent on legacy color palettes. German and Italian finishing houses are responding by qualifying metal-complex and high-performance organic alternatives, compressing the window for azo-based product lines.
Specification-driven procurement is consolidating dye supplier relationships around certified color consistency and regulatory documentation. Consumer electronics OEMs in China are unbundling after-sales technical support from commodity dye supply, creating separate service contracts for colorimetric calibration and bath chemistry optimization. This behavioral shift is most visible in Shenzhen and Dongguan manufacturing clusters serving export accounts.
Global Aluminum Anodizing Dyes Market Segmentation
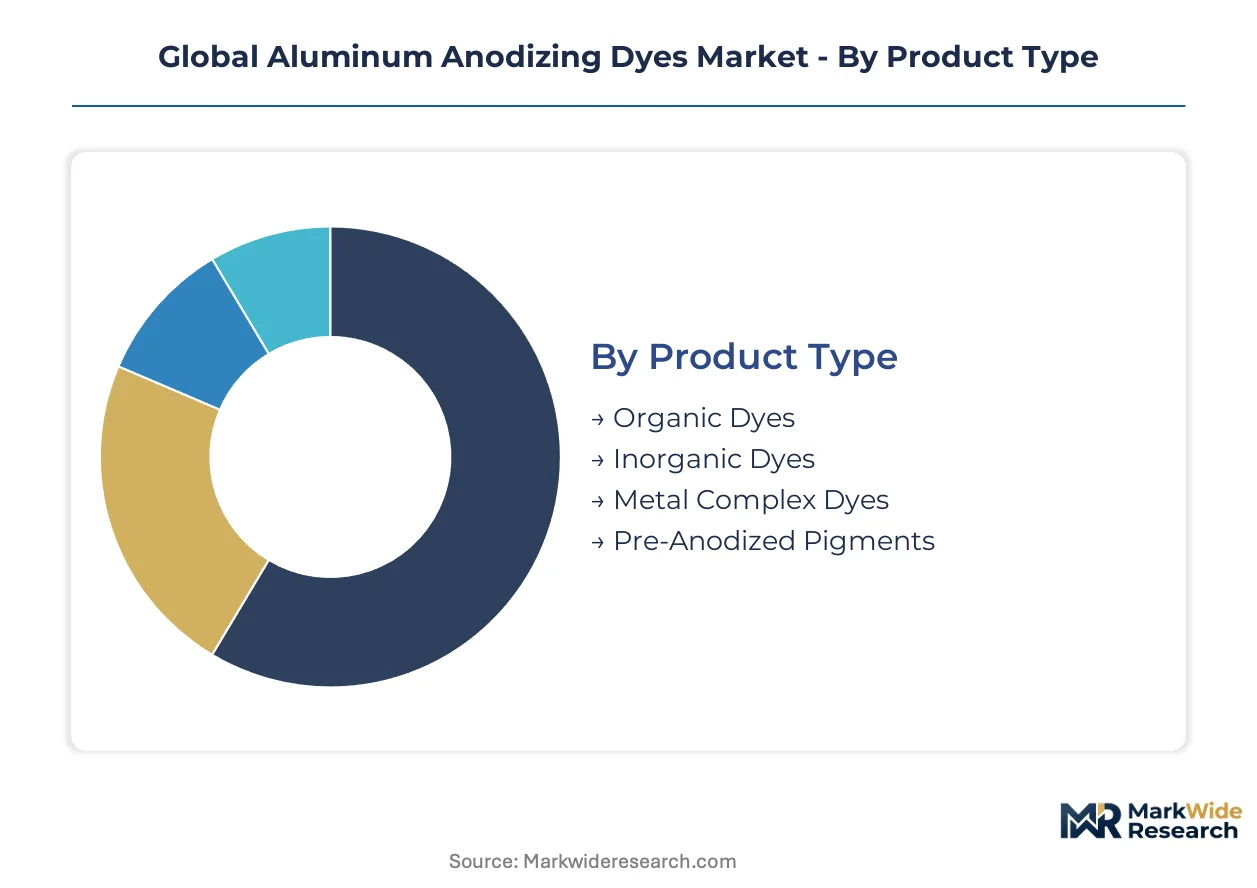
Segmentation in aluminum anodizing dyes reveals how formulation chemistry, application durability requirements, and regulatory compliance intersect to determine supplier positioning and margin capture across distinct value pools.
Product Type:
Margin pools concentrate in specialty organic and metal-complex formulations where REACH-driven chromate replacement creates specification premiums, while commodity inorganic lines face pricing pressure from powder coating substitution.
- Organic Dyes:These azo-based and anthraquinone formulations deliver vivid color gamut with molecular bonding to porous anodic oxide layers. Consumer electronics OEMs in Shenzhen and Dongguan clusters specify organic dye systems for smartphone and laptop housings where Delta-E color consistency determines supplier qualification.
- Metal Complex Dyes:Chromium-free metal-ligand complexes bond with anodic oxide layers to achieve UV-stable vivid coloration without hexavalent chromium. German and Japanese automotive trim suppliers are accelerating qualification cycles for these systems as OEMs phase out chromate conversion coatings under ECHA restrictions.
- Inorganic Dyes:Iron oxide and cobalt-based pigment dispersions dominate earth-tone architectural specifications where cost sensitivity outweighs color breadth requirements.
- Pre-Anodized Pigments:These concentrated dispersions streamline bath preparation for high-volume job-shop operations serving machinery component finishing contracts.
Organic dyes hold installed capacity across Chinese electronics manufacturing. Metal complex dyes are rotating up the share rankings in European automotive qualification programs.
Application:
Volume concentration follows manufacturing cluster geography, with specification-grade applications commanding formulation premiums tied to lightfastness certification and regulatory documentation.
- Architectural Panels:Curtain wall and facade systems require 15-25 micron anodic coatings with color stability under UV exposure and salt spray. German and Italian finishing houses specify high-performance organic and metal-complex systems to meet EU Green Deal lifecycle assessment criteria for carbon border adjustment compliance.
- Consumer Electronics:Smartphone, laptop, and tablet housings demand 5-15 micron decorative coatings with precise color matching across batch production. Chinese manufacturing hubs serving Apple and Samsung OEM accounts drive volume demand for color-consistent organic dye systems with spectrophotometric quality control protocols.
- Machinery Components:Industrial equipment and automation hardware utilize sulfuric acid anodizing with earth-tone inorganic dyes where functional corrosion resistance supersedes decorative requirements.
- Lighting Fixtures:LED housing and reflector applications specify anodized aluminum for thermal management combined with decorative coloration through organic dye systems.
- Decorative Items:Furniture hardware, sporting goods, and consumer accessories utilize anodizing for aesthetic differentiation with shorter durability requirements permitting lower-cost dye formulations.
Architectural panels hold installed capacity across European coating operations. Consumer electronics is climbing the fastest in absolute volume terms.
Technology:
Process chemistry selection determines dye compatibility and regulatory compliance trajectory, with sealing and electrolytic methods anchoring established infrastructure while organic dyeing captures specification-driven replacement demand.
- Sealing Methods:Hot water, nickel acetate, and cobalt acetate sealing processes close porous anodic oxide layers to lock in dye molecules and enhance corrosion resistance. These methods remain dominant across North American job-shop anodizers serving machinery component orders where EPA effluent guidelines constrain nickel discharge.
- Organic Dyeing:Direct immersion in organic dye baths after sulfuric acid electrolysis enables vivid coloration with molecular-level bonding to anodic oxide structure. This technology is expanding most quickly in Chinese electronics manufacturing and European automotive trim applications as metal-complex formulations displace legacy azo systems.
- Electrolytic Coloring:AC electrolysis with metal salt solutions deposits tin, nickel, or cobalt into anodic oxide pores to achieve bronze, black, and grey tones without organic dyes.
- Anodic Oxide Layer Coloring:Integral color anodizing through alloy modification or electrolyte additives produces bronze and black finishes without separate dyeing steps.
Sealing methods hold installed capacity across legacy architectural and industrial finishing lines. Organic dyeing is gaining share fastest in specification-grade consumer electronics and automotive applications.
End User Industry:
Customer procurement behavior fragments by compliance burden and colorimetric sophistication, with building and construction prioritizing cost stability while consumer durables demand batch-to-batch consistency documentation.
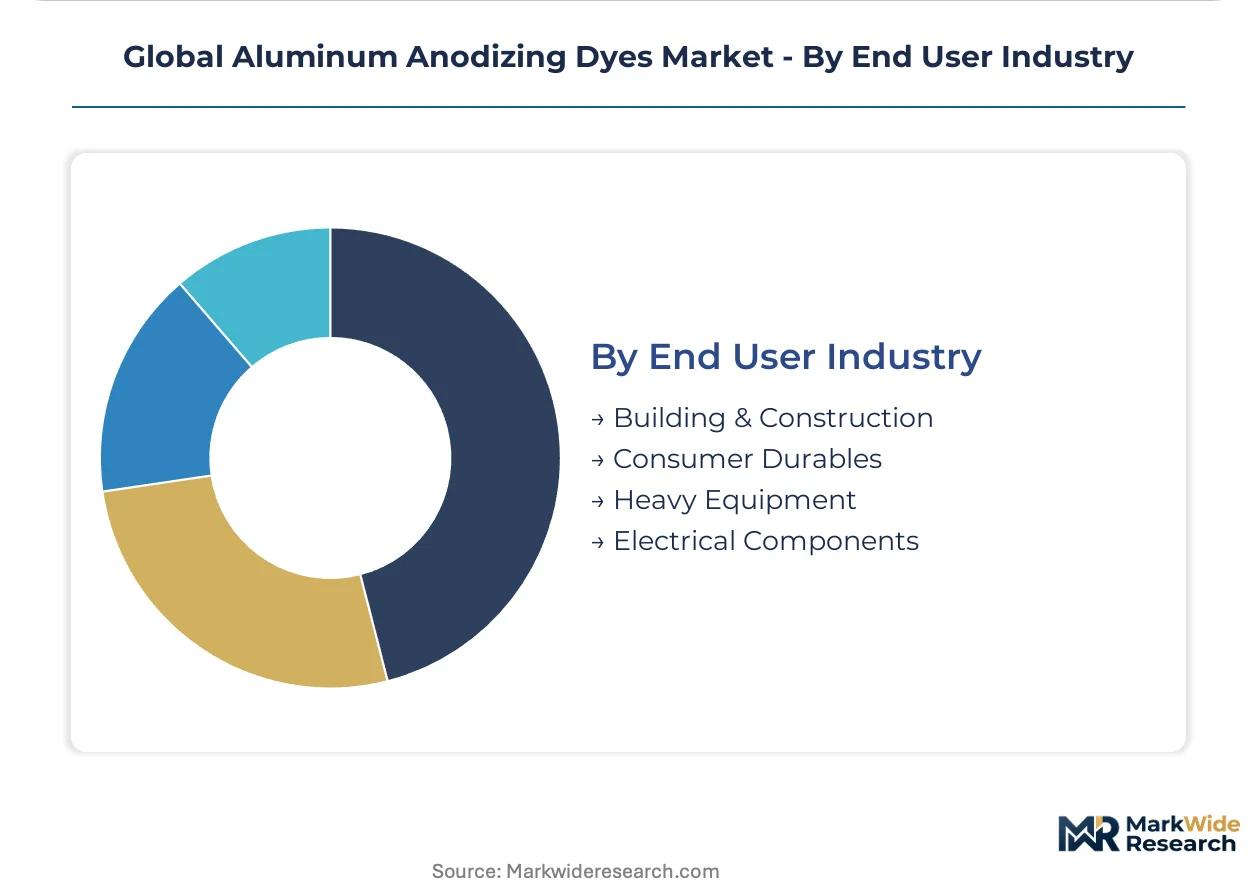
- Building & Construction:Curtain wall, window, and facade systems specify anodized aluminum for durability and aesthetic coherence across large surface installations. German and Italian architectural finishers are reformulating away from restricted azo dye precursors under ECHA authorization timelines, compressing supplier relationships around metal-complex alternatives.
- Consumer Durables:Electronics housings, appliances, and personal devices require precise color matching with regulatory documentation for RoHS and REACH compliance. Chinese OEMs in Shenzhen and Dongguan are unbundling after-sales technical support from commodity dye supply, creating separate service contracts for colorimetric calibration.
- Heavy Equipment:Agricultural, construction, and mining machinery utilize anodized components for corrosion resistance with earth-tone color palettes dominated by inorganic dye cost efficiency.
- Electrical Components:Busbar, heat sink, and enclosure applications leverage anodizing for electrical insulation and thermal management with functional rather than decorative color requirements.
Building and construction holds installed capacity across European architectural coating accounts. Consumer durables is rotating up the share rankings in Chinese manufacturing cluster procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with integrated German pigment manufacturers while Chinese dye blenders compete on volume scale in electronics manufacturing clusters. Regulatory divergence between ECHA authorization timelines and EPA effluent guidelines fragments procurement strategies across Atlantic supply chains. Automotive lightweighting mandates in Germany and Japan are rotating demand toward specification-grade metal-complex formulations.
Germany
Automotive OEM specification programs for chassis and trim components are driving qualification cycles for high-lightfastness dye systems. ECHA REACH restrictions on hexavalent chromium processes are accelerating migration toward organic dyeing systems across Baden-Württemberg coating operations. Stuttgart and Munich manufacturing clusters anchor specification-grade demand for metal-complex alternatives in premium vehicle segments.
China
Consumer electronics OEMs in Shenzhen and Dongguan are unbundling after-sales technical support from commodity dye supply for smartphone and laptop housings. MEE environmental enforcement is elevating lifecycle assessment transparency as a procurement criterion for multinational aluminum finishers. Pearl River Delta manufacturing hubs dominate volume demand for color-consistent organic dye systems serving Apple and Samsung export accounts.
United States
North American job-shop anodizers serving machinery component orders are prioritizing formulation flexibility and compressed lead times from regional dye distributors. EPA effluent guidelines and OSHA hexavalent chromium exposure limits constrain process chemistry choices toward trivalent and organic systems. Midwest industrial finishing corridors in Ohio and Michigan are consolidating supplier relationships around certified regulatory documentation.
Japan
Automotive lightweighting mandates from METI are expanding anodized aluminum specification in chassis applications requiring UV-stable coloration. JIS standards for architectural coatings are aligning with EU Green Deal carbon border adjustment criteria for export-oriented finishers. Nagoya and Osaka manufacturing clusters are accelerating metal-complex dye qualification cycles for chromate-free trim systems.
Italy
Architectural finishing houses in Lombardy and Veneto are reformulating away from restricted azo dye precursors under ECHA authorization timelines. EU Green Deal lifecycle assessment requirements are compressing supplier relationships around metal-complex alternatives for curtain wall and facade systems. Milan-based coating operations are qualifying high-performance organic systems to meet carbon border adjustment compliance criteria.
Global Aluminum Anodizing Dyes Market Competitive Landscape
Concentration sits with integrated European pigment manufacturers controlling captive azo and metal-complex production for architectural and automotive accounts. Regional dye blenders in North America and Asia compete on formulation service models and compressed lead times for job-shop anodizers. Three archetypes dominate: integrated pigment suppliers with backward synthesis control, specialty organic formulators targeting electronics OEMs, and regional blenders serving machinery component finishers. Competitive moves center on chromate-free metal-complex expansion and carbon border adjustment alignment through verified low-carbon synthesis routes.
Within the integrated European tier, Heubach Group and Clariant AG exemplify archetypes of captive raw material control and specialty organic formulation expertise respectively. Kingscote Chemicals Inc. occupies a position among North American regional blenders competing on service velocity for job-shop accounts. These three anchors illustrate how capital-intensity divergence redraws competitive boundaries between synthesis-integrated and formulation-flexible business models.
| Leading Market Players |
|---|
| Heubach Group |
| Kingscote Chemicals Inc. |
| SIC Technologies |
| Stratosphere Enterprise Co. Ltd. |
| Okuno Chemical Industries Co., Ltd. |
| Clariant AG |
| CHEMEON Surface Technology |
| Colorants Chem Private Limited |
| DayGlo Color Corporation |
| Others |
Supply & Pricing Matrix
Metal-complex dye substitution for legacy azo systems simultaneously redraws European supply geography and compresses pricing premiums across specification-grade automotive and architectural accounts. REACH-driven precursor restrictions force formulators toward captive pigment manufacturers in Germany while regional blenders in North America capture service-margin pools from job-shop machinery finishers.
Pricing Analysis
Configured-to-order pricing for metal-complex formulations commands substantial premiums over standard organic dye catalog pricing, with Delta-E certification and chromate-free documentation driving differentiation. Three-tier pricing structure across premium certification-grade, standard performance, and economy inorganic tiers reflects buyer sophistication divergence. Pricing pressure stems from powder coating substitution in architectural earth-tone segments. Machinery component finishers exhibit highest price sensitivity, while automotive OEM qualification programs demonstrate lowest elasticity.
Supply Chain Analysis
Germany and Switzerland anchor captive azo and metal-complex pigment synthesis for European architectural and automotive coating accounts. Raw material procurement draws from naphthalene derivatives, metal salt precursors, and sulfonated intermediates concentrated among integrated chemical manufacturers. Single-source vulnerability concentrates in metal-ligand complex precursors subject to ECHA authorization timelines. Distribution runs through qualified specialty chemical distributors serving regional anodizing job-shops with formulation flexibility and technical service bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation between ECHA REACH timelines and EPA effluent guidelines fragments procurement standards, creating specialist niches for compliance-focused formulators and regional service providers.
For Market Incumbents: Shield specification-grade positions by accelerating metal-complex R&D pipelines and securing captive precursor supply agreements ahead of ECHA authorization deadlines. Deepen backward integration into azo pigment synthesis to control pass-through cost volatility from restricted precursor lists.
For New Entrants and Emerging Players: EU Green Deal carbon border adjustment fast-track certification creates qualification pathways for low-carbon synthesis specialists. Target North American job-shop machinery finishing corridors with compressed lead-time service models and unbundled technical support contracts.
For Investors and Strategic Acquirers: The market sits at a substitution-phase inflection that favors chromate-free formulation specialists with verified lifecycle assessment documentation. Long-term viability centers on regulatory compliance infrastructure rather than commodity scale. Acquisition focus should concentrate on mid-cap metal-complex developers with automotive qualification pipelines. Signal to watch: ECHA authorization list expansion velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pigment Synthesis | Captive azo precursor production insulates Heubach Group from REACH supply disruptions. |
| Chromate-Free Metal Complex Expansion | Clariant AG's organic dye R&D pipeline targets ECHA-compliant automotive qualification cycles. |
| Regional Distributor Service Models | Kingscote Chemicals Inc. captures North American job-shop demand through formulation flexibility. |
| Carbon Border Adjustment Alignment | Verified low-carbon synthesis routes qualify suppliers for EU Green Deal procurement criteria. |
| Technical Support Unbundling | Shenzhen OEMs separate colorimetric calibration contracts from commodity dye supply agreements. |
Research Methodology
Cross-validation between primary interviews with coating operation managers and secondary trade data anchors the qualitative findings. Stakeholder engagement encompassed plant managers at European architectural finishers, procurement leads at Chinese electronics OEMs, technical R&D directors at pigment manufacturers, and distribution channel partners serving North American job-shops. Secondary sources included ECHA authorization databases, EPA effluent guideline filings, customs trade records, and SEC disclosures from listed chemical companies. Bottom-up volume estimates triangulated against top-down market sizing across formulation chemistry segments.
Sensitivity analysis tested forecast robustness across regulatory acceleration and substitution scenarios over the projection horizon. Segmentation modeling incorporated product type, application durability tier, end-use industry procurement behavior, and regional regulatory cluster dimensions. CAGRs derived from historical trajectory analysis adjusted for phase-out timelines and qualification cycle durations. Industry-specific inputs captured REACH authorization list revisions and automotive OEM lightweighting specification velocity.
Underlying assumptions cover stable sulfuric acid electrolysis infrastructure deployment, with deviation risk concentrated in accelerated powder coating substitution and ECHA precursor restriction expansion. Forecasts reflect these conditions with explicit scenario weighting. Recalibration cycles align with material shifts in regulatory authorization timelines and automotive platform standardization announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Global Cosmetic Pigments Market
Dyes and Pigments
Acid Stable Blue Market
Dyes and Pigments
Iridescent Pigments Market
Dyes and Pigments
Carmoisine Market
Dyes and Pigments
Lithol Rubine BK Market
Dyes and Pigments
Algal Pigments Market
Dyes and Pigments
Titanium Dioxide Pigment Market
Dyes and Pigments
Water-Based Pigments Market
Dyes and Pigments
Pearl Pigment Market
Dyes and Pigments
Metallic Pigments Market
Dyes and Pigments
Acid Violet 43 Market
Dyes and Pigments
Copper Chromite Black Pigment Market
Dyes and Pigments
Cacao Husk Pigment Market
Dyes and Pigments
Photoluminescent Paints Market
Dyes and Pigments
Europe Hair Colorants Market
Dyes and Pigments
Pharmaceutical Dyes Market