
 Automotive Suspension System Lubricants Market | 2026-2036
Automotive Suspension System Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Suspension System Lubricants Market Insights
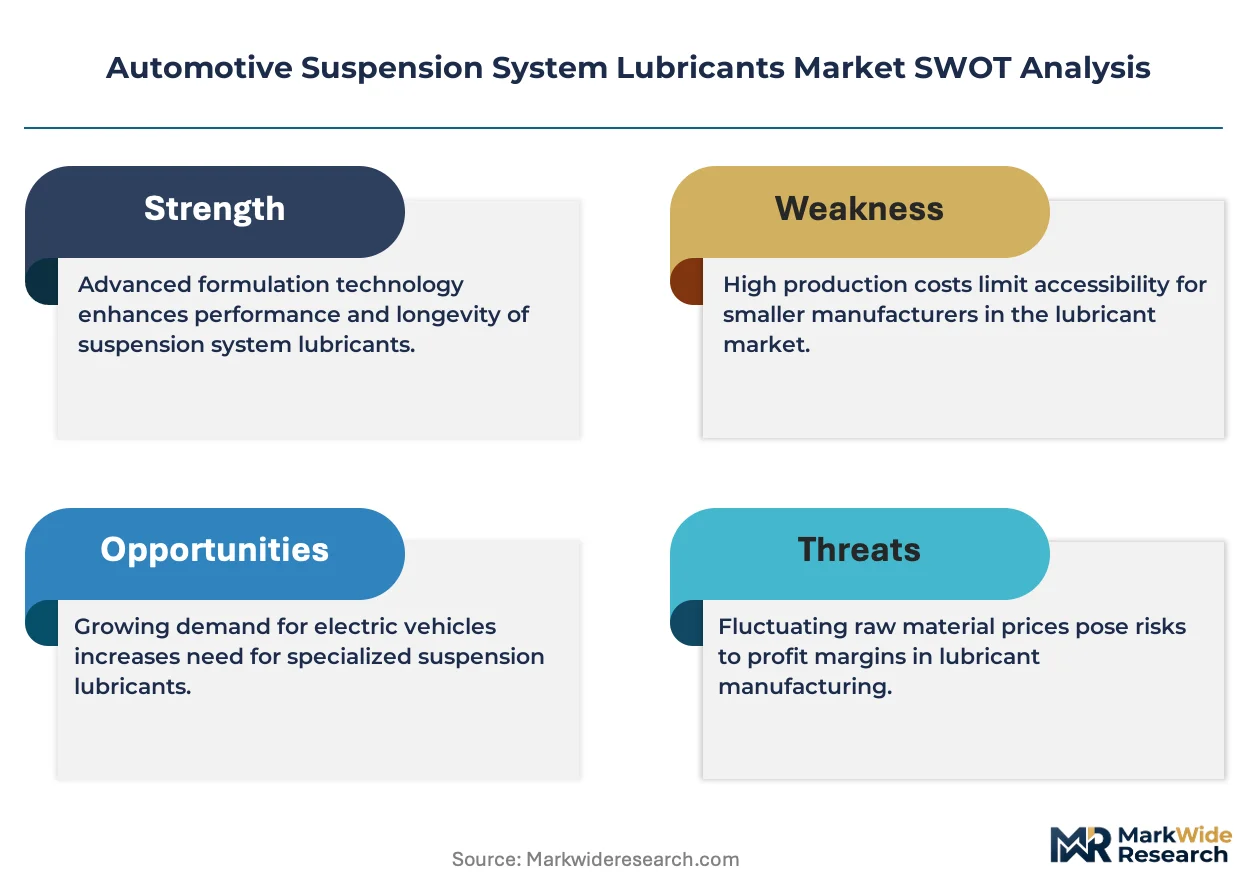
Multi-source procurement for base oil feedstocks is repositioning how lubricant blenders manage cost volatility and supply security. Shell plc leverages its integrated upstream-downstream structure to sustain margin control across synthetic grease production. FUCHS PETROLUB SE anchors its position through specialized OEM partnerships in European passenger vehicle chassis systems. Exxon Mobil Corp. competes on manufacturing scale, operating large-batch blending facilities that serve multiple aftermarket channels simultaneously.
Automotive suspension system lubricants are formulated products designed to reduce friction, prevent wear, and maintain damping performance across shock absorbers, strut assemblies, control arm bushings, and ball joints, typically operating within temperature ranges from minus forty to one hundred fifty degrees Celsius and incorporating thickeners such as lithium complex or polyurea for mechanical stability under cyclic loading. Their primary commercial purpose is to extend service intervals and preserve ride quality characteristics specified by vehicle manufacturers. Greases dominate volume demand due to their adhesion properties and sealing function in exposed underbody locations, while synthetic technology commands premium positioning as OEMs tighten low-temperature viscosity specifications for electrified platforms. Aftermarket Providers represent a fragmented but high-margin channel where technical service support and brand recognition determine repeat purchasing behavior among independent repair facilities.
EPA regulations under the Toxic Substances Control Act constrain certain additive chemistries in lubricants sold into U.S. vehicle service markets, while REACH registration requirements in Europe mandate full substance characterization for imported formulation components. The EU Green Deal and associated F-Gas Regulation indirectly shape demand by accelerating chassis lightweighting programs that impose new thermal and compatibility requirements on suspension lubricants. Stakeholders must monitor evolving OEM specifications for electrified vehicle architectures, where modified duty cycles and regenerative braking loads alter suspension component friction profiles and corresponding lubricant performance demands.
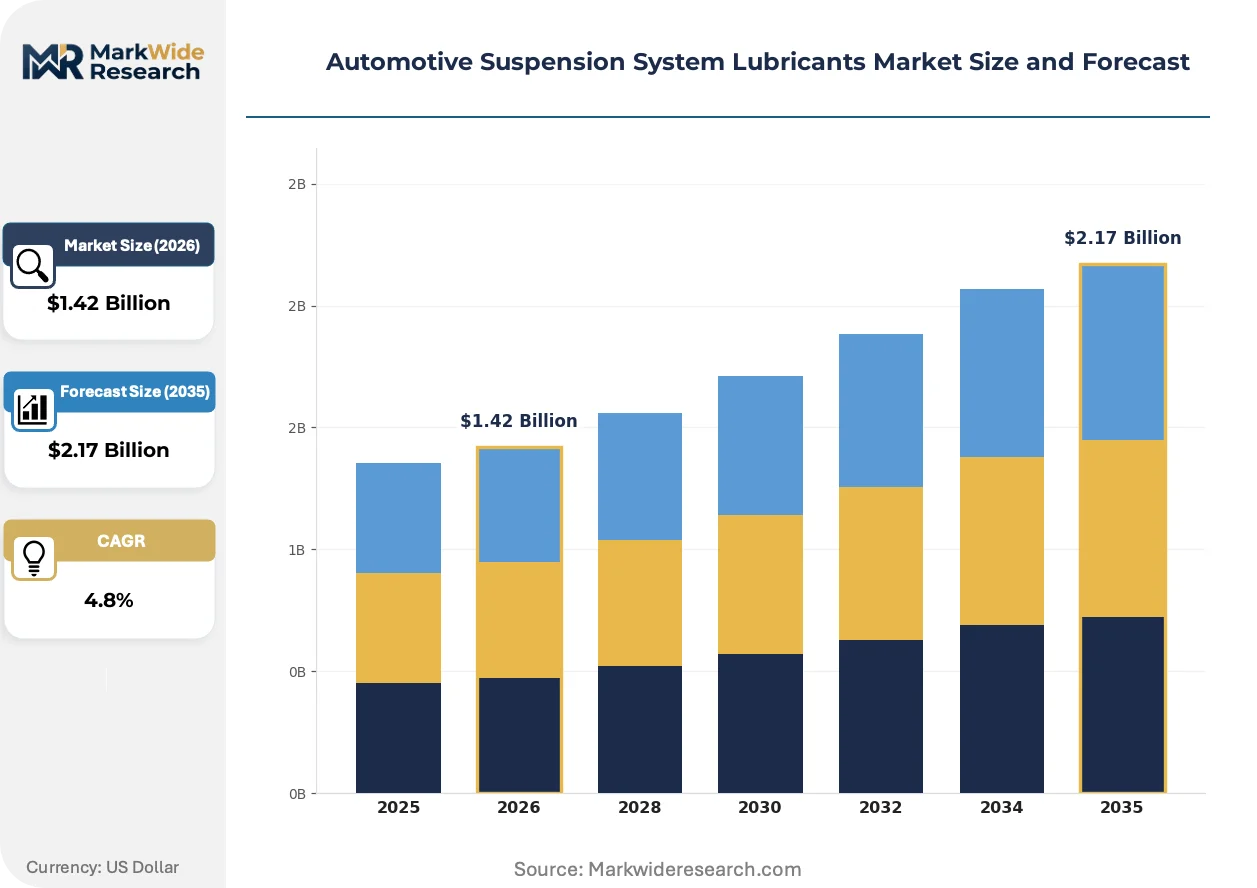
Market Dynamics
Electric vehicle platform proliferation is restructuring suspension lubricant specifications, as regenerative braking systems and battery-weight distribution impose novel friction and thermal loads on chassis components.
Growth Catalysts
- EPA Fuel-Economy Mandates:The United States' Corporate Average Fuel Economy standards compel automakers to specify low-viscosity synthetic greases that reduce parasitic drag in underbody systems.
- EV Chassis Engineering:Battery-electric architectures demand modified suspension kinematics, creating fresh demand for polyurea-thickened lubricants with extended service intervals.
- Germany's Precision Manufacturing:Stuttgart and Munich-based OEMs specify high-performance chassis greases that command technical premiums across European supply chains.
Market Restraints
- Base Oil Volatility:Group III and PAO feedstock prices fluctuate with naphtha cracking economics, compressing blender margins during upstream disruptions.
- REACH Compliance Burden:ECHA registration requirements for novel additive packages extend formulation development timelines by eighteen to thirty-six months.
- Mineral Oil Substitution:Conventional lithium-complex greases retain cost advantages in price-sensitive aftermarket channels, slowing synthetic penetration.
Strategic Opportunities
- India's Aftermarket Expansion:Noida and Chennai automotive clusters generate unmet demand for technically supported chassis lubricants as vehicle parc ages.
- F-Gas Regulation Tailwind:The EU Green Deal accelerates lightweight suspension materials that require compatible lubricant chemistries with enhanced thermal conductivity.
- Digital Service Integration:Connected vehicle diagnostics enable predictive maintenance alerts, opening direct-to-fleet lubricant replenishment channels.
Industry Challenges
- Tribology Talent Scarcity:Formulation chemists with combined expertise in elastomer compatibility and electrified duty cycles command premium compensation.
- OEM Specification Divergence:Proprietary grease approvals from individual automakers fragment volume and complicate inventory planning for blenders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Suspension System Lubricants Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.17 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Greases, Oils, Powders, Pastes Application: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Trucks, Race Cars Technology: Synthetic, Semi-Synthetic, Mineral, Biodegradable End User: OEMs, Aftermarket Providers, Service Stations, Fleet Owners |
| Companies Covered | BP Plc, Exxon Mobil Corp., FUCHS PETROLUB SE, Ferdinand Bilstein GmbH + Co. KG, Lucas Oil Products Inc., MOTUL SA, Valvoline Inc., Shell plc, TotalEnergies SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Suspension System Lubricants Market Trends and Innovations
Synthetic chemistry advancement and regulatory chemistry constraints are simultaneously elevating formulation complexity and procurement sophistication across the value chain.
Polyurea-thickened synthetic greases are expanding into electric vehicle suspension architectures. These lubricants deliver superior mechanical stability under high-frequency damper cycling. BMW and Mercedes-Benz procurement teams now mandate polyurea chemistry for front-strut assemblies. The technology is expanding into premium aftermarket segments as independent repair chains seek OEM-equivalent specifications.
REACH authorization procedures under ECHA jurisdiction now require full substance dossiers for imported thickener packages. This regulatory tightening excludes non-compliant suppliers from European formulation supply. Small and mid-scale blenders in Poland and the Czech Republic face capital-intensive testing obligations to maintain market access.
Fleet operators now consolidate lubricant procurement through integrated maintenance contracts rather than spot aftermarket purchases. Large logistics companies in the United States negotiate multi-year supply agreements with technical service bundles attached. This consolidation compresses margins for distributors lacking diagnostic capabilities or field engineering support.
Automotive Suspension System Lubricants Market Segmentation
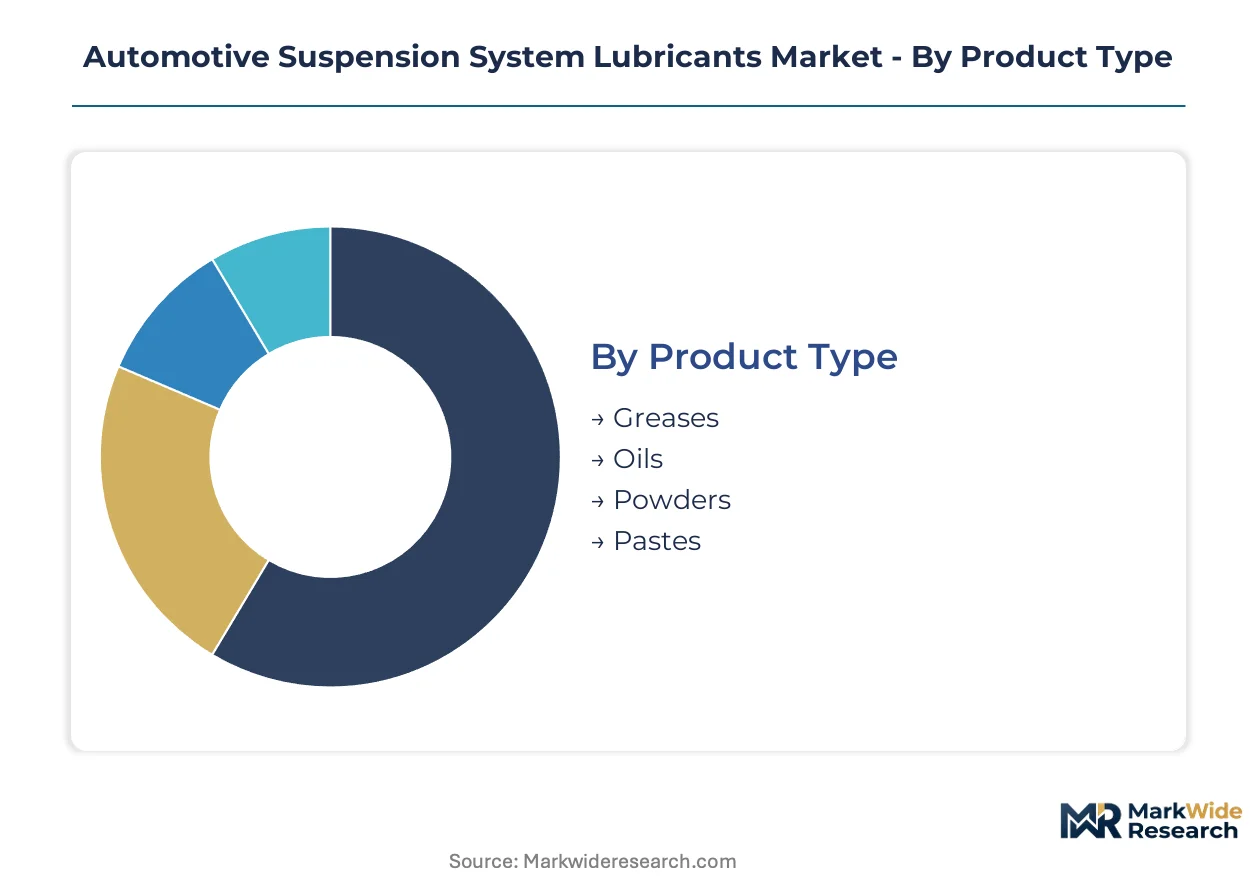
Segmentation in automotive suspension lubricants reveals how formulation chemistry, duty cycle severity, and procurement authority fragment demand across divergent technical specifications and margin structures. Buyers prioritize adhesion permanence, temperature stability, or regulatory compliance depending on vehicle architecture and service interval economics.
Product Type:
Buyers in this category differentiate primarily by exposure severity and reapplication frequency, with underbody sealing needs dominating volume against precision dosing applications.
- Greases:Lithium-complex and polyurea-thickened formulations provide mechanical stability under cyclic damper loading while sealing against water and road salt ingress. Demand concentrates in German OEM chassis specifications for premium passenger vehicles, where extended service intervals justify synthetic chemistry premiums despite mineral oil cost advantages in aftermarket channels.
- Oils:Low-viscosity synthetic fluids reduce parasitic drag in active suspension systems and hydraulic damper circuits. Stuttgart-based automakers specify these for electrified platforms where regenerative braking loads alter thermal profiles, with EPA fuel-economy mandates accelerating adoption across U.S. vehicle assemblies.
- Powders:Dry-film lubricants serve specialty motorsport and extreme-temperature applications where conventional base oils degrade.
- Pastes:High-viscosity compounds address assembly-line anti-seize requirements and threaded fastener lubrication during suspension module construction.
Greases lead volumes today; polyurea-thickened synthetics within this category are gaining share fastest.
Application:
Vehicle mass and duty cycle intensity determine specification stringency, with electrified passenger platforms creating novel thermal and kinematic demands absent in legacy commercial architectures.
- Passenger Vehicles:Battery-electric architectures impose modified suspension kinematics and weight distribution patterns that demand polyurea-thickened lubricants with extended drain intervals. BMW and Mercedes-Benz procurement teams in Germany now mandate these chemistries for front-strut assemblies, with specifications cascading into premium aftermarket segments as independent repair chains seek OEM equivalence.
- Heavy-Duty Trucks:Fleet operators in the United States consolidate procurement through integrated maintenance contracts with technical service bundles attached, compressing margins for distributors lacking diagnostic capabilities. High-load kingpin and spring-eye applications prioritize mechanical stability under constant vibration exposure.
- Commercial Vehicles:Light-duty vans and delivery trucks balance cost sensitivity with reliability requirements across diverse climatic operating envelopes.
- Race Cars:Motorsport applications demand extreme-pressure additives and rapid-breakdown formulations for post-event inspection visibility.
Heavy-Duty Trucks anchor current revenue concentration; Passenger Vehicles are expanding most quickly as EV platform proliferation rewrites specification books.
Technology:
Base oil selection reflects a trade-off between low-temperature fluidity requirements and feedstock cost volatility, with regulatory chemistry constraints increasingly tilting procurement toward synthetic categories.
- Synthetic:Polyalphaolefin and ester-based formulations deliver minus forty to one hundred fifty degrees Celsius operating ranges with stable viscosity indices. OEM procurement departments specify these for electric vehicle suspensions where modified duty cycles and regenerative braking loads alter friction profiles, with REACH authorization procedures excluding non-compliant suppliers from European formulation supply.
- Mineral:Group I and II base stocks retain cost advantages in price-sensitive aftermarket channels, though lithium-complex thickeners face substitution pressure as OEM specifications tighten.
- Semi-Synthetic:Blended formulations balance performance enhancement with partial cost mitigation for mid-tier vehicle segments.
- Biodegradable:Vegetable-derived base stocks address environmental compliance in sensitive operating territories, though thermal oxidation stability limits deployment to moderate-duty applications.
Mineral technology retains volume leadership; Synthetic categories are climbing the fastest as electrified platform specifications proliferate.
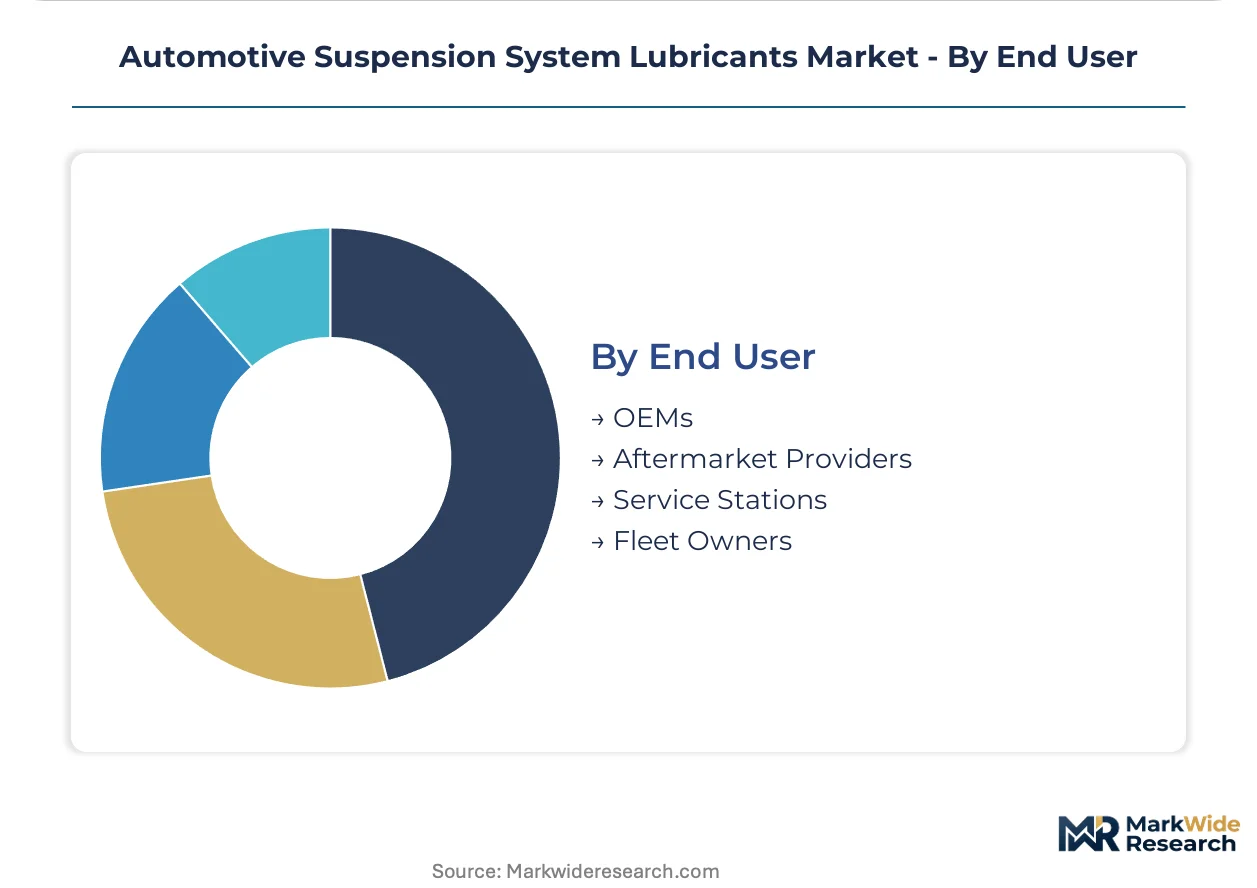
End User:
Procurement sophistication and technical support requirements separate stakeholders, with specification authority residing at OEM engineering centers while volume aggregates through fragmented service channels.
- OEMs:Vehicle manufacturers in Germany and the United States exercise proprietary grease approvals that fragment blender volumes and complicate inventory planning. Procurement teams specify polyurea chemistry for precision chassis systems, with individual automaker divergences preventing standardization across supply chains.
- Fleet Owners:Large logistics operators negotiate multi-year supply agreements with predictive maintenance integration, enabling direct replenishment channels through connected vehicle diagnostics. This consolidation rewards lubricant suppliers with field engineering capabilities and compresses pure-distributor margins.
- Aftermarket Providers:Fragmented independent repair facilities depend on brand recognition and technical service support for repeat purchasing decisions.
- Service Stations:High-volume quick-lube channels prioritize inventory turns and universal compatibility over application-specific optimization.
OEMs command specification authority; Fleet Owners are consolidating procurement fastest through integrated maintenance contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting formulation investments toward jurisdictions where REACH-equivalent compliance costs remain manageable. Blenders in Poland and the Czech Republic face capital-intensive testing obligations that advantage integrated producers with established ECHA dossiers.
United States
EPA fuel-economy mandates under Corporate Average Fuel Economy standards compel automakers to specify low-viscosity synthetic greases. The Toxic Substances Control Act constrains additive chemistries in vehicle service markets. Detroit and Michigan-based OEM procurement teams now mandate polyurea-thickened lubricants for electrified platform suspensions.
Germany
Stuttgart and Munich-based automakers specify high-performance chassis greases that command technical premiums across European supply chains. ECHA registration requirements under REACH mandate full substance characterization for imported formulation components. The Baden-Württemberg automotive cluster drives precision manufacturing standards that cascade into aftermarket specifications.
China
Domestic EV platform proliferation generates demand for extended-service-interval lubricants with modified thermal stability profiles. MIIT standards for new energy vehicles indirectly shape chassis component requirements. The Yangtze River Delta manufacturing corridor concentrates blending capacity serving both local OEMs and export markets.
India
Noida and Chennai automotive clusters generate unmet demand for technically supported chassis lubricants as vehicle parc ages. BIS certification requirements for automotive fluids create compliance barriers for non-standardized imports. The Tamil Nadu industrial belt anchors southern aftermarket distribution networks.
Japan
Precision suspension engineering for hybrid and battery-electric platforms sustains premium formulation demand. METI guidelines for resource-efficient manufacturing influence lubricant selection criteria. The Kanto region around Tokyo concentrates OEM engineering centers that exercise proprietary grease approval authority.
Automotive Suspension System Lubricants Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty synthetic formulations and regional aftermarket consolidation. The market structure reflects moderate consolidation among integrated oil majors alongside fragmentation among regional blenders serving independent service channels. Three archetypes dominate: upstream-integrated majors with captive base oil supply, specialized lubricant houses with OEM approval portfolios, and regional distributors with technical service capabilities. Capacity expansion and strategic partnerships represent the dominant competitive vectors as players position for electrified platform specifications.
Within the integrated-major tier, Shell plc and Exxon Mobil Corp. anchor positions through scale advantages and backward integration into synthetic base oil production. FUCHS PETROLUB SE exemplifies the specialized lubricant house archetype, occupying a position defined by OEM partnership depth rather than volume throughput. These three entities collectively represent the competitive spectrum from commodity scale to technical specialization.
| Leading Market Players |
|---|
| BP Plc |
| Exxon Mobil Corp. |
| FUCHS PETROLUB SE |
| Ferdinand Bilstein GmbH + Co. KG |
| Lucas Oil Products Inc. |
| MOTUL SA |
| Valvoline Inc. |
| Shell plc |
| TotalEnergies SE |
| Others |
Pricing and Supply Chain Analysis
Formulation chemists with combined expertise in elastomer compatibility and electrified duty cycles concentrate in the Stuttgart-Munich corridor, where labor-cost differentials between German engineering centers and Polish blending facilities widen pricing-tier spreads across synthetic and mineral formulations.
Pricing Analysis
Distributor margin compression runs through aftermarket channels as fleet operators consolidate procurement through direct-to-OEM agreements with technical service bundles attached. Three-tier pricing structure across premium, standard, and economy levels separates polyurea-thickened synthetics from lithium-complex semi-synthetics from mineral-based economy grades. Cost compression in the economy tier is intensifying because conventional greases retain cost advantages in price-sensitive independent repair facilities. Fleet owners exhibit the lowest price sensitivity due to predictive maintenance integration, while service stations prioritize inventory turns over application-specific optimization.
Supply Chain Analysis
Single-source vulnerability sits with Group III and PAO base oil feedstocks drawn from naphtha cracking economics in the United States, South Korea, and Singapore. Synthetic base oil production rests on polyalphaolefin and ester chemistry inputs, with thickener packages sourced from lithium complex and polyurea specialty chemical suppliers. Tariff exposure on imported additive packages from non-REACH-compliant jurisdictions fragments European formulation supply. Distribution runs through integrated oil majors with captive base oil production, regional blenders serving independent service channels, and technical distributors with field engineering capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a geographic-arbitrage play between REACH-compliant European formulation costs and India's BIS certification barriers that protect domestic blenders from standardized import competition.
For Market Incumbents: Extend polyurea-thickened synthetic capacity to serve BMW and Mercedes-Benz procurement mandates for electrified platform suspensions. Deepen backward integration into Group III base oil production to cushion margin compression during naphtha cracking disruptions. Lock in multi-year supply agreements with fleet operators before diagnostic-enabled predictive maintenance consolidates procurement further. For New Entrants and Emerging Players: Capture unmet demand in Noida and Chennai automotive clusters where aging vehicle parc outpaces technically supported chassis lubricant supply. Target India's aftermarket through BIS-certified formulations that bypass import compliance barriers. Lead with technical service support bundled with grease products to differentiate from commodity distributors lacking field engineering presence. For Investors and Strategic Acquirers: Specialized lubricant houses with OEM approval portfolios are the most active acquirer in this space, seeking targets with polyurea formulation expertise and German automaker relationships. The long-term viability window favors blenders with REACH dossiers and electric vehicle specification alignment over mineral-dependent commodity producers. Watch for inflection when connected vehicle diagnostics penetration crosses threshold to enable predictive maintenance-driven direct replenishment channels.| Strategic Initiative | Industry Significance |
|---|---|
| Polyurea Formulation Capacity Expansion | Meets BMW and Mercedes-Benz electrified platform procurement mandates with extended-service-interval chemistry. |
| REACH Dossier Completion | Preserves European market access as ECHA authorization procedures exclude non-compliant thickener suppliers. |
| Fleet Maintenance Contract Integration | Captures volume consolidation as logistics operators negotiate multi-year agreements with predictive diagnostics. |
| India BIS Certification Investment | Unlocks Noida and Chennai aftermarket demand protected from non-standardized import competition. |
| Backward Integration into Synthetic Base Oil | Insulates margin control from naphtha cracking volatility affecting Group III and PAO feedstock economics. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and dealership operations managers with secondary validation from vehicle production databases, IHS Markit registration data, SEC 10-K filings from integrated oil majors, and customs trade records for base oil and thickener imports. Bottom-up volume builds across grease, oil, powder, and paste categories triangulated against top-down market sizing from automotive production forecasts.
Historical reference periods anchored the projection horizon to established OEM specification cycles and regulatory implementation timelines, with segmentation modeling across product type, application, technology, and end user dimensions. CAGRs were derived from elasticity-adjusted demand curves incorporating electric vehicle platform proliferation rates, REACH compliance cost trajectories, and fleet operator procurement consolidation patterns. Industry-specific inputs included electrified suspension duty cycle severity indices and polyurea thickener adoption curves from German automaker technical specifications.
Base oil price volatility, REACH authorization delays, and OEM specification divergence are the dominant revision risks that could compress or extend the projected expansion trajectory. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Qatar Automotive Lubricants Market
Lubricants
Chile Lubricants Market
Lubricants
Open Gear Lubricants Market
Lubricants
Poland Commercial Vehicles Lubricants Market
Lubricants
Forestry Lubricants Market
Lubricants
Norway Commercial Vehicles Lubricants Market
Lubricants
Egypt Lubricants Market
Lubricants
Industrial Gear Oil Market
Lubricants
Russia Commercial Vehicles Lubricants Market
Lubricants
Construction Lubricants Market
Lubricants
France Lubricants Market
Lubricants
Plastic Lubricants Market
Lubricants
Italy Lubricants Market
Lubricants
Lubricants for Cement Industry Market
Lubricants
Morocco Lubricants Market
Lubricants
Global Finished Lubricant Market