
 Malaysia Commercial Vehicles Lubricants Market | 2026-2036
Malaysia Commercial Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Commercial Vehicles Lubricants Market Foresight
Fleet operators are rotating toward higher-specification lubricant procurement as transportation companies extend vehicle replacement cycles. PETRONAS Lubricants International leverages captive refinery feedstock to dominate domestic base oil supply. Shell anchors its position through integrated service programs bundling oil analysis with fleet maintenance contracts. ExxonMobil competes via specialized synthetic formulations engineered for tropical heat degradation.
Malaysia commercial vehicles lubricants comprise formulated petroleum-based or synthetic fluids engineered to reduce friction, dissipate heat, and prevent wear in diesel engines, transmissions, and hydraulic systems operating under tropical ambient temperatures exceeding 30°C and high humidity conditions. These products serve to extend equipment life, maintain fuel efficiency, and ensure compliance with manufacturer warranty requirements across heavy-duty trucking and bus fleets. Engine oil captures the dominant margin pool due to high consumption frequency and technical complexity, while hydraulic oil grows fastest from expanding construction equipment parc linked to infrastructure development. Bulk packaging leads volume throughput among fleet operators, though pails sustain relevance for repair shops serving fragmented owner-operator segments.
Malaysia's Department of Standards enforces MS specifications for lubricant performance, while the Department of Environment implements Euro 5 emission standards that tighten engine cleanliness requirements and shorten drain intervals. The Ministry of Transport mandates commercial vehicle fitness inspections that indirectly enforce lubricant quality compliance through engine condition assessment. Stakeholders must monitor DSM's potential adoption of ACEA 2021 sequences and the impact of biodiesel blending mandates on lubricant additive chemistry compatibility.
Market Dynamics
Euro 5 emission alignment by Malaysia's Department of Standards is compressing drain intervals and elevating synthetic blend specifications across heavy-duty fleet operations.
Growth Catalysts
- Cross-border logistics expansion:Fleet operators in the heavy-duty trucking sector are accelerating lubricant refresh cycles as logistics providers extend haulage corridors linking Port Klang to ASEAN markets.
- MS specification enforcement:Malaysia's Department of Standards mandates lubricant performance benchmarks that elevate quality baselines and disqualify substandard imports from neighboring supply zones.
- Synthetic formulation adoption:Tropical heat degradation risks are pushing transport operators toward higher-specification lubricants engineered for ambient temperatures exceeding 30°C.
Market Restraints
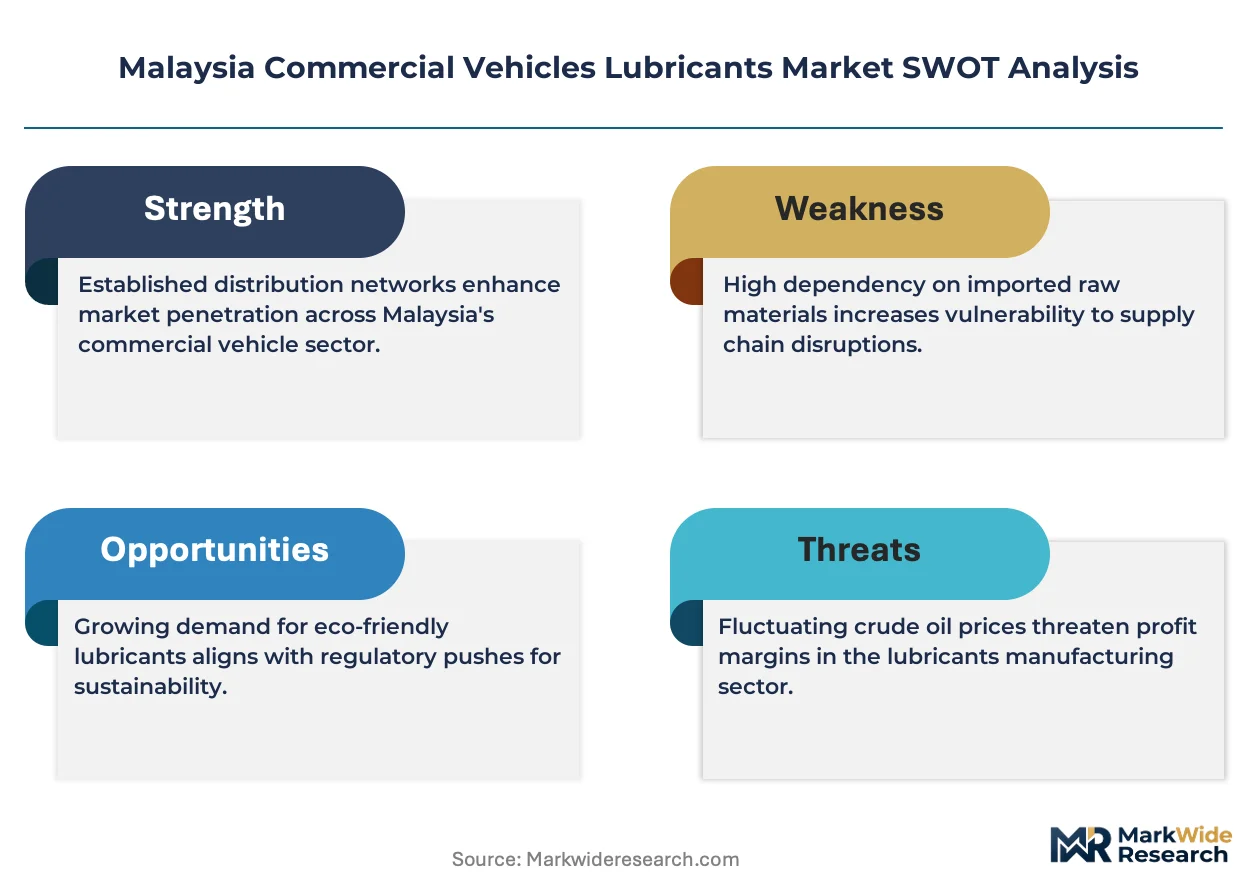
- Base oil supply concentration:Domestic supply chains depend heavily on captive refinery output from PETRONAS, creating vulnerability to upstream capacity constraints.
- Biodiesel blending incompatibility:Malaysia's biodiesel mandates introduce additive chemistry conflicts that accelerate lubricant breakdown and void certain manufacturer warranties.
- Price volatility in Group II/III base stocks:Regional refining margins fluctuate with crude differentials, compressing blender margins and discouraging inventory buildup.
Strategic Opportunities
- East Coast logistics corridor development:Kuantan Port expansion and industrial zone growth in Pahang create underpenetrated demand pockets beyond the Klang Valley cluster.
- Integrated oil analysis services:Bundled predictive maintenance programs combining fluid diagnostics with fleet scheduling software represent a channel innovation opportunity.
- ACEA 2021 sequence preparation:Anticipated DSM alignment with European sequences offers first-mover positioning for blenders investing in additive package upgrades.
Industry Challenges
- Additive chemist scarcity:Formulation expertise for tropical climate lubricants remains concentrated among a small cohort of specialists, constraining product development velocity.
- Multi-standard compliance complexity:Simultaneous adherence to MS specifications, OEM approvals, and anticipated ACEA sequences extends certification timelines and raises testing costs.
- Legacy fleet compatibility:Older commercial vehicles in owner-operator segments lack engine sealing and materials compatibility with low-viscosity synthetic formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Commercial Vehicles Lubricants Market |
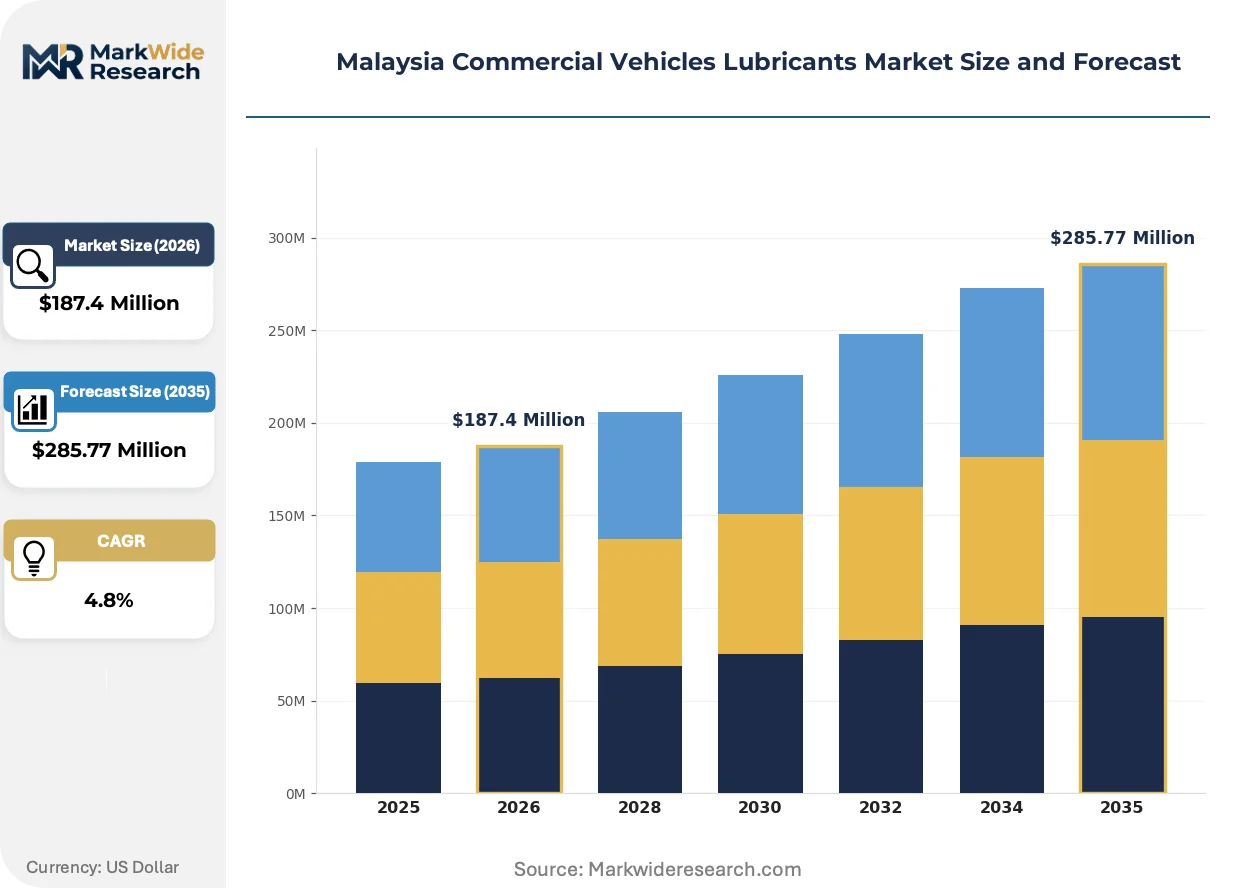
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Grease, Hydraulic Oil End User: Fleet Operators, Transportation Companies, Logistics Providers, Repair Shops Packaging Type: Bulk, Drums, Pails, Sachets Distribution Channel: Direct Sales, Retail, Online, Wholesalers |
| Companies Covered | PETRONAS Lubricants International, BP Plc (Castrol), Royal Dutch Shell Plc, Chevron Corporation, ExxonMobil Corporation, FUCHS, Valvoline Inc, TotalEnergies, Petron Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Commercial Vehicles Lubricants Market Shifts & Advancements
Formulation chemistry and service delivery models are diverging as tropical climate requirements and emission compliance pressures reshape technical specifications.
Low-viscosity synthetic blends are fragmenting traditional mineral oil dominance in heavy-duty engine applications. Fleet operators with vehicles under extended replacement cycles are adopting 5W-30 and 10W-40 grades at accelerating rates. This viscosity shift is fragmenting the historical correlation between vehicle age and lubricant grade selection, creating parallel specification tracks within single fleet portfolios.
Malaysia's Department of Environment implements Euro 5 emission standards that tighten engine cleanliness requirements and shorten drain intervals. The regulation forces lubricant formulators to enhance dispersant and detergent additive packages to manage soot loading. Heavy-duty trucking fleets operating cross-border routes face the steepest compliance adjustments, with many advancing from 20,000-kilometer to 15,000-kilometer service cycles.
Fluid analysis subscriptions are displacing transactional bulk purchasing among large fleet operators. Predictive maintenance platforms bundle oil condition monitoring with automated reordering, compressing the role of traditional distributors. This service unbundling concentrates most visibly in the Klang Valley logistics cluster, where port-linked warehousing operations prioritize uptime guarantees over unit cost minimization.
Malaysia Commercial Vehicles Lubricants Market Segmentation
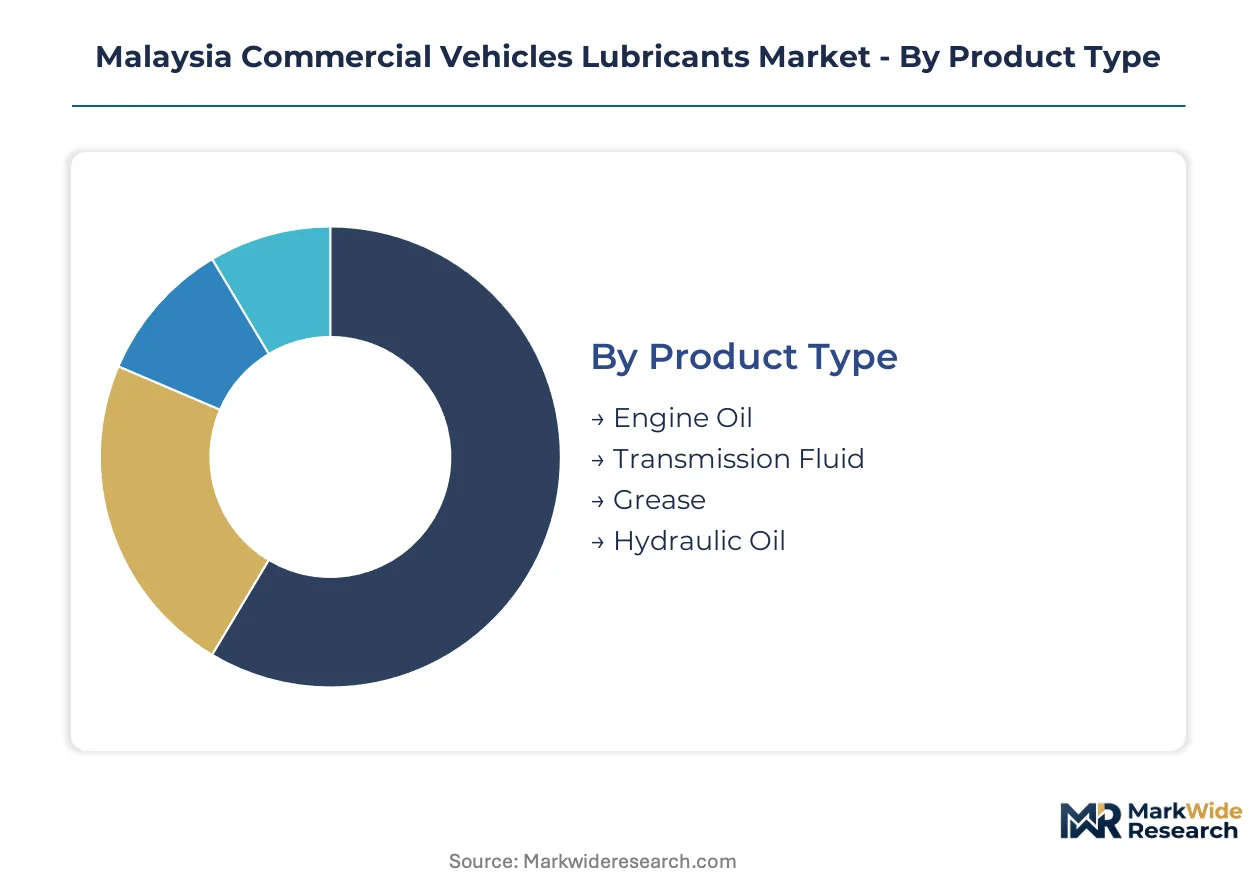
Segmentation in Malaysia's commercial vehicles lubricants market reveals how procurement patterns diverge between large fleet operators and fragmented service channels. Understanding these divisions exposes where margin pools concentrate and which specification tiers command pricing power.
Product Type:
Product type segmentation determines which lubricant categories flow through bulk direct channels versus packaged retail networks, with technical complexity driving channel selection.
- Engine Oil:Formulated petroleum-based or synthetic fluids engineered to reduce friction, dissipate heat, and prevent wear in diesel engines operating under tropical ambient temperatures exceeding 30°C. Demand concentrates in heavy-duty trucking fleets serving Port Klang-linked logistics corridors, where Euro 5 alignment is compressing drain intervals and elevating synthetic blend specifications.
- Hydraulic Oil:Specialized fluids transmitting power in construction equipment and material handling systems while resisting oxidation under high humidity conditions. Growth is accelerating fastest from expanding construction equipment parc linked to infrastructure development in the Klang Valley and emerging East Coast industrial zones.
- Transmission Fluid:High-viscosity lubricants protecting gear systems in commercial vehicle drivetrains against shear degradation.
- Grease:Semi-solid lubricants sealing bearings and chassis components from tropical moisture ingress.
By volume, Engine Oil leads. By growth pace, Hydraulic Oil is climbing the fastest.
End User:
End user segmentation maps specification requirements against procurement sophistication, with large operators demanding integrated service bundles while smaller buyers prioritize unit economics.
- Fleet Operators:Heavy-duty trucking and bus fleet managers with centralized maintenance programs and extended vehicle replacement cycles. These buyers dominate bulk procurement volumes in the Klang Valley logistics cluster, where predictive maintenance platforms are displacing transactional purchasing.
- Logistics Providers:Cross-border haulage specialists operating ASEAN-linked corridors from Port Klang. Procurement concentrates on higher-specification synthetic formulations as these operators face the steepest Euro 5 compliance adjustments and accelerated refresh cycles.
- Transportation Companies:Passenger bus and charter operators with scheduled maintenance protocols.
- Repair Shops:Fragmented service providers serving owner-operator segments with pail-packaged products.
Fleet Operators capture the largest volume share. Logistics Providers are expanding procurement most rapidly.
Packaging Type:
Packaging segmentation reflects the cost-volume trade-offs between centralized fleet supply and decentralized service point replenishment.
- Bulk:Tanker-delivered lubricants for high-throughput fleet depots and port-linked warehousing operations. Channel concentration in the Klang Valley supports automated reordering systems tied to fluid analysis subscriptions.
- Drums:Intermediate-volume containers serving mid-sized fleet maintenance facilities.
- Pails:Small-batch packaging sustaining relevance for repair shops serving fragmented owner-operator segments in secondary cities.
- Sachets:Single-use portions for emergency roadside service and remote construction sites.
Bulk packaging dominates throughput. Pails retain stable share in service shop channels.
Distribution Channel:
Channel segmentation tracks the unbundling of traditional distributor roles as integrated service programs capture strategic accounts.
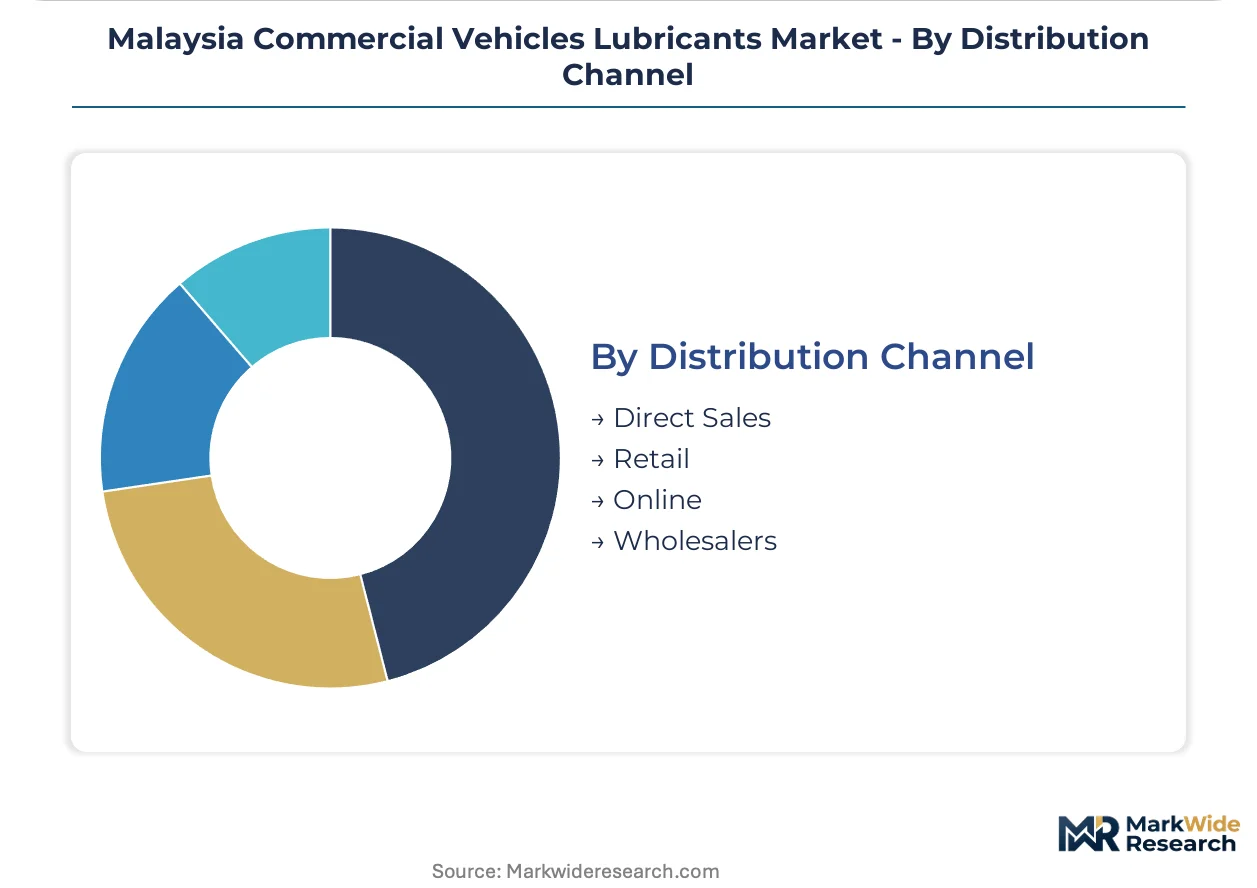
- Direct Sales:Manufacturer-to-fleet relationships bundling lubricant supply with oil analysis and maintenance scheduling software. PETRONAS Lubricants International leverages captive refinery feedstock to anchor these programs.
- Wholesalers:Regional distributors serving secondary markets and smaller fleet operators outside the Klang Valley core.
- Retail:Automotive parts stores and service stations catering to owner-operators and emergency purchases.
- Online:Emerging digital procurement platforms for standardized specification products.
Direct Sales commands the premium account base. Wholesalers maintain broadest geographic coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysia exports commercial vehicle lubricants through ASEAN-linked haulage corridors into Thailand, Indonesia, and Vietnam, with Port Klang serving as the primary transshipment node for regional distribution networks.
Klang Valley
Port-linked warehousing and last-mile distribution hubs concentrate bulk procurement volumes from heavy-duty trucking fleets. The Department of Standards enforces MS specifications that elevate quality baselines across this logistics cluster. Euro 5 alignment is compressing drain intervals and elevating synthetic blend specifications among fleet operators.
Johor Bahru Corridor
Cross-border haulage into Singapore drives demand for higher-specification lubricants engineered for tropical heat degradation. The Ministry of Transport mandates commercial vehicle fitness inspections that indirectly enforce lubricant quality compliance. Industrial zones near the Second Link generate concentrated demand from logistics providers.
Penang Industrial Zone
Manufacturing supply chains and port operations sustain steady consumption of hydraulic and transmission fluids. The Department of Environment implements emission standards that tighten engine cleanliness requirements. Bayan Lepas and Butterworth host fleet maintenance facilities serving electronics and pharmaceutical logistics.
Kuantan Port Expansion
East Coast logistics corridor development creates underpenetrated demand pockets beyond the Klang Valley cluster. Infrastructure investment in Pahang is expanding construction equipment parc linked to lubricant consumption. The Kuantan Port Authority is developing container terminal capacity to capture transshipment flows.
East Malaysia (Sabah and Sarawak)
Palm oil plantation logistics and remote construction sites sustain pail-packaged product demand for fragmented owner-operator segments. Biodiesel blending mandates introduce additive chemistry conflicts that accelerate lubricant breakdown. Kota Kinabalu and Kuching serve as distribution nodes for secondary city service shops.
Malaysia Commercial Vehicles Lubricants Market Competitive Landscape
Listed leaders compete with private specialists across refinery integration and formulation expertise. PETRONAS Lubricants International anchors domestic supply through captive base oil production, while international majors leverage global additive technology portfolios. Three archetypes dominate: integrated national oil companies, multinational lubricant specialists, and regional blending operations. Capacity expansion and integrated service program bundling represent the dominant competitive moves.
Within the integrated national oil company tier, PETRONAS Lubricants International exemplifies backward integration into base oil supply. Among multinational specialists, Royal Dutch Shell Plc and ExxonMobil Corporation occupy positions anchored by tropical climate formulation expertise and predictive maintenance platform development. These three entities represent the structural poles around which competitive dynamics organize.
| Leading Market Players |
|---|
| PETRONAS Lubricants International |
| BP Plc (Castrol) |
| Royal Dutch Shell Plc |
| Chevron Corporation |
| ExxonMobil Corporation |
| FUCHS |
| Valvoline Inc |
| TotalEnergies |
| Petron Corporation |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between PETRONAS Lubricants International and Klang Valley fleet operators lock in base oil supply access and compress price volatility exposure for synthetic blend procurement. These arrangements anchor pricing visibility while insulating bulk buyers from regional Group II/III base stock margin fluctuations.
Pricing Analysis
The viscosity-grade pricing gap separates legacy mineral formulations from low-viscosity synthetic blends and next-generation ACEA-prepped specifications. Three-tier pricing structure across premium synthetic, mid-grade semi-synthetic, and economy mineral levels tracks certification tier and volume commitment scale. Cost compression in economy mineral tiers is intensifying because biodiesel blending mandates accelerate drain interval frequency and erode per-liter value capture. Fleet operators with centralized maintenance programs exhibit lowest price sensitivity; fragmented owner-operator segments through repair shops show highest elasticity.
Supply Chain Analysis
Inventory cycles at Port Klang blending facilities run tighter than regional norms due to tropical humidity degradation risks and just-in-time fleet replenishment patterns. Geographic supply concentration centers on Malaysia, Singapore, and Thailand for base oil refining and additive package compounding. Raw material dependencies draw from Group II/III base stocks, detergent-dispersant additive chemicals, and viscosity modifier polymers. Single-source vulnerability persists around PETRONAS captive refinery output for domestic base oil. Distribution runs through direct manufacturer-to-fleet relationships for bulk volumes, supplemented by regional wholesalers serving secondary markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Malaysia commercial vehicles lubricants market functions as a defensive-moat sector where regulatory entrenchment around MS specifications and Euro 5 alignment creates high switching costs for fleet operators.
For Market Incumbents: Compound defensive positioning through predictive maintenance platform integration and ACEA 2021 sequence pre-certification investments. PETRONAS Lubricants International and Shell should deepen additive package R&D partnerships to neutralize emerging regional blenders. Captive refinery capacity expansion in Kuantan would preempt East Coast corridor demand capture by competitors. For New Entrants and Emerging Players: Predictive fluid analysis service gaps among mid-sized fleet operators outside Klang Valley present the most penetrable white-space target. Kuantan Port-linked logistics clusters and Pahang industrial zones offer under-served geography with accelerating construction equipment parc growth. A go-to-market angle bundling oil analysis subscriptions with flexible bulk delivery scheduling would bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fleet operators with integrated service contracts spanning lubricant supply, condition monitoring, and maintenance scheduling software. Long-term viability centers on formulation expertise scarcity for tropical climate specifications and regulatory compliance complexity. Acquisition targets should display additive chemistry capabilities aligned with anticipated ACEA sequence adoption. The signal to watch is DSM announcement timing for ACEA 2021 alignment, which would accelerate specification upgrade cycles and consolidate margin pools among pre-certified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Additive Package Upgrade Investment | ACEA 2021 sequence preparation by DSM creates first-mover certification advantage for pre-invested blenders. |
| East Coast Distribution Capacity Buildout | Kuantan Port expansion and Pahang industrial zone growth generate underpenetrated demand beyond Klang Valley saturation. |
| Predictive Maintenance Platform Integration | Fluid analysis subscriptions displace transactional purchasing among uptime-focused fleet operators. |
| Long-term Fleet Supply Agreement | Direct manufacturer relationships with cross-border logistics providers lock in synthetic blend volume commitments. |
| Backward Integration into Base Oil | Captive refinery feedstock control insulates margin pressure from regional Group II/III price volatility. |
Research Methodology
Desk research of trade flow databases, Department of Standards technical specifications, and PETRONAS annual disclosures preceded structured interviews with fleet maintenance directors, lubricant formulation chemists, and regional distribution channel managers. Primary fieldwork captured procurement pattern shifts and Euro 5 compliance cost impacts. Secondary validation drew from customs import records, Ministry of Transport vehicle registration data, and construction equipment parc estimates. Bottom-up volume modeling triangulated against top-down market sizing from base oil consumption trends.
Variance decomposition across product type, end user sophistication, packaging format, and geographic cluster shaped the analytical framework. Segmentation dimensions modeled include lubricant category, fleet size tier, distribution channel structure, and regional logistics corridor development stage. CAGRs were derived from trend extrapolation adjusted for regulatory phase-in effects and infrastructure investment pipelines. Forecast inputs incorporated biodiesel mandate progression timelines and anticipated ACEA sequence adoption schedules.
Forecasts assume regulatory continuity in Malaysia's Department of Standards MS specifications and Department of Environment Euro 5 enforcement; material policy shifts would require re-modeling. Base oil supply disruptions from PETRONAS refinery maintenance or regional crude differential shocks represent specific revision triggers. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Lubricants for Cement Industry Market
Lubricants
Russia Automotive Lubricants Market
Lubricants
North America Lubricants Market
Lubricants
Myanmar Lubricants Market
Lubricants
Mexico Automotive Engine Oils Market
Lubricants
Turkey Automotive Lubricants Market
Lubricants
Egypt Lubricants Market
Lubricants
Global Agricultural Lubricants Market
Lubricants
America Lubricants Market
Lubricants
Italy Lubricants Market
Lubricants
South America Lubricants Market
Lubricants
Non-Flammable Hydraulic Fluids Market
Lubricants
Aluminum Extrusion Lubricants Market
Lubricants
Wire Rope Lubricants Market
Lubricants
Colombia Lubricants Market
Lubricants
Israel Lubricants Market