
 China Commercial Vehicles Lubricants Market | 2026-2036
China Commercial Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
China Commercial Vehicles Lubricants Market Outlook
Fleet operators are collapsing their supplier base toward national oil companies with integrated refining and blending capabilities. China Petroleum & Chemical Corporation leverages its Sinopec-branded service station network to secure fleet contracts across provincial highway corridors. PetroChina Company Limited anchors its position through captive crude supply from Daqing and Changqing oilfields, ensuring cost-competitive base oil production.
Commercial vehicle lubricants are formulated blends of base oils and additive packages designed to reduce friction, dissipate heat, and neutralize combustion acids in diesel engines operating under severe duty cycles, with viscosity grades typically spanning SAE 15W-40 to 10W-30 for turbocharged heavy-duty applications. Engine oil dominates product type revenue due to mandatory drain interval compliance under GB 11122, while synthetic formulations capture expanding share as OEMs extend factory-fill specifications to 100,000-kilometer service intervals. Fleet operators represent the fastest-growing end user segment as third-party logistics providers consolidate vehicle pools under centralized maintenance programs.
MIIT enforces fuel consumption limits for heavy-duty commercial vehicles under Stage IV standards, compelling lubricant formulators to develop lower-viscosity grades that reduce parasitic engine losses without sacrificing wear protection. GB national standards and China VI emissions regulations from MEE jointly dictate ash content and sulfur limits compatible with exhaust aftertreatment systems. Stakeholders must monitor how provincial environmental bureaus enforce low-sulfur mandates in inland manufacturing zones where enforcement historically lags coastal provinces.
Market Dynamics
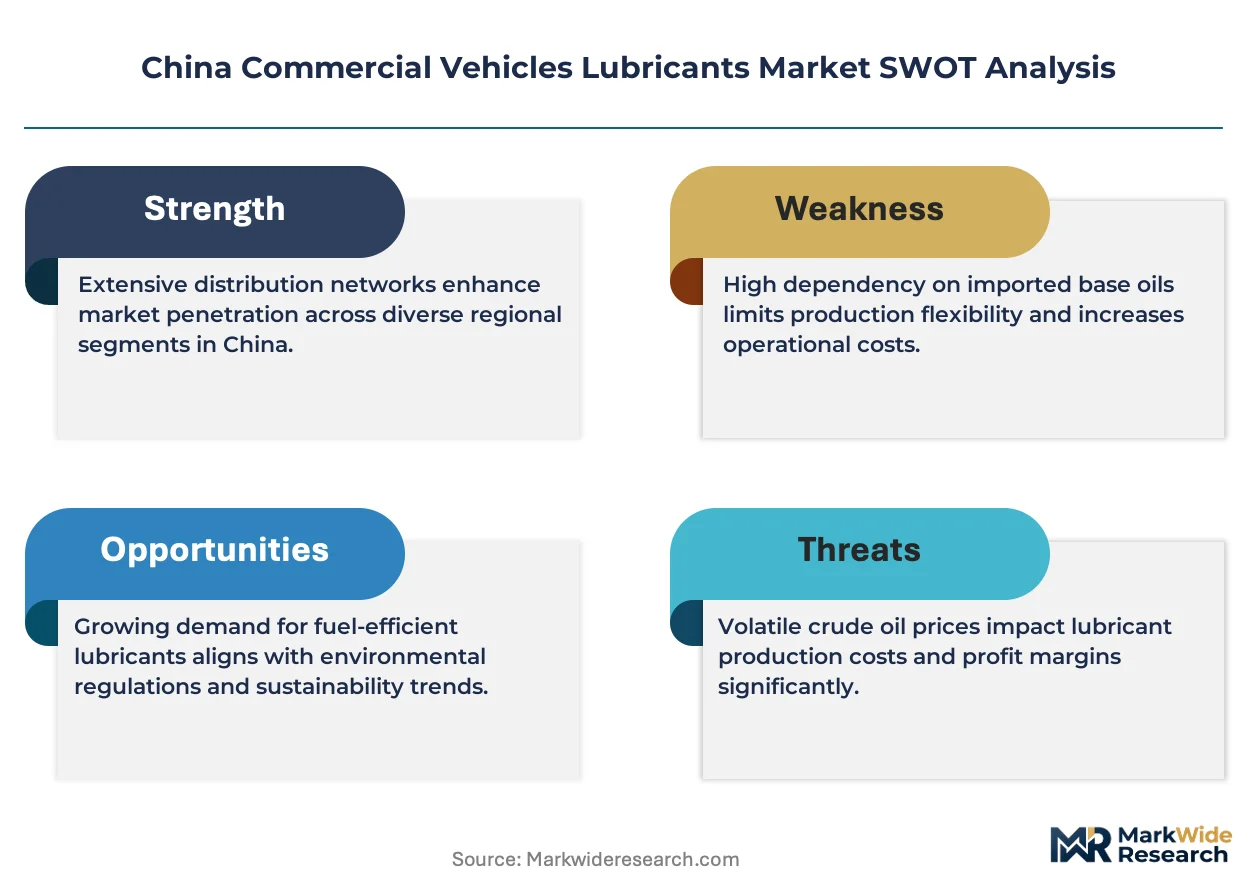
MIIT Stage IV fuel consumption limits are compressing lubricant viscosity grades across heavy-duty fleets, forcing formulators to balance parasitic loss reduction against wear protection in turbocharged diesel architectures.
Growth Catalysts
- China VI emissions architecture:MEE mandates for exhaust aftertreatment compatibility are pulling low-ash, low-sulfur formulations into factory-fill specifications at domestic OEMs.
- Third-party logistics consolidation:Fleet operators in the Yangtze River Delta are centralizing procurement under national oil companies with integrated blending capabilities.
- Synthetic base oil adoption:Extended drain intervals to 100,000 kilometers are displacing mineral formulations in long-haul trucking corridors.
Market Restraints
- Base oil supply concentration:Captive crude from Daqing and Changqing fields limits independent blender access to cost-competitive feedstock.
- Additive package import dependency:Performance chemical supply remains concentrated with multinational suppliers subject to tariff friction.
- GB 11122 compliance timeline:Accelerated specification updates force reformulation cycles shorter than typical product development windows.
Strategic Opportunities
- Inland province logistics densification:Sichuan and Shaanxi manufacturing zones present underpenetrated demand as highway networks extend westward.
- Dual carbon policy alignment:MIIT carbon intensity targets create preferential procurement status for lubricants with verified lifecycle emissions reductions.
- Digital fleet management integration:Oil condition monitoring systems are opening direct supplier-to-operator channels bypassing traditional distributor networks.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in tribology and additive synergy remains concentrated with state-owned research institutes.
- Blending asset utilization:Regional plants face capacity misalignment as demand shifts toward coastal megaplants with synthetic production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Commercial Vehicles Lubricants Market |
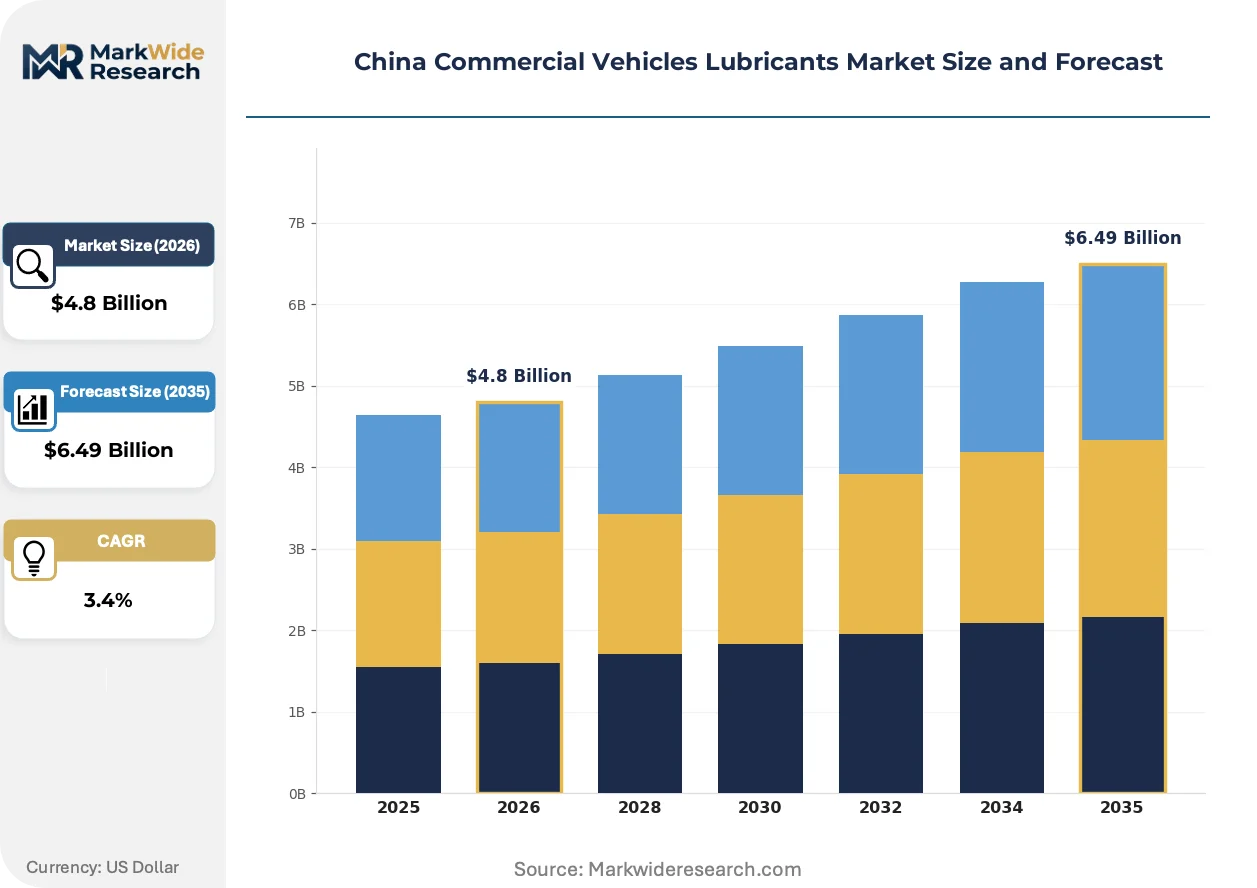
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.49 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Gear Oil, Transmission Fluid, Hydraulic Oil Formulation: Synthetic, Semi-Synthetic, Mineral, Biodegradable End User: Fleet Operators, Logistics Companies, Construction Firms, Municipal Transport Distribution Channel: Direct Sales, Retail Stores, Online Sales, Distributors |
| Companies Covered | China Petroleum & Chemical Corporation, China National Petroleum Corporation, BP PLC (Castrol), ExxonMobil Corporation, Royal Dutch Shell Plc, Chevron Corporation, TotalEnergies, Fuchs Petrolub SE, PetroChina Company Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Commercial Vehicles Lubricants Market Strategic Shifts
Synthetic formulation architectures are rewriting competitive requirements as extended service intervals and emissions hardware protection become non-negotiable specifications.
Group III+ and PAO base stocks are decomposing the traditional mineral-dominant supply structure. Domestic blenders are retrofitting coastal plants to handle higher-viscosity-index feedstocks. The technology is decomposing price-based competition into performance-contracting models where drain interval guarantees determine contract awards.
GB 11122 diesel engine oil specifications are tightening phosphorus and sulfur limits to protect diesel particulate filters. Formulators must recalibrate anti-wear additive chemistry without sacrificing extreme-pressure performance. Heavy-duty OEMs in Shandong and Hubei provinces are responding with factory-fill exclusivity agreements that lock out non-compliant suppliers.
Fleet maintenance departments are consolidating lubricant purchasing under centralized procurement platforms. Traditional provincial distributors are losing shelf space to direct national oil company contracts with integrated billing and logistics. The shift is most visible among cross-province logistics operators running Shanghai-Chengdu and Beijing-Guangzhou corridors.
China Commercial Vehicles Lubricants Market Segmentation
China's commercial vehicle lubricants market fragments across four critical dimensions. Product type and formulation determine technical compliance with MIIT fuel economy mandates, while end-user concentration and channel structure dictate procurement economics for state-owned and private fleet operators.
Product Type:
Channel mix varies sharply by lubricant function, with factory-fill contracts flowing through direct national oil company relationships and aftermarket volume splitting between service station networks and independent distributors.
- Engine Oil:Formulated blends of base oils and additive packages designed to reduce friction, dissipate heat, and neutralize combustion acids in diesel engines operating under severe duty cycles. Demand concentrates in the Yangtze River Delta manufacturing corridor, where heavy-duty truck production clusters around Shanghai, Jiangsu, and Zhejiang provinces, driven by GB 11122 mandatory drain interval compliance.
- Gear Oil:Extreme-pressure lubricants protecting hypoid and spiral-bevel gear sets in commercial vehicle axles and differentials. Fleet operators in long-haul trucking corridors are consolidating procurement under centralized maintenance programs, displacing traditional provincial distributor relationships.
- Transmission Fluid:Friction-modified formulations for automated manual and fully automatic transmissions in heavy-duty applications. Specifications tighten under OEM factory-fill agreements.
- Hydraulic Oil:Anti-wear formulations for power steering and brake systems in commercial chassis. Municipal transport fleets drive specification stability.
Engine oil dominates installed base. Synthetic formulations in extended-drain applications are where expansion concentrates.
Formulation:
Cost tier stratification separates premium synthetic formulations from mineral alternatives, with semi-synthetic occupying a contracting middle ground as fleet operators optimize total cost of ownership.
- Synthetic:Group III+ and PAO base stocks delivering viscosity stability across extreme temperature ranges and extended service intervals. OEMs in Shandong and Hubei provinces are responding with factory-fill exclusivity agreements that lock out non-compliant suppliers, driven by 100,000-kilometer drain interval specifications.
- Semi-Synthetic:Blended formulations combining Group II base stocks with synthetic content for moderate service intervals. Independent blenders face feedstock access constraints from captive crude supply.
- Mineral:Refined petroleum-based formulations dominating legacy fleet applications and price-sensitive owner-operator segments. Volume share erodes as synthetic production scales at coastal megaplants.
- Biodegradable:Vegetable-derived base stocks for municipal and environmentally sensitive applications. Dual carbon policy alignment creates preferential procurement status in state-owned fleet tenders.
Mineral formulations retain legacy fleet share. Synthetic architectures are climbing the fastest as emissions hardware protection becomes non-negotiable.
End User:
Customer type determines contract structure, with national logistics platforms commanding direct supplier relationships while fragmented construction and municipal segments persist with distributor intermediation.
- Fleet Operators:Third-party logistics providers consolidating vehicle pools under centralized maintenance programs. Procurement is shifting toward national oil companies with integrated refining and blending capabilities across provincial highway corridors.
- Logistics Companies:E-commerce fulfillment and express delivery fleets with standardized specifications and volume-based pricing. Cross-province operators running Shanghai-Chengdu and Beijing-Guangzhou corridors drive demand concentration.
- Construction Firms:Project-based procurement for off-highway equipment with severe-duty cycle requirements. Regional blending plants serve this segment through traditional distributor networks.
- Municipal Transport:State-owned bus and sanitation fleets with stable specifications and tender-based procurement. Environmental bureaus enforce low-sulfur mandates with variable rigor across inland provinces.
Fleet operators command contract value. Logistics companies are gaining share fastest as e-commerce fulfillment networks densify.
Distribution Channel:
Supply concentration dictates channel economics, with integrated national oil companies bypassing traditional distributors through captive service station networks and direct fleet contracts.
- Direct Sales:National oil company contracts with integrated billing, logistics, and technical service for large fleet accounts. Sinopec-branded service station networks secure fleet contracts through volume commitments and drain interval guarantees.
- Retail Stores:Service station and automotive parts counter sales for owner-operators and small fleet maintenance. Shelf space consolidates toward national brands with verified GB 11122 compliance.
- Online Sales:B2B procurement platforms and specialized lubricant e-commerce for standardized specifications. Digital fleet management integration opens direct supplier-to-operator channels.
- Distributors:Provincial and regional intermediaries serving fragmented construction and municipal segments. Traditional distributors are losing share as procurement centralizes under national platforms.
Direct sales capture fleet value. Online sales are expanding most quickly as procurement platforms digitize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta port complex anchors China's commercial vehicle lubricants distribution, with Shanghai's deepwater terminals feeding base oil supply chains into Jiangsu and Zhejiang blending facilities.
Yangtze River Delta
Heavy-duty truck production clusters around Shanghai, Jiangsu, and Zhejiang provinces drive concentrated lubricant demand. MIIT Stage IV fuel consumption limits compel formulators to develop lower-viscosity grades for turbocharged diesel architectures. Synthetic production lines at coastal megaplants are displacing regional blending capacity as fleet procurement centralizes.
Beijing-Tianjin-Hebei
Cross-province logistics operators running the Beijing-Guangzhou corridor command direct national oil company contracts. China VI emissions regulations from MEE enforce low-ash, low-sulfur formulation requirements. Municipal transport fleets in Beijing maintain stable specifications under tender-based procurement with environmental bureau oversight.
Shandong Peninsula
Heavy-duty OEMs in Shandong province are executing factory-fill exclusivity agreements that lock out non-compliant suppliers. GB 11122 diesel engine oil specifications tighten phosphorus limits to protect diesel particulate filters. Independent blenders face feedstock access constraints from captive crude supply concentration.
Sichuan-Chongqing
Highway network extension into western China presents underpenetrated demand for fleet lubricant procurement. Provincial environmental bureaus enforce low-sulfur mandates with variable rigor compared to coastal provinces. Third-party logistics providers are consolidating vehicle pools under centralized maintenance programs in the Chengdu manufacturing zone.
Pearl River Delta
E-commerce fulfillment networks in Guangdong province densify express delivery fleet specifications. Synthetic base oil adoption accelerates as extended drain intervals reach 100,000 kilometers. Digital fleet management integration opens direct supplier-to-operator channels bypassing traditional distributor networks.
China Commercial Vehicles Lubricants Market Competitive Environment
Listed leaders compete with private specialists across integrated refining and blending capabilities, with state-owned enterprises commanding captive crude supply and multinational affiliates leveraging imported additive technology. Market structure concentrates around national oil companies with vertical control over base oil production, while independent blenders occupy price-sensitive segments through regional distributor relationships. Three archetypes dominate: integrated state-owned refiners with service station networks, multinational lubricant specialists with technology licensing arrangements, and regional independents serving fragmented construction fleets. Competitive moves center on synthetic production line retrofitting and direct fleet contract acquisition with drain interval guarantees.
Among state-owned integrated refiners, China Petroleum & Chemical Corporation and PetroChina Company Limited exemplify the captive supply archetype, anchoring market position through control of Daqing and Changqing field crude. BP PLC (Castrol) and Royal Dutch Shell Plc represent the multinational technology tier, occupying positions defined by additive package performance and factory-fill relationships with domestic OEMs. These four entities illustrate the competitive tension between feedstock security and formulation technology as distinct sources of market leverage.
| Leading Market Players |
|---|
| China Petroleum & Chemical Corporation |
| China National Petroleum Corporation |
| BP PLC (Castrol) |
| ExxonMobil Corporation |
| Royal Dutch Shell Plc |
| Chevron Corporation |
| TotalEnergies |
| Fuchs Petrolub SE |
| PetroChina Company Limited |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between Sinopec and Yangtze River Delta fleet operators lock in both Group III+ base oil supply access and price visibility across multi-year procurement windows, insulating large buyers from spot market volatility while compressing margins for independent blenders locked out of captive Daqing crude.
Pricing Analysis
Volume-discount tiering structures stratify procurement economics across fleet scale categories, with cross-province logistics operators commanding 100,000-kilometer drain interval guarantees at synthetic-grade price points that owner-operators cannot access. Price differentiation hinges on GB 11122 compliance certification and integrated service bundling through Sinopec-branded station networks. Cost compression in mineral formulations is intensifying because coastal megaplants are scaling synthetic production lines. Owner-operators remain most price-sensitive, while national logistics platforms prioritize total cost of ownership over per-liter pricing.
Supply Chain Analysis
Inbound logistics costs from Middle Eastern and Southeast Asian additive package suppliers face persistent container availability constraints at Shanghai and Ningbo port complexes, elevating working capital requirements for independent blenders. Base oil production concentrates in China, with supplemental Group III+ imports from South Korea and Singapore. Raw material dependencies span PAO base stocks, dispersant-detergent additive systems, and viscosity index improvers. Single-source vulnerability runs through multinational additive suppliers subject to tariff friction. Distribution runs through national oil company service station networks and direct fleet contracts, displacing traditional provincial distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's commercial vehicle lubricants market reads as a service-attach opportunity where oil condition monitoring and predictive maintenance subscriptions are expanding faster than base lubricant volume as fleet operators digitize asset management.
For Market Incumbents: Compound synthetic blending capacity at coastal megaplants to capture factory-fill exclusivity agreements from Shandong and Hubei OEMs. Deepen backward integration into additive package formulation through state-owned research institute partnerships, neutralizing import dependency risks from multinational suppliers. Defend against independent blender price erosion by locking in 100,000-kilometer drain interval guarantees with cross-province logistics operators. For New Entrants and Emerging Players: Digital fleet management integration gaps among inland province operators present white-space openings where incumbents under-serve with legacy distributor models. Target Sichuan and Shaanxi manufacturing zones through oil condition monitoring system partnerships that bypass traditional procurement channels. Penetrate via direct supplier-to-operator platforms with real-time viscosity degradation alerts and automated replenishment triggers. For Investors and Strategic Acquirers: Capital is best deployed toward regional blending assets with retrofit potential for Group III+ handling and established relationships with municipal transport fleets under dual carbon procurement preferences. Long-term viability favors operators with verified lifecycle emissions documentation aligned with MIIT carbon intensity targets. Watch provincial environmental bureau enforcement rigor in inland zones as the inflection signal for synthetic formulation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Synthetic Production Line Retrofit | Enables 100,000-kilometer drain interval compliance under GB 11122 specifications. |
| Direct Fleet Contract Acquisition | Bypasses traditional distributors through Sinopec-branded service station network penetration. |
| Additive Package Localization | Reduces tariff exposure from multinational suppliers via state-owned research institute partnerships. |
| Oil Condition Monitoring Integration | Opens digital supplier-to-operator channels with predictive maintenance subscription revenue. |
| Inland Province Distribution Buildout | Captures underpenetrated demand as highway networks extend into Sichuan-Chongqing corridor. |
Study Parameters
A spread of perspectives from fleet procurement directors, lubricant formulation chemists, MIIT regulatory affairs specialists, and Sinopec distribution managers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation through customs trade records, GB standards documentation, SEC filings from listed oil companies, and MIIT fuel economy disclosure databases. Bottom-up volume estimates from provincial vehicle registration data were triangulated against top-down base oil production figures from state-owned refinery disclosures.
Segmentation dimensions modeled span product type, formulation chemistry, end-user category, and distribution channel across the analysis window. CAGRs were derived from trend extrapolation of synthetic adoption rates, fleet consolidation patterns, and emissions hardware penetration curves. Industry-specific forecast inputs include MIIT Stage IV compliance timelines and China VI aftertreatment protection requirements.
Forecasts assume regulatory continuity in MIIT fuel economy mandates and MEE emissions enforcement regimes; material policy shifts would require re-modeling of synthetic formulation demand trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Global Group IV and V Lubricants Market
Lubricants
Industrial Lubricants Market
Lubricants
Japan Lubricants Market
Lubricants
South America Commercial Vehicles Lubricants Market
Lubricants
United Kingdom Commercial Vehicles Lubricants Market
Lubricants
Europe Grease Market
Lubricants
Nigeria Lubricants Market
Lubricants
Myanmar Lubricants Market
Lubricants
Global Process Oil Market
Lubricants
Food Grade Lubricant Market
Lubricants
Netherlands Metalworking Fluids Market
Lubricants
Global Mineral Oil Market
Lubricants
Aluminum Extrusion Lubricants Market
Lubricants
Global Automotive Engine Oils Market
Lubricants
Vietnam Lubricants Market
Lubricants
Bulgaria Passenger Vehicles Lubricants Market